
 Mobile Stroke Unit (MSTU) Market | 2026-2036
Mobile Stroke Unit (MSTU) Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Stroke Unit (MSTU) Market Foresight
Telemedicine-enabled stroke diagnostics is recalibrating what health systems purchase, shifting capital allocation from static imaging suites to mobile platforms. Siemens Healthineers leverages its portable CT scanner portfolio to anchor technology leadership in pre-hospital neurological assessment. GE HealthCare competes through integrated software solutions that synchronize wireless communication between ambulances and receiving stroke centers.
A Mobile Stroke Unit is a specially equipped emergency response vehicle incorporating a portable CT scanner, telemedicine equipment, and intravenous thrombolytic administration capability, designed to deliver hospital-level stroke diagnosis and treatment before patient arrival at a medical facility. The unit typically operates through wireless communication links that transmit real-time imaging data to neurologists at receiving hospitals, enabling rapid treatment decisions during patient transport. Portable CT scanner installations command the dominant share of product type expenditure due to their specialized radiological certification requirements and limited manufacturer base. Emergency Medical Services end users represent the fastest-growing demand channel as municipal health authorities restructure acute care networks around time-critical neurological intervention.
The FDA breakthrough device program streamlines premarket review for novel stroke diagnostic technologies, directly shaping manufacturer R&D priorities and product development timelines. Germany's national stroke registry standards, administered through regional medical associations, mandate response time documentation that favors MSTU deployment in metropolitan areas. Stakeholders must monitor evolving reimbursement codes for mobile stroke interventions, as coverage determinations by Medicare and comparable national payers will dictate fleet expansion feasibility across health system budgets.
Market Dynamics
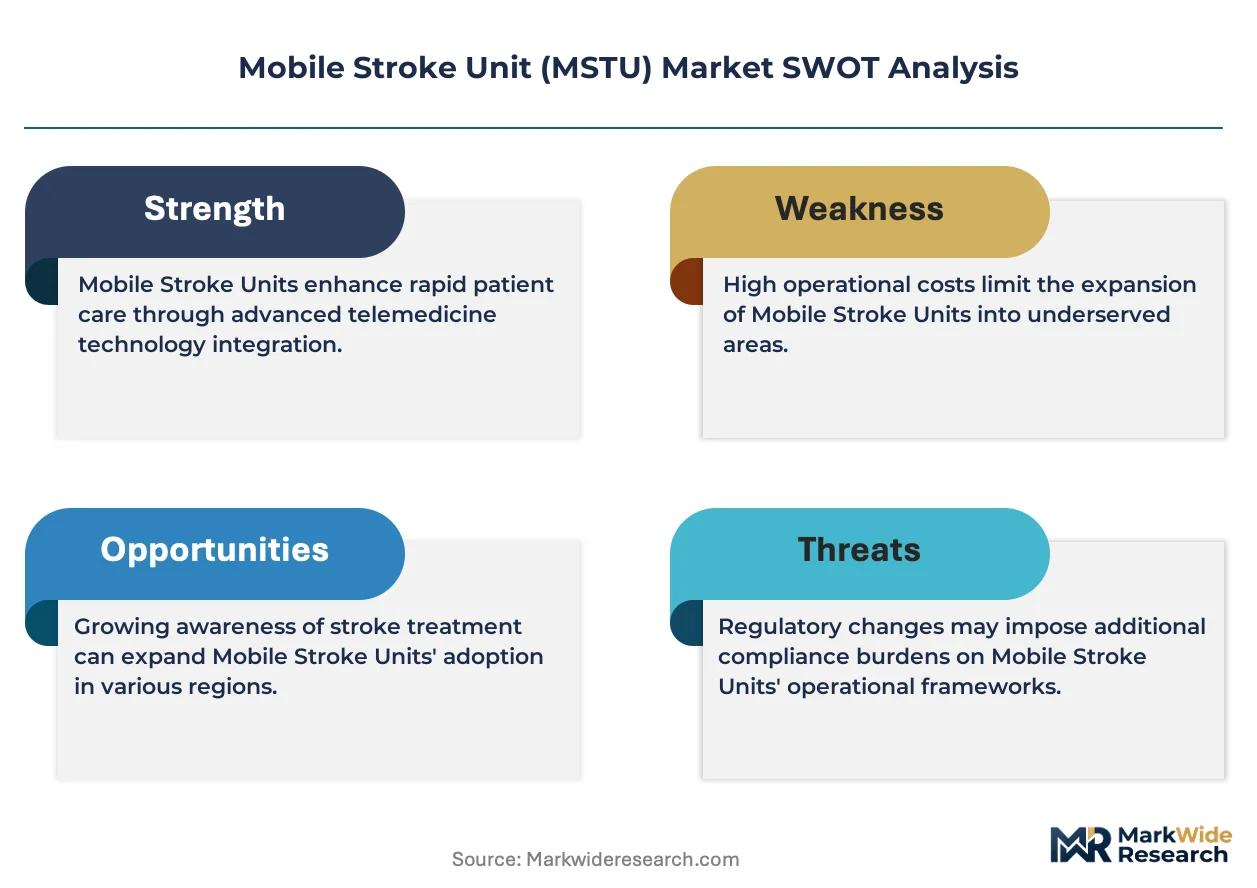
Telemedicine-enabled stroke diagnostics is compressing treatment windows from hours to minutes, forcing health systems to reallocate capital from fixed imaging suites to mobile platforms that deliver hospital-level care during patient transport.
Growth Catalysts
- Breakthrough Device Pathway:The FDA's accelerated premarket review for novel stroke diagnostics is shortening product development cycles for portable imaging systems.
- Emergency Medical Services Fleet Expansion:Municipal health authorities across Germany are restructuring acute care networks around time-critical neurological intervention.
- Portable CT Scanner Technology:Specialized radiological certification requirements and limited manufacturer base are concentrating investment in mobile radiological platforms.
Market Restraints
- Reimbursement Code Uncertainty:Coverage determinations by Medicare and comparable national payers remain unresolved, constraining fleet expansion feasibility across health system budgets.
- Supply Concentration in Imaging Components:The specialized portable CT scanner base depends on a narrow set of certified radiological equipment suppliers.
- Wireless Communication Infrastructure Gaps:Real-time imaging data transmission requires consistent high-bandwidth connectivity that remains uneven across rural transport corridors.
Strategic Opportunities
- Metropolitan Network Density:Germany's national stroke registry standards mandate response time documentation that favors MSTU deployment in urban clusters.
- Integrated Software Convergence:Wireless communication synchronization between ambulances and receiving stroke centers creates new platform differentiation vectors.
- Pre-Hospital Thrombolytic Administration:Intravenous treatment capability during transport opens reimbursement negotiations for intervention codes previously limited to hospital settings.
Industry Challenges
- Neurologist Telemedicine Availability:Real-time specialist consultation for mobile units requires 24/7 staffing models that strain regional stroke center resources.
- Legacy Hospital Imaging Suite Integration:Data format compatibility between portable CT systems and fixed radiology information systems demands costly interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Stroke Unit (MSTU) Market |
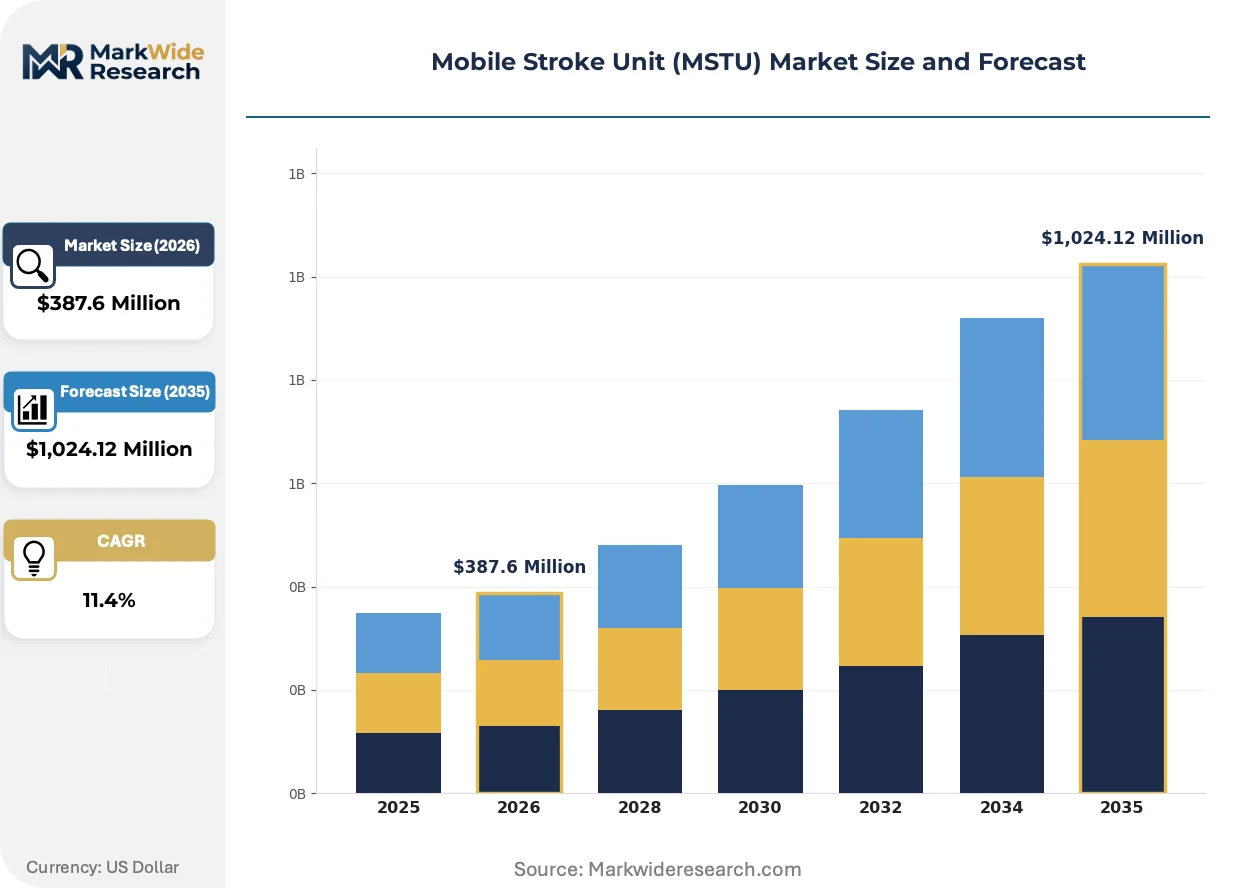
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable CT Scanner, Telemedicine Equipment, Emergency Response Vehicle, Intravenous System Application: Pre-Hospital Care, In-Hospital Services, Remote Monitoring, Patient Transport End User: Emergency Medical Services, Hospitals, Clinics, Rehabilitation Centers Technology: Wireless Communication, Imaging Technology, Diagnostic Tools, Software Solutions |
| Companies Covered | Demers Ambulances, Frazer Ltd., Siemens Healthineers, GE HealthCare, Excellance Inc., Tri-Star Industries Ltd., MEYTEC GmbH Informationssysteme, NeuroLogica Corp., Falck A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Stroke Unit (MSTU) Market Shifts & Advancements
Stroke care delivery is migrating from centralized hospital towers to distributed mobile platforms, rewiring capital flows and competitive positioning across pre-hospital emergency medicine.
Artificial intelligence-enabled image analysis is integrating into portable CT scanner workflows to accelerate hemorrhagic versus ischemic stroke classification. Emergency medical services fleets in the United States are piloting these tools to reduce neurologist consultation bottlenecks during transport. This compression of diagnostic decision time is integrating machine learning into regulatory pathways previously reserved for human-read imaging.
The FDA breakthrough device designation is streamlining premarket review timelines for novel stroke diagnostic technologies. This regulatory acceleration is compressing product development cycles from typical 510(k) pathways. Portable imaging manufacturers targeting the United States market are restructuring clinical trial designs to align with this expedited framework.
Hospital procurement departments are unbundling after-sales service contracts from equipment purchases, forcing manufacturers to compete on discrete maintenance and software update pricing. Metropolitan health systems in Germany are leading this shift, separating capital acquisition from ongoing technical support. This disaggregation is pressuring traditional bundled pricing models across European emergency medical services procurement.
Mobile Stroke Unit (MSTU) Market Segmentation
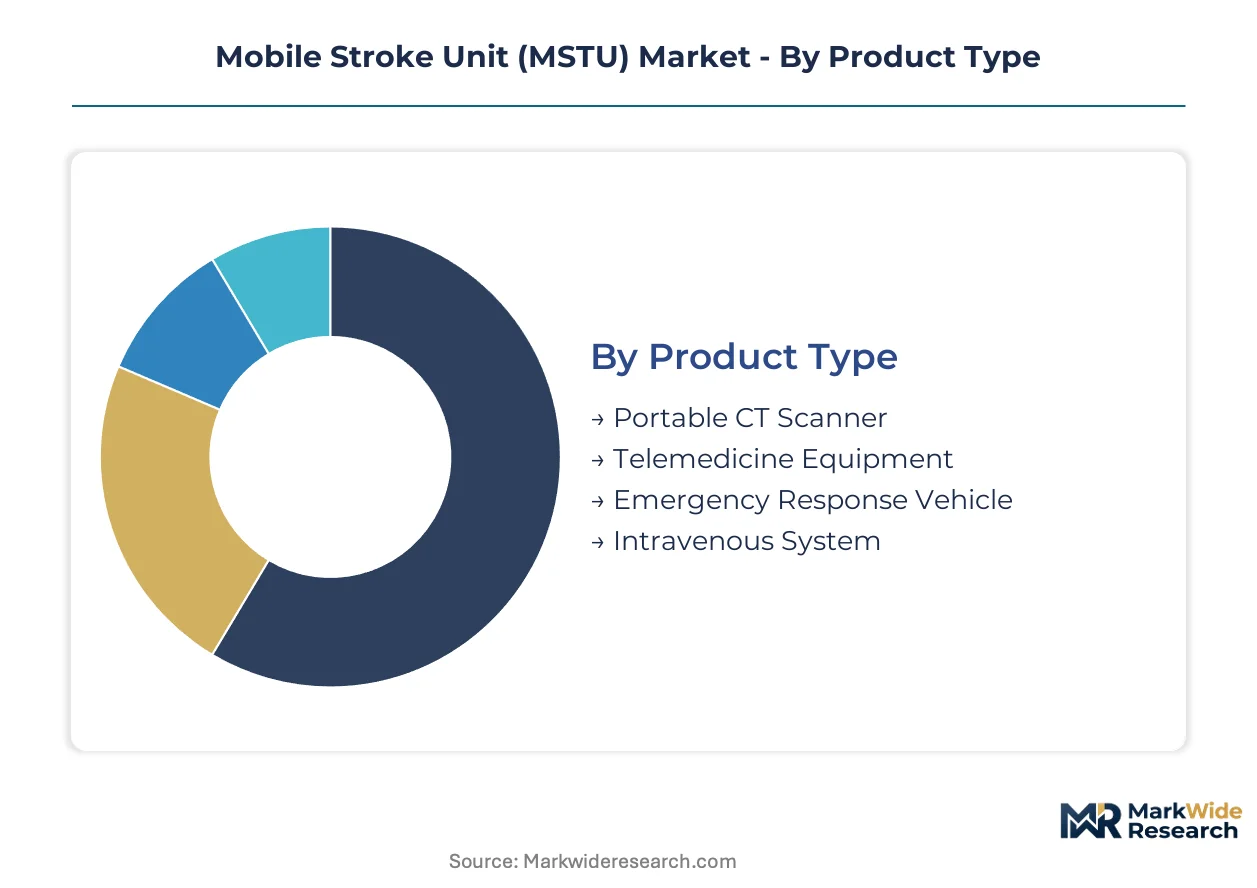
Segmentation in the Mobile Stroke Unit market reveals how capital allocation splits between hardware platforms, service delivery modes, and connectivity infrastructure. Procurement decisions vary sharply across emergency medical services, hospital networks, and municipal health authorities with differing technical requirements.
Product Type:
Customization intensity spans from fully bespoke vehicle integrations to standardized component procurement, with radiological certification requirements driving specification divergence.
- Portable CT Scanner:Self-contained computed tomography systems with specialized shielding and vibration dampening for mobile deployment. Demand concentrates in German metropolitan EMS fleets where KBA vehicle certification mandates specific radiological safety configurations. Siemens Healthineers and GE HealthCare dominate supply through limited manufacturer base constraints.
- Telemedicine Equipment:Real-time video consultation systems with bidirectional data transmission capability. Emergency medical services across the United States are standardizing on interoperable platforms that synchronize with receiving stroke centers. FDA breakthrough device designations are accelerating hardware refresh cycles.
- Emergency Response Vehicle:Modified ambulance chassis with reinforced structural elements and power systems. Municipal procurement in Germany favors modular retrofit packages over ground-up custom builds.
- Intravenous System:Stabilized medication administration units with thrombolytic storage and dosing controls. Hospital-based MSTU programs specify integrated pumps with remote monitoring capability.
Most installed capacity flows through Portable CT Scanner configurations. Expansion is steepest in Telemedicine Equipment as wireless infrastructure matures.
Application:
Volume distribution across applications tracks the migration of acute stroke intervention from fixed facilities to mobile platforms.
- Pre-Hospital Care:Direct thrombolytic administration and imaging during patient transport. German stroke registry standards mandate response time documentation that favors metropolitan deployment. Medicare reimbursement code development in the United States is reshaping fleet investment feasibility.
- In-Hospital Services:Supplementary imaging capacity and overflow patient management. Urban hospital networks in the United States deploy MSTUs as flexible surge resources during fixed scanner maintenance.
- Remote Monitoring:Continuous telemetry and specialist consultation without physical transport. Rural transport corridors with uneven wireless bandwidth limit practical deployment.
- Patient Transport:Inter-facility transfer with maintained treatment protocols. Rehabilitation centers in Germany contract dedicated MSTU services for post-acute transfers.
Pre-Hospital Care commands the dominant share of operational deployments. Remote Monitoring is climbing fastest as 5G infrastructure reaches rural corridors.
End User:
Customer type segmentation reflects diverging procurement authority between municipal health authorities and private hospital systems.
- Emergency Medical Services:Municipal fleet operators with standardized vehicle specifications and centralized maintenance contracts. Germany's regional medical associations are restructuring acute care networks around neurological response time targets.
- Hospitals:Academic medical centers and stroke centers with dedicated neurology departments. United States health systems are piloting AI-enabled image analysis to reduce specialist consultation bottlenecks.
- Clinics:Outpatient facilities with limited imaging infrastructure. Urban clusters favor shared MSTU access models over capital acquisition.
- Rehabilitation Centers:Post-acute facilities requiring inter-facility transport with maintained treatment continuity. German national stroke registry documentation requirements extend into post-acute phases.
Most fleet ownership sits with Emergency Medical Services. Hospitals are gaining share fastest through public-private partnership structures.
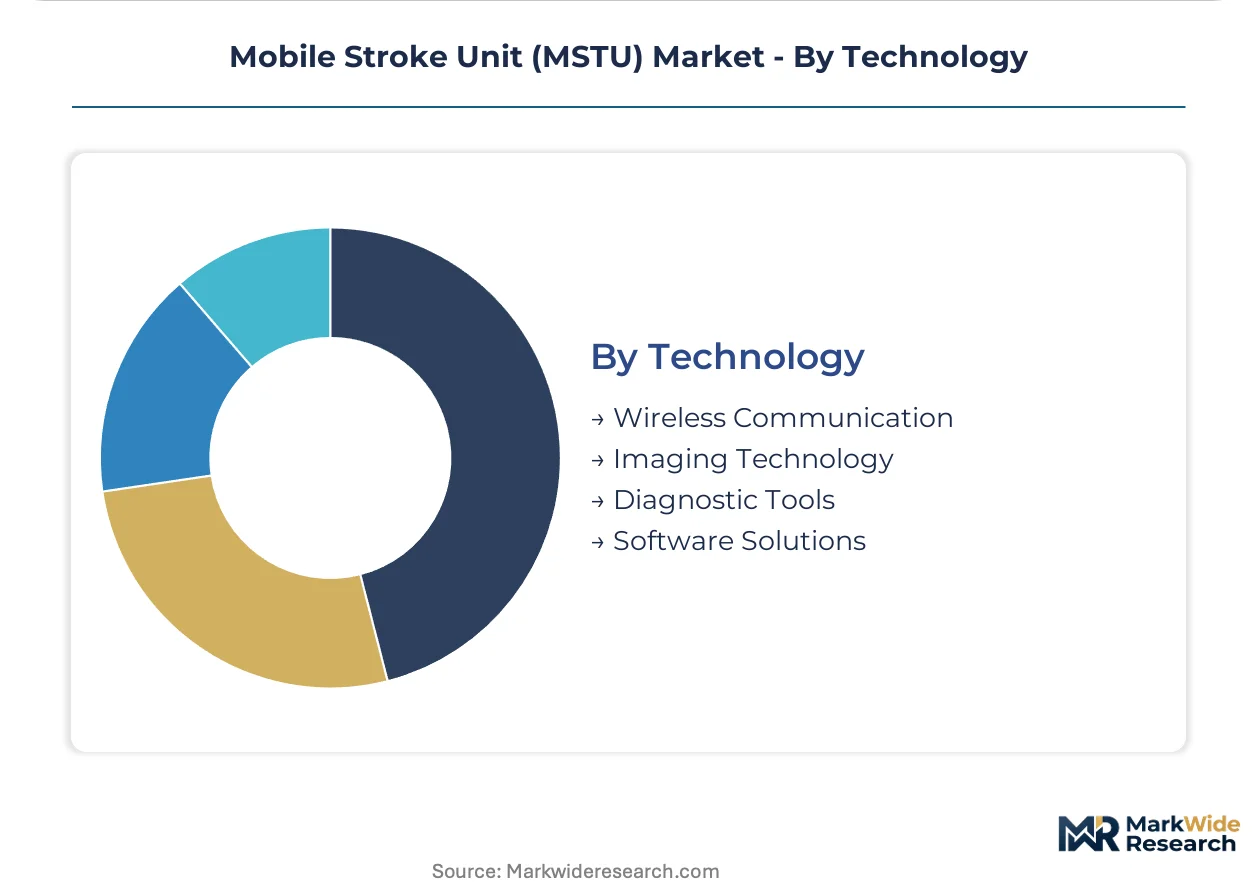
Technology:
Technology segmentation tracks the unbundling of integrated systems into discrete procurement categories.
- Wireless Communication:High-bandwidth data transmission systems enabling real-time imaging relay. FCC spectrum allocation in the United States and comparable national frameworks shape equipment compatibility requirements.
- Imaging Technology:CT reconstruction algorithms and detector arrays optimized for mobile power constraints. FDA premarket review pathways for novel diagnostic technologies are compressing development timelines.
- Diagnostic Tools:Hemorrhagic versus ischemic stroke classification systems including AI-enabled analysis. Emergency medical services in the United States are piloting machine learning integration into regulatory pathways.
- Software Solutions:Platform integration and data format compatibility systems. German procurement departments are separating software update contracts from hardware acquisition.
Wireless Communication anchors current infrastructure investment. Diagnostic Tools are expanding most quickly as AI classification gains regulatory traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys more Mobile Stroke Units per capita than any other nation, while the United States concentrates absolute fleet volume in metropolitan hospital networks. Regulatory frameworks and reimbursement policies diverge sharply between these two markets, creating distinct procurement patterns.
United States
The FDA breakthrough device designation accelerates premarket review for portable stroke diagnostics, compressing product development timelines. Medicare reimbursement code development remains unresolved, constraining fleet expansion feasibility across health system budgets. Urban hospital networks in Chicago, Houston, and Los Angeles pilot AI-enabled image analysis to reduce neurologist consultation bottlenecks.
Germany
KBA vehicle certification mandates specific radiological safety configurations for ambulance chassis modifications. National stroke registry standards administered through regional medical associations require response time documentation that favors metropolitan deployment. Emergency medical services fleets in Berlin, Munich, and Hamburg are restructuring acute care networks around neurological intervention targets.
United Kingdom
NHS England stroke pathway guidelines emphasize pre-hospital thrombolytic administration where transport times exceed 60 minutes. The Medicines and Healthcare products Regulatory Agency oversees portable imaging system approvals alongside EU MDR alignment post-Brexit. London Ambulance Service and West Midlands regional networks evaluate shared MSTU access models over capital acquisition.
Japan
PMDA regulatory pathways for novel diagnostic technologies maintain rigorous clinical evidence requirements that extend product development cycles. METI industrial policy supports domestic medical device manufacturing through targeted R&D subsidies. Stroke centers in Tokyo, Osaka, and Nagoya metropolitan areas test telemedicine-enabled pre-hospital consultation systems.
Canada
Health Canada premarket review for portable CT systems follows a parallel pathway to FDA 510(k) submissions, enabling synchronized North American launches. Provincial health authorities in Ontario and Alberta pilot MSTU deployment through public-private partnership structures. Toronto and Calgary urban clusters concentrate operational trials with integrated wireless communication infrastructure.
Mobile Stroke Unit (MSTU) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with imaging equipment vendors commanding premium positions and ambulance fabricators competing on customization flexibility. The portable CT scanner segment concentrates around a limited manufacturer base due to specialized radiological certification requirements. Three archetypes dominate: diversified medical technology conglomerates with portable imaging portfolios, dedicated ambulance modification specialists, and telemedicine platform integrators. Competitive moves center on strategic partnerships between imaging manufacturers and vehicle fabricators, plus software convergence plays that synchronize wireless communication protocols.
Among diversified medical technology conglomerates, Siemens Healthineers and GE HealthCare anchor the imaging equipment tier through portable CT scanner portfolios. Frazer Ltd. exemplifies the ambulance modification specialist archetype, focusing on emergency vehicle customization. MEYTEC GmbH Informationssysteme occupies a position within the telemedicine integration segment, connecting mobile units to receiving stroke centers.
| Leading Market Players |
|---|
| Demers Ambulances |
| Frazer Ltd. |
| Siemens Healthineers |
| GE HealthCare |
| Excellance Inc. |
| Tri-Star Industries Ltd. |
| MEYTEC GmbH Informationssysteme |
| NeuroLogica Corp. |
| Falck A/S |
| Others |
Supply & Pricing Matrix
KBA vehicle certification for radiological safety configurations gates qualified supply access for German EMS fleets and anchors premium-tier pricing for portable CT scanner integrations. Municipal procurement departments unbundle after-sales service contracts from equipment purchases, forcing manufacturers to compete on discrete maintenance pricing and compressing margins across European emergency medical services.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for emergency response vehicle chassis as municipal fleets standardize on modular retrofit packages. Three-tier pricing structure across premium, standard, and economy levels reflects radiological certification grade and wireless communication bandwidth capability. Cost compression in telemedicine equipment is intensifying because FDA breakthrough device designations are accelerating hardware refresh cycles. Hospital networks exhibit the least price sensitivity due to integrated stroke center budgets, while municipal EMS authorities face the tightest capital constraints.
Supply Chain Analysis
Single-source vulnerability sits with specialized portable CT scanner manufacturers in Germany and the United States, where Siemens Healthineers and GE HealthCare anchor the certified radiological equipment base. The supply chain draws from precision-machined detector arrays, high-density shielding alloys, and medical-grade wireless transmission modules. Tariff exposure on German-manufactured vehicle chassis components creates procurement risk for North American fleet operators. Distribution runs through direct manufacturer-to-health-system contracts with limited aftermarket channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mobile Stroke Unit market functions as a geographic-arbitrage play: FDA breakthrough device pathways in the United States compress regulatory timelines versus PMDA rigor in Japan, lowering effective R&D cost burdens for manufacturers prioritizing North American launches.
For Market Incumbents: Anchor technology leadership through backward integration into AI-enabled diagnostic software development, countering emerging telemedicine platform integrators threatening hardware commoditization. Deepen captive supply of portable CT scanner detector arrays to defend against single-source concentration risks in radiological component markets. For New Entrants and Emerging Players: Rural rehabilitation centers in Canada represent an underserved buyer archetype with limited MSTU access and flexible procurement timelines through provincial public-private partnership structures. Target inter-facility patient transport contracts with post-acute facilities as the most penetrable application segment, leveraging standardized wireless communication protocols to bypass neurologist staffing bottlenecks. For Investors and Strategic Acquirers: Valuations sit cheapest among ambulance modification specialists lacking integrated imaging portfolios, presenting consolidation targets for diversified medical technology conglomerates seeking vehicle fabrication capabilities. Watch Medicare reimbursement code finalization as the critical inflection signal dictating fleet expansion feasibility across United States health system budgets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated premarket review compresses product development timelines for portable imaging systems. |
| Hospital System Partnership | Academic stroke centers provide clinical validation sites and anchor reference customer networks. |
| Software Companion Development | AI-enabled hemorrhagic-ischemic classification reduces neurologist consultation bottlenecks during transport. |
| Reimbursement Strategy | Medicare coverage determinations dictate capital allocation feasibility across municipal EMS budgets. |
| CE Marking Pathway | EU MDR alignment post-Brexit enables synchronized European launches with KBA-certified vehicle integrations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with EMS fleet managers, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, German national stroke registry documentation, and hospital procurement records. Bottom-up installation tracking and top-down health system budget analysis were triangulated to cross-validate market sizing.
Segment-weighting approaches distributed value across product type, application, end user, and technology dimensions, with portable CT scanner configurations receiving distinct treatment due to specialized radiological certification requirements. CAGRs were derived from modeled fleet expansion trajectories and equipment replacement cycles. Forecast inputs incorporated wireless communication infrastructure deployment timelines and evolving national payer coverage determinations.
Underlying measurement precision varies by segment; emergency medical services end user data carry tighter precision than rehabilitation center estimates due to centralized municipal procurement documentation. Forecasts reflect assumptions about regulatory pathway timelines and reimbursement code development that could shift with policy changes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Endovascular Therapy Devices Market
Cardiovascular Devices
Cardiac Medical Device Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Anticoagulation Market
Cardiovascular Devices
Spain Cardiovascular Devices Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
Chile Cardiovascular Devices Market
Cardiovascular Devices
Middle East and Africa Heart Valve Repair and Replacement Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Global Coil Wound Devices Market
Cardiovascular Devices
Global Pediatric Interventional Cardiology Market
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
Global PTA Balloon Catheter Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Centrifugal Blood Pumps Market