
 Cardiovascular Ultrasound Market | 2026-2036
Cardiovascular Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular Ultrasound Market Insights
Software-defined imaging analytics is pivoting how cardiovascular ultrasound vendors monetize hardware deployments. GE HealthCare leverages cloud-based AI quantification tools to extend recurring revenue beyond initial system sales. Koninklijke Philips sustains competitive positioning through integrated informatics platforms that anchor hospital enterprise contracts. Siemens Healthineers dominates the premium segment with advanced automation features that reduce operator dependency in busy cardiac catheterization laboratories.
Cardiovascular ultrasound employs high-frequency sound waves, typically 2-15 MHz, to generate real-time images of cardiac structures, blood flow dynamics, and vascular anatomy for diagnostic and procedural guidance. Phased array technology leads system shipments due to its compact probe footprint optimized for transthoracic imaging between rib spaces. Portable ultrasound represents the fastest-expanding product category as cardiology clinics and mobile health units prioritize bedside and field-deployable diagnostics over fixed-cart installations. Doppler ultrasound, spanning both continuous wave and pulsed wave modalities, commands concentrated margin pools where hemodynamic assessment integrates with interventional planning.
FDA premarket review pathways for AI-enabled echocardiography software shape product development timelines and clinical validation requirements for US market entry. The EU Medical Device Regulation imposes stricter conformity assessment procedures on cardiovascular ultrasound systems sold in European member states, elevating documentation burdens for manufacturers. Stakeholders must monitor how reimbursement policy evolution for point-of-care cardiac imaging influences capital allocation between centralized hospital departments and distributed ambulatory settings.
Market Dynamics
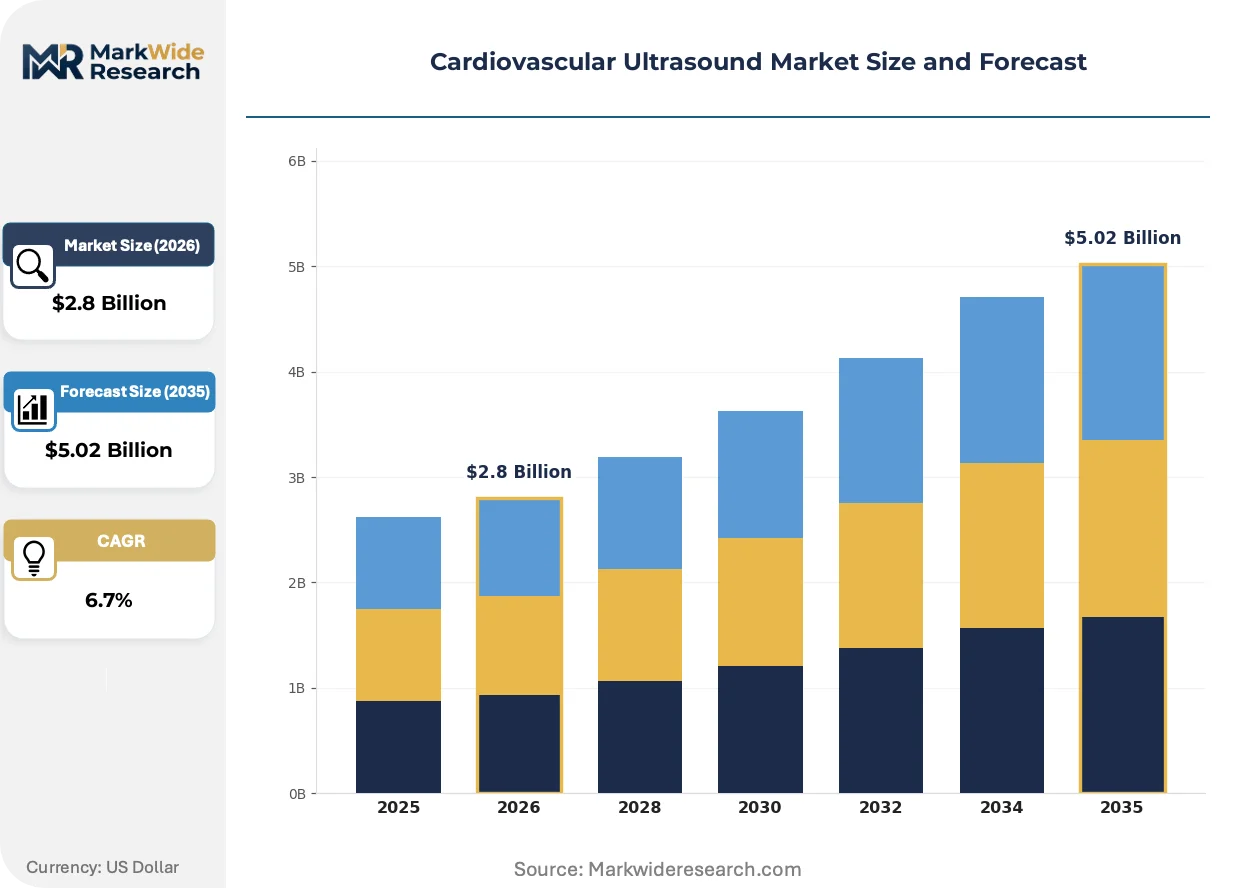
Software-defined imaging analytics is compressing hardware replacement cycles while redirecting vendor revenue toward recurring cloud subscriptions and AI-enabled service tiers.
Growth Catalysts
- AI-enabled diagnostic workflows:FDA premarket review pathways for machine-learning echocardiography tools accelerate clinical validation investments and expand reimbursable indications for automated quantification.
- Point-of-care deployment:Hospital cardiology departments prioritize portable systems for bedside hemodynamic assessment, reducing dependency on centralized imaging suites.
- Integrated informatics platforms:Enterprise health networks standardize echocardiography protocols across multi-site service lines, creating vendor lock-in through data interoperability requirements.
Market Restraints
- Semiconductor supply concentration:Phased array transducer manufacturing depends on specialized piezoelectric crystal supplies concentrated in East Asian foundries, exposing procurement to geopolitical disruption.
- EU Medical Device Regulation compliance:Stricter conformity assessment procedures for cardiovascular ultrasound systems elevate documentation burdens and extend time-to-market for European commercialization.
- Operator skill dependency:Doppler hemodynamic assessment requires specialized cardiologist training that limits deployment velocity in resource-constrained settings.
Strategic Opportunities
- Rural and mobile health expansion:Underserved United States counties and emerging market peripheries present untapped demand for handheld cardiac screening devices operated by non-specialist clinicians.
- Interventional guidance integration:Real-time 3D echocardiography is converging with catheter-based structural heart procedures, opening premium pricing tiers in cardiac catheterization laboratories.
- Reimbursement policy evolution:Medicare coverage determinations for point-of-care cardiac imaging create tailwinds for ambulatory clinic capital allocation away from hospital-based departments.
Industry Challenges
- Sonographer workforce scarcity:Cardiac imaging specialization requires extended fellowship training that health systems struggle to staff amid competing diagnostic radiology demands.
- Legacy system integration:PACS interoperability failures between incumbent ultrasound platforms and cloud-native AI tools fragment enterprise imaging workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Ultrasound Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Ultrasound, Doppler Ultrasound, 3D Ultrasound, Portable Ultrasound, Handheld Ultrasound Application: Cardiac Imaging, Vascular Imaging, Peripheral Vascular Assessment, Echocardiography, Stress Testing End User: Cardiology Clinics, Diagnostic Centers, Ambulatory Surgical Units, Academic & Research Institutes, Mobile Health Units Technology: Phased Array, Continuous Wave Doppler, Pulsed Wave Doppler, Contrast Echocardiography, Speckle Tracking |
| Companies Covered | GE HealthCare, Koninklijke Philips, Siemens Healthineers, Canon Medical Systems, Samsung Medison, Shenzhen Mindray Bio-Medical Electronics, Fujifilm Holdings, Hitachi, Esaote, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Ultrasound Market Trends and Innovations
Real-time computational imaging and automated measurement algorithms are displacing manual interpretation workflows while compressing examination duration and operator variability.
Shear wave elastography for myocardial tissue characterization is converging with conventional B-mode imaging to enable non-invasive fibrosis assessment without biopsy. Academic medical centers in Germany and Japan deploy these hybrid systems for cardiomyopathy staging. The technology is converging with existing echocardiography infrastructure to extend hardware utility rather than trigger replacement cycles.
EU AI Act risk classification rules for medical device software reshape development roadmaps for vendors targeting European health systems. High-risk algorithmic diagnostic tools face mandatory conformity assessment and post-market monitoring obligations. Cardiovascular ultrasound AI modules fall under intensified scrutiny, forcing manufacturers to restructure clinical validation protocols and documentation practices ahead of 2025 implementation deadlines.
Subscription-based service unbundling separates hardware ownership from software access and algorithm updates. Hospital procurement committees in the United States increasingly favor operational expenditure models over capital-intensive system purchases. This financing pivot concentrates negotiating leverage with integrated delivery networks that can aggregate multi-site contract volume.
Cardiovascular Ultrasound Market Segmentation
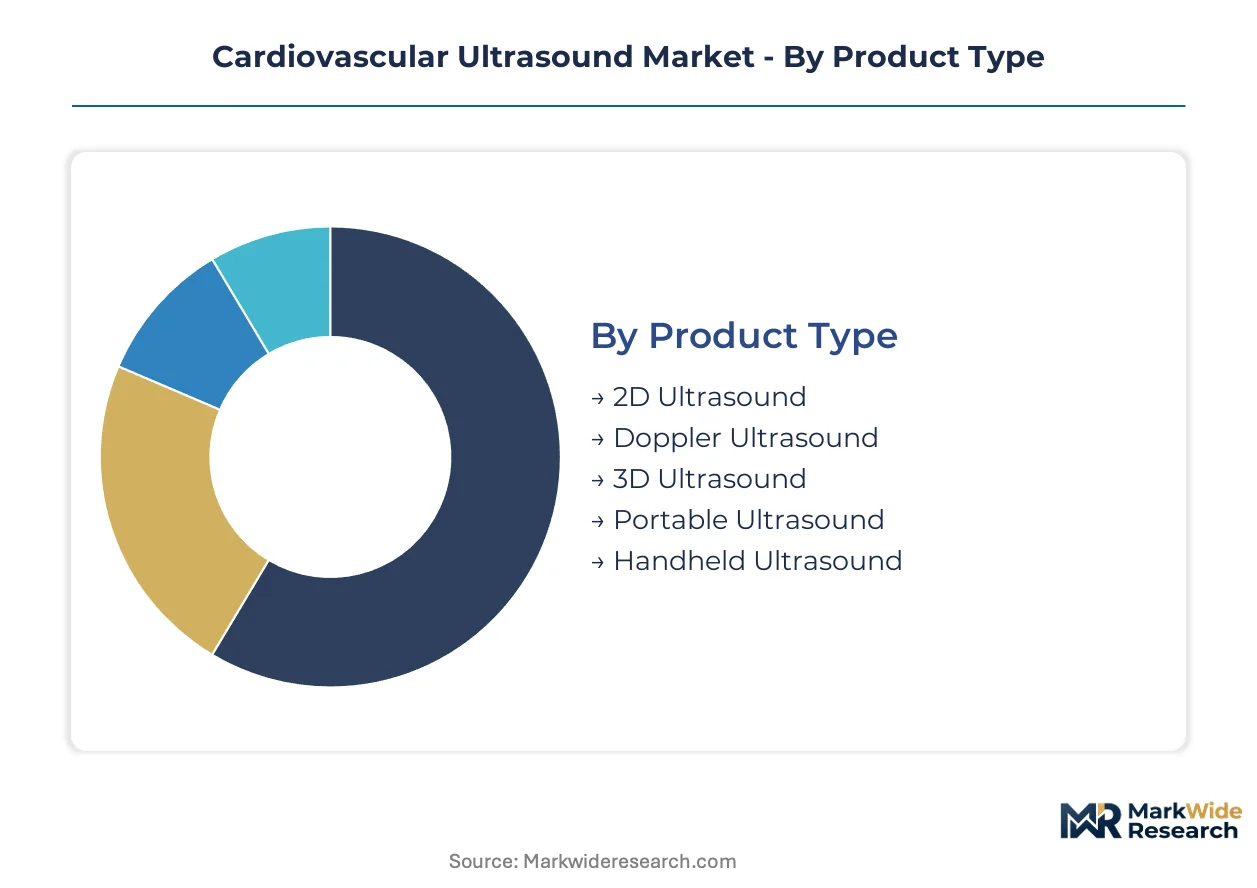
Segmentation in cardiovascular ultrasound reveals how purchasing committees allocate capital across performance tiers and deployment settings. Hospital procurement teams weigh image resolution requirements against mobility needs when selecting system configurations.
Product Type:
Capital expenditure thresholds and point-of-care deployment strategies drive product selection across acute care and ambulatory networks.
- 2D Ultrasound:Conventional B-mode imaging generates cross-sectional cardiac views using linear and curved array transducers. Hospital cardiology departments in the United States standardize on these systems for routine transthoracic protocols, though software upgrade paths now extend utility beyond traditional replacement cycles.
- Doppler Ultrasound:Continuous wave and pulsed wave modalities quantify blood flow velocity and pressure gradients across valves and vessels. Cardiac catheterization laboratories concentrate demand here, where hemodynamic assessment integrates with interventional planning and procedural guidance.
- 3D Ultrasound:Real-time volumetric reconstruction enables en face visualization of cardiac structures from transthoracic and transesophageal approaches.
- Portable Ultrasound:Cart-based systems with battery operation and wireless connectivity address bedside imaging requirements.
- Handheld Ultrasound:Smartphone-connected probes and pocket-sized devices expand screening access in mobile health deployments.
Volume sits with 2D systems; growth tilts toward handheld and portable configurations.
Application:
Clinical indication breadth determines reimbursement eligibility and capital justification for departmental acquisition committees.
- Cardiac Imaging:Transthoracic and transesophageal echocardiography constitute the foundational application, generating structural and functional assessments of myocardial performance. United States integrated delivery networks anchor procurement volume here, where bundled payment models incentivize diagnostic accuracy.
- Vascular Imaging:Carotid, aortic, and peripheral arterial assessment extends ultrasound utility beyond the heart. Academic medical centers in Germany deploy these protocols for preoperative surgical planning, particularly in endovascular intervention candidacy screening.
- Peripheral Vascular Assessment:Deep vein thrombosis detection and chronic venous insufficiency evaluation serve ambulatory clinic workflows.
- Echocardiography:Dedicated cardiac ultrasound protocols encompass standard views and measurement conventions.
- Stress Testing:Exercise and pharmacological stress echocardiography assess ischemic burden under hemodynamic challenge.
Procedure volume concentrates in cardiac imaging; vascular applications are climbing the fastest.
End User:
Site-of-care economics and reimbursement differentials reshape where cardiovascular ultrasound capital lands.
- Cardiology Clinics:Specialist-owned practices and hospital outpatient departments perform elective echocardiography with dedicated systems. Medicare reimbursement rate variations between facility and non-facility settings influence equipment financing preferences in the United States.
- Diagnostic Centers:Independent imaging facilities aggregate multi-modality diagnostics including echocardiography, vascular ultrasound, and nuclear cardiology. Volume-based purchasing agreements with payers in Japan concentrate procurement decisions here.
- Ambulatory Surgical Units:Preoperative cardiac clearance and same-day procedure monitoring create demand for compact systems.
- Academic & Research Institutes:Teaching hospitals and university medical centers prioritize research-enabled platforms with advanced quantification tools.
- Mobile Health Units:Rural screening programs and disaster response deployments utilize battery-operated handheld devices.
Diagnostic centers capture the largest installed base; mobile health units are gaining share fastest.
Technology:
Transducer architecture and signal processing methods differentiate performance tiers and operator dependency levels.
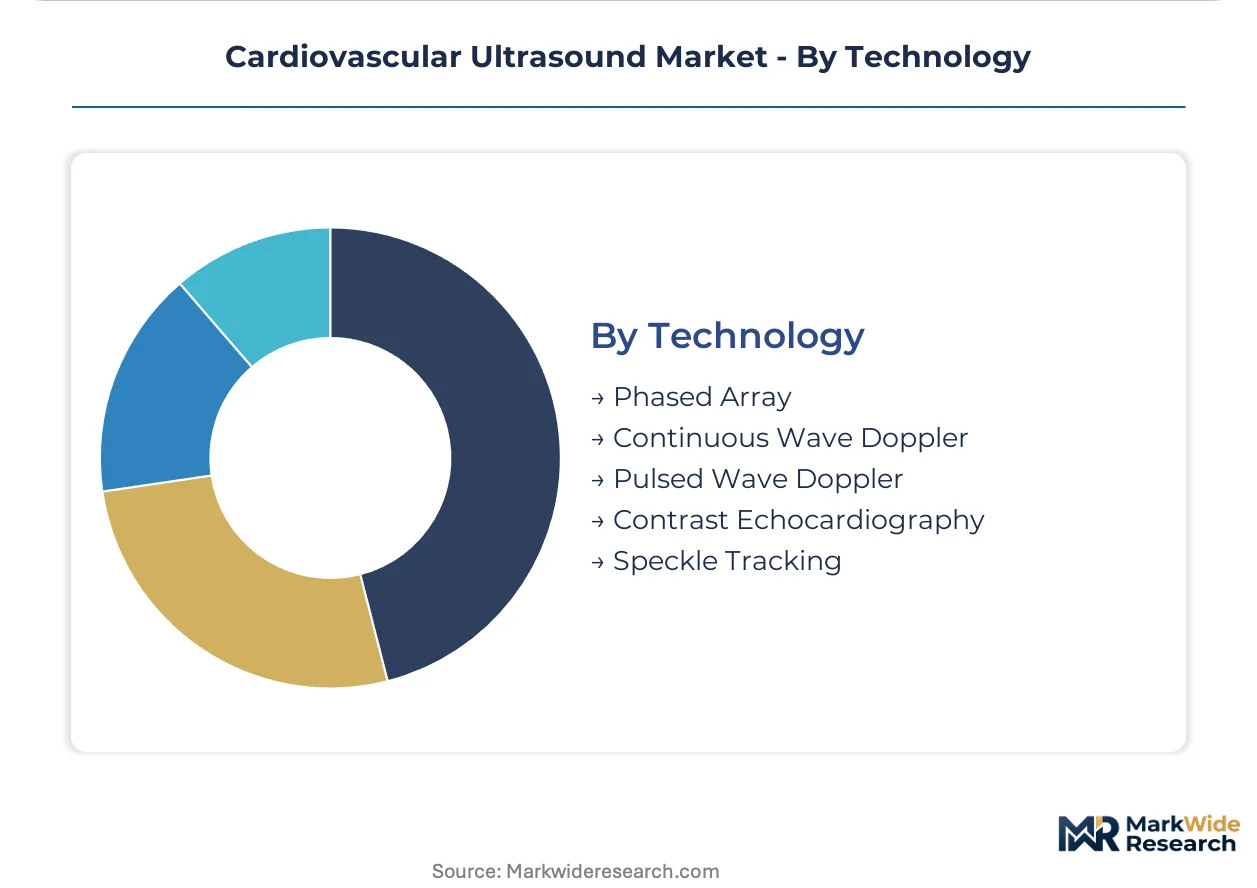
- Phased Array:Electronic beam steering through small-aperture transducers optimizes cardiac imaging between rib spaces. Siemens Healthineers and GE HealthCare anchor premium system shipments with advanced phased array platforms targeting cardiac catheterization laboratories.
- Continuous Wave Doppler:Uninterrupted ultrasound transmission enables high-velocity flow measurement without aliasing artifacts. Interventional cardiologists in France rely on this modality for transvalvular gradient assessment during structural heart procedures.
- Pulsed Wave Doppler:Range-gated sampling permits velocity measurement at specific anatomical locations.
- Contrast Echocardiography:Microbubble enhancement agents improve endocardial border delineation and perfusion assessment.
- Speckle Tracking:Pattern recognition algorithms quantify myocardial deformation and strain mechanics.
Phased array dominates current shipments; speckle tracking shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiovascular ultrasound system manufacturing concentrates in Germany, Japan, and the United States, while consumption demand spreads across hospital networks in North America, Western Europe, and East Asia. Production capacity for phased array transducers and premium imaging platforms remains geographically concentrated, creating supply chain exposure to East Asian component sourcing.
United States
Integrated delivery networks in Texas, California, and the Northeast Corridor standardize echocardiography protocols across multi-site cardiology service lines. FDA premarket review pathways for AI-enabled diagnostic tools reshape product development timelines for manufacturers targeting US market entry. Academic medical centers in Boston and the Research Triangle deploy advanced 3D echocardiography systems for structural heart procedure guidance.
Germany
University hospitals in Bavaria and Baden-Württemberg lead European adoption of shear wave elastography for myocardial tissue characterization. EU Medical Device Regulation conformity assessment procedures elevate documentation burdens for cardiovascular ultrasound systems sold in German health networks. Industrial clusters around Munich and Stuttgart host precision transducer manufacturing operations serving domestic and export demand.
Japan
Volume-based purchasing agreements between diagnostic centers and payers concentrate procurement decisions in Tokyo, Osaka, and Nagoya metropolitan areas. METI industrial policy supports domestic manufacturing of advanced medical imaging equipment including portable ultrasound platforms. Prefectural health systems prioritize compact systems for aging population cardiac screening in rural Honshu and Kyushu regions.
China
Provincial hospital networks in the Yangtze River Delta and Pearl River Delta expand installed base of mid-tier echocardiography systems for cardiology department modernization. NMPA regulatory pathways for imported and domestically manufactured ultrasound devices create differentiated market access timelines. Shenzhen-based electronics manufacturing clusters supply transducer components and handheld device assembly for domestic consumption and export markets.
India
Cardiology clinics in Maharashtra, Karnataka, and Delhi-NCR drive demand for cost-optimized portable systems amid expanding private healthcare infrastructure. CDSCO medical device registration requirements influence product portfolio decisions for multinational manufacturers entering Indian markets. Tier-2 city hospital networks in Gujarat and Tamil Nadu prioritize bedside imaging capabilities over centralized radiology department dependency.
Cardiovascular Ultrasound Market Competitive Landscape
Top-tier vendors anchor premium-tier system shipments, while mid-tier specialists and regional fabricators compete on price-accessible portable configurations. The vendor landscape stratifies across three archetypes: diversified health technology conglomerates with enterprise informatics integration, dedicated ultrasound specialists with transducer manufacturing expertise, and emerging electronics manufacturers leveraging component cost advantages. Competitive moves concentrate on AI-enabled software licensing arrangements and cloud-native service tier unbundling.
Within the diversified health technology tier, GE HealthCare, Koninklijke Philips, and Siemens Healthineers exemplify positioning through integrated informatics platforms and enterprise contract anchoring. These US, Dutch, and German-origin entities respectively represent archetypes of cloud-based AI quantification tools, hospital enterprise system integration, and premium automation features for catheterization laboratory deployment. Their collective presence shapes procurement standards for integrated delivery networks standardizing echocardiography protocols across multi-site operations.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips |
| Siemens Healthineers |
| Canon Medical Systems |
| Samsung Medison |
| Shenzhen Mindray Bio-Medical Electronics |
| Fujifilm Holdings |
| Hitachi |
| Esaote |
| Others |
Pricing and Supply Chain Analysis
Integrated delivery network procurement committees in the United States anchor pricing power through multi-site volume aggregation, compressing vendor margins while elevating subscription-based service tiers over capital-intensive system purchases. This buyer concentration forces manufacturers to unbundle hardware ownership from software access, reshaping revenue recognition across the cardiovascular ultrasound value chain.
Pricing Analysis
Margin tightening in mid-tier portable systems reflects intensified competition from Shenzhen-based electronics manufacturers leveraging component cost advantages. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation sophistication and AI-enabled quantification depth, with Siemens Healthineers and GE HealthCare commanding brand premiums in catheterization laboratory deployments. Cost-down pressure on handheld configurations accelerates because smartphone-connected probe makers target rural screening programs with aggressive operational expenditure models. Price sensitivity concentrates among independent diagnostic centers in Japan and tier-2 city hospitals in India, while academic medical centers in Germany exhibit lowest sensitivity due to research-enabled platform requirements.
Supply Chain Analysis
Domestic-content mandates under China's NMPA pathway and India's PLI scheme for medical devices are forcing multinational manufacturers to localize final assembly and source transducer crystals from approved regional foundries. Phased array transducer manufacturing draws from specialized piezoelectric crystal supplies concentrated in East Asian foundries, with Japan and South Korea hosting precision ceramic operations critical to beam-steering performance. Single-source vulnerability persists in high-purity lead zirconate titanate substrates and application-specific integrated circuits for signal processing. Distribution runs through hospital GPO contracts in the United States, volume-based purchasing agreements in Japan, and provincial procurement consortia in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiovascular ultrasound vendor consolidation accelerates as FDA premarket validation requirements for AI-enabled diagnostics force sub-scale players to exit or sell. Software-defined revenue models favor incumbents with cloud infrastructure already deployed across integrated delivery networks.
For Market Incumbents: Extend enterprise informatics platform penetration through multi-site echocardiography protocol standardization, locking hospital systems into data interoperability ecosystems that raise switching costs. Acquire handheld ultrasound specialists with FDA-cleared AI modules to defend against emerging entrants targeting point-of-care deployment. Prioritize backward integration into transducer crystal supply through joint ventures with Japanese ceramic manufacturers, mitigating East Asian geopolitical exposure.
For New Entrants and Emerging Players: Mobile health units in underserved United States counties present the most penetrable white-space target, where non-specialist clinicians require simplified handheld devices for cardiac screening without centralized radiology support. Rural prefectural health systems in Japan's Honshu and Kyushu regions offer secondary expansion terrain amid aging population diagnostic demand. Partner with telemedicine platform providers to embed ultrasound image transmission into remote cardiology consultation workflows, bypassing direct hospital procurement committee barriers.
For Investors and Strategic Acquirers: The window for entry favors mid-tier portable system specialists with CE marking pathway progress and existing hospital pilot deployments in Germany or Japan. Long-term viability hinges on recurring software revenue attachment rates exceeding hardware replacement cycles. Acquisition target archetype: ultrasound OEMs with proprietary speckle tracking algorithms and cloud-native AI quantification tools already validated in academic medical center settings. Watch FDA breakthrough device designation grants for automated ejection fraction measurement as the inflection signal indicating which AI modules will capture reimbursable indication expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for AI Echocardiography Module | Premarket review pathway acceleration enables reimbursable automated quantification claims in United States integrated networks. |
| CE Marking Pathway Under EU MDR | Conformity assessment completion unlocks German university hospital procurement and EU-wide commercialization. |
| Hospital System Partnership for Enterprise Informatics | Multi-site protocol standardization creates vendor lock-in through PACS interoperability requirements and data migration friction. |
| Software Companion Development for Handheld Devices | Smartphone-connected probe differentiation shifts competitive basis from hardware specifications to algorithm accuracy. |
| Reimbursement Strategy for Point-of-Care Imaging | Medicare coverage determination alignment directs capital allocation toward ambulatory clinics away from hospital departments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across ultrasound product managers, hospital biomedical engineers, GPO contracts managers, and interventional cardiologists. FDA 510(k) clearances, EU MDR technical documentation, and NMPA registration databases supplied regulatory trajectory intelligence. Bottom-up installed base estimates triangulated against top-down health system capital expenditure surveys.
Data-stream reconciliation across shipment volumes, average selling price trajectories, and software attachment rates informed analytical framework construction across the projection horizon. Segmentation dimensions modeled include product type tier, deployment setting, technology architecture, and regional regulatory cluster. CAGRs derived from curve-fitting historical replacement cycles against AI-enabled upgrade adoption patterns, with shear wave elastography penetration and point-of-care reimbursement evolution as cardiovascular-specific forecast inputs.
Caveats apply where FDA guidance evolution on machine-learning diagnostic tools or EU AI Act implementation delays could materially shift the outlook. Semiconductor supply disruptions in East Asian foundries and sonographer workforce scarcity in United States health systems represent additional revision triggers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
Renal Denervation Devices Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Atherosclerotic Renovascular Treatment Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
Iliac Artery Stents Market
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Global Arterial Stents Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Acute Surgical Mechanical Circulatory Support System Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Abdominal Aortic Aneurysm (AAA) Repair Devices Market
Cardiovascular Devices
Vena Cava Clips and Filters Market