
 Global Breast Lesion Localization Methods Market | 2026-2036
Global Breast Lesion Localization Methods Market Size, Share, and Industry Trends Forecast 2026-2036
Global Breast Lesion Localization Methods Market Foresight
Radiologist workforce density is bifurcating market access between mature healthcare systems and emerging economies where trained imagers remain scarce. Hologic Inc. leverages its integrated mammography-to-surgery platform to dominate imaging-guided localization workflows. BD sustains broad hospital contracting power through its multi-modality device portfolio spanning wire and seed technologies. Merit Medical Systems anchors its position in interventional radiology suites with specialized delivery systems.
Breast lesion localization methods encompass technologies that mark non-palpable breast abnormalities for surgical or diagnostic retrieval, typically employing radiopaque wires, radioactive seeds, magnetic markers, or radar reflectors detectable through intraoperative probes or imaging systems. These methods serve the critical function of enabling precise tissue removal while minimizing excision volumes and preserving cosmetic outcomes. Wire localization retains the largest installed base across cancer treatment centers, though magnetic marker localization represents the fastest-growing segment as facilities seek radiation-free alternatives that eliminate scheduling constraints between localization and surgery. Radar localization occupies a premium niche where real-time intraoperative tracking commands higher reimbursement.
FDA 510(k) clearance pathways govern device commercialization in the United States, while EMA coordination with notified bodies enforces MDR compliance for European market access. Japan's PMDA maintains distinct clinical trial requirements that extend approval timelines relative to other developed markets. Stakeholders must monitor evolving reimbursement coding for magnetic and radar modalities as payors recalibrate coverage decisions against long-term cost-effectiveness evidence.
Market Dynamics
Magnetic marker localization is compressing procedural timelines by eliminating the radiation safety protocols and scheduling dependencies that constrain wire-based workflows in ambulatory surgical centers.
Growth Catalysts
- FDA 510(k) clearance streamlining:Expedited premarket notification pathways for predicate device comparisons accelerate magnetic and radar localization technologies into commercial distribution, reducing time-to-revenue for manufacturers.
- Ambulatory surgical center expansion:CMS reimbursement parity for outpatient breast procedures channels localization volumes away from inpatient settings, creating concentrated demand for same-day localization-to-surgery solutions.
- Radiologist workforce density gaps:Shortages of trained breast imagers in emerging economies drive demand for technologies requiring less specialized interpretation, expanding addressable markets beyond traditional screening infrastructure.
Market Restraints
- Radioactive seed disposal costs:Iodine-125 and palladium-103 seed technologies impose ongoing radioactive waste management liabilities that compress margins for facilities without dedicated nuclear medicine infrastructure.
- PMDA clinical trial requirements:Japan's pharmaceutical and medical devices agency mandates extended local validation studies that extend approval timelines by 18-24 months relative to FDA pathways, delaying market entry.
- Wire localization installed base:Capital depreciation cycles and surgeon familiarity with established wire-guided techniques create switching friction that slows magnetic marker penetration in community hospital settings.
Strategic Opportunities
- India screening program expansion:National health mission initiatives targeting breast cancer early detection in tier-2 and tier-3 cities create first-mover advantages for localization technologies compatible with mobile mammography units.
- EU MDR Article 117 convergence:Drug-device combination product regulations for radioactive seeds create compliance complexity that magnetic marker competitors can exploit through simpler device-only classification pathways.
- Radar-reflector same-day surgery:Real-time intraoperative tracking without preoperative localization appointments enables fully integrated breast biopsy-to-excision workflows in high-throughput surgical centers.
Industry Challenges
- Interventional radiology technologist certification:Specialized training requirements for magnetic seed injection and radar probe operation create bottlenecks in procedure scaling, particularly in markets with limited IR specialist pipelines.
- Reimbursement coding fragmentation:Magnetic and radar localization modalities lack standardized CPT codes in US commercial payor networks, forcing prior authorization burdens that delay revenue recognition and create administrative drag.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Breast Lesion Localization Methods Market |
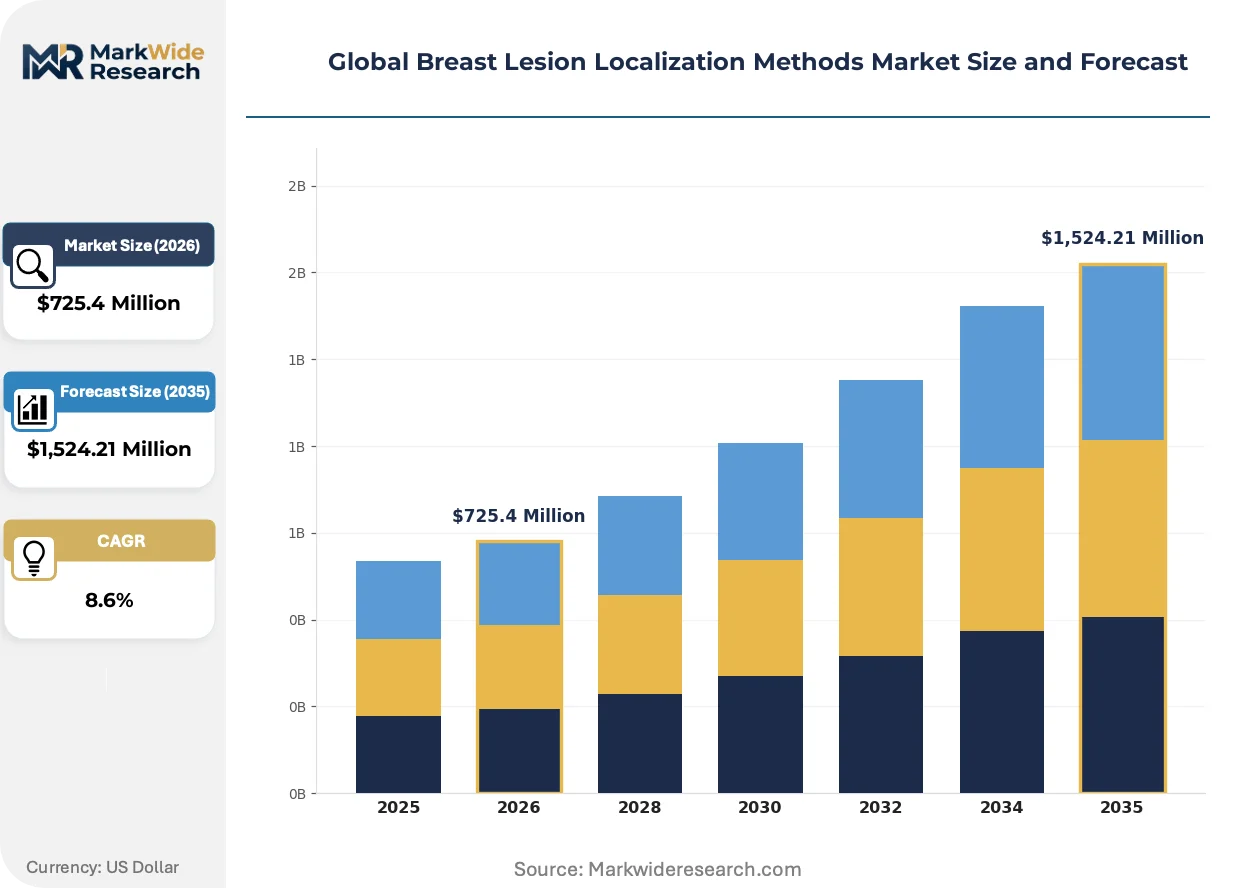
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $1,524.21 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Localization Technique: Wire Localization, Radioactive Seed Localization, Magnetic Marker Localization, Radar Localization Imaging Guidance: Mammography, Ultrasound, MRI, Stereotactic Imaging Clinical Application: Diagnostic Biopsy, Surgical Excision, Preoperative Planning, Lesion Marking Healthcare Facility Type: Specialty Clinics, Cancer Treatment Centers, Diagnostic Laboratories, Ambulatory Surgical Centers |
| Companies Covered | Hologic Inc., BD, Merit Medical Systems, Argon Medical Devices, SOMATEX Medical Technologies GmbH, Cook Medical, Intramedical Imaging, LLC, Stryker, Endomagnetics Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Breast Lesion Localization Methods Market Shifts & Advancements
Non-radioactive localization technologies are restructuring procedural economics by collapsing the coordination overhead between radiology scheduling and surgical theater availability. Three developments are compressing adoption cycles.
Magnetic seed technology is miniaturizing. Sienna+ and Magseed systems now deploy through 20-gauge needles, enabling radiologists to place multiple markers through single access points. Community hospitals in Germany and Japan are adopting these systems to eliminate the 24-48 hour scheduling windows required for radioactive seed decay safety protocols. The technology is miniaturizing procedural footprints while preserving localization precision.
EU MDR technical documentation requirements are intensifying post-market surveillance obligations for radioactive seed manufacturers. Notified bodies now demand extended clinical follow-up data on seed migration rates and extraction completeness, elevating compliance costs for legacy iodine-125 products. European hospital procurement committees are responding by weighting magnetic alternatives more heavily in tender evaluations, accelerating substitution in CE-mark markets.
Same-day localization-to-excision protocols are reshaping surgical scheduling patterns. Ambulatory surgical centers in the United States are unbundling radiology and surgery appointments, enabling patients to complete both procedures within single facility visits. This compression is most visible in Texas and Florida markets where high ASC density supports competitive differentiation through convenience positioning.
Global Breast Lesion Localization Methods Market Segmentation
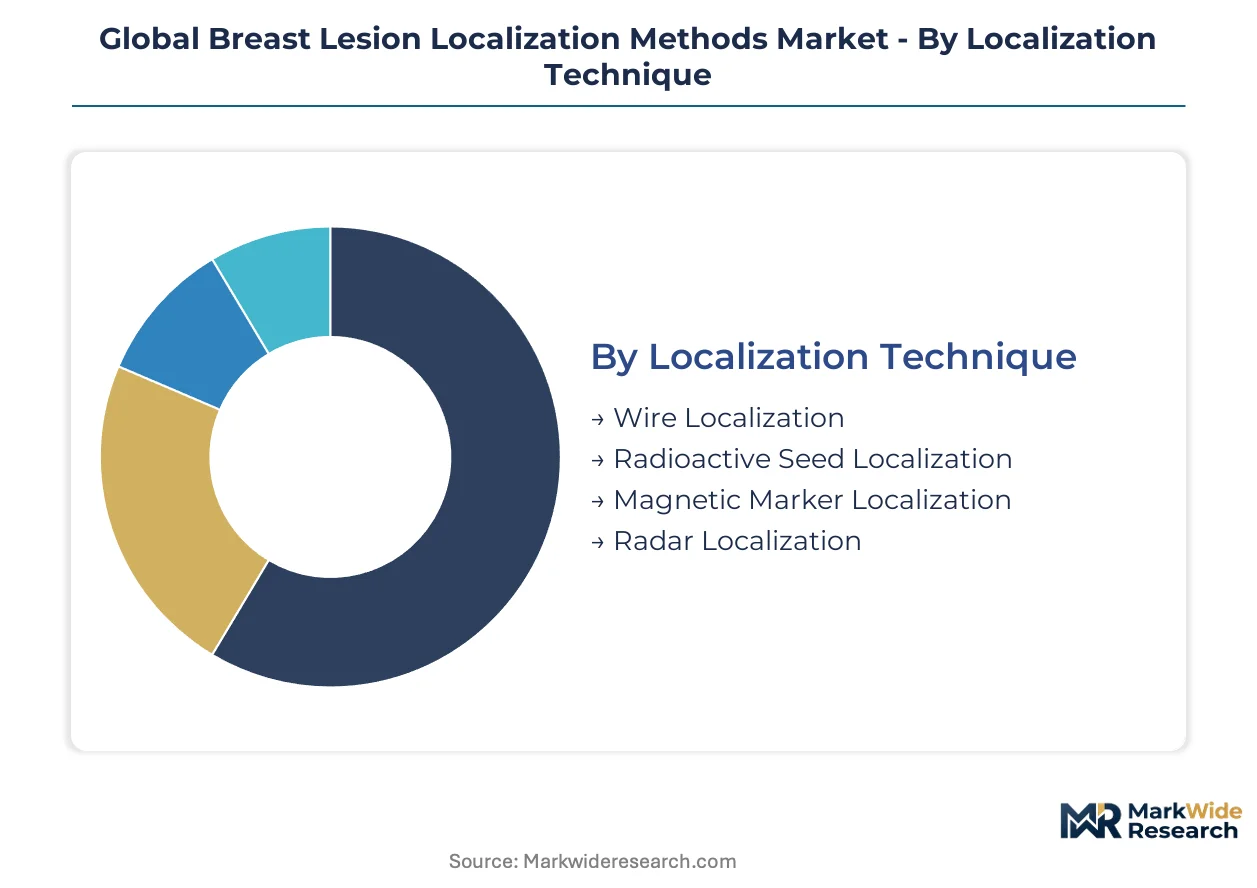
Segmentation in breast lesion localization methods reveals how substitution pressures and facility economics reshape technology deployment across procedural workflows. Understanding these divisions exposes where magnetic and radar modalities displace legacy wire systems.
Localization Technique:
Magnetic marker localization exerts the strongest substitution pressure on radioactive seed and wire-based alternatives, driven by radiation elimination and scheduling compression.
- Wire Localization:Stainless steel or titanium wires with hooked or barbed tips anchor to lesion tissue under imaging guidance. Cancer treatment centers in Germany and Japan retain substantial installed bases where surgeon familiarity and capital depreciation cycles delay switching.
- Radioactive Seed Localization:Iodine-125 or palladium-103 encapsulated seeds emit gamma radiation detectable by intraoperative probes. Facilities in the United States face mounting radioactive waste disposal costs that compress margins and accelerate magnetic alternative evaluation.
- Magnetic Marker Localization:Iron oxide or metallic alloy markers generate detectable magnetic fields without ionizing radiation. Ambulatory surgical centers in Texas and Florida adopt these systems to enable same-day localization-to-excision protocols that eliminate 24-48 hour scheduling windows.
- Radar Localization:Electromagnetic reflectors enable real-time intraoperative tracking through proprietary detection systems. Premium surgical centers command higher reimbursement for integrated biopsy-to-excision workflows.
Wire localization retains volume leadership; magnetic marker localization holds the steepest expansion curve.
Imaging Guidance:
Cost tier stratification separates high-capital MRI and stereotactic systems from portable ultrasound alternatives accessible to community facilities.
- Mammography:X-ray-based compression imaging remains the standard for screening-detected non-palpable lesions. Japan's screening programs drive consistent procedure volumes through dedicated breast imaging suites.
- Ultrasound:Real-time acoustic imaging enables bedside marker placement without radiation exposure. Community hospitals in India deploy portable units for tier-2 and tier-3 city outreach.
- MRI:Magnetic resonance guidance targets occult lesions invisible to mammography or ultrasound. Academic medical centers in the United States concentrate demand for high-value preoperative planning workflows.
- Stereotactic Imaging:Computer-guided coordinate targeting enables sub-millimeter precision for microcalcification clusters. Specialized breast centers integrate these systems with vacuum-assisted biopsy platforms.
Mammography anchors procedure volume; ultrasound is gaining share fastest among imaging modalities.
Clinical Application:
Application maturity varies sharply, with surgical excision commanding premium pricing while diagnostic biopsy faces commoditization from per-procedure reimbursement cuts.
- Diagnostic Biopsy:Tissue sampling for histopathological confirmation precedes definitive treatment decisions. High-throughput centers in Florida process substantial volumes through standardized protocols.
- Surgical Excision:Definitive lesion removal with margin assessment constitutes the revenue-intensive core of localization workflows. German cancer treatment centers prioritize cosmetic outcome preservation through precise tissue targeting.
- Preoperative Planning:Multi-lesion mapping and surgical approach simulation support complex cases. Academic institutions in Japan leverage advanced imaging for treatment pathway optimization.
- Lesion Marking:Temporary or permanent marker placement for surveillance or future intervention. Community hospitals utilize this application for high-risk patient monitoring programs.
Surgical excision generates the highest revenue per procedure; preoperative planning shows the strongest volume acceleration.
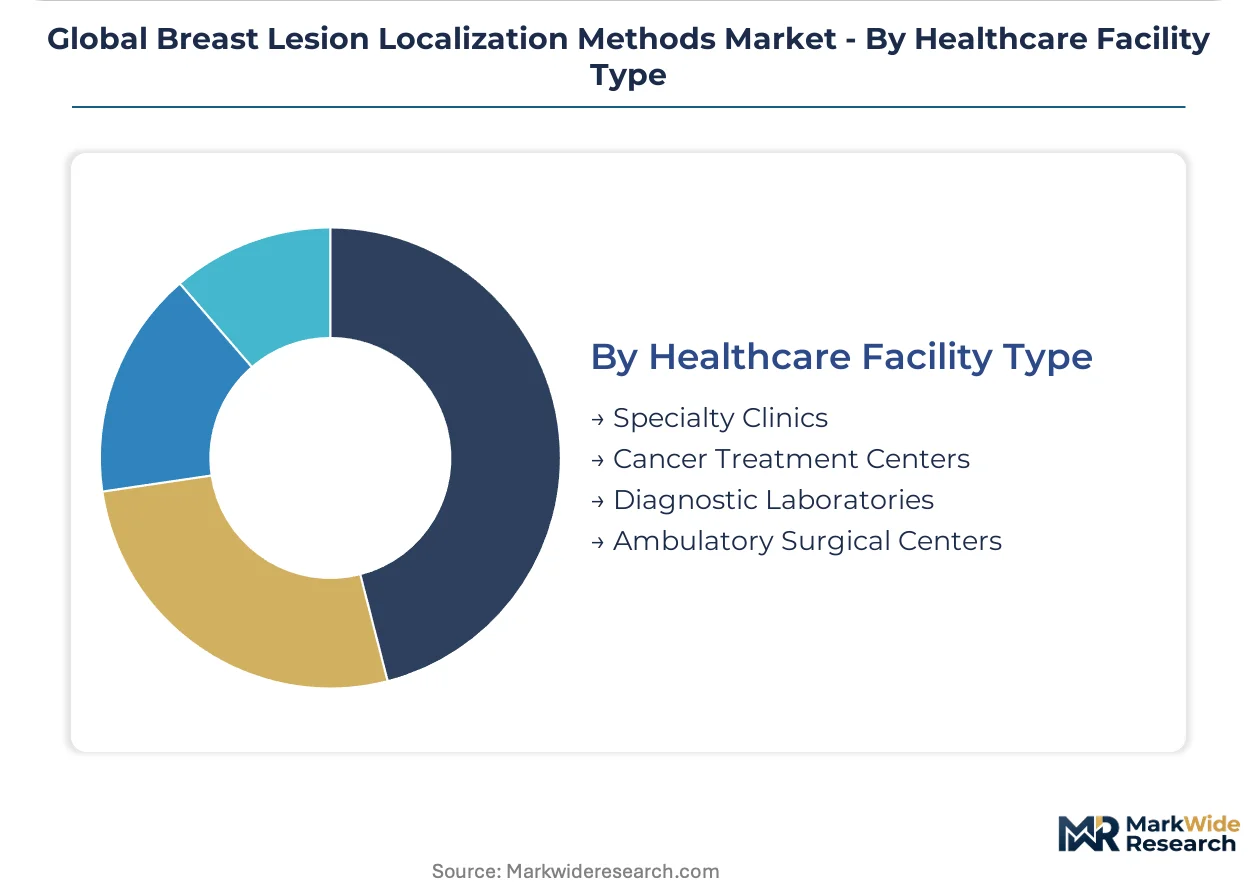
Healthcare Facility Type:
Customer type concentration shifts toward outpatient settings as CMS reimbursement parity channels localization away from inpatient environments.
- Specialty Clinics:Dedicated breast imaging centers concentrate diagnostic localization volumes. Urban clusters in the United States consolidate referrals through integrated mammography-to-biopsy workflows.
- Cancer Treatment Centers:Comprehensive oncology facilities combine localization with multimodal therapy planning. German hospital networks coordinate surgical and radiation oncology scheduling through centralized booking systems.
- Diagnostic Laboratories:Independent pathology-focused facilities handle marker placement for external surgical referral. India's national health mission initiatives expand mobile unit deployment to underserved districts.
- Ambulatory Surgical Centers:Same-day procedure facilities demand streamlined localization-to-excision solutions. Texas and Florida ASC density supports competitive differentiation through convenience positioning.
Cancer treatment centers retain the deepest procedure integration; ambulatory surgical centers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature screening infrastructures and emerging systems building first-time localization capacity. The United States and Germany favor same-day magnetic marker protocols that compress radiology-to-surgery timelines, while India and Japan prioritize portable wire-guided systems compatible with mobile screening units and high-volume academic workflows respectively.
United States
CMS reimbursement parity for outpatient breast procedures channels localization volumes toward ambulatory surgical centers in Texas and Florida. FDA 510(k) clearance pathways expedite magnetic and radar device commercialization, compressing time-to-market for predicate-based submissions. Dallas-Fort Worth ASC clusters adopt same-day localization-to-excision protocols as competitive differentiators.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia coordinate surgical and radiation oncology scheduling through centralized booking systems that favor magnetic marker elimination of 24-48 hour radioactive seed decay windows. EU MDR Article 117 compliance complexity for radioactive seeds elevates tender evaluations for device-only magnetic alternatives. Berlin-Brandenburg cancer treatment centers weight post-market surveillance data heavily in procurement decisions.
Japan
PMDA clinical trial requirements extend approval timelines by 18-24 months relative to FDA pathways, delaying magnetic marker penetration despite academic medical center demand in Tokyo and Osaka. Screening program density in Kanto and Kansai regions sustains wire localization volumes where surgeon familiarity and capital depreciation cycles resist switching. Nagoya-area institutions concentrate MRI-guided preoperative planning for occult lesions.
India
National health mission initiatives targeting breast cancer early detection in tier-2 and tier-3 cities create first-mover advantages for wire and magnetic technologies compatible with mobile mammography units. CDSCO regulatory pathways for imported devices favor established manufacturers with local distribution partnerships. Maharashtra and Karnataka urban clusters deploy portable ultrasound-guided localization for outreach programs.
United Kingdom
NHS England procurement frameworks standardize magnetic marker adoption across London and Southeast imaging networks, eliminating radioactive seed waste management liabilities from hospital budgets. MHRA post-Brexit regulatory alignment with EU MDR maintains CE marking recognition for continental suppliers. Midlands cancer alliances coordinate multi-site localization protocol harmonization.
Global Breast Lesion Localization Methods Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that concentrates on modality-specific delivery systems and detection hardware. The upper tier commands hospital contracting power through multi-product portfolios spanning imaging, localization, and surgical guidance. Three archetypes populate the competitive terrain: integrated mammography-to-surgery platforms, interventional radiology suite specialists, and magnetic marker pure-plays. Consolidation pressure manifests through strategic partnerships for distribution access and technology licensing for radar detection algorithms.
Among US-based device manufacturers, Hologic Inc., BD, and Merit Medical Systems occupy anchor positions within their respective archetypes. Hologic exemplifies the integrated platform approach through its mammography-guided localization workflow dominance. BD represents multi-modality contracting power across wire and seed technologies. Merit Medical Systems anchors the interventional radiology specialist tier with delivery system focus. These three entities collectively illustrate how scale, portfolio breadth, and procedural integration define competitive positioning in this market.
| Leading Market Players |
|---|
| Hologic Inc. |
| BD |
| Merit Medical Systems |
| Argon Medical Devices |
| SOMATEX Medical Technologies GmbH |
| Cook Medical |
| Intramedical Imaging, LLC |
| Stryker |
| Endomagnetics Ltd |
| Others |
Supply & Pricing Matrix
High-volume manufacturing of magnetic seed cores in Germany and Japan generates scale economies that compress unit costs while elevating price floors for smaller competitors lacking dedicated sintering facilities. These concentration effects ripple through contract negotiations, with hospital GPOs leveraging multi-year commitments to secure preferential terms against spot-market premiums for radioactive alternatives.
Pricing Analysis
Contract-based long-term offtake agreements dominate hospital procurement, with three-year GPO contracts anchoring volume commitments for magnetic marker systems. Price differentiation hinges on FDA clearance tier and after-sales service bundling, with 510(k)-predicate devices commanding premiums over de novo pathways. Cost compression in wire localization segments is intensifying because ASC reimbursement parity eliminates inpatient facility fees, squeezing legacy technology margins. Community hospital buyers exhibit highest price sensitivity, while academic medical centers prioritize integration depth over unit economics.
Supply Chain Analysis
Germany and the United States anchor precision alloy fabrication for magnetic seed cores, while Japan concentrates radar reflector semiconductor etching capacity. Rare earth element processing draws from Chinese separation facilities, with neodymium-iron-boron powder shipments feeding European magnet assembly lines. Single-source vulnerability in iodine-125 encapsulation creates supply chain risk for radioactive seed manufacturers facing extended lead times from Canadian reactor facilities. Distribution runs through specialized medical device distributors holding cold-chain and radiation-handling certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital system consolidation and GPO aggregation, with three national purchasing collectives now controlling over half of US localization device procurement volume.
For Market Incumbents: Consolidate market position through backward integration into magnetic alloy powder production, securing captive supply of neodymium-iron-boron feedstock against Chinese export quota volatility. Deepen hospital system partnerships by embedding localization workflows within electronic health record platforms, creating switching costs that resist emerging entrant displacement. For New Entrants and Emerging Players: Anchor in India's tier-2 and tier-3 city outreach programs, where national health mission screening expansion outpaces established distribution infrastructure. Target portable ultrasound-guided magnetic marker deployment for mobile mammography units, leveraging CDSCO regulatory pathways that favor device-only classifications over radioactive seed competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among magnetic marker pure-plays with disposable seed and reusable probe business models, generating predictable replacement cycles absent capital equipment refresh dependencies. Acquisition targets should demonstrate hospital system IDN penetration above regional averages and FDA 510(k) predicate libraries enabling rapid line extensions. Monitor CMS reimbursement coding decisions for radar localization as inflection indicator for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Predicate device pathways compress commercialization timelines for magnetic seed competitors. |
| Hospital System Partnership | Integrated EHR workflows at Texas ASC clusters lock in same-day protocol adoption. |
| CE Marking Pathway Optimization | MDR Article 117 device-only classification avoids radioactive seed combination product burdens. |
| Software Companion Development | Real-time intraoperative tracking algorithms differentiate radar localization premium tiers. |
| Reimbursement Strategy | CPT code standardization for magnetic modalities reduces prior authorization administrative drag. |
Research Methodology
Desk research of FDA 510(k) filings, EMA MDR technical documentation, and hospital GPO contract databases preceded structured interviews with breast imaging radiologists, ASC operations directors, and biomedical engineering procurement leads. Secondary validation drew from CMS reimbursement coding bulletins, PMDA approval summaries, and CDSCO import registration records. Bottom-up procedure volume estimates triangulated against top-down market sizing from device manufacturer revenue disclosures.
Variance decomposition across localization technique, imaging guidance modality, and healthcare facility type segments structured the analytical framework over the projection horizon. CAGRs derived from logistic adoption curves for magnetic marker substitution against wire localization installed base depreciation. Modeled inputs incorporated radiologist workforce density projections and ambulatory surgical center construction permitting data.
Decision-makers should treat outputs as directional under assumptions of stable CMS outpatient reimbursement parity and EU MDR enforcement continuity; material deviation in either would warrant model refresh. Specific risk factors include PMDA regulatory delays extending Japan market entry timelines and radioactive waste disposal cost spikes compressing seed technology margins. Recalibration cycles align with material shifts in national screening program funding and magnetic marker CPT coding decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Lung Biopsy Systems Market
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
Companion Diagnostics Market
Diagnostic Devices
AI Portable Chest X-ray Triage Device Market
Diagnostic Devices
Thrombus Precursor Protein Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Portable Diagnostic Devices Market
Diagnostic Devices
Global Real Time Polymerase Chain Reaction Systems Market
Diagnostic Devices
Pulmonary Function Testing Devices Market
Diagnostic Devices
Immunology-Oncology ELISA Kits Market
Diagnostic Devices
US Point of Care Diagnostics Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
Point of Care Blood Testing Devices Market