
 Global Vascular Stents Market | 2026-2036
Global Vascular Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vascular Stents Market Outlook
Ireland is tilting toward a European stent manufacturing hub as Boston Scientific Corporation anchors substantial production capacity in Galway. Abbott Laboratories leverages its vertically integrated nitinol supply chain to sustain cost advantages across coronary and peripheral portfolios. Medtronic Plc competes through specialized drug-elution coating technologies that differentiate its product line in high-acuity hospital segments.
Vascular stents are expandable tubular mesh devices, typically fabricated from cobalt-chromium, platinum-iridium, or absorbable polymers, designed to scaffold arterial lumina and restore patency following percutaneous transluminal angioplasty. Drug-eluting stents dominate value pools due to sustained clinical preference for sirolimus-analogue elution profiles, while bioresorbable stents occupy a premium niche constrained by strut thickness limitations and long-term vessel remodeling data. Coronary artery disease applications anchor volume demand, though peripheral artery disease represents the fastest-growing application segment as below-the-knee intervention protocols expand.
The FDA's premarket approval framework and the EU Medical Device Regulation (MDR) impose divergent evidentiary requirements that shape clinical trial investment and market access timelines for manufacturers. Japan's PMDA maintains distinct pharmacovigilance reporting standards for drug-eluting platforms that influence post-market surveillance costs across Asia-Pacific distribution networks. Stakeholders must monitor how reimbursement parity between bioresorbable and metallic platforms evolves across national health technology assessment bodies.
Market Dynamics
Bioresorbable scaffold platforms are compressing the traditional metallic stent value chain as polymer chemistry advances reduce strut thickness below 100 microns, forcing manufacturers to reallocate R&D budgets from incremental drug-elution improvements toward fully absorbable architectures.
Growth Catalysts
- India's PLI Scheme for Medical Devices:Domestic cobalt-chromium production incentives are expanding local manufacturing capacity and reducing import dependency for coronary stent supply chains.
- Below-the-Knee Intervention Protocols:Peripheral artery disease applications are accelerating as interventional cardiologists adopt infrapopliteal stenting techniques previously reserved for bypass surgery.
- Japan's PMDA Pharmacovigilance Standards:Streamlined post-market surveillance pathways for drug-eluting platforms are compressing time-to-reimbursement across Asia-Pacific distribution networks.
Market Restraints
- Nitinol Supply Concentration:Captive sourcing from limited superelastic alloy foundries creates input cost volatility for peripheral stent manufacturers dependent on shape-memory properties.
- EU MDR Evidentiary Requirements:Clinical trial investment thresholds for bioresorbable scaffolds have doubled compared to pre-2017 CE marking pathways, extending market access timelines.
- Balloon Angioplasty Resurgence:Drug-coated balloon technologies threaten metallic stent volumes in femoropopliteal segments where restenosis rates have narrowed.
Strategic Opportunities
- Indonesia's Cath Lab Expansion:Hospital infrastructure investment in Jakarta and Surabaya is creating first-mover advantages for stent distributors establishing direct procurement relationships.
- Polymer-Metal Hybrid Convergence:Combination platforms integrating absorbable polymers with radiopaque markers are opening premium positioning between durable and fully resorbable categories.
- Central Government Procurement in Brazil:ANVISA's consolidated purchasing frameworks for public hospital networks favor manufacturers with localized sterile packaging capabilities.
Industry Challenges
- Polymer Degradation Modeling Expertise:Computational simulation talent for predicting 24-month vessel remodeling remains scarce across device engineering functions.
- MDR Technical Documentation Burden:Clinical evaluation report preparation for legacy drug-eluting stents is consuming 40% of regulatory affairs bandwidth at mid-tier manufacturers.
- Cleanroom Capacity Constraints:Sterile stent packaging line expansion requires capital deployment that conflicts with parallel bioresorbable pilot production investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vascular Stents Market |
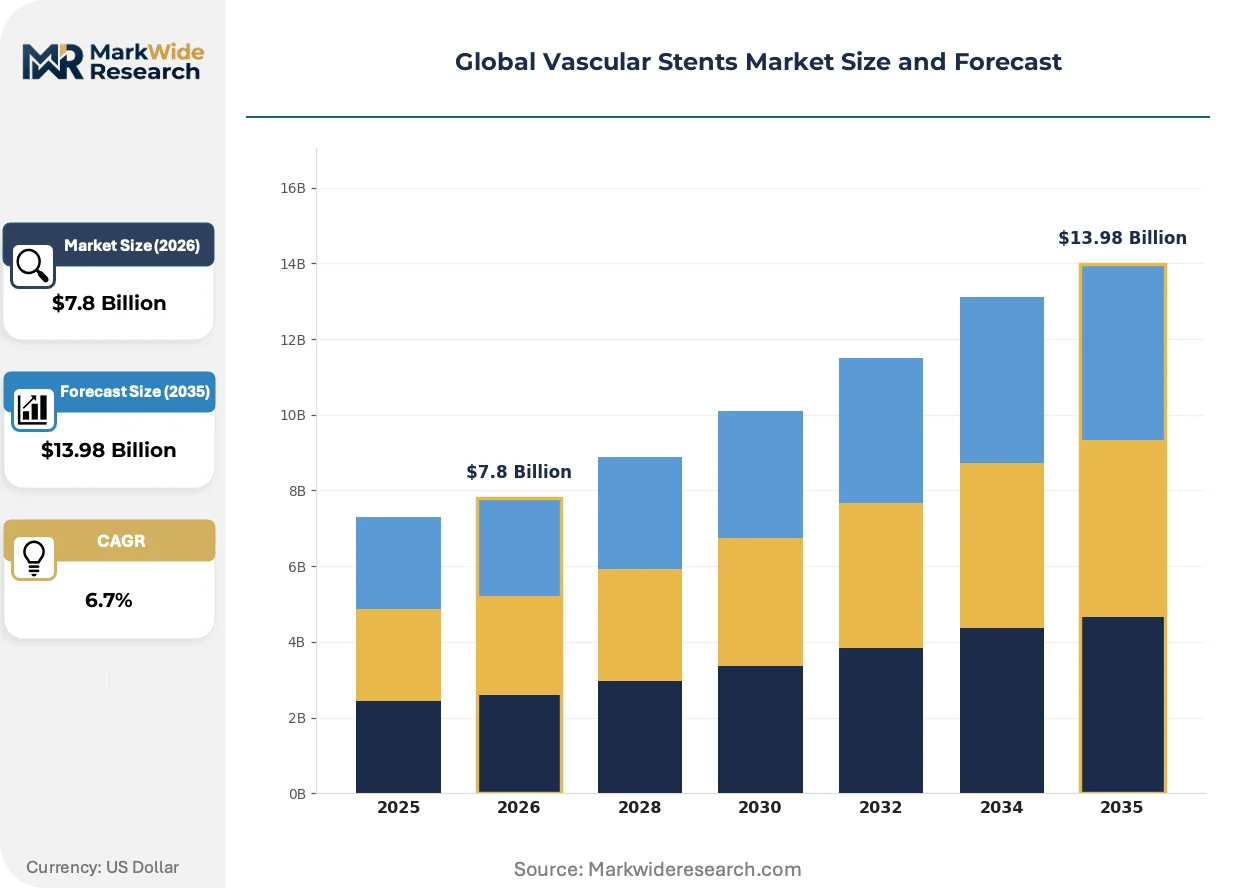
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.98 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drug-Eluting Stents, Bare Metal Stents, Bioresorbable Stents, Covered Stents Application: Coronary Artery Disease, Peripheral Artery Disease, Neurovascular Conditions, Renal Artery Stenosis Delivery Method: Balloon Angioplasty, Direct Implantation, Catheter-Based Delivery, Retrograde Access End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions |
| Companies Covered | Abbott Laboratories, Medtronic Plc, Boston Scientific Corporation, B. Braun SE, Terumo Corporation, Biotronik SE & Co. KG, Shanghai MicroPort Medical Group, Lepu Medical Technology (Beijing) Co., Ltd., Meril Life Sciences Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vascular Stents Market Strategic Shifts
Computational modeling and connected health architectures are converging to transform how stent performance is predicted, monitored, and reimbursed across the care continuum.
Polymer-lipid hybrid coatings are digitizing the interface between implantable devices and post-intervention monitoring systems. Integrated sensor-enabled stents transmit real-time flow data to catheterization lab networks, enabling interventional cardiologists to optimize antiplatelet therapy duration based on individual endothelialization patterns rather than fixed protocols. Hospital systems in Germany and South Korea are piloting these connected platforms to reduce 30-day readmission penalties.
REACH authorization pathways for novel absorbable polymers are compressing toxicology review timelines for European manufacturers. ECHA's streamlined substance registration for magnesium-based scaffolds has reduced preclinical testing costs by enabling read-across from established cardiovascular implant data. Galway-based production facilities are leveraging this regulatory efficiency to accelerate bioresorbable pipeline candidates toward MDR conformity assessment.
Catheterization lab purchasing committees are consolidating vendor relationships around full-procedure bundles rather than device-only transactions. Stent manufacturers now compete on integrated angioplasty balloon, guidewire, and imaging system provision, displacing standalone product procurement in US hospital networks. This concentration is most visible in integrated delivery networks across Texas and Florida, where supply chain rationalization has reduced approved stent SKUs by 60% within three years.
Global Vascular Stents Market Segmentation
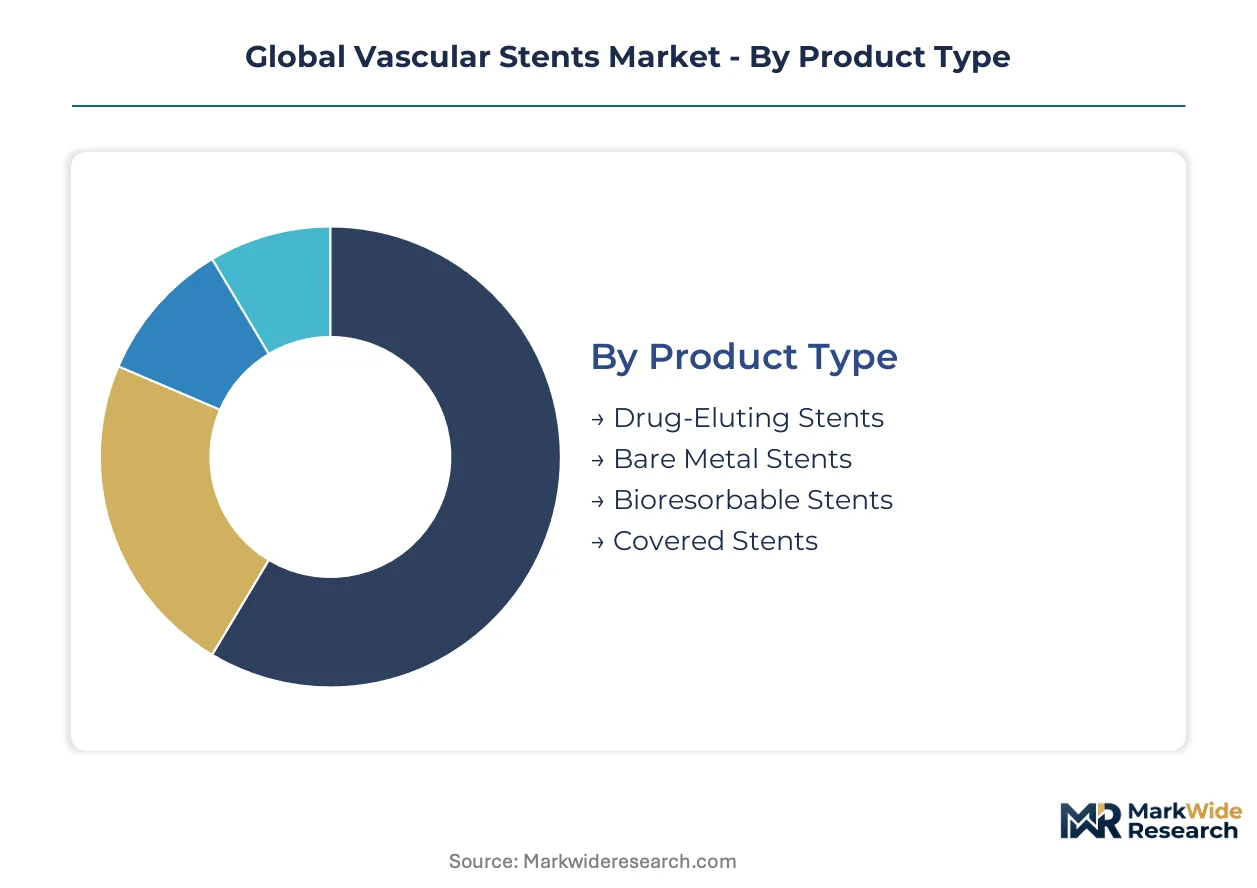
Stent segmentation determines procurement patterns across hospital systems and shapes how manufacturers allocate R&D budgets between incremental improvements and breakthrough platforms. Product type classifications dictate reimbursement tiers, while application-based splits guide sales force deployment toward interventional cardiologists versus vascular surgeons.
Product Type:
Cost tier differentiation separates premium drug-elution platforms from commodity metallic alternatives and experimental absorbable architectures.
- Drug-Eluting Stents:Polymer matrices release sirolimus analogues over 30-90 days to suppress neointimal hyperplasia. Demand concentrates in German and South Korean hospital networks where reimbursement fully covers premium antiproliferative coatings.
- Bare Metal Stents:Cobalt-chromium lattices without pharmacological coating occupy price-sensitive procurement channels. Indian public hospital tenders favor these platforms where central government purchasing prioritizes unit cost over restenosis reduction.
- Bioresorbable Stents:Magnesium and polymer scaffolds absorb within 24-36 months, enabling vessel restoration.
- Covered Stents:Expanded polytetrafluoroethylene membranes contain aneurysm sacs and seal perforations.
Drug-Eluting Stents commands the established base. The steepest expansion runs through Bioresorbable Stents.
Application:
Anatomical site determines stent specification requirements for radial force, flexibility, and deliverability through tortuous vasculature.
- Coronary Artery Disease:Lesions in epicardial vessels require thin-strut platforms compatible with complex bifurcation techniques. Japanese catheterization labs generate concentrated demand through high percutaneous coronary intervention volumes per capita.
- Peripheral Artery Disease:Femoropopliteal and infrapopliteal segments drive nitinol self-expanding platform adoption. Below-the-knee protocols in Brazilian public hospitals are accelerating volume fastest as bypass alternatives expand.
- Neurovascular Conditions:Intracranial aneurysm and stroke interventions utilize flow-diverting and intracranial stent platforms.
- Renal Artery Stenosis:Ostial lesion treatment balances radial strength against vessel tapering.
Coronary Artery Disease anchors manufacturer revenue. Peripheral Artery Disease is climbing the fastest as intervention boundaries extend distal to the knee.
Delivery Method:
Deployment technique shapes device design priorities for trackability, pushability, and crossing profile in calcified lesions.
- Balloon Angioplasty:Predilation and stent delivery through integrated balloon catheters remains the dominant workflow. US integrated delivery networks in Texas and Florida standardize on balloon-expandable platforms for procurement efficiency.
- Direct Implantation:Stent deployment without predilation reduces procedure steps in selected lesion morphologies.
- Catheter-Based Delivery:Transfemoral and transradial access routes dictate catheter length and hydrophilic coating specifications.
- Retrograde Access:Collateral channel crossing for chronic total occlusion revascularization.
Balloon Angioplasty retains procedural dominance. Catheter-Based Delivery is gaining share fastest as radial access adoption accelerates.
End User:
Customer type determines purchasing authority location and service bundling requirements.
- Hospitals:Catheterization lab committees negotiate full-procedure bundles encompassing stents, balloons, and imaging. German hospital networks consolidate vendors around integrated supply agreements covering coronary and peripheral portfolios.
- Ambulatory Surgical Centers:Outpatient settings prioritize rapid inventory turnover and simplified SKU matrices.
- Specialty Clinics:Focused vascular practices concentrate on niche applications like dialysis access maintenance.
- Research Institutions:Academic medical centers drive bioresorbable scaffold clinical trial enrollment.
Hospitals capture the volume concentration. Ambulatory Surgical Centers are expanding most quickly as procedure migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Galway anchors cobalt-chromium fabrication for European distribution, while domestic manufacturing incentives in India compress import dependency. Hospital procurement consolidation across Germany and catheterization lab expansion in Indonesia reshape regional competitive dynamics.
United States
Integrated delivery networks in Texas and Florida consolidate vendors around full-procedure bundles encompassing stents, balloons, and imaging systems. FDA premarket approval pathways for bioresorbable scaffolds compress review timelines for novel polymer platforms. Minneapolis and Boston anchor R&D concentration for drug-elution coating technologies.
Germany
Hospital networks prioritize premium antiproliferative coatings where reimbursement fully covers drug-eluting platforms. EU MDR conformity assessment extends market access timelines through elevated clinical trial investment thresholds. Galway-based production facilities leverage REACH authorization efficiencies to accelerate bioresorbable pipeline candidates.
India
Central government medical device incentives under the PLI scheme expand domestic cobalt-chromium production capacity. CDSCO regulatory harmonization streamlines import substitution pathways for coronary stent supply chains. Maharashtra and Gujarat host scaling manufacturing clusters reducing dependency on foreign-sourced metallic platforms.
Japan
Catheterization labs generate concentrated demand through high percutaneous coronary intervention volumes per capita. PMDA pharmacovigilance reporting standards for drug-eluting platforms influence post-market surveillance costs across Asia-Pacific distribution networks. Tokyo and Osaka anchor specialized coating technology development for high-acuity hospital segments.
Brazil
Below-the-knee intervention protocols in public hospitals accelerate peripheral artery disease stent volumes as bypass alternatives expand. ANVISA consolidated purchasing frameworks for public hospital networks favor manufacturers with localized sterile packaging capabilities. São Paulo anchors distribution infrastructure for catheterization lab supply chains.
Global Vascular Stents Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying cobalt-chromium lattices and nitinol superelastic alloys. The market structure concentrates around three tiers: multinational device conglomerates with vertically integrated supply chains, mid-tier regional fabricators leveraging domestic regulatory advantages, and emerging polymer chemistry specialists pursuing bioresorbable differentiation. Strategic moves center on backward integration into nitinol foundry capacity and geographic expansion through localized sterile packaging facilities.
Among US-based multinationals, Abbott Laboratories, Medtronic Plc, and Boston Scientific Corporation exemplify the integrated platform archetype, each occupying positions spanning coronary and peripheral portfolios through captive supply chain control. These entities anchor competitive dynamics through specialized drug-elution coating technologies and vertically integrated nitinol sourcing that sustains cost advantages across high-acuity hospital segments.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic Plc |
| Boston Scientific Corporation |
| B. Braun SE |
| Terumo Corporation |
| Biotronik SE & Co. KG |
| Shanghai MicroPort Medical Group |
| Lepu Medical Technology (Beijing) Co., Ltd. |
| Meril Life Sciences Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Indian cobalt-chromium foundries is compressing input costs for metallic stent manufacturers while simultaneously eroding pricing power across Asia-Pacific procurement channels. This utilization dynamic forces suppliers to absorb margin pressure or divert capacity toward bioresorbable polymer pilot lines where premium positioning remains intact.
Pricing Analysis
EU MDR dictates the pricing tier structure through elevated clinical trial investment thresholds that stratify manufacturers across premium, standard, and economy levels. FDA premarket approval tiers separate drug-eluting platforms with sirolimus-analogue coatings from bare metal alternatives, with price differentiation hinging on certification grade and antiproliferative efficacy data. Cost compression in the bare metal segment is intensifying because Indian domestic production under PLI incentives has expanded supply faster than public hospital tender absorption. Ambulatory surgical centers exhibit the highest price sensitivity, while German hospital networks purchasing full-procedure bundles show the least.
Supply Chain Analysis
Contract manufacturing concentration rests with Galway-based production facilities and Maharashtra-Gujarat fabrication clusters that anchor cobalt-chromium lattice output for European and Asian distribution. Raw material dependencies draw from superelastic nitinol foundries in the United States, platinum-iridium wire suppliers in Germany, and magnesium alloy feedstock processors in Japan. Single-source vulnerability in nitinol shape-memory alloy sourcing exposes peripheral stent manufacturers to input cost volatility when foundry capacity tightens. Distribution runs through hospital procurement committees in integrated delivery networks that consolidate vendor relationships around full-procedure bundles encompassing stents, balloons, and imaging systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Catheterization lab purchasing committees are consolidating vendor relationships around full-procedure bundles, creating platform-economics dynamics where interoperability between stent delivery systems and imaging architectures determines contract renewal probability.
For Market Incumbents: Build regulatory-data moats through MDR technical documentation libraries that mid-tier competitors cannot replicate without consuming forty percent of regulatory affairs bandwidth. Deepen backward integration into nitinol foundry capacity to neutralize superelastic alloy supply volatility that threatens peripheral stent margins. Secure hospital system partnerships in Texas and Florida integrated delivery networks where supply chain rationalization has reduced approved stent SKUs by sixty percent within three years. For New Entrants and Emerging Players: Indonesia's cath lab expansion in Jakarta and Surabaya represents the most penetrable entry point where direct procurement relationships with first-mover distributors remain unclaimed. Below-the-knee intervention protocols in Brazilian public hospitals offer secondary white-space as bypass alternatives accelerate peripheral artery disease stent volumes. Target polymer-metal hybrid platforms integrating absorbable polymers with radiopaque markers to open premium positioning between durable and fully resorbable categories without requiring full bioresorbable scaffold regulatory investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among stent manufacturers with hospital system partnership agreements that embed inventory management and procedure training into multi-year contracts. Long-term viability across the projection horizon favors acquisition targets with captive nitinol supply chains and localized sterile packaging capabilities in Brazil or India where ANVISA and CDSCO procurement frameworks reward domestic production. Watch for REACH authorization pathway expansions for magnesium-based scaffolds as the signal indicating European bioresorbable market access timelines are compressing.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Texas integrated delivery networks consolidate vendors around full-procedure bundles encompassing stents, balloons, and imaging systems. |
| CE Marking Pathway | EU MDR conformity assessment extends market access timelines through elevated clinical trial investment thresholds for bioresorbable scaffolds. |
| Backward Integration | Captive nitinol foundry capacity neutralizes superelastic alloy input cost volatility for peripheral stent manufacturers. |
| Software Companion Development | Integrated sensor-enabled stents transmit real-time flow data to catheterization lab networks in Germany and South Korea. |
| Reimbursement Strategy | Japan's PMDA pharmacovigilance standards influence post-market surveillance costs across Asia-Pacific distribution networks. |
Study Parameters
Operator-level perspectives from interventional cardiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from FDA premarket approval filings, EMA MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up stent volume modeling across product type, application, and delivery method segments triangulated against top-down market sizing from trade flow analysis.
Scenario-bracketing framed the analytical approach across the analysis window, with conservative and expansion cases reflecting differential bioresorbable scaffold adoption trajectories and drug-coated balloon substitution rates. Segmentation dimensions modeled encompassed product type classifications, anatomical application sites, deployment techniques, and end-user facility categories. CAGRs derived from procedure volume growth in catheterization labs, reimbursement parity evolution, and polymer chemistry advancement curves.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or central government medical device incentive funding would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway efficiency, supply chain localization trends, and competitive dynamics among multinational device conglomerates. Quarterly review of cath lab capacity expansion announcements, PLI scheme beneficiary lists, and MDR conformity assessment completion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Transcranial Doppler Ultrasound Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Stent-Assisted Coiling Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Global Drug Eluting Balloon Catheters Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Global Intracranial Stents Market
Cardiovascular Devices
Cardiac Cannulas Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Cardiac Surgery Devices Market
Cardiovascular Devices
Global Vascular Patch Market
Cardiovascular Devices
Cardiovascular Catheter Market