
 Tricuspid Valve Repair Market | 2026-2036
Tricuspid Valve Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Tricuspid Valve Repair Market Outlook
The EU Medical Device Regulation is pivoting European procurement toward certified bioprosthetic valve suppliers. Edwards Lifesciences Corporation leverages its transcatheter platform to sustain leadership in minimally invasive repair systems. Abbott anchors its position through structural heart device specialization across cardiac centers. Medtronic competes with integrated surgical and catheter-based portfolios that span ring annuloplasty to percutaneous delivery.
Tricuspid valve repair encompasses surgical and transcatheter interventions that restore coaptation in the right atrioventricular valve using annuloplasty rings, clips, or replacement bioprostheses fabricated from bovine pericardium or porcine tissue. These procedures primarily serve heart failure patients with functional tricuspid regurgitation who face elevated mortality when left untreated. Transcatheter repair systems command the fastest expansion as hospitals shift volumes from open surgical ring annuloplasty toward percutaneous clip-based therapies that reduce intensive care stays. Surgical repair retains dominance in congenital heart defect corrections where durable mechanical fixation remains essential for pediatric and young adult cohorts.
The FDA maintains rigorous premarket approval pathways for transcatheter tricuspid devices through its Office of Cardiovascular Devices, while the EU MDR requires renewed clinical evidence for bioprosthetic valve CE markings that previously cleared under the MDD. These frameworks elevate barriers for new entrants and compel incumbents to generate prospective registry data. ISO 13485 quality management standards further shape manufacturing compliance across device supply chains. Stakeholders must monitor reimbursement decisions by CMS and parallel health technology assessment bodies, as coverage determinations will dictate whether transcatheter repair volumes shift decisively from academic cardiac centers toward community hospital settings.
Market Dynamics
The shift from surgical ring annuloplasty to transcatheter clip-based repair is compressing hospital length-of-stay metrics and redistributing procedure volumes from academic cardiac centers toward community hospitals equipped with catheterization laboratories.
Growth Catalysts
- EU MDR bioprosthetic certification:The tightened CE marking requirements under the Medical Device Regulation are consolidating procurement around established suppliers with prospective registry data, accelerating hospital consolidation of vendor relationships.
- Transcatheter delivery systems:Percutaneous clip technologies are displacing open surgical approaches in functional tricuspid regurgitation cases, reducing intensive care utilization and enabling same-day discharge protocols.
- Heart failure patient cohorts:Cardiac centers in the United States are prioritizing minimally invasive options for elderly comorbid populations previously excluded from surgical candidacy.
Market Restraints
- Bovine pericrostium supply concentration:Bioprosthetic valve fabricators depend on concentrated sourcing of bovine pericardial tissue from specific processing facilities, creating vulnerability to supply interruptions.
- FDA premarket approval timelines:The Office of Cardiovascular Devices maintains rigorous evidentiary standards for transcatheter tricuspid devices, extending commercialization timelines for novel entrants.
- Mechanical valve substitution:Pediatric congenital defect corrections continue to favor durable mechanical fixation over bioprosthetic alternatives, limiting addressable market expansion in younger demographics.
Strategic Opportunities
- CMS reimbursement expansion:Coverage determinations for transcatheter tricuspid repair in community hospital settings would unlock procedure volume growth outside academic medical centers.
- Annuloplasty ring innovation:Convergence of imaging-guided delivery with adjustable ring technologies enables real-time procedural optimization during surgical repair.
- ISO 13485 manufacturing scale-up:Quality management certification expansion into emerging cardiac device clusters creates first-mover positioning in undersupplied geographies.
Industry Challenges
- Interventional cardiologist training pipelines:Transcatheter clip deployment demands specialized structural heart expertise that outpaces current fellowship program output.
- Legacy surgical suite reconfiguration:Hybrid operating room investments required for combined surgical-catheter procedures strain capital allocation at mid-tier hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tricuspid Valve Repair Market |
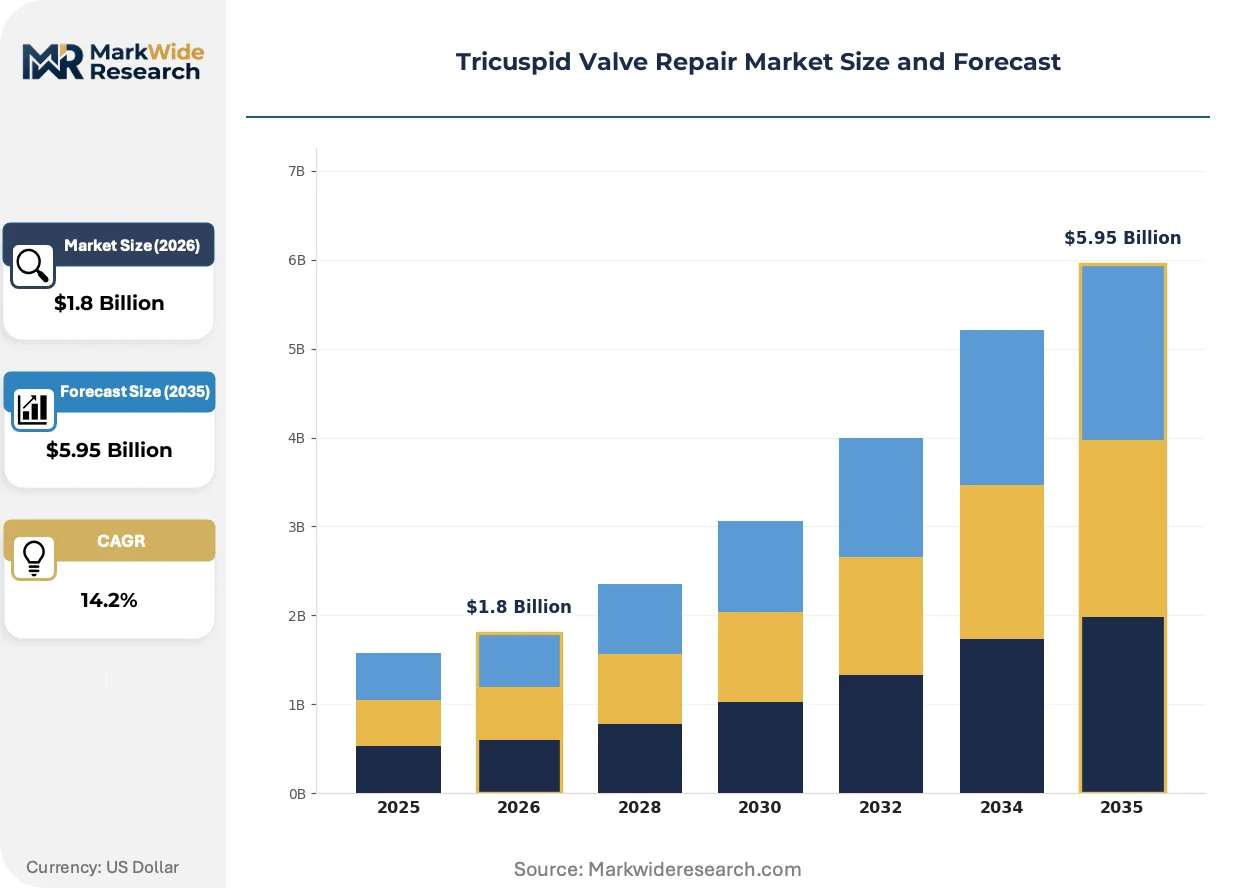
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Repair, Transcatheter Repair, Ring Annuloplasty, Bioprosthetic Valve Technology: Mechanical Valve, Biological Valve, Balloon Valvuloplasty, Surgical Clips End User: Hospitals, Cardiac Centers, Clinics, Ambulatory Surgical Centers Application: Heart Failure, Valve Dysfunction, Congenital Heart Defects, Atrial Fibrillation |
| Companies Covered | Edwards Lifesciences Corporation, Abbott, Medtronic, Boston Scientific Corporation, LivaNova PLC, Corcym, JenaValve Technology, Venus Medtech, CardioValve, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tricuspid Valve Repair Market Strategic Shifts
Transcatheter repair platforms are compressing the traditional surgical dominance of tricuspid intervention, while regulatory frameworks on both sides of the Atlantic reshape competitive positioning through evidentiary requirements.
Edge-to-edge clip repair is electrifying the functional tricuspid regurgitation segment by enabling leaflet coaptation without cardiopulmonary bypass. Cardiac catheterization laboratories at high-volume centers are adopting these systems faster than surgical departments anticipated, compressing the window between diagnosis and intervention for decompensated heart failure patients.
The EU Medical Device Regulation is forcing renewed clinical evidence generation for bioprosthetic valves that previously cleared under the MDD directive. Manufacturers must now maintain prospective registries to sustain CE markings, elevating post-market surveillance costs while creating separation between resourced incumbents and capital-constrained challengers.
Hospital procurement committees are unbundling device selection from physician preference cards, centralizing contracting decisions under value-analysis frameworks. This shift concentrates purchasing leverage within integrated delivery networks in the United States, displacing the traditional device representative-driven sales model that dominated cardiac surgery for decades.
Tricuspid Valve Repair Market Segmentation
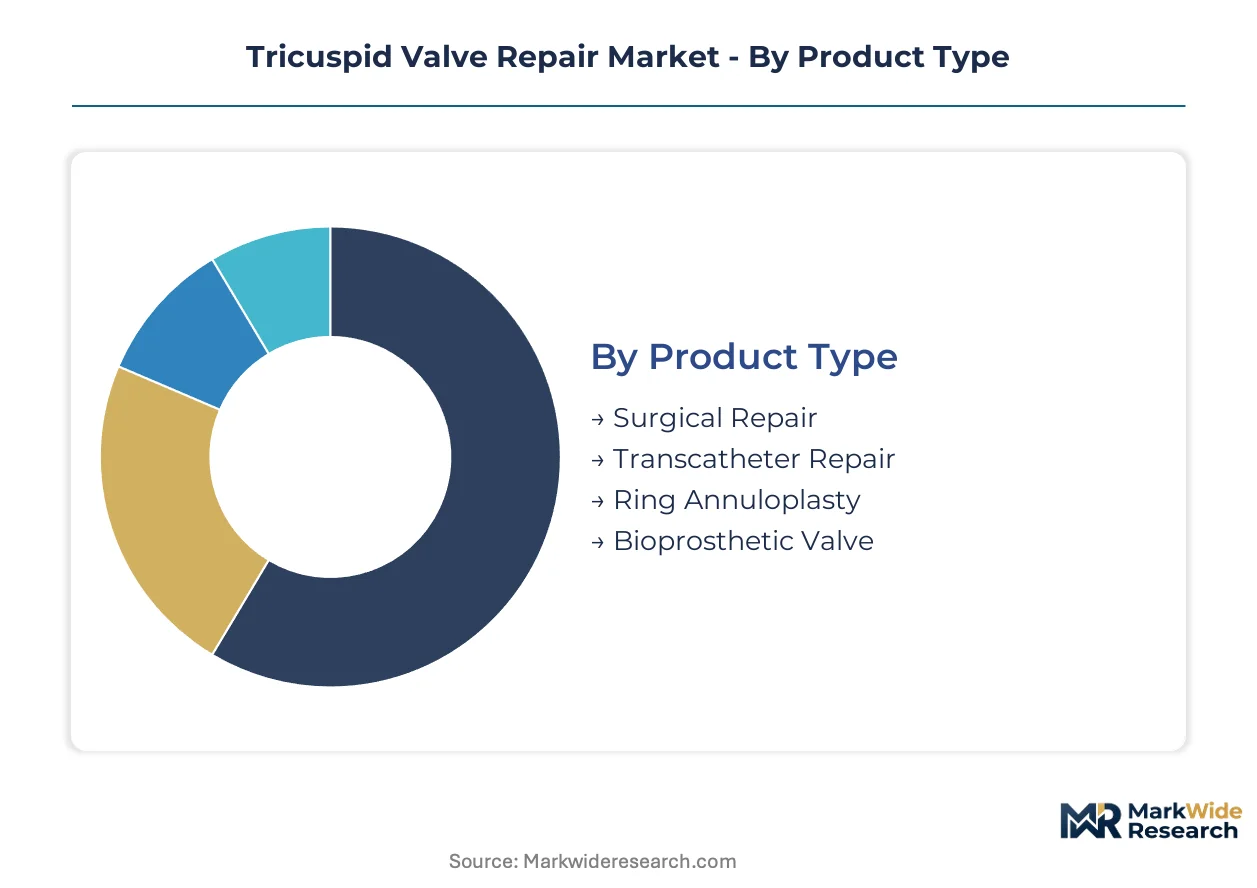
Tricuspid valve repair segmentation reveals how reimbursement pathways, procedural complexity, and patient acuity reshape purchasing decisions across cardiac care settings. Manufacturers must align portfolio depth with the specific technical and economic requirements of each segment tier.
Product Type:
Hospital procurement committees weight capital intensity against length-of-stay reduction when selecting between open surgical and percutaneous repair platforms.
- Surgical Repair:Open procedures utilizing direct valve reconstruction with suture techniques and ring implantation. Academic medical centers in the United States maintain surgical volumes for complex reoperations and combined mitral-tricuspid interventions where durable mechanical fixation outweighs recovery speed.
- Transcatheter Repair:Percutaneous delivery systems deploy clips or replacement valves via femoral venous access. Cardiac catheterization laboratories at high-volume centers are expanding these programs fastest, driven by same-day discharge protocols and reduced intensive care utilization.
- Ring Annuloplasty:Rigid or flexible rings restore annular dimensions during surgical correction. Demand concentrates in congenital defect repairs where growth accommodation and long-term durability remain paramount.
- Bioprosthetic Valve:Tissue-engineered replacements fabricated from bovine pericardium or porcine tissue. EU MDR certification requirements are consolidating procurement around established suppliers with prospective registry data.
Surgical repair leads on scale; transcatheter repair leads on momentum.
Technology:
Material selection and fixation mechanism determine reimbursement coding and long-term anticoagulation burden for patient cohorts.
- Mechanical Valve:Pyrolytic carbon constructs with titanium sewing rings provide lifelong durability. Pediatric cardiac centers favor these implants for congenital corrections where reoperation avoidance justifies anticoagulation management.
- Biological Valve:Tissue-derived constructs from bovine or porcine sources eliminate chronic anticoagulation. Elderly heart failure patients with functional tricuspid regurgitation drive demand where life expectancy aligns with bioprosthetic longevity.
- Balloon Valvuloplasty:Percutaneous dilation for stenotic lesions. Limited applicability in tricuspid disease restricts utilization to select congenital or rheumatic cases.
- Surgical Clips:Edge-to-edge leaflet approximation devices deployed via transcatheter access. Structural heart programs are training interventional cardiologists specifically for clip deployment to capture shifting procedure volumes.
Biological valve technology dominates current implant volumes; surgical clips are climbing the fastest.
End User:
Facility infrastructure and case volume thresholds determine which settings can support advanced structural heart programs.
- Hospitals:General acute care facilities with cardiac surgery capabilities. Community hospitals are investing in hybrid operating rooms to capture transcatheter volumes previously referred to academic centers.
- Cardiac Centers:Dedicated cardiovascular institutes with specialized structural heart teams. These settings generate the clinical evidence and training pipelines that diffuse techniques to broader practice.
- Clinics:Outpatient diagnostic and follow-up settings. Preoperative screening and post-procedural monitoring functions expand as transcatheter repair shifts toward same-day protocols.
- Ambulatory Surgical Centers:Freestanding facilities with catheterization capabilities. Regulatory and reimbursement barriers currently limit tricuspid intervention to hospital-based settings.
Cardiac centers lead on scale; hospitals lead on momentum.
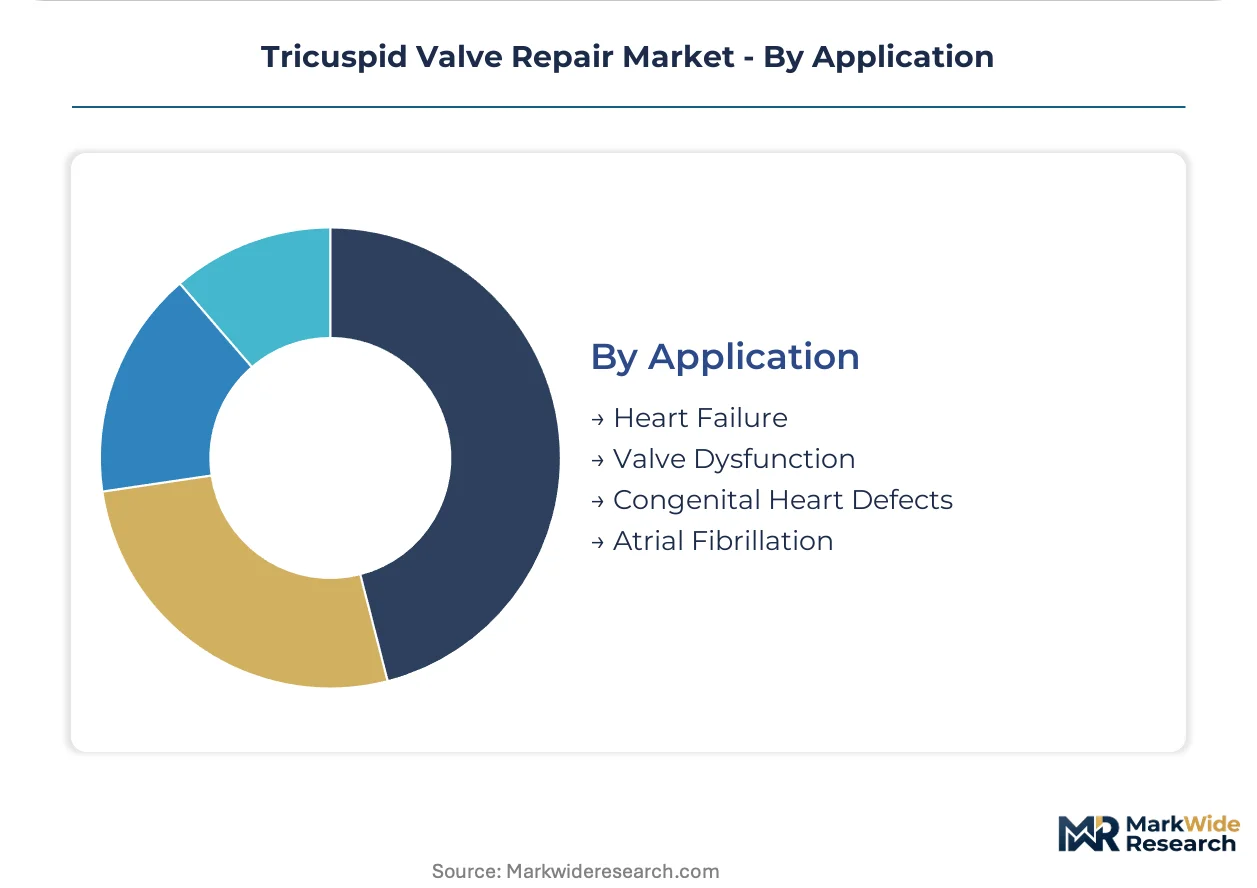
Application:
Underlying pathophysiology dictates procedural urgency, device selection, and long-term surveillance intensity.
- Heart Failure:Functional tricuspid regurgitation secondary to left-sided disease and ventricular remodeling. Transcatheter repair is displacing surgical referral in decompensated patients previously deemed inoperable.
- Valve Dysfunction:Primary structural abnormalities including prolapse, flail leaflets, and endocarditis sequelae. Surgical reconstruction remains preferred where leaflet tissue quality permits durable repair.
- Congenital Heart Defects:Ebstein anomaly and other developmental anomalies requiring early intervention. Pediatric cardiac centers maintain surgical dominance due to growth considerations and reoperation likelihood.
- Atrial Fibrillation:Functional regurgitation exacerbated by annular dilation from chronic arrhythmia. Combined ablation-repair procedures concentrate at electrophysiology-capable cardiac centers.
Heart failure leads on scale; valve dysfunction leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The tricuspid valve repair industry traces its commercial origins to surgical annuloplasty systems developed in the United States during the 1960s, with transcatheter platforms later emerging from European structural heart programs in the 2000s.
United States
Hospital systems in the United States prioritize minimally invasive procedures for elderly heart failure patients with functional tricuspid regurgitation. The FDA Office of Cardiovascular Devices maintains rigorous premarket approval pathways that extend commercialization timelines for novel entrants. Academic cardiac centers in Cleveland and Houston generate clinical evidence that diffuses techniques to community hospitals investing in hybrid operating rooms.
Germany
German cardiac centers drive adoption of transcatheter clip-based therapies that reduce intensive care utilization and enable same-day discharge protocols. The EU Medical Device Regulation requires renewed clinical evidence for bioprosthetic valve CE markings previously cleared under the MDD directive. Medical technology clusters in Bavaria and Baden-Württemberg host established suppliers with prospective registry data supporting certification compliance.
Switzerland
Swiss structural heart programs concentrate on complex reoperations and combined mitral-tricuspid interventions where durable mechanical fixation outweighs recovery speed. Swissmedic maintains stringent quality standards for bioprosthetic valve manufacturing that align with ISO 13485 certification requirements. The Zurich-Geneva corridor anchors specialized cardiac surgery training pipelines that supply interventional cardiologists across European markets.
China
Domestic manufacturers in China scale production of annuloplasty rings and surgical clips to serve expanding hospital infrastructure in tier-one cities. The National Medical Products Administration accelerates review pathways for innovative structural heart devices while maintaining post-market surveillance mandates. Medical device industrial parks in Shanghai and Shenzhen attract foreign joint ventures seeking manufacturing cost advantages and regional market access.
Japan
Japanese cardiac centers favor mechanical valve implants for pediatric congenital corrections where reoperation avoidance justifies anticoagulation management. The Pharmaceuticals and Medical Devices Agency requires extensive clinical evidence for transcatheter tricuspid devices that extends approval timelines relative to Western markets. Tokyo and Osaka metropolitan areas concentrate specialized structural heart teams that train interventional cardiologists for clip deployment procedures.
Tricuspid Valve Repair Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the tricuspid valve repair market, where integrated surgical-catheter portfolios demand distinct manufacturing capabilities than pure-play transcatheter platforms. The vendor base stratifies between diversified cardiovascular conglomerates with ring annuloplasty heritage and specialized structural heart entrants focused exclusively on percutaneous delivery. Three archetypes dominate: full-range suppliers spanning surgical to transcatheter repair, transcatheter specialists leveraging clip-based platforms, and regional fabricators serving price-sensitive procurement committees. Competitive moves concentrate on M&A to acquire transcatheter clip technologies and strategic partnerships to secure bovine pericardium supply chains.
Among diversified cardiovascular conglomerates, Edwards Lifesciences Corporation, Abbott, and Medtronic occupy positions that exemplify full-range portfolio strategy. Edwards Lifesciences represents the transcatheter platform archetype with established structural heart specialization. Abbott anchors the integrated device-diagnostics positioning through cardiac care system breadth. Medtronic sits within the surgical-catheter convergence tier with capabilities spanning mechanical fixation to percutaneous delivery systems.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Abbott |
| Medtronic |
| Boston Scientific Corporation |
| LivaNova PLC |
| Corcym |
| JenaValve Technology |
| Venus Medtech |
| CardioValve |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committee consolidation across United States integrated delivery networks is compressing vendor margins and forcing bioprosthetic valve fabricators to absorb certification compliance costs while maintaining supply continuity from concentrated tissue processing facilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA premarket approval tier and ISO 13485 certification grade. Premium tiers command substantial markups for transcatheter delivery systems with prospective registry data, while economy positioning concentrates in surgical annuloplasty rings serving price-sensitive community hospitals. Cost compression in the standard tier intensifies because EU MDR renewal requirements are elevating post-market surveillance expenditures. Academic cardiac centers exhibit lowest price sensitivity due to research funding offsets; mid-tier hospital systems face acute budget constraints.
Supply Chain Analysis
Device returns and explant flows from cardiac centers feed quality feedback loops that refine bioprosthetic valve manufacturing specifications. Raw material sourcing draws from bovine pericardium processing facilities in the United States, Switzerland, and Australia, with porcine tissue supplies anchored in Germany and Denmark. Manufacturing hinges on specialized tissue fixation chemistries and pyrolytic carbon machining capabilities concentrated among established suppliers. Single-source vulnerability in bovine tissue sterilization creates exposure to regulatory inspection disruptions. Distribution runs through GPO contracts and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tricuspid valve repair market compounds steadily as aging heart failure demographics expand the addressable patient pool requiring minimally invasive intervention options.
For Market Incumbents: Anchor market position through backward integration into bovine pericardium tissue processing to secure supply continuity against emerging entrant price undercutting. Prioritize ISO 13485 certification maintenance across manufacturing footprints to sustain EU MDR compliance leverage. Defensive patent clustering around transcatheter clip delivery geometries protects against specialized structural heart challengers. For New Entrants and Emerging Players: Image-guided annuloplasty ring adjustment technologies offer a technology-first wedge into surgical repair segments where incumbent R&D investment has lagged. Target community hospital hybrid operating room investments as the most penetrable infrastructure expansion vector. Pursue white-space positioning in pediatric congenital defect corrections where mechanical valve demand remains underserved by transcatheter platforms. Lead with training program partnerships to overcome interventional cardiologist pipeline constraints. For Investors and Strategic Acquirers: Asymmetric upside sits with transcatheter clip platform specialists possessing prospective registry data but lacking full cardiovascular portfolio breadth. Long-term viability over the coming decade rests on reimbursement expansion rather than technology differentiation alone. Monitor CMS coverage determinations for community hospital transcatheter procedures as the decisive inflection signal for volume migration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Premarket approval pathways through the Office of Cardiovascular Devices gate commercial entry for novel transcatheter platforms. |
| CE Marking Pathway | EU MDR renewal requirements compel prospective registry investment that separates resourced incumbents from capital-constrained challengers. |
| Hospital System Partnership | Integrated delivery network contracting consolidation displaces traditional device representative-driven sales models. |
| Software Companion Development | Imaging-guided delivery integration enables real-time procedural optimization during annuloplasty ring deployment. |
| Reimbursement Strategy | CMS coverage determinations dictate whether transcatheter repair volumes shift from academic centers to community hospitals. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement encompassed structural heart program directors, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR notified body documentation, CMS Medicare coverage determinations, and hospital procurement database extracts. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue segmentation.
Historical reference periods anchored the projection horizon to documented adoption curves from transcatheter mitral repair diffusion. Segmentation dimensions spanned product type, technology mechanism, end-user facility tier, application pathophysiology, and regional regulatory cluster. CAGRs emerged from logistic adoption curve fitting adjusted for reimbursement inflection points. Forecast inputs incorporated interventional cardiologist fellowship program output rates and hybrid operating room capital investment pipelines.
The model holds under stable reimbursement trajectories; deviation in CMS coverage determinations or EU MDR enforcement intensity would shift volume projections materially. Forecasts embed assumptions regarding training pipeline expansion and tissue supply continuity. Practitioners should monitor notified body inspection backlogs and bovine pericardium processing facility regulatory actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Valve Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Centrifugal Blood Pumps Market
Cardiovascular Devices
Global Coil Wound Devices Market
Cardiovascular Devices
Global Sclerotherapy Market
Cardiovascular Devices
Cardiovascular CT Systems Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Cardiovascular Surgical Devices Market
Cardiovascular Devices
North America Cardiac Assist Devices Market
Cardiovascular Devices
Continuous Cardiac Monitoring Systems Market
Cardiovascular Devices
Cardiovascular Prosthetic Devices Market