
 China Cardiovascular Devices Market | 2026-2036
China Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Cardiovascular Devices Market Outlook
Interventional cardiologist supply is reorganizing care delivery across China's cardiovascular device ecosystem. Lepu Medical Technology leverages domestic manufacturing scale to anchor pricing power in drug-eluting stent segments. Abbott Laboratories sustains technology leadership in structural heart through transcatheter valve platforms. MicroPort Scientific Corporation specializes in electrophysiology catheter design for complex arrhythmia cases.
Cardiovascular devices encompass implantable and percutaneous instruments engineered from cobalt-chromium alloys, nitinol, or bioresorbable polymers to restore cardiac function or vascular patency. These systems operate under hemodynamic stress conditions exceeding 120 mmHg systolic pressure and must demonstrate fatigue resistance through 400 million cycle testing protocols. Stent platforms occupy the largest installed base while electrophysiology catheter systems represent the fastest-expanding margin pool as atrial fibrillation procedure volumes rise. Bioresorbable stent technology differentiates through polymer scaffold degradation timelines calibrated to 24-month vascular restoration windows.
NMPA Class III device registration requirements and GB standard compliance frameworks shape product development timelines and clinical evidence thresholds for market authorization. The country's national pharmaceutical regulator enforces biocompatibility testing under ISO 10993 series protocols alongside mandatory domestic multi-center trials. Provincial centralized procurement mechanisms under healthcare security administration oversight compress realized pricing for mature stent categories. Stakeholders must monitor NMPA innovation approval pathway utilization rates and provincial volume-based purchasing expansion to calibrate portfolio prioritization between premium technology segments and cost-optimized platforms.
Market Dynamics
Provincial volume-based purchasing mechanisms are compressing realized pricing for mature stent categories while simultaneously accelerating catheterization laboratory expansion in tier-three hospitals across Jiangsu and Guangdong provinces.
Growth Catalysts
- NMPA Streamlined Review Pathway:The regulator's innovation approval track compresses domestic device development timelines by reducing redundant clinical evidence requirements for breakthrough cardiovascular technologies.
- Bioresorbable Polymer Scaffolds:These 24-month degradation window platforms eliminate permanent metal implant complications and enable complete vascular restoration in younger patient cohorts.
- Electrophysiology Procedure Volume Concentration:Atrial fibrillation ablation demand clusters in Beijing and Shanghai tertiary centers, pulling specialized catheter system adoption ahead of peripheral market penetration.
Market Restraints
- Cobalt-Chromium Alloy Input Volatility:Specialty alloy pricing fluctuations squeeze gross margins on bare-metal and drug-eluting stent platforms already under procurement pressure.
- GB Standard Compliance Burden:Mandatory biocompatibility testing under ISO 10993 series protocols extends pre-market timelines by 8-14 months for novel material introductions.
- Structural Heart Surgery Substitution:Transcatheter valve repair platforms capture intermediate-risk patients previously routed to surgical valve replacement, constraining surgical device addressable markets.
Strategic Opportunities
- Western Province Hospital Infrastructure:Sichuan and Shaanxi tier-two facilities lack catheterization laboratory density, creating whitespace for electrophysiology system deployment.
- AI-Integrated Mapping Convergence:Machine learning algorithms fused with 3D electroanatomical mapping reduce procedure time and fluoroscopy exposure in complex arrhythmia cases.
- Dual Carbon Policy Tailwinds:MEE manufacturing emission standards incentivize domestic production facility upgrades that align with NMPA quality system modernization requirements.
Industry Challenges
- Interventional Cardiologist Supply Bottleneck:Fellowship-trained electrophysiology specialists concentrate in coastal provinces, limiting procedure capacity expansion in interior regions despite installed equipment base.
- Class III Certification Timeline Compression:Multi-center domestic trial requirements and post-market surveillance obligations strain regulatory affairs team bandwidth across mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Cardiovascular Devices Market |
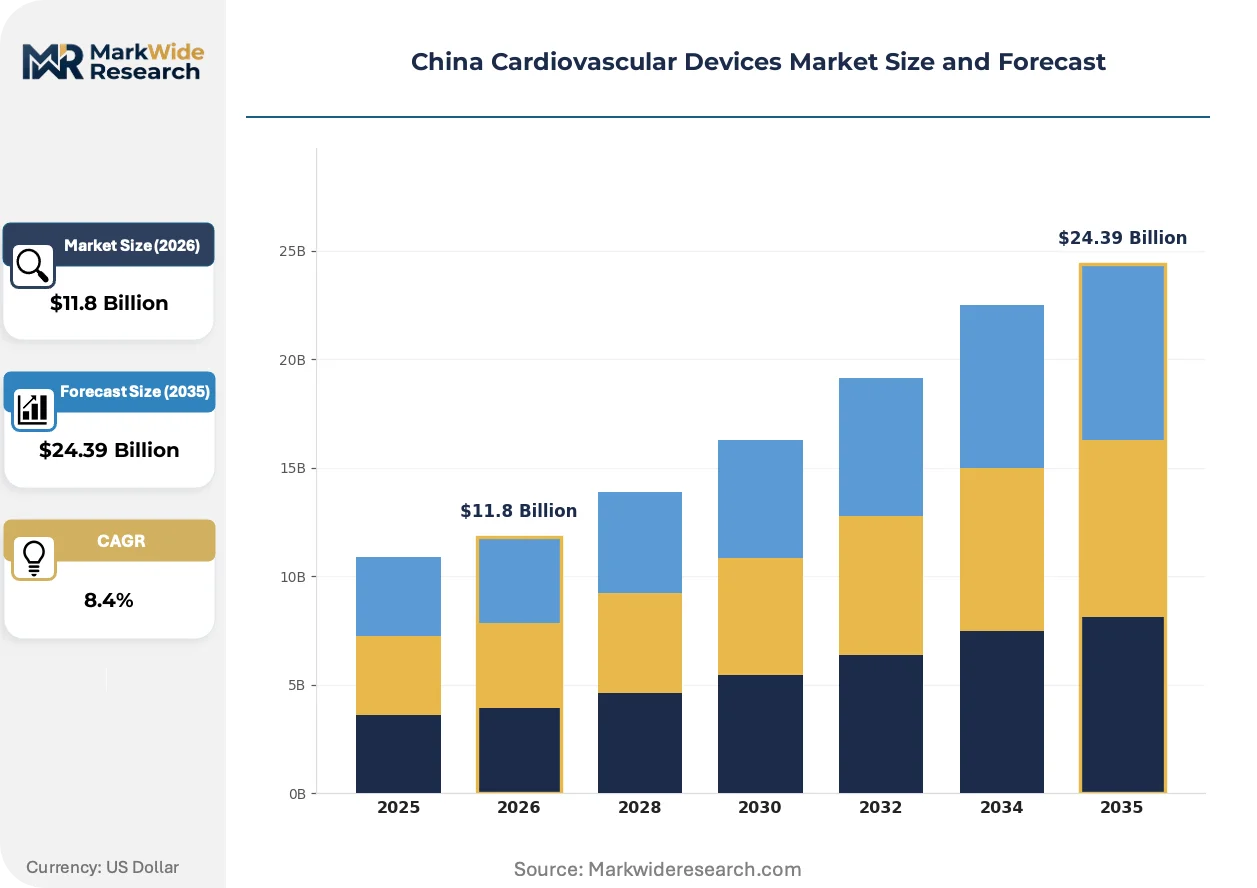
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Catheters, Pacemakers, Valves End User: Hospitals, Clinics, Specialty Cardiac Centers, Rehabilitation Facilities Technology: Angioplasty, Bioresorbable Stents, Electrophysiology, Ultrasound Application: Coronary Diseases, Arrhythmias, Heart Valve Disorders, Peripheral Artery Disease |
| Companies Covered | Mindray Medical International Limited, Abbott Laboratories, Lepu Medical Technology (Beijing) Co Ltd, Terumo Corporation, Boston Scientific Corporation, MicroPort Scientific Corporation, Medtronic PLC, Edwards Lifesciences, Kossel Medtech (Suzhou) Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Cardiovascular Devices Market Strategic Shifts
Minimally invasive coronary intervention techniques are restructuring procedural economics and device selection criteria across China's hospital procurement hierarchies.
Bioresorbable stent technology is displacing permanent metal platforms in younger patient segments seeking long-term vascular patency without implant-related complications. Tertiary hospital interventional cardiologists in Beijing and Shanghai are adopting these polymer scaffolds for de novo lesions in patients under 65 years. The shift is compressing conventional drug-eluting stent premium pricing power and forcing manufacturers to recalibrate portfolio mix toward resorbable platforms.
NMPA's innovation approval pathway is accelerating domestic cardiovascular device commercialization by parallel-tracking technical review and quality system inspection processes. Domestic manufacturers leveraging this track achieve market authorization 30-40% faster than standard Class III review timelines. Electrophysiology catheter systems and novel ablation technologies are capturing disproportionate benefit from this regulatory efficiency.
Hospital procurement committees are consolidating supplier relationships around full-procedure platform vendors capable of delivering stent, balloon, and accessory bundles under single tender awards. This behavior is displacing standalone product purchasing and favoring integrated portfolio manufacturers. The pattern concentrates in Guangdong and Jiangsu provincial centralized purchasing pools where volume aggregation authority sits with healthcare security administration oversight bodies.
China Cardiovascular Devices Market Segmentation
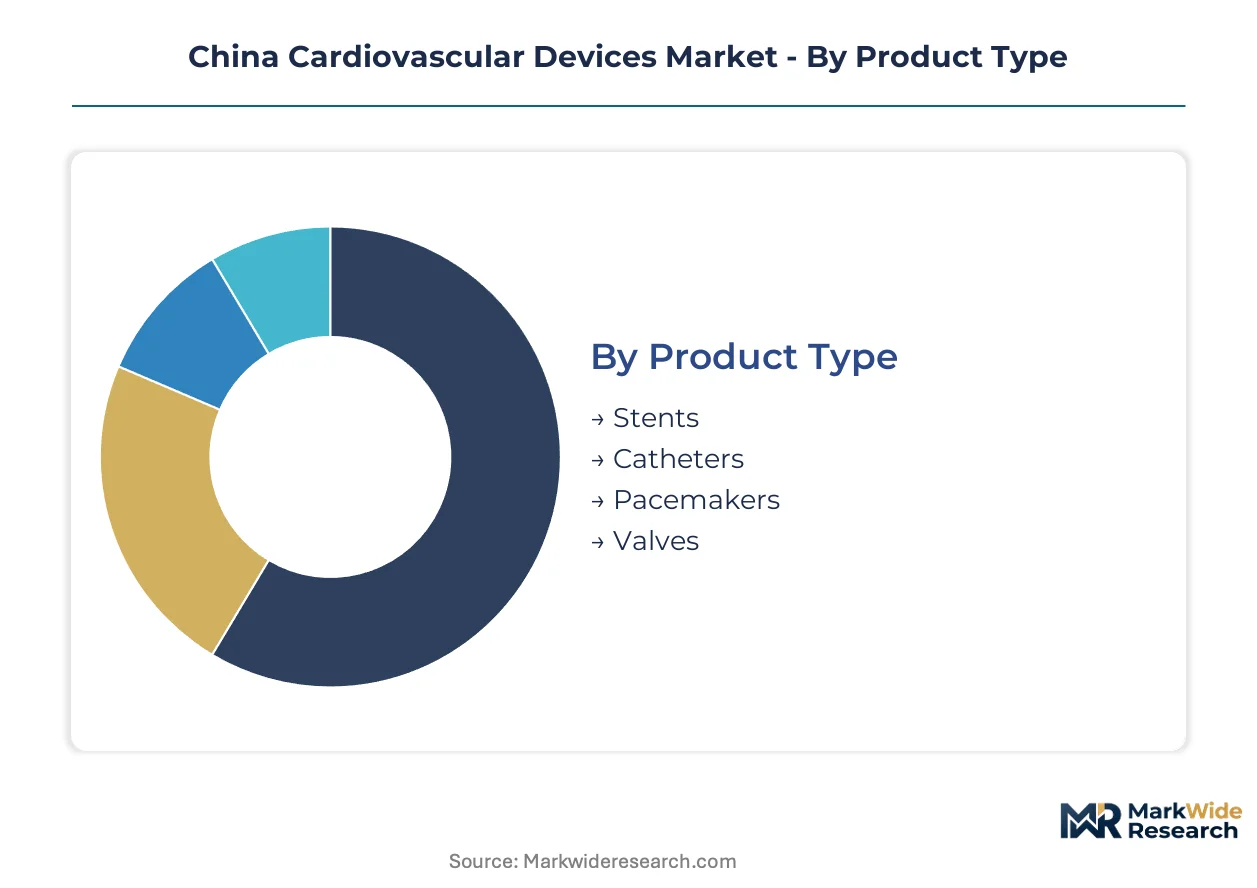
China's cardiovascular device segmentation reflects divergent regulatory pathways and procurement hierarchies. NMPA Class III certification requirements create distinct commercialization timelines across material platforms and intervention modalities.
Product Type:
NMPA technical review intensity varies by implant permanence and material novelty, shaping manufacturer portfolio prioritization and clinical evidence investment.
- Stents:Cobalt-chromium alloy and polymer scaffold platforms dominate installed base volumes. Provincial centralized procurement in Jiangsu and Guangdong compresses drug-eluting stent pricing while bioresorbable variants command premium positioning through NMPA innovation pathway designation.
- Catheters:Electrophysiology ablation and diagnostic catheter systems represent the fastest-expanding margin pool. Beijing and Shanghai tertiary centers drive specialized catheter adoption for complex arrhythmia cases ahead of peripheral market penetration.
- Pacemakers:Implantable pulse generator systems face extended biocompatibility testing under ISO 10993 protocols.
- Valves:Transcatheter repair platforms capture intermediate-risk patients from surgical replacement pools.
Established volume favors stents; emerging adoption favors catheters.
End User:
Facility tier determines reimbursement bandwidth and procurement committee authority, concentrating premium technology access in coastal urban centers.
- Hospitals:Tier-three public institutions in Guangdong and Jiangsu provinces anchor catheterization laboratory expansion and centralized purchasing volume aggregation.
- Specialty Cardiac Centers:Beijing and Shanghai tertiary electrophysiology hubs concentrate fellowship-trained interventional cardiologist supply and complex procedure economics.
- Clinics:Diagnostic and post-interventional monitoring functions cluster in urban outpatient networks.
- Rehabilitation Facilities:Post-acute cardiac recovery programs drive secondary device utilization for monitoring and therapeutic support.
Procurement authority concentrates in hospitals; specialized capability concentrates in cardiac centers.
Technology:
Material degradation timelines and energy delivery modalities differentiate regulatory evidence requirements and reimbursement positioning.
- Bioresorbable Stents:Polymer scaffold platforms with 24-month vascular restoration windows eliminate permanent metal complications. Younger patient cohorts in Beijing and Shanghai tertiary centers drive de novo lesion adoption for patients under 65 years.
- Electrophysiology:3D electroanatomical mapping and ablation catheter systems reduce fluoroscopy exposure. Atrial fibrillation procedure volumes in coastal provinces pull specialized system deployment ahead of interior market development.
- Angioplasty:Balloon catheter and conventional stent delivery systems anchor mature intervention economics.
- Ultrasound:Intravascular imaging and therapeutic ultrasound platforms support procedure guidance and optimization.
Clinical validation maturity favors angioplasty; technology substitution momentum favors bioresorbable platforms.
Application:
Disease prevalence patterns and intervention risk stratification shape addressable market sizing and technology platform selection criteria.
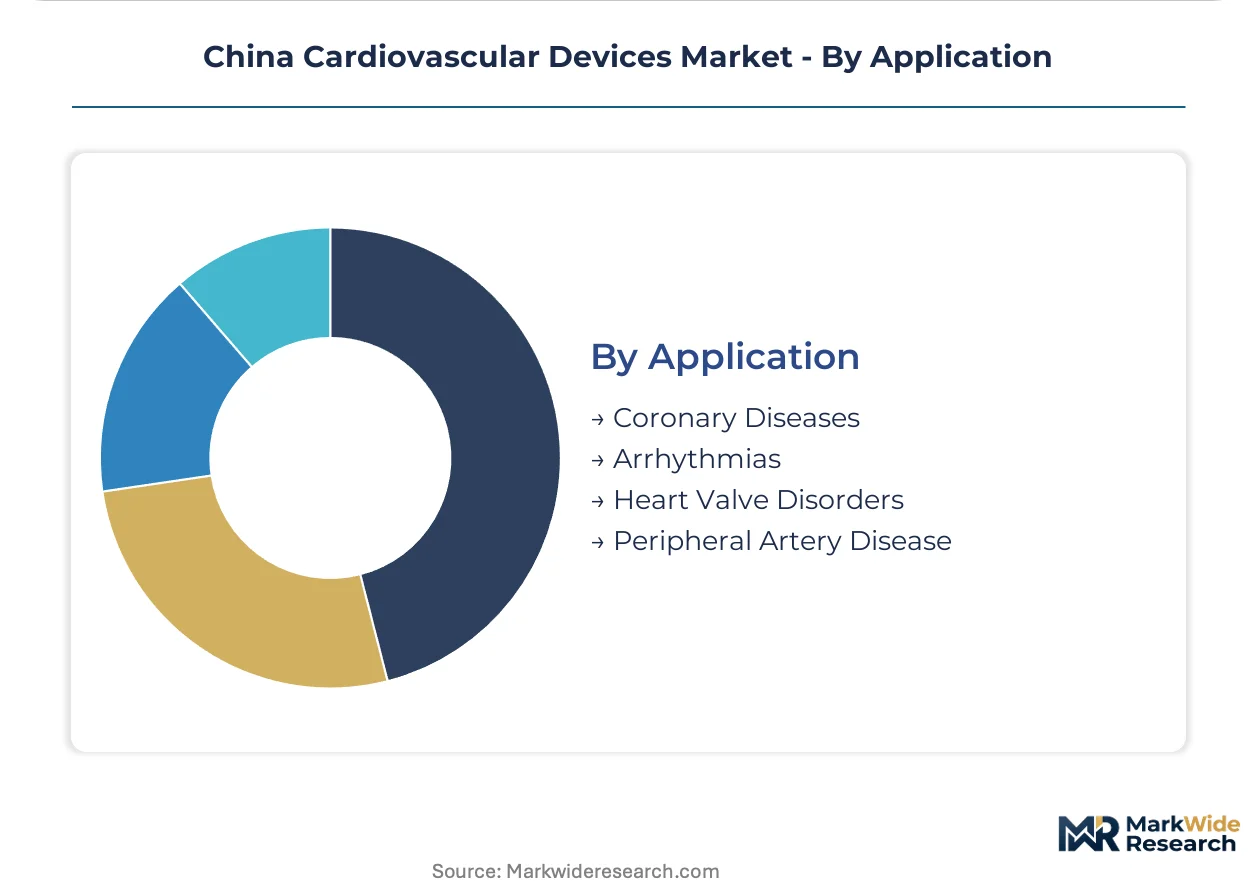
- Coronary Diseases:De novo lesion intervention and revascularization procedures anchor stent and angioplasty system demand. Tier-three hospital catheterization laboratory expansion in Sichuan and Shaanxi creates whitespace for procedural volume growth.
- Arrhythmias:Atrial fibrillation ablation volumes concentrate in Beijing and Shanghai tertiary centers. Electrophysiology specialist supply bottlenecks constrain procedure capacity expansion in interior provinces despite equipment installation.
- Heart Valve Disorders:Transcatheter repair platforms displace surgical replacement in intermediate-risk patient segments.
- Peripheral Artery Disease:Lower-limb revascularization procedures drive specialized catheter and stent platform development.
Procedure volume scale favors coronary applications; margin expansion favors arrhythmia interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across China's cardiovascular device market diverge sharply between coastal innovation hubs and interior expansion zones, with bioresorbable stent adoption clustering in Beijing and Shanghai while tier-three hospitals in western provinces drive volume procurement of conventional platforms.
Yangtze River Delta
Jiangsu province anchors catheterization laboratory expansion through tier-three public hospital infrastructure investments. NMPA's innovation approval pathway accelerates domestic device commercialization for manufacturers headquartered in Suzhou and Nanjing. Shanghai tertiary centers concentrate electrophysiology specialist supply and complex arrhythmia procedure economics.
Pearl River Delta
Guangdong provincial centralized purchasing pools aggregate volume procurement authority under healthcare security administration oversight. GB standard compliance frameworks shape product development timelines for Shenzhen and Dongguan manufacturers. Guangzhou hospitals lead bioresorbable stent adoption in younger patient cohorts seeking permanent implant alternatives.
Beijing-Tianjin-Hebei
Beijing's tertiary electrophysiology hubs drive specialized catheter system adoption ahead of national market penetration. NMPA Class III certification requirements enforce biocompatibility testing protocols that extend pre-market timelines for novel material introductions. Tianjin manufacturing clusters supply cobalt-chromium alloy components for stent platforms.
Sichuan-Chongqing
Western province hospital infrastructure gaps create whitespace for catheterization laboratory deployment in tier-two facilities. Provincial volume-based purchasing mechanisms compress realized pricing for mature stent categories while expanding addressable procedure volumes. Chengdu anchors regional distribution networks serving interior electrophysiology equipment installation.
Shandong Peninsula
Qingdao and Jinan medical device manufacturing bases supply domestic stent and balloon catheter platforms. MEE manufacturing emission standards incentivize production facility upgrades aligning with NMPA quality system modernization. Regional hospitals participate in national centralized procurement while building interventional cardiologist training capacity.
China Cardiovascular Devices Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in China's cardiovascular device market structure. Domestic manufacturers leverage manufacturing scale and NMPA regulatory familiarity to anchor pricing power in mature stent segments. Multinational corporations sustain technology leadership through structural heart and electrophysiology platforms. Competitive dynamics center on portfolio diversification into bioresorbable materials and strategic partnerships for AI-integrated mapping systems.
Among multinational anchors, Abbott Laboratories and Boston Scientific Corporation occupy positions exemplifying integrated cardiovascular portfolio breadth. Domestic scale specialists include Lepu Medical Technology (Beijing) Co Ltd and MicroPort Scientific Corporation, representing archetypes of NMPA pathway utilization and provincial procurement aggregation. Mindray Medical International Limited anchors diversified medical device manufacturing capabilities spanning multiple intervention modalities.
| Leading Market Players |
|---|
| Mindray Medical International Limited |
| Abbott Laboratories |
| Lepu Medical Technology (Beijing) Co Ltd |
| Terumo Corporation |
| Boston Scientific Corporation |
| MicroPort Scientific Corporation |
| Medtronic PLC |
| Edwards Lifesciences |
| Kossel Medtech (Suzhou) Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Fourteen-month pre-market timelines for novel cobalt-chromium alloy introductions concentrate supply-side leverage among Tianjin-based component manufacturers, compressing margin buffers for mid-scale stent assemblers while amplifying pricing power for integrated raw-material processors serving NMPA-certified facilities.
Pricing Analysis
Long-term offtake contracts dominate procurement between tier-three hospital systems and established stent manufacturers, though spot purchasing persists for emergency catheterization laboratory restocking. Three-tier pricing structure across premium bioresorbable scaffolds, standard drug-eluting platforms, and economy bare-metal variants reflects NMPA innovation pathway designation and volume scale. Cost compression in mature stent categories intensifies because Jiangsu and Guangdong provincial centralized purchasing pools aggregate demand under healthcare security administration oversight. Price-sensitive buyers cluster in western province tier-two facilities expanding catheterization laboratory capacity, while Beijing and Shanghai tertiary centers demonstrate reduced sensitivity for electrophysiology ablation systems.
Supply Chain Analysis
Strategic stockpiling of cobalt-chromium alloy feedstock characterizes tier-one manufacturer inventory strategy, insulating against specialty metal price volatility that squeezes gross margins on bare-metal and drug-eluting stent platforms. Domestic supply concentrates in Tianjin alloy processing clusters and Suzhou polymer scaffold fabrication facilities, with critical nitinol wire inputs drawing from United States and European specialty metallurgy suppliers. Single-source vulnerability permeates bioresorbable polymer precursor supply, where proprietary degradation-timeline formulations hinge on captive relationships with academic spin-out chemistry providers. Distribution runs through provincial medical device procurement platforms under healthcare security administration oversight, with hospital system GPO contracts consolidating supplier relationships around full-procedure platform vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity characterizes this market as interventional cardiologist supply bottlenecks in interior provinces create service-capability gaps that specialized device vendors can exploit through targeted capability-building partnerships.
For Market Incumbents: Consolidate supplier relationships around electrophysiology catheter system portfolios capable of delivering full-procedure bundles under single tender awards, defending against standalone product displacement by integrated competitors. Deepen backward integration into cobalt-chromium alloy processing to offset raw material volatility squeezing margins on mature stent categories already under provincial procurement pressure. Anchor pricing power through NMPA innovation pathway utilization for bioresorbable scaffold platforms. For New Entrants and Emerging Players: NMPA streamlined review pathway designation offers accelerated market authorization timelines for breakthrough cardiovascular technologies, enabling faster commercialization than standard Class III review tracks. Target Sichuan and Shaanxi tier-two hospital infrastructure gaps where catheterization laboratory density lags coastal provinces, creating whitespace for electrophysiology system deployment. Pursue AI-integrated 3D electroanatomical mapping convergence as differentiated go-to-market positioning for complex arrhythmia cases. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational cardiovascular divisions seeking to divest mature stent portfolios under sustained pricing compression from Chinese provincial volume-based purchasing mechanisms. Five-to-ten year viability framing favors electrophysiology and structural heart platforms capturing procedure volume concentration in Beijing and Shanghai tertiary centers. Monitor NMPA innovation approval pathway utilization rates as inflection indicator for domestic manufacturer competitive positioning against multinational technology leaders.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Innovation Pathway Utilization | Domestic manufacturers achieve 30-40% faster market authorization than standard Class III review timelines. |
| Provincial GPO Contract Consolidation | Hospital procurement committees aggregate supplier relationships around full-procedure platform vendors in Jiangsu and Guangdong. |
| Bioresorbable Polymer R&D Investment | Twenty-four-month degradation window platforms eliminate permanent metal implant complications for younger patient cohorts. |
| Electrophysiology Specialist Training Partnerships | Fellowship capacity expansion in interior provinces addresses interventional cardiologist supply bottlenecks constraining procedure volume. |
| Cobalt-Chromium Alloy Backward Integration | Tianjin manufacturing clusters supply critical components while insulating against specialty metal input volatility. |
Study Parameters
Operator-level perspectives from interventional cardiologists, hospital procurement committee directors, biomedical engineers, and GPO contracts managers anchored the qualitative base for this cardiovascular device market assessment. Primary field engagement combined structured interviews with secondary validation against NMPA Class III registration filings, provincial centralized procurement databases, hospital procurement records, and GB standard compliance documentation. Bottom-up procedure volume modeling and top-down market sizing triangulation ensured cross-verification of segment-level estimates.
Sensitivity analysis across pricing elasticity assumptions and regulatory timeline scenarios informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, end-user facility tier, material technology platform, and application area, with provincial procurement policy evolution treated as orthogonal scenario variable. CAGRs derived from fitted growth curves applied to base-year estimates, incorporating electrophysiology procedure volume trajectories and bioresorbable stent adoption curves as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained NMPA innovation pathway throughput or accelerated western province hospital infrastructure investment would require recalibration. Forecasts reflect documented assumptions regarding interventional cardiologist training pipeline expansion and provincial volume-based purchasing mechanism coverage extension. Revision becomes warranted when electrophysiology specialist supply constraints or cobalt-chromium alloy input volatility cross thresholds that alter manufacturer margin structure or procedure capacity expansion feasibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Patient-Controlled Injectors Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
Heart Valves Market
Cardiovascular Devices
Intra-Aortic Balloon Pump (IABP) Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Global Cardiac Output Monitoring Devices Market
Cardiovascular Devices
Cardiovascular Surgical Devices Market
Cardiovascular Devices
Drug Eluting Stent (DES) Market
Cardiovascular Devices
Transcatheter Heart Valve Replacement (THVR) Market
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
Ventricular Fibrillation Treatment Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Artificial Blood Vessels Market