
 Atherectomy Devices Market | 2026-2036
Atherectomy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Atherectomy Devices Market Analysis
Nitinol is recalibrating catheter flexibility benchmarks across the atherectomy landscape. Boston Scientific Corporation leverages in-house alloy sourcing to dominate peripheral orbital systems. Medtronic anchors its position through mechanical debulking platforms with integrated aspiration. Abbott Laboratories differentiates via optical coherence tomography compatibility in coronary applications.
Atherectomy devices are catheter-based systems employing cutting, grinding, or ablative mechanisms to excise calcified or fibrotic plaque from arterial lumens, typically requiring 6-8 French guiding catheter compatibility and rotational speeds exceeding 80,000 RPM for effective lesion modification. These instruments restore vessel patency in obstructed peripheral and coronary arteries where balloon angioplasty alone proves insufficient. Directional atherectomy retains mature utility in femoropopliteal segments while imaging-enabled devices capture expanding margin pools through real-time tissue characterization. Rotational platforms sustain volume leadership in calcified coronary lesions where burr sizing precision determines procedural safety.
FDA 510(k) clearance pathways govern device commercialization in the United States while the EU MDR and CE marking requirements impose strengthened clinical evidence standards for European market access. Japan's PMDA maintains distinct pharmaceutical and medical device agency oversight with localized clinical trial expectations for coronary indications. Stakeholders must monitor reimbursement coding evolution for atherectomy-specific Current Procedural Terminology designations and corresponding diagnosis-related group classifications that determine hospital purchasing cycles.
Market Dynamics
Nitinol alloy sourcing constraints and imaging-guided procedure adoption are compressing competitive timelines across catheter-based plaque excision systems. Device manufacturers must now secure captive supply chains for shape-memory materials while integrating optical coherence tomography compatibility into next-generation platforms.
Growth Catalysts
- FDA 510(k) Pre-market Notification:Streamlined clearance pathways for predicate-based submissions accelerate time-to-revenue for rotational and orbital platform iterations.
- Outpatient Surgical Centers:Ambulatory facility expansion in the United States shifts procedure volume away from inpatient settings, expanding addressable site counts for catheter-based systems.
- Calcified Lesion Prevalence:Aging demographics in Germany and Japan generate sustained clinical need for mechanical debulking where balloon angioplasty demonstrates insufficient luminal gain.
Market Restraints
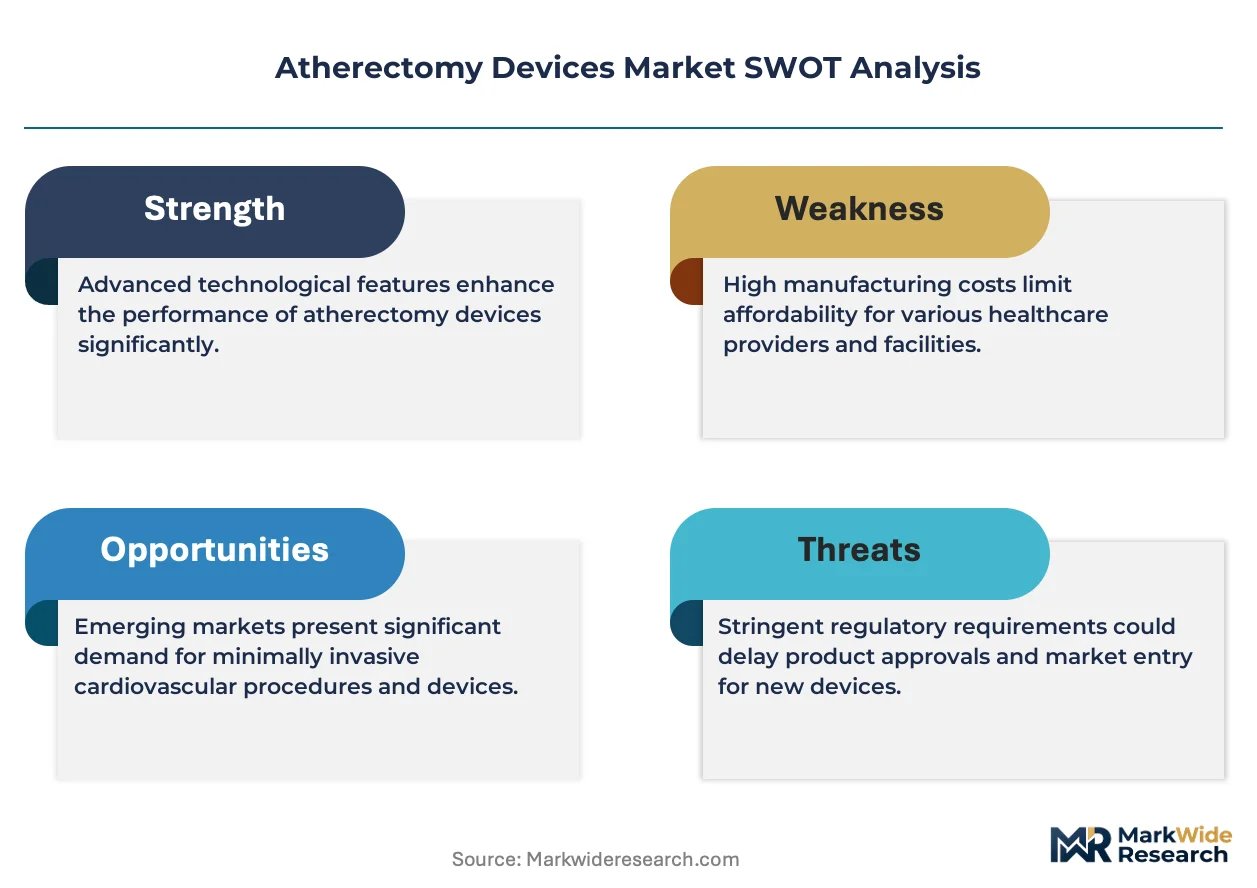
- Nitinol Raw Material Concentration:Shape-memory alloy production concentrates among limited specialty metallurgical suppliers, exposing device manufacturers to input cost volatility and allocation risk.
- EU MDR Clinical Evidence Requirements:Strengthened post-market surveillance and clinical data mandates under European Medical Device Regulation extend certification timelines and inflate regulatory compliance expenditure.
- Drug-Coated Balloon Substitution:Paclitaxel-eluting balloon platforms compete for femoropopliteal lesion treatment, particularly in moderate calcification cases where atherectomy adds procedural complexity without proven patency superiority.
Strategic Opportunities
- Japan PMDA Coronary Pathway:Localized clinical trial infrastructure and reimbursement negotiation frameworks create first-mover advantages for imaging-integrated devices targeting calcified coronary lesions.
- Optical Coherence Tomography Convergence:Real-time tissue characterization through integrated imaging catheters enables precise plaque modification endpoints, differentiating premium platforms from conventional mechanical systems.
- Direct-to-Ambulatory Distribution:Bypassing traditional hospital purchasing committees through specialized interventional cardiology distributors reduces sales cycle duration and improves margin capture.
Industry Challenges
- Interventional Cardiologist Training Requirements:Rotational atherectomy demands specialized burr sizing expertise and complication management protocols, limiting addressable operator pools and constraining procedure volume scalability.
- CE Marking Transition Complexity:Legacy device certifications under the Medical Devices Directive require technical documentation remediation and notified body reassignment, disrupting European market continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atherectomy Devices Market |
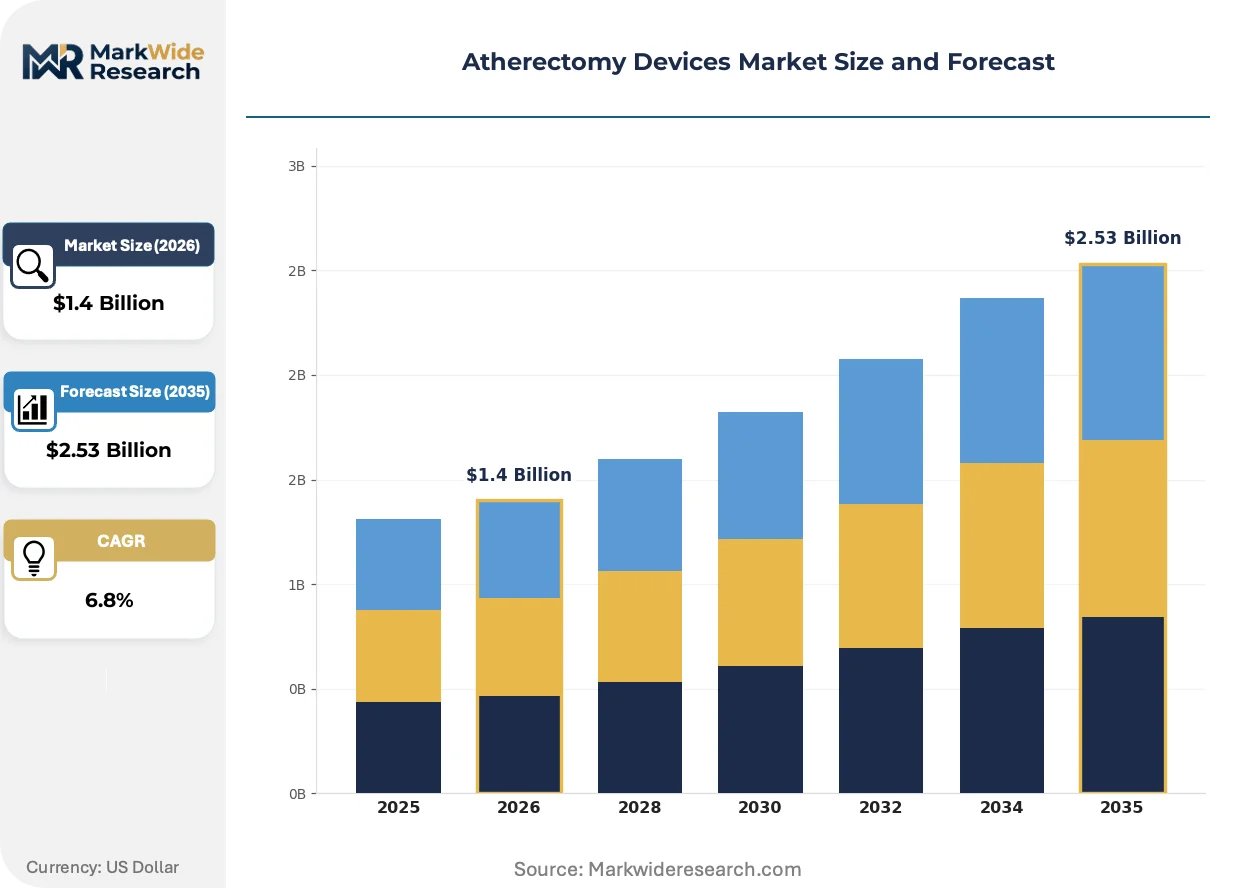
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circular Cutting, Directional, Laser, Rotational End User: Hospitals, Outpatient Surgical Centers, Specialty Clinics, Cardiovascular Institutes Application: Peripheral Artery Disease, Coronary Artery Disease, Venous Disease, Aneurysm Treatment Technology: Radiofrequency, Mechanical, Combination Devices, Imaging-Enabled Devices |
| Companies Covered | Boston Scientific Corporation, Medtronic, Cardiovascular Systems, Inc., Avinger, Koninklijke Philips N.V., BD, Abbott Laboratories, AngioDynamics, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atherectomy Devices Market Emerging Trajectories
Real-time intravascular imaging integration and single-use disposable economics are compressing device lifecycle expectations. Manufacturers must now engineer catheter platforms that combine mechanical debulking with tissue characterization while managing sterilization and materials cost structures.
Excimer laser atherectomy systems are rewriting treatment protocols for chronic total occlusions and in-stent restenosis. Interventional cardiologists in high-volume United States academic medical centers are adopting these platforms for lesions previously deemed un-crossable with conventional wire techniques. The technology is rewriting referral patterns by enabling percutaneous revascularization in patients who would otherwise face surgical bypass.
EU MDR Article 10 clinical evaluation requirements are tightening evidence standards for legacy device families. Manufacturers must now generate post-market clinical follow-up data or equivalent literature reviews for predicate-based submissions, inflating regulatory affairs headcount and documentation burden. Peripheral orbital systems with predicate lineages dating to the 1990s face particular scrutiny during notified body transition audits.
Hospital value analysis committees are consolidating purchasing authority for capital-intensive catheter systems. Interventional radiology and cardiology departments in United States integrated delivery networks now submit unified technology assessments, replacing specialty-specific procurement autonomy. This concentration demands economic outcome documentation and total cost-of-ownership modeling that device manufacturers rarely maintained under fragmented purchasing structures.
Atherectomy Devices Market Segmentation
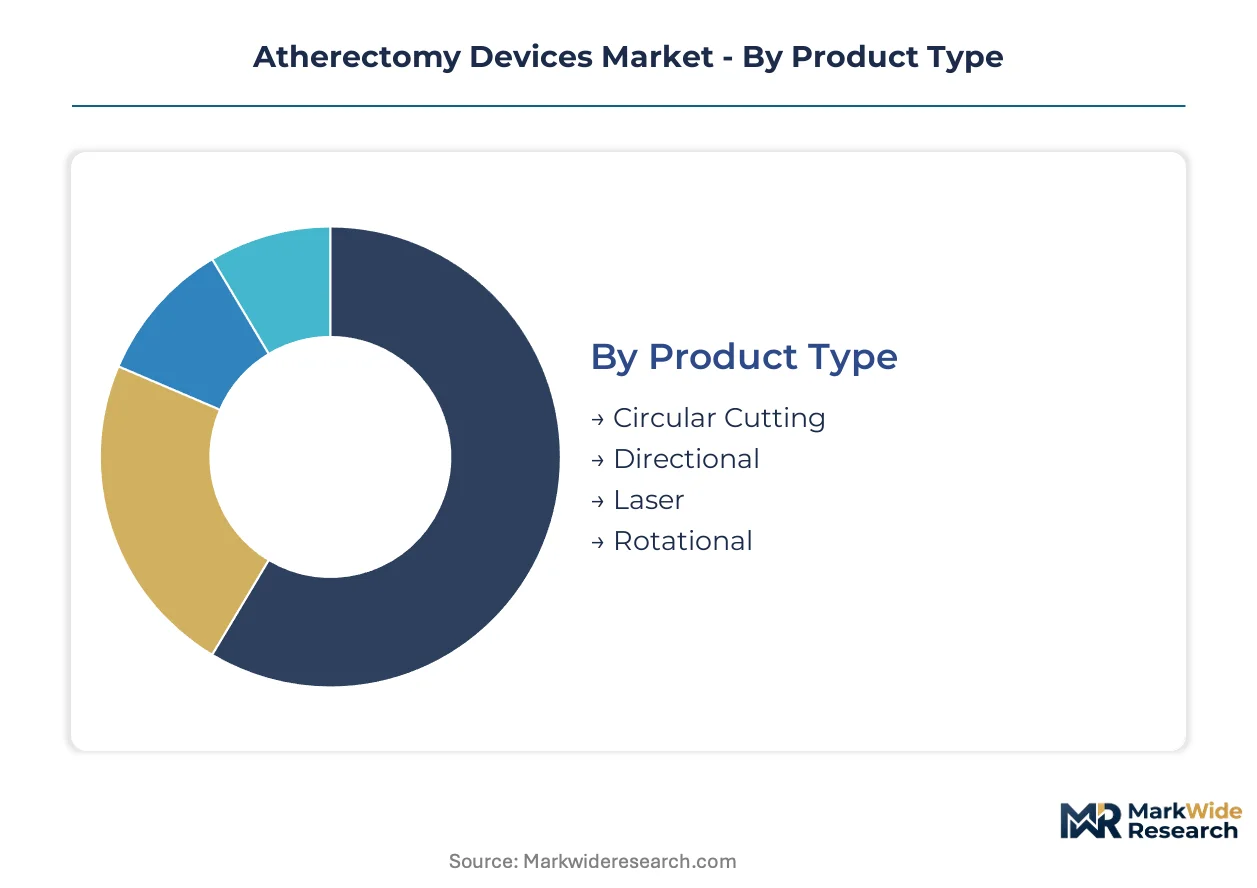
Atherectomy device segmentation reveals how technical specifications, clinical settings, and lesion characteristics intersect to determine purchasing patterns. Manufacturers must align platform engineering with specific arterial anatomies and reimbursement environments to capture procedure volume.
Product Type:
Rotational and orbital mechanisms dominate calcified coronary interventions where burr sizing precision governs safety margins.
- Rotational:Diamond-tipped burrs operating at 80,000+ RPM ablate calcified plaque through differential cutting. Demand concentrates in United States academic medical centers where interventional cardiologists manage complex coronary lesions requiring precise luminal modification.
- Directional:Cutting windows with adjustable depth settings excise fibrotic material while preserving vessel wall integrity. German hospitals favor these platforms for femoropopliteal segments where controlled tissue removal reduces distal embolization risk.
- Laser:Excimer systems deliver ultraviolet energy to vaporize chronic total occlusions without mechanical contact.
- Circular Cutting:Rotational atherectomy variants with circumferential blade arrays address concentric calcification patterns.
Rotational platforms lead on scale; laser systems lead on momentum for previously untreatable lesions.
End User:
Site-of-care economics and reimbursement coding determine capital deployment cycles across catheter-based systems.
- Hospitals:Integrated delivery networks maintain centralized value analysis committees that consolidate purchasing authority for high-cost interventional platforms. United States hospital systems negotiate multi-year service contracts bundling device supply with technical training.
- Outpatient Surgical Centers:Ambulatory facilities capture shifting peripheral procedure volume through streamlined scheduling and lower facility fees. United States freestanding centers exploit atherectomy-specific CPT code reimbursements to justify equipment acquisition.
- Specialty Clinics:Dedicated vascular access centers focus on dialysis circuit maintenance and recurrent stenosis management.
- Cardiovascular Institutes:Academic medical centers combine research protocols with high-complexity case referrals.
Hospitals retain volume leadership; outpatient surgical centers are expanding most quickly through site-of-care migration.
Application:
Lesion location and calcification burden dictate device selection across arterial territories.
- Peripheral Artery Disease:Femoropopliteal and infrapopliteal segments generate the largest procedure volumes where mechanical debulking precedes adjunctive therapies. Japanese reimbursement frameworks specifically cover directional atherectomy for critical limb ischemia cases.
- Coronary Artery Disease:Calcified lesions resistant to balloon dilatation require rotational or orbital modification before stent deployment. United States interventionalists increasingly integrate optical coherence tomography guidance to optimize burr sizing.
- Venous Disease:Deep vein thrombosis and post-thrombotic syndrome applications employ modified atherectomy techniques for venous stenosis.
- Aneurysm Treatment:Aortic and peripheral aneurysm interventions utilize atherectomy adjunctively to optimize landing zones.
Peripheral artery disease leads on scale; coronary applications show steepest expansion trajectory through imaging integration.
Technology:
Energy delivery modalities and visualization capabilities differentiate platform generations.
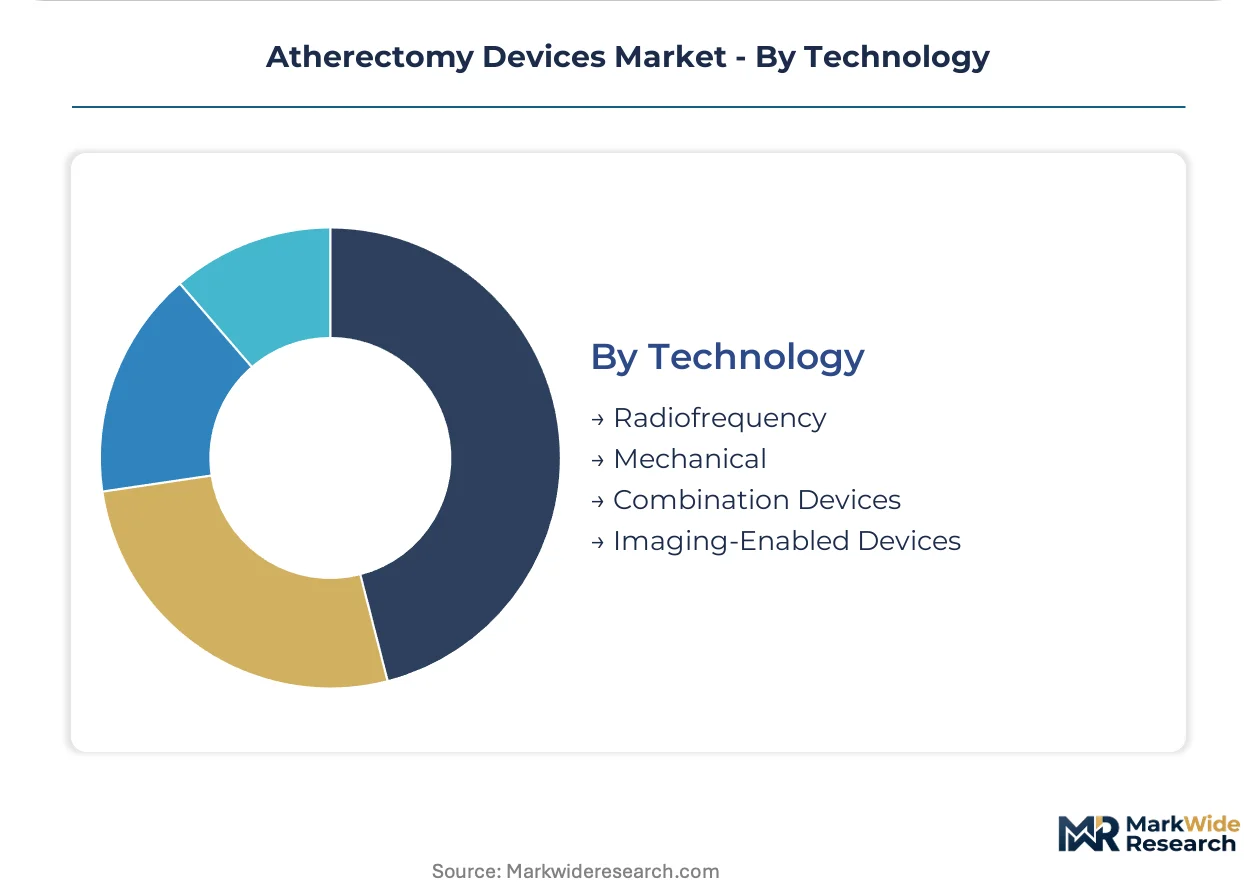
- Mechanical:Cutting, grinding, and sanding mechanisms remain the foundational technology with mature predicate pathways through FDA 510(k) submissions. Boston Scientific and Medtronic dominate this segment through established operator training programs.
- Imaging-Enabled Devices:Integrated intravascular ultrasound and optical coherence tomography catheters provide real-time tissue characterization. Abbott Laboratories differentiates coronary platforms through OCT compatibility that enables precise plaque modification endpoints.
- Radiofrequency:Thermal energy systems target fibrotic and calcified lesions through controlled resistive heating.
- Combination Devices:Hybrid platforms merge mechanical debulking with aspiration or drug delivery functions.
Mechanical systems lead on scale; imaging-enabled devices lead on momentum through procedure safety improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American atherectomy device innovation through dense interventional cardiology research infrastructure. FDA 510(k) clearance pathways and established reimbursement frameworks accelerate commercialization timelines for rotational and orbital platforms. The United States, Germany, and Japan concentrate procedure volume and regulatory precedent.
United States
Academic medical centers in Cleveland and Boston drive adoption of imaging-integrated atherectomy systems for calcified coronary lesions. FDA premarket notification requirements under 510(k) pathways govern predicate-based submissions for mechanical debulking platforms. The Texas Medical Center in Houston concentrates operator training programs and high-complexity case referrals.
Germany
University hospitals in Munich and Heidelberg favor directional atherectomy for femoropopliteal segments with controlled tissue removal protocols. CE marking under EU MDR Article 10 imposes strengthened clinical evidence standards for legacy device recertification. The Rhine-Main cluster around Frankfurt hosts notified body technical documentation review centers.
Japan
PMDA maintains distinct oversight for coronary indications with localized clinical trial expectations for imaging-enabled devices. Tokyo and Osaka medical centers generate sustained demand for mechanical debulking in aging patient populations. The Kobe biomedical cluster advances intravascular ultrasound integration with rotational platforms.
Switzerland
Swissmedic certification requirements align with EU MDR standards while permitting parallel market access negotiations. Basel and Zurich host vascular surgery conferences that shape European operator training curricula. The Lake Geneva region concentrates medical device regulatory consulting expertise for CE marking transition support.
United Kingdom
NICE technology appraisals influence NHS purchasing cycles for catheter-based interventional systems. London teaching hospitals and the Oxford-Cambridge corridor participate in multinational clinical trials for optical coherence tomography-guided procedures. The Midlands manufacturing base supplies nitinol components to European device assemblers.
Atherectomy Devices Market Vendor Landscape
Strategic partnerships dominate the current landscape as manufacturers secure captive nitinol supply chains and imaging technology licenses. The vendor base concentrates among diversified medical technology conglomerates with interventional cardiology portfolios and specialized catheter engineering firms. Three archetypes prevail: alloy-integrated manufacturers, imaging-platform developers, and procedure-training ecosystem builders. M&A activity and vertical integration into shape-memory materials represent the primary competitive vectors.
Among diversified conglomerates with interventional portfolios, Boston Scientific Corporation, Medtronic, and Abbott Laboratories exemplify distinct strategic positions. Boston Scientific Corporation anchors the orbital atherectomy segment through in-house nitinol sourcing capabilities. Medtronic occupies a central position in mechanical debulking platforms with integrated aspiration functions. Abbott Laboratories represents the imaging-convergence archetype through optical coherence tomography compatibility positioning.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Cardiovascular Systems, Inc. |
| Avinger |
| Koninklijke Philips N.V. |
| BD |
| Abbott Laboratories |
| AngioDynamics |
| Terumo Corporation |
| Others |
Supply Flow & Price Mechanics
Captive nitinol sourcing anchors supply positioning and pricing power for device manufacturers competing on catheter flexibility benchmarks. Alloy-integrated producers command premium positioning through in-house shape-memory material control, while outsourced suppliers face margin compression from raw material allocation risk and specialty metallurgical supplier concentration.
Pricing Analysis
Input-cost pass-through from nitinol alloy volatility shapes pricing stratification across mechanical debulking platforms. Three-tier pricing structure across premium, standard, and economy levels separates imaging-integrated systems with OCT compatibility from conventional rotational devices and refurbished capital equipment. Pricing pressure stems from drug-coated balloon substitution in moderate calcification cases where atherectomy adds procedural complexity without proven patency superiority. Outpatient surgical centers exhibit highest price sensitivity through ambulatory facility fee constraints, while academic medical centers prioritize imaging integration over unit economics.
Supply Chain Analysis
Reverse-logistics flows for catheter refurbishment and remanufacturing concentrate in United States and German service hubs serving European and North American installed bases. Nitinol raw material draws from limited specialty metallurgical suppliers in the United States and Germany, with shape-memory alloy wire and tubing feeding catheter assembly operations. Single-source vulnerability in nitinol production exposes manufacturers to input cost volatility and allocation constraints during demand surges. Distribution runs through specialized interventional cardiology distributors bypassing traditional hospital purchasing committees, reducing sales cycle duration for ambulatory facility penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The atherectomy devices market functions as a stable compounder anchored by aging demographics in Japan, Germany, and the United States generating sustained clinical need for mechanical debulking where balloon angioplasty demonstrates insufficient luminal gain.
For Market Incumbents: Deepen captive nitinol supply chain control through backward integration into shape-memory alloy sourcing or long-term offtake agreements with specialty metallurgical suppliers. Secure imaging technology licenses for optical coherence tomography compatibility to defend against drug-coated balloon substitution in moderate calcification cases. Fortify operator training ecosystems to constrain addressable pools for emerging entrants lacking procedural education infrastructure.
For New Entrants and Emerging Players: Enter via Japan PMDA coronary pathway leveraging localized clinical trial infrastructure and reimbursement negotiation frameworks for imaging-integrated devices targeting calcified coronary lesions. Target outpatient surgical centers in the United States through direct-to-ambulatory distribution models exploiting atherectomy-specific CPT code reimbursements. Position on excimer laser platforms for chronic total occlusion applications previously deemed un-crossable with conventional wire techniques.
For Investors and Strategic Acquirers: Roll-up economics work for specialized catheter engineering firms because device lifecycle compression and single-use disposable economics favor scale players with integrated manufacturing and regulatory affairs capabilities. Mid-cap manufacturers with predicate device lineages and established 510(k) submission track records present viable acquisition targets for platform consolidation. Monitor EU MDR notified body transition audit outcomes for legacy device families as inflection indicators for European market continuity risk.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined predicate-based clearance accelerates rotational platform iterations for United States commercialization. |
| CE Marking Pathway | EU MDR Article 10 compliance secures European market access for imaging-enabled catheter systems. |
| Hospital System Partnership | Integrated delivery network contracts bundle device supply with operator training and service agreements. |
| Software Companion Development | Optical coherence tomography integration enables real-time tissue characterization for precise plaque modification endpoints. |
| Reimbursement Strategy | Atherectomy-specific CPT code optimization drives outpatient surgical center equipment acquisition decisions. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body technical documentation. Bottom-up procedure volume modeling and top-down market sizing triangulated demand estimates across the analysis window.
Segment-weighting approaches distributed value and volume projections across product type, end user, application, and technology dimensions, with rotational, directional, laser, and orbital mechanisms each carrying distinct growth assumptions. CAGRs were derived from procedure volume elasticity to aging demographic penetration, reimbursement code expansion, and imaging integration adoption curves. Forecast inputs incorporated nitinol raw material allocation constraints, EU MDR transition timelines, and drug-coated balloon competitive substitution rates.
The model holds under stable regulatory clearance pathways and sustained reimbursement coverage; deviation in FDA predicate device scrutiny or CMS coding revisions would shift commercialization timelines. Forecasts reflect assumptions regarding operator training scalability and ambulatory site-of-care migration rates. Practitioners should monitor PMDA coronary indication approvals and EU MDR notified body capacity constraints for early signals of regional access expansion or contraction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Continuous Cardiac Monitoring Systems Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Global Pericardiocentesis Procedures Market
Cardiovascular Devices
Peripherally Inserted Central Catheters Market
Cardiovascular Devices
Cardiovascular Stents Market
Cardiovascular Devices
Global Heart Pump Devices Market
Cardiovascular Devices
Renal Denervation Devices Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Global Cardiovascular Ultrasound System Market
Cardiovascular Devices
Global Aortic Endografts Market
Cardiovascular Devices
Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
Global Cardiac Resynchronization Therapy Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market
Cardiovascular Devices
Abdominal Aortic Aneurysm (AAA) Repair Devices Market