
 Global Vascular Patch Market | 2026-2036
Global Vascular Patch Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vascular Patch Market Foresight
Modularization of patch kits with integrated sutures and pre-cut configurations is repositioning purchasing decisions toward bundled operating-room solutions. Baxter International leverages its integrated hospital supply contracts to anchor kit distribution across North American cardiac centers. W. L. Gore & Associates specializes in expanded polytetrafluoroethylene formulations that dominate high-strength anastomosis applications. LeMaitre Vascular competes through focused R&D intensity in biological patch sourcing and customization.
A vascular patch is a biocompatible implantable material used to close, reconstruct, or reinforce blood vessels during surgical procedures, typically manufactured from expanded polytetrafluoroethylene, bovine pericardium, or autologous vein segments with thickness ranging from 0.3 to 0.6 millimeters to match native arterial wall compliance. Its primary purpose is to restore vascular continuity without stenosis or thrombogenic complications following endarterectomy, aneurysmorrhaphy, or trauma repair. Synthetic patches in ePTFE and Dacron lead volume due to standardized availability and off-the-shelf deployment, while bovine and porcine biological variants command premium positioning in infected fields where resistance to bacterial colonization determines clinical selection. Cardiovascular surgery remains the dominant application channel, though dialysis access patch angioplasty represents the fastest-growing segment as hemodialysis populations expand.
The FDA's 510(k) pathway and the European Medicines Agency's Medical Device Regulation framework govern preclinical validation and post-market surveillance, with ISO 7198 setting dimensional and mechanical benchmarks for vascular prostheses. Japan's Pharmaceuticals and Medical Devices Agency imposes additional biocompatibility testing protocols that extend approval timelines for foreign manufacturers. China's National Medical Products Administration is aligning its technical review standards with global norms, reshaping market access calculus for multinational suppliers. Stakeholders must monitor evolving reimbursement thresholds for biological versus synthetic patches across national health systems to anticipate portfolio margin shifts.
Market Dynamics
Cardiovascular implant manufacturers face intensifying documentation burdens under the FDA's updated premarket submission requirements, forcing portfolio rationalization and accelerating consolidation among mid-tier suppliers unable to absorb compliance costs.
Growth Catalysts
- Biological Patch Sourcing:Bovine pericardium variants are displacing synthetic alternatives in infected surgical fields where bacterial colonization resistance determines clinical selection. Cardiovascular surgery suites in Germany and Japan are expanding procurement of biological configurations.
- Hemodialysis Access Expansion:Dialysis access patch angioplasty represents accelerating demand as end-stage renal disease populations expand across aging demographics. Hospital systems in the United States are prioritizing dedicated vascular access centers.
- ISO 7198 Harmonization:China's National Medical Products Administration is aligning technical review standards with global dimensional and mechanical benchmarks for vascular prostheses, streamlining market access for multinational suppliers.
Market Restraints
- Raw Material Concentration:Expanded polytetrafluoroethylene supply chains concentrate among specialty chemical manufacturers in the United States and Germany, creating input cost volatility for patch producers.
- Biocompatibility Testing Burden:Japan's Pharmaceuticals and Medical Devices Agency imposes extended approval timelines through additional testing protocols that foreign manufacturers must navigate.
- Synthetic Patch Limitations:ePTFE and Dacron variants face structural constraints in highly compliant arterial wall applications where thickness matching below 0.3 millimeters proves technically challenging.
Strategic Opportunities
- Modular Kit Expansion:Bundled operating-room solutions integrating pre-cut configurations with sutures are capturing purchasing decisions away from standalone patch procurement in North American cardiac centers.
- Peripheral Artery Disease Interventions:Underpenetrated patient populations in Japan present white-space expansion for biological patch deployment in femoral endarterectomy procedures.
- European MDR Alignment:The European Medicines Agency's Medical Device Regulation framework creates competitive advantage for manufacturers with established post-market surveillance infrastructure.
Industry Challenges
- Regulatory Documentation Talent:510(k) pathway submission expertise remains scarce among mid-sized manufacturers, extending time-to-market for product line extensions.
- Legacy System Integration:Hospital supply chain software in Germany requires custom API development to accommodate kit-based procurement workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vascular Patch Market |
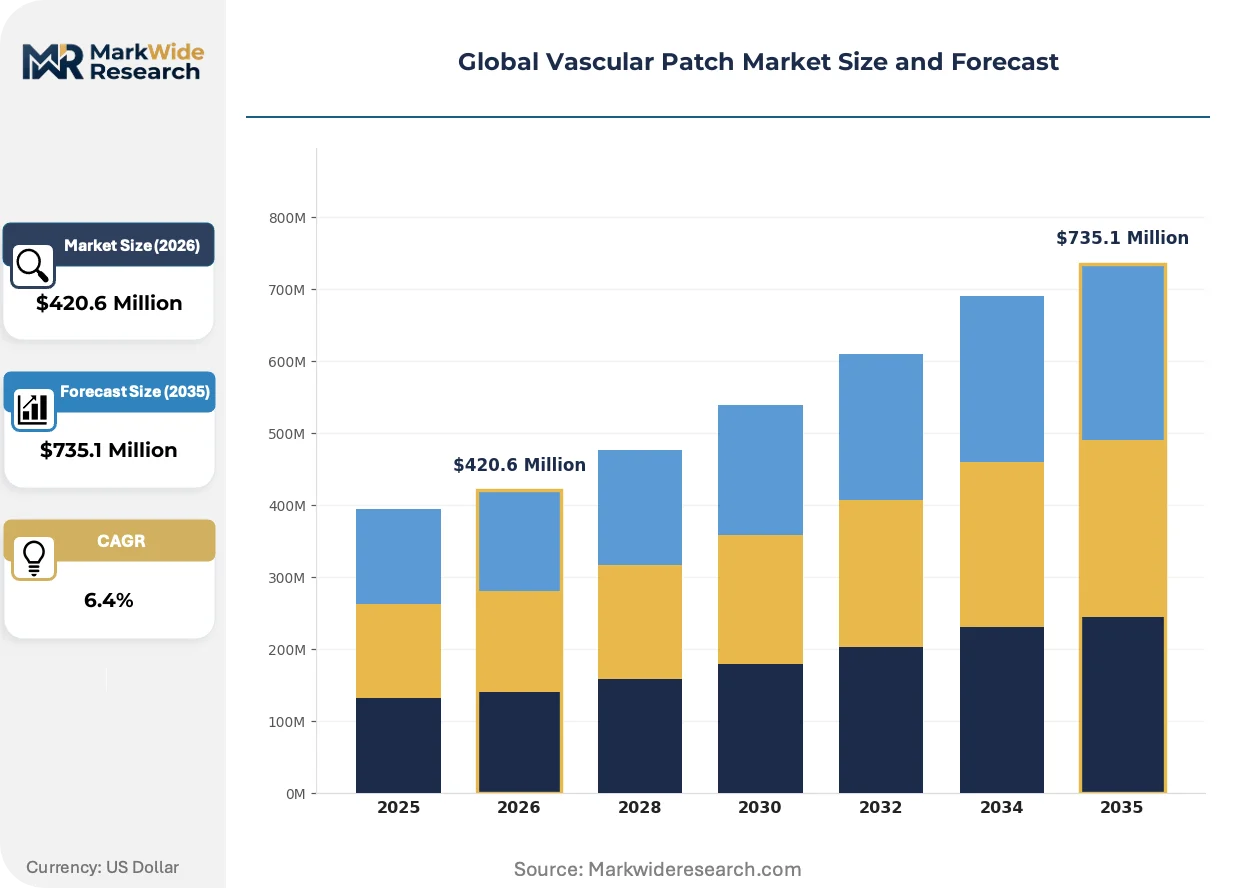
| Market Size in 2026 | $420.6 Million |
| Market Size in 2035 | $735.1 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous, Synthetic, Bovine, Porcine, Polymer-based Application: Cardiovascular Surgery, Peripheral Artery Disease, Dialysis Access, Trauma Repair, Aneurysm Treatment End User: Specialty Clinics, Cardiac Centers, Chronic Care Facilities, Ambulatory Surgery Centers Material: Expanded Polytetrafluoroethylene, Dacron, Collagen, Silk, Polyurethane |
| Companies Covered | Baxter International, LeMaitre Vascular, W. L. Gore & Associates, B. Braun Melsungen AG, Edwards Lifesciences Corporation, Getinge AB, Terumo Corporation, Medtronic, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vascular Patch Market Shifts & Advancements
Material science convergence with digital surgical planning is reconfiguring how vascular patches are specified, manufactured, and deployed across cardiovascular service lines.
Bioresorbable scaffold technologies are absorbing development resources from traditional permanent implants. Research consortia in Germany and Japan are advancing polycaprolactone and polyglycolic acid formulations that match native arterial compliance during the critical 6-12 month remodeling window. Cardiovascular surgery training programs in the United States are absorbing these materials into fellowship curricula ahead of commercial availability.
The European Union's Medical Device Regulation is compressing approval timelines for biological products with established predicate histories while extending scrutiny for novel synthetic formulations. Manufacturers with legacy bovine pericardium portfolios are accelerating MDR technical documentation to defend market position. Japanese regulators are observing EMA implementation patterns to inform PMDA guidance updates.
Hospital procurement committees are consolidating vendor relationships around integrated supply contracts that bundle patches with sutures, sealants, and access devices. Cardiac centers in the United States are displacing fragmented purchasing through single-source agreements with distributors holding comprehensive cardiovascular implant portfolios. German hospital systems are piloting consignment inventory models that transfer carrying cost risk to suppliers.
Global Vascular Patch Market Segmentation
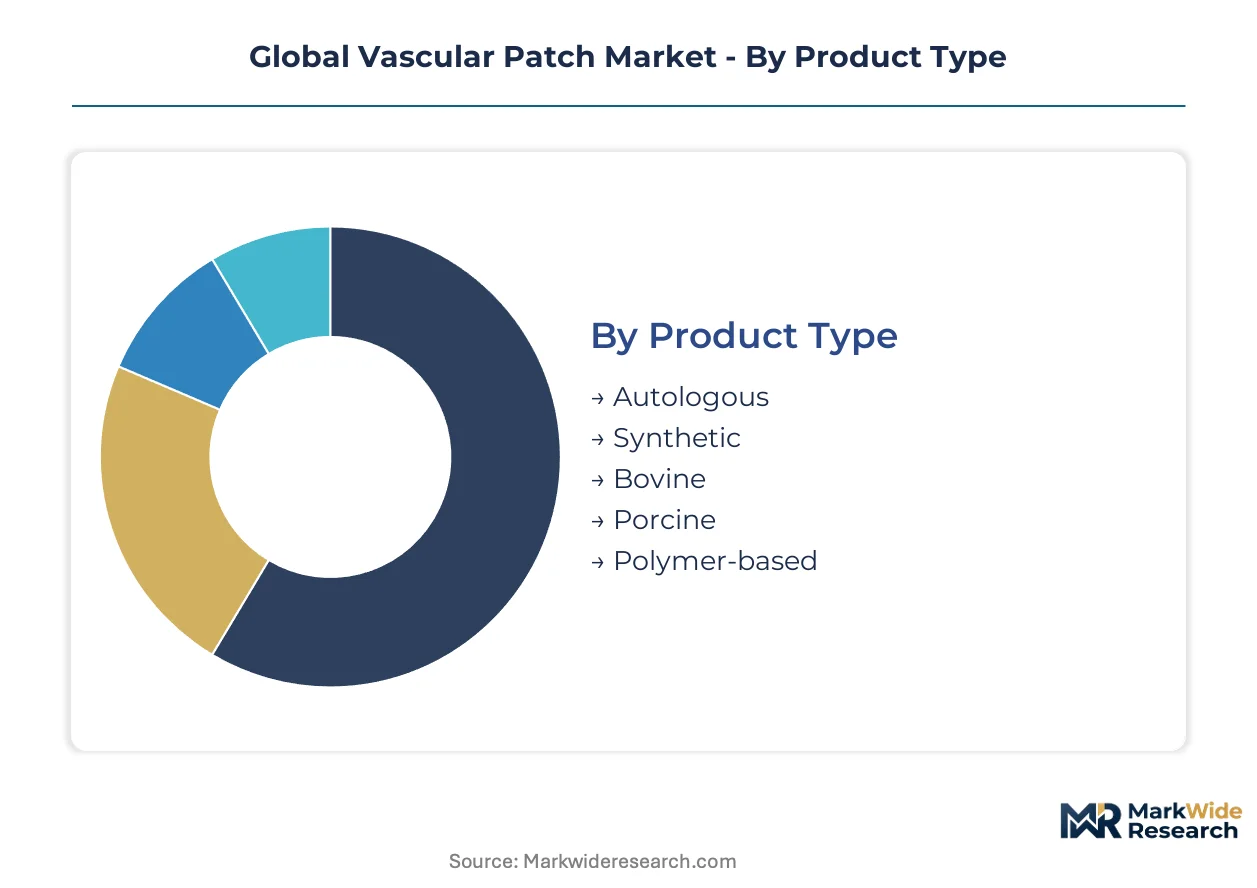
Vascular patch procurement diverges sharply across clinical settings, with standalone implant sales dominating high-volume cardiac centers while integrated kit configurations capture ambulatory workflows. Material selection and application context determine margin structures more than volume scale alone.
Product Type:
Synthetic patches operate as standalone implants with standardized deployment protocols, while biological variants increasingly embed within pre-configured surgical kits requiring specialized handling workflows.
- Synthetic:Expanded polytetrafluoroethylene and Dacron formulations deliver consistent mechanical properties for high-throughput cardiovascular surgery suites in the United States. Hospital procurement committees favor these configurations for predictable reimbursement coding and off-the-shelf availability.
- Bovine:Pericardium-derived patches demonstrate superior resistance to bacterial colonization in infected surgical fields across German cardiac centers. Premium positioning reflects extended biocompatibility validation and specialized cold-chain logistics requirements.
- Autologous:Patient-derived vein segments eliminate rejection risk but require intraoperative harvesting time that constrains throughput in Japanese hospital systems.
- Porcine:Biological alternatives from porcine sources offer thickness profiles below 0.4 millimeters for small-vessel applications in peripheral artery disease interventions.
- Polymer-based:Emerging polycaprolactone scaffolds integrate with digital surgical planning platforms for patient-specific sizing in research consortia.
Synthetic patches lead volumes today; bovine configurations are gaining share fastest in infected-field applications.
Application:
Procedure complexity and reimbursement tiering separate high-margin cardiovascular reconstruction from volume-driven dialysis access maintenance.
- Cardiovascular Surgery:Open-heart procedures utilizing patches for endarterectomy and aneurysmorrhaphy command premium pricing in United States academic medical centers. Recovery in elective procedure volumes is expanding procurement budgets for biological configurations.
- Dialysis Access:Patch angioplasty for hemodialysis fistula maintenance represents accelerating demand as end-stage renal disease populations expand across aging demographics in Japan. Ambulatory surgery centers prioritize synthetic options for cost efficiency.
- Peripheral Artery Disease:Femoral endarterectomy applications in underpenetrated Japanese patient populations present white-space expansion for biological patch deployment.
- Trauma Repair:Emergency vascular reconstruction favors synthetic availability due to inventory standardization requirements in German trauma networks.
- Aneurysm Treatment:Complex aortic reconstruction procedures demand high-strength anastomosis performance that concentrates demand among specialized cardiac centers.
Cardiovascular surgery anchors revenue today; dialysis access demonstrates the steepest expansion trajectory.
End User:
Facility scale and case-mix sophistication determine whether patches enter through integrated supply contracts or standalone procurement channels.
- Cardiac Centers:High-volume cardiovascular service lines in the United States negotiate bundled agreements covering patches, sutures, and sealants through single-source distributors.
- Specialty Clinics:Peripheral vascular practices in Germany concentrate demand for biological patches in femoral endarterectomy cases.
- Ambulatory Surgery Centers:Dialysis access procedures in United States outpatient settings prioritize synthetic patches for standardized reimbursement pathways.
- Chronic Care Facilities:Long-term hemodialysis centers in Japan maintain consignment inventory models that transfer carrying cost risk to suppliers.
Cardiac centers dominate procurement value today; ambulatory surgery centers are expanding volume fastest.
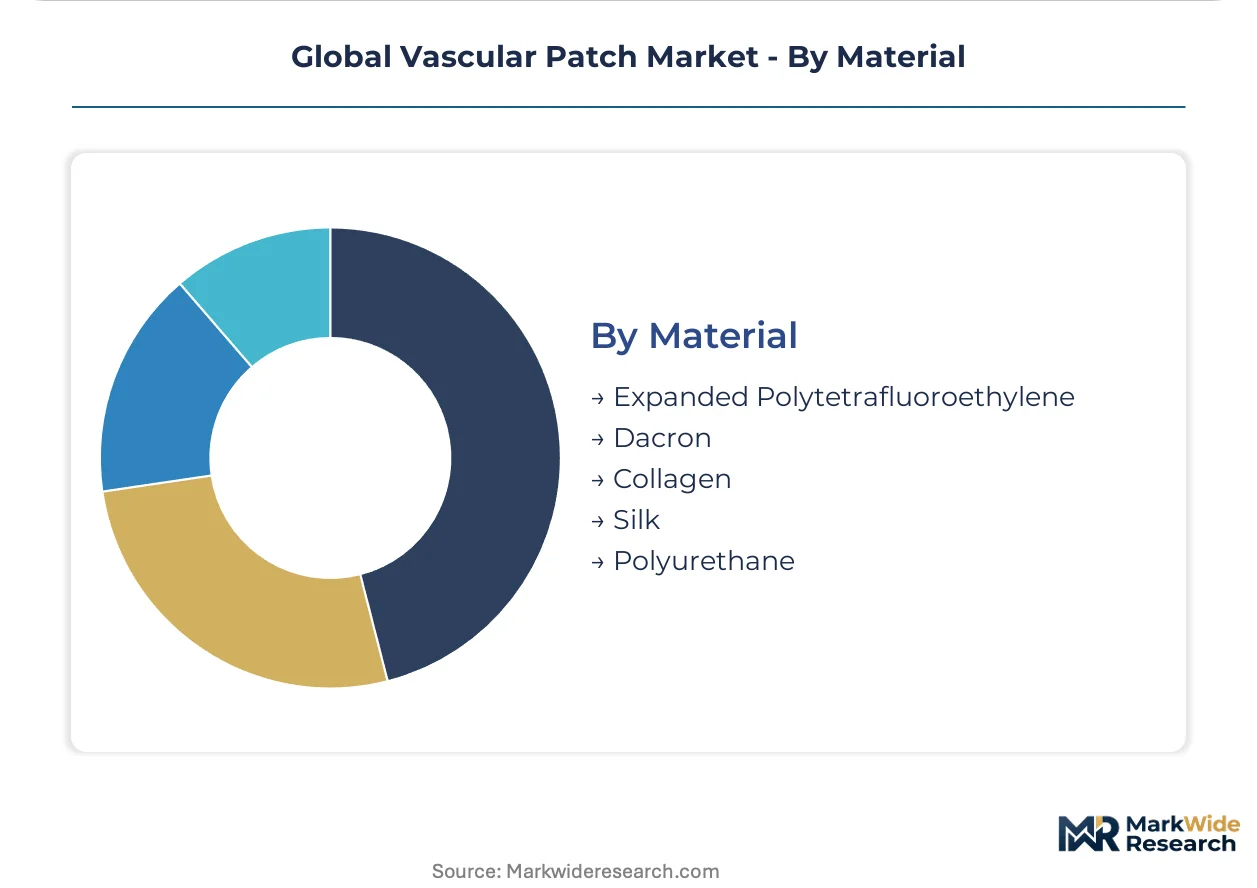
Material:
Supply chain concentration and manufacturing sophistication separate commodity synthetics from specialty biological substrates.
- Expanded Polytetrafluoroethylene:ePTFE formulations from United States and German specialty chemical manufacturers dominate high-strength applications. Input cost volatility constrains margin predictability for patch producers.
- Dacron:Polyester-based patches serve standardized cardiovascular procedures with established predicate histories under FDA 510(k) pathways.
- Collagen:Biological substrates support cell infiltration during arterial wall remodeling in research-stage applications.
- Silk:Natural protein fibers enable ultra-thin configurations below 0.3 millimeters for small-caliber vessel reconstruction.
- Polyurethane:Elastomeric properties match highly compliant arterial wall applications where thickness matching proves technically challenging for conventional synthetics.
Expanded polytetrafluoroethylene leads implant volumes today; polyurethane is climbing the fastest in compliance-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vascular patch manufacturing traces its commercial roots to expanded polytetrafluoroethylene innovations developed in the United States during the 1970s, with subsequent biological patch processing expertise concentrating in German and Swiss medical device clusters.
United States
Academic medical centers in Boston and Cleveland drive demand for biological configurations in complex aortic reconstructions. FDA 510(k) pathway documentation requirements intensify compliance burdens for mid-tier manufacturers seeking product line extensions. The Minneapolis-St. Paul corridor anchors integrated hospital supply contract negotiations that bundle patches with sutures and sealants.
Germany
Cardiac centers in Munich and Heidelberg expand procurement of bovine pericardium variants for infected-field applications where bacterial colonization resistance determines clinical selection. EMA Medical Device Regulation technical documentation deadlines accelerate portfolio rationalization among manufacturers with legacy biological substrates. The Baden-Württemberg medical technology cluster concentrates cold-chain logistics expertise for biological patch distribution.
Japan
Tokyo and Osaka hospital systems prioritize dialysis access patch angioplasty as end-stage renal disease populations expand across aging demographics. PMDA extended biocompatibility testing protocols delay market entry for foreign manufacturers navigating approval timelines. The Kobe medical device manufacturing zone develops consignment inventory models that transfer carrying cost risk to suppliers.
China
Shanghai and Beijing cardiac centers absorb synthetic patch volumes as open-heart procedure volumes recover in tier-one hospital systems. NMPA alignment with ISO 7198 dimensional and mechanical benchmarks streamlines technical review standards for multinational suppliers seeking market access. The Suzhou industrial park attracts vascular prosthesis manufacturing investments from established Western players.
Switzerland
Geneva and Zurich specialty clinics concentrate demand for ultra-thin patch configurations below 0.4 millimeters in peripheral artery disease interventions. Swissmedic post-market surveillance infrastructure supports competitive positioning for manufacturers with established biological product predicate histories. The Basel pharmaceutical-medical device corridor facilitates research consortia advancing bioresorbable scaffold technologies.
Global Vascular Patch Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material sophistication and regulatory validation depth, with biological patch specialists commanding pricing power in infected-field applications while synthetic patch fabricators compete on throughput and standardization. The vendor base organizes into three archetypes: diversified medical device conglomerates with integrated hospital supply contracts, focused vascular specialists with concentrated R&D intensity, and mid-tier regional manufacturers serving price-sensitive procurement committees. Consolidation accelerates as compliance costs under FDA and EMA frameworks exceed absorption capacity for sub-scale participants. Dominant competitive moves include strategic partnerships to secure biological substrate supply chains and geographic licensing arrangements to navigate Japan's extended approval timelines.
Within the diversified conglomerate tier, Baxter International and Medtronic occupy positions anchored by comprehensive cardiovascular implant portfolios and established single-source distribution agreements with North American cardiac centers. Among focused vascular specialists, LeMaitre Vascular exemplifies the biological sourcing and customization archetype, while W. L. Gore & Associates represents the high-strength synthetic formulation segment. These three companies collectively illustrate the competitive spectrum from integrated supply chain scale to specialized material science depth.
| Leading Market Players |
|---|
| Baxter International |
| LeMaitre Vascular |
| W. L. Gore & Associates |
| B. Braun Melsungen AG |
| Edwards Lifesciences Corporation |
| Getinge AB |
| Terumo Corporation |
| Medtronic |
| BD |
| Others |
Supply & Pricing Matrix
Hospital procurement committee consolidation around bundled operating-room solutions in the United States is forcing patch manufacturers to absorb suture and sealant costs into kit pricing, compressing standalone implant margins while elevating working capital requirements for inventory-heavy configurations.
Pricing Analysis
Three-tier pricing structure across premium biological, standard synthetic, and economy Dacron configurations governs vascular patch transactions. Premium-mid-economy pricing differentiation rests on ISO 7198 compliance certification and cold-chain handling capability. Cost compression in the synthetic tier is intensifying because ePTFE feedstock volatility from United States and German specialty chemical manufacturers feeds through to contract renegotiations. Ambulatory surgery centers in dialysis access applications exhibit the sharpest price sensitivity, while academic medical centers in complex aortic reconstructions show minimal elasticity for bovine pericardium variants.
Supply Chain Analysis
Regional distribution centers in Minneapolis-St. Paul, Munich, and Tokyo anchor hub-and-spoke patterns for patch deployment. Manufacturing concentrates in the United States for ePTFE formulations, Germany for biological processing, and Japan for dialysis access configurations. Raw material dependencies draw from bovine pericardium sourcing in New Zealand and Australia, specialty fluoropolymer resins in the United States, and polyester fiber in Germany. Single-source vulnerability in expanded polytetrafluoroethylene precursor supply creates structural risk for synthetic patch producers. Distribution runs through integrated hospital supply contracts in North America and consignment inventory models in Japanese chronic care facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's extended PMDA approval timelines versus China's accelerating NMPA alignment with ISO 7198 creates a geographic-arbitrage window for manufacturers with established predicate device histories to shift technical documentation resources toward faster market access.
For Market Incumbents: Lock in biological substrate supply chains through long-term sourcing agreements with New Zealand and Australian processors before competitor consolidation accelerates. Prioritize MDR technical documentation completion for legacy bovine pericardium portfolios to defend market position against emerging bioresorbable scaffold entrants. Capacity addition in the Baden-Württemberg cluster secures cold-chain logistics advantage for infected-field applications. For New Entrants and Emerging Players: Launch via consignment inventory partnerships with Japanese chronic care facilities to bypass upfront procurement committee barriers. Peripheral artery disease interventions in underpenetrated Japanese femoral endarterectomy cases present the most penetrable white-space target. Dialysis access patch angioplasty in United States ambulatory surgery centers offers volume scale through standardized synthetic procurement pathways. For Investors and Strategic Acquirers: Asymmetric upside sits with focused vascular specialists possessing concentrated R&D intensity in biological patch customization and established predicate histories under FDA 510(k) pathways. Long-term viability hinges on portfolio breadth spanning synthetic throughput and biological premium positioning. Watch for EMA MDR technical documentation completion rates as inflection indicator for competitive consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Streamlined premarket submission reduces time-to-market for product line extensions in cardiovascular surgery suites. |
| Biological Substrate Backward Integration | Captive supply of bovine pericardium from New Zealand processors secures margin control in infected-field applications. |
| Hospital System Partnership | Single-source agreements with United States cardiac centers displace fragmented patch procurement through bundled kit configurations. |
| CE Marking Pathway Acceleration | MDR technical documentation completion defends European market position for legacy biological patch portfolios. |
| Reimbursement Strategy Development | Biological versus synthetic coding differentiation anticipates portfolio margin shifts across national health systems. |
Research Methodology
Bottom-up cardiovascular procedure modeling reconciled against top-down vascular prosthesis manufacturing tracking forms the analytical core of this study. Primary interviews with cardiac surgeons, hospital purchasing committees, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and ISO 7198 compliance registries. Triangulation across bottom-up demand estimation and top-down supply verification ensures dimensional consistency.
Historical trendline analysis of open-heart procedure volumes, dialysis access interventions, and peripheral artery disease treatments anchors the projection framework. Segmentation dimensions span material type, application context, end-user facility scale, and regional regulatory cluster. CAGRs derive from procedure volume elasticity modeling, reimbursement trajectory assessment, and material substitution dynamics. Forecast inputs incorporate hemodialysis population demographics, EMA MDR implementation pacing, and NMPA technical review standardization.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden biocompatibility testing protocol changes or biological substrate supply disruptions. Outputs reflect documented assumptions regarding procedure volume recovery, regulatory alignment timelines, and procurement consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Global Pediatric Interventional Cardiology Market
Cardiovascular Devices
Cardiac Ablation Market
Cardiovascular Devices
Endovascular Stent Market
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Congestive Heart Failure Treatment Devices Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Global Vascular Graft Market
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market