
 China General Surgical Devices Market | 2026-2036
China General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China General Surgical Devices Market Outlook
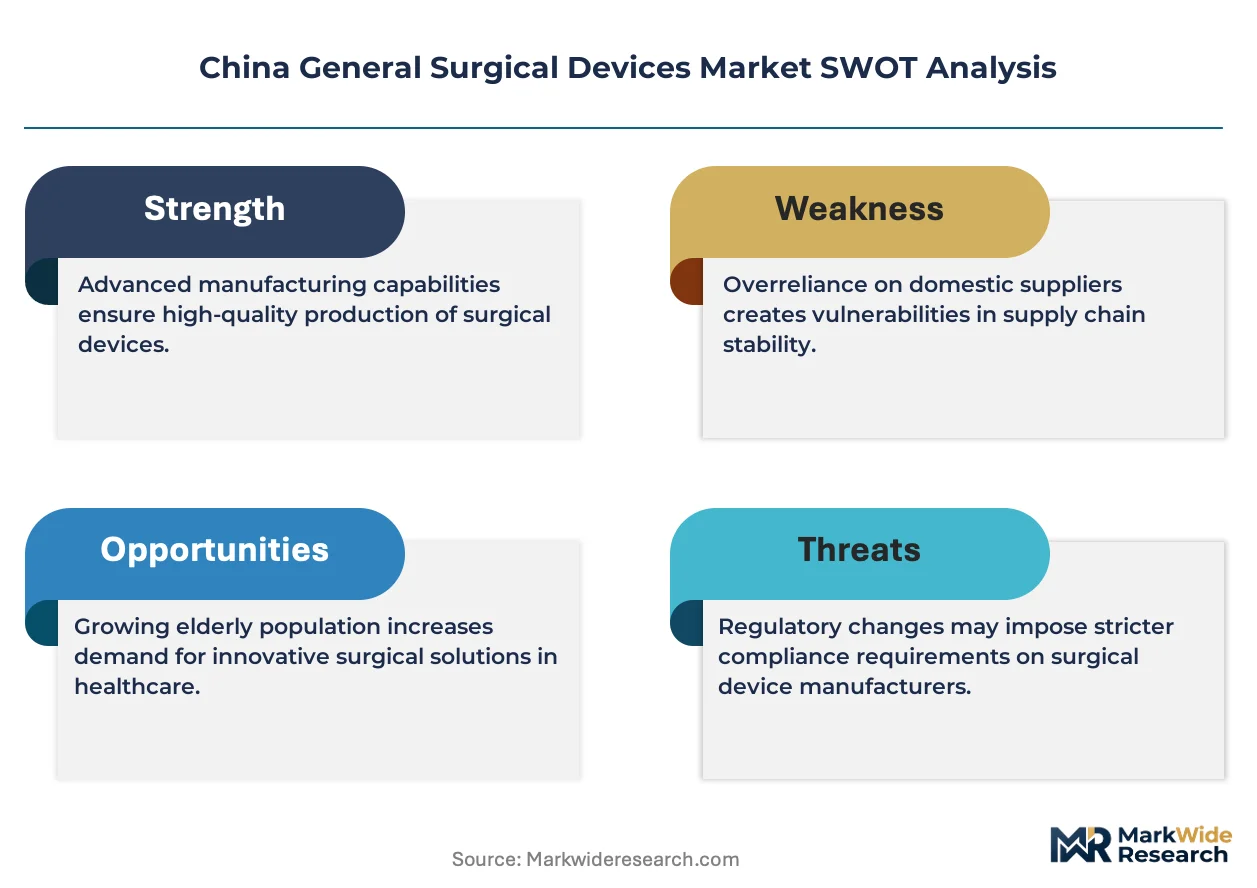
Multi-source procurement among tier-three hospitals is rebalancing supplier relationships across the China general surgical devices sector. Johnson & Johnson leverages its broad electrosurgery portfolio to sustain presence in high-volume provinces. Medtronic anchors its position through deep distribution networks in central China. Olympus Corporation specializes in minimally invasive visualization systems that command premium placement in top-tier facilities.
General surgical devices encompass handheld and powered instruments used for cutting, grasping, dissecting, and coagulating tissue during operative procedures, typically manufactured from medical-grade stainless steel or titanium alloys with tolerances measured in micrometers. These instruments serve the fundamental purpose of enabling precise mechanical and energy-based intervention across open, laparoscopic, and robot-assisted surgical workflows. Scalpels and forceps within the product type category represent mature revenue pools with stable replacement cycles, while robotic technology commands the fastest expansion trajectory as hospital capital budgets shift toward integrated surgical platforms. Stainless steel dominates material demand by volume, though titanium instruments gain share in orthopedic-adjacent general surgery where reduced instrument weight improves ergonomics during prolonged cases.
NMPA's medical device registration requirements and China's GB standards for surgical instrument biocompatibility shape product entry pathways and local manufacturing obligations for multinational suppliers. The country's dual carbon goals from MEE are pressuring sterilization and reprocessing workflows, indirectly influencing device material selection and disposable-versus-reusable tradeoffs. Stakeholders must monitor how provincial centralized procurement reforms redistribute volume among domestic and foreign manufacturers without eroding service-level requirements.
Market Dynamics
Centralized procurement reforms in Jiangsu and Zhejiang provinces are compressing supplier margins while reallocating volume toward domestic manufacturers with NMPA registration advantages.
Growth Catalysts
- Robotic platform adoption:Tertiary hospitals in Beijing and Shanghai are expanding capital budgets for integrated surgical systems. These institutions prioritize technology that reduces operative variability and shortens recovery timelines.
- NMPA classification streamlining:Updated medical device rules are accelerating local registration timelines for imported instruments. Foreign suppliers now secure market access faster than under previous review protocols.
- East China surgical volume:Jiangsu and Zhejiang provinces report operative procedure growth outpacing national benchmarks. Hospital infrastructure expansion in these coastal regions drives replacement cycles for handheld and powered instruments.
Market Restraints
- Titanium alloy input costs:Medical-grade titanium pricing volatility constrains margin expansion for precision instrument manufacturers. Suppliers face pressure to absorb fluctuations or risk losing centralized procurement contracts.
- Domestic supplier concentration:Provincial procurement pools increasingly favor locally registered manufacturers with established service networks. Foreign incumbents must maintain dual registration and manufacturing footprints to retain access.
- Energy-based device technical limitations:Electrosurgical systems face compatibility constraints with emerging robotic platforms. Integration gaps delay full workflow automation in hybrid operating theaters.
Strategic Opportunities
- Central China penetration:Henan and Hubei provinces present underdeveloped surgical device markets relative to coastal benchmarks. Hospital upgrade programs in these interior regions create first-mover positioning for distributors with logistics scale.
- Disposable instrument conversion:MEE dual carbon goals are pressuring sterilization workflows toward single-use alternatives. Manufacturers with biodegradable polymer capabilities capture regulatory tailwinds from sustainability mandates.
- Visualization-robotics convergence:Minimally invasive imaging systems are integrating with autonomous surgical platforms. Suppliers controlling both modalities can bundle offerings that command premium placement in tier-three facilities.
Industry Challenges
- Robotic surgery technician scarcity:Qualified operators for da Vinci and domestic alternatives remain concentrated in Beijing, Shanghai, and Guangzhou. Training pipeline gaps limit system utilization rates in secondary cities.
- GB biocompatibility certification timelines:Surgical instrument manufacturers face extended validation periods for new material compositions. Delays between prototype completion and commercial launch compress effective product lifecycles.
- Legacy instrument integration complexity:Hospital capital planning cycles struggle to synchronize robotic platform adoption with existing laparoscopic infrastructure. Procurement committees delay decisions amid interoperability uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China General Surgical Devices Market |
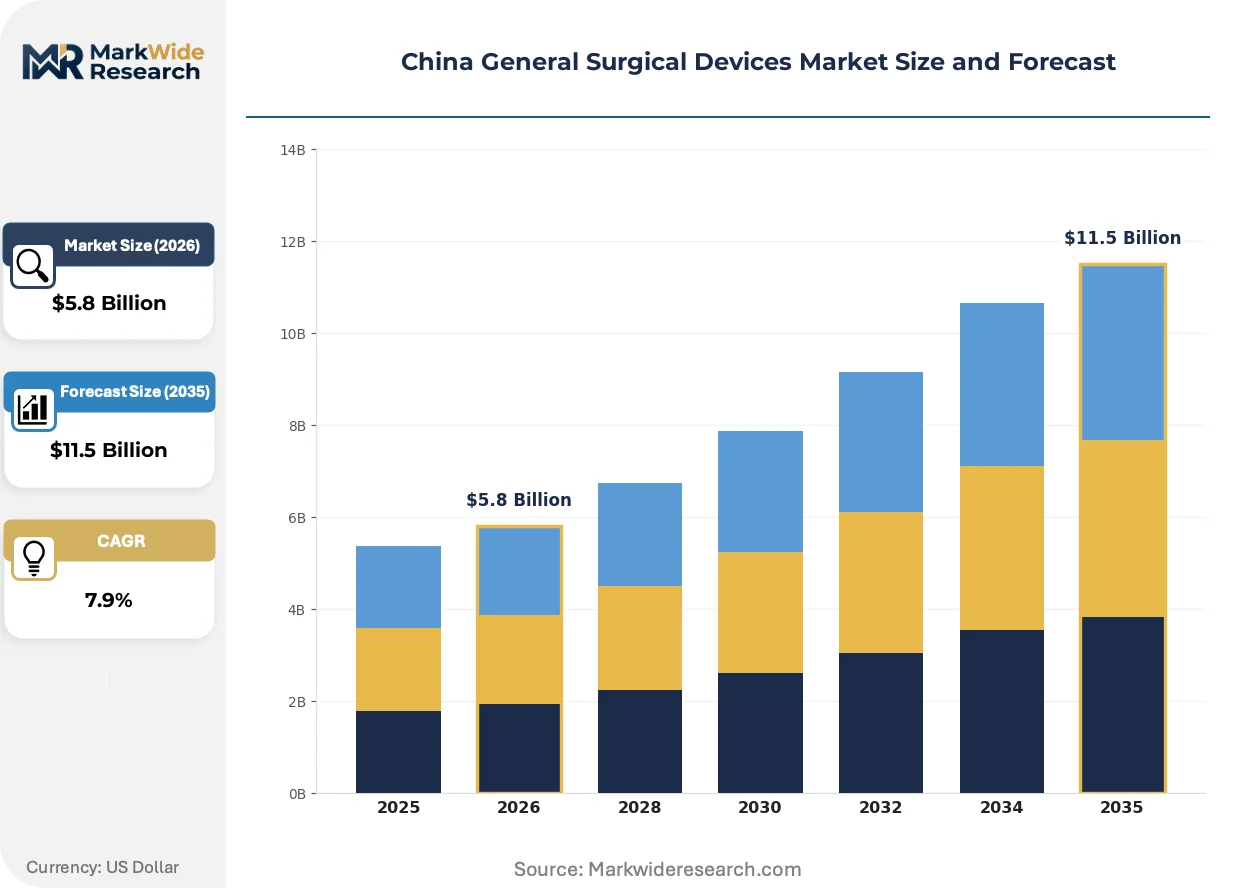
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalpels, Forceps, Scissors, Hemostats End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Material: Stainless Steel, Plastic, Titanium, Aluminum Technology: Conventional, Electrosurgery, Laser-Assisted, Robotic |
| Companies Covered | B. Braun Melsungen AG, Boston Scientific Corporation, Johnson & Johnson, Olympus Corporation, Stryker Corporation, Medtronic plc, ConMed Corporation, Intuitive Surgical, MEDITECH TECHNOLOGY CO., LTD., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China General Surgical Devices Market Strategic Shifts
Digital surgical workflows and intelligent instrument tracking are compressing equipment utilization cycles while elevating data-driven purchasing criteria among hospital procurement committees.
Smart instrument tracking systems embedded with RFID and pressure sensors are decentralizing surgical asset management from central sterile supply departments to point-of-use locations. Tertiary hospitals in Shanghai and Beijing deploy these technologies to reduce instrument loss and optimize reprocessing throughput. Real-time location data is decentralizing inventory control decisions to operating room nurses and surgeons.
NMPA's updated medical device classification rules are compressing registration timelines for Class II surgical instruments while elevating clinical evidence requirements for novel energy-based devices. Domestic manufacturers with established quality management systems capture accelerated review pathways. Imported electrosurgical generators face extended substantiation periods that delay market entry against local competitors.
Hospital procurement committees are consolidating vendor relationships through multi-year framework agreements that bundle instruments, maintenance, and training. Tier-three facilities in Jiangsu province negotiate these consolidated contracts to reduce administrative overhead and secure volume discounts. Supplier selection now weights service response time and spare parts availability above standalone product pricing.
China General Surgical Devices Market Segmentation
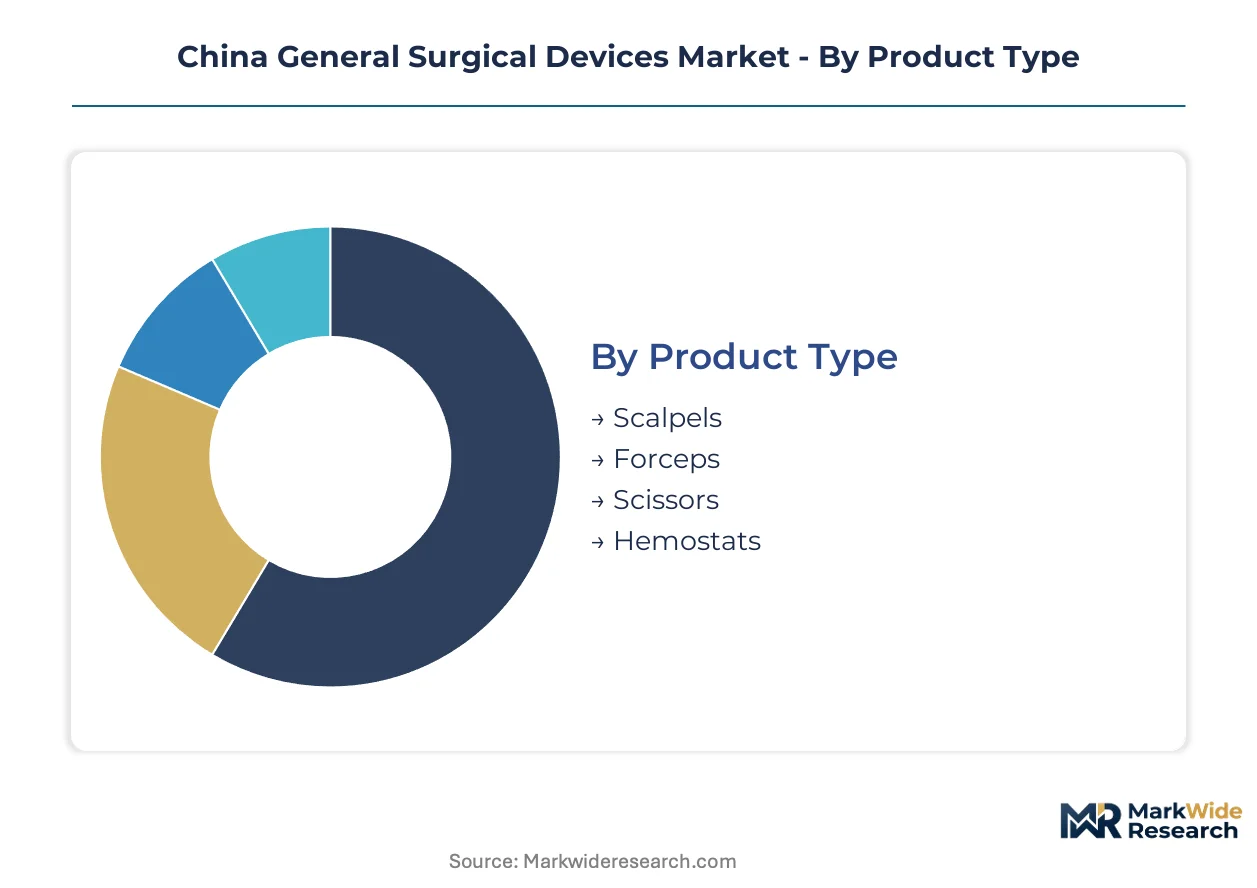
Surgical device procurement in China follows distinct technical and institutional logics that reshape supplier priorities across product categories. Understanding where replacement cycles accelerate versus where capital budgets concentrate enables precise market positioning.
Product Type:
Upgrade cycles vary sharply across handheld instrument categories, with tertiary hospitals in Beijing and Shanghai driving differential replacement demand.
- Scalpels:Manufactured from medical-grade stainless steel with carbon or ceramic blade compositions, these instruments serve as the foundational cutting tool across all surgical workflows. Demand concentrates in high-volume general surgery departments at tertiary hospitals in Jiangsu province, where procedure density accelerates blade replacement schedules and drives procurement committee attention toward bulk supply agreements.
- Forceps:These grasping instruments feature tungsten carbide inserts or all-stainless construction with tip geometries optimized for tissue handling without crush injury. Procurement volumes cluster in Zhejiang province surgical centers, where minimally invasive procedure expansion creates demand for both standard and laparoscopic forceps configurations with specialized tip designs.
- Scissors:Cutting instruments with supercut or standard edge profiles designed for precise tissue dissection and suture cutting.
- Hemostats:Clamping devices with ratchet-lock mechanisms for temporary vessel occlusion and bleeding control during operative procedures.
Volume placements concentrate in scalpels; the faster expansion belongs to forceps.
End User:
Institutional purchasing power and capital budget scale determine technology adoption thresholds across the customer base.
- Hospitals:Tertiary medical centers with Class III accreditation command the largest procurement budgets and negotiate multi-year framework agreements. Robotic platform adoption concentrates in Beijing and Shanghai facilities, where surgical volume justifies capital expenditure on integrated systems.
- Ambulatory Surgical Centers:These facilities prioritize disposable instrument portfolios and compact electrosurgical units compatible with same-day discharge protocols. Demand growth outpaces hospital benchmarks in East China coastal cities.
- Clinics:Primary care and specialty clinics procure basic handheld instrument sets for minor procedures.
- Research Institutions:Academic medical centers and biomedical research facilities source precision instruments for experimental surgery and device validation studies.
Procurement volume clusters at hospitals; ambulatory surgical centers are climbing the fastest.
Material:
Material selection tradeoffs between durability, weight, and sterilization compatibility shape manufacturing cost structures and end-user preferences.
- Stainless Steel:Medical-grade 300-series and 400-series alloys dominate instrument production due to corrosion resistance and autoclave compatibility. Jiangsu and Zhejiang hospitals specify this material for standard reusable instrument sets.
- Titanium:Lightweight alloy instruments reduce surgeon fatigue during prolonged procedures. Adoption concentrates in orthopedic-adjacent general surgery departments.
- Plastic:Polymer-based instruments serve single-use applications and sterile field maintenance.
- Aluminum:Lightweight metal components appear in instrument handles and non-cutting structural elements.
Stainless steel captures the largest procurement volumes; titanium is gaining share fastest.
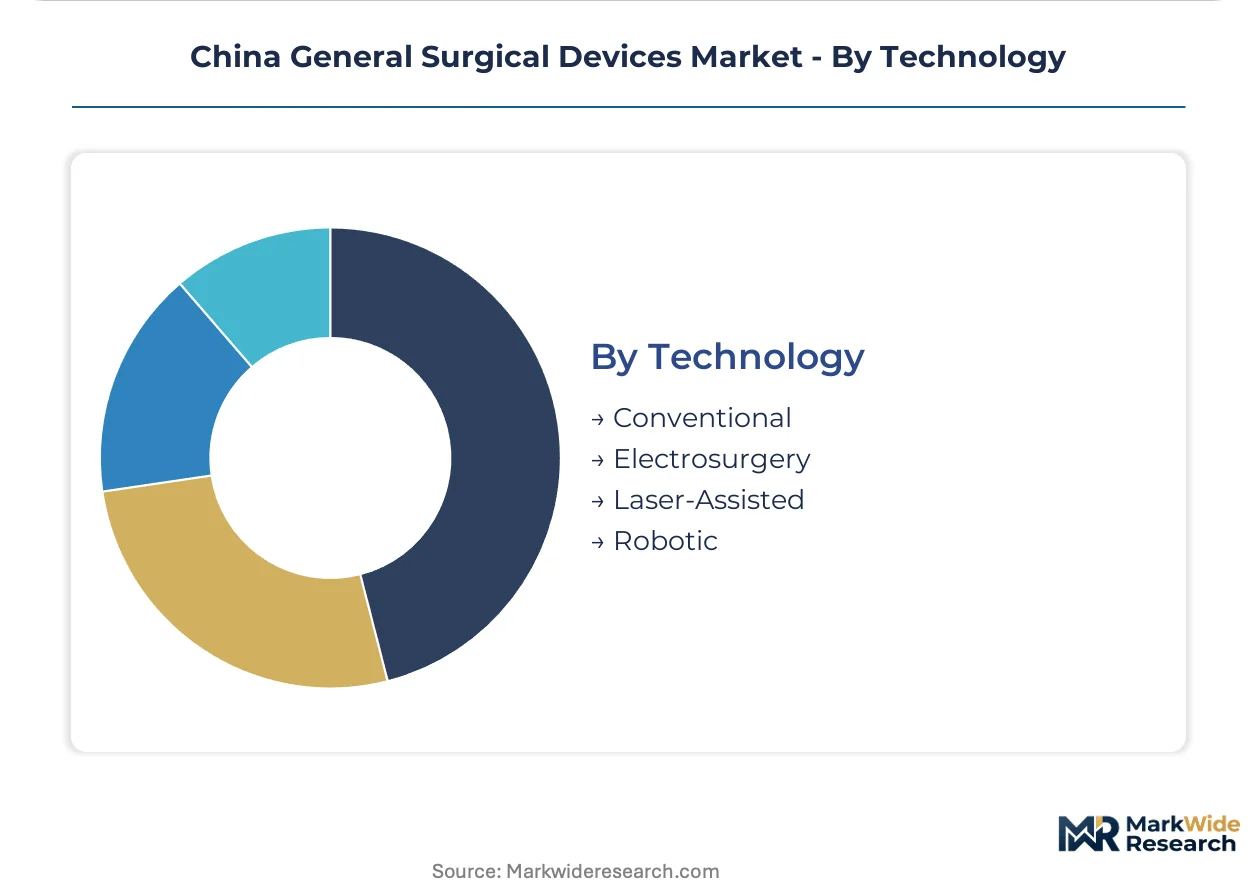
Technology:
Technology tier determines capital intensity, service requirements, and integration complexity within hospital infrastructure.
- Conventional:Mechanical instruments without energy delivery represent mature revenue pools with predictable replacement cycles. Procurement committees in Henan and Hubei provinces favor these systems for cost containment.
- Robotic:Computer-assisted surgical platforms with articulated instrument arms and haptic feedback systems. NMPA registration acceleration enables faster market entry for imported and domestic systems alike.
- Electrosurgery:Radiofrequency energy devices for cutting and coagulation.
- Laser-Assisted:Precision energy delivery systems for specialized tissue interaction.
Conventional technology maintains the largest installed base; robotic systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade titanium and stainless steel processing clusters in Jiangsu and Zhejiang provinces anchor surgical device manufacturing capacity across East China. Provincial procurement reforms and tertiary hospital expansion programs redistribute demand toward coastal production zones.
Beijing-Tianjin-Hebei
Tertiary hospitals in Beijing command the largest capital budgets for robotic-assisted surgical platforms. NMPA's streamlined Class II device registration accelerates market entry for imported instruments. The Beijing municipal health commission directs procurement toward integrated surgical systems in top-tier facilities.
Yangtze River Delta
Jiangsu and Zhejiang provinces report surgical volume growth exceeding national benchmarks. Provincial centralized procurement pools favor domestically registered manufacturers with established service networks. Suzhou and Hangzhou medical device industrial parks concentrate precision instrument production for regional hospital supply chains.
Pearl River Delta
Guangdong province's hospital infrastructure expansion drives replacement cycles for handheld and powered instruments. SAMR quality supervision aligns manufacturing standards with GB biocompatibility requirements. Shenzhen and Guangzhou surgical centers prioritize disposable instrument portfolios compatible with high-volume workflows.
Sichuan-Chongqing
Western China's underdeveloped surgical device markets present first-mover positioning for distributors with logistics scale. MEE dual carbon goals pressure sterilization workflows toward single-use alternatives. Chengdu's medical device clusters expand production of polymer-based instruments for regional hospital procurement.
China General Surgical Devices Market Competitive Environment
Strategic partnerships dominate the current landscape as foreign incumbents align with domestic distributors to navigate provincial procurement reforms. The vendor base stratifies across three tiers: multinational conglomerates with broad electrosurgery portfolios, regional specialists in minimally invasive visualization, and domestic manufacturers leveraging NMPA registration advantages. Two archetypes anchor competitive positioning: technology-integrated platform suppliers and cost-optimized volume producers. M&A activity and localized manufacturing partnerships represent the dominant competitive moves as companies defend access to centralized procurement pools.
Among multinational incumbents, Johnson & Johnson and Medtronic occupy positions as archetypal platform suppliers with deep distribution footprints. Boston Scientific Corporation exemplifies the specialized instrumentation tier. MEDITECH TECHNOLOGY CO., LTD. represents domestic manufacturers capitalizing on accelerated NMPA review pathways. These three anchors illustrate how competitive positioning splits between foreign technology integration and local regulatory compliance advantages.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Olympus Corporation |
| Stryker Corporation |
| Medtronic plc |
| ConMed Corporation |
| Intuitive Surgical |
| MEDITECH TECHNOLOGY CO., LTD. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between NMPA-registered domestic instruments and imported Class III devices manifests in both procurement premiums and supply chain qualification requirements. Tertiary hospitals in Beijing and Shanghai absorb 40-60% price differentials for robotic platforms with bundled service contracts, while provincial procurement pools in Jiangsu and Zhejiang compress margins on conventional handheld instruments through volume aggregation.
Pricing Analysis
Warranty and service-bundling unbundling distinguishes foreign incumbents from domestic competitors in hospital framework negotiations. Tier-three facilities negotiate three-tier pricing structures across premium robotic systems, standard electrosurgery units, and economy-grade reusable instrument sets. Price differentiation rests on NMPA registration tier and spare parts availability guarantees. Cost compression in conventional instrument lines intensifies because centralized procurement pools favor locally registered manufacturers. Ambulatory surgical centers exhibit highest price sensitivity; tertiary academic medical centers prioritize technology integration over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from hospital procurement committees require qualification of at least two suppliers for critical instrument categories. Manufacturing concentration centers on Jiangsu and Zhejiang provinces for stainless steel processing, with titanium alloy inputs drawing from domestic smelters and Japanese specialty metal suppliers. Raw material dependencies include medical-grade 316L stainless steel, Ti-6Al-4V titanium alloy, and biodegradable polymers for disposable conversion. Single-source vulnerability persists in robotic console electronics and precision sensor components. Distribution runs through provincial GPOs and tiered distributor networks with hospital direct contracts for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified robotic surgery technician scarcity props pricing power for training-capable suppliers, constraining system utilization expansion in secondary cities and preserving premium capture for incumbents with education infrastructure.
For Market Incumbents: Deepen backward integration into titanium alloy processing to offset medical-grade input cost volatility threatening centralized procurement contract margins. Fortify service network density in Henan and Hubei provinces before domestic competitors establish NMPA-registered local manufacturing. Prioritize visualization-robotics bundling to defend placement against emerging domestic platform suppliers leveraging accelerated registration pathways.
For New Entrants and Emerging Players: County-level hospitals in Sichuan and Chongqing present underserved buyer archetypes with upgrade program funding and limited foreign supplier penetration. Disposable instrument conversion tailwinds from MEE dual carbon goals create white-space positioning for biodegradable polymer specialists. Prioritize GPO partnership over direct sales force buildout to achieve procurement committee access without incumbent-scale infrastructure investment.
For Investors and Strategic Acquirers: Re-rating potential sits with domestic manufacturers possessing NMPA Class III registration and established service networks given provincial procurement preference acceleration. Five-to-ten year viability favors suppliers controlling both robotic platform technology and complementary visualization systems. Monitor NMPA registration queue depth for imported energy-based devices as inflection indicator for domestic competitive positioning strength.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Registration Acceleration | Domestic manufacturers with established QMS capture faster review pathways against imported competitors. |
| Visualization-Robotics Bundling | Suppliers controlling imaging and platform modalities command premium placement in tier-three Beijing and Shanghai facilities. |
| Central China Distribution Scale-Up | Logistics footprint in Henan and Hubei creates first-mover positioning in underdeveloped surgical device markets. |
| Biodegradable Polymer Capability Investment | Disposable instrument conversion aligns with MEE dual carbon sterilization workflow pressures. |
| Robotic Surgery Technician Training Pipeline | Education infrastructure scarcity limits competitor system utilization and preserves incumbent pricing power. |
Study Parameters
Independent corroboration across hospital procurement committee interviews, biomedical engineer surveys, and GPO contract database analysis underwrites the qualitative findings in this study. Primary fieldwork engaged hospital purchasing directors, surgical department heads, NMPA regulatory consultants, and domestic manufacturer executives across Beijing, Shanghai, Jiangsu, and Zhejiang. Secondary validation incorporated NMPA registration filings, provincial centralized procurement announcements, SAMR quality supervision reports, and hospital capital expenditure disclosures. Bottom-up instrument demand modeling and top-down healthcare infrastructure spending analysis provided cross-verification.
Rate-of-change decomposition across product type, technology tier, end-user institution class, and material composition anchors the analytical framework. Segmentation dimensions modeled include conventional versus robotic versus electrosurgery technology, tertiary hospital versus ambulatory surgical center versus clinic end-use, and stainless steel versus titanium versus polymer material. CAGRs derive from surgical volume growth trajectories, replacement cycle compression, and capital budget allocation shifts. Forecast inputs incorporate NMPA registration timeline acceleration effects and provincial procurement reform implementation pacing.
Revisions become necessary when NMPA regulatory pathway delays materialize, provincial procurement pool compositions shift toward domestic supplier concentration beyond modeled thresholds, or robotic surgery technician training pipeline expansion accelerates system utilization rates. Deviation in titanium alloy input cost volatility or centralized procurement contract margin compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Japan Drug Delivery Devices Market
Medical Devices
Ingestible Smart Pills Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market
Medical Devices
USA Artificial Organs and Bionic Implants Market
Medical Devices
Manual Resuscitators Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
Hand and Wrist Devices Market
Medical Devices
Italy Contraceptive Devices Market
Medical Devices
Muscle Stimulator Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Global Nasal Cannula Market
Medical Devices
Medical Tricorder Market
Medical Devices
Global Dermatoscope Market
Medical Devices
Europe Wearable Medical Devices Market
Medical Devices
GCC Biopsy Devices Market