
 Global Anastomosis Devices Market | 2026-2036
Global Anastomosis Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anastomosis Devices Market Foresight
Hospital procurement consortia is reconfiguring how anastomosis devices reach operating rooms across integrated delivery networks. Medtronic leverages its broad surgical portfolio to secure multi-year supply agreements with large health systems. Johnson & Johnson sustains competitive pressure through Ethicon's specialized focus on advanced energy and stapling platforms. B. Braun Melsungen anchors its position in Europe through direct hospital service models and localized manufacturing.
An anastomosis device creates a surgical connection between two hollow structures or vessels, typically employing stainless steel or titanium staples, absorbable polymers, or mechanical compression elements designed to maintain patency while tissue heals. Surgical staplers dominate current procedure volumes due to their speed and consistency in gastrointestinal and thoracic applications. Robotic-assisted technology represents the fastest-expanding segment as da Vinci system installations multiply in academic medical centers. Manual instruments retain significant share in cost-constrained settings where capital equipment acquisition faces budgetary resistance.
The FDA enforces rigorous premarket review for surgical staplers under 510(k) and de novo pathways, with heightened scrutiny following adverse event reporting mandates that influence manufacturer design priorities. Europe's MDR and REACH frameworks impose biocompatibility and chemical safety requirements that extend validation timelines for polymer-based anastomotic rings. Japan's PMDA maintains distinct clinical evidence standards for powered stapling devices that shape regional product registration strategies. Stakeholders must weigh regulatory capital requirements against the pull from robotic surgery adoption when allocating R&D resources across manual, semi-automatic, and fully automated platform development.
Market Dynamics
Powered stapling platforms are compressing procedure times in gastrointestinal surgery while FDA premarket notification pathways force manufacturers to revalidate device safety profiles. This dual pressure from clinical adoption and regulatory scrutiny defines current competitive positioning.
Growth Catalysts
- Minimally invasive surgery expansion:Academic medical centers in the United States, Germany, and Japan are scaling laparoscopic and robotic programs, creating sustained demand for precision anastomotic tools.
- MDR compliance timelines:Europe's Medical Device Regulation mandates enhanced biocompatibility documentation for polymer-based rings, accelerating replacement cycles for legacy devices.
- Powered stapling technology:Battery-driven firing mechanisms reduce tissue trauma variability, driving upgrade demand from manual instrument bases in thoracic departments.
Market Restraints
- Titanium supply concentration:Surgical staple raw material sourcing clusters in select Asian refining operations, exposing manufacturers to input volatility.
- PMDA evidence requirements:Japan's pharmaceutical regulator demands distinct clinical trial designs for powered devices, extending registration timelines versus 510(k) pathways.
- Manual instrument persistence:Cost-constrained hospitals in emerging markets retain reusable mechanical staplers, limiting premium device penetration.
Strategic Opportunities
- Robotic platform convergence:Integration of anastomotic staplers with da Vinci and competing surgical robots creates procedure-specific attachment markets.
- India's surgical infrastructure buildout:Government hospital procurement programs under Ayushman Bharat generate volume demand for mid-tier disposable devices.
- REACH polymer innovation:EU chemical safety frameworks incentivize development of absorbable anastomotic rings with enhanced degradation profiles.
Industry Challenges
- Robotic surgery technician scarcity:Academic medical centers face recruitment gaps for certified da Vinci system operators, limiting installed base utilization.
- 510(k) submission complexity:FDA's heightened adverse event reporting requirements for surgical staplers extend premarket review cycles and documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anastomosis Devices Market |
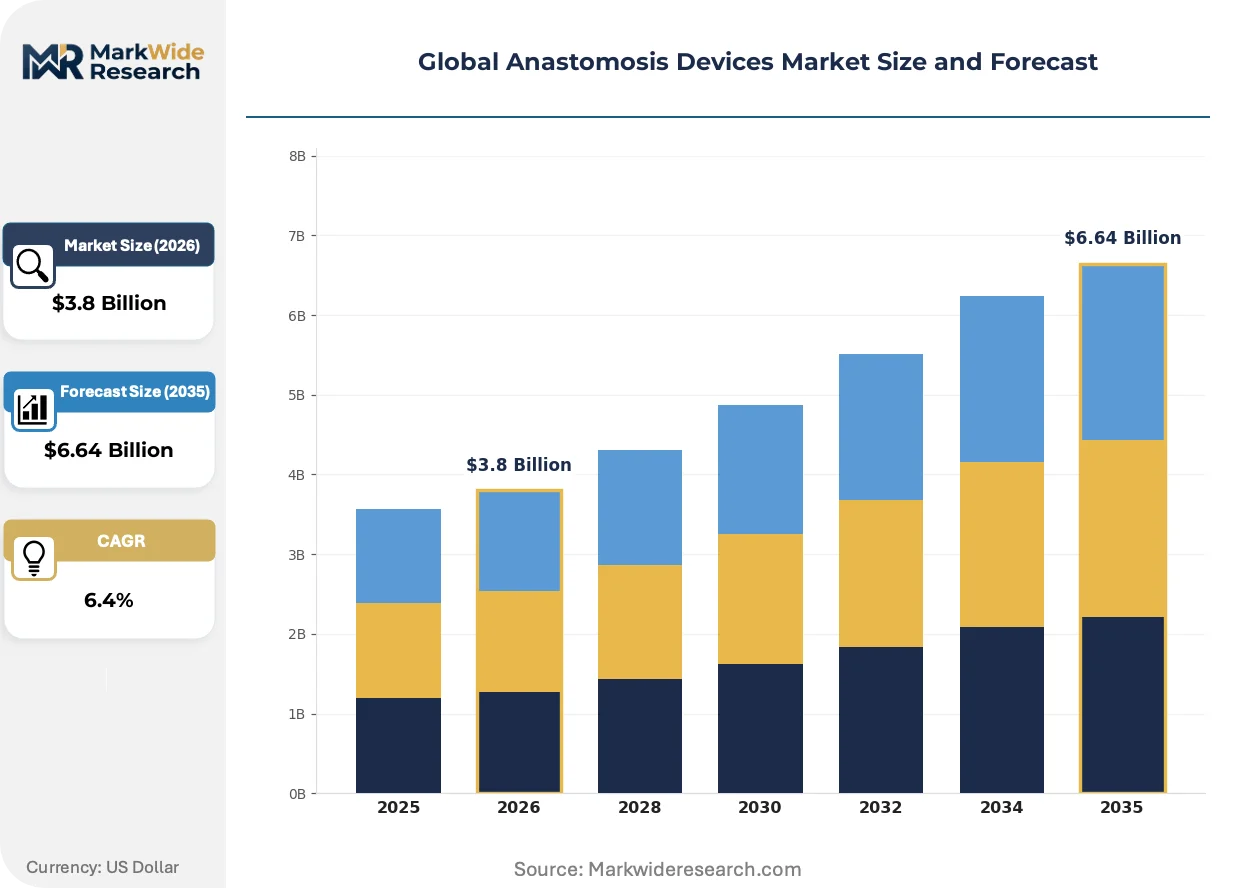
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Surgical Staplers, Vascular Clamps, Suture Instruments, Compression Devices, Clip Appliers Application: Cardiovascular Surgery, Gastrointestinal Surgery, Urological Procedures, Thoracic Surgery, Neurosurgical Procedures End User: Surgical Centers, Specialty Clinics, Academic Medical Centers, Ambulatory Surgery Facilities, Cancer Treatment Centers Technology: Manual, Semi-Automatic, Automatic, Robotic-Assisted, Laser-Based |
| Companies Covered | Medtronic, Johnson & Johnson, B. Braun Melsungen, Intuitive Surgical, Boston Scientific Corporation, Getinge, Baxter, Ethicon US, LLC, Peters Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anastomosis Devices Market Shifts & Advancements
Device miniaturization and intelligent firing mechanisms are redefining performance benchmarks across gastrointestinal and thoracic applications. Manufacturers now compete on tissue-sensing capabilities and staple line integrity rather than basic mechanical reliability.
Smart staplers incorporating real-time tissue thickness sensors are collapsing the gap between manual operator skill and consistent anastomotic outcomes. Academic medical centers in the United States are adopting these platforms fastest, compressing training curves for surgical residents while reducing leak rates in colorectal procedures.
Europe's MDR and REACH frameworks are tightening chemical safety and biocompatibility documentation for implantable polymers. Manufacturers serving EU markets now face extended validation timelines for absorbable anastomotic rings, forcing earlier-stage design choices about material composition and sterilization methods.
Hospital procurement consortia are consolidating vendor relationships across integrated delivery networks. Large United States health systems now negotiate multi-year supply agreements bundling staplers, reloads, and service contracts, displacing the fragmented purchasing patterns that previously favored regional distributors.
Global Anastomosis Devices Market Segmentation
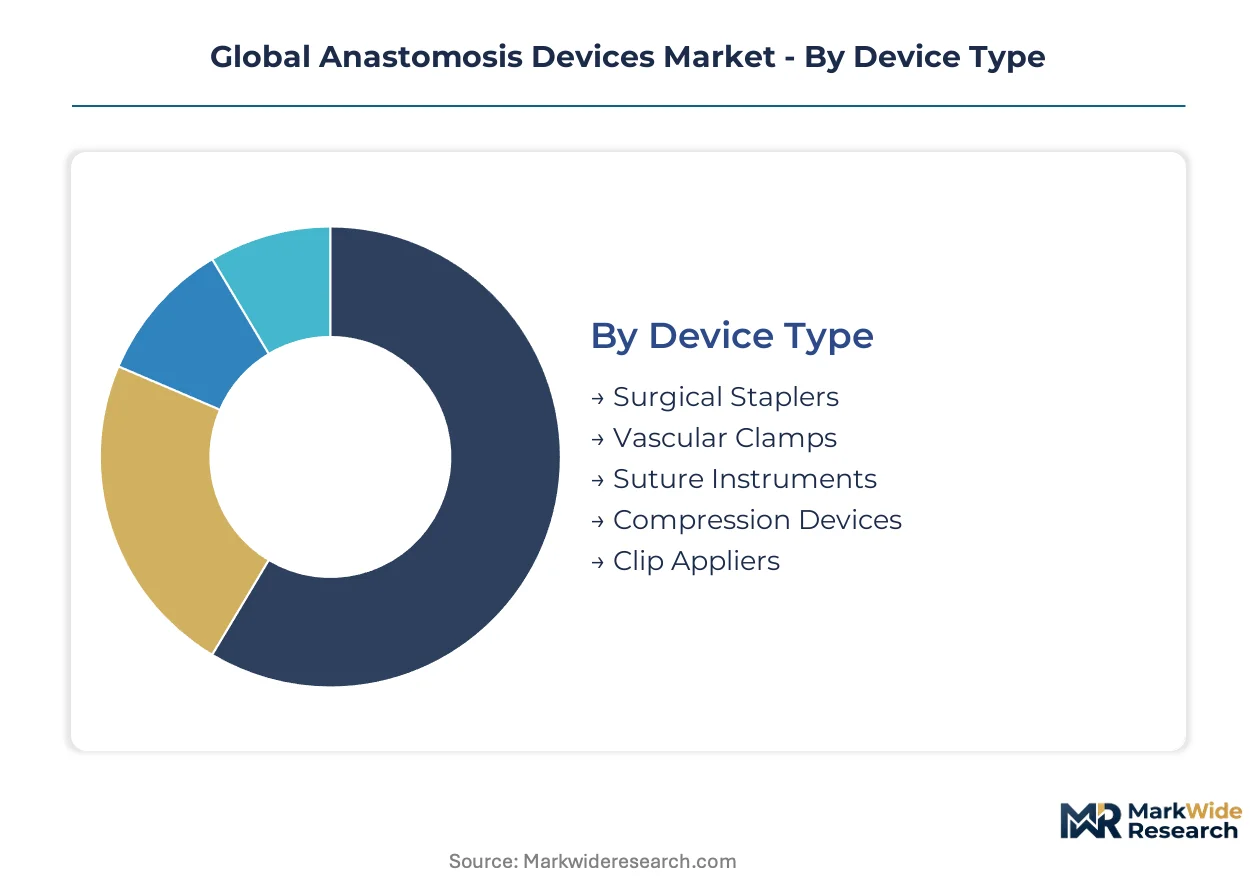
Anastomosis device segmentation reveals how clinical requirements, reimbursement structures, and capital availability fragment purchasing decisions across healthcare systems. Device manufacturers must align product portfolios with distinct technical specifications and budget cycles that vary by procedure type and facility tier.
Device Type:
The use-case spectrum spans from high-volume gastrointestinal procedures requiring rapid tissue approximation to delicate vascular reconstructions demanding atraumatic handling.
- Surgical Staplers:These devices deploy stainless steel or titanium staples in linear or circular configurations, with powered firing mechanisms now standard in thoracic departments at academic medical centers in the United States. Demand concentrates in gastrointestinal surgery where procedure volume and speed requirements justify disposable cartridge economics.
- Vascular Clamps:Atraumatic jaw designs with calibrated pressure distribution enable temporary vessel occlusion during coronary artery bypass grafting. German cardiac surgery programs favor specialized clamps with integrated flow measurement capabilities, reflecting that country's concentration of high-complexity cardiovascular centers.
- Suture Instruments:Hand-held needle drivers and automated suturing devices serve cost-constrained settings where staple cartridge costs prove prohibitive.
- Compression Devices:Mechanical anastomotic rings using nitinol or absorbable polymers create circumferential tissue approximation without foreign body retention.
- Clip Appliers:Titanium and polymer clips secure vessel branches during laparoscopic procedures, with disposable designs dominating United States ambulatory facilities.
Established volume favors surgical staplers; emerging adoption favors compression devices.
Application:
Procedure complexity and reimbursement differentiation create distinct equipment requirements across surgical disciplines.
- Cardiovascular Surgery:Coronary and peripheral vascular reconstructions demand precision anastomotic tools with minimal endothelial trauma. Japanese cardiovascular centers under PMDA oversight maintain stringent validation requirements for powered devices used in off-pump coronary artery bypass procedures.
- Gastrointestinal Surgery:Colorectal resections and bariatric procedures generate the highest staple consumption volumes globally. United States academic medical centers are deploying smart staplers with tissue-sensing technology to reduce anastomotic leak rates in colorectal cases.
- Urological Procedures:Robotic-assisted prostatectomy and partial nephrectomy drive demand for articulating staplers compatible with da Vinci systems.
- Thoracic Surgery:Lung resections and esophageal procedures require curved staple cartridges designed for confined chest cavity access.
- Neurosurgical Procedures:Cerebral vascular bypass operations utilize microvascular clamps and suture instruments with submillimeter precision.
Reimbursement intensity favors cardiovascular applications; volume expansion favors gastrointestinal surgery.
End User:
Capital availability and case mix determine whether facilities invest in robotic platforms or retain manual instrument bases.
- Academic Medical Centers:These institutions combine training mandates with research funding that supports robotic surgery program expansion. United States academic centers now standardize on powered stapling platforms across gastrointestinal and thoracic services.
- Surgical Centers:High-volume, procedure-focused facilities in Germany prioritize efficiency through standardized stapler platforms with bulk purchasing agreements.
- Specialty Clinics:Cardiovascular and urology-focused practices concentrate advanced energy devices for specific procedure sets.
- Ambulatory Surgery Facilities:Cost constraints and rapid turnover requirements favor disposable manual staplers with minimal capital investment.
- Cancer Treatment Centers:Multidisciplinary oncology programs integrate anastomotic devices across surgical oncology, interventional radiology, and gastroenterology service lines.
Technology leadership sits with academic medical centers; volume concentration sits with surgical centers.
Technology:
Automation intensity correlates directly with capital expenditure capacity and technician training infrastructure.
- Robotic-Assisted:Integration with da Vinci and competing surgical robot platforms enables wristed stapling articulation impossible with manual or laparoscopic instruments. United States academic centers are installing these systems fastest, though certified operator scarcity limits utilization rates.
- Automatic:Battery-powered firing with uniform compression profiles reduces tissue trauma variability in gastrointestinal applications. Japanese PMDA evidence requirements extend registration timelines versus FDA 510(k) pathways for these devices.
- Manual:Reusable mechanical designs persist in India's government hospital procurement programs under Ayushman Bharat infrastructure buildout.
- Semi-Automatic:Spring-assisted firing mechanisms bridge cost and performance between manual and fully powered platforms.
- Laser-Based:Experimental tissue welding technologies remain confined to research protocols at select cardiovascular institutes.
Capital deployment favors robotic-assisted platforms; accessibility favors manual technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification pathways for surgical staplers establish the regulatory baseline that shapes device validation requirements across developed markets. Academic medical centers in the United States, Germany, and Japan concentrate demand for powered stapling platforms as these institutions scale minimally invasive surgery programs.
United States
Academic medical centers in Boston and the Research Triangle drive adoption of robotic-assisted anastomotic staplers integrated with da Vinci systems. FDA heightened adverse event reporting mandates for surgical staplers since 2019 force manufacturers to revalidate safety profiles before 510(k) clearance. The Cleveland Clinic and Mayo Clinic anchor clinical validation networks that shape purchasing standards for integrated delivery networks nationwide.
Germany
Cardiac surgery programs in Berlin and Heidelberg favor specialized vascular clamps with integrated flow measurement for off-pump coronary procedures. EMA MDR compliance timelines accelerate replacement cycles for legacy polymer-based anastomotic rings throughout university hospitals. Baden-Württemberg's medical technology cluster around Tuttlingen sustains localized manufacturing and direct hospital service models for compression devices.
Japan
PMDA maintains distinct clinical evidence standards for powered stapling devices that extend registration timelines versus FDA pathways. Tokyo and Osaka academic centers concentrate da Vinci system installations, though certified operator scarcity limits utilization rates. METI funding for surgical robot infrastructure supports training program expansion at Keio University and University of Tokyo Hospitals.
India
Ayushman Bharat government hospital procurement programs generate volume demand for mid-tier disposable manual staplers in tier-2 and tier-3 cities. CDSCO regulates surgical staplers as Class C medical devices with abbreviated approval pathways for predicate-based submissions. Maharashtra and Karnataka surgical infrastructure buildout concentrates device demand in Mumbai, Pune, and Bangalore metropolitan hospital networks.
United Kingdom
NHS England procurement frameworks consolidate vendor relationships across integrated care systems, favoring multi-year supply agreements for stapling platforms. MHRA post-Brexit regulatory autonomy maintains alignment with MDR biocompatibility documentation requirements for polymer-based rings. London teaching hospitals and the Oxford-Cambridge arc anchor adoption of smart staplers with tissue-sensing technology in colorectal surgery.
Global Anastomosis Devices Market Competitive Landscape
Broad-portfolio conglomerates and specialized surgical technology firms split the market into distinct competitive spheres. Hospital procurement consortia favor suppliers offering integrated device-and-service bundles across gastrointestinal, thoracic, and cardiovascular applications. Three archetypes dominate: diversified medical technology conglomerates with stapling as one vertical among many; pure-play surgical robotics specialists; and regional European manufacturers with localized service capabilities. Competitive positioning hinges on securing multi-year integrated delivery network contracts and achieving regulatory clearances across FDA, EMA, and PMDA jurisdictions simultaneously.
Within the diversified conglomerate tier, Medtronic plc and Johnson & Johnson occupy positions defined by breadth of surgical portfolio rather than anastomosis specialization alone. B. Braun Melsungen AG represents the European service-anchored archetype with manufacturing and direct hospital relationships concentrated in German-speaking markets. Intuitive Surgical Inc. exemplifies the robotics-pure-play model, with anastomotic stapler attachments representing one component of platform ecosystem strategy.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| B. Braun Melsungen |
| Intuitive Surgical |
| Boston Scientific Corporation |
| Getinge |
| Baxter |
| Ethicon US, LLC |
| Peters Surgical |
| Others |
Supply & Pricing Matrix
Overcapacity in Asian titanium refining operations is compressing margins for staple raw material suppliers while simultaneously granting device manufacturers procurement leverage. This utilization imbalance feeds into pricing postures that vary sharply by geography and buyer tier.
Pricing Analysis
Geographic price spreads between United States academic medical centers and Indian government hospitals exceed three-to-one for comparable manual stapler platforms. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in mid-tier disposable devices is intensifying because Ayushman Bharat procurement programs emphasize volume scale over feature differentiation. Ambulatory surgery facilities exhibit the highest price sensitivity, while academic medical centers prioritize tissue-sensing capabilities over unit cost.
Supply Chain Analysis
Extended payment terms from large United States health systems are forcing tier-two suppliers to utilize supply-chain finance facilities, concentrating working capital risk. Titanium feedstock draws from Chinese and Japanese refining operations, with nitinol shape-memory alloys sourcing primarily from United States and German specialty mills. Single-source vulnerability in polymer resin supply for absorbable rings creates exposure to REACH regulatory shifts. Distribution runs through hospital procurement consortia and integrated delivery networks rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified da Vinci system operator scarcity constrains installed base utilization rates, creating a bottleneck that shapes competitive returns across robotic-assisted segments.
For Market Incumbents: Harden regulatory submission capabilities across FDA, EMA, and PMDA jurisdictions simultaneously to preempt emerging entrant clearance advantages. Deepen backward integration into titanium processing to offset raw material volatility exposure. Prioritize multi-year integrated delivery network contracts that bundle staplers, reloads, and preventive maintenance. For New Entrants and Emerging Players: India's tier-2 and tier-3 city hospital infrastructure under Ayushman Bharat offers the most penetrable white-space for mid-tier disposable manual staplers. Target gastrointestinal surgery departments in cost-constrained settings where powered platform capital requirements face budgetary resistance. Pursue CDSCO Class C device registration through predicate-based submission pathways to accelerate market entry. For Investors and Strategic Acquirers: Capital is best deployed toward robotics-pure-play specialists with da Vinci-compatible attachment portfolios and established hospital system validation networks. Long-term viability hinges on securing procedure-specific indications across colorectal, thoracic, and urological applications. Monitor PMDA powered device registration timelines as an inflection indicator for competitive positioning in Asia-Pacific expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance pathways for tissue-sensing staplers reshape competitive timelines at academic centers. |
| CE Marking Pathway | MDR biocompatibility documentation requirements extend validation cycles for polymer-based anastomotic rings. |
| Hospital System Partnership | Multi-year supply agreements with Cleveland Clinic and Mayo Clinic networks anchor purchasing standards nationwide. |
| Software Companion Development | Real-time staple line integrity algorithms differentiate powered platforms in colorectal leak rate reduction. |
| Reimbursement Strategy | CMS procedural coding alignment for robotic-assisted anastomosis drives adoption economics in United States facilities. |
Research Methodology
Desk research of FDA 510(k) filings, EMA MDR technical documentation, and hospital procurement databases preceded structured interviews with gastrointestinal surgeons, thoracic department heads, biomedical engineers, and GPO contracts managers. Primary fieldwork across United States, German, and Japanese academic medical centers combined with secondary validation from regulatory submission records and CMS reimbursement data. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Fixed assumptions across the analysis window include sustained minimally invasive surgery program expansion at academic centers, stable titanium feedstock pricing, and current FDA adverse event reporting mandate intensity. Segmentation modeling incorporated device type, application specialty, end-user facility tier, and technology automation level. CAGRs derived from logistic adoption curves for robotic platforms and linear replacement cycles for manual instruments. Forecast inputs included da Vinci system installation trajectories and PMDA registration timeline differentials.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese surgical instrument manufacturers would shift outcomes. Macroeconomic contraction affecting hospital capital budgets, regulatory deviation in polymer biocompatibility standards, or breakthrough tissue welding technology maturation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Epidural Anesthesia Sets Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
Myopia Management Lenses Market
Medical Devices
Germanium-68/Gallium-68 Generators Market
Medical Devices
North America Arthroscopy Devices Market
Medical Devices
Light Therapy Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Electronic Pill Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Prescription Goggles Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
Sphincterotomes Market
Medical Devices
Middle East and Africa Vagus Nerve Stimulation Market
Medical Devices
Intelligent Electronic Sphygmomanometers Market
Medical Devices
Glass Syringe Market
Medical Devices
Automatic Clotting Timer Systems Market