
 Ischemic Stroke Aspiration Systems Market | 2026-2036
Ischemic Stroke Aspiration Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Ischemic Stroke Aspiration Systems Market Foresight
Large-bore aspiration catheter specifications are redrawing competitive boundaries in neurovascular thrombectomy. Medtronic plc leverages its integrated neuroscience portfolio to sustain catheter supply security across major stroke centers. Penumbra, Inc. specializes in aspiration-first workflow design that anchors physician training protocols in high-volume institutions.
Ischemic stroke aspiration systems are catheter-based devices that apply controlled vacuum force to extract thrombus from intracranial vessels, typically operating through 6 French or larger distal access platforms with aspiration lumens exceeding 0.060 inches to optimize flow dynamics and clot engagement. Mechanical embolectomy devices command premium positioning due to their integration with stent retriever rescue protocols, while active vacuum technology segments attract R&D investment from manufacturers seeking to differentiate on revascularization speed and first-pass efficacy. Emergency medical services represent an emerging end-user channel as prehospital stroke identification protocols expand the treatable window for aspiration-based interventions.
FDA 510(k) clearance requirements and EU MDR technical documentation standards shape product development timelines and clinical evidence thresholds for market access in the United States and European markets. Japan's PMDA neurovascular device approval pathway adds a third regulatory checkpoint that manufacturers must navigate for commercial presence in high-reimbursement Asian healthcare systems. Stakeholders must monitor how real-world evidence mandates from regulators redefine post-market surveillance obligations and competitive differentiation through clinical outcome databases.
Market Dynamics
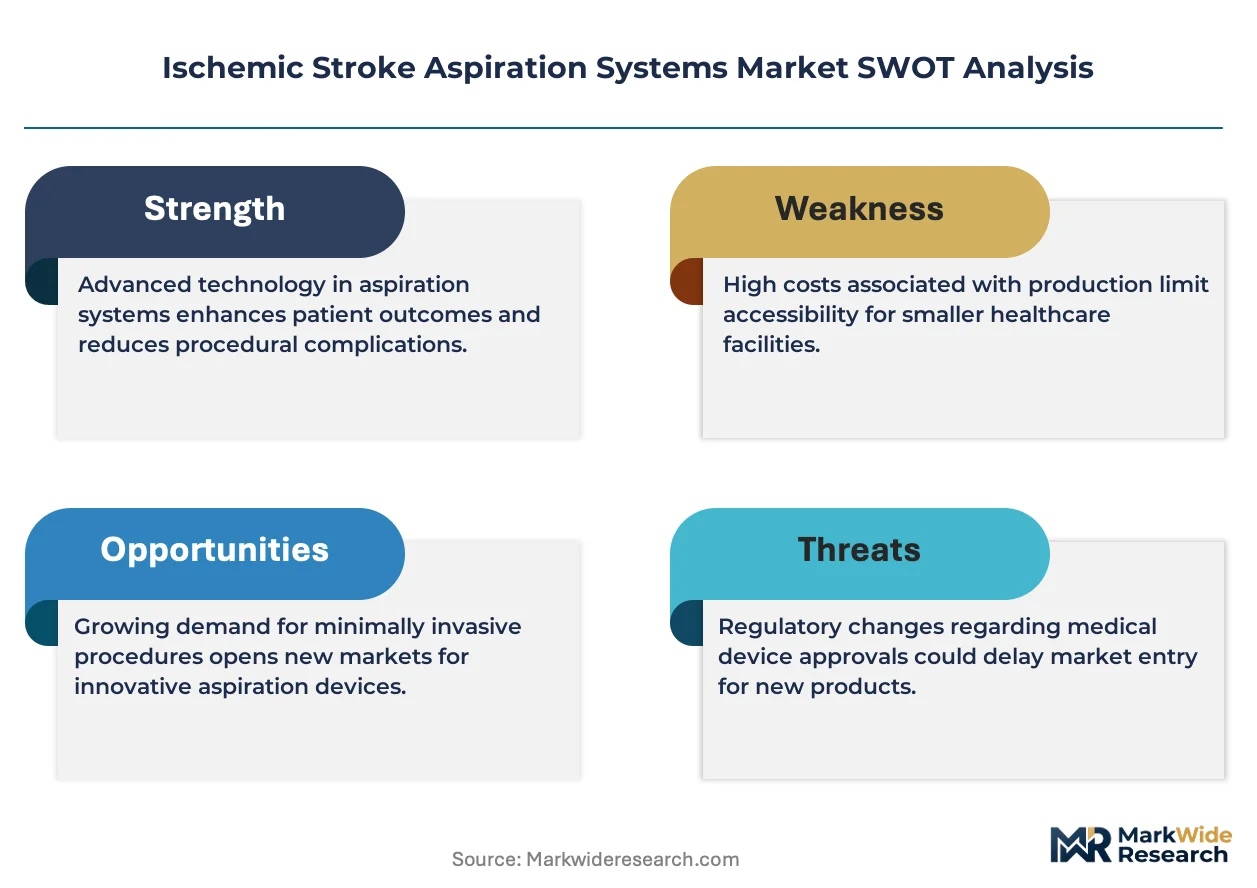
Large-bore aspiration catheter specifications are redrawing competitive boundaries as manufacturers race to optimize flow dynamics and first-pass revascularization rates in neurovascular thrombectomy.
Growth Catalysts
- FDA 510(k) clearance:Streamlined regulatory pathways accelerate product development cycles for aspiration catheter platforms seeking market access in the United States.
- Comprehensive stroke center certification:Hospital accreditation standards in the United States, Germany, and Japan drive capital investment in aspiration thrombectomy infrastructure.
- Aspiration-first workflow protocols:Physician training programs at high-volume neurovascular centers anchor clinical adoption patterns for catheter-based thrombus extraction systems.
Market Restraints
- Nitinol hypotube supply concentration:Specialized alloy sourcing for catheter shaft manufacturing creates vulnerability to raw material availability disruptions.
- EU MDR technical documentation:Recertification timelines extend product launch windows and elevate clinical evidence thresholds for European market entry.
- Stent retriever rescue protocols:Established mechanical embolectomy alternatives limit pure-play aspiration system penetration in certain clinical pathways.
Strategic Opportunities
- Emergency medical services channel:Prehospital stroke identification protocols expand the treatable intervention window for field-deployable aspiration platforms.
- Active vacuum technology convergence:Integration of controlled suction algorithms with distal access catheter designs creates differentiation on revascularization speed metrics.
- Japan PMDA neurovascular pathway:High-reimbursement Asian healthcare systems offer premium positioning for manufacturers navigating third regulatory checkpoints beyond FDA and EU MDR.
Industry Challenges
- Neurointerventionalist training pipelines:Specialized physician skill requirements for large vessel occlusion procedures create workforce bottlenecks at expanding stroke center networks.
- Real-world evidence mandates:Post-market surveillance obligations from regulators redefine competitive differentiation through clinical outcome database investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ischemic Stroke Aspiration Systems Market |
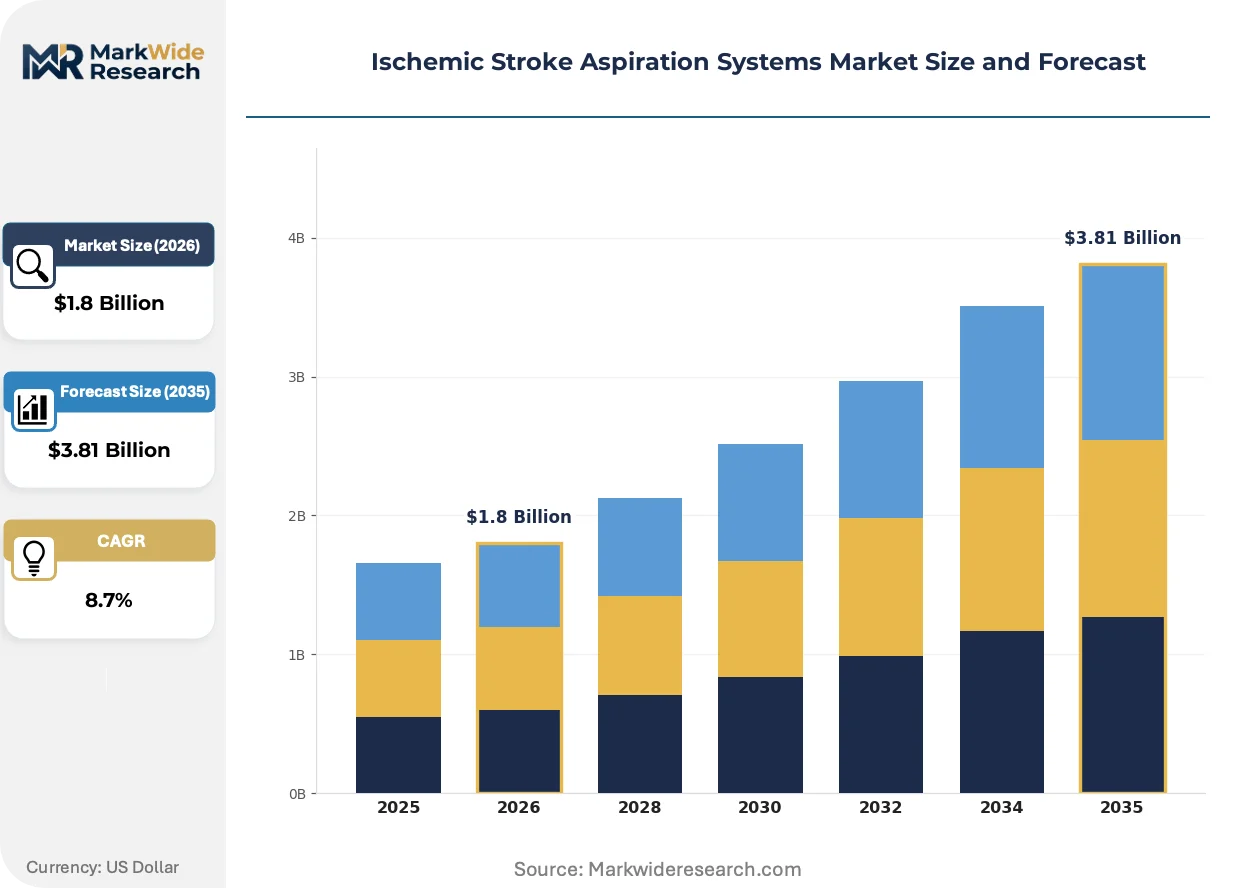
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
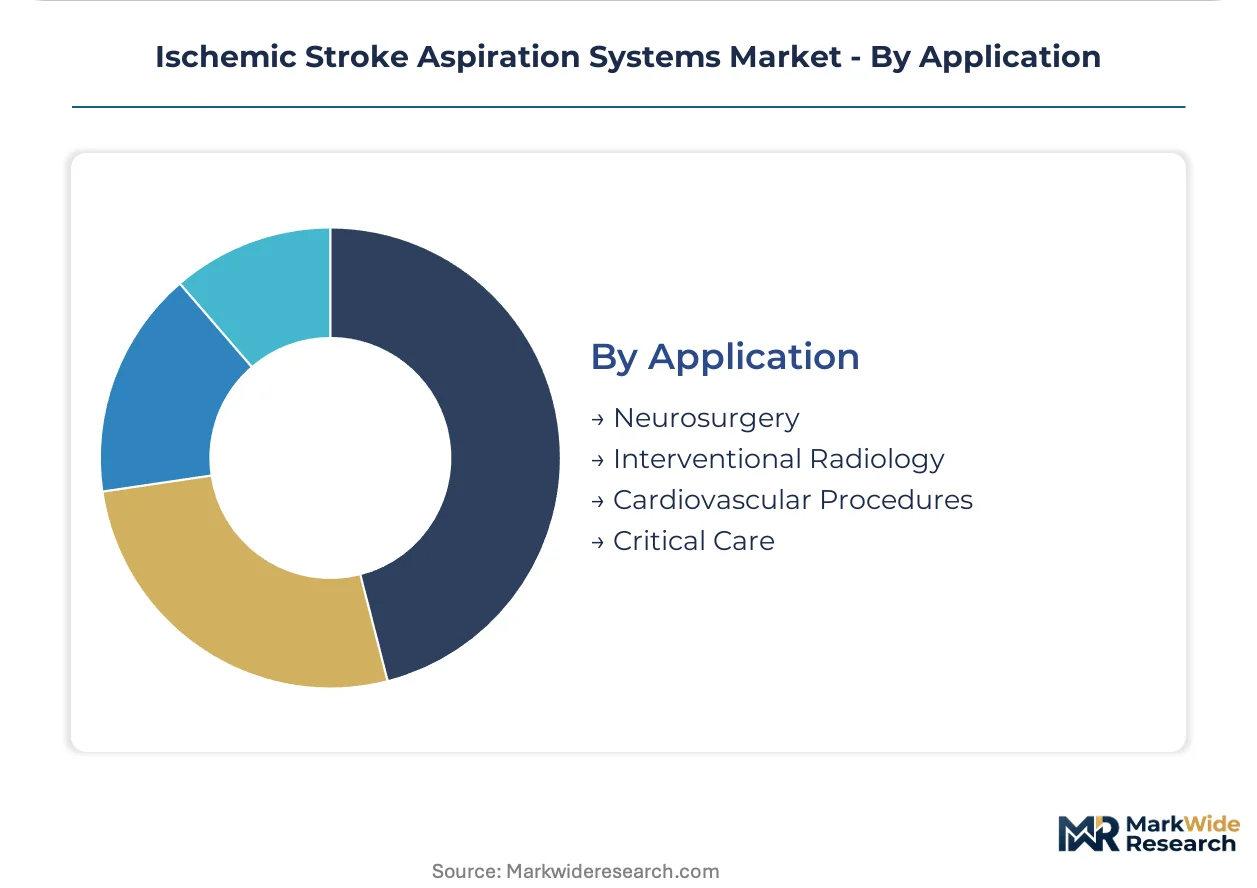
| Segmentation | Product Type: Manual Aspiration Devices, Mechanical Embolectomy Devices, Catheters, Suction Devices End User: Hospitals, Specialty Clinics, Rehabilitation Centers, Emergency Medical Services Technology: Active Vacuum, Passive Aspiration, Hybrid Systems, Delivery Systems Application: Neurosurgery, Interventional Radiology, Cardiovascular Procedures, Critical Care |
| Companies Covered | Medtronic plc, Penumbra, Inc., Stryker Corporation, Boston Scientific Corporation, Terumo Corporation, Johnson & Johnson (Cerenovus), MicroPort Scientific Corporation, Merrit Medical Systems, Inc., Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ischemic Stroke Aspiration Systems Market Shifts & Advancements
Catheter engineering advances and regulatory pathway adaptations are compressing product development cycles while reshaping how aspiration systems integrate into acute stroke care workflows.
Distal access platform designs are decomposing traditional trade-offs between catheter trackability and aspiration lumen diameter. Neurovascular centers at academic medical centers are adopting 6 French and larger platforms with aspiration lumens exceeding 0.060 inches as standard first-line configurations. This engineering trajectory is decomposing historical market segmentation between aspiration-first and stent-retriever-first treatment paradigms.
EU MDR recertification requirements are elevating clinical evidence standards for neurovascular device manufacturers seeking continued European market presence. Technical documentation obligations now mandate extended follow-up data from post-market clinical follow-up studies. Aspiration catheter portfolios with established European market share are responding by accelerating patient registry investments to defend commercial positioning.
Prehospital care integration is altering how stroke systems of care configure device procurement and deployment logistics. Emergency medical services agencies in select United States metropolitan regions are piloting mobile stroke unit configurations that incorporate aspiration platform readiness protocols. This channel evolution is most visible in states with established comprehensive stroke center density and regionalized ambulance routing mandates.
Ischemic Stroke Aspiration Systems Market Segmentation
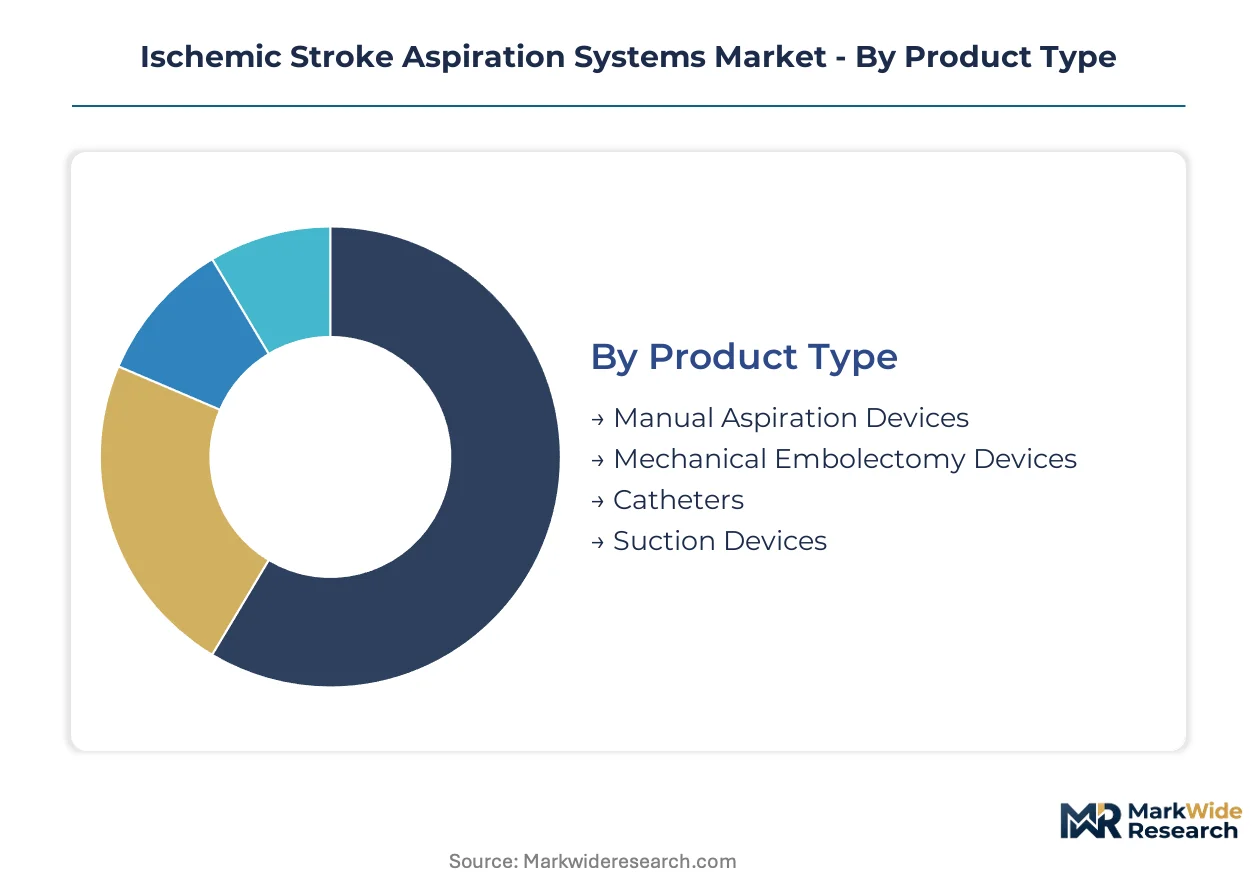
Segmentation in ischemic stroke aspiration systems reveals how product specifications, clinical settings, and technological architectures determine procurement patterns across neurovascular care networks. Understanding these divisions exposes where manufacturers concentrate R&D investment and which channel configurations yield highest margin capture.
Product Type:
Manual aspiration devices flow through hospital purchasing consortia with highest volume, while mechanical embolectomy systems concentrate in academic medical center specialty contracts.
- Mechanical Embolectomy Devices:Stent retriever-based systems integrate with aspiration platforms for rescue protocols in large vessel occlusion cases. Demand concentrates in United States comprehensive stroke centers where physician training programs anchor stent-retriever-first workflows despite aspiration-first adoption trends.
- Catheters:Large-bore aspiration catheters with 0.060+ inch lumens constitute the core hardware platform. Specifications exceeding 6 French distal access dominate procurement at high-volume neurovascular centers in Germany and Japan where catheter supply security shapes vendor selection criteria.
- Manual Aspiration Devices:Hand-operated syringe systems serve backup and resource-constrained settings.
- Suction Devices:Pump-based vacuum generators support controlled aspiration workflows.
Catheters dominate installed base. Mechanical embolectomy devices are where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive hospital installations from mobile emergency deployments requiring field-durable configurations.
- Hospitals:Comprehensive stroke centers and academic medical centers anchor aspiration system procurement through centralized capital budgets. United States hospital networks in states with regionalized ambulance routing mandates drive highest platform density per capita.
- Emergency Medical Services:Prehospital stroke identification protocols in select United States metropolitan regions pilot mobile stroke unit configurations. Field-deployable aspiration readiness expands the treatable intervention window for patients outside hospital catchment zones.
- Specialty Clinics:Outpatient neurovascular centers perform diagnostic and follow-up procedures.
- Rehabilitation Centers:Post-acute facilities manage secondary prevention and recovery protocols.
Hospitals dominate installed base. Emergency medical services are where expansion concentrates.
Technology:
Application requirements determine whether passive flow-dependent systems or algorithm-controlled active vacuum architectures command premium positioning.
- Active Vacuum:Microprocessor-controlled suction algorithms optimize thrombus engagement and minimize vessel trauma. R&D investment from manufacturers targets revascularization speed differentiation at neurovascular centers measuring first-pass efficacy metrics.
- Hybrid Systems:Dual-mode platforms switch between passive and active aspiration based on clot characteristics. Adoption concentrates in Japan where PMDA neurovascular device pathways reward technological sophistication with premium reimbursement positioning.
- Passive Aspiration:Flow-dependent systems rely on manual syringe pressure without electronic control.
- Delivery Systems:Integrated catheter-vacuum combinations streamline procedural workflow.
Passive aspiration dominates installed base. Active vacuum is where expansion concentrates.
Application:
Customer type segmentation separates high-acuity neurointerventional procedures from broader cardiovascular interventions sharing catheter technology platforms.
- Neurosurgery:Intracranial thrombectomy for large vessel occlusion strokes represents the primary indication. Neurovascular centers at academic medical centers in the United States and Germany concentrate aspiration-first protocol adoption and physician training program investments.
- Interventional Radiology:Cross-specialty operators perform thrombectomy alongside other endovascular procedures. Demand spreads across stroke center networks where interventional radiologists supplement dedicated neurointerventionalist coverage.
- Cardiovascular Procedures:Peripheral and coronary thrombectomy applications leverage adapted aspiration platforms.
- Critical Care:ICU-based interventions for stroke patients unable to transport to angiography suites.
Neurosurgery dominates installed base. Interventional radiology is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in neurovascular devices tilt toward deficit positions in European and Asian healthcare systems that rely on catheter imports from United States manufacturing clusters. Reimbursement density and regulatory pathway efficiency determine where aspiration platform investments concentrate.
United States
Comprehensive stroke center certification mandates in 48 states drive capital procurement of large-bore aspiration platforms. FDA 510(k) clearance pathways compress product launch timelines for domestic manufacturers. The Texas Medical Center in Houston anchors the highest procedural volume per capita, with Methodist Hospital and Memorial Hermann operating 24/7 thrombectomy protocols.
Germany
EU MDR recertification requirements elevate clinical evidence thresholds for aspiration catheter portfolios seeking continued market presence. The national neurovascular registry mandates outcome reporting that shapes hospital procurement decisions. Heidelberg University Hospital and Charité Berlin concentrate physician training investments, anchoring aspiration-first protocol diffusion across Baden-Württemberg and Berlin-Brandenburg.
Japan
PMDA neurovascular device approval pathways reward technological sophistication with premium reimbursement positioning for active vacuum systems. The J-Stroke registry generates real-world evidence that influences hospital purchasing committees. Tokyo Women's Medical University and Osaka University Hospital anchor high-volume aspiration centers in Kanto and Kansai regions.
United Kingdom
NHS England stroke service reconfiguration concentrates thrombectomy capacity in 24 hyper-acute stroke units, consolidating demand for aspiration platforms. NICE technology appraisal pathways determine which catheter specifications receive commissioning approval. The Greater Manchester and London stroke networks drive highest platform density, with Salford Royal and St George's University Hospitals anchoring regional referral patterns.
China
NMPA Class III medical device registration timelines extend market entry for foreign aspiration catheter manufacturers, creating openings for domestic producers. The national stroke center construction program targets 300 comprehensive centers by 2030. Beijing Tiantan Hospital and Huashan Hospital Shanghai anchor physician training and protocol standardization in the Beijing-Tianjin-Hebei and Yangtze River Delta clusters.
Ischemic Stroke Aspiration Systems Market Competitive Landscape
Listed leaders compete with private specialists across regulatory pathway expertise and catheter supply security dimensions. The vendor base stratifies into three tiers: integrated neuroscience conglomerates with diversified neurovascular portfolios, pure-play aspiration specialists with workflow-anchored training programs, and diversified medical technology firms with stroke care as one vertical among many. Consolidation pressures favor acquisition of catheter engineering capabilities by firms lacking in-house shaft manufacturing. Strategic partnerships between aspiration platform vendors and stroke center networks lock in multi-year procurement contracts.
Within the integrated neuroscience tier, Medtronic plc and Stryker Corporation exemplify scale-driven positions that leverage hospital supply chain relationships across multiple therapeutic areas. Penumbra, Inc. occupies a specialist archetype, with its corporate identity signaling pure-play commitment to neurovascular aspiration workflows. Johnson & Johnson's Cerenovus division represents the diversified healthcare conglomerate model, where stroke care sits within a broader interventional portfolio. These three anchors illustrate how competitive positioning fragments across corporate structure rather than converging on uniform strategies.
| Leading Market Players |
|---|
| Medtronic plc |
| Penumbra, Inc. |
| Stryker Corporation |
| Boston Scientific Corporation |
| Terumo Corporation |
| Johnson & Johnson (Cerenovus) |
| MicroPort Scientific Corporation |
| Merrit Medical Systems, Inc. |
| Teleflex Incorporated |
| Others |
Supply & Pricing Matrix
Large-bore catheter specifications displacing standard distal access platforms are redrawing supply geography toward United States and German manufacturing clusters while compressing price premiums on legacy 5 French configurations. This substitution dynamic concentrates procurement leverage with comprehensive stroke centers able to mandate catheter supply security clauses in multi-year contracts.
Pricing Analysis
Hospital purchasing consortia anchor contract-based pricing structures across aspiration system categories. Three-tier pricing separates active vacuum platforms from hybrid systems from passive aspiration configurations, with differentiation driven by FDA breakthrough designation status and first-pass efficacy data. Pricing pressure stems from EU MDR recertification costs flowing through to European list prices. Emergency medical services channels exhibit highest price sensitivity due to capital budget constraints, while academic medical centers prioritize supply security over unit cost.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time catheter delivery to German and United Kingdom stroke centers. Nitinol hypotube supply concentrates in United States, Japan, and Germany, with shaft manufacturing drawing from specialized alloy foundries in these geographies. Single-source vulnerability sits with concentrated hypotube suppliers serving catheter shaft production. Distribution runs through hospital purchasing consortia and GPO contracts in the United States, direct tender processes in Germany, and regional distributor networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stent retriever rescue protocols advancing as first-line alternatives in select European centers threaten pure-play aspiration positioning, forcing incumbents to defend integrated platform value.
For Market Incumbents: Consolidate catheter supply security through backward integration into nitinol hypotube sourcing or captive long-term offtake agreements with Japanese and German alloy suppliers. Defend installed base at high-volume United States comprehensive stroke centers by embedding aspiration-first training protocols into physician fellowship curricula, locking out stent-retriever-first competitors through workflow anchoring. For New Entrants and Emerging Players: Anchor in emergency medical services channels where prehospital stroke identification protocols are expanding treatable windows but incumbent platform coverage remains sparse. Target mobile stroke unit deployments in United States metropolitan regions with regionalized ambulance routing mandates, offering field-durable aspiration configurations with simplified logistics requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed catheter engineering specialists possessing EU MDR technical documentation capabilities but lacking global stroke center network relationships. Five-to-ten year viability hinges on active vacuum technology differentiation and real-world evidence database investments. Monitor Japan PMDA approval timelines as inflection indicator for premium reimbursement positioning in high-margin Asian markets.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Recertification timelines compress for portfolios with established PMCF studies. |
| Hospital System Partnership | Multi-year procurement contracts at Texas Medical Center clusters lock in platform density. |
| Software Companion Development | Algorithm-controlled suction integration differentiates active vacuum architectures at academic centers. |
| Reimbursement Strategy | PMDA pathway navigation secures premium positioning in Japanese comprehensive stroke centers. |
| Physician Training Program Expansion | Aspiration-first protocol anchoring at Heidelberg and Charité defends European market share. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearances, EU MDR technical documentation filings, and hospital procurement databases. Primary interviews engaged neurointerventionalists, stroke center purchasing committee chairs, biomedical engineers, and GPO contracts managers. Secondary sources included CMS Medicare reimbursement data, Japan's MHLW fee schedule revisions, and German neurovascular registry outcome reports. Bottom-up catheter shipment estimates triangulated against top-down comprehensive stroke center capital expenditure patterns.
Segmentation dimensions modeled include product type, end user channel, technology architecture, and application specialty across the projection horizon. CAGRs derive from procedure volume growth at certified stroke centers, catheter replacement cycles, and technology substitution curves. Industry-specific inputs incorporate PMDA approval pathway timelines, EU MDR recertification completion rates, and EMS prehospital protocol expansion trajectories.
Material uncertainties — regulatory pathway delays, nitinol supply disruptions, and stent retriever protocol advances — sit outside the modeled envelope. Forecasts reflect assumptions regarding stroke center certification momentum and physician training pipeline expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Iliac Artery Stents Market
Cardiovascular Devices
Intravenous Catheters Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Global Nitinol-Based Medical Devices Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
China Cardiovascular Devices Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
Hypertension Management Devices Market
Cardiovascular Devices
Lung Stent Market
Cardiovascular Devices
Canada Cardiovascular Devices Market