
 Saudi Arabia Ophthalmic Devices Market | 2026-2036
Saudi Arabia Ophthalmic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Ophthalmic Devices Market Analytics
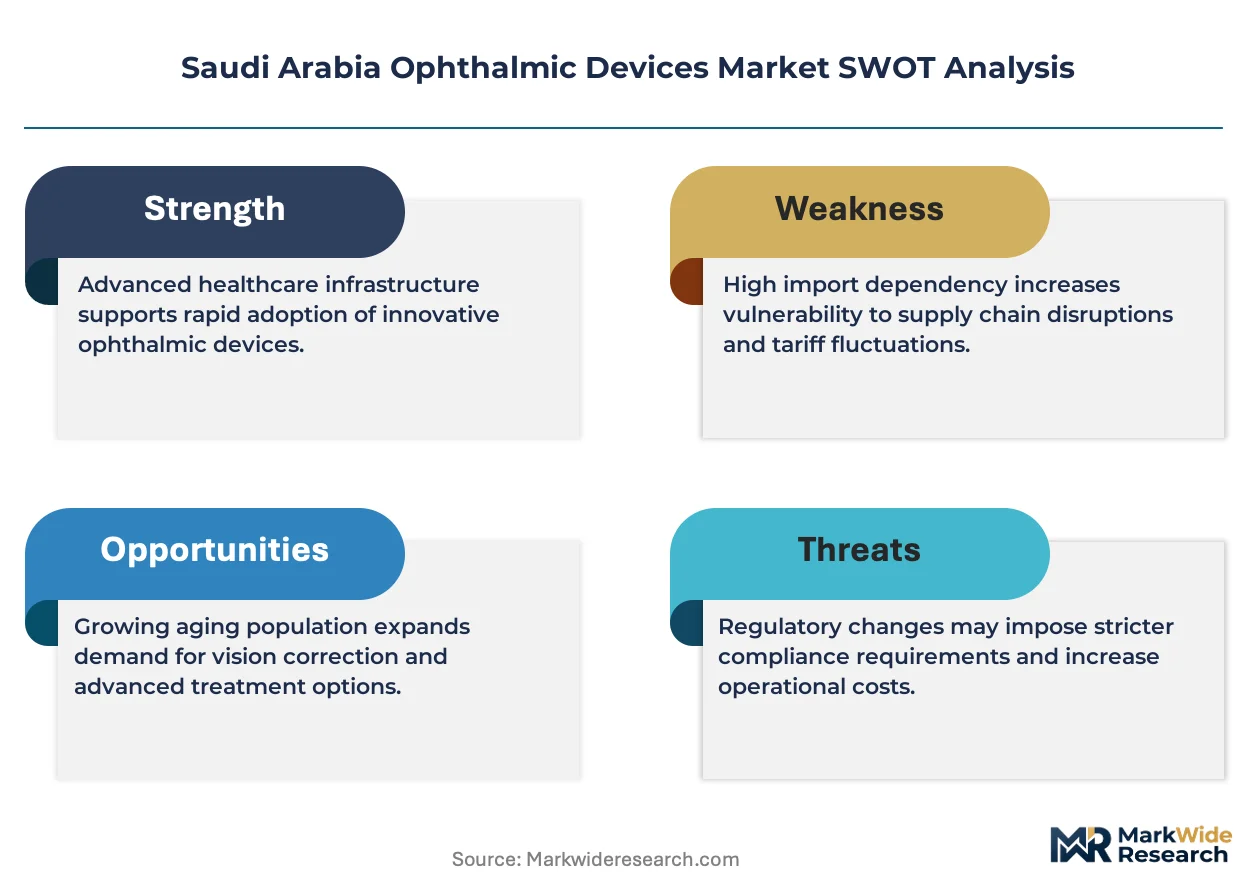
SFDA medical device registration requirements is rebalancing procurement standards for imported ophthalmic equipment, compelling distributors to validate clinical evidence for laser platforms and intraocular lenses. Alcon Inc leverages its surgical portfolio to anchor premium cataract procedure volumes across Ministry of Health facilities. Haag-Streit Group specializes in diagnostic imaging workflows for independent eye clinics seeking Swiss-engineered slit lamp configurations. EssilorLuxottica SA dominates vision care product distribution through optical retail partnerships in Riyadh and Jeddah.
Ophthalmic devices encompass precision-engineered instruments, implants, and diagnostic systems designed for ocular examination, surgical intervention, and refractive correction, typically manufactured under ISO 13485 quality management with biocompatible materials such as hydrophobic acrylic and silicone hydrogel. These devices serve the primary purpose of restoring visual acuity, managing progressive eye diseases, and enabling minimally invasive procedures that reduce recovery time for cataract and glaucoma patients. Diagnostic Equipment leads product type demand as hospitals prioritize Optical Coherence Tomography systems for early retinal disease detection, while Vision Care Products generates recurring revenue through disposable contact lens replacement cycles. Laser technology competes with ultrasound for glaucoma treatment applications where selective laser trabeculoplasty displaces conventional filtration surgery in ambulatory settings.
SFDA enforces medical device marketing authorization aligned with GCC harmonized technical regulations, requiring foreign manufacturers to appoint authorized representatives and submit clinical evaluation reports for Class III implantable devices. The Saudi Food and Drug Authority also coordinates with the Ministry of Health on health technology assessment criteria that influence tender specifications for public hospital procurement. Stakeholders must monitor SFDA guidance document updates on software-as-a-medical-device classifications that will affect AI-enabled diagnostic platforms seeking market entry.
Market Dynamics
Saudi Vision 2030 healthcare privatization is redirecting capital flows from centralized Ministry of Health procurement toward independent ambulatory surgery centers and private eye clinic networks, fragmenting historical tender concentration and elevating distributor service capabilities over price alone.
Growth Catalysts
- SFDA Registration Harmonization:The Saudi Food and Drug Authority's alignment with GCC technical regulations accelerates multi-country market access for approved devices, reducing redundant clinical trials across Gulf states.
- Femtosecond Laser Platforms:Bladeless cataract surgery adoption in Riyadh and Jeddah tertiary centers is compressing recovery timelines and expanding eligible patient pools for premium intraocular lens upgrades.
- Optical Coherence Tomography Integration:Retinal disease screening programs in Ministry of Health facilities are driving diagnostic equipment refresh cycles, with AI-enabled image analysis reducing specialist interpretation bottlenecks.
Market Restraints
- Import Dependency Concentration:Hydrophobic acrylic intraocular lens supply chains concentrate in Swiss and US manufacturing facilities, exposing distributors to currency volatility and extended shipping timelines through Jeddah Islamic Port.
- SFDA Clinical Evidence Requirements:Class III implantable device submissions now demand Saudi-specific clinical evaluation reports, extending registration timelines and freezing market entry for manufacturers lacking regional trial data.
- Phacoemulsification System Cost Structure:Capital equipment procurement budgets face pressure from disposable handpiece and viscoelastic consumable bundles that lock facilities into single-vendor service agreements.
Strategic Opportunities
- Eastern Province Undersupply:Dammam and Khobar ophthalmic surgical capacity lags Riyadh and Jeddah by approximately forty percent, creating first-mover advantages for ambulatory surgery center developers with femtosecond capability.
- Tele-ophthalmology Screening:Remote diabetic retinopathy detection programs in rural Najran and Asir regions bypass specialist scarcity through mobile OCT units connected to Riyadh-based reading centers.
- Vision 2030 Localization Incentives:Ministry of Investment manufacturing partnerships offer tariff exemptions and land allocations for surgical instrument and contact lens packaging facilities meeting fifty percent local content thresholds.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Femtosecond laser and OCT system maintenance requires certified technicians that Saudi technical institutes currently produce at insufficient volumes, forcing distributors to import Egyptian and Indian service personnel on renewable work visas.
- Legacy EMR Integration Friction:Diagnostic imaging workstations from European manufacturers lack native interoperability with Saudi Ministry of Health Seha electronic medical record architecture, necessitating costly middleware development or parallel documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Ophthalmic Devices Market |
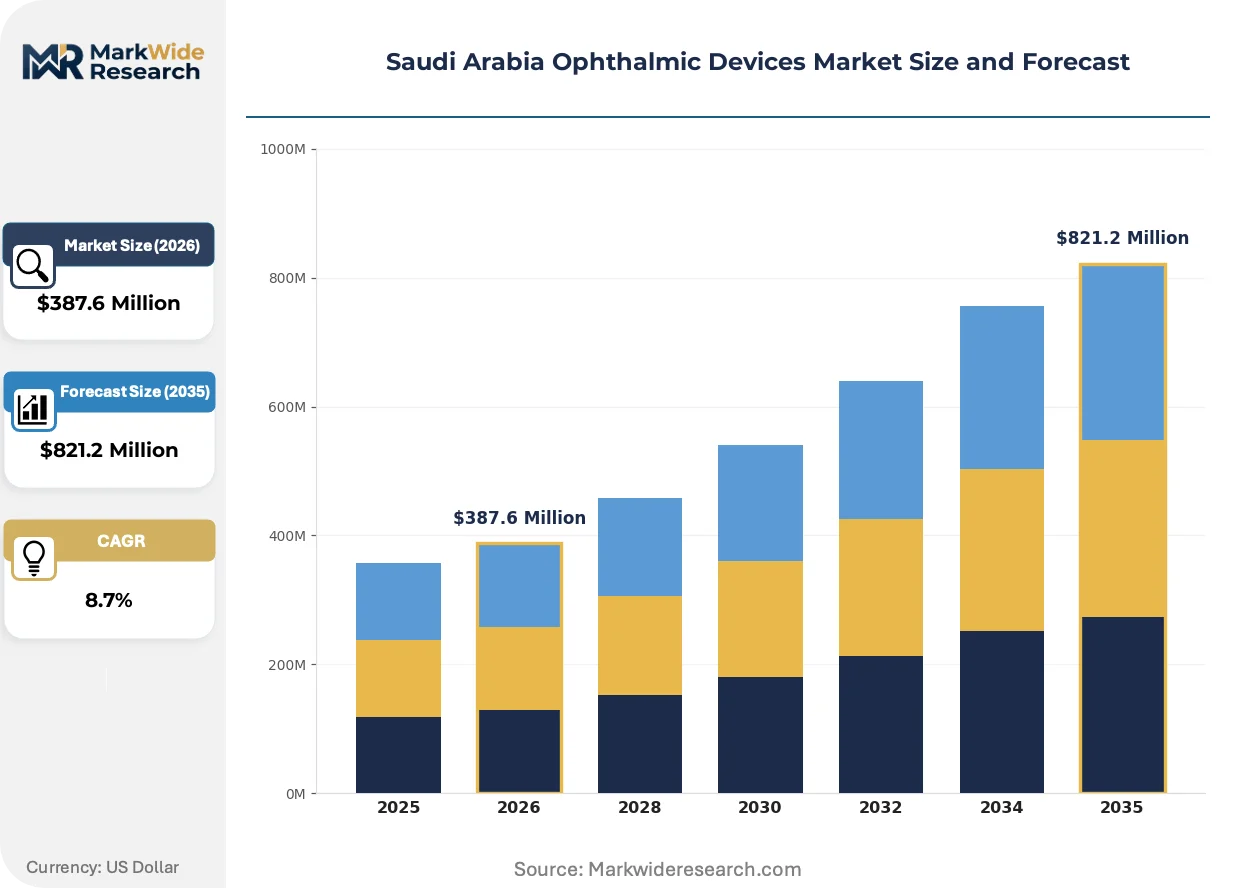
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraocular Lenses, Surgical Instruments, Diagnostic Equipment, Vision Care Products Technology: Laser, Optical Coherence Tomography, Ultrasound, Digital Imaging End User: Hospitals, Eye Clinics, Ambulatory Surgery Centers, Research Institutions Application: Cataract Surgery, Glaucoma Treatment, Refractive Surgery, Retinal Procedures |
| Companies Covered | Johnson & Johnson Vision Care, Haag-Streit Group, Alcon Inc, Topcon Corporation, Nidek Co Ltd, Bausch Health Companies Inc, EssilorLuxottica SA, Ziemer Group AG, Carl Zeiss Meditec AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Ophthalmic Devices Market Evolving Landscape
Technological convergence between diagnostic imaging and surgical planning software is compressing the traditional separation between pre-operative assessment and intra-operative execution, with artificial intelligence intermediating both workflows in Saudi tertiary centers.
Femtosecond laser-assisted cataract surgery is automating capsulotomy creation and lens fragmentation steps that previously demanded manual phacoemulsification skill. Ministry of Health flagship hospitals in Riyadh are adopting these platforms at replacement-cycle pace as older phaco machines depreciate. The technology is automating volume surgeon throughput while reducing endothelial cell loss variability, enabling same-day discharge protocols that expand ambulatory surgery center eligibility.
SFDA software-as-a-medical-device guidance documents are reclassifying AI-enabled OCT interpretation algorithms as regulated Class II products requiring clinical validation in Saudi patient populations. Foreign developers must now submit retrospective performance studies using local demographic data, extending time-to-market for diagnostic software updates. Independent eye clinics in Jeddah are responding by prioritizing platforms with existing SFDA clearance over newer unvalidated alternatives.
Direct procurement relationships between private hospital groups and European manufacturers are disintermediating traditional Saudi distributor networks for high-value capital equipment. King Faisal Specialist Hospital and Research Centre and similar tier-one institutions now negotiate laser platform purchases through dedicated Gulf representative offices, compressing distributor margins to service-only contracts. This channel compression is most visible in Riyadh where hospital procurement committees possess technical evaluation capacity absent in smaller regional facilities.
Saudi Arabia Ophthalmic Devices Market Segmentation
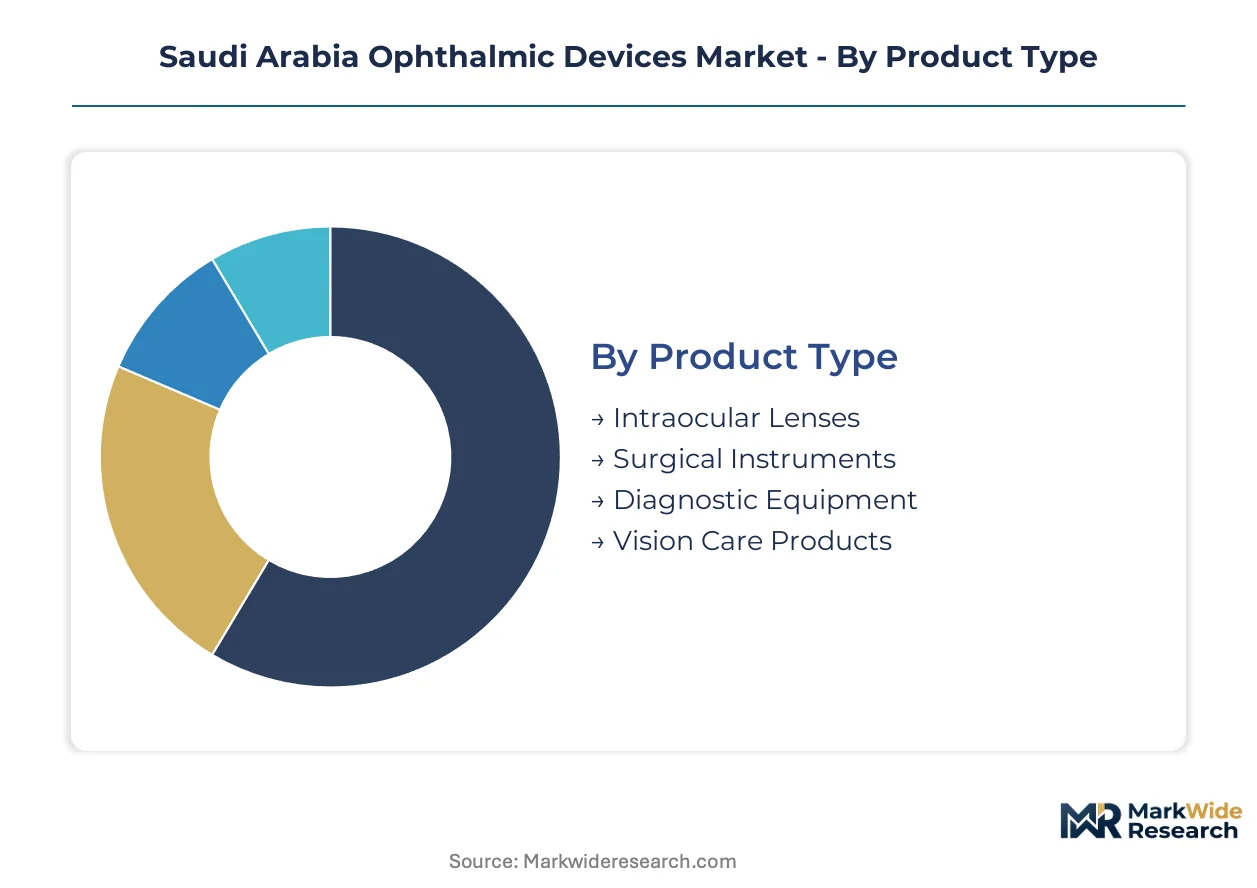
Segmentation in the Saudi Arabia ophthalmic devices market reveals how procurement authority fragmentation under Vision 2030 is reshaping vendor targeting. Product specifications, technology integration requirements, and facility infrastructure capabilities now determine channel strategy more than historical Ministry of Health tender dominance.
Product Type:
Procurement budgets diverge sharply between capital-intensive surgical platforms and recurring-consumable vision care, with private eye clinics prioritizing different bundles than public hospital networks.
- Intraocular Lenses:Hydrophobic acrylic and silicone hydrogel implants with toric and multifocal optical designs command premium positioning in Riyadh tertiary centers. Ministry of Health facilities in Jeddah are standardizing on pre-loaded delivery systems that reduce surgical variability and support same-day discharge protocols.
- Diagnostic Equipment:Optical Coherence Tomography systems with spectral-domain imaging and automated segmentation algorithms anchor retinal disease screening programs. Demand concentrates in Ministry of Health hospital networks upgrading pathology detection capabilities ahead of specialist workforce expansion.
- Surgical Instruments:Phacoemulsification handpieces, viscoelastic delivery systems, and capsulorhexis forceps manufactured under ISO 13485 protocols.
- Vision Care Products:Daily disposable silicone hydrogel contact lenses and preservative-free artificial tear formulations distributed through optical retail partnerships.
Diagnostic Equipment leads volumes today; Vision Care Products is gaining share fastest.
Technology:
Technology selection reflects facility capital cycles and reimbursement pathway maturity, with femtosecond platforms requiring dedicated ambulatory infrastructure.
- Laser:Femtosecond and excimer platforms for corneal and lenticular surgery integrate with diagnostic planning software for bladeless procedure workflows. Adoption concentrates in Jeddah and Riyadh private hospital groups with dedicated refractive surgery centers and direct manufacturer procurement relationships.
- Optical Coherence Tomography:Spectral-domain and swept-source systems with angiography modules enable non-invasive retinal vasculature assessment. SFDA software-as-a-medical-device reclassification of AI interpretation algorithms is extending validation timelines for platform upgrades.
- Ultrasound:A-scan and B-scan biometry systems for axial length measurement and posterior segment visualization in dense cataract cases.
- Digital Imaging:Fundus photography and slit-lamp documentation systems with telemedicine connectivity for rural screening programs.
Laser technology commands the highest capital allocation; Optical Coherence Tomography is expanding most quickly.
End User:
Facility type determines service intensity requirements and procurement decision velocity, with ambulatory surgery centers demanding turnkey maintenance packages.
- Hospitals:Ministry of Health tertiary centers and private hospital groups with comprehensive ophthalmology departments managing complex surgical caseloads. SFDA health technology assessment criteria and Seha EMR integration requirements shape tender specifications and lengthen evaluation cycles.
- Eye Clinics:Independent diagnostic and refractive practices in Riyadh and Jeddah optical retail corridors prioritizing Swiss-engineered slit-lamp configurations and rapid patient throughput.
- Ambulatory Surgery Centers:Privately operated day-case facilities with femtosecond laser platforms and streamlined discharge protocols.
- Research Institutions:King Faisal Specialist Hospital and academic medical centers conducting clinical trials for SFDA registration support.
Hospitals dominate current installed base; Ambulatory Surgery Centers are climbing the fastest.
Application:
Procedure volume distribution follows demographic disease burden and reimbursement pathway development, with refractive surgery remaining predominantly private-pay.
- Cataract Surgery:Phacoemulsification and femtosecond laser-assisted procedures with premium intraocular lens upgrades driving revenue per case. Volume concentrates in Ministry of Health facilities managing age-related lens opacity prevalence, with private centers capturing premium segment migration.
- Glaucoma Treatment:Selective laser trabeculoplasty and minimally invasive glaucoma surgery devices displacing conventional filtration in early-to-moderate disease. SFDA clinical evidence requirements for Class III implants are freezing market entry for novel drainage device manufacturers lacking Saudi trial data.
- Refractive Surgery:LASIK, PRK, and SMILE corneal laser procedures for myopia and astigmatism correction in private-pay patient segments.
- Retinal Procedures:Vitrectomy systems and membrane peeling instruments for diabetic retinopathy and macular pathology intervention.
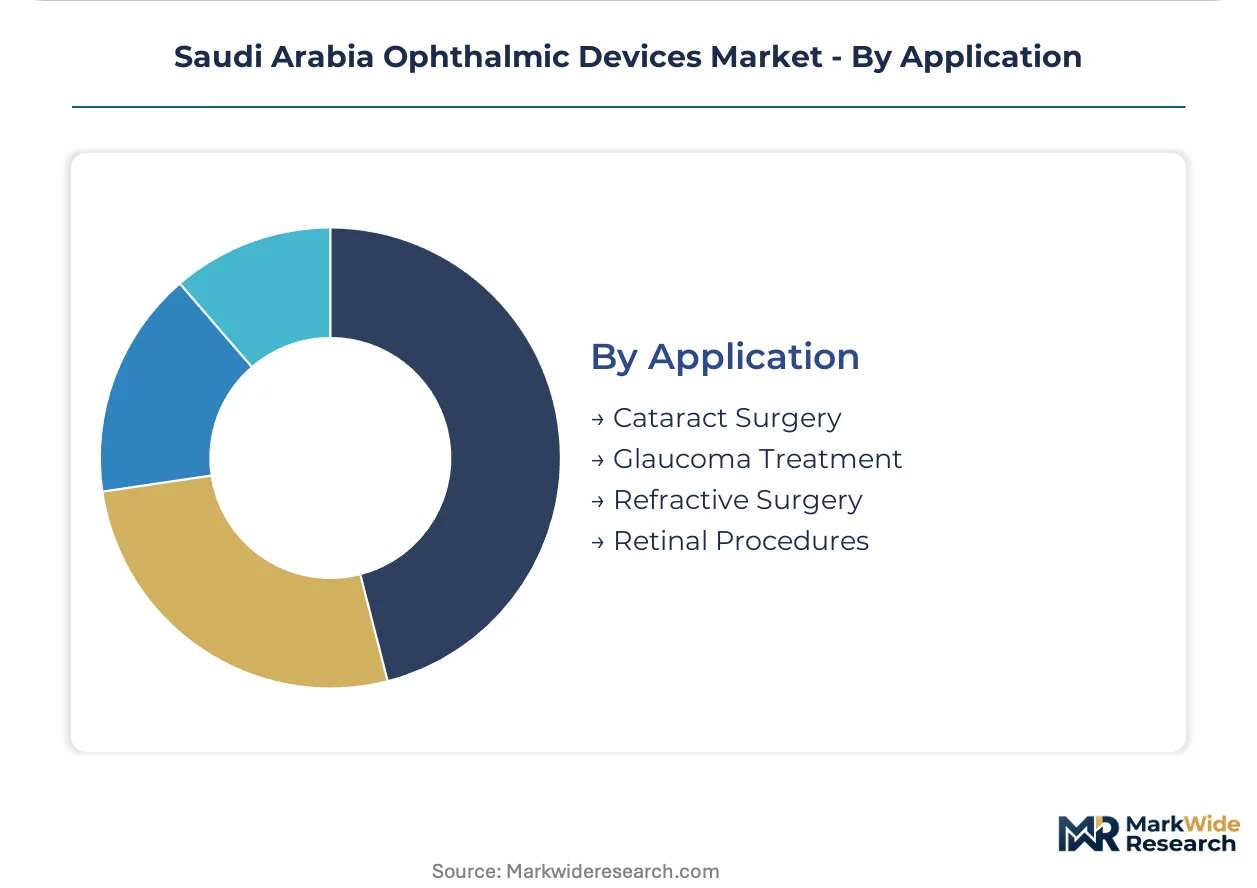
Cataract Surgery leads procedure volumes today; Glaucoma Treatment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ophthalmic device distribution in Saudi Arabia traces its modern infrastructure to the 1970s Ministry of Health hospital expansion, when Swiss and German diagnostic equipment first entered through Jeddah's port facilities. Today's procurement patterns still reflect that geographic legacy.
Riyadh
Central Province demand concentrates in Ministry of Health flagship hospitals upgrading femtosecond laser suites. SFDA health technology assessment criteria shape tender specifications for these capital acquisitions. King Faisal Specialist Hospital anchors premium procedure volumes in the capital corridor.
Jeddah
Western Region private hospital groups and independent eye clinics drive diagnostic equipment refresh cycles. The city's optical retail corridor hosts EssilorLuxottica's distribution partnerships. King Abdulaziz University Hospital manages complex surgical caseloads with direct European manufacturer procurement relationships.
Eastern Province
Dammam and Khobar surgical capacity trails Riyadh and Jeddah by approximately forty percent, creating ambulatory surgery center development opportunities. The region's petrochemical workforce generates employer-sponsored vision benefits that sustain private clinic demand. SFDA registration requirements apply uniformly but local procurement committees lack technical evaluation capacity seen in tier-one institutions.
NEOM Northwest
The giga-project's healthcare infrastructure planning incorporates tele-ophthalmology screening architectures from inception. Ministry of Investment localization incentives target manufacturing partnerships for surgical instruments and contact lens packaging. Regulatory frameworks remain under development as the zone establishes distinct SFDA coordination protocols.
Saudi Arabia Ophthalmic Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Saudi ophthalmic device sector. The market structure shows moderate consolidation at the premium surgical tier alongside fragmentation in diagnostic distribution. Three archetypes dominate: integrated surgical platform manufacturers, specialized diagnostic imaging firms, and vision care product distributors with optical retail networks. Competitive moves center on direct hospital procurement relationships that disintermediate traditional distributors, plus service-only contract transitions for maintenance-dependent laser platforms.
Among Swiss-engineered diagnostic specialists, Haag-Streit Group occupies a position exemplifying premium slit-lamp configurations for independent clinics. Alcon Inc represents the integrated surgical platform archetype with established Ministry of Health facility relationships. EssilorLuxottica SA anchors the vision care distribution tier through Riyadh and Jeddah optical retail partnerships. These three firms illustrate how geographic origin and corporate structure align with distinct market access strategies in the Kingdom.
| Leading Market Players |
|---|
| Johnson & Johnson Vision Care |
| Haag-Streit Group |
| Alcon Inc |
| Topcon Corporation |
| Nidek Co Ltd |
| Bausch Health Companies Inc |
| EssilorLuxottica SA |
| Ziemer Group AG |
| Carl Zeiss Meditec AG |
| Others |
Value Network & Pricing Analysis
Acrylic monomer spot indices from Swiss and US Gulf Coast suppliers cascade through intraocular lens manufacturing into three-tier pricing structures across premium, standard, and economy levels, with hydrophobic acrylic toric designs commanding multiples over baseline monofocal equivalents and currency hedging costs layering into landed Jeddah Islamic Port pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates femtosecond laser platforms with turnkey service contracts from refurbished phacoemulsification systems and basic diagnostic workstations. Price differentiation rests on SFDA registration tier and ISO 13485 certification status, with Class III implantable devices carrying clinical evidence premiums. Cost compression in standard-tier phaco handpiece bundles is intensifying because Ministry of Health facilities are consolidating procurement volumes. Independent eye clinics in Riyadh optical corridors show least price sensitivity for Swiss-engineered slit-lamp configurations, while Eastern Province ambulatory surgery centers prioritize capital equipment financing over upfront acquisition.
Supply Chain Analysis
Refurbished femtosecond laser platforms and certified pre-owned OCT systems flow back through distributor networks serving budget-constrained facilities in Asir and Najran regions, creating secondary market liquidity that cushions primary equipment pricing. Hydrophobic acrylic raw materials and silicone hydrogel polymer feedstocks concentrate in Swiss, US, and Japanese chemical manufacturing facilities. Supply chain risk centers on single-source dependency for femtosecond laser cavity components subject to export license variability. Distribution runs through authorized Saudi representatives with SFDA establishment licensing and in-country technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi Arabia ophthalmic devices market represents a late-cycle quality story where femtosecond laser-assisted cataract surgery and AI-enabled OCT interpretation are shifting procurement specifications toward premium platforms with validated clinical outcomes.
For Market Incumbents: Anticipate direct procurement compression from tier-one institutions like King Faisal Specialist Hospital by deepening service-only contract capabilities and securing multi-year maintenance agreements that lock out competing distributors. Backward integration into consumable handpiece manufacturing reduces disposable bundle vulnerability from single-vendor lock-in. Prioritize SFDA software-as-a-medical-device clearance for AI diagnostic modules ahead of algorithm reclassification enforcement. For New Entrants and Emerging Players: Independent ambulatory surgery centers in Dammam and Khobar offer the most penetrable buyer archetype given forty percent surgical capacity undersupply relative to Riyadh and Jeddah. Tele-ophthalmology screening deployments in rural Najran bypass specialist scarcity through mobile diagnostic units connected to centralized reading centers. A go-to-market angle through Ministry of Investment localization partnerships secures tariff exemptions and land allocations for assembly or packaging facilities meeting fifty percent local content thresholds. For Investors and Strategic Acquirers: Asymmetric upside sits with diagnostic imaging specialists possessing existing SFDA clearance for AI-enabled OCT platforms, as validation timeline extensions freeze market entry for unapproved algorithm updates. Long-term viability across the analysis window favors manufacturers with established Gulf representative offices capable of bypassing traditional distributor networks. The signal to watch is SFDA guidance document publication on software-as-a-medical-device classifications affecting diagnostic platform upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Pathway Acceleration | Early clearance for femtosecond laser platforms secures Ministry of Health tender participation before competitor submissions mature. |
| Localization Partnership Formation | Ministry of Investment manufacturing agreements unlock tariff exemptions for surgical instrument assembly meeting content thresholds. |
| Tele-ophthalmology Platform Deployment | Mobile OCT units with Riyadh-based reading center connectivity address specialist scarcity in rural Asir and Najran regions. |
| Service-Only Contract Transition | Maintenance agreements for depreciating laser platforms defend revenue as direct procurement disintermediates equipment sales. |
| AI Diagnostic Module Validation | Retrospective performance studies using Saudi demographic data satisfy SFDA software-as-a-medical-device requirements ahead of enforcement. |
Research Methodology
Coverage spans Riyadh, Jeddah, Eastern Province, and emerging NEOM Northwest corridors, with primary inputs from each region combining structured interviews with ophthalmology department heads, biomedical engineering directors, hospital procurement committee members, and SFDA regulatory affairs specialists. Secondary validation drew from SFDA medical device registration databases, Ministry of Health tender documentation, GCC harmonized technical regulation filings, and Seha EMR integration specifications. Bottom-up facility-level equipment counts triangulated against top-down import value flows through Jeddah Islamic Port customs records.
Granularity-level modeling disaggregated the Saudi Arabia ophthalmic devices market across product type, technology platform, end-user facility category, and application procedure volume throughout the forecast period. CAGRs were derived from equipment replacement cycle analysis, procedure volume elasticity to surgical workforce expansion, and premium technology adoption curves in tertiary centers. Industry-specific forecast inputs incorporated femtosecond laser platform depreciation schedules and AI-enabled diagnostic software reclassification timeline assumptions.
Inputs from SFDA registration databases and Ministry of Health procurement portals were available through the study window; gaps in private hospital group direct procurement transaction records introduce uncertainty bands around capital equipment value estimates. Forecasts reflect assumptions regarding Vision 2030 healthcare privatization pace and specialist workforce expansion timelines. Practitioners should monitor SFDA software-as-a-medical-device guidance publication and NEOM regulatory framework development for early signals affecting market access pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Implantable Port Market
Medical Devices
Global Disability Devices Market
Medical Devices
Saudi Arabia Artificial Organs and Bionic Implants Market
Medical Devices
Bare Metal Stents Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
Radiotherapy Positioning Devices Market
Medical Devices
Keratoprosthesis (Kpro) Market
Medical Devices
Pulmonary Function Testing System Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Medical Pendant Market
Medical Devices
Ligament Augmentation Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Vitrectomy Devices Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Blood Lancet Market