
 Therapeutic Catheters Market | 2026-2036
Therapeutic Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Therapeutic Catheters Market Analytics
Interventional cardiology fellowship training capacity is rotating toward structural heart and peripheral vascular pathways, expanding the physician pool capable of complex catheter-based procedures. Boston Scientific Corporation leverages its integrated manufacturing footprint to sustain balloon catheter supply security across multiple continents. Medtronic plc anchors its competitive stance through deep R&D intensity in electrophysiology ablation catheters. Abbott Laboratories differentiates via specialized positions in transcatheter mitral repair delivery systems.
Therapeutic catheters are sterile, single-use tubular devices engineered from polyurethanes, Pebax, or nylon composites with hydrophilic coatings, designed to access, dilate, drain, or deliver agents within vascular, urological, or neurological anatomies. Balloon catheters command the largest revenue pool among product types due to their ubiquity in angioplasty and valvuloplasty, while drainage catheters represent the fastest-growing segment as minimally invasive abscess and biliary interventions displace open surgical alternatives. Among delivery modes, transfemoral access dominates procedural volume, though transradial approaches gain structural share in coronary interventions due to reduced bleeding complications and same-day discharge economics.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access barriers for catheter manufacturers serving Western markets. ISO 13485 quality management systems and biocompatibility testing under ISO 10993 constitute baseline compliance infrastructure that determines supplier eligibility for hospital procurement contracts. Stakeholders must monitor evolving reimbursement coding for catheter-based procedures as payors recalibrate site-of-service policies between hospitals and ambulatory surgical centers.
Market Dynamics
Stricter FDA 510(k) premarket notification pathways for Class II devices are compressing product development timelines and forcing catheter manufacturers to front-load clinical validation investments before commercial launch.
Growth Catalysts
- EU MDR technical documentation obligations:Manufacturers achieving CE marking under the Medical Device Regulation gain preferential access to Western European hospital procurement frameworks, accelerating market penetration.
- Transradial access protocols:Interventional cardiologists adopting transradial approaches for coronary interventions drive demand for specialized catheter geometries optimized for radial artery anatomy.
- Aging demographics in the United States:Expanding Medicare-eligible populations sustain procedural volume growth for catheter-intensive cardiovascular and peripheral vascular interventions.
Market Restraints
- Nitinol and polymer feedstock volatility:Price instability in shape-memory alloys and specialized polyurethane resins compresses gross margins for balloon catheter manufacturers.
- Single-source sterilization capacity:Ethylene oxide sterilization facility concentration in the United States Midwest creates supply vulnerability for catheter distributors.
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization study backlogs at contracted laboratories extend product validation cycles by quarters.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentives for domestic catheter manufacturing attract contract manufacturing investments serving South Asian and Middle Eastern markets.
- AI-guided catheter navigation:Integration of electromagnetic tracking with machine learning algorithms enables real-time anatomical mapping during complex electrophysiology procedures.
- Same-day discharge economics:Ambulatory surgical centers adopting transcatheter peripheral interventions create channel expansion beyond traditional hospital purchasing.
Industry Challenges
- Electrophysiology fellowship pipeline constraints:Limited accredited training positions restrict the specialist physician pool capable of advanced ablation catheter procedures.
- Legacy ERP integration with UDI compliance:Hospital systems struggle to synchronize unique device identifier tracking with existing inventory management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Therapeutic Catheters Market |
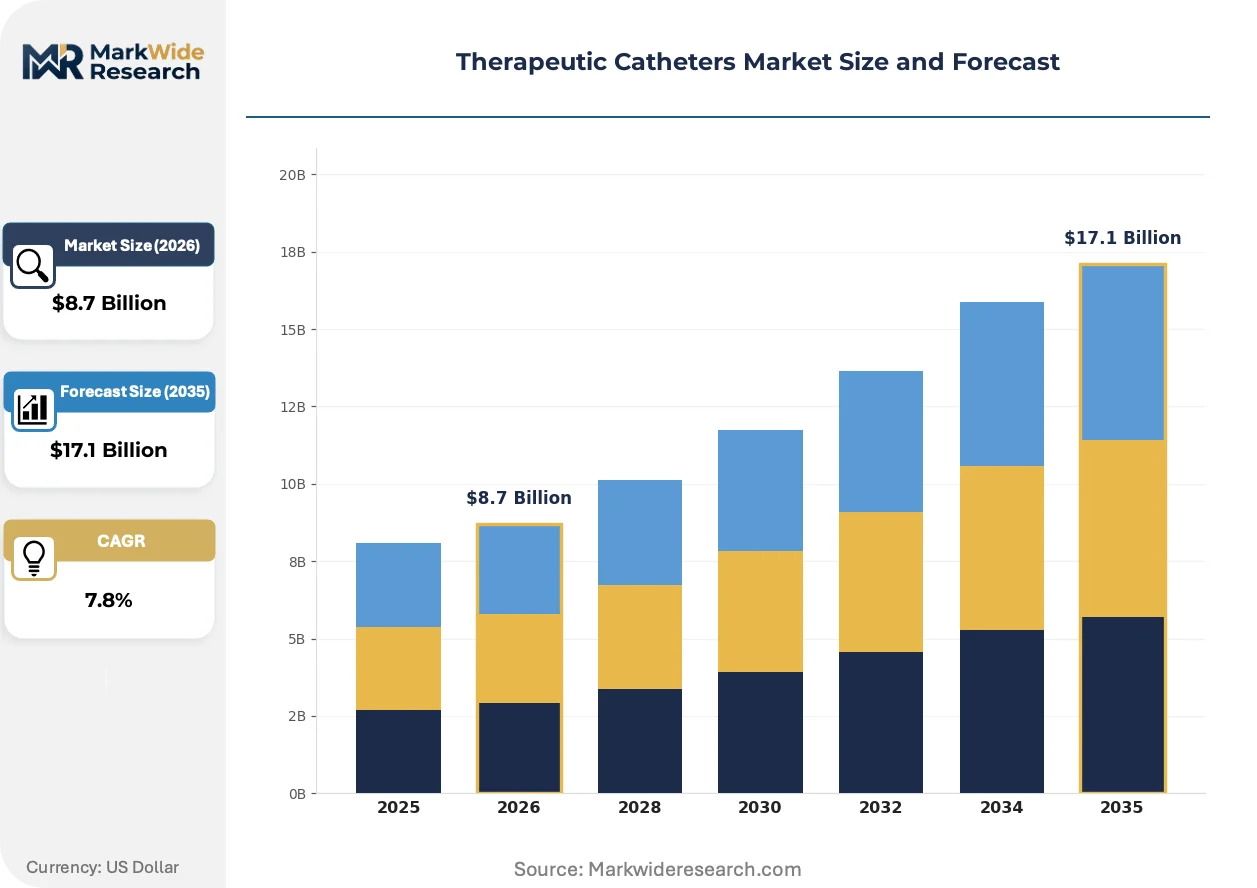
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Catheters, Drainage Catheters, Guidewires, Central Venous Catheters End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Home Healthcare Application: Cardiovascular Procedures, Urological Procedures, Gastroenterology Procedures, Neurological Treatments Delivery Mode: Transfemoral, Transradial, Percutaneous, Surgical |
| Companies Covered | Boston Scientific Corporation, Medtronic plc, Becton Dickinson and Company, Johnson & Johnson Services, Inc., Teleflex Incorporated, Abbott Laboratories, Stryker Corporation, Terumo Corporation, Edwards Lifesciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Therapeutic Catheters Market Evolving Landscape
Catheter engineering is pivoting from passive delivery conduits toward active sensing and modulation platforms, embedding pressure, temperature, and impedance feedback directly into device architecture.
Robotic catheter navigation systems are decomposing the traditional hand-manipulation skill barrier in interventional electrophysiology. Large academic medical centers in Germany and the United States are deploying magnetic-driven platforms for atrial fibrillation ablations. This technology is decomposing the historical correlation between operator case volume and procedural success rates.
Japan's PMDA has accelerated conditional approval pathways for breakthrough catheter devices, compressing the traditional Shonin review timeline for novel structural heart delivery systems. Domestic manufacturers are leveraging this regulatory velocity to trial transcatheter mitral repair platforms earlier than Western competitors. Electrophysiology catheter segments show the strongest response, with domestic firms filing premarket submissions months ahead of historical baselines.
Hospital procurement committees are consolidating supplier relationships around full-procedure bundles rather than discrete device purchasing. Cardiovascular service lines now negotiate balloon catheter, guidewire, and sheath combinations under single-source agreements. This consolidation is most visible in United States integrated delivery networks, where standardized catheter form factors reduce inventory complexity across multi-hospital systems.
Therapeutic Catheters Market Segmentation
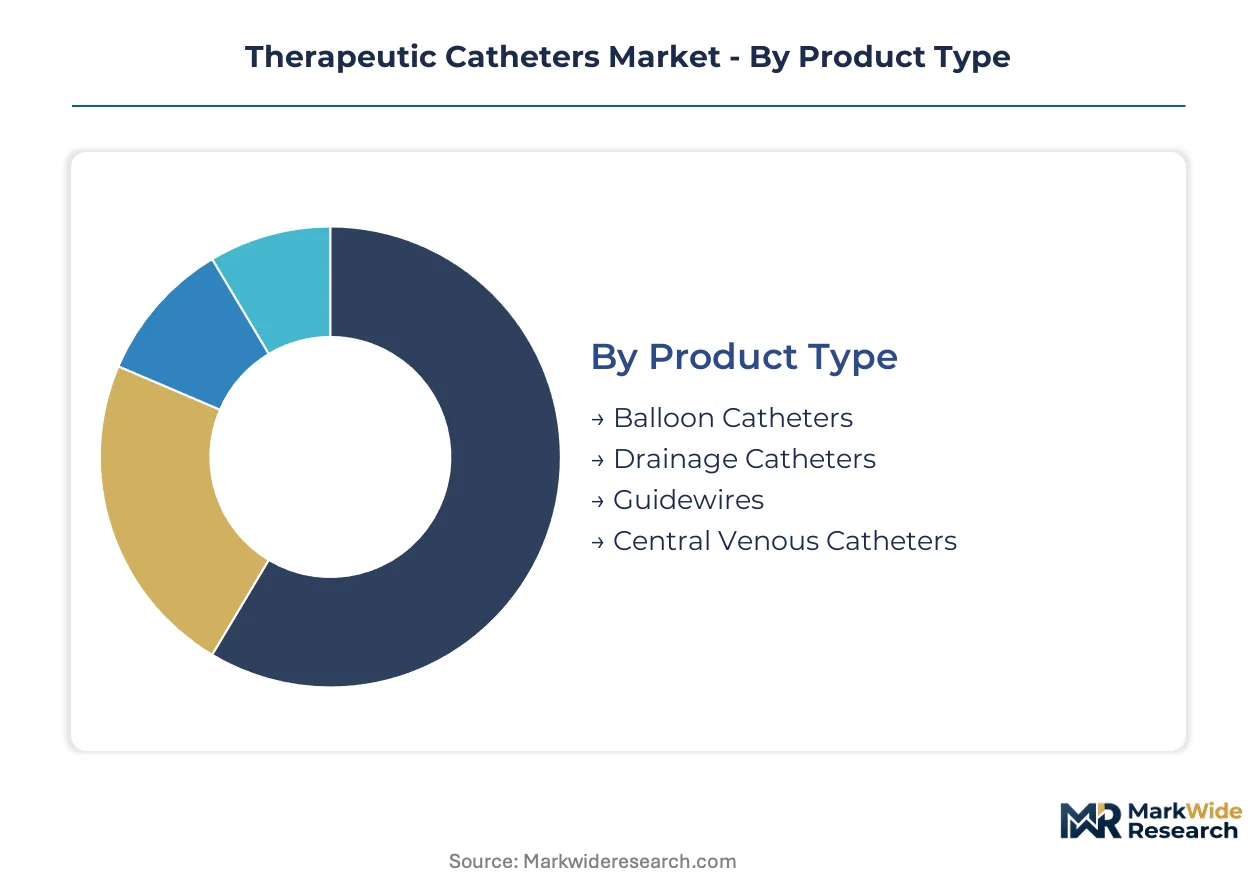
Segmentation in therapeutic catheters reveals how clinical utility, anatomical access, and care setting economics fragment purchasing authority across hospital systems. Manufacturers must align form factor engineering with procedure-specific reimbursement codes and sterilization logistics that vary by delivery mode and end-use environment.
Product Type:
Balloon catheters dominate export flows to Western European and Middle Eastern markets, while drainage catheters increasingly serve domestic hospital procurement in the United States and India.
- Balloon Catheters:Polyurethane and Pebax composite construction with hydrophilic coatings enables controlled inflation pressures for angioplasty and valvuloplasty. Demand concentrates in United States cardiovascular service lines where Medicare reimbursement for percutaneous coronary intervention sustains high-volume utilization.
- Drainage Catheters:Multi-lumen silicone or PVC designs facilitate percutaneous abscess and biliary decompression. Adoption accelerates in ambulatory surgical centers across Germany and Japan as minimally invasive alternatives displace open surgical drainage.
- Guidewires:Nitinol-core devices with hydrophilic polymer jackets navigate tortuous vascular anatomy during complex interventions.
- Central Venous Catheters:Antimicrobial-impregnated polyurethane formulations reduce bloodstream infection risk in intensive care settings.
Balloon catheters hold the largest share; momentum sits with drainage catheters.
End User:
Cost tier stratification separates capital-intensive hospital purchasing from price-sensitive home healthcare procurement, with outpatient clinics occupying a mid-tier reimbursement position.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements covering catheter bundles across cardiovascular, electrophysiology, and interventional radiology service lines. FDA 510(k) clearance history and ISO 13485 certification determine supplier eligibility for these contracts.
- Outpatient Clinics:Freestanding interventional cardiology and urology practices purchase procedure-specific catheter inventories with shorter replenishment cycles.
- Ambulatory Surgical Centers:Medicare site-of-service payment differentials drive transcatheter peripheral intervention migration to these lower-cost settings.
- Home Healthcare:Indwelling urinary and peripherally inserted central catheter demand reflects chronic disease management outside institutional settings.
Hospitals anchor procurement volume; ambulatory surgical centers are climbing the fastest.
Application:
Volume concentration in cardiovascular procedures reflects aging demographics, while neurological applications command premium pricing due to catheter precision requirements.
- Cardiovascular Procedures:Coronary angioplasty, structural heart interventions, and peripheral vascular revascularization consume the majority of balloon and guiding catheter production. United States procedural growth aligns with expanding Medicare-eligible populations and transradial access protocol adoption.
- Urological Procedures:Nephrostomy, ureteral stenting, and suprapubic catheterization address obstructive uropathy and malignancy-related drainage needs.
- Gastroenterology Procedures:Biliary drainage and percutaneous endoscopic gastrostomy tube placement serve malignant and benign luminal obstruction.
- Neurological Treatments:Flow-directed microcatheters enable aneurysm coiling and arteriovenous malformation embolization with sub-millimeter navigational precision.
Cardiovascular procedures retain dominant share; neurological treatments follow the steepest expansion trajectory.
Delivery Mode:
Customer type differentiation separates high-volume transfemoral standard-of-care from emerging transradial protocols favored by patient safety advocates and same-day discharge programs.
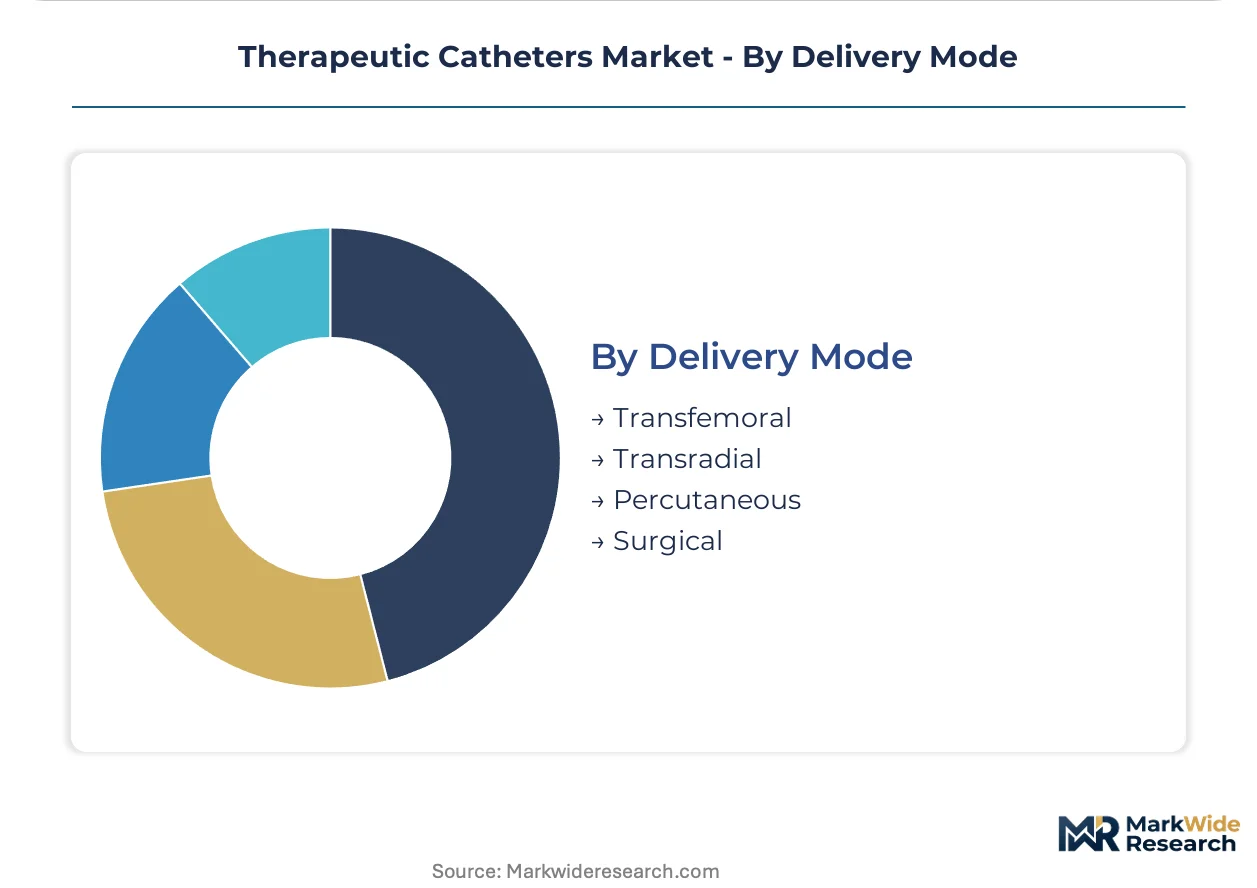
- Transfemoral:Femoral artery access remains the default approach for complex structural heart interventions requiring large-bore sheath compatibility. European and United States teaching hospitals maintain the highest procedural volumes for transcatheter aortic valve replacement via this route.
- Transradial:Radial artery cannulation reduces access-site bleeding and enables ambulatory discharge protocols in coronary diagnostic and interventional procedures. Japanese interventional cardiologists pioneered technique standardization now spreading through German and United States practice networks.
- Percutaneous:Image-guided access without surgical cutdown serves drainage and biopsy applications across multiple anatomical targets.
- Surgical:Open surgical exposure accompanies catheter placement in complex congenital heart disease and select neurosurgical shunt procedures.
Transfemoral access commands current volume; transradial approaches gain structural share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) premarket notification pathways for Class II devices anchor the United States as the procedural volume leader, while EU MDR technical documentation obligations reshape competitive access across Western Europe. Japan's PMDA accelerated conditional approval pathways compress review timelines for breakthrough catheter platforms.
United States
Medicare-eligible population expansion and transradial access protocol adoption drive cardiovascular procedural growth. FDA 510(k) clearance requirements compress product development timelines for catheter manufacturers. Minneapolis and Boston anchor electrophysiology and structural heart catheter development clusters.
Germany
Interventional cardiology fellowship training capacity expansion and integrated delivery network procurement consolidation sustain demand. EU MDR CE marking obligations determine supplier eligibility for hospital frameworks. Heidelberg and Munich academic medical centers deploy robotic catheter navigation systems for atrial fibrillation ablations.
Japan
PMDA accelerated conditional approval pathways enable earlier trial initiation for transcatheter mitral repair platforms. Domestic manufacturers file premarket submissions months ahead of historical baselines. Tokyo and Osaka electrophysiology catheter segments show strongest regulatory response velocity.
India
Production-linked incentive schemes for medical devices attract contract manufacturing investments serving South Asian markets. CDSCO medical device registration requirements shape import substitution strategies. Gujarat and Karnataka industrial corridors concentrate domestic catheter manufacturing capacity expansion.
United Kingdom
NHS procurement frameworks prioritize ISO 13485-certified suppliers with established CE marking histories. MHRA post-Brexit regulatory alignment creates transitional compliance complexity for catheter distributors. London and Cambridge medtech clusters focus on AI-guided catheter navigation algorithm development.
Therapeutic Catheters Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the therapeutic catheters market. Integrated multinational conglomerates with diversified cardiovascular portfolios occupy premium-tier positions, while specialized electrophysiology and drainage catheter firms compete on procedural-specific innovation. Mid-scale regional manufacturers exploit India's PLI scheme to capture South Asian price-sensitive demand. Dominant competitive moves include backward integration into nitinol and polymer feedstock supply, and strategic partnerships with academic medical centers for robotic navigation platform validation.
Among diversified cardiovascular conglomerates, Boston Scientific Corporation and Medtronic plc occupy positions exemplifying integrated manufacturing and deep R&D intensity archetypes respectively. Abbott Laboratories represents specialized structural heart delivery system positioning. These three anchors demonstrate how geographic footprint breadth and procedural focus depth constitute alternative competitive vectors.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic plc |
| Becton Dickinson and Company |
| Johnson & Johnson Services, Inc. |
| Teleflex Incorporated |
| Abbott Laboratories |
| Stryker Corporation |
| Terumo Corporation |
| Edwards Lifesciences Corporation |
| Others |
Value Network & Pricing Analysis
Multi-year supply agreements between integrated delivery networks and catheter manufacturers lock in both nitinol and polymer feedstock access and cost predictability across volatile commodity cycles. These contracts embed FDA 510(k) clearance history and ISO 13485 certification as non-negotiable eligibility gates, concentrating pricing power with incumbent suppliers possessing established regulatory dossiers.
Pricing Analysis
Transatlantic price spreads of 15-30% separate United States hospital procurement from Western European tenders, reflecting divergent reimbursement coding and site-of-service economics. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance tier and clinical validation depth, with balloon catheters commanding top-tier positioning due to procedural volume concentration. Pricing pressure stems from Medicare site-of-service payment compression favoring ambulatory surgical centers over traditional hospitals. Home healthcare channels exhibit highest price sensitivity, while cardiovascular service lines in academic medical centers prioritize performance metrics over unit cost.
Supply Chain Analysis
Strategic stockpiling of ethylene oxide-sterilized catheter inventories dominates hospital procurement strategy, buffering against single-source sterilization facility concentration in the United States Midwest. Manufacturing capacity concentrates in United States, Germany, and Japan, with India emerging as a contract manufacturing hub serving South Asian price tiers. Nitinol shape-memory alloys, specialized polyurethane resins, and hydrophilic coating chemistries constitute critical input dependencies. Single-source sterilization vulnerability represents the primary structural risk, with distribution running through GPO-mediated hospital procurement frameworks and direct-to-ASC channel expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story anchored in regulatory entrenchment. FDA 510(k) clearance pathways and EU MDR technical documentation obligations create years-long validation barriers that protect incumbent positions from rapid competitive displacement.
For Market Incumbents: Compound defensive positioning through backward integration into nitinol and polymer feedstock supply, insulating margin structures from commodity volatility. Prioritize capacity addition in India's PLI-subsidized manufacturing corridors to capture South Asian and Middle Eastern demand at lower cost positions. Channel control through exclusive GPO contracts represents the critical lever against emerging regional manufacturers. For New Entrants and Emerging Players: Lead with AI-guided catheter navigation platforms targeting electrophysiology segments where robotic deployment decomposes historical operator-volume correlations. India's domestic hospital procurement frameworks offer the most penetrable geography, with CDSCO registration requirements less stringent than FDA pathways. Reimbursement strategy alignment with Medicare site-of-service differentials enables ambulatory surgical center channel entry. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electrophysiology catheter specialists with installed-base consumable pull-through. Long-term viability across the analysis window favors manufacturers with dual FDA-CE marking capabilities and established academic medical center validation partnerships. Watch for PMDA accelerated approval pathway utilization as an inflection indicator for breakthrough device velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation unlocks Western European hospital procurement frameworks. |
| Hospital System Partnership | Integrated delivery network bundle agreements secure multi-year catheter volume commitments. |
| Software Companion Development | AI-guided navigation algorithms differentiate electrophysiology platforms in academic centers. |
| Reimbursement Strategy | Medicare site-of-service coding alignment enables ambulatory surgical center channel expansion. |
| FDA Submission | 510(k) clearance history determines supplier eligibility for United States GPO contracts. |
Research Methodology
The analysis maps balloon catheter, drainage catheter, guidewire, and central venous catheter sub-sectors, each validated through interventional cardiologists, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation ensured cross-verification across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, end user, application, and delivery mode segmentation dimensions. CAGRs derived from procedure volume elasticity to demographic shifts and reimbursement policy trajectories. Forecast inputs incorporated transradial access protocol adoption curves, robotic navigation platform deployment rates, and sterilization capacity expansion timelines.
Forecasts assume regulatory continuity in FDA 510(k), EU MDR, and PMDA regimes; material policy shifts would require re-modeling. Specific risk factors include ethylene oxide sterilization facility disruptions, nitinol feedstock price volatility, and electrophysiology fellowship pipeline constraints. Revision becomes warranted when transradial procedural share crosses thresholds that fundamentally alter catheter geometry demand profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Breast Lesion Localization Market
Diagnostic and Therapeutic Devices
Smart Inhalers Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market
Diagnostic and Therapeutic Devices
RF Microneedling Market
Diagnostic and Therapeutic Devices
Therapeutic Apheresis Market
Diagnostic and Therapeutic Devices
Crohn's Disease Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Therapeutic Support Surface Market
Diagnostic and Therapeutic Devices
Intracranial Hemorrhage Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Pelvic Congestion Syndrome Treatment Market
Diagnostic and Therapeutic Devices
Therapeutic Robots Market