
 Atrial Appendage Occluder Market | 2026-2036
Atrial Appendage Occluder Market Size, Share, and Industry Trends Forecast 2026-2036
Atrial Appendage Occluder Market Analysis
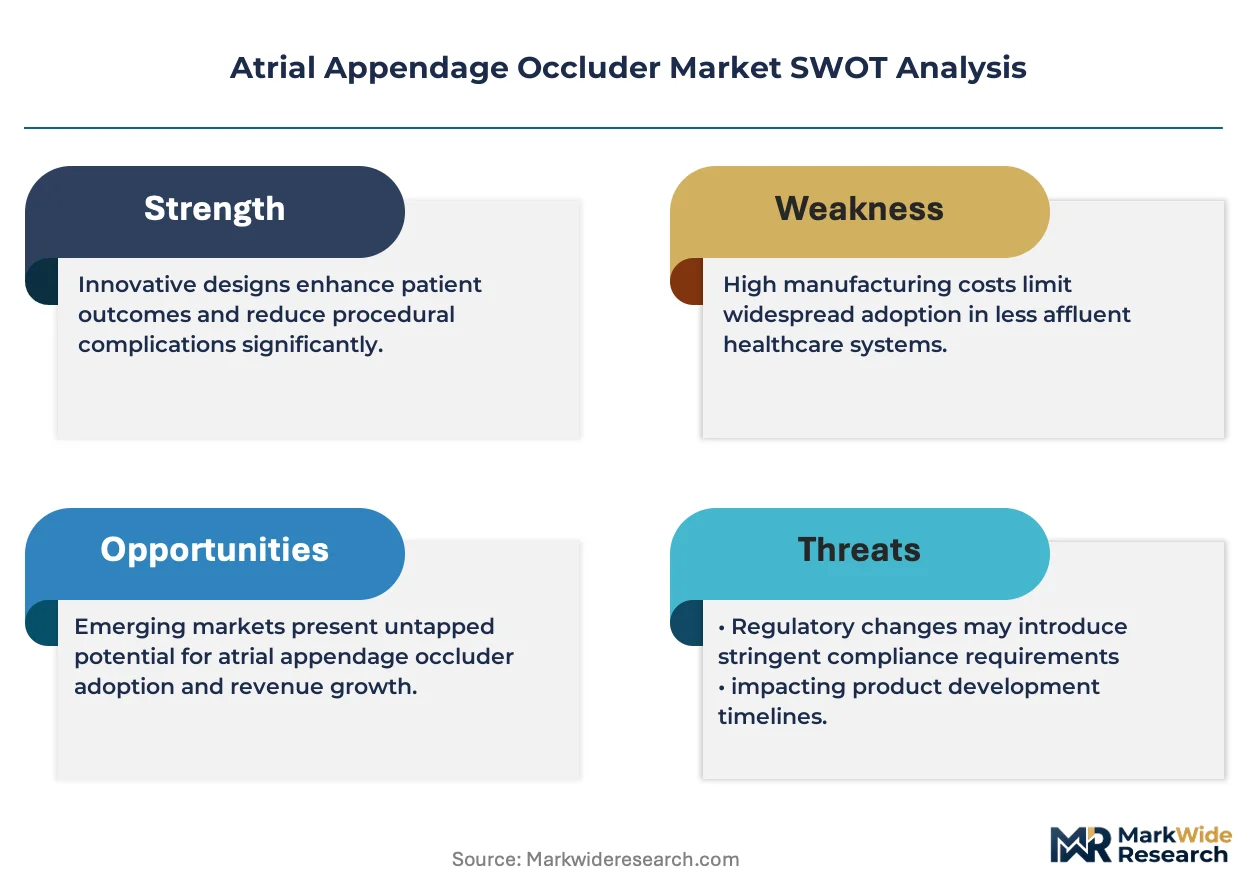
A shortage of interventional electrophysiologists trained in transseptal puncture techniques is redrawing competitive dynamics across the atrial appendage occluder landscape. Boston Scientific Corporation leverages its Watchman device portfolio and proprietary closure technology to sustain leadership in North American hospital systems. Abbott Laboratories anchors its position through integrated imaging guidance platforms that streamline implant workflows. AtriCure specializes in hybrid surgical-catheter approaches that differentiate its offering for complex anatomies.
An atrial appendage occluder is a permanently or temporarily implanted device designed to seal the left atrial appendage, a trabeculated muscular pouch where thrombus formation commonly occurs in patients with non-valvular atrial fibrillation; most commercial devices employ nitinol frames with permeable polyester fabric membranes delivered via 8-14 French transseptal sheaths. The primary purpose is stroke prevention without the bleeding risks associated with chronic oral anticoagulation. Product type segmentation reveals Watchman and Amulet platforms commanding established reimbursement codes, while mechanical technology leads volume due to proven long-term sealing performance and extensive clinical trial evidence. Bio-absorbable technology represents the fastest-growing segment as manufacturers seek to eliminate late-term device-related thrombosis risks and enable complete endothelialization without permanent foreign material.
The FDA maintains stringent premarket approval requirements through its Office of Cardiovascular Devices, while the EU Medical Device Regulation imposes enhanced clinical evidence standards through notified body conformity assessments. These frameworks shape demand by mandating rigorous follow-up protocols that favor devices with robust long-term safety databases. Stakeholders must monitor evolving anticoagulation pharmacotherapy advances and their impact on procedural volumes, as next-generation oral agents could alter the risk-benefit calculus for invasive closure strategies.
Market Dynamics
The left atrial appendage occluder market is restructuring around catheter-based stroke prevention as anticoagulation pharmacotherapy faces bleeding-risk limitations. Device manufacturers compete on transseptal delivery precision, imaging integration, and long-term thrombosis-free performance data.
Growth Catalysts
- EU MDR clinical evidence standards:Enhanced post-market surveillance requirements favor devices with established safety databases, accelerating consolidation around proven nitinol-frame platforms.
- Cardiac center expansion:United States hospital systems are building dedicated electrophysiology labs to capture high-margin structural heart procedures.
- Bio-absorbable material innovation:Magnesium-alloy and polymer scaffolds that fully endothelialize eliminate late-term device-related thrombosis risks.
Market Restraints
- Nitinol supply concentration:Shape-memory alloy production concentrates in specialized German and Japanese metallurgical facilities, exposing device makers to input volatility.
- FDA premarket approval timelines:The Office of Cardiovascular Devices mandates extended follow-up protocols that delay commercialization by 18-24 months versus EU pathways.
- Direct oral anticoagulant substitution:Next-generation factor Xa inhibitors with improved bleeding profiles threaten procedural volumes for mechanical closure.
Strategic Opportunities
- India's CDSCO fast-track pathway:The country's national pharmaceutical regulator offers accelerated review for devices addressing unmet stroke prevention needs in atrial fibrillation patients.
- Hybrid surgical-catheter suites:Convergence of thoracoscopic access with transseptal delivery opens complex anatomies previously excluded from percutaneous closure.
- Japan's geriatric reimbursement expansion:METI-aligned coverage policies now include catheter-based interventions for patients over 75 with elevated CHA₂DS₂-VASc scores.
Industry Challenges
- Transseptal puncture skill scarcity:Interventional electrophysiologists capable of safe septal crossing number fewer than 3,000 across OECD markets, creating procedural bottlenecks.
- ISO 13485 certification complexity:Quality management system audits for active implantable devices require 12-18 month preparation cycles that strain mid-cap engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atrial Appendage Occluder Market |
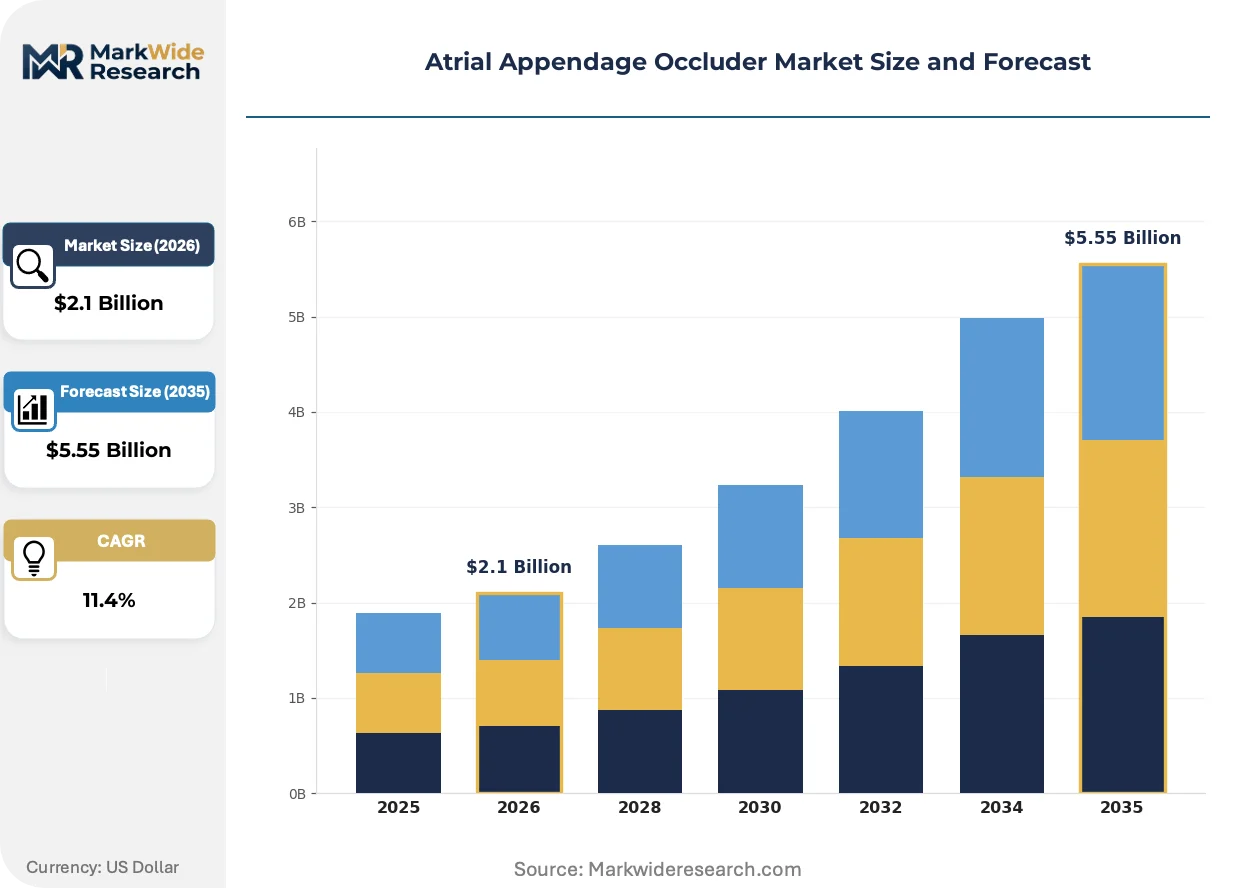
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Watchman, Amulet, WaveCrest, Lifetech End User: Hospitals, Cardiac Centers, Specialty Clinics, Research Institutions Delivery Mode: Transfemoral, Transseptal, Surgical, Hybrid Technology: Mechanical, Bio-absorbable, Polymer-based, Device-assisted |
| Companies Covered | Boston Scientific Corporation, Abbott Laboratories, AtriCure, Inc., Johnson & Johnson, Occlutech, Lifetech Scientific, Lepu Medical Technology, Cardia, Inc., SentreHEART, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atrial Appendage Occluder Market Emerging Trajectories
Catheter-delivered left atrial appendage closure is evolving through three concurrent vectors: device miniaturization, regulatory harmonization pressures, and shifting site-of-care economics. Each vector reconfigures competitive positioning without altering the fundamental stroke-prevention value proposition.
Next-generation occluder designs are miniaturizing delivery sheaths from 14 French to 8-10 French profiles. Academic medical centers in Germany and the United States are piloting these platforms for same-day discharge protocols. The structural compression of procedural footprint is enabling migration from catheterization laboratories to ambulatory surgical centers.
The EU Medical Device Regulation is enforcing enhanced clinical evidence standards through notified body conformity assessments. Manufacturers must now submit 5-year post-implant safety data for CE marking renewal. High-volume mechanical occluder portfolios with established registries absorb these compliance costs more efficiently than emerging bio-absorbable entrants.
Hospital procurement committees are unbundling device pricing from imaging and follow-up services. United States integrated delivery networks now negotiate device-only contracts while retaining internal echo-cardiography capacity. This purchasing pattern shift concentrates volume with vendors offering transparent single-use pricing rather than bundled procedural packages.
Atrial Appendage Occluder Market Segmentation
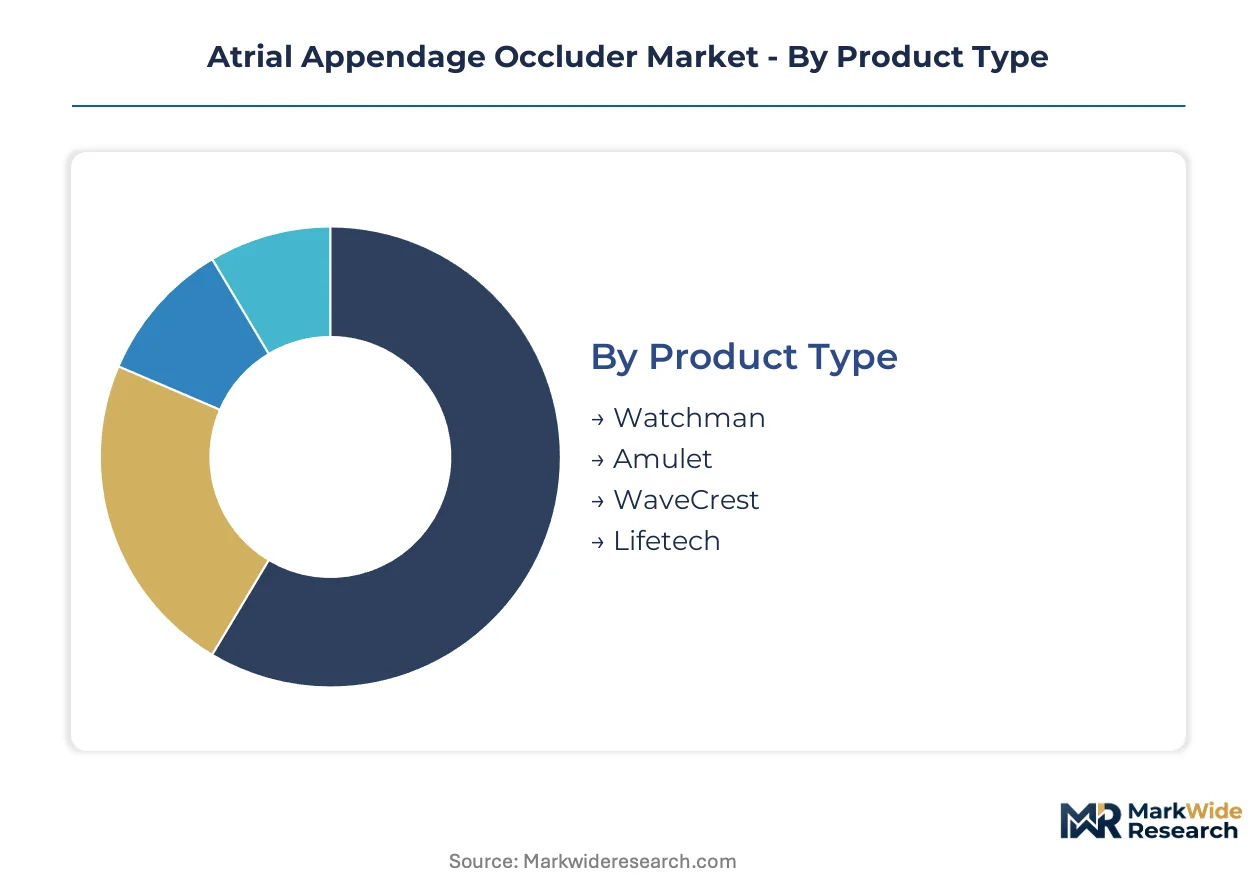
Device-level segmentation in atrial appendage closure reveals how technical specifications, delivery complexity, and reimbursement pathways fragment purchasing authority across hospital systems. Each dimension carries distinct regulatory, training, and supply chain implications that reshape competitive positioning.
Product Type:
Domestic demand concentrates on platforms with established FDA premarket approval and dedicated reimbursement codes, while export-led growth targets emerging markets seeking proven safety databases.
- Watchman:Nitinol-frame construction with permeable polyester fabric membrane delivered via 14 French transseptal sheath. Demand concentrates in United States integrated delivery networks where Boston Scientific holds exclusive contracts and physician training infrastructure. Reimbursement stability under Medicare DRG codes sustains procedural volumes.
- Amulet:Dual-seal design with proximal and distal lobes accommodating variable appendage anatomies. European cardiac centers in Germany and France drive adoption where Abbott's imaging integration platforms streamline implant workflows and reduce fluoroscopy time.
- WaveCrest:Fully percutaneous retrieval capability without surgical backup requirements. Compact frame suits smaller appendage morphologies prevalent in Asian patient populations.
- Lifetech:Regional manufacturing base in China supports cost-competitive positioning for price-sensitive hospital procurement committees across Southeast Asia.
Watchman holds the largest share; momentum sits with Amulet as dual-seal designs gain preference for complex anatomies.
End User:
Cost-tier stratification separates high-complexity academic centers from community hospitals and outpatient facilities seeking streamlined workflows.
- Hospitals:Comprehensive catheterization laboratories with onsite cardiac surgery backup for procedural complications. United States tertiary centers absorb the majority of Watchman and Amulet volumes through bundled payment arrangements.
- Cardiac Centers:Dedicated electrophysiology facilities with specialized interventional staff. Germany's reimbursement structures favor these settings for catheter-based interventions in atrial fibrillation patients with elevated stroke risk.
- Specialty Clinics:Outpatient-focused models pursuing same-day discharge protocols with miniaturized 8-10 French delivery systems.
- Research Institutions:Clinical trial sites generating 5-year post-implant safety data required for EU MDR CE marking renewal and FDA premarket approval supplements.
Hospitals dominate current volume; specialty clinics represent the steepest expansion trajectory as site-of-care economics shift toward ambulatory settings.
Delivery Mode:
Application-specific constraints dictate access route selection, with anatomical complexity and operator skill availability determining feasibility.
- Transfemoral:Standard percutaneous access through femoral vein with transseptal puncture to reach left atrium. United States hospital systems default to this approach for the majority of elective procedures given established training pathways.
- Transseptal:Direct septal crossing techniques requiring specialized electrophysiology expertise. Scarce interventionalist capacity across OECD markets creates procedural bottlenecks and waitlist accumulation.
- Surgical:Thoracoscopic or sternotomy-based exclusion for appendages unsuitable for percutaneous closure. Reserved for concomitant cardiac surgery cases.
- Hybrid:Convergence of surgical access with catheter-based device delivery. AtriCure specializes in this approach for complex anatomies previously excluded from standalone percutaneous closure.
Transfemoral access commands the largest share; hybrid delivery is climbing the fastest as combined surgical-catheter suites expand capability boundaries.
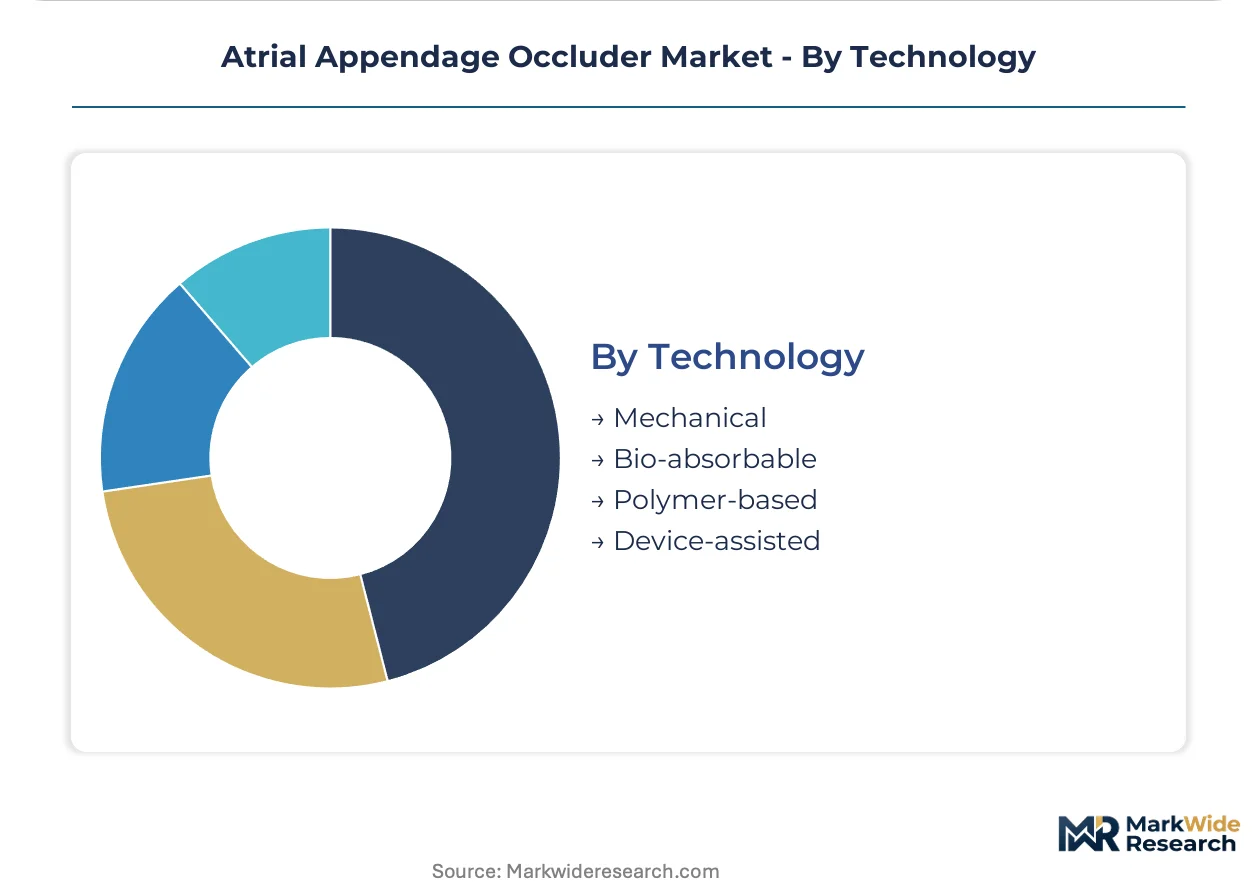
Technology:
Maturity gradients separate proven mechanical platforms from emerging bio-absorbable innovations seeking to eliminate late-term device-related thrombosis.
- Mechanical:Nitinol-frame devices with polyester fabric membranes representing the commercial standard. Extensive clinical trial evidence supports long-term sealing performance and established regulatory pathways across FDA and EU MDR frameworks.
- Bio-absorbable:Magnesium-alloy and polymer scaffolds designed for complete endothelialization without permanent foreign material. Academic medical centers in Germany and the United States pilot these platforms to address late-term thrombosis risks.
- Polymer-based:Synthetic material alternatives to metal frames with modified degradation profiles.
- Device-assisted:Integrated imaging guidance and delivery precision technologies streamlining implant workflows and reducing radiation exposure.
Mechanical technology retains the largest share; bio-absorbable platforms are gaining share fastest as manufacturers pursue elimination of permanent implant complications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States cardiac centers deploy catheter-based closure as first-line stroke prevention for anticoagulation-ineligible patients, while German reimbursement structures favor these interventions across broader atrial fibrillation populations. Japan's geriatric coverage expansion and India's fast-track regulatory pathway create divergent demand profiles across major markets.
United States
Integrated delivery networks in Texas, Florida, and California are building dedicated electrophysiology labs to capture high-margin structural heart procedures. FDA premarket approval pathways through the Office of Cardiovascular Devices mandate rigorous follow-up protocols that favor devices with established safety databases. The Cleveland Clinic and Mayo Clinic anchor clinical trial networks generating long-term performance data required for Medicare reimbursement stability.
Germany
Cardiac centers in Bavaria and North Rhine-Westphalia drive procedural volumes where statutory health insurance reimburses catheter-based interventions for elevated CHA₂DS₂-VASc scores. EU Medical Device Regulation enforces enhanced clinical evidence standards through notified body conformity assessments that favor proven nitinol-frame platforms. Berlin and Heidelberg academic medical centers pilot bio-absorbable magnesium-alloy scaffolds addressing late-term thrombosis risks.
Japan
METI-aligned coverage policies now include left atrial appendage closure for patients over 75 with elevated stroke risk, expanding addressable populations beyond prior restrictions. PMDA regulatory frameworks require 5-year post-implant safety data for device approval renewals. Tokyo and Osaka cardiac centers concentrate interventional electrophysiologist training capacity for transseptal puncture techniques.
India
CDSCO fast-track pathways accelerate review for devices addressing unmet stroke prevention needs in atrial fibrillation patients with limited anticoagulation access. Maharashtra and Karnataka hospital systems are expanding catheterization laboratory infrastructure to serve growing middle-class demand. Mumbai and Bangalore medical device clusters support regional manufacturing bases for cost-competitive positioning across Southeast Asian export markets.
China
NMPA regulatory frameworks are harmonizing with international standards while maintaining domestic manufacturing preference through volume-based procurement. Shanghai and Beijing cardiac centers concentrate physician training for transseptal delivery techniques. Shenzhen and Suzhou industrial clusters host nitinol-frame device production serving price-sensitive hospital procurement committees across provincial health systems.
Atrial Appendage Occluder Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the atrial appendage occluder landscape. The upper tier commands hospital system contracts through bundled procedural packages and dedicated physician training infrastructure. Mid-cap specialists compete on imaging integration, delivery precision, and bio-absorbable material innovation. Dominant competitive moves include strategic partnerships with academic medical centers for clinical trial enrollment and geographic expansion into fast-track regulatory jurisdictions.
Among US-based diversified medical technology corporations, Boston Scientific Corporation and Abbott Laboratories occupy positions exemplifying the integrated leader archetype through established reimbursement codes and proprietary closure platforms. AtriCure, Inc. represents the hybrid surgical-catheter specialist tier, differentiating through combined thoracoscopic and transseptal approaches for complex anatomies previously excluded from standalone percutaneous closure.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Abbott Laboratories |
| AtriCure, Inc. |
| Johnson & Johnson |
| Occlutech |
| Lifetech Scientific |
| Lepu Medical Technology |
| Cardia, Inc. |
| SentreHEART, Inc. |
| Others |
Supply Flow & Price Mechanics
Bio-absorbable magnesium-alloy scaffolds displacing nitinol-frame platforms are redrawing supply geography toward German metallurgical facilities and polymer research clusters while compressing premium pricing tiers previously sustained by permanent implant differentiation. This substitution dynamic concentrates procurement leverage with academic medical centers piloting endothelialization-first protocols.
Pricing Analysis
Long-term offtake agreements between United States integrated delivery networks and established device manufacturers anchor pricing stability, while spot purchasing for emerging bio-absorbable platforms commands 15-25% premiums reflecting limited manufacturing scale. Price differentiation hinges on FDA premarket approval tier and bundled procedural service inclusion, with Medicare DRG-reimbursed hospitals exhibiting lowest sensitivity and Southeast Asian procurement committees demonstrating acute price responsiveness to volume discounts.
Supply Chain Analysis
Inventory lead times for nitinol shape-memory alloy extend 16-24 weeks due to concentrated production in German and Japanese metallurgical facilities, creating procedural scheduling constraints for high-volume cardiac centers. Raw material dependencies center on nickel-titanium feedstock, polyester fabric membranes, and magnesium-alloy precursors, with tariff exposure on Chinese-sourced polymer components representing the primary structural vulnerability. Distribution runs through GPO-negotiated contracts for tier-one hospitals and regional distributor networks for emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The atrial appendage occluder market is cycling through a post-pandemic procedural volume recovery as deferred elective interventions return to catheterization laboratory schedules across OECD health systems.
For Market Incumbents: Consolidate physician training infrastructure around transseptal puncture technique certification to lock out emerging competitors lacking interventional electrophysiologist relationships. Acquire bio-absorbable material specialists in Germany and United States research clusters before EU MDR clinical evidence requirements harden competitive moats around established safety databases. For New Entrants and Emerging Players: Lead with India's CDSCO fast-track pathway and Southeast Asian price-sensitive hospital procurement committees where cost-competitive positioning outweighs brand loyalty. Target specialty clinic same-day discharge protocols with miniaturized 8-10 French delivery systems as the most penetrable white-space segment bypassing incumbent bundled contracts. For Investors and Strategic Acquirers: EU MDR 5-year post-implant surveillance renewal requirements reshape the acquisition landscape toward mechanical occluder portfolios with established registries that absorb compliance costs more efficiently than development-stage bio-absorbable entrants. Monitor PMDA coverage expansion signals in Japan's geriatric reimbursement policies as the inflection indicator for Asian market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment unlocks statutory health insurance reimbursement across German cardiac centers. |
| Hospital System Partnership | Exclusive device contracts with United States integrated delivery networks secure procedural volume commitments. |
| Reimbursement Strategy | Medicare DRG code stability determines Watchman and Amulet platform adoption in tertiary centers. |
| FDA Submission | Premarket approval through Office of Cardiovascular Devices mandates extended follow-up protocols favoring established players. |
| Software Companion Development | Integrated imaging guidance platforms reduce fluoroscopy time and differentiate Abbott's implant workflows. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with interventional electrophysiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers, cross-referenced against FDA 510(k) and PMA filings, EU MDR notified body assessments, CMS Medicare reimbursement databases, and hospital procurement records, with bottom-up procedural volume estimates triangulated against top-down market sizing.
Across the analysis window, the forecasting framework models device-level segmentation by product type, end-user facility tier, delivery mode complexity, and technology maturity gradient, with CAGRs derived from procedure volume trajectories and ASP evolution patterns, incorporating anticoagulation pharmacotherapy substitution risk and interventionalist training pipeline constraints as scenario-weighted inputs.
The analysis sits within stated boundaries; outcomes outside sustained Medicare reimbursement stability, nitinol supply continuity, and EU MDR compliance cost absorption would require recalibration. Forecasts reflect documented assumptions regarding procedural adoption curves and regulatory pathway timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
China Respiratory Devices Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Europe Sternal Closure Systems Market
Medical Devices
Asthma Spacers Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Urethral Bulking System Market
Medical Devices
Global Medical Footwear Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
China Ophthalmic Devices Market
Medical Devices
Global Sternal Closure Systems Market
Medical Devices
Tinnitus Maskers Market
Medical Devices
Global Thermoelectric Devices in Medical and Laboratory Offering Market
Medical Devices
Nephrostomy Catheters Market