
 Tinnitus Maskers Market | 2026-2036
Tinnitus Maskers Market Size, Share, and Industry Trends Forecast 2026-2036
Tinnitus Maskers Market Analytics
The EU Medical Device Regulation (MDR) is shifting compliance burdens for sound therapy devices marketed as therapeutic interventions rather than wellness products. Starkey Hearing leverages its vertically integrated manufacturing in the United States to sustain cost advantages in custom-molded masker production. Widex differentiates through proprietary fractal tone algorithms that anchor its premium positioning in audiologist-dispensed channels.
A tinnitus masker is an electronic sound-generating device that produces broadband or narrowband acoustic stimuli at calibrated output levels typically between 0 and 90 dB SPL to perceptually suppress or distract from phantom auditory sensations. These devices serve primarily to reduce perceived tinnitus loudness and improve patient-reported quality of life metrics in chronic cases. Hearing aids with integrated masking functions dominate value generation due to dual-purpose reimbursement eligibility and higher average selling prices, while wearable maskers represent the fastest-expanding category as consumer electronics manufacturers enter with Bluetooth-enabled form factors. Sound therapy devices occupy a mature niche in clinical settings where audiologists program customized stimulus protocols.
The FDA regulates combination hearing aid-tinnitus masker devices under 21 CFR 874.3300, requiring premarket notification for devices exceeding specified output limits, while the EU MDR mandates notified body involvement for Class IIa therapeutic sound generators. Health Canada and the TGA in Australia maintain parallel classification frameworks that influence multinational registration strategies. Stakeholders must monitor whether emerging software-based masker applications trigger medical device reclassification in major jurisdictions.
Market Dynamics
The FDA's over-the-counter hearing aid regulations are compressing device classification pathways, forcing combined hearing aid-masker manufacturers to recalibrate regulatory submission strategies and pricing architectures simultaneously.
Growth Catalysts
- Veterans Affairs Expansion:United States VA healthcare systems are scaling tinnitus management programs for service-connected disability claims, creating institutional procurement pipelines for programmable masker devices.
- EU MDR Therapeutic Reclassification:The Medical Device Regulation is shifting compliance burdens for sound therapy devices marketed as clinical interventions rather than wellness products, elevating barrier credibility for certified manufacturers.
- Bluetooth Low Energy Integration:Wearable maskers incorporating wireless audio streaming are capturing consumer electronics channels previously inaccessible to medical device distributors.
Market Restraints
- Semiconductor Component Volatility:MEMS microphone and DSP chip supply concentration in East Asian foundries creates input cost instability for masker manufacturers.
- Reimbursement Fragmentation:Statutory health insurance coverage for tinnitus retraining therapy varies by German federal state, limiting addressable patient populations despite national policy frameworks.
- Software Substitution Threat:Smartphone-based masker applications distributed through app stores compete with dedicated hardware on accessibility and price, pressuring entry-level device segments.
Strategic Opportunities
- Underpenetrated Australian Clinical Channel:The TGA's parallel classification framework to FDA 21 CFR 874.3300 creates first-mover potential for combination devices in audiologist-dispensed networks.
- Fractal Tone Algorithm Convergence:Proprietary sound generation protocols are unifying with hearing aid compression architectures, enabling premium positioning through differentiated acoustic processing.
- Direct-to-Consumer Telehealth Distribution:Remote hearing aid dispensing regulations in select United States states are opening subscription-based masker delivery models outside traditional clinical gatekeeping.
Industry Challenges
- Audiological Calibration Skill Scarcity:Programming customized stimulus protocols requires specialized training that outpaces workforce pipeline capacity in expanding clinical networks.
- Notified Body Certification Timelines:EU MDR Class IIa therapeutic sound generator approvals face extended review queues, delaying market entry for notified body-dependent manufacturers.
- Legacy Analog Device Integration:Healthcare systems with installed bases of non-programmable maskers face capital-intensive upgrade cycles to support digital connectivity and remote monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tinnitus Maskers Market |
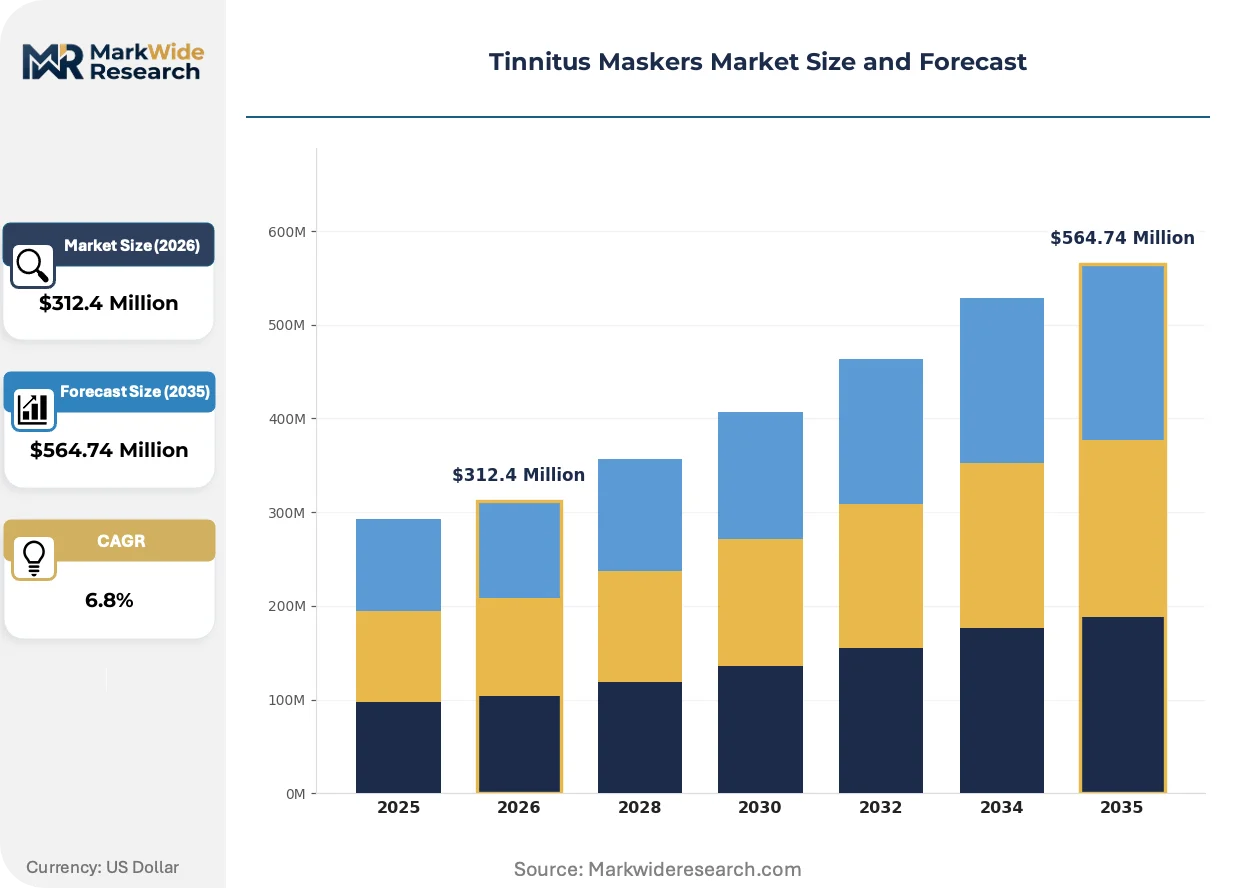
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Noise Machines, Hearing Aids, Sound Therapy Devices, Wearable Maskers Application: Home Use, Clinical Settings, Professional Therapy, Sleep Enhancement End User: Individuals, Audiologists, Therapists, Clinics Technology: Digital Signal Processing, Analog Devices, Bluetooth Connectivity, Noise Cancellation |
| Companies Covered | Starkey Hearing, Oticon, Sivantos, ReSound, Widex, Demant, GN Hearing, Neuromod Devices, Neuromonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tinnitus Maskers Market Evolving Landscape
Acoustic processing architectures are converging with hearing aid signal chains, while regulatory jurisdictions compete to define software-based therapeutic boundaries. Device form factors fragment across clinical prescription and consumer self-selection channels.
Fractal tone generation algorithms are unifying with multi-channel wide dynamic range compression in premium combination devices. Audiologist-dispensed channels in Germany and the United States are adopting these integrated platforms at accelerated replacement cycles. The technology is unifying previously separate device categories into single-unit reimbursement codes that compress patient out-of-pocket expenditure.
The EU MDR's therapeutic sound generator classification is mandating notified body involvement for Class IIa devices marketed with clinical claims. Manufacturers must demonstrate biocompatibility and electrical safety beyond prior wellness-product exemptions. German statutory health insurance reimbursement pathways are most affected, driving consolidation toward CE-marked, clinically validated product portfolios.
Patient self-selection through direct-to-consumer channels is displacing traditional audiologist gatekeeping for entry-level masker categories. United States consumers increasingly initiate tinnitus management through online hearing assessments and telehealth consultations. This behavioral shift concentrates in metropolitan markets with limited audiology practice density, where geographic access barriers override clinical preference for in-person fitting protocols.
Tinnitus Maskers Market Segmentation
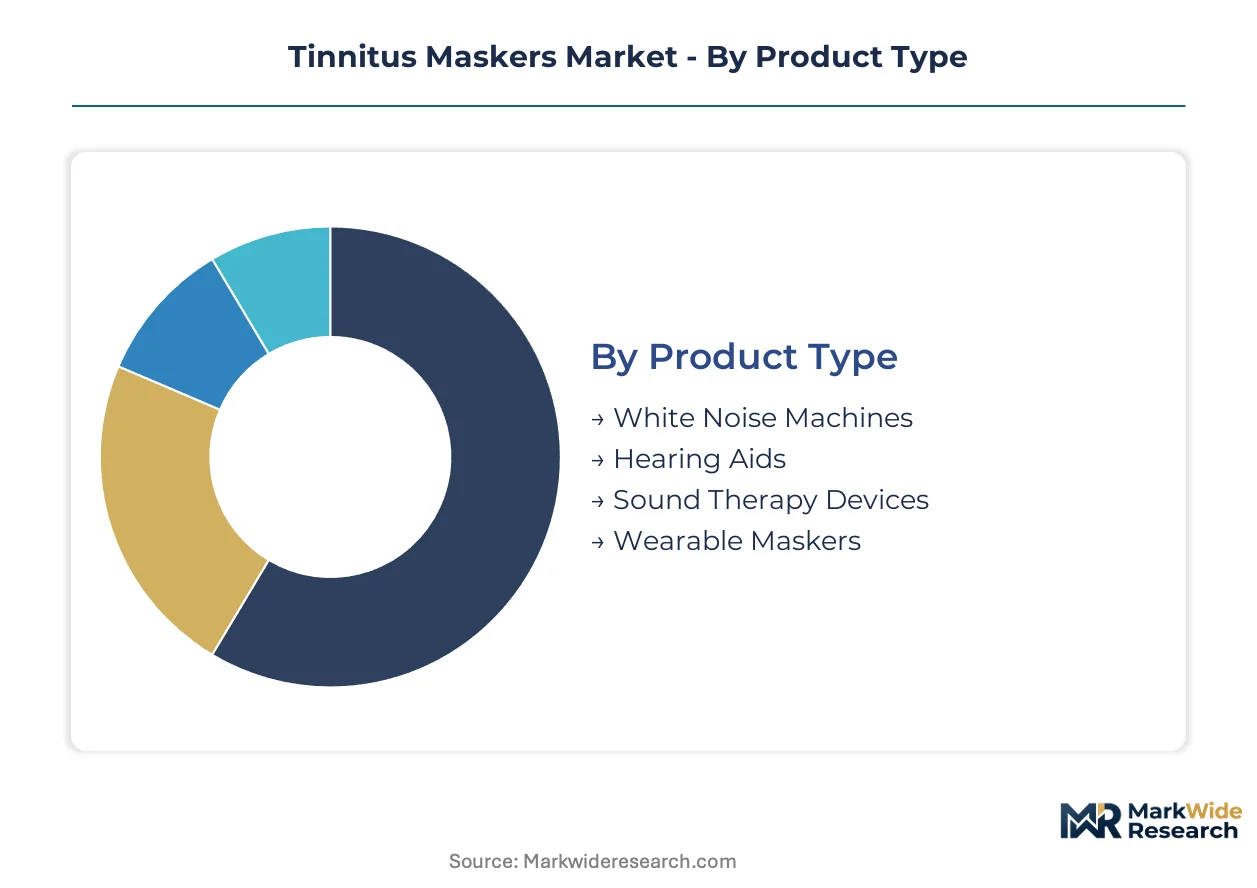
Tinnitus masker segmentation reveals divergent value capture strategies across clinical reimbursement channels and consumer self-selection. Product architecture choices determine whether manufacturers pursue audiologist-dispensed premium positioning or direct-to-consumer volume scaling.
Product Type:
Hearing aids with integrated masking functions command premium pricing through dual-purpose reimbursement codes, while wearable maskers expand through consumer electronics distribution.
- Hearing Aids:Combination devices embed broadband masker circuits within hearing aid signal chains, enabling single-unit billing under audiology reimbursement protocols. Demand concentrates in Germany where statutory health insurance covers tinnitus retraining therapy with programmable devices.
- Wearable Maskers:Bluetooth-enabled form factors stream customized soundscapes through earbud-style hardware, capturing consumer channels previously inaccessible to medical distributors. These devices are gaining share fastest among younger patients initiating management through telehealth platforms.
- Sound Therapy Devices:Tabletop or bedside units generate environmental sound fields for sleep-concurrent masking, occupying a mature niche in clinical procurement.
- White Noise Machines:Simple broadband generators serve entry-level home use with minimal programming requirements and price points below audiology consultation thresholds.
Today's leader: Hearing Aids. Tomorrow's challenger: Wearable Maskers.
Application:
Clinical settings anchor revenue through reimbursed fitting protocols, while home use segments scale through direct-to-consumer accessibility.
- Clinical Settings:Audiologist-supervised programming of customized stimulus protocols occurs in dedicated tinnitus clinics and hospital audiology departments. German federal state reimbursement variations create geographic demand concentration despite national policy frameworks.
- Home Use:Self-directed masker deployment bypasses clinical gatekeeping, expanding fastest in United States metropolitan markets with limited audiology practice density where geographic access barriers override preference for in-person fitting.
- Professional Therapy:Structured tinnitus retraining therapy programs incorporate masker devices as core intervention components within multi-session treatment protocols.
- Sleep Enhancement:Nocturnal masking applications prioritize comfort-optimized form factors and automatic volume attenuation during sleep stages.
Clinical Settings currently dominate revenue contribution. Home Use demonstrates the steepest expansion trajectory as telehealth regulations relax.
End User:
Audiologists control premium device dispensing through professional fitting requirements, while individual consumers drive volume in entry-level categories.
- Audiologists:These practitioners prescribe and program combination hearing aid-masker devices, capturing margin through bundled service fees alongside hardware markup in reimbursed markets.
- Individuals:Self-purchasing consumers select entry-level maskers through online retailers and direct-to-consumer hearing health platforms, concentrated in United States states with remote dispensing permissibility.
- Therapists:Psychologists and counseling professionals incorporate maskers into cognitive behavioral therapy protocols for tinnitus-related distress management.
- Clinics:Institutional purchasers within Veterans Affairs healthcare systems and hospital networks procure programmable devices at volume for tinnitus management program expansion.
Audiologists anchor premium positioning. Individuals represent the volume expansion frontier.
Technology:
Digital signal processing enables personalized stimulus calibration, while analog architectures persist in cost-sensitive installed bases.
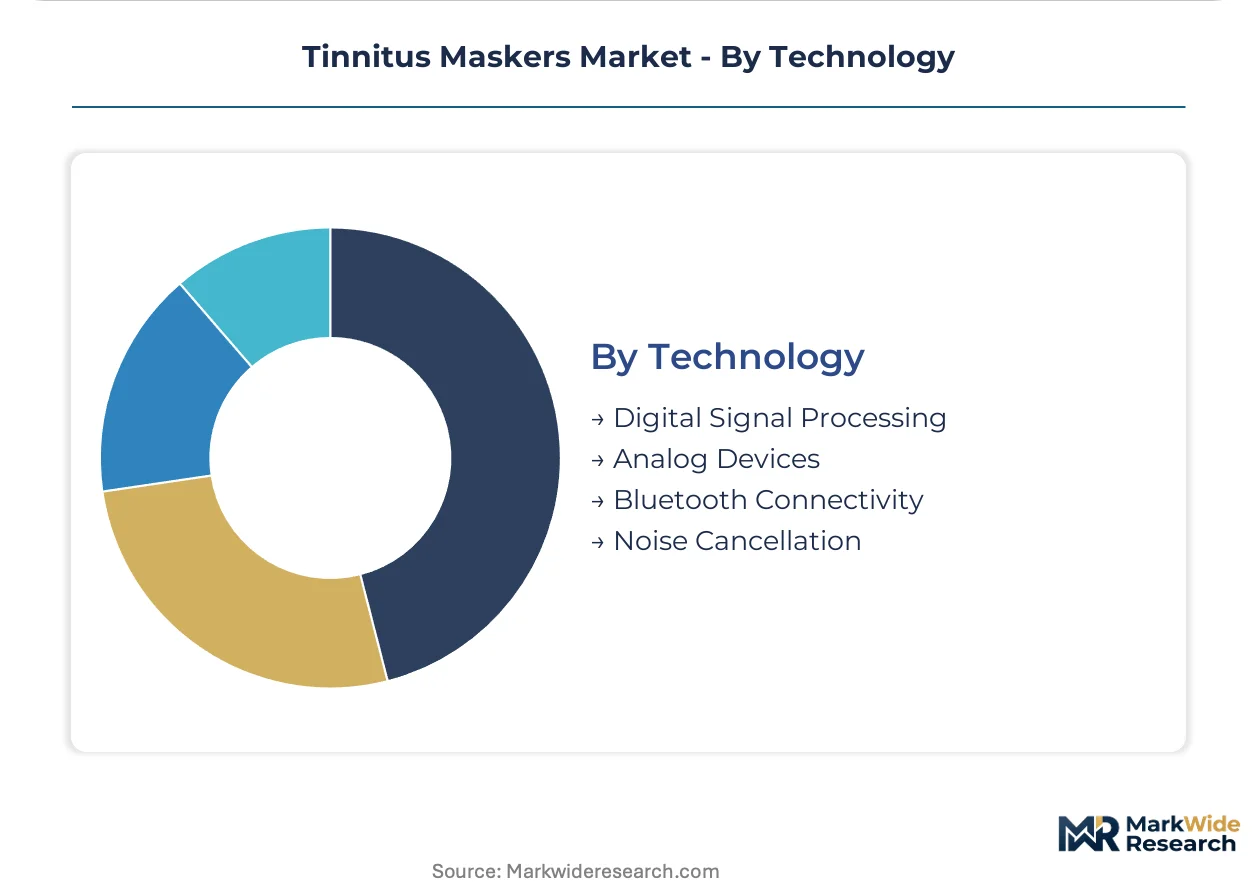
- Digital Signal Processing:Multi-channel wide dynamic range compression algorithms integrate fractal tone generation with adaptive gain control, unifying previously separate device categories into single-unit platforms.
- Bluetooth Connectivity:Wireless audio streaming capability enables smartphone app control and remote programming, blurring boundaries between medical devices and consumer electronics.
- Analog Devices:Legacy non-programmable maskers occupy healthcare systems facing capital-intensive upgrade cycles to support digital connectivity and remote monitoring.
- Noise Cancellation:Active acoustic suppression technology targets patients with concurrent hearing sensitivity, though regulatory classification complexity limits deployment.
Digital Signal Processing commands the technology premium. Bluetooth Connectivity enables the fastest channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tinnitus masker manufacturing and clinical adoption trace their commercial lineage to post-war audiology programs in the United States and Germany, where veteran rehabilitation systems first institutionalized sound therapy protocols for service-connected hearing disabilities.
United States
Veterans Affairs healthcare systems maintain the world's largest institutional procurement pipeline for programmable masker devices, driven by service-connected disability claims processing. FDA 21 CFR 874.3300 governs combination hearing aid-masker premarket notifications, with recent over-the-counter regulations compressing device classification pathways. Minneapolis-St. Paul anchors domestic manufacturing clusters where vertically integrated producers sustain cost advantages in custom-molded production.
Germany
Statutory health insurance reimbursement for tinnitus retraining therapy drives clinical adoption of programmable masker devices, though federal state coverage variations fragment addressable patient populations. EU MDR Class IIa therapeutic sound generator classifications mandate notified body involvement for clinical marketing claims. Berlin and Munich concentrate audiologist-dispensed channels where fractal tone algorithm integration accelerates device replacement cycles.
Australia
TGA classification frameworks parallel FDA 21 CFR 874.3300 structures, creating first-mover potential for combination devices in underpenetrated audiologist networks. Remote dispensing regulations in select states enable subscription-based masker delivery outside traditional clinical gatekeeping. Sydney and Melbourne metropolitan markets demonstrate the steepest telehealth adoption curves where geographic access barriers override preference for in-person fitting protocols.
Canada
Health Canada maintains classification frameworks influencing multinational registration strategies for therapeutic sound generators. Provincial reimbursement fragmentation limits clinical penetration despite national policy frameworks for hearing health. Toronto and Vancouver concentrate audiology practice networks where digital signal processing platforms displace legacy analog installed bases.
United Kingdom
NHS audiology procurement channels prioritize cost-calibrated masker solutions within constrained reimbursement budgets. MHRA post-Brexit regulatory divergence from EU MDR timelines creates submission strategy complexity for multinational manufacturers. London and Manchester anchor private audiology networks where Bluetooth-enabled wearable maskers capture consumer self-selection channels.
Tinnitus Maskers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology integration strategies. The vendor base stratifies between vertically integrated hearing aid manufacturers controlling captive semiconductor supply chains and software-centric entrants licensing acoustic processing algorithms. Three archetypes dominate: combination device specialists unifying masker circuits with hearing aid signal chains, standalone wearable masker producers leveraging consumer electronics distribution, and clinical sound therapy platform vendors serving institutional procurement channels. Competitive moves concentrate on M&A for algorithm portfolios and capacity expansion into telehealth-compatible remote programming infrastructure.
Within the integrated device tier, Starkey Hearing exemplifies vertically integrated manufacturing architectures, while Widex occupies a position anchored by proprietary acoustic processing differentiation. Neuromod Devices represents the standalone therapeutic platform archetype, situating its offerings within clinical prescription channels distinct from consumer self-selection markets.
| Leading Market Players |
|---|
| Starkey Hearing |
| Oticon |
| Sivantos |
| ReSound |
| Widex |
| Demant |
| GN Hearing |
| Neuromod Devices |
| Neuromonics |
| Others |
Value Network & Pricing Analysis
MEMS microphone spot pricing volatility cascades through East Asian foundry networks into finished masker cost structures, compressing margins at the entry-level wearable tier while premium combination devices absorb input shocks through audiologist-dispensed pricing power anchored in German statutory reimbursement codes.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the tinnitus masker landscape, with premium tiers commanding audiologist dispensing fees alongside hardware markup while economy tiers compete with smartphone application substitutes. FDA 21 CFR 874.3300 certification tier and fractal tone algorithm differentiation drive price separation between programmable clinical devices and basic broadband generators. Cost compression in the wearable category intensifies as consumer electronics entrants leverage existing Bluetooth supply chains. Individual consumers initiating therapy through telehealth platforms exhibit highest price sensitivity, whereas Veterans Affairs institutional procurement demonstrates lowest sensitivity due to service-connected disability claim mandates.
Supply Chain Analysis
Reverse logistics flows for remanufactured hearing aid-masker units concentrate refurbishment capacity in Minneapolis-St. Paul and Berlin, extending device lifecycle value capture for vertically integrated manufacturers. DSP chip fabrication concentrates in Taiwan and South Korea, while MEMS microphone assembly draws from Chinese and Vietnamese facilities. Single-source vulnerability in advanced node semiconductor access creates procurement risk for multi-channel compression architectures. Distribution runs through audiologist-dispensed channels in reimbursed markets and direct-to-consumer electronics retail in self-selection segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the tinnitus masker market rests on algorithmic premiumization displacing commodity hardware, with fractal tone intellectual property and remote programming infrastructure capturing value previously lost to clinical service bundling.
For Market Incumbents: Extend proprietary acoustic processing differentiation into subscription-based remote calibration services, insulating against software substitution threats from smartphone masker applications. Deepen backward integration into DSP chip design to reduce East Asian foundry dependency. Secure notified body pre-certification under EU MDR Class IIa pathways ahead of competitor queue positioning. For New Entrants and Emerging Players: Capture the underpenetrated Australian clinical channel where TGA classification parallels create first-mover timing before established manufacturers redirect registration resources. Target direct-to-consumer telehealth distribution in United States states with remote hearing aid dispensing permissibility. Deploy Bluetooth-enabled wearable form factors through consumer electronics retail partnerships rather than audiology gatekeeping. For Investors and Strategic Acquirers: Asymmetric upside sits with algorithm-licensing specialists possessing fractal tone generation patents and telehealth-compatible remote programming platforms. Long-term viability favors acquisition targets combining clinical validation data with direct-to-consumer regulatory clearance. Monitor EU MDR notified body certification queue lengths as inflection indicator for competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Pre-Certification | EU MDR Class IIa therapeutic sound generator approval accelerates German reimbursement eligibility. |
| Fractal Tone Algorithm Acquisition | Proprietary acoustic processing IP anchors premium positioning in audiologist-dispensed channels. |
| Telehealth Platform Integration | Remote programming capability captures United States direct-to-consumer regulatory permissibility. |
| Bluetooth Supply Chain Partnership | Consumer electronics distribution opens volume scaling outside clinical gatekeeping networks. |
| Veterans Affairs Contract Procurement | Institutional pipeline secures predictable demand through service-connected disability claim processing. |
Research Methodology
Coverage spans the United States, Germany, Australia, Canada, and the United Kingdom, with primary inputs from each market combined with secondary validation. Audiologists, Veterans Affairs procurement officers, biomedical engineers, and GPO contracts managers contributed stakeholder perspectives. FDA 510(k) filings, EU MDR notified body documentation, TGA registration databases, and statutory health insurance reimbursement schedules provided secondary anchor points. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation converged on segment-level estimates.
Rate-of-change decomposition across the projection horizon isolates volume drivers from price-mix effects in hearing aid-masker combination units versus standalone wearable categories. Product architecture, distribution channel, technology generation, and regional regulatory cluster dimensions structure the analytical framework. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns in reimbursed audiology channels. Forecast inputs incorporate Bluetooth Low Energy penetration trajectories and EU MDR implementation timeline assumptions.
Notified body certification delays, semiconductor supply disruption, and software substitution acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about reimbursement stability and regulatory classification continuity. Practitioners should monitor notified body queue lengths, MEMS microphone pricing indices, and smartphone masker application download velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Batteries for Skin Patches Market
Medical Devices
Spine Bone Stimulators Market
Medical Devices
Global Urinary Incontinence Treatment Devices Market
Medical Devices
Walkers and Rollators Market
Medical Devices
Left Atrial Appendage Devices Market
Medical Devices
Global Wedge Pressure Catheter Market
Medical Devices
Cochlear Implant Systems Market
Medical Devices
Vaginal Specula Market
Medical Devices
Internal Trauma Fixation Device Market
Medical Devices
Global Mobile ECG Devices Market
Medical Devices
Global Enteral Feeding Tubes Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
ECG Sensor Patch Market
Medical Devices
Sweden Minimally Invasive Surgery Devices Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Radial Compression Devices Market