
 North America Arthroscopy Devices Market | 2026-2036
North America Arthroscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Arthroscopy Devices Market Analytics
The FDA's 510(k) clearance framework is expanding the cost-of-entry calculus for arthroscopy device manufacturers seeking rapid market access. Stryker Corporation leverages its integrated visualization and instrument portfolio to sustain premium positioning across academic medical centers. Arthrex Inc. anchors its competitive stance through specialized soft-tissue fixation systems and surgeon education infrastructure. Smith & Nephew PLC differentiates via advanced radiofrequency ablation platforms targeting outpatient settings.
Arthroscopy devices encompass minimally invasive surgical instruments, visualization systems, and fluid management apparatus designed for joint cavity examination and intervention through small portal incisions, typically operating with irrigation pressures of 50-150 mmHg and high-definition camera resolutions exceeding 1080p for tissue differentiation. These systems enable diagnostic assessment and therapeutic repair of synovial joints while reducing perioperative morbidity versus open procedures. Surgical instruments command substantial margin pools given their consumable nature and procedure-linked replacement cycles, while robotic-assisted systems represent the fastest-expanding technology segment as capital equipment amortization models shift toward per-procedure leasing. Knee surgery applications dominate procedure volumes, though shoulder surgery applications are gaining share as implant fixation techniques advance.
The FDA maintains stringent biocompatibility and sterilization validation requirements under 21 CFR Part 820 quality system regulations, while Health Canada enforces parallel Medical Device License standards affecting cross-border product harmonization. State-level certificate-of-need provisions in New York and Illinois constrain ambulatory surgical center expansion, directly shaping end-user demand distribution. Stakeholders must monitor evolving CMS outpatient procedure reimbursement determinations and state-level scope-of-practice expansions for physician assistants performing arthroscopic interventions.
Market Dynamics
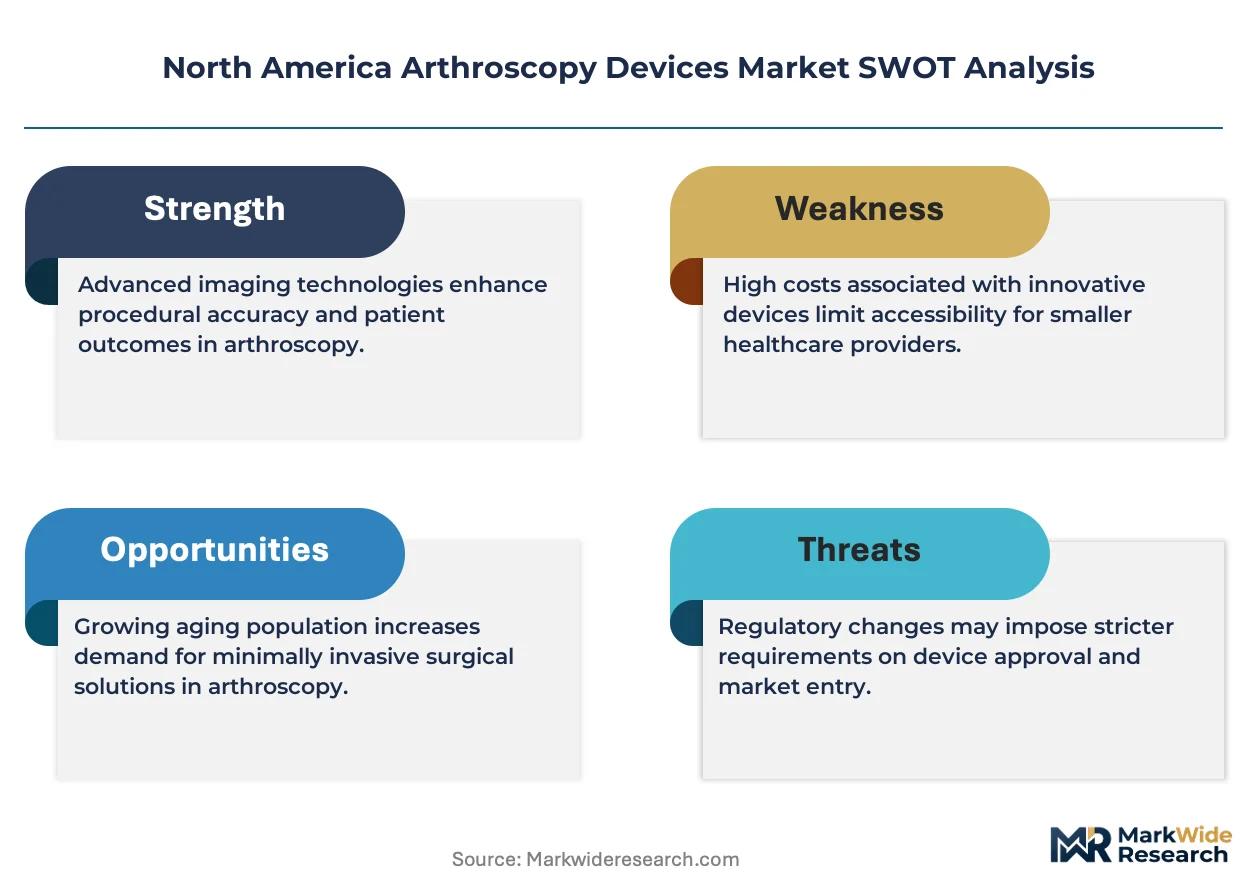
Outpatient migration from hospital inpatient settings to ambulatory surgical centers is compressing reimbursement rates and forcing device manufacturers to reconfigure their go-to-market economics around lower-cost delivery sites.
Growth Catalysts
- CMS outpatient reimbursement expansion:The Centers for Medicare & Medicaid Services is broadening procedure codes eligible for same-day surgical facility payment, accelerating site-of-service shifts across Texas and California health systems.
- Radiofrequency ablation platforms:Advanced energy-based tissue modification systems are reducing operative time and postoperative recovery intervals, expanding candidacy for arthroscopic intervention among older patient cohorts.
- Physician assistant scope expansion:State-level scope-of-practice liberalization in Florida and Arizona permits advanced practice providers to perform diagnostic arthroscopy, extending surgical capacity without specialist surgeon recruitment.
Market Restraints
- Certificate-of-need barriers:New York and Illinois CON provisions block ambulatory surgical center licensing, constraining addressable procedure volume growth in high-density metropolitan markets.
- Capital equipment amortization pressure:Robotic-assisted arthroscopy systems require substantial upfront investment and extended depreciation schedules, limiting adoption to well-capitalized academic medical centers and multi-facility health systems.
- Biocompatibility validation costs:FDA 21 CFR Part 820 quality system regulations impose lengthy sterilization and material compatibility testing protocols, extending product development timelines and premarket submission expenses.
Strategic Opportunities
- Shoulder surgery application expansion:Implant fixation technique advances are broadening rotator cuff repair indications, opening procedural white space beyond the dominant knee surgery segment.
- Per-procedure leasing models:Capital equipment financing innovation is lowering barriers to robotic system adoption among independent ambulatory surgical centers and smaller hospital networks.
- Health Canada harmonization:Medical Device License pathway alignment with FDA 510(k) clearance standards is streamlining cross-border product registration and accelerating Canadian market entry timing.
Industry Challenges
- Visualization system integration complexity:High-definition camera platforms exceeding 1080p resolution require substantial IT infrastructure upgrades and staff retraining, creating implementation friction in legacy surgical suites.
- Fluid management standardization gaps:Irrigation pressure parameters ranging 50-150 mmHg lack universal protocol consensus, complicating device interoperability and training curriculum development across health system networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Arthroscopy Devices Market |
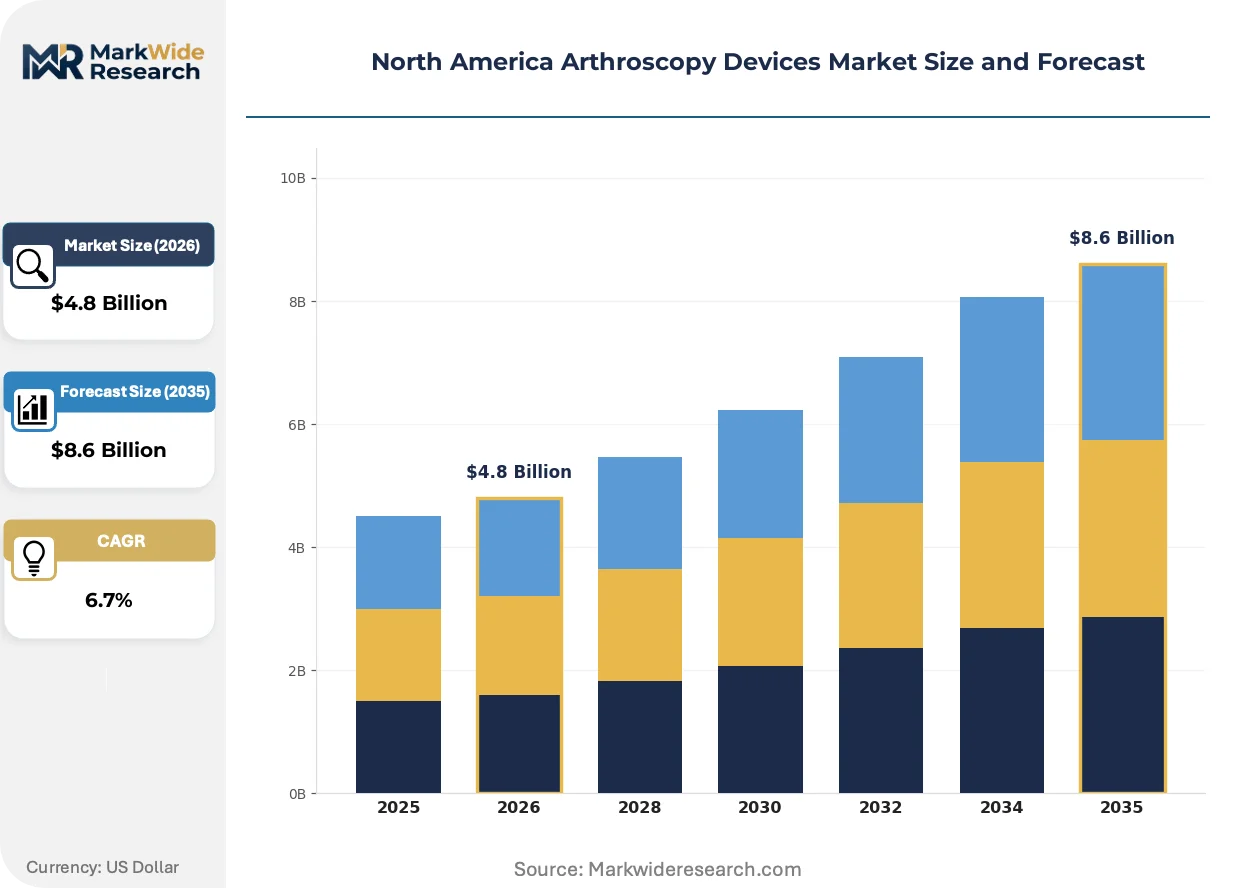
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arthroscopes, Fluid Management Systems, Radiofrequency Devices, Surgical Instruments End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Sports Medicine Facilities Technology: Visualization Systems, Navigation Systems, Robotic-Assisted Systems, Disposable Devices Application: Knee Surgery, Shoulder Surgery, Hip Surgery, Wrist Surgery |
| Companies Covered | Stryker Corporation, Arthrex Inc., Smith & Nephew PLC, Conmed Corporation, Johnson & Johnson, Medtronic PLC, Karl Storz GmbH & Co. KG, Zimmer Biomet Holdings Inc., Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Arthroscopy Devices Market Evolving Landscape
Arthroscopy device development is pivoting toward intelligent instrumentation and service-based revenue models that decouple manufacturer economics from unit sales volume alone.
Robotic-assisted surgical platforms are automating instrument positioning and tissue manipulation through haptic feedback and preoperative planning integration. Academic medical centers in the United States are piloting these systems for complex knee ligament reconstruction, with capital acquisition decisions increasingly favoring per-case utilization agreements over outright purchase. This automation is compressing operative variability and reducing revision procedure rates while shifting manufacturer revenue toward recurring software and service streams.
The FDA is tightening 510(k) substantial equivalence requirements for reusable arthroscopy instruments, demanding enhanced sterilization validation and material fatigue documentation. Manufacturers face extended premarket notification preparation periods and supplemental clinical data requests, particularly for shaver systems and radiofrequency probes. Device firms are responding by accelerating single-use disposable instrument development to bypass reprocessing validation burdens and accelerate clearance timelines.
Hospital procurement departments are consolidating vendor contracts into integrated visualization and instrument portfolios, displacing standalone instrument purchasing. Multi-facility health systems in California and Texas are negotiating enterprise-wide agreements that bundle capital equipment, consumables, and service contracts under multi-year commitments. This concentration is favoring manufacturers with comprehensive product ecosystems and penalizing niche instrument specialists lacking visualization platform integration.
North America Arthroscopy Devices Market Segmentation
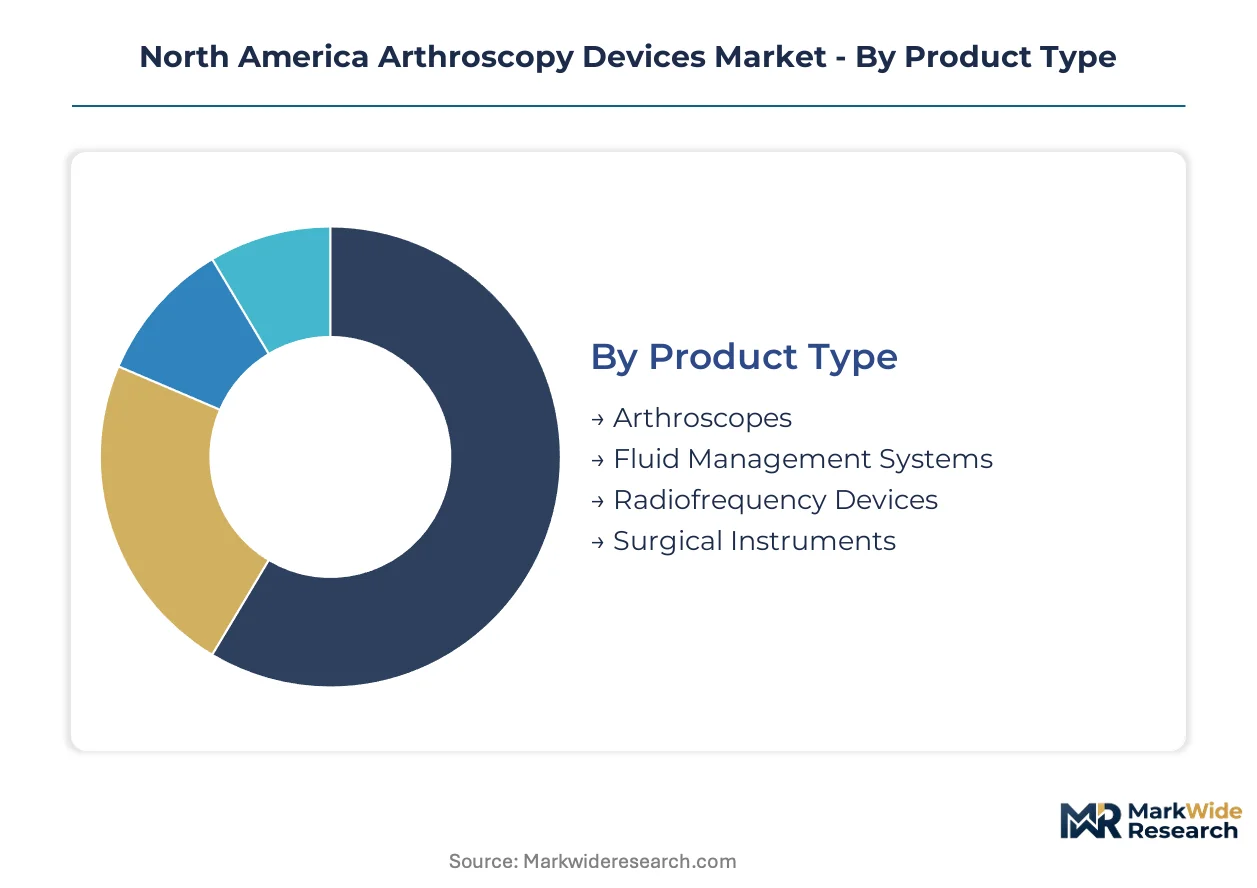
Arthroscopy device segmentation reveals divergent capital requirements across product categories, with visualization platforms demanding substantial infrastructure investment while consumable instruments generate recurring revenue streams. Understanding these structural differences enables manufacturers to align portfolio development with site-of-service economics and reimbursement trajectories.
Product Type:
Capital intensity varies sharply across this category, with integrated visualization platforms requiring multimillion-dollar surgical suite upgrades while single-use instruments operate on leaner deployment models.
- Arthroscopes:High-definition optical systems with 1080p-plus resolution capabilities enable tissue differentiation at irrigation pressures of 50-150 mmHg. Demand concentrates in academic medical centers across Texas and California as these institutions prioritize surgical precision for complex joint reconstruction.
- Fluid Management Systems:Irrigation and suction apparatus maintain joint cavity distension during procedures. Ambulatory surgical centers in Florida and Arizona are adopting compact, integrated units that reduce footprint requirements and support same-day discharge protocols.
- Radiofrequency Devices:Energy-based tissue ablation systems reduce operative time through controlled thermal modification.
- Surgical Instruments:Reusable and disposable shavers, graspers, and punches constitute high-velocity consumable categories.
Surgical instruments absorb the bulk of installed capacity; radiofrequency devices are expanding most quickly.
End User:
Procurement authority and reimbursement rates diverge substantially across this category, with hospital systems leveraging volume leverage for enterprise pricing while independent facilities prioritize capital efficiency.
- Hospitals:Inpatient and outpatient departments within integrated health systems command the deepest capital budgets and longest depreciation schedules. Texas and California hospital networks are consolidating vendor contracts into multi-year visualization and instrument bundles.
- Ambulatory Surgical Centers:Freestanding same-day surgical facilities operate under compressed reimbursement frameworks that favor disposable instruments and leased capital equipment. CMS outpatient reimbursement expansion is accelerating site migration to these settings.
- Orthopedic Clinics:Physician-owned practices performing diagnostic and minor therapeutic arthroscopy.
- Sports Medicine Facilities:Specialized centers serving athletic populations with high procedure volumes.
Hospitals retain dominant procurement volume; ambulatory surgical centers are gaining share fastest.
Technology:
Automation intensity and software dependency create distinct investment profiles across this category, with robotic platforms requiring substantial training infrastructure and recurring licensing fees.
- Visualization Systems:Camera towers, light sources, and monitors delivering high-definition joint cavity imaging. Hospital systems in California are piloting 4K resolution upgrades that demand substantial IT infrastructure investment and staff retraining.
- Navigation Systems:Optical and electromagnetic tracking for instrument positioning guidance. Academic medical centers are deploying these platforms for complex knee ligament reconstruction where anatomical precision reduces revision rates.
- Robotic-Assisted Systems:Automated instrument positioning with haptic feedback and preoperative planning integration.
- Disposable Devices:Single-use shavers, cannulas, and radiofrequency probes bypass sterilization validation burdens.
Visualization systems anchor current installed base; robotic-assisted systems show steepest expansion trajectory.
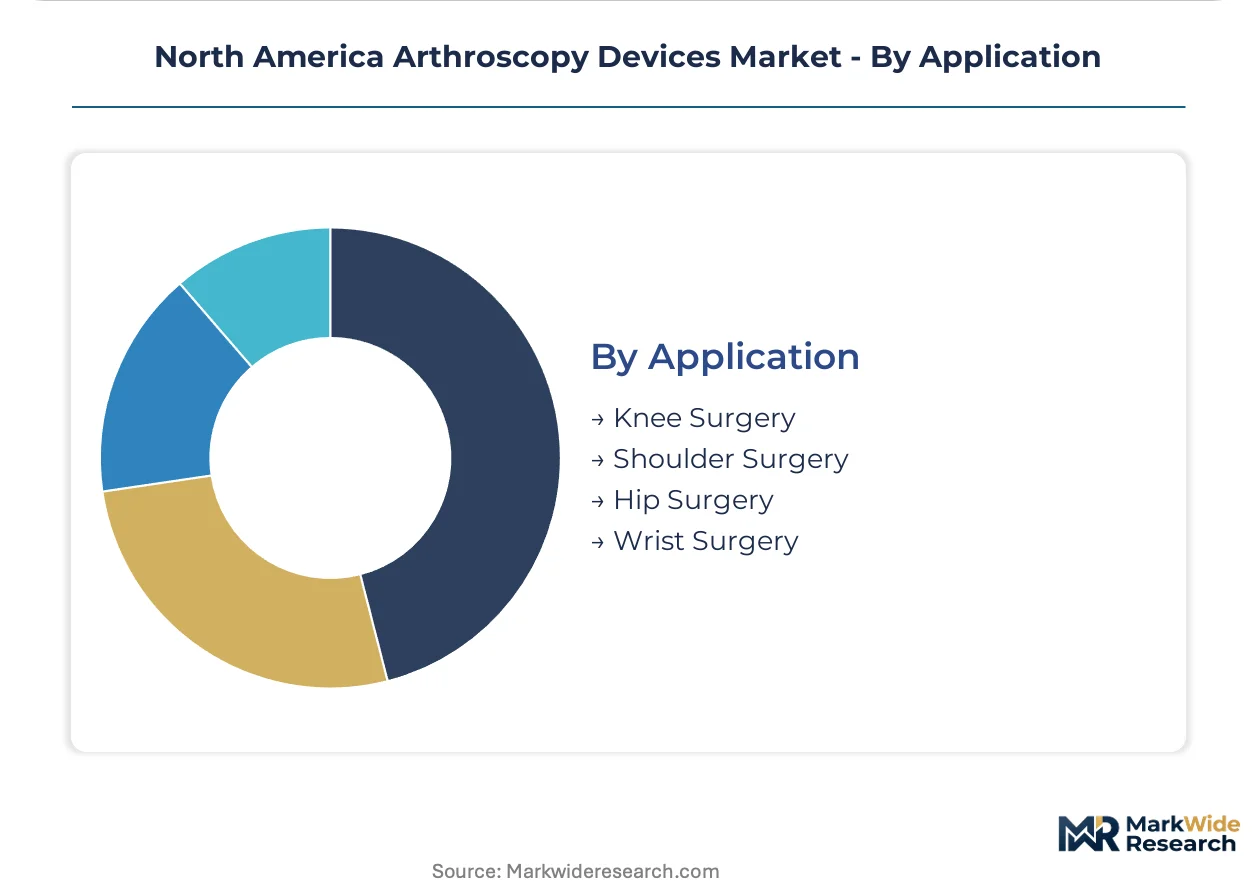
Application:
Procedure volume concentration and reimbursement coding maturity create divergent addressable market profiles across joint types.
- Knee Surgery:Ligament reconstruction, meniscal repair, and chondroplasty procedures constitute the dominant volume category. Hospital systems and ambulatory surgical centers across the United States maintain dedicated knee service lines with established coding and payment pathways.
- Shoulder Surgery:Rotator cuff repair and labral fixation applications are gaining share as implant fixation techniques advance. Texas health systems are expanding shoulder-specific capacity to capture growing demand from aging patient cohorts.
- Hip Surgery:Femoroacetabular impingement and labral repair procedures.
- Wrist Surgery:Diagnostic and therapeutic arthroscopy for carpal ligament and triangular fibrocartilage complex injuries.
Knee surgery commands dominant procedure volume; shoulder surgery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device innovation zones in Texas and California concentrate arthroscopy device manufacturing and clinical adoption. Federal research funding and state-level healthcare infrastructure investments reinforce this geographic clustering. Cross-border regulatory harmonization between the United States and Canada accelerates product commercialization timelines.
United States
Texas and California hospital systems drive arthroscopy procedure volume through integrated sports medicine service lines. The FDA maintains 510(k) clearance pathways for minimally invasive surgical tools under 21 CFR Part 820 quality system regulations. Academic medical centers in Houston and Los Angeles pilot robotic-assisted arthroscopy platforms for complex knee ligament reconstruction.
Canada
Health Canada enforces Medical Device License standards that parallel FDA biocompatibility requirements. Provincial health authorities in Ontario and Quebec prioritize ambulatory surgical center expansion for orthopedic procedures. Toronto and Montreal medical device clusters benefit from cross-border supply chain integration with US manufacturers.
Mexico
Northern border states attract arthroscopy device manufacturing through maquiladora program tax incentives. Federal health regulator COFEPRIS aligns medical device registration with international standards to facilitate export markets. Medical device production concentrates in Tijuana and Mexicali to serve US distribution networks.
North America Arthroscopy Devices Market Competitive Landscape
US-based producers anchor the premium visualization and capital equipment tier; European specialists hold positions in optical systems and precision instrumentation. The market structure consolidates around integrated portfolio vendors capable of bundling capital equipment, consumables, and service contracts. Three archetypes dominate: diversified medical technology conglomerates with orthopedic divisions, pure-play arthroscopy specialists with surgeon education infrastructure, and optical systems manufacturers leveraging camera technology crossovers. Competitive intensity manifests through enterprise contract consolidation and per-procedure leasing model innovation.
Among US-based diversified manufacturers, Stryker Corporation and Johnson & Johnson occupy positions representing the integrated portfolio archetype, bundling visualization towers with consumable instrument lines. Arthrex Inc. exemplifies the specialist model, anchoring competitive positioning through soft-tissue fixation focus and proprietary surgeon training networks. These three companies represent the structural segmentation between conglomerate scale advantages and specialist depth in arthroscopy-specific clinical workflows.
| Leading Market Players |
|---|
| Stryker Corporation |
| Arthrex Inc. |
| Smith & Nephew PLC |
| Conmed Corporation |
| Johnson & Johnson |
| Medtronic PLC |
| Karl Storz GmbH & Co. KG |
| Zimmer Biomet Holdings Inc. |
| Olympus Corporation |
| Others |
Value Network & Pricing Analysis
Captive production of high-definition camera sensors and precision-machined surgical instruments anchors supply positioning for arthroscopy device manufacturers, simultaneously insulating premium pricing tiers from commodity cost volatility while compressing margins for non-integrated competitors lacking upstream control over optical component sourcing.
Pricing Analysis
Short lead-time premiums command substantial markups for disposable radiofrequency probes and single-use shavers needed for urgent surgical schedules, while spot inventory of reusable arthroscopes trades at discounts. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance tier and after-sales service bundling. Cost compression in the standard tier intensifies as hospital procurement departments consolidate vendor contracts into multi-year visualization bundles. Independent ambulatory surgical centers exhibit highest price sensitivity; academic medical centers prioritize performance specifications over unit cost.
Supply Chain Analysis
Optical glass and precision-machined stainless steel supply rests on German and Japanese specialty manufacturers, with final assembly concentrating in Mexico's northern border maquiladora zones and select Texas medical device clusters. Critical inputs span sapphire lens substrates, radiofrequency generator components, and biocompatible polymer housings. Single-source vulnerability runs through German optical suppliers for 4K camera modules. Distribution runs through hospital procurement departments and GPO contracts, with direct-to-facility logistics for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into precision optical component manufacturing and proprietary surgeon training infrastructure constitutes the decisive upstream lever in this vertical-integration race, separating consolidated portfolio vendors from instrument specialists facing margin compression.
For Market Incumbents: To counter disposable instrument specialists bypassing sterilization validation burdens, deepen captive supply of high-definition camera sensors and expand proprietary surgeon education networks that lock in institutional purchasing loyalty. Anchor enterprise contract renewals through bundled visualization tower upgrades and multi-year service agreements. For New Entrants and Emerging Players: Capture shoulder surgery application white space in Texas health systems expanding rotator cuff capacity, where implant fixation technique advances outpace established vendor relationships. Penetrate through per-procedure leasing models for robotic-assisted platforms that lower capital barriers for independent ambulatory surgical centers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical technology conglomerates seeking orthopedic division expansion. Long-term viability favors targets with FDA 510(k) clearance portfolios and installed visualization base in California hospital networks. Watch CMS outpatient reimbursement determination timing as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortened clearance timelines capture outpatient migration momentum in Texas and California health systems. |
| Surgeon Education Infrastructure Expansion | Proprietary training networks lock in institutional purchasing preferences and reduce competitive switching. |
| Per-Procedure Leasing Model Development | Capital-light deployment opens independent ambulatory surgical centers previously blocked by equipment costs. |
| Health Canada Harmonization Investment | Streamlined cross-border registration accelerates Canadian market entry through Ontario provincial procurement. |
| Disposable Instrument Portfolio Buildout | Single-use shavers and radiofrequency probes bypass FDA reprocessing validation burdens and compress development timelines. |
Research Methodology
Multi-period observation of CMS reimbursement code expansions, FDA 510(k) clearance volumes, and ambulatory surgical center licensing patterns anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA premarket notification databases, CMS Medicare payment determinations, hospital procurement records, and Health Canada Medical Device License filings. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue segmentation.
Input-output matrices modeled demand drivers across product type, end user, technology, and application dimensions throughout the forecast period. CAGRs derived from segmented growth rate reconciliation against macro healthcare expenditure trends. Industry-specific forecast inputs incorporated CMS outpatient procedure reimbursement trajectories and state-level certificate-of-need policy evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA 510(k) substantial equivalence requirement tightening and ambulatory surgical center licensing policy shifts. Projections reflect documented assumptions regarding reimbursement stability and regulatory pathway continuity. A small set of named triggers—CMS coding expansions, CON provision relaxations, and robotic platform cost curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Creatinine Meter Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Craniomaxillofacial Plate and Installation Tools Market
Medical Devices
Animal Ultrasound Market
Medical Devices
Arthroscopy Procedures and Products Market
Medical Devices
Digital Respiratory Devices Market
Medical Devices
Heart Closure Devices Market
Medical Devices
Surgical Robotic Services Market
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
Intelligent Electronic Sphygmomanometers Market
Medical Devices
Ovulation Microscope Market
Medical Devices
Interatrial Shunt Devices Market
Medical Devices
Cardiac Implants Market
Medical Devices
Autotransfusion Devices Market
Medical Devices
Global Cardiac Prosthetic Devices Market
Medical Devices
Canada Digital X-Ray Devices Market