
 Intravascular Temperature Management Systems Market | 2026-2036
Intravascular Temperature Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Intravascular Temperature Management Systems Market Analytics
Modular catheter-and-control-unit bundling is hardening as the preferred procurement configuration for hospital systems evaluating total cost of ownership. Stryker Corporation leverages its critical care portfolio breadth to anchor bundled service contracts across integrated delivery networks. Medtronic Plc competes through deep R&D intensity in integrated temperature feedback systems. Zoll Medical Corporation specializes in emergency-care-focused configurations that dominate ambulance and resuscitation bay deployments.
Intravascular temperature management systems are catheter-based devices that circulate temperature-controlled saline through closed-loop lumens to induce, maintain, or reverse hypothermia or normothermia, typically achieving set points within 0.5 degrees Celsius precision through automated feedback algorithms. Their primary purpose is to prevent or treat perioperative hypothermia, manage fever in sepsis, and deliver neuroprotective targeted temperature management following cardiac arrest or traumatic brain injury. Cooling catheters command the largest installed base due to established reimbursement for therapeutic hypothermia protocols, while integrated systems represent the fastest-expanding category as hospitals consolidate warming and cooling functions onto single platforms. Emergency care centers drive disproportionate growth in warming catheter demand as pre-hospital temperature management protocols expand beyond traditional hospital boundaries.
The FDA maintains Class II device oversight with 510(k) premarket notification requirements for intravascular thermal regulation systems, while the EU Medical Device Regulation imposes stricter clinical evidence standards for temperature management claims under CE marking pathways. ISO 10993 biocompatibility testing and IEC 60601 electrical safety standards shape product development timelines and international market access feasibility. Stakeholders must monitor evolving CMS reimbursement determinations for targeted temperature management procedures and anticipate how updated AHA resuscitation guidelines will reshape protocol-driven device specifications across acute care settings.
Market Dynamics
Hospital procurement consolidation is forcing intravascular temperature management vendors to restructure pricing around total cost-of-ownership metrics rather than device-centric contracts, compressing margins for standalone catheter suppliers while rewarding integrated platform providers.
Growth Catalysts
- CMS reimbursement expansion:Updated procedural codes for targeted temperature management in cardiac arrest protocols are pulling device adoption into community hospitals previously restricted by payment uncertainty.
- Pre-hospital emergency protocols:Ambulance services across the United States are embedding warming catheters into field resuscitation standards, extending demand beyond traditional perioperative settings.
- Closed-loop automation:Machine learning-enabled feedback algorithms are reducing nurse staffing intensity for temperature maintenance, lowering operational barriers to protocol compliance.
Market Restraints
- Single-use catheter costs:Polymer raw material volatility and sterilization validation expenses are inflating per-procedure consumable pricing, squeezing hospital operating budgets.
- EU MDR clinical evidence requirements:Stricter CE marking pathways for temperature management claims are extending product registration timelines and freezing new entrant market access.
- Surface cooling substitution:Advanced conductive water-circulating blankets are capturing low-acuity cases where intravascular placement carries unjustified procedural risk.
Strategic Opportunities
- Japan's aging surgical population:METI-backed hospital modernization incentives are creating first-mover advantages for vendors bundling temperature management with anesthesia workstations.
- Sepsis fever management protocols:Emerging critical care guidelines are expanding addressable indications beyond neuroprotection into infectious disease temperature modulation.
- Integrated delivery network standardization:IDN-wide device contracts are opening multi-site deployment opportunities for platforms supporting both cooling and warming functions.
Industry Challenges
- Perfusionist staffing shortages:Specialized training requirements for intravascular catheter placement are creating bottleneck constraints in high-volume cardiac centers.
- Legacy EMR integration complexity:Temperature data interoperability with existing hospital information systems is delaying automated documentation rollouts.
- ISO 10993 biocompatibility retesting:Material formulation changes are triggering extended validation cycles that compress product refresh windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravascular Temperature Management Systems Market |
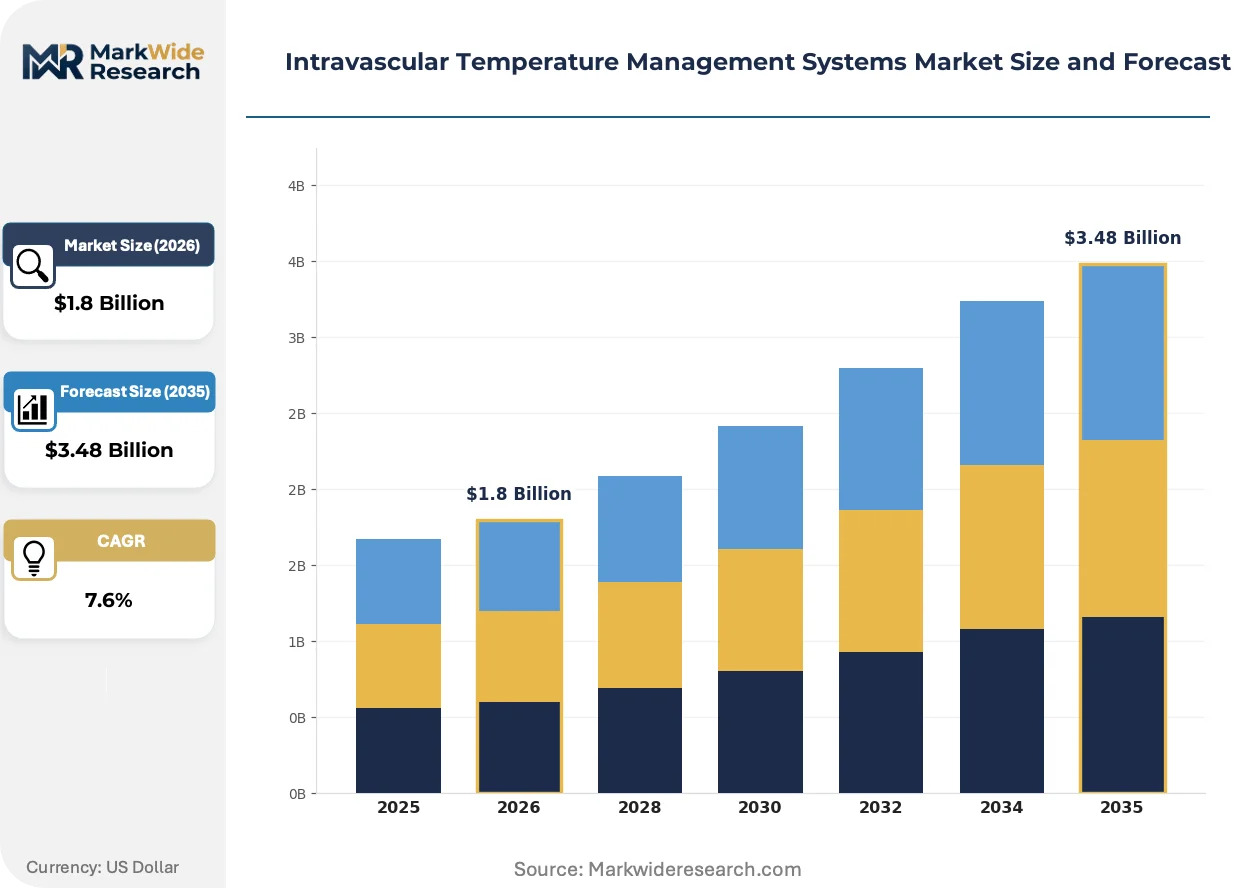
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooling Catheters, Warming Catheters, Temperature Sensors, Control Units End User: Hospitals, Emergency Care Centers, Ambulatory Surgical Centers, Clinics Application: Cardiac Arrest, Surgery, Trauma Care, Neuroprotection Technology: Active Warming, Passive Warming, Cryotherapy, Integrated Systems |
| Companies Covered | Stryker Corporation, Bard Medical, 3M Company, Smiths Medical, Belmont Instrument Corporation, Medtronic Plc, Becton, Dickinson And Company, Asahi Kasei Corporation, Zoll Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravascular Temperature Management Systems Market Evolving Landscape
Digital integration and automation are compressing the skill threshold for precise thermal management while regulatory harmonization efforts are reshaping competitive entry barriers across major healthcare markets.
Dual-lumen catheter designs with integrated temperature sensing are rewriting the competitive landscape for perioperative normothermia maintenance. Community hospitals and ambulatory surgical centers are adopting these platforms at accelerating rates, displacing manual surface warming methods that required continuous nursing adjustment. The technology is rewriting staffing models by enabling automated set-and-forget protocols that reduce labor intensity without sacrificing precision.
The EU Medical Device Regulation's clinical evidence requirements for temperature management claims are forcing manufacturers to sponsor prospective outcome studies that were previously unnecessary under the Medical Device Directive. This regulatory shift is favoring incumbent vendors with established clinical trial infrastructure while raising capital barriers for novel catheter entrants. Cooling catheter suppliers targeting European hospital systems are responding by consolidating regulatory affairs functions and pursuing notified body partnerships earlier in development cycles.
Hospital value analysis committees are unbundling device procurement from service contracts, separating capital equipment acquisition from training and maintenance agreements that were historically bundled. This purchasing behavior shift is disrupting traditional vendor lock-in strategies and opening opportunities for third-party clinical education specialists. The pattern is most visible in United States academic medical centers where supply chain autonomy from physician preference items is accelerating.
Intravascular Temperature Management Systems Market Segmentation
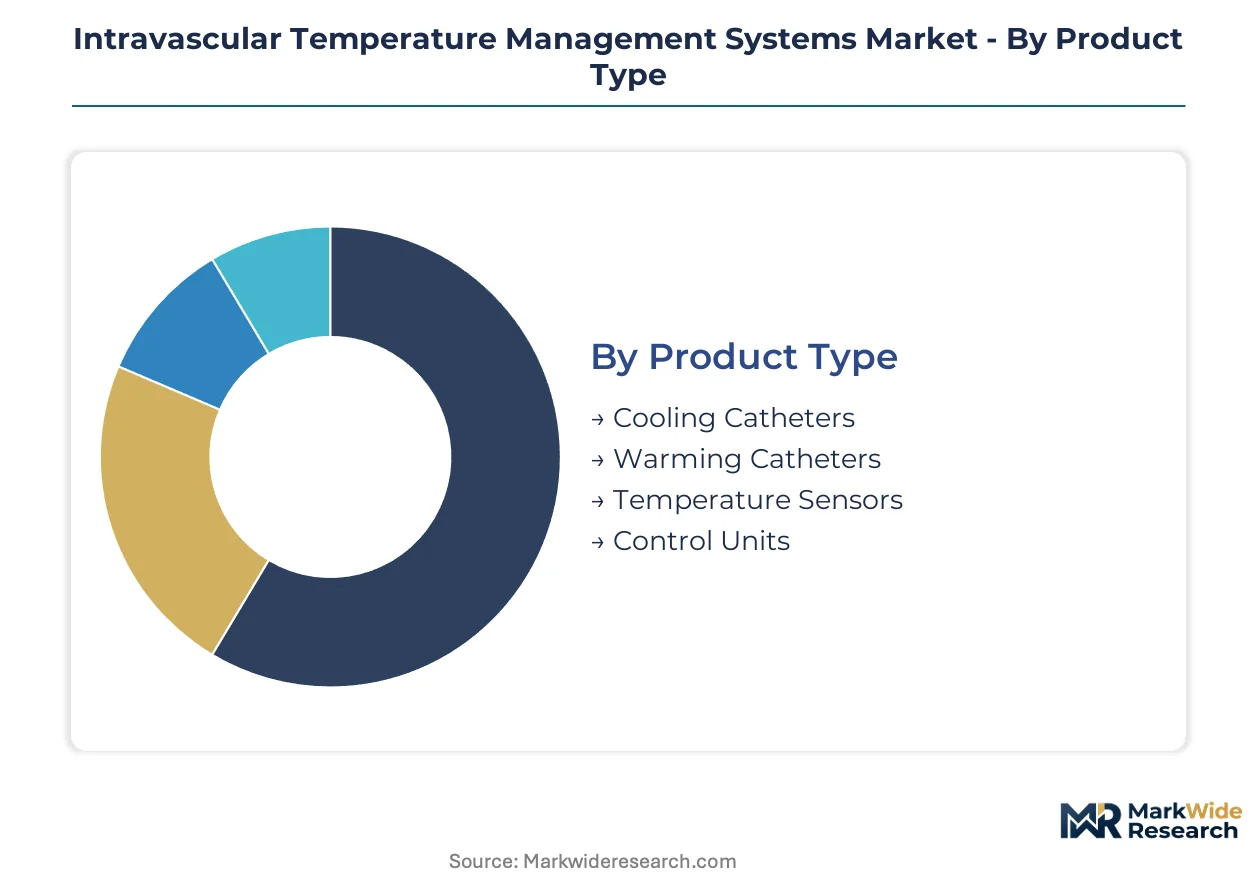
Intravascular temperature management systems fragment across four critical dimensions that determine procurement patterns and clinical deployment. Product configuration drives capital allocation decisions, while end-user setting shapes regulatory compliance requirements and reimbursement pathways.
Product Type:
Standardization pressure mounts on consumable components as hospitals consolidate vendor relationships, while control units retain customization flexibility for integrated network deployments.
- Cooling Catheters:Dual-lumen or multi-lumen designs circulate chilled saline through closed-loop circuits to achieve neuroprotective hypothermia. Academic medical centers in the United States anchor demand as therapeutic hypothermia protocols harden into standard of care for cardiac arrest survivors. FDA 510(k) clearance requirements for thermal regulation claims compress refresh cycles for polymer formulations.
- Warming Catheters:Heated saline circulation systems prevent perioperative hypothermia during prolonged surgical procedures. Ambulance services across the United States are embedding these platforms into field resuscitation protocols, extending addressable use beyond traditional operating rooms. Machine learning-enabled feedback algorithms are reducing nurse staffing intensity for temperature maintenance.
- Temperature Sensors:Integrated thermocouple arrays provide real-time core temperature monitoring with 0.1-degree Celsius precision. These components are increasingly bundled into catheter platforms rather than sold as standalone accessories.
- Control Units:Automated consoles manage saline circulation rates and temperature setpoints through proprietary feedback algorithms. Hospital value analysis committees are separating capital equipment procurement from service contracts, disrupting traditional vendor lock-in strategies.
Leading the category by volume: Cooling Catheters. Growing fastest: Control Units as integrated platform consolidation accelerates.
End User:
Procurement authority concentrates at the IDN level for hospital systems while emergency and ambulatory settings retain purchasing autonomy.
- Hospitals:Integrated delivery networks dominate capital allocation for intravascular temperature platforms, with perioperative protocols tightening across developed healthcare systems. Total cost-of-ownership metrics now govern contract negotiations.
- Emergency Care Centers:Pre-hospital deployment of warming catheters is expanding fastest here as field resuscitation standards evolve. CMS reimbursement expansion for targeted temperature management is pulling device adoption into community settings.
- Ambulatory Surgical Centers:Cost-sensitive outpatient facilities favor single-use warming configurations over capital-intensive integrated systems. Dual-lumen catheter designs with automated feedback are displacing manual surface warming methods.
- Clinics:Limited procedural volume restricts adoption to referral centers managing complex fever or neuroprotection cases. Surface cooling substitution captures most low-acuity temperature management needs.
Highest procurement volume: Hospitals. Steepest expansion trajectory: Emergency Care Centers.
Application:
Protocol standardization varies sharply by clinical indication, with cardiac arrest guidelines most mature and trauma applications still developing evidentiary bases.
- Cardiac Arrest:Targeted temperature management following return of spontaneous circulation commands established reimbursement codes and AHA guideline endorsement. Community hospitals are adopting cooling platforms as CMS procedural codes clarify payment pathways.
- Surgery:Perioperative normothermia maintenance represents the highest procedural volume application, with warming catheters deployed across cardiac, orthopedic, and general surgical suites. Automated set-and-forget protocols are rewriting staffing models.
- Trauma Care:Field and emergency department deployment of warming technology is accelerating as damage control resuscitation protocols emphasize core temperature preservation. Evidence base remains less codified than cardiac applications.
- Neuroprotection:Therapeutic hypothermia for traumatic brain injury and stroke commands premium catheter configurations with precise temperature control. Academic medical centers drive protocol development and device specification.
Dominant application by procedure volume: Surgery. Gaining share fastest: Trauma Care.
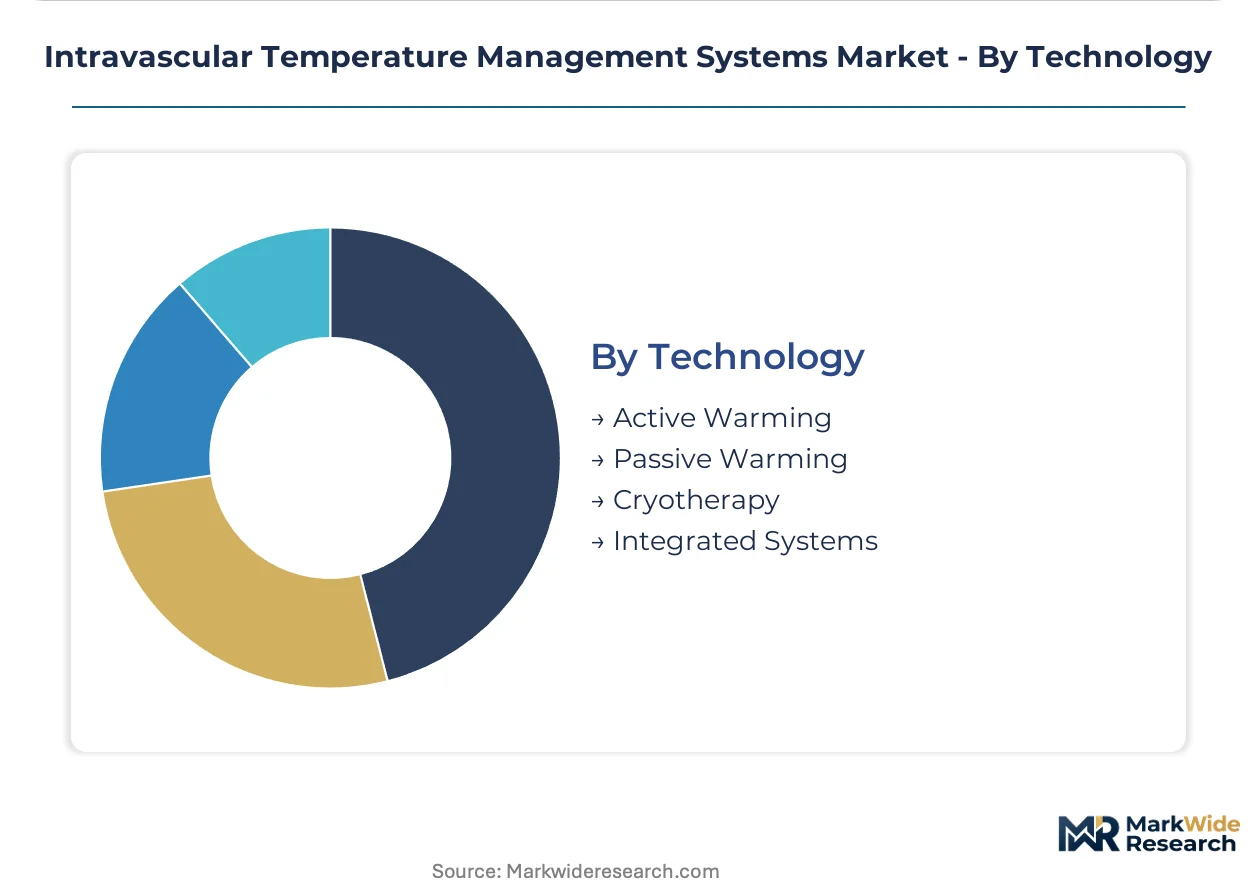
Technology:
Integration momentum favors platforms combining multiple thermal modalities, while standalone warming and cooling systems face margin compression.
- Active Warming:Forced-air and conductive surface systems compete with intravascular approaches for perioperative normothermia. Advanced water-circulating blankets are capturing low-acuity cases where catheter placement carries procedural risk.
- Passive Warming:Insulation blankets and reflective materials retain body heat without energy input. These systems occupy the economy tier of temperature management and face displacement from automated intravascular alternatives.
- Cryotherapy:External cooling applications for orthopedic and dermatological indications operate outside the core intravascular market but share regulatory pathways and hospital procurement channels.
- Integrated Systems:Single platforms supporting both warming and cooling functions through modular catheter configurations are consolidating hospital capital budgets. IDN-wide standardization contracts favor vendors offering comprehensive thermal management portfolios.
Highest installed base: Active Warming. Expanding most quickly: Integrated Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in the United States, Germany, and Japan while consumption spreads across developed healthcare systems. Production clusters serve export markets from FDA-cleared and CE-marked facilities. Regional demand patterns diverge sharply between emergency-care expansion and perioperative protocol standardization.
United States
Academic medical centers in Boston and the Research Triangle drive protocol development for targeted temperature management. FDA 510(k) premarket notification requirements compress refresh cycles for catheter polymer formulations. The Cleveland Clinic and Mayo Clinic anchor multicenter clinical validation studies that shape AHA resuscitation guideline updates.
Germany
EU MDR clinical evidence requirements for temperature management claims extend product registration timelines for catheter suppliers. The country's national pharmaceutical regulator enforces stricter biocompatibility testing under ISO 10993 standards. Baden-Württemberg's medical technology cluster hosts precision manufacturing for integrated control unit components serving European hospital networks.
Japan
METI-backed hospital modernization incentives create first-mover advantages for vendors bundling temperature management with anesthesia workstations. PMDA oversight maintains alignment with international electrical safety standards under IEC 60601. The Kansai region's Osaka-Kobe medical device corridor concentrates R&D for dual-lumen catheter designs with integrated sensing arrays.
United Kingdom
NHS supply chain consolidation favors integrated platform providers offering total cost-of-ownership contracting. MHRA post-Brexit regulatory autonomy maintains equivalence with EU MDR evidence standards for CE-marked devices. London's academic hospital trusts lead European adoption of automated feedback algorithms for perioperative normothermia maintenance.
China
NMPA Class II device registration requirements for thermal regulation systems accelerate local manufacturing partnerships. The country's national medical products administration harmonizes with international standards through GB adoption of ISO 10993 protocols. Yangtze River Delta medical device parks in Suzhou and Shanghai host joint ventures producing control units for domestic hospital procurement.
Intravascular Temperature Management Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across catheter and control unit segments. The vendor base organizes into three tiers: integrated critical care portfolio holders, emergency-care-focused device specialists, and component suppliers serving private-label arrangements. Strategic moves concentrate on bundled service contracting, regulatory affairs consolidation, and machine learning-enabled automation differentiation.
Within the diversified medical technology tier, Stryker Corporation and Medtronic Plc exemplify platform breadth strategies. Stryker leverages critical care portfolio integration to anchor multi-year service contracts across United States integrated delivery networks. Medtronic occupies a position emphasizing deep R&D intensity in closed-loop feedback systems. Zoll Medical Corporation represents the emergency-care specialist archetype, with configurations dominating ambulance and resuscitation bay deployments where field protocol standardization drives specification.
| Leading Market Players |
|---|
| Stryker Corporation |
| Bard Medical |
| 3M Company |
| Smiths Medical |
| Belmont Instrument Corporation |
| Medtronic Plc |
| Becton, Dickinson And Company |
| Asahi Kasei Corporation |
| Zoll Medical Corporation |
| Others |
Value Network & Pricing Analysis
Closed-loop automation architectures are compressing per-procedure labor costs while simultaneously concentrating procurement power among integrated delivery networks that command volume discounts across catheter and control unit bundles. This technological shift tightens margins for standalone component suppliers even as it rewards platform vendors with captive service revenue streams.
Pricing Analysis
Margin tightening in the consumables tier reflects polymer raw material volatility and sterilization validation expenses that hospitals increasingly refuse to absorb through device-centric contracts. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center configurations from community hospital deployments and ambulatory surgical center entry-level systems. Cost-down pressure on warming catheter suppliers accelerates because emergency care centers are unbundling capital equipment from training agreements. Ambulatory surgical centers exhibit the highest price sensitivity, while academic medical centers prioritize total cost-of-ownership metrics over unit pricing.
Supply Chain Analysis
Domestic-content mandates under the EU MDR and FDA 510(k) pathways are reshaping sourcing strategies for catheter polymer formulations and precision-machined control unit components. Manufacturing concentrates in the United States, Germany, and Japan, with the Kansai corridor and Baden-Württemberg cluster anchoring dual-lumen catheter production. Supply chains draw from medical-grade silicone suppliers in Germany, thermoplastic elastomer producers in the United States, and precision sensor manufacturers in Japan. Single-source vulnerability around sterilization validation services creates bottleneck exposure. Distribution runs through integrated delivery network procurement offices and group purchasing organizations that consolidate hospital system demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over feedback algorithm development and catheter manufacturing determines contract win rates across IDN standardization initiatives.
For Market Incumbents: Hedge against surface cooling substitution by deepening software companion development for EMR integration and automated documentation workflows. Acquire regulatory affairs capabilities in European notified body relationships early to compress EU MDR registration timelines. Prioritize backward integration into polymer formulation to defend margin position against raw material volatility. For New Entrants and Emerging Players: Machine learning-enabled temperature prediction algorithms offer a technology-first wedge into community hospital segments where nurse staffing constraints create acute protocol compliance pain points. Target trauma care applications where evidentiary bases remain less codified than cardiac arrest protocols, enabling faster clinical validation cycles. Pursue private-label catheter manufacturing arrangements with established control unit vendors to bypass capital-intensive console development. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified critical care portfolio holders seeking to fill temperature management gaps. Long-term viability hinges on reimbursement strategy execution and AHA guideline alignment rather than pure technology differentiation. Watch CMS procedural code expansions for targeted temperature management as the primary inflection signal for community hospital adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clears neuroprotective hypothermia claims for cardiac arrest protocols under Class II device oversight. |
| CE Marking Pathway | Unlocks EU hospital procurement under MDR clinical evidence requirements for temperature management. |
| Hospital System Partnership | Secures multi-site IDN standardization contracts for integrated warming-cooling platforms. |
| Software Companion Development | Enables EMR interoperability that reduces legacy integration friction for automated documentation. |
| Reimbursement Strategy | Aligns device specifications with CMS procedural codes for targeted temperature management coverage. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare reimbursement filings underwrites the qualitative findings on IDN purchasing behavior. Primary interviews with clinicians, biomedical engineers, hospital purchasing committee members, and GPO contracts managers were combined with secondary validation from FDA 510(k) clearances, EU MDR notified body documentation, and ISO 10993 biocompatibility testing records. Bottom-up catheter shipment estimates and top-down control unit capital expenditure tracking were triangulated to anchor market sizing.
Rate-of-change decomposition across product type, end user setting, clinical application, and technology platform dimensions structured the analytical framework over the projection horizon. CAGRs were derived from procedure volume elasticity to reimbursement expansion, protocol penetration curves in emergency care, and replacement cycle dynamics for integrated systems. Forecast inputs incorporated AHA resuscitation guideline revision timelines and METI-backed hospital modernization incentive trajectories.
Several conditions sit outside the modeled scope, including speculative regulatory harmonization between FDA and PMDA pathways, breakthrough surface cooling technologies that displace intravascular placement, and macroeconomic shocks to polymer feedstock pricing. Forecasts reflect documented assumptions about protocol standardization velocity and staffing shortage persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Surgical Incision Closure Devices Market
Medical Devices
Infant Oxygen Hoods Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
South Africa Minimally Invasive Surgical Devices Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Netherlands Aesthetic Devices Market
Medical Devices
Infant Radiant Warmer Market
Medical Devices
Intrauterine Insemination Devices Market
Medical Devices
Fracture Fixation Products Market
Medical Devices
Eye Massage Device Market
Medical Devices
Dose Monitoring Devices Market
Medical Devices
Canada Digital X-Ray Devices Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Global Stent Graft Balloon Catheter Market