
 Orthokeratology Lens Market | 2026-2036
Orthokeratology Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Orthokeratology Lens Market Intelligence
Specialist optical retail networks is reshaping how orthokeratology lenses reach end consumers, with trained optometrists now serving as the primary education and fitting gatekeepers. Bausch & Lomb Incorporated leverages its established eye care infrastructure to sustain practitioner loyalty across North American markets. Menicon Co., Ltd. dominates precision manufacturing of high-Dk rigid gas permeable materials for overnight wear applications. CooperVision competes through direct-to-practitioner training programs that build fitting confidence among newly certified orthokeratologists.
Orthokeratology lenses are reverse-geometry rigid gas permeable contact lenses manufactured from fluorosilicone acrylate or fluorocarbon materials with oxygen permeability values exceeding 100 Dk/t, designed to temporarily reshape the central corneal epithelium during overnight wear to reduce refractive error. Myopia control applications now command the largest addressable patient pool as pediatric prescriptions accelerate across Asia-Pacific markets. Rigid gas permeable lenses retain the dominant manufacturing volume share due to their established safety profile and precise corneal molding capability. Hospital pharmacies and optical stores together capture the majority of distribution value, though online sales channels are gaining traction for replacement lens reorders among established wearers.
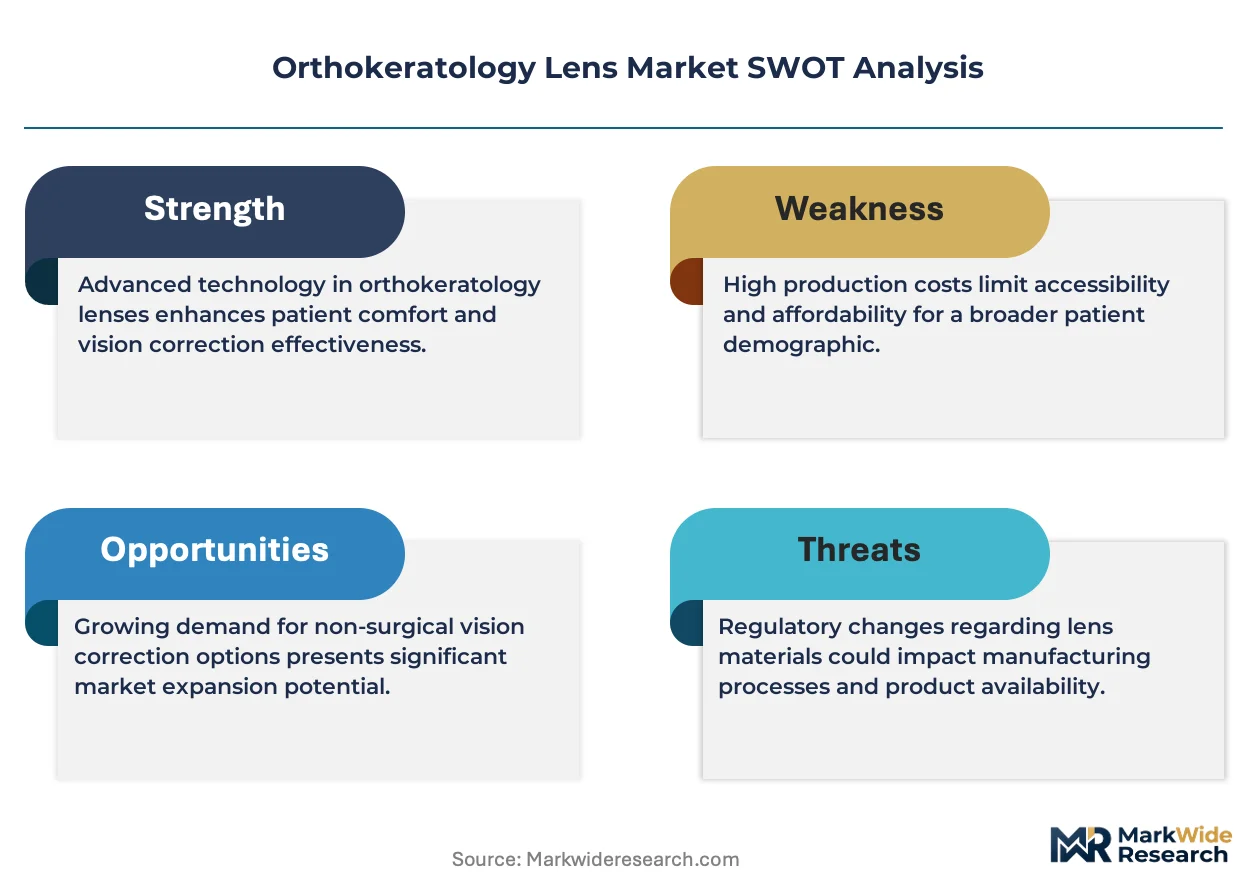
FDA 510(k) clearance requirements and ISO 18369 international contact lens standards jointly define material biocompatibility and dimensional tolerance thresholds for market entry. The EU Medical Device Regulation now classifies orthokeratology devices as Class IIa or IIb depending on wear duration, intensifying notified body scrutiny across European markets. Stakeholders must monitor evolving national myopia control guidelines and reimbursement policy shifts that could either accelerate or constrain practitioner adoption curves.
Market Dynamics
Pediatric myopia management protocols in East Asian school systems are accelerating practitioner certification in overnight corneal reshaping, while fluorosilicone acrylate material shortages and ISO 18369 compliance timelines compress manufacturing throughput for independent lens laboratories.
Growth Catalysts
- East Asian school-based screening mandates:China's Ministry of Education requires annual refractive error assessments for students through grade nine, channeling myopic children toward orthokeratology clinics in tier-one cities.
- High-Dk material innovation:Fluorocarbon-silicone copolymers with oxygen permeability exceeding 125 Dk/t extend safe overnight wear duration, reducing hypoxic complications that previously limited pediatric adoption.
- FDA 510(k) pathway clarity:Streamlined premarket notification procedures for orthokeratology devices reduce regulatory uncertainty, encouraging domestic manufacturers to enter the US market.
Market Restraints
- Fluorosilicone monomer supply concentration:Japanese and German chemical producers control over 80% of high-purity fluorinated monomer output, exposing lens manufacturers to input cost volatility and allocation constraints.
- Practitioner training bottlenecks:Corneal topography interpretation and reverse-geometry fitting protocols require 40-60 hours of supervised certification, limiting the pool of qualified orthokeratologists in secondary markets.
- LASIK substitution threat:Laser vision correction for adult myopes retains cost advantages and immediate visual outcomes, capturing patients who might otherwise consider orthokeratology for daytime lens-free activity.
Strategic Opportunities
- India's underpenetrated pediatric segment:Private ophthalmology chains in Mumbai, Delhi, and Bangalore are building dedicated myopia control centers, creating first-mover advantage for orthokeratology training programs.
- Direct-to-practitioner digital platforms:Cloud-based corneal topography sharing and remote fitting consultation tools reduce geographic barriers between specialized lens laboratories and rural optometrists.
- EU Medical Device Regulation Class IIa pathway:Streamlined conformity assessment for daily-wear orthokeratology designs accelerates market entry for manufacturers willing to limit wear duration claims.
Industry Challenges
- Corneal topography technician scarcity:Accurate orthokeratology fitting requires operators skilled in placido disk image acquisition and eccentricity analysis, a competency gap particularly acute in Latin American and Southeast Asian markets.
- ISO 18369-2 dimensional tolerance compliance:Sub-micron manufacturing precision for reverse-geometry curves demands capital-intensive lathe technology that smaller independent laboratories struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthokeratology Lens Market |
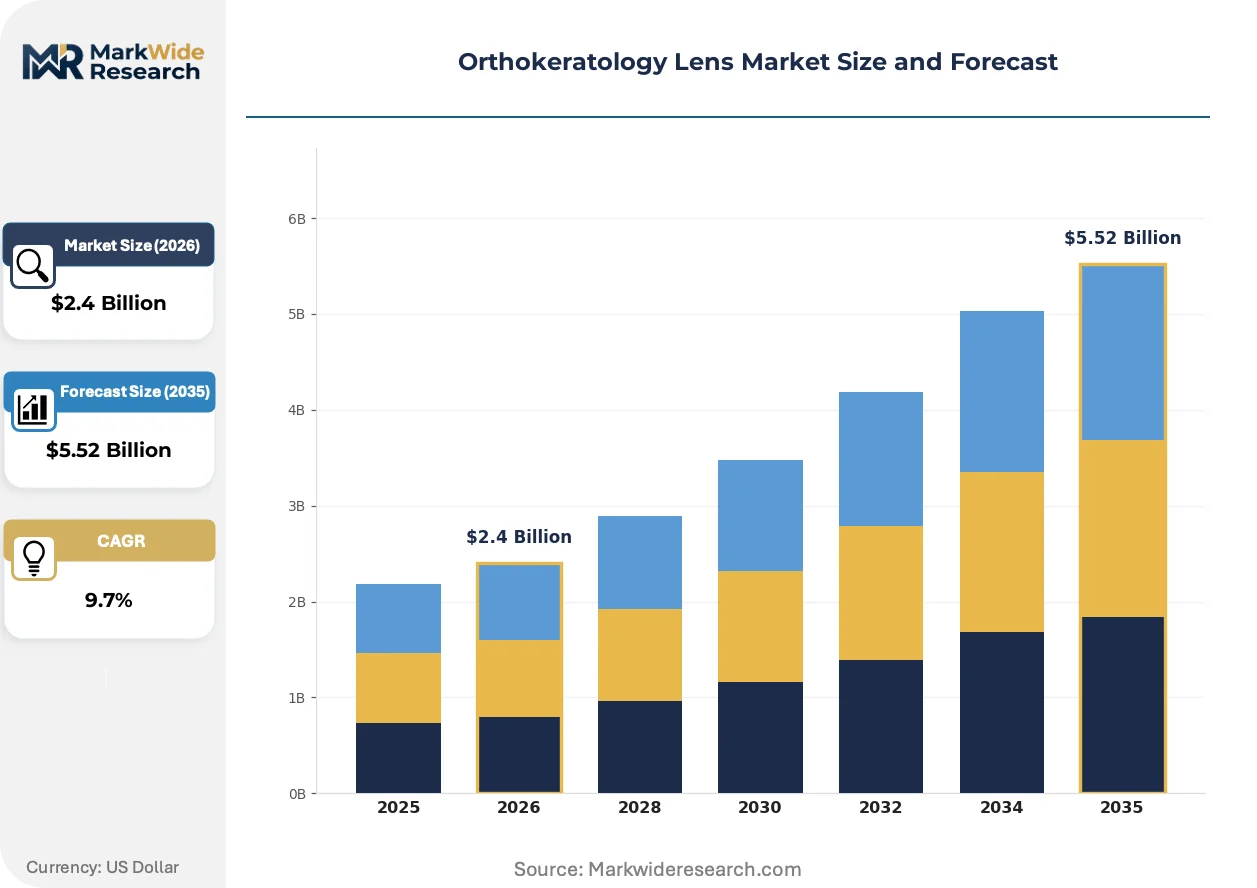
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scleral Lenses, Rigid Gas Permeable Lenses, Soft Lenses, Hybrid Lenses Application: Myopia Control, Astigmatism Correction, Presbyopia Treatment, Vision Enhancement End User: Optometrists, Ophthalmologists, Clinics, Retail Stores Distribution Channel: Online Sales, Hospital Pharmacies, Optical Stores, Direct Sales |
| Companies Covered | Bausch & Lomb Incorporated, Johnson & Johnson Vision Care, Inc., CooperVision, Menicon Co., Ltd., Euclid Systems Corporation, Alpha Corporation, Brighten Optix, Art Optical Contact Lens, Inc., TruForm Optics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthokeratology Lens Market Strategic Shifts & Innovations
Wavefront-guided corneal mapping and machine learning-driven fitting algorithms are compressing the traditional trial-and-error orthokeratology workflow, while regulatory convergence around myopia control claims reshapes competitive positioning across major markets.
Topography-guided custom orthokeratology designs incorporating higher-order aberration correction are rendering obsolete empirically fitted diagnostic lens sets that dominated clinical practice for two decades. Pediatric ophthalmology practices in Shanghai, Seoul, and Tokyo are adopting these systems within 18-24 month replacement cycles, compressing inventory carrying costs for conventional diagnostic fitting sets while elevating capital requirements for practices.
The EU Medical Device Regulation's 2021 reclassification of extended-wear orthokeratology devices as Class IIb intensifies notified body scrutiny of clinical evidence packages. Manufacturers must now submit prospective safety data for wear durations exceeding 24 hours, extending time-to-market by 12-18 months for next-generation materials. European practitioners are responding by consolidating supplier relationships around established CE-marked portfolios rather than evaluating unproven entrants.
Parental purchasing for pediatric myopia control is shifting from hospital-based ophthalmology departments toward specialized optical retail chains with dedicated orthokeratology fitting suites. This channel migration fragments the traditional prescriber-dispenser relationship, forcing lens manufacturers to maintain parallel training and technical support infrastructures. The transition is most visible in China's tier-one cities, where private optical chains now capture over half of new orthokeratology fittings through aggressive myopia control marketing to affluent households.
Orthokeratology Lens Market Segmentation
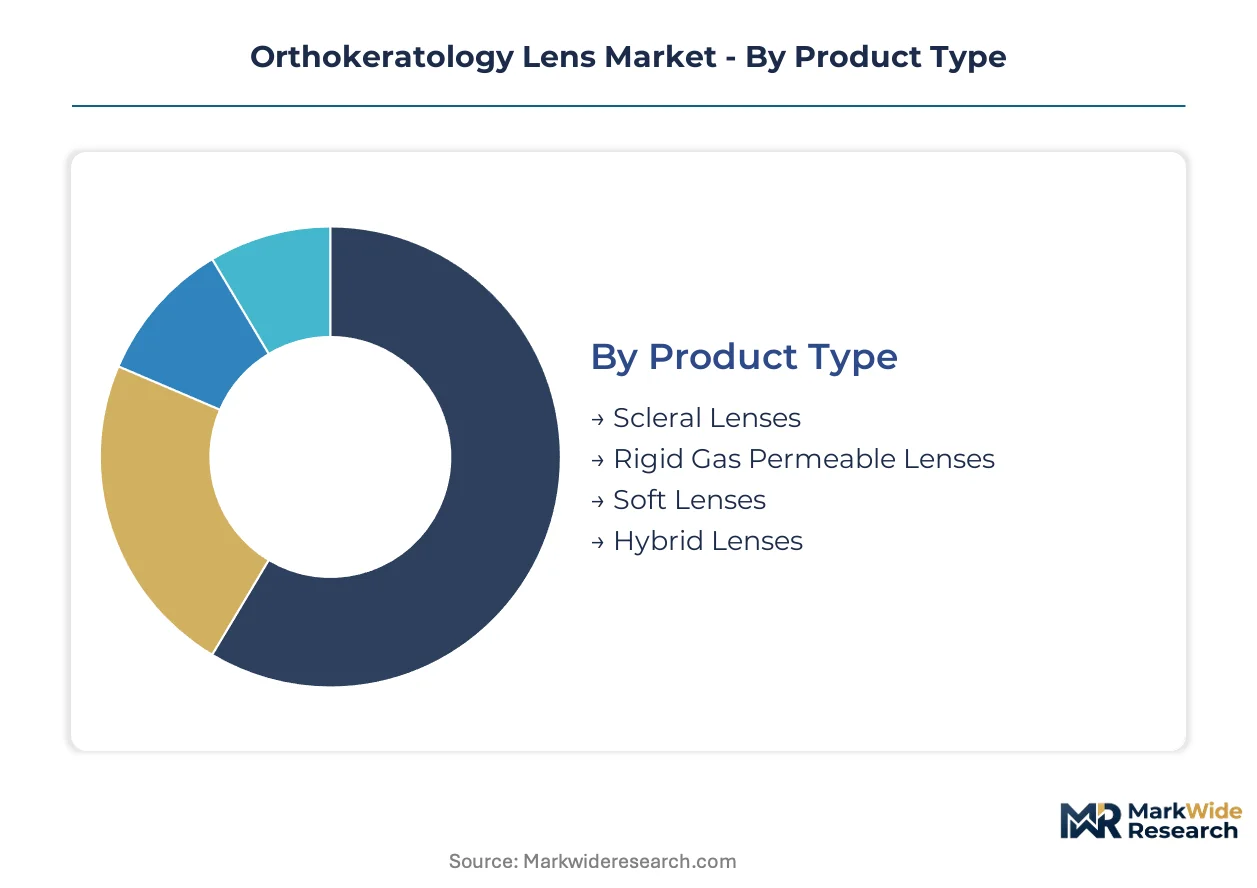
Orthokeratology lens segmentation reveals distinct service intensity requirements across product categories, with fitting complexity and follow-up cadence varying dramatically by lens design. Reverse-geometry RGP products demand intensive practitioner support, while distribution channel choice determines reorder friction and patient retention economics.
Product Type:
After-sales service intensity escalates with corneal molding precision requirements, creating divergent margin structures across lens architectures.
- Rigid Gas Permeable Lenses:Fluorosilicone acrylate or fluorocarbon materials with Dk/t values exceeding 100 enable overnight epithelial reshaping through reverse-geometry curvature profiles. Pediatric myopia protocols in Shanghai, Seoul, and Tokyo drive demand concentration, where 18-24 month replacement cycles compress diagnostic inventory costs for practices.
- Scleral Lenses:Large-diameter designs vaulting over the cornea to rest on the sclera require specialized impression-based fitting and frequent saline exchange monitoring. Irregular cornea patients and severe dry eye populations in German and US specialty clinics generate the primary demand pull.
- Hybrid Lenses:RGP center with soft skirt periphery reduces adaptation discomfort for new orthokeratology candidates.
- Soft Lenses:Limited orthokeratology efficacy due to insufficient molding force; niche daytime wear applications only.
By volume, Rigid Gas Permeable Lenses lead. By growth pace, Scleral Lenses are expanding most quickly.
Application:
Clinical reimbursement pathways and parental willingness-to-pay create tiered pricing power across therapeutic indications.
- Myopia Control:Pediatric overnight corneal reshaping to slow axial elongation now commands the largest addressable patient pool. China's Ministry of Education screening mandates channel myopic students toward orthokeratology clinics in Beijing, Shanghai, and Shenzhen.
- Astigmatism Correction:Toric reverse-geometry designs address corneal irregularity through meridian-specific curvature adjustments. Adult athletes and military personnel in South Korea and Singapore seek lens-free daytime vision for occupational requirements.
- Presbyopia Treatment:Multifocal orthokeratology for presbyopic myopes remains technically challenging with limited practitioner adoption.
- Vision Enhancement:Elective performance optimization for non-pathological refractive error carries discretionary purchase risk.
Myopia Control generates dominant revenue share. Astigmatism Correction is climbing the fastest.
End User:
Practitioner certification depth and capital equipment requirements fragment the fitting base across clinical settings.
- Optometrists:Primary fitting gatekeepers in North American and European markets, with 40-60 hour supervised certification requirements limiting qualified practitioner supply. Private practice optometrists in US suburban markets build recurring revenue through annual membership models covering lenses and follow-up visits.
- Ophthalmologists:Hospital-based pediatric departments in East Asia drive high-volume myopia control programs with integrated topography systems.
- Clinics:Dedicated myopia control centers in Indian metro areas are emerging as training hubs for newly certified orthokeratologists.
- Retail Stores:China's specialized optical chains capture over half of new fittings in tier-one cities through aggressive marketing.
Optometrists handle the highest fitting volume. Retail Stores are gaining share fastest.
Distribution Channel:
Channel selection determines patient acquisition cost and replacement lens friction, with digital penetration concentrated among established wearers.
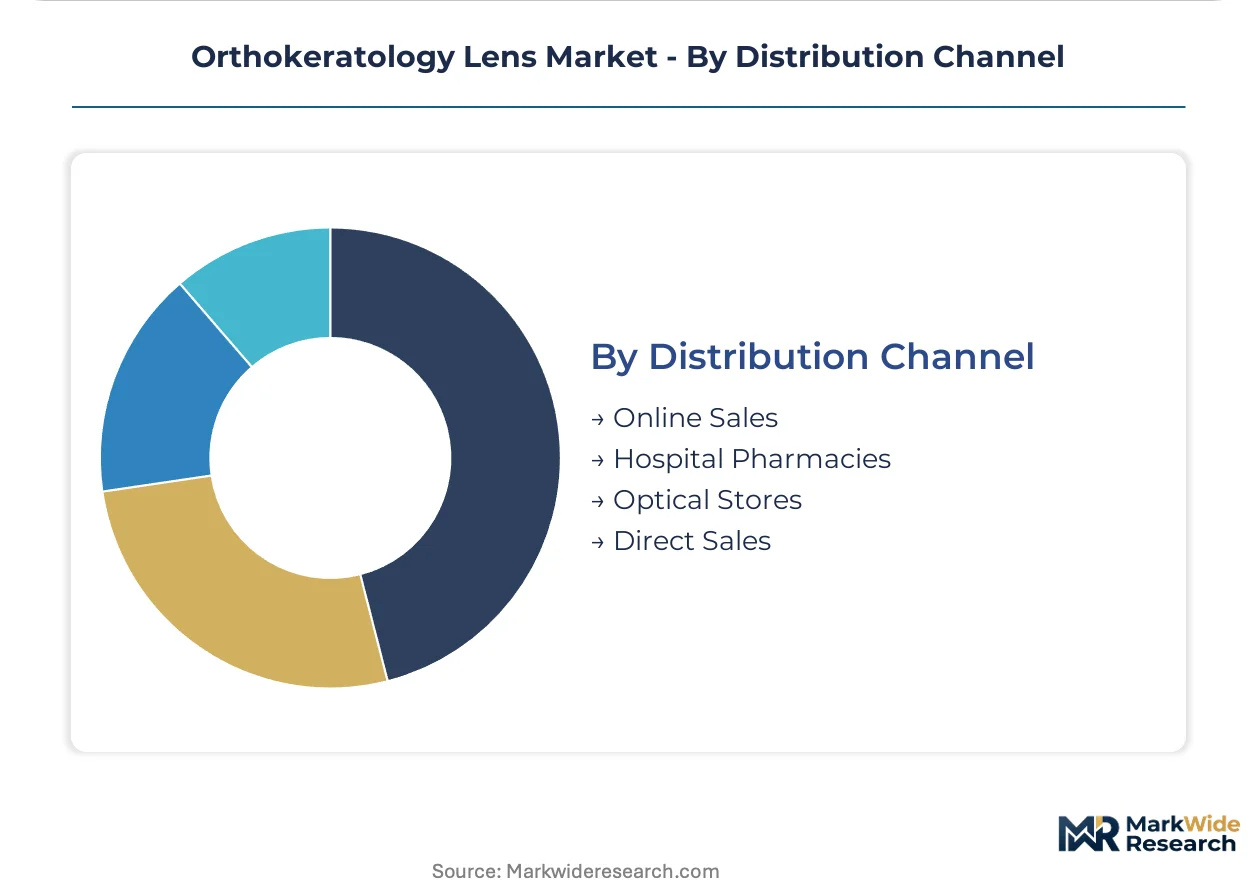
- Optical Stores:Specialized fitting suites with corneal topography equipment capture the majority of initial consultations. Japanese and South Korean retail chains invest in dedicated orthokeratology zones with trained consultants.
- Hospital Pharmacies:Tertiary eye hospital dispensing maintains prescriber control over lens selection and follow-up scheduling.
- Direct Sales:Manufacturer-to-practitioner relationships dominate high-Dk RGP material distribution, with Menicon and Bausch & Lomb maintaining dedicated technical field forces.
- Online Sales:Replacement lens reorders among established wearers bypass clinical channels, though initial fitting requires physical examination.
Optical Stores lead by transaction volume. Online Sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA medical device registration requirements and ISO 18369 compliance protocols anchor orthokeratology lens commercialization pathways across China's tier-one cities, where pediatric myopia screening mandates channel demand toward certified practitioners.
China
Beijing, Shanghai, and Shenzhen concentrate over half of domestic orthokeratology fittings through specialized optical chains with dedicated corneal topography suites. NMPA Class III medical device registration requires clinical trial submissions for new lens designs, extending time-to-market for domestic manufacturers. The Yangtze River Delta cluster hosts precision lens laboratories serving both domestic brands and multinational supply chains.
United States
FDA 510(k) premarket notification pathways define material biocompatibility and dimensional tolerance thresholds for overnight wear devices. Suburban optometry practices in California, Texas, and Florida build recurring revenue through annual membership models covering lenses and follow-up visits. The FDA's streamlined orthokeratology device reviews encourage domestic manufacturers to enter the market with novel fluorosilicone acrylate formulations.
Japan
METI industrial standards and PMDA medical device regulations govern high-Dk rigid gas permeable material manufacturing. Nagoya-based precision manufacturers supply fluorocarbon-silicone copolymers to lens laboratories across Asia-Pacific. Tokyo and Osaka pediatric ophthalmology departments drive adoption of wavefront-guided custom orthokeratology designs with 18-24 month replacement cycles.
Germany
EU Medical Device Regulation Class IIb classification for extended-wear orthokeratology intensifies notified body scrutiny of clinical evidence packages. Bavarian and Baden-Württemberg specialty clinics serve irregular cornea patients with scleral lens vault designs requiring impression-based fitting. German chemical producers control high-purity fluorinated monomer output, exposing lens manufacturers to input allocation constraints.
South Korea
MFDS medical device approval pathways and national myopia control guidelines shape practitioner certification requirements. Seoul Capital Area ophthalmology chains aggressively market overnight corneal reshaping to affluent parents of school-age children. Busan-Ulsan manufacturing clusters produce reverse-geometry lens designs for export across Southeast Asian markets.
Orthokeratology Lens Market Key Industry Players
Established optical multinationals and specialized rigid gas permeable manufacturers split the market into technology-led and precision-manufacturing archetypes. The vendor base concentrates around companies with captive high-Dk material supply chains and dedicated practitioner training infrastructures. Three strategic archetypes dominate: integrated eye care conglomerates with broad distribution reach, precision lens laboratories focused on custom topography-guided designs, and regional specialists serving price-sensitive secondary markets. Competitive intensity centers on practitioner certification program expansion and ISO 18369-2 compliant manufacturing capacity additions.
Among integrated eye care conglomerates, Bausch & Lomb Incorporated and Johnson & Johnson Vision Care, Inc. represent the technology-led archetype with established North American practitioner relationships. Menicon Co., Ltd. exemplifies the precision-manufacturing archetype through its position in high-Dk fluorosilicone acrylate material production for overnight wear applications. CooperVision occupies a hybrid position, combining direct-to-practitioner training investments with broad geographic coverage across certified orthokeratologist networks.
| Leading Market Players |
|---|
| Bausch & Lomb Incorporated |
| Johnson & Johnson Vision Care, Inc. |
| CooperVision |
| Menicon Co., Ltd. |
| Euclid Systems Corporation |
| Alpha Corporation |
| Brighten Optix |
| Art Optical Contact Lens, Inc. |
| TruForm Optics, Inc. |
| Others |
Cost & Logistics Intelligence
Japanese and German chemical producers' grip on high-purity fluorinated monomer output funnels margin capture toward upstream material suppliers, leaving independent lens laboratories exposed to allocation-driven cost volatility. This concentration forces downstream pricing stratification between multinational conglomerates with captive supply and smaller fabricators purchasing spot market monomers.
Pricing Analysis
Geographic price spreads of 40-60% separate China's tier-one city clinics from secondary market optometrists in India and Southeast Asia. Three-tier pricing structure across premium wavefront-guided custom designs, standard diagnostic-fitted lenses, and economy empirical fitting sets dominates the market. Price differentiation hinges on ISO 18369-2 certification grade and bundled after-sales service intensity. Cost compression in the economy tier is intensifying because independent laboratories struggle to finance sub-micron lathe technology. Parental purchasers in East Asian hospital pharmacies show lowest price sensitivity, while Indian retail chain patients exhibit highest elasticity.
Supply Chain Analysis
Nagoya-based precision manufacturers and Bavarian specialty chemical houses hold dominant contract-manufacturing capacity for high-Dk fluorosilicone acrylate materials. Lens fabrication draws from Japanese fluorocarbon-silicone copolymer output, German fluorinated monomer feedstocks, and Chinese precision lathe machining clusters. Single-source vulnerability concentrates in the 80% monomer supply share held by two national producer bases. Distribution runs through manufacturer-to-practitioner direct relationships for initial fitting sets, with online channels capturing replacement lens reorders among established wearers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthokeratology lens economics increasingly resemble a service-attach model, where annual membership programs covering topography monitoring and lens replacement expand faster than per-unit hardware transactions. This recurring-revenue layer now commands disproportionate strategic attention from vendor planning teams.
For Market Incumbents: Entrench practitioner loyalty through expanded certification program capacity in underserved secondary markets, countering LASIK substitution threats with myopia control outcome guarantees. Backward integration into fluorosilicone acrylate material production insulates margin pools from Japanese-German monomer allocation constraints. Channel control via exclusive fitting suite partnerships with China's specialized optical chains limits competitor access to the highest-value patient acquisition funnel. For New Entrants and Emerging Players: Build out digital topography-sharing platforms targeting India's underpenetrated pediatric segment, where Mumbai and Delhi private ophthalmology chains seek remote fitting support. White-space opportunity concentrates in cloud-based corneal mapping tools that reduce geographic barriers between rural optometrists and specialized lens laboratories. Direct-to-practitioner training investments accelerate certification velocity where 40-60 hour supervised requirements currently throttle qualified fitter supply. For Investors and Strategic Acquirers: Capital is best deployed toward precision-manufacturing specialists with ISO 18369-2 compliant sub-micron lathe capacity and established CE-marked portfolios under the EU Medical Device Regulation. Long-term viability over a 5-10 year horizon favors vendors with captive high-Dk material supply chains and dedicated technical field forces. Signal to monitor: NMPA Class III registration approval velocity for domestic Chinese manufacturers, which would signal competitive intensity inflection in the largest addressable market.| Strategic Initiative | Industry Significance |
|---|---|
| Practitioner Certification Program Expansion | Accelerates qualified fitter supply in secondary markets where 40-60 hour training requirements currently limit adoption. |
| High-Dk Material Backward Integration | Captures margin pools currently retained by Japanese and German fluorinated monomer suppliers. |
| Wavefront-Guided Custom Design Launch | Displaces empirically fitted diagnostic lens sets that dominated clinical practice for two decades. |
| Cloud-Based Topography Platform Integration | Reduces geographic barriers between specialized Nagoya laboratories and rural optometrists. |
| EU MDR Class IIa Pathway Acceleration | Streamlines conformity assessment for daily-wear designs amid intensified Class IIb scrutiny. |
Research Approach
Desk research of FDA 510(k) filings, NMPA Class III registration databases, ISO 18369 compliance records, and East Asian school screening policy documents preceded structured interviews with orthokeratology-certified optometrists, pediatric ophthalmology department heads, lens laboratory technical directors, and optical chain procurement managers. Bottom-up and top-down triangulation validated patient volume estimates against fluorosilicone acrylate material consumption patterns.
Assumptions around NMPA registration timelines, ISO 18369-2 dimensional tolerance compliance rates, and East Asian school screening mandate enforcement were held fixed across baseline scenarios, while fluorinated monomer price volatility and LASIK substitution elasticities were varied in sensitivity runs. Segmentation modeling incorporated product type, application indication, end-user certification depth, and distribution channel friction. CAGRs were derived from fitted growth curves anchored to disclosed practitioner certification velocities and replacement cycle compression trends.
Stress conditions across fluorosilicone monomer supply disruptions, EU MDR notified body backlog extensions, and LASIK technology cost reductions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including regulatory reclassification and substitute technology acceleration. Quarterly review of NMPA approval cadence, practitioner certification throughput, and monomer allocation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Indonesia Devices Market
Medical Devices
Neurovascular Catheters Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Global Bone Tumor Ablation Devices Market
Medical Devices
Global Portable Oxygen Concentrators Market
Medical Devices
Steerable Needles Market
Medical Devices
Ultrasound Stimulator Market
Medical Devices
Digital Medical Thermometers Market
Medical Devices
Self-Injections Market
Medical Devices
Germany Drug Delivery Devices Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
Global Soft Tissue Allografts Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Global Trauma Fixation Devices Market