
 Peripheral Guidewires Market | 2026-2036
Peripheral Guidewires Market Size, Share, and Industry Trends Forecast 2026-2036
Peripheral Guidewires Market Outlook
Modular guidewire configurations paired with single-use accessory kits is restructuring how cath labs evaluate total procedure economics. Boston Scientific Corporation leverages its integrated ecosystem to bundle guidewires with complementary devices, sustaining premium positioning across hospital systems. Abbott Laboratories anchors its competitiveness through nitinol metallurgy expertise, while Asahi Intecc specializes in torque-response engineering for complex lesion navigation.
Peripheral guidewires are elongated, flexible instruments typically constructed from nitinol or stainless steel cores with hydrophilic or hydrophobic polymer coatings, designed to traverse tortuous vascular anatomy and deliver therapeutic devices to target lesions. Hydrophilic guidewires dominate procedural preference for chronic total occlusions due to their low-friction surface properties, whereas stiff guidewires command margin pools in heavily calcified anatomy where support and pushability determine outcomes. Cardiology applications lead absolute consumption volumes, though gastroenterology and neurology represent faster-growing addressable spaces as interventional techniques migrate beyond traditional vascular territories.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements impose escalating biocompatibility and sterilization validation burdens on coated guidewire submissions, compressing development timelines for smaller manufacturers. Japan's PMDA and China's NMPA maintain distinct coating chemistry disclosure standards that fragment regulatory harmonization efforts. Stakeholders must monitor evolving notified body capacity constraints in Europe and anticipate how FDA guidance on lubricious coatings may reshape competitive differentiation in the coming regulatory cycle.
Market Dynamics
Hospital cath labs are consolidating purchasing authority into centralized value-analysis committees, compressing vendor margins and forcing guidewire manufacturers to bundle accessories into single-SKU procedure kits. This procurement centralization is restructuring how Boston Scientific, Abbott, and Asahi Intecc compete on total cost-per-procedure rather than unit price.
Growth Catalysts
- Chronic Total Occlusion Procedural Volume:Cardiology departments in the United States, Germany, and Japan are expanding dedicated CTO programs. Hydrophilic guidewire consumption tracks directly to these lab expansions.
- EU MDR Harmonization:The Medical Device Regulation's standardized coating biocompatibility testing is reducing redundant country-by-country submissions for manufacturers with notified body partnerships in Germany or the Netherlands.
- Nitinol Metallurgy Advances:Shape-memory alloy processing improvements are yielding guidewires with superior torque response and kink resistance. Complex lesion navigability is expanding treatable patient populations.
Market Restraints
- Nitinol Raw Material Concentration:Premium-grade nitinol wire drawing capacity concentrates among a handful of specialized metallurgical suppliers in the United States and Japan. Input cost volatility transmits directly to guidewire manufacturing economics.
- FDA 510(k) Documentation Burden:Lubricious coating chemistry disclosure requirements have intensified, extending premarket notification preparation timelines for smaller manufacturers without dedicated regulatory affairs infrastructure.
- Polymer Coating Technical Limitations:Hydrophilic surface durability remains constrained by delamination risk in heavily calcified anatomy. This limits guidewire reusability and drives per-procedure consumption.
Strategic Opportunities
- Neurology Interventional Migration:Mechanical thrombectomy and intracranial stenting procedures are creating addressable demand for micro-guidewires with distal flexibility profiles unmatched by current neurovascular portfolios.
- Japan PMDA Fast-Track Pathway:The Sakigake designation for breakthrough devices offers abbreviated review timelines for guidewires with novel torque-transmission architectures. Early entrants capture premium positioning in Tokyo and Osaka academic centers.
- Single-Use Accessory Kit Bundling:Cath lab administrators are consolidating vendor relationships. Manufacturers with in-house production of introducers, needles, and exchange systems can construct proprietary ecosystems that lock out component competitors.
Industry Challenges
- Coating Chemist Talent Scarcity:Formulation expertise for biocompatible hydrophilic polymers resides in a narrow cohort of specialists with experience in both medical device and pharmaceutical surface science. Recruitment competition intensifies as EU MDR technical documentation demands expand.
- Legacy Sterilization Infrastructure:Ethylene oxide sterilization capacity constraints in the United States are forcing guidewire manufacturers to validate alternative terminal sterilization methods or absorb extended logistics timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peripheral Guidewires Market |
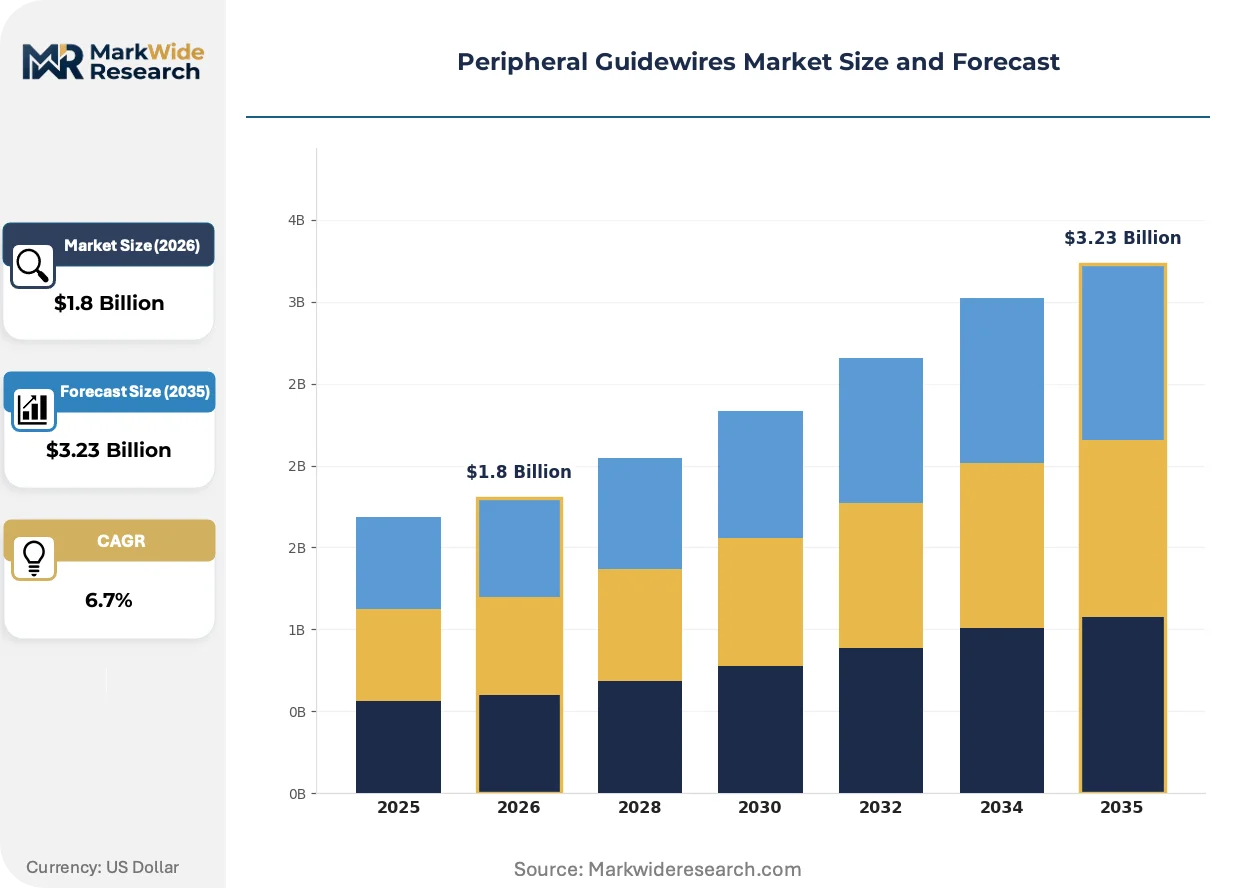
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrophilic Guidewires, Pushable Guidewires, Coated Guidewires, Stiff Guidewires End User: Clinics, Hospitals, Surgical Centers, Research Institutions Material: Nitinol, Stainless Steel, Polymer, Coatings Application: Cardiology, Urology, Neurology, Gastroenterology |
| Companies Covered | Terumo Corporation, Cook Medical, Boston Scientific Corporation, Teleflex Incorporated, Merit Medical Systems, Abbott Laboratories, Asahi Intecc, B. Braun Melsungen AG, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peripheral Guidewires Market Strategic Shifts
Guidewire architecture is fragmenting into application-specific designs as interventional techniques migrate beyond coronary and peripheral vascular territories. Manufacturers are engineering distinct torque-response profiles for renal, carotid, and below-the-knee anatomies rather than adapting universal platforms.
Polymer-sheathed nitinol core technology is expanding into gastroenterology and urology interventional suites. ERCP and percutaneous nephrostomy specialists are adopting hydrophilic-coated guidewires originally developed for peripheral vascular applications. This cross-specialty adoption is compressing the addressable market for legacy stainless steel biliary wires and forcing incumbent suppliers to defend installed base through conversion pricing.
FDA guidance on lubricious coating biocompatibility is tightening documentation standards for 510(k) submissions. The agency's 2023 safety communication on coating particulate generation has triggered retrospective testing obligations for marketed devices. Peripheral guidewire portfolios with hydrophilic polymer surfaces face the highest compliance burden, particularly those with silicone or polyethylene oxide chemistries manufactured before 2020.
Hospital value-analysis committees are consolidating purchasing authority across interventional service lines. Cardiology, radiology, and vascular surgery departments in United States health systems are ceding independent procurement autonomy to centralized supply chain functions. This concentration is privileging vendors with broad portfolio breadth and penalizing niche guidewire specialists dependent on physician preference item status.
Peripheral Guidewires Market Segmentation
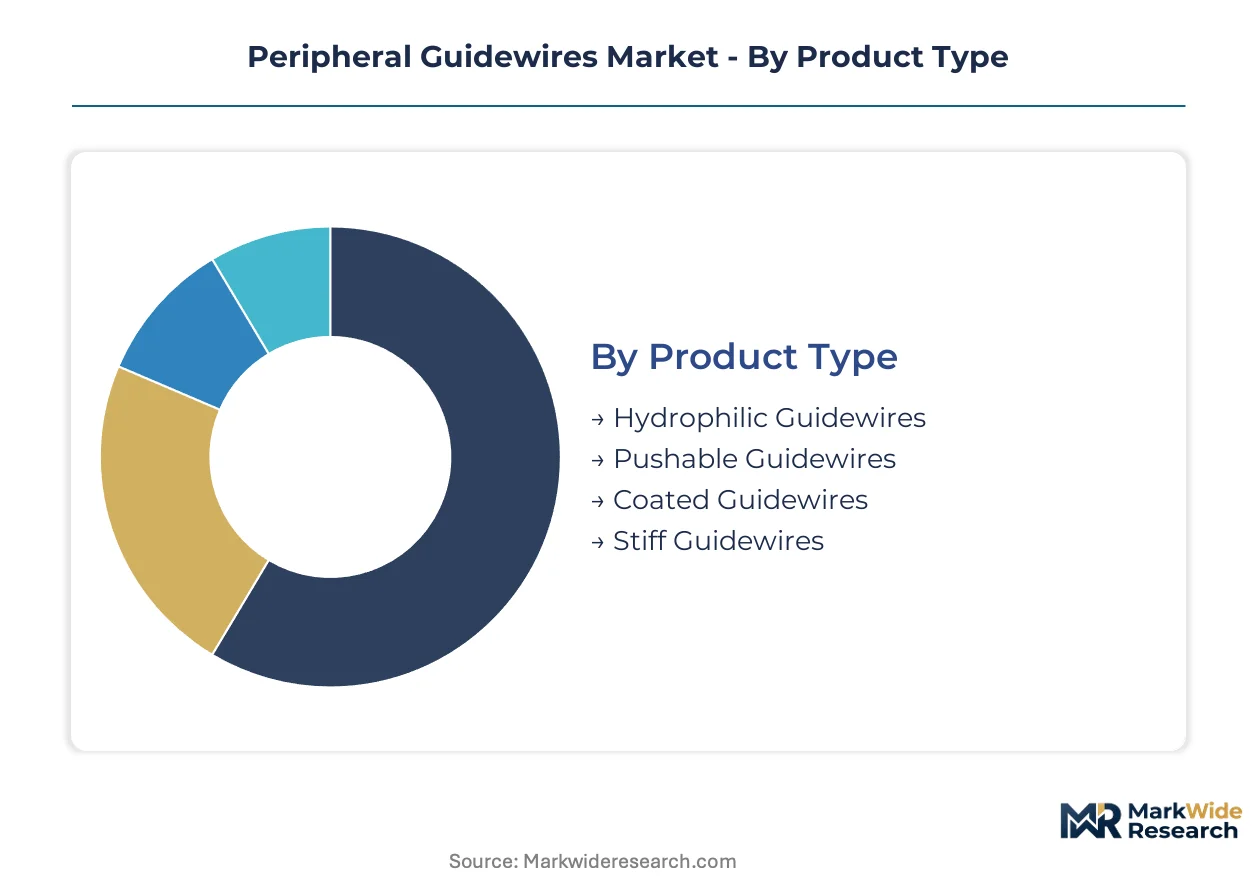
Guidewire segmentation reveals how regulatory burden, material science, and clinical application intersect to determine manufacturing complexity and commercial priority. Manufacturers must align certification pathways with the specific performance demands of each segment category.
Product Type:
FDA 510(k) clearance timelines vary substantially across coating chemistries, with hydrophilic polymers facing intensified biocompatility documentation requirements under recent agency guidance.
- Hydrophilic Guidewires:These devices incorporate polyethylene oxide or silicone-based surface layers that activate upon saline contact to reduce friction coefficients. Cardiology departments in the United States, Germany, and Japan prioritize these for chronic total occlusion programs where lesion crossing success depends on lubricity. FDA's coating particulate generation safety communication has imposed retrospective testing obligations on legacy hydrophilic portfolios.
- Stiff Guidewires:Constructed with reinforced nitinol cores and minimal polymer overlay, these instruments deliver the pushability and support required for calcified arterial segments. Demand concentrates in heavily calcified below-the-knee procedures where device delivery platform stability determines procedural outcomes. EU MDR technical documentation for stiff variants emphasizes core material fatigue testing over surface chemistry validation.
- Pushable Guidewires:Stainless steel or nitinol shafts with basic polymer jackets serve routine diagnostic catheter exchanges and standard interventional access.
- Coated Guidewires:Hydrophobic silicone or PTFE surface treatments target specific anatomical navigational challenges without full hydrophilic activation requirements.
Leading the category by volume: Hydrophilic Guidewires. Growing fastest: Stiff Guidewires.
End User:
Procurement authority consolidation is restructuring how each customer type evaluates total procedure economics rather than unit acquisition cost.
- Hospitals:Academic medical centers and community hospital systems in the United States operate centralized value-analysis committees that bundle guidewire purchasing across cardiology, radiology, and vascular surgery service lines. These institutions demand single-SKU procedure kits combining guidewires with introducers and exchange systems. FDA 510(k) clearance documentation must satisfy hospital credentialing committees that scrutinize coating biocompatibility data.
- Surgical Centers:Ambulatory surgical facilities concentrate on high-volume peripheral vascular and endoscopic procedures where rapid turnover favors disposable guidewire platforms over reprocessing protocols. Medicare reimbursement dynamics in the United States favor same-day discharge procedures that deploy cost-optimized guidewire configurations.
- Clinics:Office-based interventional suites in cardiology and urology represent emerging demand nodes for diagnostic-grade guidewires.
- Research Institutions:Academic research hospitals in Tokyo and Osaka leverage Japan's PMDA Sakigake fast-track pathway to evaluate novel torque-transmission architectures in first-in-human protocols.
Volume concentration: Hospitals. Steepest expansion trajectory: Surgical Centers.
Material:
Raw material sourcing geography directly shapes supply security and input cost volatility for finished guidewire manufacturers.
- Nitinol:Nickel-titanium shape-memory alloys processed through specialized wire drawing yield superior torque response and kink resistance compared to conventional metals. Premium-grade nitinol capacity concentrates among metallurgical suppliers in the United States and Japan, transmitting raw material cost volatility directly to guidewire manufacturing economics. PMDA and FDA submissions for nitinol-based devices require extensive fatigue and corrosion validation protocols.
- Stainless Steel:304V and 316LVM grades provide cost-effective alternatives for diagnostic applications and standard interventional access where shape-memory properties offer limited incremental value. Chinese and Indian stainless steel producers supply commoditized wire stock that bypasses the supply concentration risks affecting nitinol procurement.
- Polymer:Pebax and nylon jacket materials determine distal flexibility profiles and lesion navigability in tortuous anatomy.
- Coatings:Hydrophilic polymer formulation expertise resides in a narrow specialist cohort with cross-disciplinary medical device and pharmaceutical surface science experience.
Dominant by revenue: Nitinol. Gaining share fastest: Coatings.
Application:
Clinical migration of interventional techniques beyond traditional vascular territories is fragmenting guidewire architecture into anatomy-specific designs.
- Cardiology:Coronary and peripheral vascular procedures consume the largest absolute guidewire volumes, with chronic total occlusion interventions driving hydrophilic platform preference. Cardiology departments in Germany maintain dedicated CTO programs that standardize on specific torque-response profiles. EU MDR conformity assessment for cardiology guidewires prioritizes coating durability validation under cyclic loading conditions.
- Neurology:Mechanical thrombectomy and intracranial stenting procedures demand micro-guidewires with distal flexibility profiles unmatched by current neurovascular portfolios. Tokyo academic centers are early adopters of novel torque-transmission architectures through Japan's PMDA Sakigake pathway. Neurology applications represent the steepest expansion trajectory as interventional techniques migrate into intracranial territories.
- Gastroenterology:ERCP and percutaneous nephrostomy specialists are adopting hydrophilic-coated guidewires originally developed for peripheral vascular applications.
- Urology:Percutaneous nephrostomy and ureteral access procedures utilize polymer-sheathed nitinol cores adapted from vascular platforms.
Highest procedural volume: Cardiology. Expanding most quickly: Neurology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guidewire manufacturing concentrates in Japan and the United States where nitinol metallurgy expertise resides, while procedural consumption clusters in aging Western European and North American hospital systems. This production-consumption divide shapes regional competitive dynamics.
United States
Academic medical centers in Boston and Cleveland operate dedicated chronic total occlusion programs that standardize on hydrophilic platform configurations. FDA's 2023 safety communication on coating particulate generation imposes retrospective testing obligations on legacy portfolios. Minneapolis and Irvine host the headquarters of diversified device conglomerates that bundle guidewires into single-SKU procedure kits for hospital value-analysis committees.
Germany
Rhineland university hospitals maintain specialized CTO intervention units that drive demand for torque-responsive nitinol architectures. EU MDR technical documentation requirements for coating biocompatibility testing concentrate notified body partnerships in Berlin and Munich. The Baden-Württemberg industrial corridor hosts precision metallurgical suppliers that draw premium-grade nitinol wire for guidewire cores.
Japan
Tokyo and Osaka academic centers leverage PMDA's Sakigake fast-track designation to evaluate novel torque-transmission architectures in first-in-human protocols. Japan's aging demographic sustains high procedural volumes for peripheral vascular interventions. Aichi Prefecture hosts specialized wire-drawing facilities that supply shape-memory alloy components to domestic and export markets.
China
Shanghai and Beijing hospital systems are expanding interventional cardiology departments to address rising peripheral artery disease prevalence. NMPA maintains distinct coating chemistry disclosure standards that fragment regulatory harmonization with FDA and EU pathways. The Yangtze River Delta hosts domestic guidewire manufacturers that compete on cost-optimized stainless steel platforms for diagnostic applications.
India
Mumbai and Delhi NCR medical centers are adopting hydrophilic-coated guidewires for peripheral interventions as interventional cardiology training expands. CDSCO regulatory submissions for coated devices require biocompatibility validation protocols adapted from FDA guidance. The Karnataka medical device cluster in Bengaluru hosts contract manufacturers that assemble guidewire components for export markets.
Peripheral Guidewires Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies into three layers: multinational device ecosystems with broad interventional portfolios, mid-cap specialists with metallurgical or coating expertise, and regional assemblers serving cost-sensitive diagnostic segments. Strategic moves center on bundling guidewires into procedure kits and securing notified body partnerships for EU MDR conformity. Capacity expansion in nitinol wire drawing and coating formulation facilities represents the second dominant competitive vector.
Within the diversified ecosystem tier, Boston Scientific Corporation and Abbott Laboratories anchor competitive positioning through integrated portfolio breadth and metallurgical expertise respectively. Asahi Intecc occupies a specialist position emphasizing torque-response engineering for complex lesion navigation. These three companies exemplify how scale-driven bundling capabilities and technical specialization create distinct competitive moats in a market where hospital procurement centralization privileges vendors with comprehensive interventional platforms.
| Leading Market Players |
|---|
| Terumo Corporation |
| Cook Medical |
| Boston Scientific Corporation |
| Teleflex Incorporated |
| Merit Medical Systems |
| Abbott Laboratories |
| Asahi Intecc |
| B. Braun Melsungen AG |
| Medtronic |
| Others |
Value Chain & Pricing Dynamics
Captive nitinol wire drawing in Japan and the United States anchors both supply security and premium pricing power for finished guidewire manufacturers serving hospital value-analysis committees. This backward integration into shape-memory alloy processing insulates tier-one vendors from raw material volatility while justifying three-tier pricing structures across premium, standard, and economy certification levels.
Pricing Analysis
Margin tightening in economy-grade stainless steel configurations reflects CDSCO-registered Indian contract manufacturers flooding diagnostic segments with cost-optimized platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance tier and nitinol core fatigue certification. Surgical centers exhibit highest price sensitivity due to Medicare reimbursement compression, while academic medical centers absorb premium hydrophilic platforms for chronic total occlusion programs.
Supply Chain Analysis
Japan's domestic-content incentives for PMDA Sakigake-designated devices are reshaping sourcing toward Aichi Prefecture wire-drawing facilities and away from U.S. metallurgical suppliers. Premium-grade nitinol, hydrophilic polymer formulations, and Pebax jacket materials draw from concentrated Japanese and American specialty chemical producers. Single-source vulnerability in ethylene oxide sterilization capacity forces validation of alternative terminal methods. Distribution runs through diversified device conglomerates bundling guidewires into single-SKU procedure kits for hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nitinol wire drawing capacity scarcity props pricing across all tiers, constraining volume expansion for manufacturers without captive metallurgical supply or qualified Japanese supplier partnerships.
For Market Incumbents: Hedge coating chemistry exposure by diversifying hydrophilic polymer formulation partnerships beyond the narrow specialist cohort concentrated in U.S. and German surface science clusters. Accelerate EU MDR notified body capacity reservations in Berlin and Munich before backlog extends conformity assessment timelines. Prioritize backward integration into nitinol wire drawing or exclusive offtake agreements with Aichi Prefecture suppliers to defend margin position against input cost volatility. For New Entrants and Emerging Players: Novel torque-transmission architectures for mechanical thrombectomy applications offer the most penetrable white space, as current neurovascular portfolios lack distal flexibility profiles demanded by Tokyo and Osaka academic centers. Target Japan's PMDA Sakigake fast-track pathway to compress regulatory timelines and establish premium positioning before diversified conglomerates adapt vascular platforms. Pursue clinician-investor partnerships in Japanese academic medical centers to secure first-in-human protocol access and subsequent hospital system adoption. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified device conglomerates seeking to fill neurology guidewire gaps or secure nitinol metallurgy capabilities. Mid-cap specialists with proprietary coating formulation expertise and PMDA Sakigake designations present the highest long-term viability within a five-to-ten-year window. Monitor FDA guidance evolution on lubricious coating biocompatibility documentation as the inflection signal distinguishing acquisition-ready targets from compliance-burdened laggards.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Partnership | Secures conformity assessment capacity in Berlin or Munich before backlog extends certification timelines. |
| Hospital System Bundling Agreement | Locks out component competitors through single-SKU procedure kits combining guidewires with introducers. |
| PMDA Sakigake Designation Pursuit | Abbreviates review timelines for novel torque-transmission architectures in Tokyo academic centers. |
| Nitinol Wire Drawing Capacity Expansion | Captive supply of shape-memory alloy cores insulates manufacturing economics from raw material volatility. |
| Alternative Sterilization Validation | Reduces dependency on constrained ethylene oxide infrastructure through radiation or vaporized hydrogen peroxide protocols. |
Study Parameters
FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract registries formed the secondary backbone for this analysis. Primary interviews with interventional cardiologists, cath lab purchasing committee chairs, biomedical engineers at GPOs, and regulatory affairs leads at notified bodies combined with secondary validation. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market size estimation across the analysis window.
Historical trendline analysis of chronic total occlusion procedural volumes, coating chemistry regulatory filing patterns, and nitinol raw material pricing informed projection mechanics. The analytical framework segmented by product type, end user, material composition, and application with regional regulatory cluster as an additional modeling dimension. CAGRs derived from weighted average of procedure volume growth and price trajectory assumptions incorporating EU MDR compliance cost pass-through and Japan PMDA fast-track adoption curves.
Several conditions sit outside the modeled scope, including unforeseen FDA guidance revisions on lubricious coating particulate generation, notified body insolvency or capacity collapse in Europe, and trade restriction impacts on nitinol alloy cross-border movement. Forecasts reflect documented assumptions regarding procedural volume continuity and reimbursement stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Disability Devices Market
Medical Devices
Global Electromyography Devices Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Global Ventilators Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Semiconductor Laser Therapeutic Device Market
Medical Devices
Sinus Implants Market
Medical Devices
Interlaminar Device Market
Medical Devices
North America Ablation Devices Market
Medical Devices
Global Prosthetic Heart Valve Market
Medical Devices
Transcatheter Pacing System Market
Medical Devices
Electroencephalography (EEG) Systems Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
Support Surfaces Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Medical Devices Reimbursement Market