
 Asia Pacific Reprocessed Medical Devices Market | 2026-2036
Asia Pacific Reprocessed Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Reprocessed Medical Devices Market Analysis
Japan's PMDA reprocessing guidelines is consolidating the cost-of-entry calculus for foreign device refurbishers seeking market access. Stryker Sustainability Solutions Inc. leverages its established sterilization infrastructure to dominate hospital contract negotiations across Tokyo and Osaka. Medline Industries anchors its regional footprint through dedicated reprocessing facilities serving Australian public health networks. Johnson & Johnson competes on brand trust in endoscope refurbishment, where clinical skepticism remains a barrier.
Reprocessed medical devices are single-use or limited-use instruments restored to functional and sterility specifications through validated cleaning, testing, and repackaging protocols, typically achieving 50-80% cost reduction versus original equipment. Their primary purpose is to lower per-procedure supply costs without compromising clinical outcomes in high-volume surgical and diagnostic settings. Catheters and electrosurgical devices lead product type revenue pools, with endoscopes representing the fastest-growing segment as optical refurbishment techniques advance. Hospitals capture the dominant share of end-user demand, while ambulatory surgical centers emerge as a concentrated growth channel where throughput economics favor reprocessed supplies.
India's CDSCO, Australia's TGA, and Japan's PMDA collectively enforce sterility assurance and traceability standards that determine which reprocessors gain market access across the region. Compliance with these frameworks shapes procurement eligibility, particularly for cardiovascular and surgical instrument applications where patient safety scrutiny intensifies. Stakeholders must monitor regulatory divergence between national frameworks, as harmonization gaps create compliance complexity for multi-country operators.
Market Dynamics
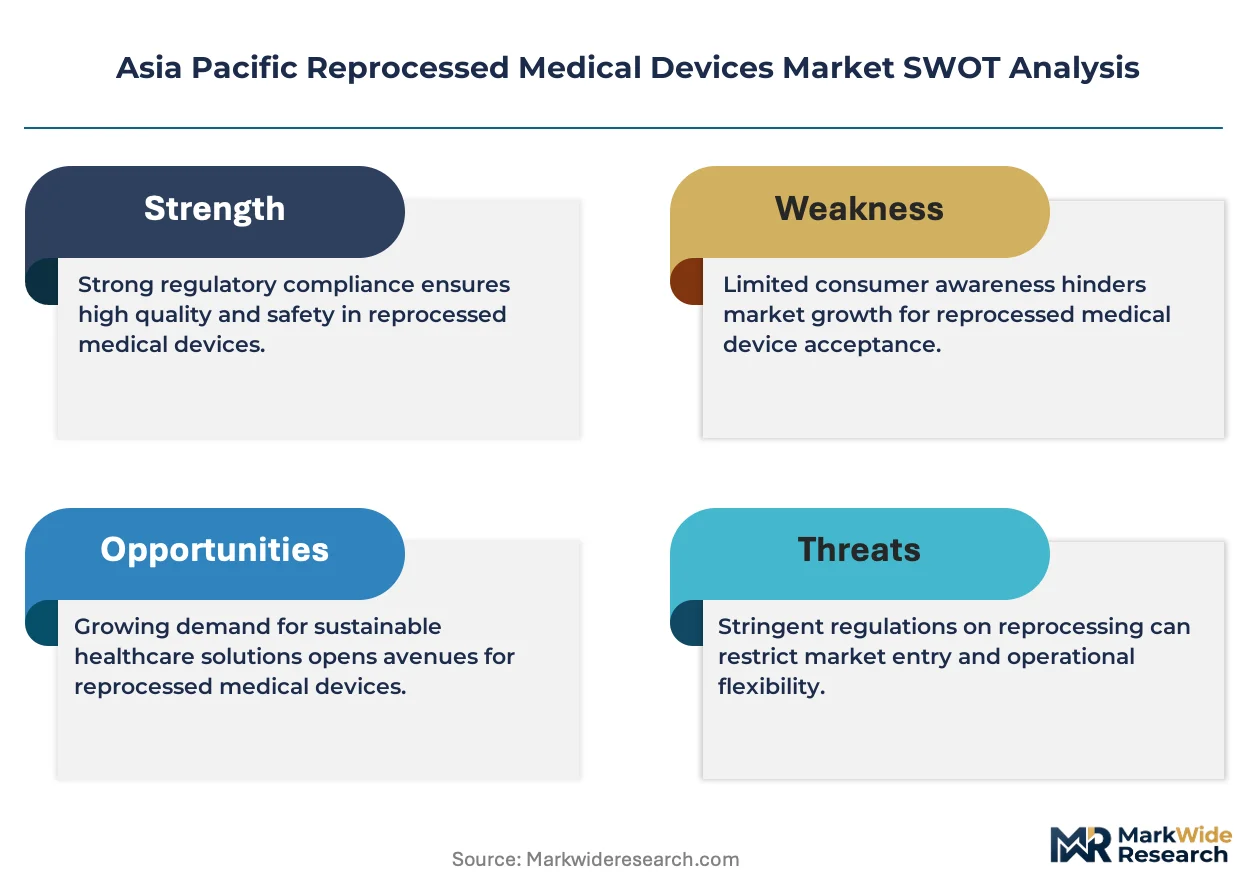
Japan's PMDA reprocessing guidelines and India's CDSCO quality tightening are compressing market access timelines while elevating compliance capital requirements for device refurbishers across the region.
Growth Catalysts
- Cardiovascular catheter demand:India's tertiary hospital networks are expanding catheter reprocessing volumes to offset ballooning procedural supply costs in interventional cardiology suites.
- PMDA guideline harmonization:Japan's sterility assurance protocols are creating procurement eligibility standards that validate reprocessed device quality for risk-averse hospital buyers.
- Optical refurbishment advancement:Endoscope reprocessing capabilities are penetrating Australian public health procurement systems through dedicated facility investments.
Market Restraints
- Traceability infrastructure costs:Multi-country operators face capital intensity from divergent national sterility documentation systems across Japan, Australia, and India.
- Clinical skepticism barriers:Physician resistance to refurbished endoscopes in Japan's premium hospital segment limits volume penetration despite cost advantages.
- Single-use device substitution:Original equipment manufacturers are deploying polymer innovations that shorten device lifecycles and narrow reprocessing windows.
Strategic Opportunities
- Ambulatory surgical center channel:Australia's day-surgery networks present concentrated throughput economics where reprocessed supply contracts deliver margin compression.
- CDSCO compliance tailwind:India's tightened cardiovascular catheter norms are accelerating third-party certification demand from domestic hospital procurement officers.
- Electrosurgical device convergence:Integration of radiofrequency refurbishment with advanced cleaning protocols is opening new device categories for commercialization.
Industry Challenges
- Sterility assurance technician scarcity:Japan and Australia face workforce gaps in validated cleaning protocol execution, extending facility certification timelines.
- Legacy hospital system integration:India's tertiary networks require custom traceability software interfaces to connect reprocessed device tracking with existing inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Reprocessed Medical Devices Market |
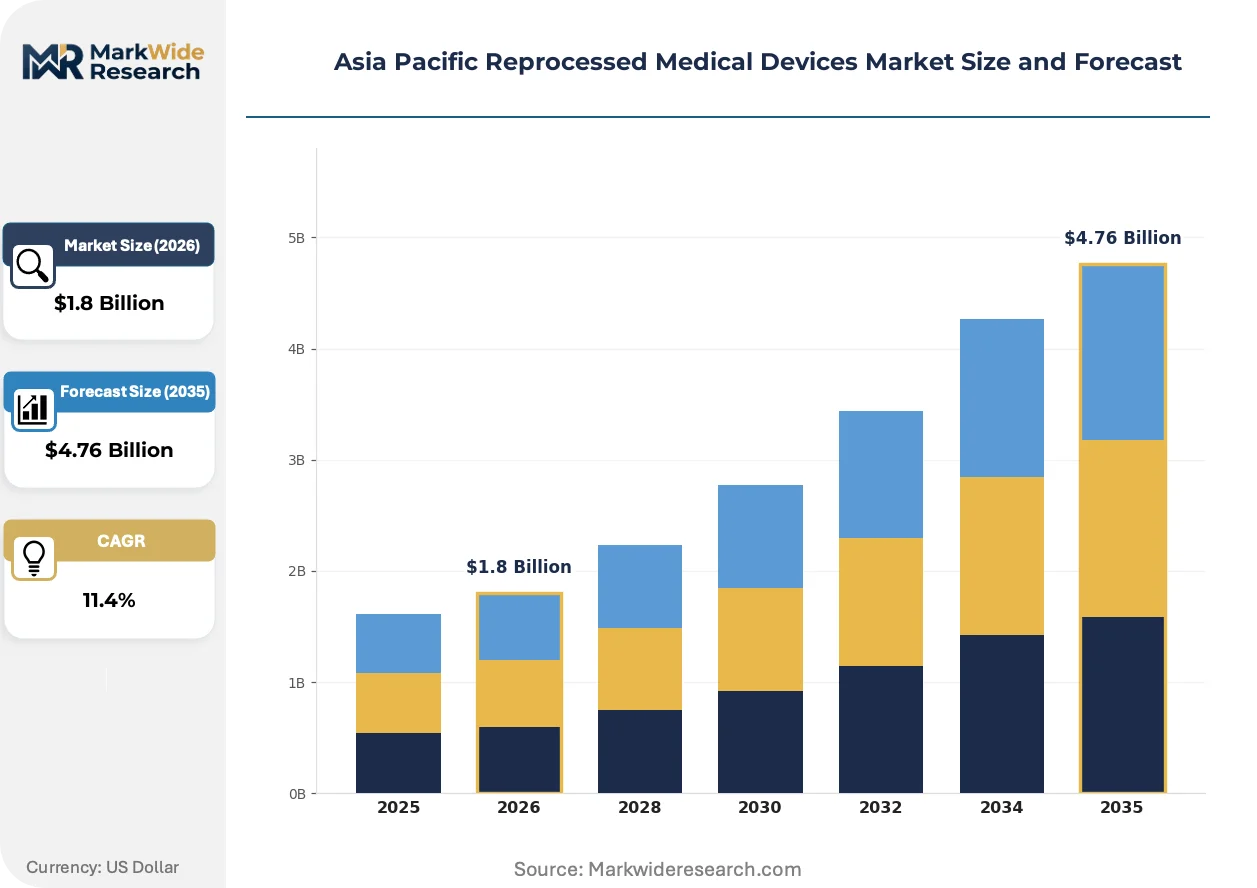
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrosurgical Devices, Catheters, Endoscopes, Surgical Instruments End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Healthcare Technology: Steam Sterilization, Ethylene Oxide, Radiation, Chemical Disinfection Application: Surgery, Diagnostic Procedures, Wound Care, Cardiovascular |
| Companies Covered | Stryker Sustainability Solutions Inc., Medline Industries, Johnson & Johnson, ReNu Medical, Sterilmed, NEScientific, Centurion Medical Products Corporation, Vanguard AG, SureTek Medical, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Reprocessed Medical Devices Market Emerging Trajectories
Plasma-based sterilization systems and automated optical inspection platforms are compressing refurbishment cycle times while expanding device category eligibility beyond traditional boundaries.
Advanced hydrogen peroxide vapor sterilization is decentralizing reprocessing capability from centralized facilities to individual hospital campuses across Australia's public health networks. Queensland and Victoria health systems are piloting in-house catheter refurbishment units that bypass third-party logistics. This capability diffusion is compressing turnaround times from days to hours and enabling just-in-time surgical supply models.
Japan's PMDA issued updated sterility assurance guidelines in 2024 that mandate enhanced endotoxin testing for cardiovascular reprocessed devices. The regulation elevates capital requirements for market entrants while consolidating incumbent positions among established refurbishers. Tokyo and Osaka hospital procurement officers are now requiring PMDA certification documentation as a mandatory bid qualification criterion.
Hospital buying committees across Southeast Asia are consolidating vendor relationships from multi-supplier fragmentation toward single-source reprocessing contracts. Australian state health procurement agencies are leading this concentration, bundling catheter and endoscope refurbishment under multi-year agreements. This behavioral shift is visible most acutely in New South Wales and Victoria, where tender specifications now prioritize volume-scale pricing over unit-cost competition.
Asia Pacific Reprocessed Medical Devices Market Segmentation
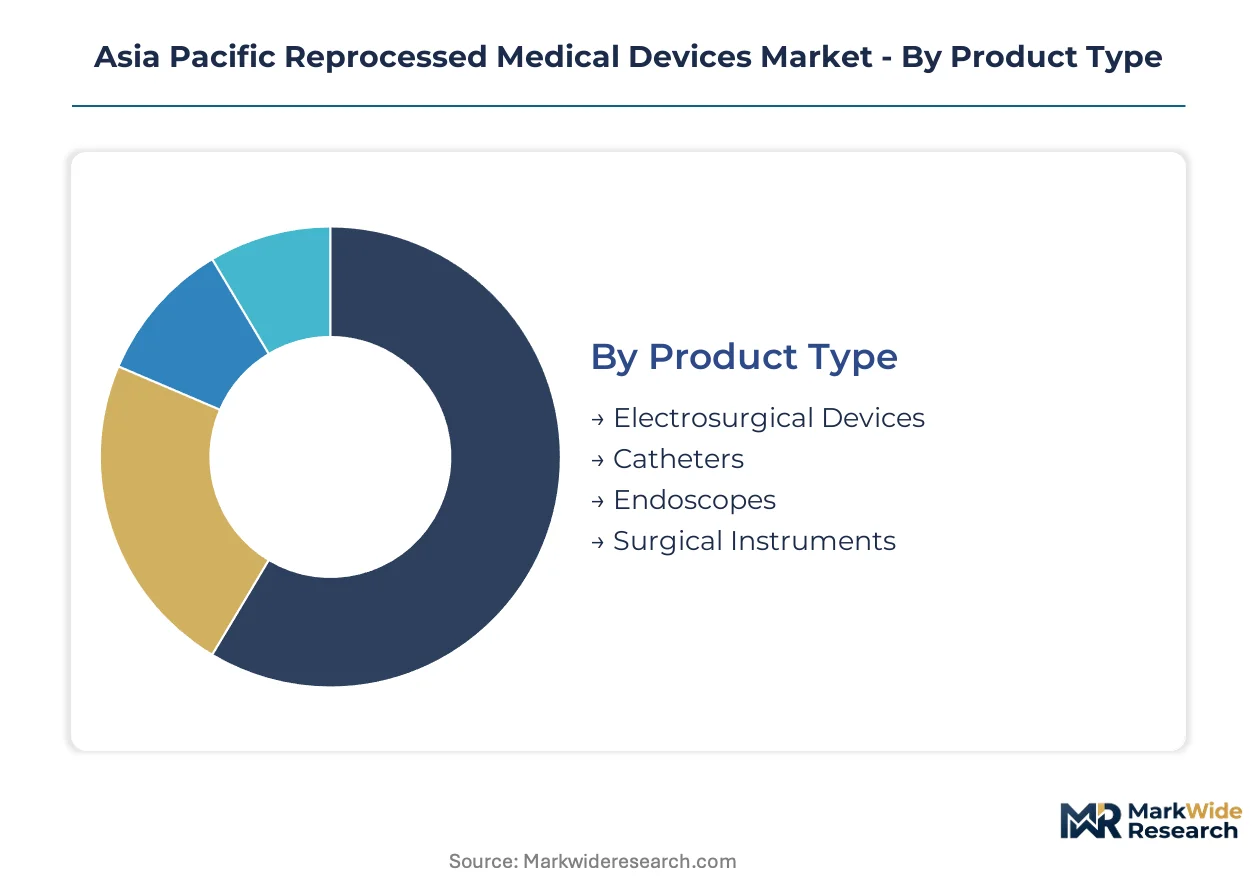
Device reprocessing economics in Asia Pacific diverge sharply by product complexity and sterility assurance requirements. Procurement committees weight capital recovery timelines against regulatory compliance burdens when segmenting vendor contracts across the region's hospital networks.
Product Type:
Cost tier determines contract negotiation leverage, with premium refurbishment commanding stricter certification thresholds than standard reprocessing tiers.
- Catheters:Polymer-based interventional devices undergo validated cleaning and functional testing to restore lumen integrity and sterility assurance. India's tertiary hospital networks concentrate procurement volumes here as CDSCO cardiovascular norms tighten compliance documentation requirements.
- Endoscopes:Optical instrument refurbishment demands advanced borescope inspection and fiber-optic calibration to restore imaging clarity. Australian public health procurement systems are channeling dedicated facility investments into this segment as optical refurbishment techniques advance.
- Electrosurgical Devices:Radiofrequency generators and electrode tips require insulation testing and thermal calibration validation.
- Surgical Instruments:Metallic forceps, scissors, and clamps undergo ultrasonic cleaning and hardness testing for structural integrity restoration.
Catheters lead on scale; endoscopes lead on momentum.
End User:
Volume throughput shapes reprocessing contract economics, with high-procedure environments capturing unit-cost advantages unavailable to low-frequency operators.
- Hospitals:Tertiary medical centers with centralized sterilization departments manage multi-category refurbishment programs across cardiovascular, surgical, and diagnostic suites. Tokyo and Osaka procurement officers leverage PMDA certification requirements to consolidate vendor relationships toward single-source contracts.
- Ambulatory Surgical Centers:Day-surgery facilities with concentrated procedure schedules achieve favorable per-unit economics through dedicated reprocessing agreements. Australia's state health networks are bundling catheter and endoscope refurbishment under multi-year tenders in Queensland and Victoria.
- Clinics:Outpatient diagnostic centers rely on third-party reprocessing logistics due to limited in-house sterilization infrastructure.
- Home Healthcare:Patient-directed care settings face traceability constraints that limit reprocessed device eligibility to low-risk categories.
Hospitals dominate procurement value; ambulatory surgical centers are gaining share fastest.
Technology:
Application maturity determines capital deployment patterns, with established sterilization modalities competing against emerging platform investments.
- Steam Sterilization:Saturated steam under pressure achieves spore kill assurance for heat-stable metallic instruments. Japan's PMDA guidelines validate this modality as the baseline standard for hospital procurement eligibility across Tokyo metropolitan facilities.
- Ethylene Oxide:Low-temperature gas sterilization penetrates heat-sensitive polymer lumens and electronic components. India's CDSCO mandates residual gas testing protocols that extend validation timelines for cardiovascular catheter applications.
- Radiation:Gamma and electron beam irradiation deliver terminal sterilization for packaged single-use devices reprocessed into limited-use status.
- Chemical Disinfection:Hydrogen peroxide vapor and peracetic acid systems enable point-of-use reprocessing in decentralized Australian hospital campuses.
Steam sterilization anchors installed base; chemical disinfection shows steepest expansion trajectory.
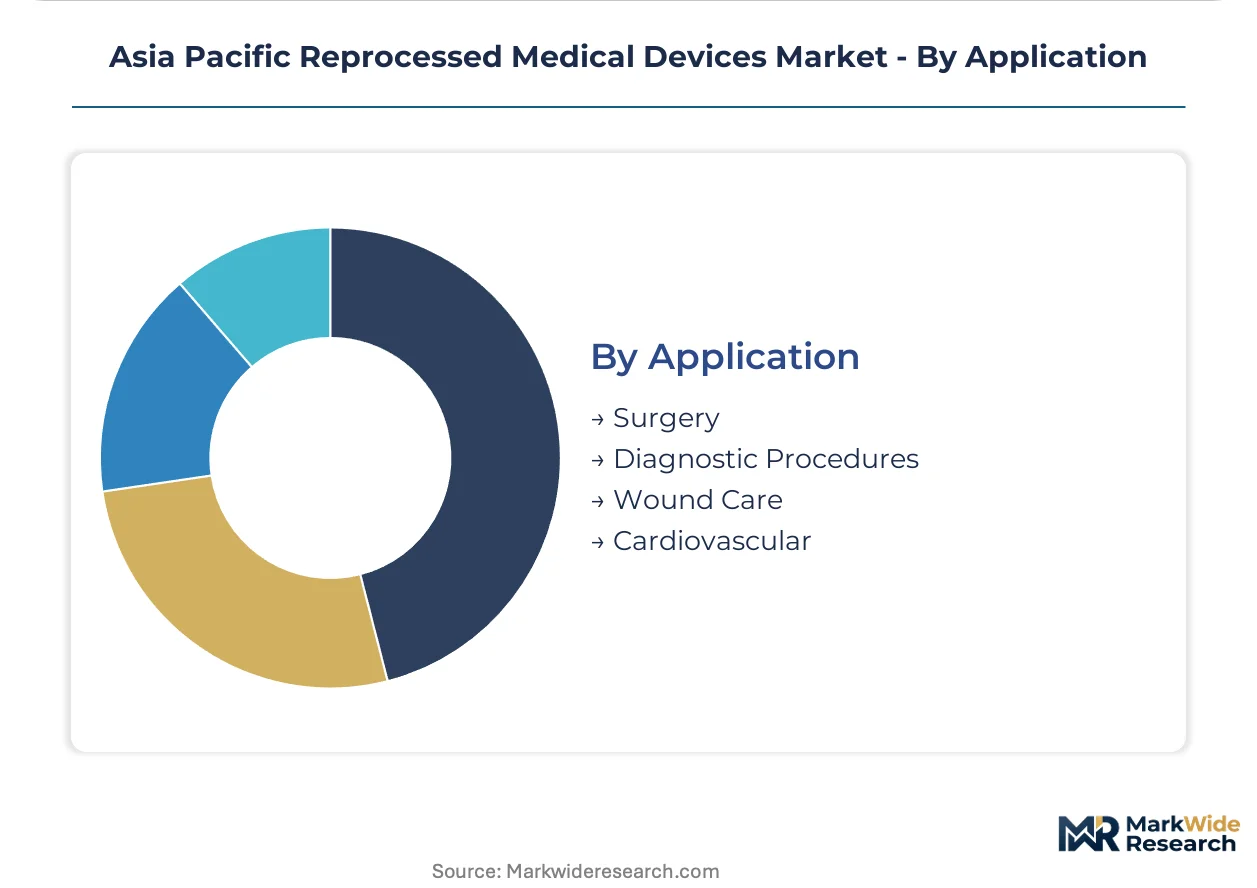
Application:
Clinical risk stratification governs regulatory scrutiny intensity, with invasive procedures facing sterility assurance thresholds exceeding diagnostic use cases.
- Cardiovascular:Interventional cardiology devices require endotoxin testing and particulate validation under PMDA and CDSCO frameworks. Japan's 2024 guideline updates mandate enhanced documentation that elevates capital barriers for reprocessor market entry.
- Surgery:Operating theater instruments demand bioburden reduction and functional sharpness restoration for reusable metallic tool categories.
- Diagnostic Procedures:Endoscope channels and biopsy forceps undergo cleaning verification with ATP testing and microbiological sampling protocols.
- Wound Care:Negative pressure therapy devices and irrigation systems face polymer degradation limits that narrow reprocessing windows.
Cardiovascular commands premium pricing; diagnostic procedures scale most efficiently.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reprocessed medical device operations trace their Asia Pacific lineage to Japan's centralized sterilization infrastructure developed during the 1990s healthcare cost containment era, later diffusing to Australia's public procurement systems and India's emerging tertiary hospital networks.
Japan
Tokyo and Osaka metropolitan hospital procurement officers drive catheter and endoscope reprocessing volumes through single-source contract consolidation. PMDA's 2024 sterility assurance guideline updates mandate enhanced endotoxin testing documentation that elevates capital barriers for new market entrants. Kansai region medical centers leverage established refurbishment infrastructure to compress device turnaround times.
Australia
Queensland and Victoria state health procurement agencies bundle multi-year catheter and endoscope refurbishment tenders under volume-scale pricing frameworks. TGA sterility documentation requirements shape vendor eligibility across public hospital networks. New South Wales health systems pilot in-house hydrogen peroxide vapor sterilization units that decentralize reprocessing from third-party facilities.
India
Tertiary hospital networks in Maharashtra and Karnataka expand cardiovascular catheter reprocessing to offset interventional cardiology supply cost inflation. CDSCO tightened quality norms accelerate third-party certification demand from domestic procurement officers. Delhi-NCR medical institutions invest in traceability software interfaces connecting reprocessed device tracking with legacy inventory platforms.
South Korea
Seoul Capital Area hospital systems adopt electrosurgical device refurbishment programs to manage operating theater supply expenditures. MFDS sterility assurance protocols validate reprocessor market access for cardiovascular and surgical instrument applications. Busan-Ulsan regional medical clusters develop dedicated cleaning protocol capabilities serving southeastern hospital networks.
Asia Pacific Reprocessed Medical Devices Market Vendor Landscape
The competitive structure tilts toward diversified medical technology conglomerates with captive sterilization infrastructure. Hospital contract negotiations favor established players possessing validated cleaning protocol certifications across multiple device categories. Three archetypes dominate: integrated sterilization service providers, dedicated refurbishment specialists, and diversified device manufacturers extending into aftermarket services. Capacity expansion and strategic partnerships constitute the primary competitive moves, with procurement consolidation driving scale requirements.
Among integrated service providers, Stryker Sustainability Solutions Inc. and Medline Industries occupy positions anchored by established regional facility networks. Johnson & Johnson represents the diversified manufacturer archetype extending brand trust into refurbishment segments. These three entities exemplify the scale-driven tier where sterilization infrastructure and regulatory certification documentation determine contract eligibility.
| Leading Market Players |
|---|
| Stryker Sustainability Solutions Inc. |
| Medline Industries |
| Johnson & Johnson |
| ReNu Medical |
| Sterilmed |
| NEScientific |
| Centurion Medical Products Corporation |
| Vanguard AG |
| SureTek Medical |
| Others |
Supply Flow & Price Mechanics
Polymer resin indices for medical-grade plastics cascade through Asia Pacific reprocessing economics, compressing margins on standard-tier catheter refurbishment while elevating premium-tier endoscope pricing power for PMDA-certified operators serving Tokyo metropolitan hospitals.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs contract negotiations, with PMDA certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from CDSCO compliance investments that elevate fixed costs for cardiovascular catheter reprocessors. Ambulatory surgical centers in Australia exhibit highest price sensitivity, while Japan's tertiary hospital networks prioritize certification documentation over unit cost.
Supply Chain Analysis
Workforce scarcity for validated sterility assurance technicians concentrates refurbishment capacity in Japan, Australia, and India despite equipment availability elsewhere. Supply chains draw from medical-grade polymer suppliers, optical component manufacturers, and hydrogen peroxide vapor sterilization system producers. Single-source vulnerability runs through specialized endotoxin testing reagent suppliers. Distribution runs through third-party logistics networks serving hospital sterilization departments and dedicated reprocessing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific reprocessed medical devices offer margin expansion through CDSCO compliance-driven premium-tier consolidation and ambulatory surgical center volume capture offsetting polymer input volatility.
For Market Incumbents: Deepen PMDA certification documentation investments to lock in Tokyo and Osaka single-source contract renewals before 2024 guideline implementation fully propagates. Expand captive hydrogen peroxide vapor sterilization capacity in Queensland and Victoria to intercept Australian public health decentralization trends. Prioritize sterility assurance technician training pipelines to compress facility certification timelines against workforce scarcity. For New Entrants and Emerging Players: Capture India's third-party cardiovascular catheter certification demand accelerating under tightened CDSCO norms. Target Maharashtra and Karnataka tertiary hospital networks with traceability software interfaces bridging legacy inventory platforms. Lead with CDSCO compliance-as-a-service positioning rather than price competition. For Investors and Strategic Acquirers: Asymmetric upside sits with electrosurgical device refurbishment specialists possessing radiofrequency calibration capabilities across Seoul Capital Area hospital systems. Long-term viability hinges on regulatory certification moats widening under PMDA and CDSCO convergence trends. Watch MFDS guideline harmonization signals as South Korean market entry inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Certification Investment | Tokyo hospital procurement officers now mandate documentation as mandatory bid qualification criterion. |
| Ambulatory Surgical Center Partnership | Queensland and Victoria day-surgery networks achieve favorable per-unit economics through dedicated agreements. |
| Traceability Software Development | Delhi-NCR medical institutions require custom interfaces connecting reprocessed device tracking with legacy platforms. |
| Hydrogen Peroxide Vapor Decentralization | New South Wales health systems pilot in-house units compressing turnaround times from days to hours. |
| Electrosurgical Device Convergence | Radiofrequency refurbishment integration with advanced cleaning protocols opens new commercialization categories. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining hospital procurement officer discussions, biomedical engineer consultations, GPO contracts manager input, and regulatory affairs lead assessments with secondary validation against hospital procurement databases, GPO contract repositories, CDSCO filing records, and PMDA guideline documentation. Bottom-up device category volume builds triangulated against top-down healthcare expenditure flows.
Comparable-period anchoring linked projection horizon assumptions to historical reprocessing penetration rates across cardiovascular, surgical, and diagnostic application segments. Modeling incorporated technology modality splits, end-user facility tiers, and regional regulatory cluster variations. CAGRs derived from segmented growth rate synthesis incorporating sterilization infrastructure deployment timelines and compliance investment cycles.
Underlying measurement precision varies by segment; cardiovascular catheter volumes carry tighter precision than emerging electrosurgical device categories. Forecasts embed assumptions regarding PMDA guideline adoption velocity and CDSCO enforcement intensity. Material deviation in sterility assurance technician workforce availability or polymer resin cost trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Artificial Respirator Market
Medical Devices
United States Respiratory Devices Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Powered Mattress System Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Spinal Non-Fusion Technologies Market
Medical Devices
Electronic Smart Mask Market
Medical Devices
Auto-Transfusion Systems Market
Medical Devices
Infusion Fluid Holder Market
Medical Devices
Heart Defect Closure Devices Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
Hearing Aids Market
Medical Devices
Medication Dispensing and Packaging Systems Market
Medical Devices
Anorectal Manometry Systems Market
Medical Devices
Hemodynamic Flow Alteration Devices Market