
 Subcutaneous Implantable Defibrillator System Market | 2026-2036
Subcutaneous Implantable Defibrillator System Market Size, Share, and Industry Trends Forecast 2026-2036
Subcutaneous Implantable Defibrillator System Market Analytics
The EU Medical Device Regulation (MDR) is realigning clinical evidence requirements for implantable cardiac devices, compelling manufacturers to expand post-market surveillance infrastructure. Boston Scientific Corporation leverages its electrophysiology portfolio breadth to sustain catheter-lab relationships that feed S-ICD referrals. Medtronic plc anchors North American training networks that condition physician preference for subcutaneous implant techniques. Abbott differentiates through integrated remote monitoring ecosystems that pair S-ICD devices with its cardiac diagnostics platform.
A subcutaneous implantable defibrillator system comprises a pulse generator and subcutaneous electrode array that delivers high-voltage therapy without transvenous leads, typically operating with energy outputs of 80 joules and employing multi-phase waveform algorithms to minimize myocardial damage. The device serves patients with channelopathies, congenital heart defects, or elevated infection risk who require sudden cardiac death protection without endovascular hardware. Single-chamber devices dominate procedural volumes due to established implant workflows and broad payer coverage, while leadless devices represent the fastest-growing category as manufacturers resolve energy delivery and longevity constraints. Hospitals capture the largest share of end-user value, though ambulatory surgical centers are gaining capacity as simplified two-incision techniques reduce operative time and recovery requirements.
The FDA governs premarket approval and post-approval study commitments for S-ICD systems under its cardiovascular device branch, while the EU MDR requires notified body conformity assessment with expanded clinical evaluation reporting. Japan's PMDA maintains distinct pharmaceutical and medical device agency review tracks that condition market entry timelines for foreign manufacturers. Stakeholders must monitor how CMS national coverage determinations and parallel European hospital procurement frameworks reshape access economics for next-generation subcutaneous platforms.
Market Dynamics
Leadless subcutaneous electrode arrays are displacing conventional leaded architectures across tertiary cardiac centers, compressing implant times while expanding candidate pools beyond traditional transvenous contraindications.
Growth Catalysts
- EU MDR post-market surveillance mandates:Expanded clinical evidence requirements compel manufacturers to build longitudinal patient registries, deepening physician confidence in long-term S-ICD performance data.
- Two-incision simplified techniques:Ambulatory surgical centers now capture cases previously routed to catheterization labs, broadening site-of-service economics for payers and providers.
- Channelopathy patient identification:Cardiac electrophysiology programs screen high-risk genetic cohorts for implant candidacy without endovascular hardware requirements.
Market Restraints
- Generator longevity constraints:Current lithium-silver vanadium oxide cell chemistries limit device replacement cycles to 7-9 years, accelerating reintervention burdens.
- Transvenous ICD residual preference:Established electrophysiologists maintain workflow familiarity with leaded systems, slowing subcutaneous technique diffusion.
- Reimbursement fragmentation:CMS national coverage determinations vary by site of service, creating payment uncertainty for hospital outpatient versus ASC settings.
Strategic Opportunities
- Pediatric congenital heart defect applications:S-ICD systems serve growing survivor populations with complex anatomy unsuited to transvenous lead placement.
- Remote monitoring ecosystem integration:Cloud-connected diagnostic platforms enable automated transmission of arrhythmia episodes to centralized monitoring centers.
- Japan PMDA streamlined review tracks:Foreign manufacturers access accelerated approval pathways for cardiac rhythm devices with prior FDA or CE marking.
Industry Challenges
- Subcutaneous implant technique training:Electrophysiology fellowship programs lack standardized curricula for parasternal electrode tunneling, constraining qualified operator supply.
- Multi-phase waveform algorithm validation:Novel energy delivery protocols require extensive preclinical modeling to demonstrate myocardial damage reduction without efficacy compromise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subcutaneous Implantable Defibrillator System Market |
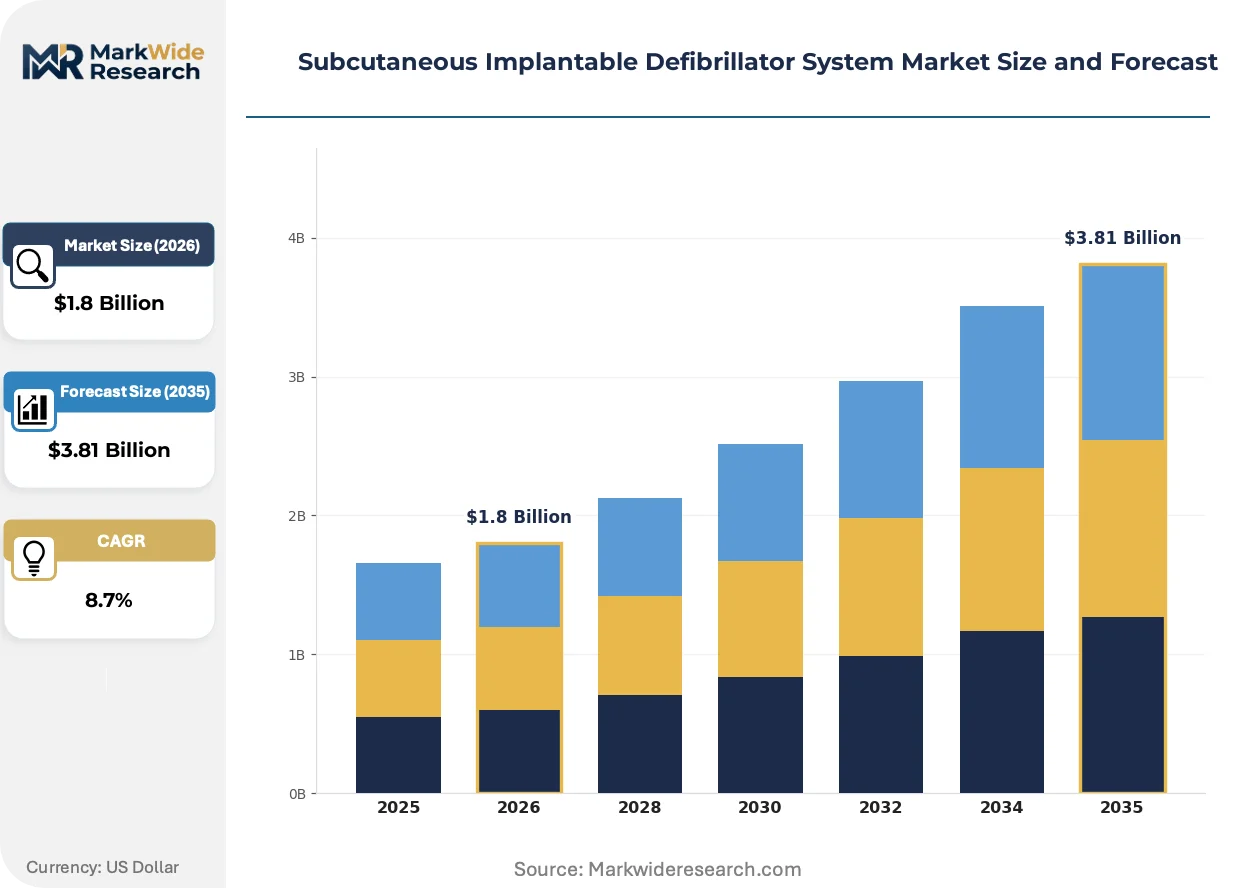
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Chamber Devices, Dual-Chamber Devices, Leadless Devices, Programmable Devices End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Centers, Homecare Settings Technology: Wireless Technology, Remote Monitoring, Battery Management, Data Analytics Application: Arrhythmias, Heart Failure, Cardiac Arrest, Sudden Cardiac Death |
| Companies Covered | Boston Scientific Corporation, Medtronic plc, Abbott, BIOTRONIK, MicroPort Scientific Corporation, LivaNova PLC, Biotronik SE, Imricor Medical Systems, Element Science, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subcutaneous Implantable Defibrillator System Market Evolving Landscape
Device miniaturization and algorithm sophistication are compressing the functional gap between subcutaneous and transvenous systems, reshaping competitive positioning across implantable cardiac rhythm management.
Multi-phase waveform technology is converging with high-capacitance generator designs to deliver 80-joule therapy through entirely extrathoracic electrode configurations. Tertiary hospital electrophysiology departments adopt these systems for patients with prior lead infections or congenital anomalies. The convergence is enabling same-day discharge protocols previously impossible with transvenous hardware.
FDA's evolving premarket submission pathways for cardiovascular devices compress time-to-market for subcutaneous rhythm platforms through streamlined review tracks. Manufacturers face reduced clinical trial burden when leveraging predicate device equivalence. Early-stage S-ICD innovators target these pathways to accelerate commercial entry against established portfolios.
Hospital procurement committees now bundle S-ICD acquisition with remote monitoring service contracts, displacing standalone device purchasing. Integrated diagnostic platforms capture recurring revenue streams through cloud-based arrhythmia analysis. This bundling pattern concentrates in United States health systems with captive electrophysiology networks.
Subcutaneous Implantable Defibrillator System Market Segmentation
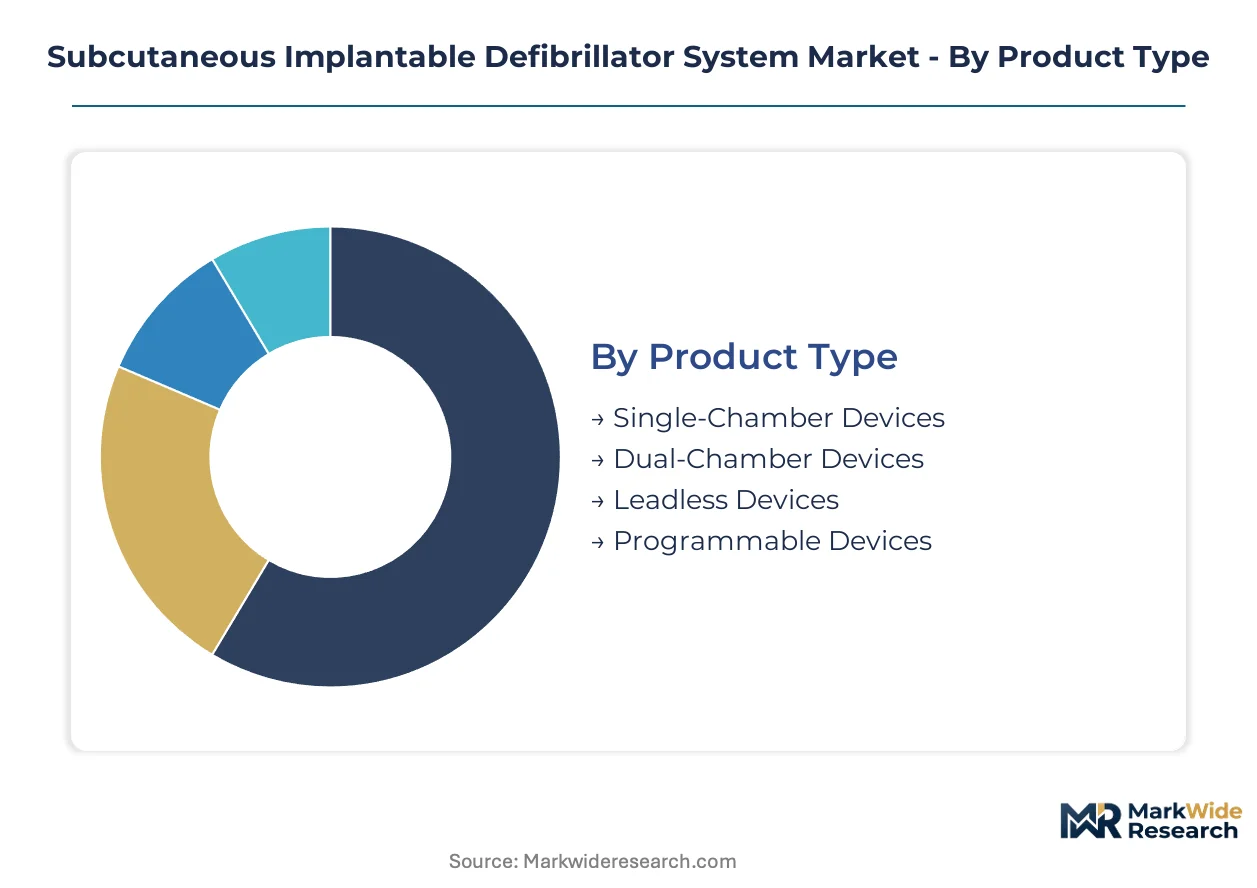
Segmentation in the Subcutaneous Implantable Defibrillator System Market reveals how regulatory pathways, implant site economics, and patient risk profiles reshape procurement priorities across healthcare delivery networks. Manufacturers align product portfolios to specific certification burdens while providers select configurations based on procedural volume and reimbursement clarity.
Product Type:
FDA premarket approval requirements vary substantially across device architectures, with leadless platforms facing novel clinical evidence demands while single-chamber systems leverage predicate device equivalence.
- Single-Chamber Devices:These systems deploy one subcutaneous electrode array delivering 80-joule therapy through parasternal tunneling techniques. Tertiary hospital electrophysiology departments in the United States concentrate procurement volumes here due to established CMS reimbursement codes and streamlined implant workflows.
- Leadless Devices:Entirely extrathoracic configurations eliminate electrode leads through high-capacitance generator designs and multi-phase waveform algorithms. Demand concentrates in German and French cardiac centers managing congenital heart defect patients with complex anatomy unsuited to conventional hardware.
- Dual-Chamber Devices:Expanded sensing capabilities require additional subcutaneous electrodes for atrial rhythm discrimination.
- Programmable Devices:Software-configurable therapy parameters enable post-implant customization without hardware revision.
Single-chamber devices sit at the top of the volume ranking, with leadless platforms climbing the fastest.
End User:
Site-of-service economics drive divergent purchasing patterns, with hospital outpatient departments capturing complex cases while ambulatory surgical centers exploit simplified two-incision techniques.
- Hospitals:Comprehensive electrophysiology programs manage high-risk implant candidacy evaluations, channelopathy screening, and generator replacement procedures. United States health systems with captive referral networks dominate value capture through bundled device and monitoring contracts.
- Ambulatory Surgical Centers:Streamlined two-incision S-ICD techniques compress operative time below 60 minutes, enabling same-day discharge protocols. Texas and Florida ASC networks expand capacity fastest where state-level certificate-of-need restrictions remain minimal.
- Rehabilitation Centers:Post-implant recovery monitoring and patient education programs support device acceptance.
- Homecare Settings:Remote monitoring infrastructure enables episode transmission without facility-based follow-up.
Hospitals retain dominant procurement volume, though ambulatory surgical centers are gaining share fastest.
Technology:
Cloud connectivity and power management architectures differentiate competitive offerings as providers prioritize operational reliability and data integration.
- Remote Monitoring:Automated arrhythmia episode transmission to centralized monitoring centers enables rapid clinical response. United States integrated delivery networks demand these capabilities for population health management of sudden cardiac death risk cohorts.
- Wireless Technology:Bluetooth and cellular-enabled device interrogation eliminates in-clinic follow-up requirements. Japanese tertiary centers prioritize these systems to address geographic dispersion of implant recipients across archipelago regions.
- Battery Management:Lithium-silver vanadium oxide cell optimization extends generator longevity toward 9-year replacement cycles.
- Data Analytics:Machine learning algorithms for arrhythmia prediction and therapy optimization remain emerging capabilities.
Remote monitoring commands the largest installed base, with wireless technology expanding most quickly.
Application:
Patient risk stratification and underlying cardiac pathology determine device configuration selection and implant urgency.
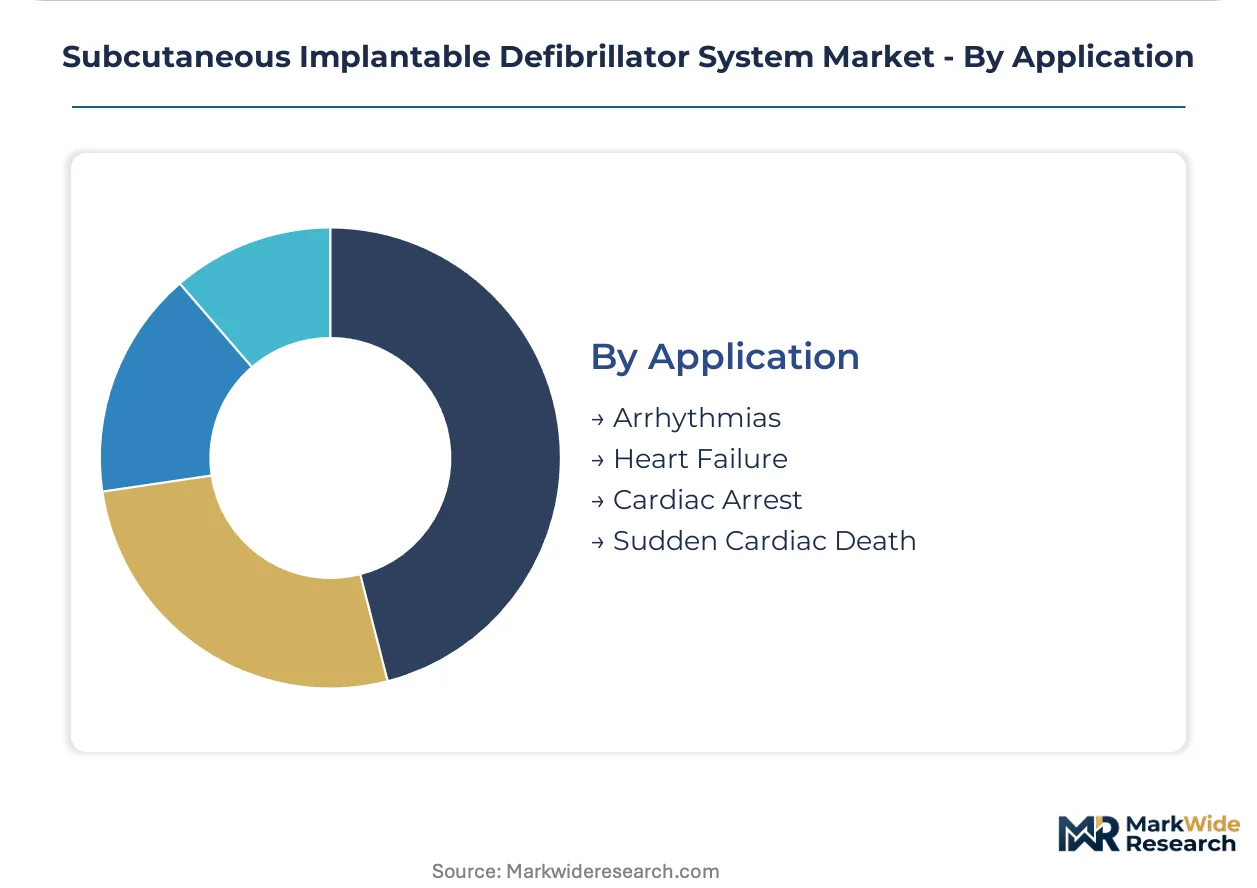
- Sudden Cardiac Death:Primary and secondary prevention indications drive the majority of implant volumes. United States electrophysiology programs screen genetic channelopathy families and post-myocardial infarction survivors for S-ICD candidacy without transvenous lead requirements.
- Arrhythmias:Ventricular tachycardia and fibrillation episodes requiring high-voltage therapy termination. German university hospitals concentrate expertise here for patients with prior lead infections or endovascular hardware contraindications.
- Heart Failure:Device therapy complements medical management in reduced ejection fraction populations.
- Cardiac Arrest:Survivor evaluation and secondary prevention implant decisions.
Sudden cardiac death prevention dominates procedural indications, with arrhythmia applications showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrophysiology specialists concentrate in United States academic medical centers, German university hospitals, and Japanese cardiac institutes, anchoring procedural expertise for subcutaneous defibrillator implantation across three continents.
United States
Tertiary hospital electrophysiology departments drive implant volumes through established CMS reimbursement codes and captive referral networks. The FDA's streamlined premarket review pathways compress commercial entry timelines for subcutaneous rhythm devices. Texas and Florida ambulatory surgical centers expand capacity fastest where certificate-of-need restrictions remain minimal.
Germany
University hospitals in Berlin and Munich concentrate expertise for congenital heart defect patients requiring leadless extrathoracic configurations. The EU MDR mandates expanded post-market surveillance infrastructure for implantable cardiac devices. Bavarian cardiac centers pioneer same-day discharge protocols through simplified two-incision techniques.
Japan
PMDA maintains distinct pharmaceutical and medical device agency review tracks that condition market entry timelines for foreign manufacturers. The Tokyo and Osaka metropolitan clusters house the archipelago's densest electrophysiology fellowship programs. Remote monitoring systems with cellular connectivity address geographic dispersion of implant recipients across Japan's islands.
United Kingdom
NHS England's specialized commissioning frameworks determine access to subcutaneous defibrillator therapy for channelopathy screening programs. The MHRA post-Brexit regulatory autonomy creates parallel conformity assessment requirements distinct from EU MDR. London and Manchester academic health science centers coordinate national patient registries for longitudinal device performance tracking.
Australia
TGA approval pathways leverage prior FDA or CE marking to accelerate market entry for cardiac rhythm devices. Melbourne and Sydney cardiac institutes manage elevated infection-risk patients through subcutaneous systems avoiding endovascular hardware. State-based procurement frameworks create payment variability between public hospital networks and private surgical facilities.
Subcutaneous Implantable Defibrillator System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the subcutaneous defibrillator landscape, with integrated medical device conglomerates holding manufacturing depth against specialized cardiac rhythm boutiques. The vendor base consolidates around three to four electrophysiology portfolios with comprehensive implantable device ecosystems. Strategic archetypes include diversified cardiovascular conglomerates, pure-play cardiac rhythm specialists, and emerging leadless technology innovators. Dominant competitive moves encompass remote monitoring platform integration and ambulatory surgical center partnership networks.
Among diversified cardiovascular conglomerates, Boston Scientific Corporation and Medtronic plc occupy positions anchoring North American training infrastructure and catheter-lab referral relationships. Abbott represents the integrated diagnostic ecosystem archetype, pairing subcutaneous devices with cloud-connected monitoring platforms. These three companies exemplify the scale-driven tier where portfolio breadth conditions physician preference and procurement committee decisions.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic plc |
| Abbott |
| BIOTRONIK |
| MicroPort Scientific Corporation |
| LivaNova PLC |
| Biotronik SE |
| Imricor Medical Systems |
| Element Science |
| Others |
Value Network & Pricing Analysis
Leadless electrode miniaturization and high-capacitance generator manufacturing simultaneously compress production costs and concentrate component sourcing among specialized lithium-silver vanadium oxide cell suppliers and precision electrode fabricators. This dual shift elevates pricing power for upstream material specialists while pressuring device OEM margins through captive supply dependencies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated remote monitoring bundles from standalone hardware and basic generator replacements. FDA premarket approval tier and CE marking under EU MDR differentiate price bands, with certified devices commanding substantial premiums over predicate-equivalent systems. Cost compression in the economy tier intensifies as ambulatory surgical centers negotiate volume contracts for simplified two-incision procedures. Pediatric congenital heart defect applications show least price sensitivity due to limited therapeutic alternatives, while routine generator replacement cycles face acute sensitivity from hospital procurement committees.
Supply Chain Analysis
Regional distribution centers in Minnesota, Massachusetts, and Dublin anchor hub-and-spoke patterns that feed tertiary hospital electrophysiology departments and ambulatory surgical center networks. Component sourcing draws from Japanese lithium-cell specialists, German precision electrode manufacturers, and Swiss capacitor suppliers. Single-source vulnerability concentrates in high-capacitance generator subassemblies where qualified secondary suppliers remain scarce. Distribution runs through manufacturer-direct field inventory systems rather than third-party medical device distributors, preserving margin control and enabling rapid implant kit customization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where reimbursement clarity and procedural training infrastructure now filter demand toward premium remote monitoring-integrated systems over standalone hardware. The shift toward cloud-connected diagnostic platforms rewards vendors with captive software ecosystems.
For Market Incumbents: Extend remote monitoring platform integration to capture recurring revenue streams and deepen hospital system lock-in against emerging leadless technology innovators. Anchor North American training networks to condition physician preference for subcutaneous implant techniques before competing catheter-lab relationships solidify. Prioritize EU MDR post-market surveillance infrastructure investments to satisfy expanded clinical evidence requirements and defend premium positioning. For New Entrants and Emerging Players: Algorithm-first differentiation in multi-phase waveform energy delivery offers entry wedge against established electrophysiology portfolios with legacy single-phase architectures. Target Japanese PMDA streamlined review tracks for accelerated commercial entry using prior FDA predicate equivalence. Penetrate German university hospital congenital heart defect centers where leadless extrathoracic configurations address complex anatomies underserved by incumbent transvenous-compatible designs. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play cardiac rhythm specialists lacking integrated diagnostic ecosystems relative to diversified cardiovascular conglomerates with cloud platform breadth. Five-to-ten year viability hinges on remote monitoring subscriber retention rates and generator replacement cycle compression from cell chemistry advances. Monitor CMS national coverage determination shifts between hospital outpatient and ambulatory surgical center reimbursement parity as inflection indicator for site-of-service economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway Optimization | Streamlined premarket review compresses commercial entry timelines against predicate device portfolios. |
| Hospital System Partnership | Bundled device and remote monitoring contracts lock in multi-year procurement commitments across captive networks. |
| CE Marking Pathway Investment | EU MDR conformity assessment with expanded clinical evaluation reporting secures continental access. |
| Software Companion Development | Cloud-connected diagnostic platforms enable automated arrhythmia transmission to centralized monitoring centers. |
| Reimbursement Strategy | CMS national coverage determination alignment between hospital outpatient and ASC settings shapes site economics. |
Research Methodology
Direct dialogue with electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers grounded qualitative insights in frontline procurement and implant workflow realities. Secondary validation drew from FDA premarket approval filings, EU MDR notified body assessments, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up implant volume modeling and top-down market sizing triangulated through electrophysiology fellowship program capacity and tertiary hospital cath-lab expansion plans.
Bottom-up demand modeling segmented the market by device architecture, end-user site of service, and application indication across the projection horizon. Analytical frameworks incorporated lithium-silver vanadium oxide cell longevity trajectories, two-incision technique diffusion curves, and remote monitoring platform adoption rates. CAGRs derived from weighted average of historical implant growth, regulatory pathway acceleration effects, and reimbursement clarity progression without year-specific anchoring.
The model holds under stable FDA and EU MDR regulatory frameworks; deviation in premarket review timeline compression or post-market surveillance mandate intensity would shift commercial entry assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Catheter Introducer Sheaths Market
Medical Devices
Global Holter ECG Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Elastomeric Infusion Pump Market
Medical Devices
Medical Smart Glasses Market
Medical Devices
Biomedical Warming and Thawing Devices Market
Medical Devices
Canada Anesthesia Devices Market
Medical Devices
North America Ultrasound Probe Disinfection Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
Advanced Infusion Systems Market
Medical Devices
Artificial Pancreas Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Knee Walkers Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
IV Fluid Transfer Drugs Devices Market