
 Cerebral Thrombectomy Devices Market | 2026-2036
Cerebral Thrombectomy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cerebral Thrombectomy Devices Market Analytics
Software-enabled aspiration control is repositioning device economics toward per-procedure service contracts rather than capital-only sales. Stryker Corporation leverages its neurovascular platform breadth to anchor hospital system loyalty across integrated delivery networks. Medtronic sustains R&D intensity in aspiration catheter portfolio expansion, while Penumbra, Inc. specializes in thrombus extraction system differentiation through proprietary separator technology.
Cerebral thrombectomy devices are interventional instruments designed to mechanically remove blood clots from intracranial vessels, typically employing nitinol-based stent retrievers or large-bore aspiration catheters operating at vacuum pressures exceeding 750 mmHg to restore cerebral perfusion. Stent retriever systems dominate procedural volume in acute ischemic stroke intervention due to established clinical evidence and physician training infrastructure. Aspiration catheters represent the fastest-growing product category as direct aspiration first pass techniques gain adoption in comprehensive stroke centers. Hybrid technology approaches combining mechanical retrieval with localized pharmacological delivery are emerging as margin-rich segments where device firms command premium positioning.
FDA breakthrough device designation pathways compress premarket timelines for novel thrombectomy platforms, while EU MDR technical documentation requirements reshape conformity assessment costs for European market access. Japan's PMDA reviews cerebral devices through the Sakigake designation framework, accelerating availability for acute stroke interventions. Stroke system certification standards from the Joint Commission in the United States and analogous accreditation bodies in Germany and Japan dictate hospital purchasing eligibility for thrombectomy-capable facilities. Stakeholders must monitor evolving large vessel occlusion triage protocols and payer coverage determinations for extended therapeutic windows.
Market Dynamics
The cerebral thrombectomy devices market is being structurally reshaped by the migration from capital-equipment sales toward software-enabled per-procedure service contracts, compressing traditional device economics and locking hospital systems into platform ecosystems.
Growth Catalysts
- Stroke center certification mandates:Joint Commission standards in the United States and analogous frameworks in Germany and Japan require 24/7 neurointerventional coverage, forcing hospital infrastructure investment in thrombectomy-capable facilities.
- FDA breakthrough pathways:Expedited premarket review timelines for novel aspiration platforms are accelerating clinical adoption curves and shortening product development cycles.
- Nitinol stent retriever standardization:Established physician training infrastructure and procedural protocols anchored around mechanical retrieval devices sustain volume growth in acute ischemic stroke intervention.
Market Restraints
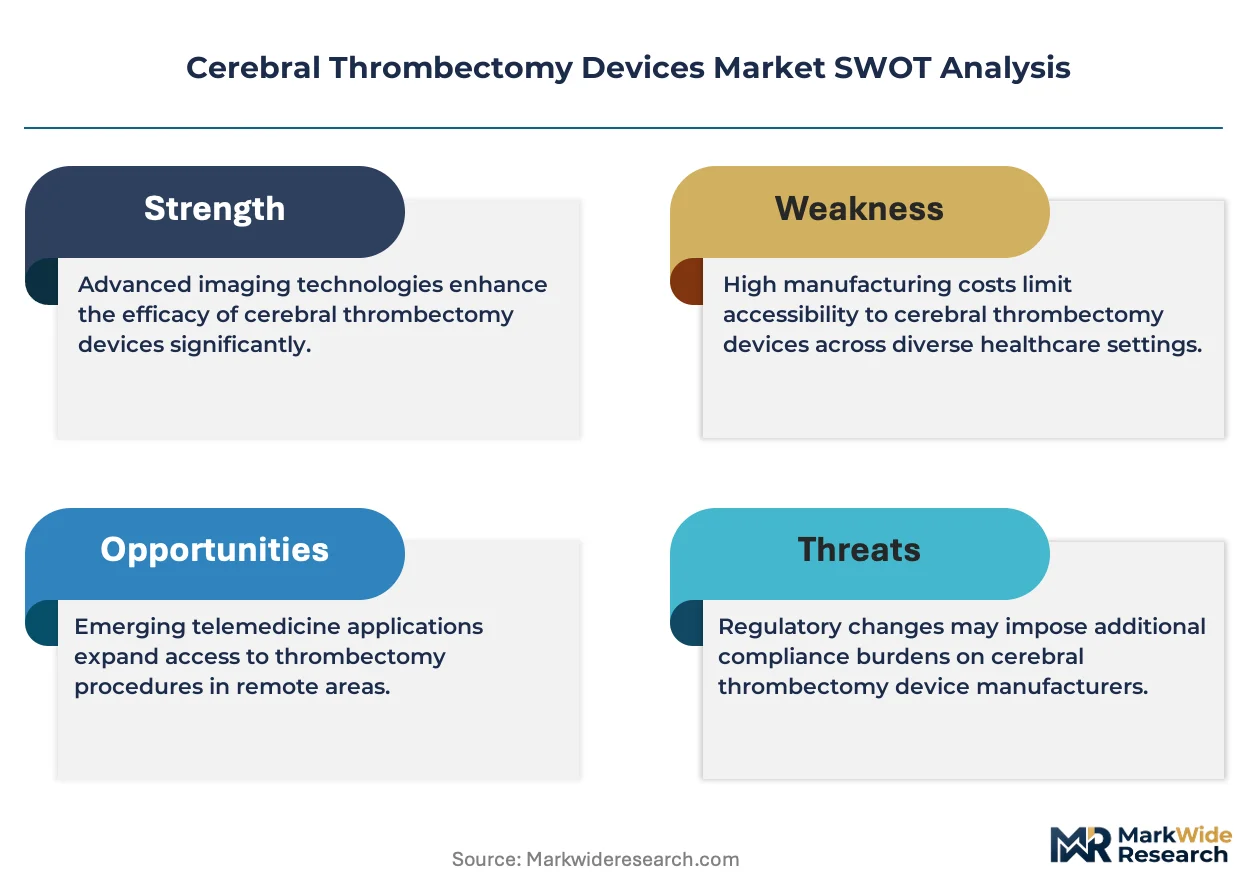
- EU MDR technical documentation burden:Conformity assessment cost inflation and notified body capacity constraints are compressing margins and delaying European market access for smaller device manufacturers.
- Supply concentration in nitinol wire:Dependence on specialized shape-memory alloy suppliers creates input cost volatility and single-source vulnerability for stent retriever production.
- Large vessel occlusion triage protocol fragmentation:Inconsistent emergency medical services routing algorithms across hospital networks limit addressable procedure volume in underpenetrated regions.
Strategic Opportunities
- Extended therapeutic window expansion:Payer coverage determinations for thrombectomy beyond traditional time limits in the United States are enlarging eligible patient populations and procedural volume ceilings.
- Hybrid pharmacomechanical platforms:Convergence of localized thrombolytic delivery with aspiration catheter technology creates premium positioning opportunities in comprehensive stroke centers.
- Direct-to-aspiration technique diffusion:First-pass aspiration protocols are penetrating community hospital settings previously constrained by stent retriever training requirements.
Industry Challenges
- Neurointerventionalist workforce scarcity:Specialized physician training pipeline limitations restrict 24/7 coverage expansion at tertiary stroke centers, creating procedural access bottlenecks.
- Integration complexity with imaging infrastructure:Real-time perfusion imaging and mobile stroke unit connectivity requirements demand capital coordination across radiology and interventional departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cerebral Thrombectomy Devices Market |
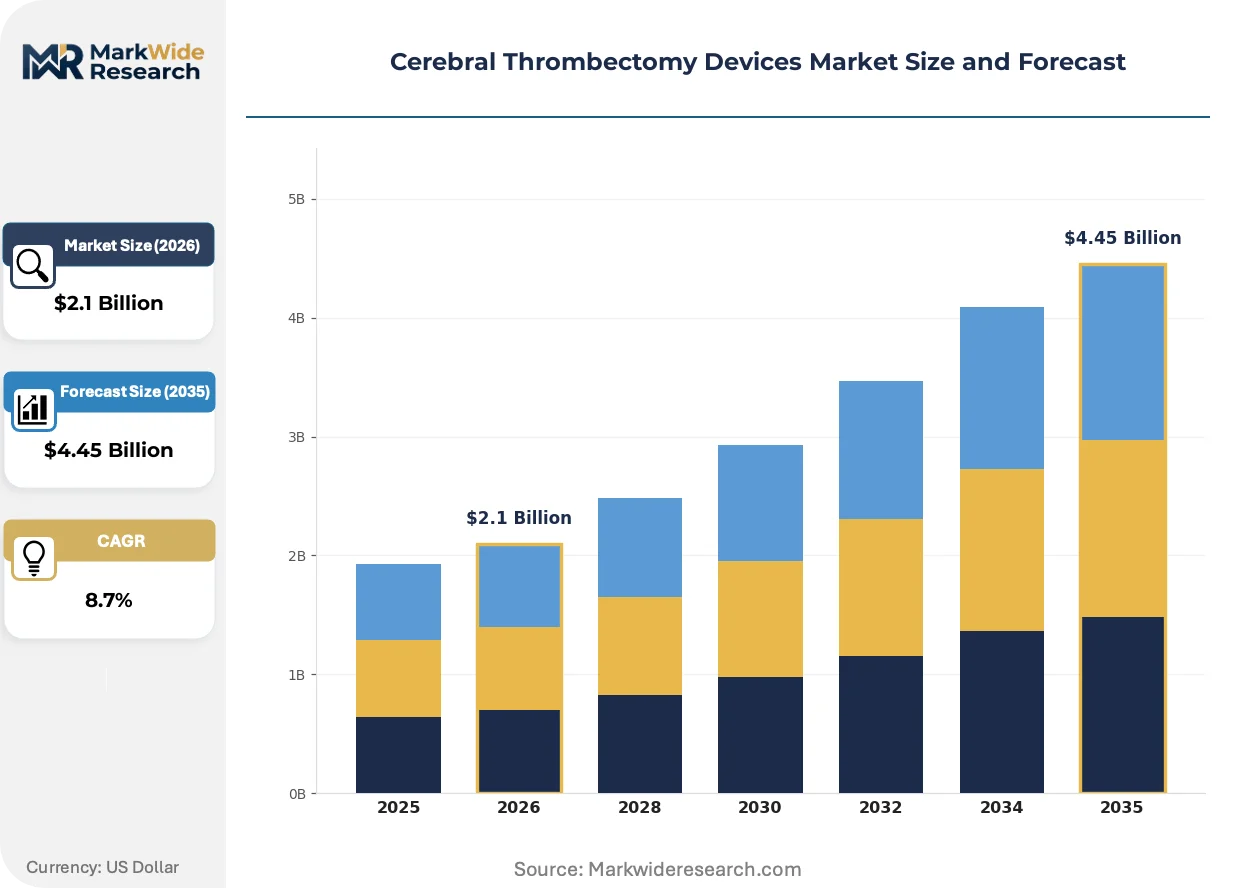
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stent Retriever, Aspiration Catheter, Manual Thrombectomy Device, Combination Device Technology: Mechanical, Pharmacological, Hybrid, Electrical End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Emergency Care Facilities Procedure Type: Acute Ischemic Stroke, Chronic Thrombosis, Emergency Intervention, Non-Emergency Treatment |
| Companies Covered | Stryker Corporation, Medtronic, Penumbra, Inc., MicroVention, Inc., Johnson & Johnson, Boston Scientific Corporation, Terumo Corporation, Imperative Care, Inc., Acandis GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cerebral Thrombectomy Devices Market Evolving Landscape
Device architecture is converging around intelligent aspiration control systems that embed software-defined functionality into previously mechanical instruments, redefining value capture models and competitive differentiation.
Aspiration platforms with integrated vacuum pressure modulation and flow-sensing feedback are unifying procedural steps previously requiring multiple device exchanges. Comprehensive stroke centers in the United States and Germany are adopting these systems at accelerating replacement cycles. This unification is compressing procedure times and enabling outcome-based contracting structures that shift vendor revenue toward per-case utilization fees.
The European Union Medical Device Regulation's heightened clinical evidence requirements for Class III implantable devices are extending conformity assessment timelines and reshaping European go-to-market strategies. Manufacturers are responding by front-loading clinical trial investment and consolidating regulatory affairs capabilities in notified body-preferred jurisdictions. Aspiration catheter portfolios face particular scrutiny given their classification complexity and predicate device dependencies.
Hospital procurement committees are consolidating vendor relationships around integrated neurovascular platforms rather than discrete device categories. United States integrated delivery networks are negotiating enterprise-wide contracts that bundle stent retrievers, aspiration systems, and access devices under single-source agreements. This concentration is most visible in multi-hospital systems pursuing Joint Commission stroke certification across their entire network footprint.
Cerebral Thrombectomy Devices Market Segmentation
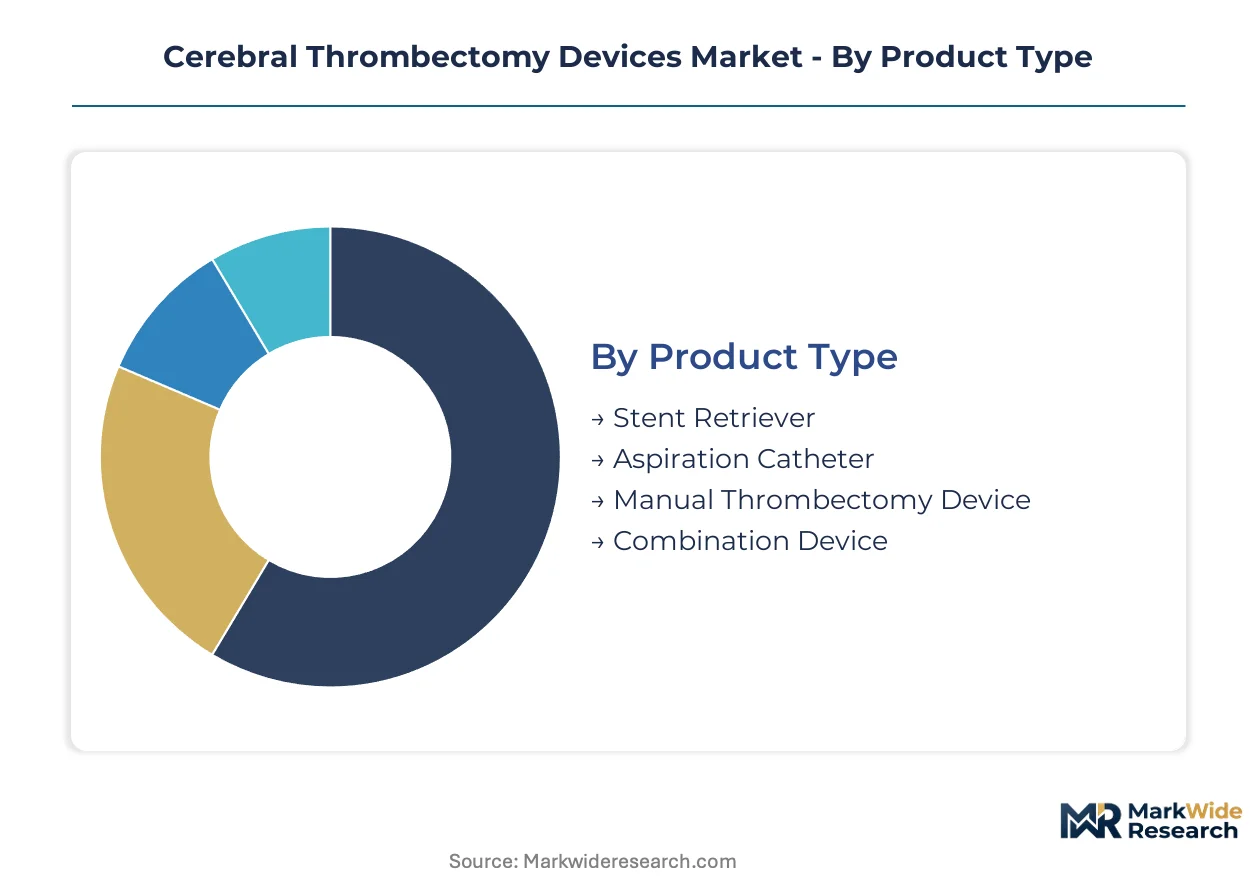
Cerebral thrombectomy devices fragment across four distinct dimensions that shape procurement patterns and vendor positioning. Supply concentration varies dramatically by product architecture, with nitinol-based platforms commanding premium positioning against emerging aspiration alternatives.
Product Type:
Supply concentration clusters around nitinol stent retriever manufacturing, where specialized wire drawing and laser cutting capabilities create moats for established producers.
- Stent Retriever:Self-expanding nitinol mesh systems deploy through microcatheters to ensnare thrombus for mechanical extraction. Demand concentrates in tertiary stroke centers across the United States and Germany, where established training infrastructure and Joint Commission certification requirements sustain procedural volume.
- Aspiration Catheter:Large-bore suction systems operating at vacuum pressures exceeding 750 mmHg enable direct clot aspiration without stent deployment. Comprehensive stroke centers in Japan and community hospitals throughout the United States are adopting these systems fastest, driven by reduced training barriers and faster procedure times.
- Manual Thrombectomy Device:Hand-operated aspiration syringes and manual extraction tools for resource-constrained settings.
- Combination Device:Integrated platforms merging stent retriever and aspiration functionality into single-procedure systems.
Today's leader: Stent Retriever. Tomorrow's challenger: Aspiration Catheter.
Technology:
Cost tier stratification separates mechanical platforms from emerging pharmacological and hybrid alternatives, with reimbursement codes driving hospital procurement decisions.
- Mechanical:Physical clot disruption and retrieval through stent, aspiration, or manual instruments. United States integrated delivery networks and German hospital systems anchor demand, with FDA breakthrough pathways and EU MDR compliance timelines compressing competitive windows.
- Pharmacological:Localized thrombolytic delivery systems including intra-arterial tPA administration catheters. Japanese stroke centers under PMDA Sakigake designation protocols represent the primary adoption geography, with extended therapeutic window trials expanding eligible populations.
- Hybrid:Convergent mechanical-pharmacological platforms combining aspiration with localized drug delivery.
- Electrical:Emerging ultrasound-enhanced or electromechanical thrombus disruption technologies in preclinical and early clinical stages.
Mechanical platforms dominate current revenue. Hybrid architectures are gaining share fastest.
End User:
Customer type fragmentation creates distinct procurement channels, with hospital system consolidation favoring enterprise-wide vendor contracts over discrete device purchases.
- Hospitals:Tertiary and comprehensive stroke centers with 24/7 neurointerventional coverage. United States hospital systems pursuing Joint Commission stroke certification and German university hospitals under analogous frameworks represent concentrated demand, with procurement committees bundling device categories under single-source agreements.
- Outpatient Clinics:Ambulatory settings managing post-acute stroke monitoring and secondary prevention.
- Rehabilitation Centers:Long-term care facilities addressing neurological recovery after thrombectomy intervention.
- Emergency Care Facilities:Mobile stroke units and freestanding emergency departments requiring rapid triage capabilities.
Hospitals command current spend. Emergency Care Facilities are expanding most quickly.
Procedure Type:
Volume distribution skews heavily toward acute interventions, with reimbursement policy shifts determining addressable market ceilings for extended-window procedures.
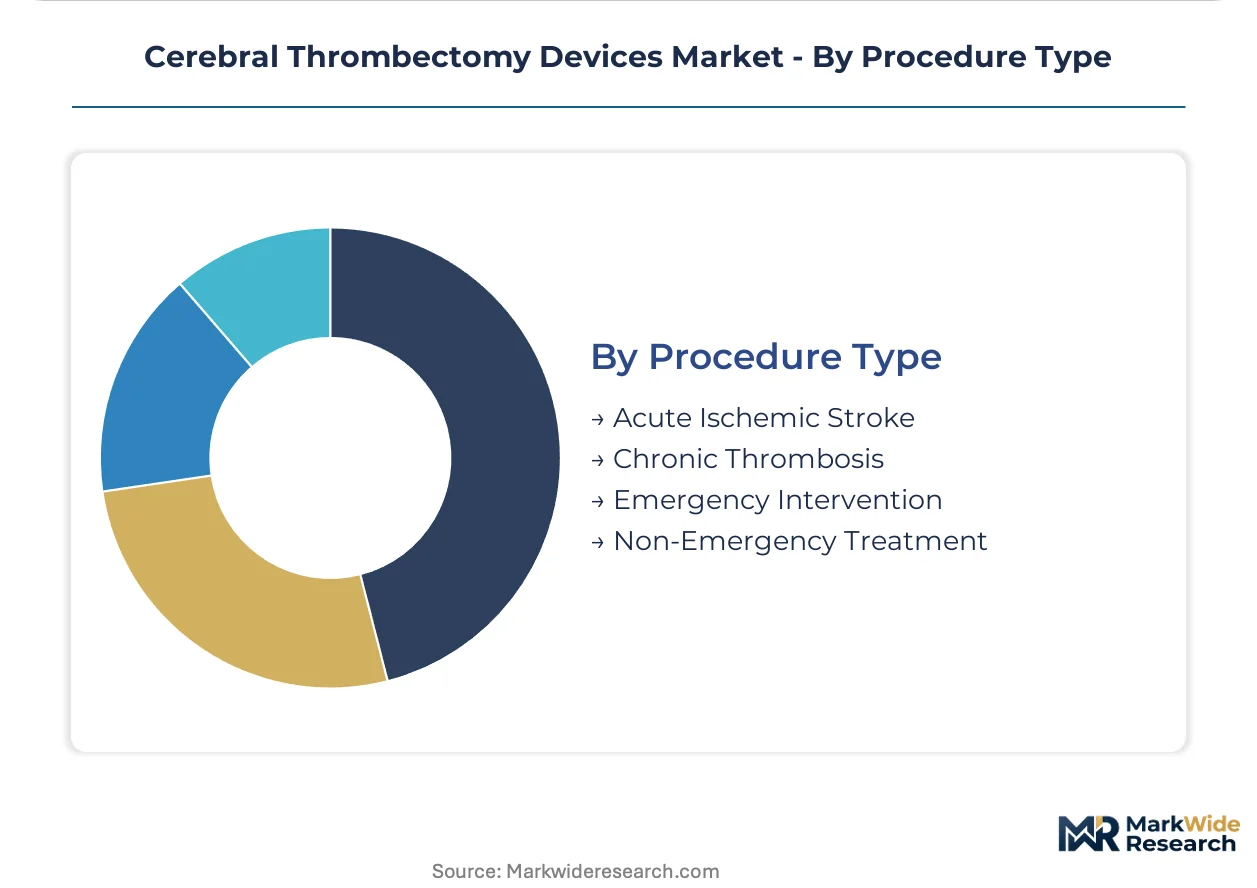
- Acute Ischemic Stroke:Emergency large vessel occlusion intervention within traditional therapeutic windows. United States payer coverage determinations and Japan's PMDA accelerated review pathways sustain procedural growth, with stroke center certification mandates forcing infrastructure investment.
- Chronic Thromosis:Scheduled interventions for organized or subacute intracranial clots.
- Emergency Intervention:Time-critical procedures outside standard stroke protocols including trauma and iatrogenic occlusions.
- Non-Emergency Treatment:Elective thrombectomy for stable patients with accessible lesion anatomy.
Acute Ischemic Stroke anchors present volume. Emergency Intervention shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production investment toward jurisdictions with streamlined premarket pathways, as FDA breakthrough designations and Japan's Sakigake framework compress approval timelines relative to EU MDR conformity burdens.
United States
Joint Commission stroke center certification mandates drive hospital procurement across integrated delivery networks, with tertiary facilities in Texas, Florida, and California expanding 24/7 neurointerventional coverage. FDA breakthrough device pathways accelerate premarket review for novel aspiration platforms. The Cleveland Clinic and Mayo Clinic anchor clinical trial infrastructure in the Midwest, generating real-world evidence for extended therapeutic window protocols.
Germany
University hospitals under federal state hospital frameworks concentrate demand for stent retriever systems, with Baden-Württemberg and Bavaria hosting the highest procedural volumes. EU MDR technical documentation requirements reshape conformity assessment costs, favoring established manufacturers with regulatory affairs scale. The Stuttgart-Mannheim corridor houses specialized nitinol wire processing capabilities serving device producers.
Japan
PMDA Sakigake designation accelerates availability for acute stroke interventions, with Tokyo and Osaka metropolitan areas concentrating comprehensive stroke center investment. Aging demographics expand eligible patient populations for thrombectomy beyond traditional time windows. The Kobe biomedical cluster supports localized manufacturing of aspiration catheter components for Asia-Pacific distribution.
China
NMPA priority review pathways for innovative medical devices attract multinational joint ventures, with Shanghai and Beijing hosting regulatory strategy operations. Provincial health commissions in Guangdong and Jiangsu are certifying regional stroke centers at accelerating pace. The Suzhou Industrial Park clusters contract manufacturers serving both domestic and export markets.
Switzerland
Swissmedic's alignment with EU MDR standards enables parallel market access strategies, with Zurich and Geneva anchoring neurovascular R&D operations for European headquarters. Precision manufacturing capabilities in the Jura Arc support nitinol component production for stent retriever systems. The country's bilateral agreements with the EU mitigate notified body capacity constraints affecting continental competitors.
Cerebral Thrombectomy Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated neurovascular platforms commanding hospital system loyalty through enterprise-wide contracting while component suppliers capture value at the materials tier. The vendor base concentrates around three strategic archetypes: diversified medtech conglomerates with neurovascular divisions, pure-play thrombectomy specialists, and regional challengers leveraging regulatory proximity. Dominant competitive moves include backward integration into nitinol wire supply and strategic partnerships with stroke center certification consultancies.
Within the diversified medtech tier, Stryker Corporation and Medtronic occupy positions anchored by platform breadth across integrated delivery networks. Among specialists, Penumbra, Inc. exemplifies focused differentiation through proprietary aspiration technology. These three entities represent the competitive spectrum from consolidated portfolio players to targeted innovation shops, each deploying distinct value capture models against hospital procurement consolidation.
| Leading Market Players |
|---|
| Stryker Corporation |
| Medtronic |
| Penumbra, Inc. |
| MicroVention, Inc. |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Terumo Corporation |
| Imperative Care, Inc. |
| Acandis GmbH |
| Others |
Value Network & Pricing Analysis
Neurointerventionalist workforce concentration in the United States Midwest and Germany's Baden-Württemberg region creates labor-cost differentials that widen pricing-tier spreads between premium aspiration platforms and standard stent retriever systems.
Pricing Analysis
Capacity additions in China's Jiangsu and Guangdong provinces are reshaping price floors for nitinol wire components, compressing margins on standard-tier stent retrievers while premium aspiration systems with FDA breakthrough designation sustain value-based pricing. Three-tier pricing structure across premium, standard, and economy levels separates software-enabled platforms with per-procedure contracts from capital-only mechanical devices. Pricing pressure stems from EU MDR conformity assessment cost inflation affecting smaller manufacturers. Community hospitals in the United States exhibit highest price sensitivity, while tertiary stroke centers under Joint Commission certification mandates show lowest.
Supply Chain Analysis
Domestic-content mandates under China's NMPA priority review pathways are reshaping sourcing patterns, requiring multinational joint ventures to localize nitinol wire processing and catheter assembly operations. Supply concentrates in the United States for laser-cut stent retriever manufacturing, Germany for precision nitinol wire drawing, and Japan for aspiration catheter component finishing. Raw material dependencies center on nickel-titanium shape-memory alloys, specialized polymer extrusions for catheter shafts, and vacuum pump systems. Single-source vulnerability in nitinol wire supply creates structural risk. Distribution runs through hospital procurement committees and integrated delivery network enterprise contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FDA breakthrough pathway speed in the United States contrasts with EU MDR cost burdens, rewarding manufacturers with dual-track regulatory capabilities.
For Market Incumbents: Extend platform ecosystem lock-in through software-enabled per-procedure service contracts that bind hospital systems to integrated neurovascular portfolios. Anchor hospital loyalty via Joint Commission stroke certification consultancy partnerships. Counter emerging pure-play aspiration specialists by backward integration into nitinol wire supply. Prioritize R&D investment in hybrid pharmacomechanical platforms where premium positioning endures.
For New Entrants and Emerging Players: Launch via direct-to-aspiration technique diffusion in United States community hospitals previously constrained by stent retriever training infrastructure. Target underpenetrated emergency intervention segments outside standard stroke protocols. Exploit EU MDR notified body capacity constraints by pursuing FDA breakthrough designation first, then leveraging Swissmedic alignment for parallel European access. White-space exists in mobile stroke unit connectivity solutions.
For Investors and Strategic Acquirers: Diversified medtech conglomerates with neurovascular divisions are the most active acquirers in this space, seeking aspiration technology specialists to fill portfolio gaps. Long-term viability hinges on software-defined device architectures shifting revenue toward recurring utilization fees. Acquisition target archetype: pure-play aspiration catheter developers with proprietary separator technology. Watch for extended therapeutic window payer coverage determinations as inflection indicator for procedural volume ceilings.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway Pursuit | Expedited premarket review compresses competitive windows for novel aspiration platforms against EU MDR delays. |
| Software-Enabled Per-Procedure Contracting | Shifts revenue from capital equipment sales toward recurring utilization fees within hospital system ecosystems. |
| Joint Commission Stroke Certification Partnership | Locks hospital procurement eligibility through mandatory infrastructure investment in 24/7 neurointerventional coverage. |
| Backward Integration into Nitinol Wire Supply | Captures value at materials tier while mitigating single-source vulnerability and input cost volatility. |
| Hybrid Pharmacomechanical Platform Development | Creates premium positioning in comprehensive stroke centers through localized thrombolytic delivery convergence. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down device shipment tracking forms the analytical core of this study. Primary interviews with interventional neuroradiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers were validated against secondary sources including FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, hospital procurement registries, and EU MDR notified body documentation. Triangulation between demand-side procedure volume estimates and supply-side manufacturing capacity data ensures consistency across geographic segments.
Input-output matrices map nitinol wire feedstock through stent retriever and aspiration catheter production to end-use hospital consumption across the projection horizon. Segmentation dimensions modeled include product architecture, technology tier, end-user facility type, and procedure urgency classification. CAGRs were derived from regression analysis against stroke center certification mandates and payer coverage expansion trajectories. Forecast inputs incorporate neurointerventionalist workforce pipeline constraints and real-time perfusion imaging infrastructure penetration.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR notified body capacity bottlenecks or sudden shifts in large vessel occlusion triage protocols. Forecasts reflect assumptions regarding extended therapeutic window reimbursement determinations and software-enabled service contract adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Contact and Intraocular Lenses Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Stimulation Therapies Market
Medical Devices
Radiofrequency (RF) Ablation System Market
Medical Devices
Electronic Smart Mask Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Radial Compression Devices Market
Medical Devices
Cyberknife Technology Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
Anesthesia Resuscitators Masks Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
US Stethoscope Market
Medical Devices
Otorhinolaryngology Devices Market
Medical Devices
Bariatric Beds Market
Medical Devices
Syringe Scale Magnifiers Market