
 Wireless Neurostimulator Market | 2026-2036
Wireless Neurostimulator Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Neurostimulator Market Analytics
A capital-intensity divergence between fully integrated neuromodulation platforms and component-assemblers is rotating competitive advantage toward players with captive manufacturing of implantable pulse generators. Medtronic leverages vertical integration across device fabrication and clinical trial infrastructure to sustain premium positioning in deep brain stimulation systems. Abbott Laboratories anchors its portfolio through proprietary directional lead technology that differentiates its spinal cord stimulation offerings from commodity competitors.
Wireless neurostimulators are implantable or wearable electronic devices that deliver precisely modulated electrical impulses to targeted neural structures via radiofrequency or inductive coupling, typically operating at frequencies between 1-40 MHz with biocompatible titanium or polymer enclosures designed for multi-year residence in physiological environments. These systems serve therapeutic purposes across chronic neurological conditions by interrupting pain signal transmission or restoring dysfunctional neural circuit activity. Implantable devices dominate current revenue pools due to higher per-procedure pricing and recurring battery replacement cycles, while wearable peripheral nerve stimulation platforms represent the fastest-expanding segment as ambulatory care models gain traction. Hospitals remain the primary end-user channel, though pain management centers are capturing disproportionate growth by specializing in minimally invasive neurostimulation trials that reduce total cost of care.
The FDA's breakthrough devices program and the EU Medical Device Regulation reshape product development timelines, with the former compressing premarket review for novel neuromodulation indications and the latter imposing stricter clinical evidence requirements on legacy device renewals. ISO 14708 active implantable medical device standards govern electromagnetic compatibility and battery safety, directly influencing design specifications that manufacturers must satisfy for multi-jurisdiction market access. Stakeholders should monitor evolving CMS reimbursement decisions for closed-loop adaptive stimulation algorithms, as coverage determinations will determine whether next-generation systems achieve commercial scale or remain confined to cash-pay specialty practices.
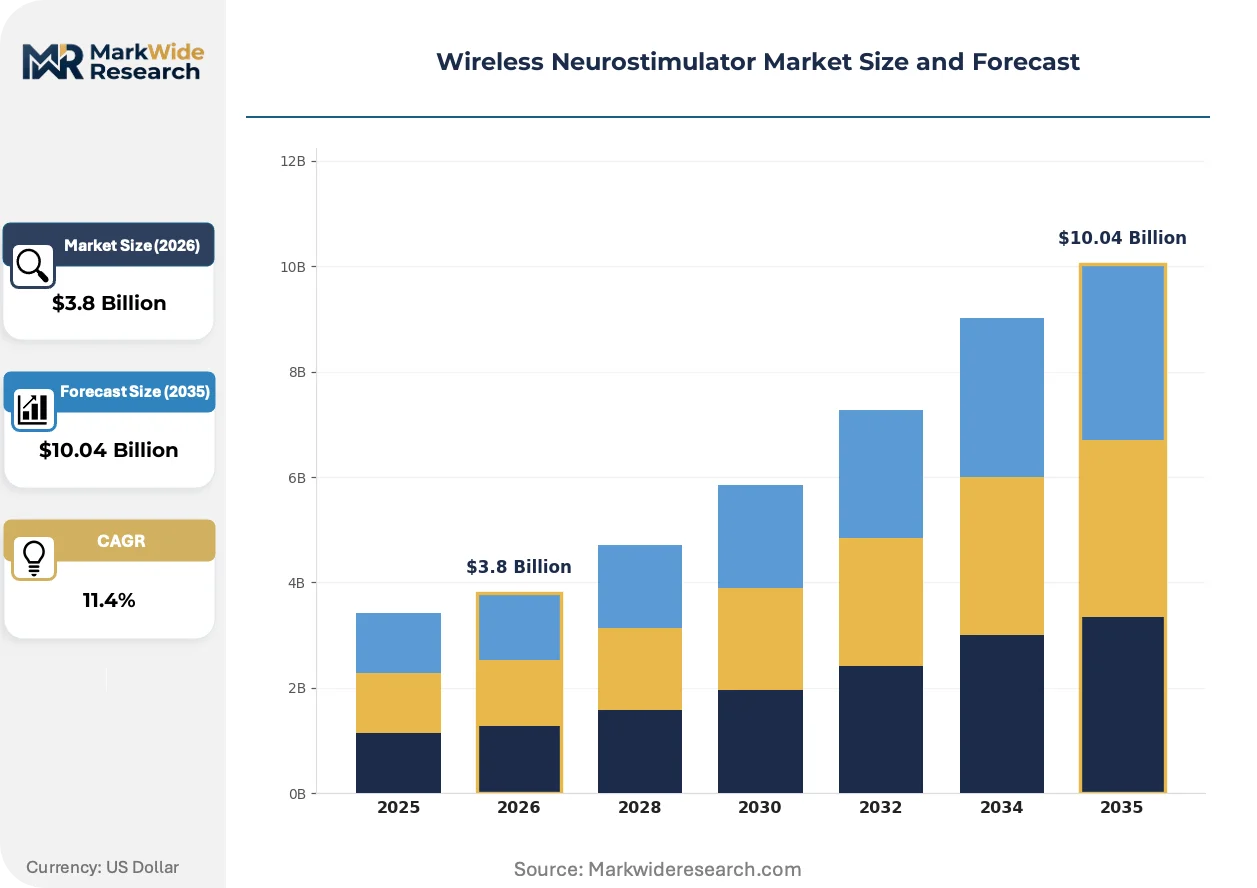
Market Dynamics
Closed-loop adaptive stimulation algorithms are compressing development timelines while fragmenting competitive positioning between algorithm developers and legacy hardware manufacturers. The FDA breakthrough device designation pathway accelerates premarket review for neuromodulation systems incorporating real-time biosignal feedback.
Growth Catalysts
- Peripheral nerve stimulation reimbursement:CMS coverage determinations for non-spinal indications expand addressable patient populations beyond traditional spinal cord stimulation candidates in United States pain management centers.
- Ambulatory surgical center migration:Minimally invasive implantation techniques enable same-day discharge protocols that reduce total procedure costs and expand site-of-care options for chronic pain patients.
- ISO 14708 electromagnetic compatibility standards:Harmonized active implantable device requirements streamline multi-jurisdiction regulatory submissions, compressing time-to-market for manufacturers targeting both FDA and EMA pathways.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing capacity concentrates in East Asian chemical suppliers, exposing implantable pulse generator manufacturers to input cost volatility and dual-use export control risks.
- EU Medical Device Regulation clinical evidence requirements:Legacy device renewals face retrospective clinical data collection mandates that extend certification timelines and strain post-market surveillance budgets.
- Pharmacological pain management substitution:Extended-release opioid formulations and non-opioid analgesics retain first-line status in many European national formularies, limiting neurostimulator penetration in conservative prescribing environments.
Strategic Opportunities
- India chronic pain infrastructure:Underpenetrated implantable neurostimulator penetration in tertiary care hospitals creates whitespace for wearable peripheral nerve stimulation platforms targeting neuropathic pain indications.
- Japan PMDA regenerative medicine product pathway:Convergence of neurostimulation with cell-based therapies for Parkinson's disease qualifies for expedited review, enabling novel indication expansion beyond pain management.
- Closed-loop algorithm licensing:Revenue-sharing arrangements between hardware OEMs and AI-driven biosignal processing software vendors unlock recurring revenue streams independent of device replacement cycles.
Industry Challenges
- Neurophysiology-clinical engineering talent scarcity:Cross-functional expertise spanning neural signal processing, biocompatibility engineering, and regulatory strategy commands premium compensation, constraining R&D team scaling.
- Multi-jurisdiction certification synchronization:Divergent electromagnetic compatibility testing protocols between FDA, PMDA, and NMPA create redundant validation cycles that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Neurostimulator Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Devices, Wearable Devices, Portable Devices, Neuromodulation Systems End User: Hospitals, Clinics, Pain Management Centers, Rehabilitation Facilities Technology: Transcranial Magnetic Stimulation, Deep Brain Stimulation, Spinal Cord Stimulation, Peripheral Nerve Stimulation Application: Chronic Pain Management, Mental Health Disorders, Epilepsy Treatment, Stroke Rehabilitation |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott Laboratories, Nevro Corporation, LivaNova PLC, NeuroPace Inc., Axonics Inc., Saluda Medical, ElectroCore Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Neurostimulator Market Evolving Landscape
Algorithmic personalization is displacing fixed-parameter stimulation protocols across implantable neurostimulator portfolios. Real-time biosignal interpretation enables therapy adjustment without clinician intervention.
Directional lead technology with independent current control is supplanting cylindrical quadripolar designs in spinal cord stimulation systems. Pain management specialists at United States academic medical centers are adopting these platforms for targeted dorsal column activation. The shift is compressing revision surgery rates while elevating hardware pricing premiums over commodity cylindrical alternatives.
EU Medical Device Regulation post-market clinical follow-up requirements are extending surveillance obligations for legacy neuromodulation systems. Manufacturers must now collect real-world performance data across distributed implant registries. High-volume spinal cord stimulation portfolios face disproportionate compliance cost burdens compared to emerging peripheral nerve platforms with smaller installed bases.
Hospital procurement committees are consolidating neurostimulator vendor relationships to secure volume-based pricing and standardized training protocols. Single-source agreements are displacing multi-vendor competitive bidding at United States health systems exceeding five-hundred beds. The concentration is visible most acutely in Midwestern integrated delivery networks where supply chain rationalization initiatives target implantable device categories.
Wireless Neurostimulator Market Segmentation
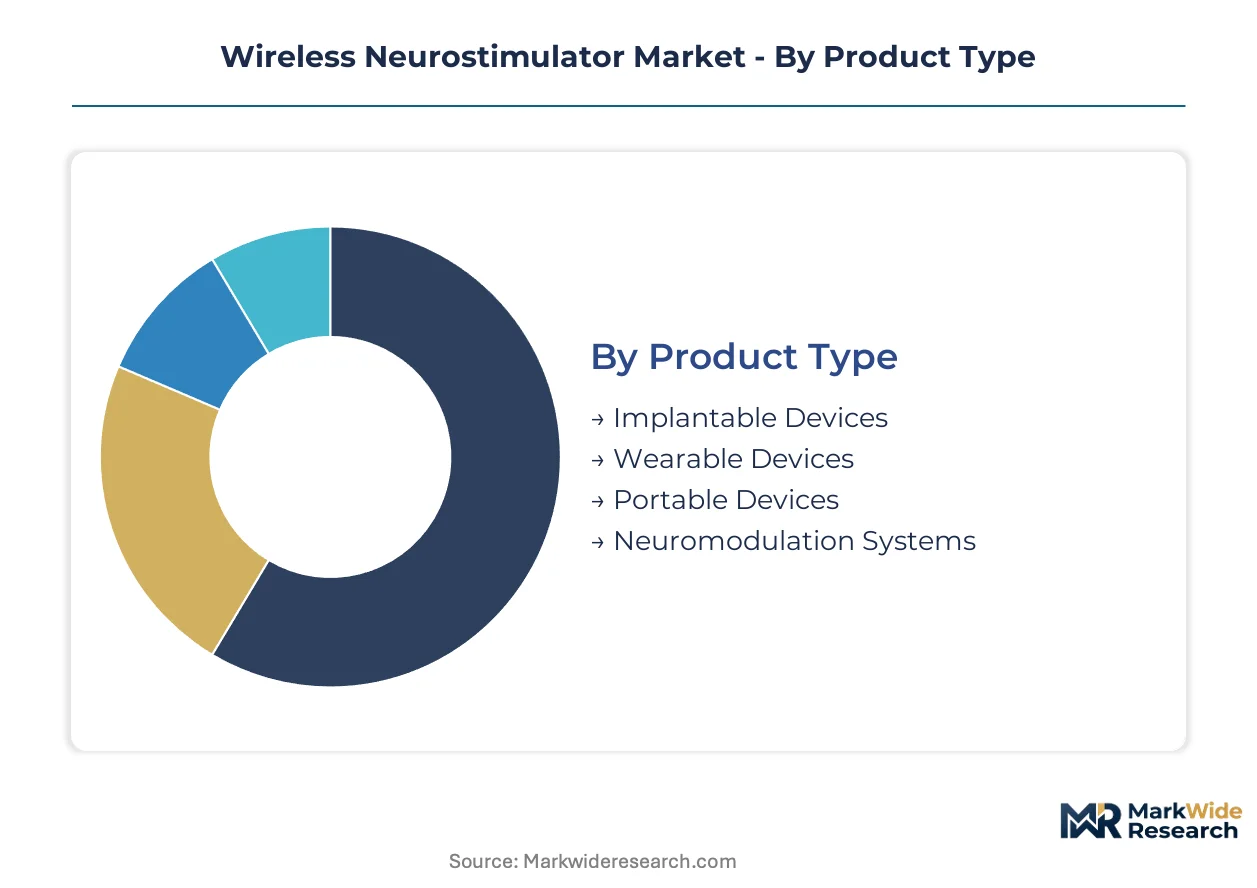
Wireless neurostimulator segmentation reveals divergent regulatory pathways across product architectures. Implantable systems face active implantable medical device standards while wearables navigate simpler electrical safety classifications. These distinctions reshape capital allocation and geographic prioritization for manufacturers.
Product Type:
FDA breakthrough device designation and EU MDR classification intensity vary sharply across physical form factors, concentrating R&D investment toward categories with clearer premarket review timelines.
- Implantable Devices:Titanium or polymer-encased pulse generators with multi-year battery residence deliver precisely modulated electrical impulses via radiofrequency coupling at 1-40 MHz. United States pain management centers concentrate demand for spinal cord and deep brain configurations as CMS reimbursement frameworks mature for invasive neuromodulation procedures. The category handles the majority of throughput; Wearable Devices is the fastest mover on share.
- Wearable Devices:External peripheral nerve stimulation platforms with ambulatory biosignal monitoring enable same-day discharge protocols. Pain management centers in United States academic medical systems are capturing disproportionate growth by specializing in minimally invasive neurostimulation trials that reduce total cost of care.
- Portable Devices:Handheld or belt-worn units for temporary neural modulation outside clinical settings.
- Neuromodulation Systems:Integrated hardware-software platforms combining implantable generators with external programming interfaces.
Implantable hardware commands premium pricing through recurring battery replacement cycles; wearable platforms are climbing the fastest on patient volume expansion.
End User:
Procurement authority and clinical trial infrastructure concentration determine site-of-care economics across United States delivery networks.
- Hospitals:Tertiary care institutions with catheterization laboratories and neurosurgical suites handle complex deep brain stimulation implantation requiring intraoperative neurophysiological monitoring. United States health systems exceeding five-hundred beds are consolidating vendor relationships to secure volume-based pricing and standardized training protocols.
- Pain Management Centers:Specialty clinics with dedicated neuromodulation trial programs enable rapid patient selection for permanent implantation. Midwestern integrated delivery networks are rationalizing supply chains toward single-source agreements in this category.
- Clinics:Outpatient facilities with limited surgical capability focusing on wearable peripheral nerve stimulation.
- Rehabilitation Facilities:Post-acute centers integrating neurostimulation with physical therapy protocols for stroke recovery.
Hospitals retain the highest revenue per procedure; pain management centers are gaining share fastest through ambulatory surgical center migration.
Technology:
Electromagnetic compatibility testing protocols diverge between invasive and non-invasive neural interfaces, fragmenting certification synchronization across FDA, PMDA, and NMPA pathways.
- Spinal Cord Stimulation:Epidurally implanted quadripolar or directional leads with independent current control target dorsal column activation for chronic pain. United States academic medical centers are adopting proprietary directional lead technology that differentiates offerings from commodity cylindrical alternatives.
- Deep Brain Stimulation:Bilateral subthalamic or globus pallidus interna targeting for movement disorders requires stereotactic neurosurgical placement. Japan PMDA regenerative medicine product pathway enables convergence with cell-based therapies for Parkinson's disease, qualifying for expedited review.
- Peripheral Nerve Stimulation:Subcutaneous lead placement adjacent to named peripheral nerves for localized pain control.
- Transcranial Magnetic Stimulation:Non-invasive cortical modulation using time-varying magnetic fields, regulated as electrical stimulation devices rather than active implants.
Spinal cord configurations dominate current revenue pools; peripheral nerve stimulation is expanding most quickly on CMS coverage determination expansion.
Application:
Clinical evidence requirements under EU MDR post-market clinical follow-up extend surveillance obligations disproportionately toward large installed-base indications.
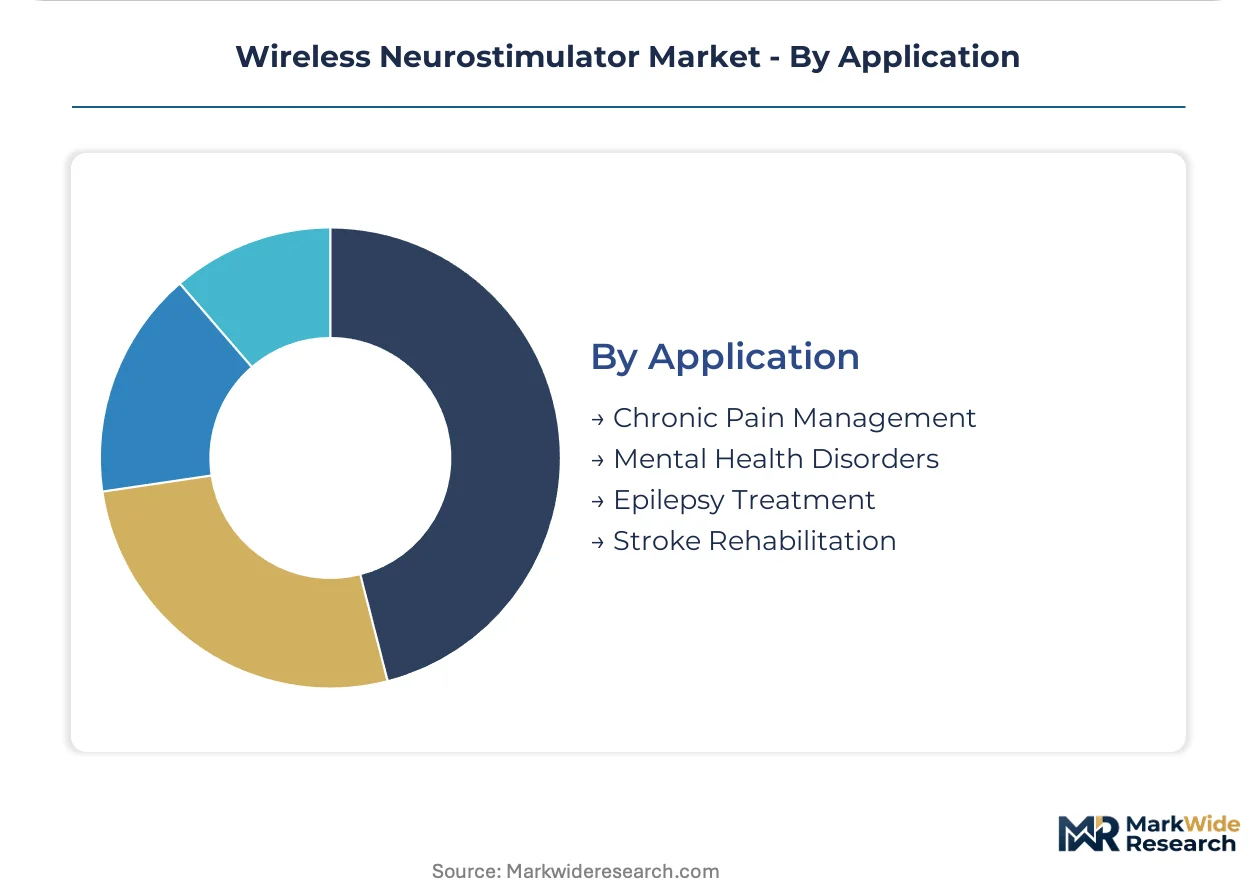
- Chronic Pain Management:Failed back surgery syndrome and complex regional pain syndrome represent primary indications with established reimbursement. United States CMS coverage determinations for non-spinal peripheral nerve indications are expanding addressable patient populations beyond traditional spinal cord stimulation candidates.
- Epilepsy Treatment:Responsive neurostimulation with closed-loop seizure detection and intervention requires long-term real-world performance data collection across distributed implant registries under EU MDR mandates.
- Mental Health Disorders:Treatment-resistant depression and obsessive-compulsive disorder applications face pharmacological substitution competition from extended-release opioid and non-opioid analgesics in European national formularies.
- Stroke Rehabilitation:Cortical or peripheral stimulation combined with task-specific training to enhance motor recovery.
Chronic pain management commands the dominant procedure volume; stroke rehabilitation is gaining share fastest on aging population prevalence expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in wireless neurostimulation hardware favor net-importing markets with mature reimbursement frameworks. The United States maintains substantial trade deficits in implantable pulse generators while exporting specialized lead components to European assembly facilities.
United States
Chronic pain management clinics in Midwestern integrated delivery networks drive implantable spinal cord stimulator volume. FDA breakthrough device designation compresses premarket review timelines for neuromodulation systems with closed-loop algorithms. Minneapolis and Boston anchor concentrated manufacturing clusters where captive production of titanium enclosures supports premium-tier positioning.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia specialize in deep brain stimulation implantation requiring intraoperative neurophysiological monitoring. EU Medical Device Regulation post-market clinical follow-up mandates extend surveillance obligations for legacy neuromodulation systems. The Stuttgart industrial corridor houses precision machining suppliers serving implantable pulse generator fabrication.
Japan
Aging demographics expand addressable patient populations for movement disorder applications beyond traditional pain management. PMDA regenerative medicine product pathway enables convergence of neurostimulation with cell-based therapies for Parkinson's disease. The Kanto region around Tokyo concentrates demand for stereotactic neurosurgical placement capabilities.
India
Underpenetrated implantable neurostimulator adoption in tertiary care hospitals creates whitespace for wearable peripheral nerve stimulation platforms. CDSCO regulatory harmonization with ISO 14708 active implantable medical device standards streamlines import clearance for multinational manufacturers. Maharashtra and Karnataka host emerging distribution hubs targeting neuropathic pain indications in urban centers.
China
Domestic demand for non-invasive cortical modulation devices outpaces invasive implantable system adoption due to conservative surgical referral patterns. NMPA electromagnetic compatibility testing protocols diverge from FDA standards, creating redundant validation cycles for multi-jurisdiction submissions. Yangtze River Delta manufacturing clusters supply biocompatible polymer enclosures to regional device assemblers.
Wireless Neurostimulator Market Competitive Landscape
Concentration sits with diversified medtech conglomerates possessing captive manufacturing of implantable pulse generators and clinical trial infrastructure. Mid-cap specialists in closed-loop algorithm development fragment the software layer through licensing arrangements with hardware OEMs. Two strategic archetypes dominate: vertically integrated neuromodulation platforms spanning device fabrication through post-market surveillance, and component-assemblers relying on outsourced titanium enclosure supply. Competitive moves center on strategic partnerships between algorithm developers and legacy hardware manufacturers, plus geographic expansion into underpenetrated Asian markets through distributor acquisitions.
Among diversified medtech conglomerates, Medtronic and Boston Scientific Corporation exemplify the vertically integrated archetype with in-house production capabilities spanning lead fabrication through pulse generator assembly. Abbott Laboratories occupies a differentiated position through proprietary directional lead technology. Nevro Corporation and LivaNova PLC represent mid-scale specialists competing on algorithmic personalization rather than manufacturing scale. Smaller innovators including NeuroPace Inc., Axonics Inc., and Saluda Medical sit within the emerging closed-loop adaptive stimulation tier, licensing biosignal processing capabilities to larger OEMs rather than competing on hardware volume.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Nevro Corporation |
| LivaNova PLC |
| NeuroPace Inc. |
| Axonics Inc. |
| Saluda Medical |
| ElectroCore Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-to-one-hundred-day lead times for biocompatible titanium enclosures concentrate pricing power with East Asian forging suppliers, compressing margins for implantable pulse generator assemblers while elevating premiums for manufacturers with captive machining capabilities in Minneapolis and Boston industrial clusters.
Pricing Analysis
Configured-to-order pricing for patient-specific lead geometries commands spreads exceeding standard catalog configurations, with three-tier pricing structure across premium, standard, and economy levels stratifying by ISO 14708 certification tier and after-sales programming support bundling. Price differentiation hinges on electromagnetic compatibility testing documentation depth and geographic delivery cost from Midwestern distribution hubs. Pricing pressure stems from lithium-ion cathode material cost volatility transmitted through battery supplier contracts. Pain management centers in United States academic medical systems exhibit highest price sensitivity due to GPO consolidated purchasing, while tertiary hospitals with neurosurgical suites absorb premium positioning for deep brain stimulation systems.
Supply Chain Analysis
Inbound logistics costs through Los Angeles and Rotterdam ports constrain just-in-time inventory models for biocompatible polymer feedstocks, with container availability fluctuations amplifying working capital requirements for European assembly facilities. Geographic supply concentration centers on China for rare earth magnet processing, Japan for precision capacitor fabrication, and Germany for titanium alloy forging. Raw material dependencies span lithium cobalt oxide cathodes, platinum-iridium electrode alloys, and medical-grade silicone encapsulants. Single-source vulnerability in East Asian chemical processing exposes manufacturers to dual-use export control disruptions. Distribution runs through specialized medical device distributors with temperature-controlled logistics certification rather than generalist healthcare supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital procurement committee consolidation at United States health systems exceeding five-hundred beds, fragmenting vendor access for mid-scale neuromodulation specialists.
For Market Incumbents: Fortify captive manufacturing of implantable pulse generators through backward integration into titanium enclosure forging, insulating margin structures from East Asian supplier pricing volatility. Deepen hospital system partnerships with standardized training protocols that embed switching costs, defending against closed-loop algorithm licensing entrants threatening hardware commoditization. For New Entrants and Emerging Players: Differentiate on ambulatory peripheral nerve stimulation platforms targeting India tertiary care hospitals where implantable penetration remains underdeveloped. White-space concentrates in wearable neuropathic pain indications with same-day discharge protocols, leveraging CDSCO regulatory harmonization to compress import clearance timelines versus invasive system competitors. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because closed-loop algorithm developers fragment the software layer while hardware OEMs seek biosignal processing capabilities to defend premium positioning. Acquisition targets with FDA breakthrough device designation momentum and proprietary directional lead IP command strategic scarcity premiums. The signal to watch is CMS coverage determination timing for adaptive stimulation algorithms, which will separate scaled commercial platforms from cash-pay niche players.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates premarket review for closed-loop neuromodulation systems with real-time biosignal feedback capabilities. |
| Hospital System Partnership | Secures volume-based pricing and standardized training protocols at Midwestern integrated delivery networks. |
| Closed-Loop Algorithm Licensing | Unlocks recurring revenue streams independent of hardware replacement cycles through AI-driven biosignal processing. |
| Backward Integration into Titanium Forging | Insulates implantable pulse generator margins from East Asian supplier concentration and export control risks. |
| Reimbursement Strategy | Determines commercial scale for next-generation adaptive stimulation systems through CMS coverage decisions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pain management specialists, hospital purchasing committee members, biomedical engineers at implantable device manufacturers, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, CMS national coverage determinations, ISO 14708 certification registries, and hospital procurement database extracts. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product architecture, technology type, end-user site-of-care, and geographic regulatory cluster. CAGRs derived from procedure volume trajectories weighted by reimbursement pathway maturity and technology adoption S-curve positioning. Industry-specific forecast inputs incorporated lithium-ion battery supply elasticity and EU MDR post-market surveillance cost burdens.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement expansion for peripheral nerve indications or prolonged lithium supply disruption would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway timelines and hospital consolidation velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Anti-Blue Ray Myopia Lenses Market
Medical Devices
IoT Medical Devices Market
Medical Devices
Ventilator Accessories Market
Medical Devices
Bone Conduction Hearing Aids Market
Medical Devices
Baby Thermometer Market
Medical Devices
Mobile Operating Rooms Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Interspinous Process Decompression Devices Market
Medical Devices
Biological Microscope Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Silastic Implant Market
Medical Devices
Inhaled Corticosteroid Device Market
Medical Devices
Medical Machine Battery Market