
 Middle East and Africa Medical Devices Market | 2026-2036
Middle East and Africa Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Medical Devices Market Foresight
South Africa's domestic medical device manufacturing base is tilting toward diagnostic assembly and consumables production to reduce import dependency. Siemens Healthineers leverages its imaging installed base across sub-Saharan hospital networks to sustain service revenue streams. Medtronic anchors its regional presence through cardiac rhythm management device distribution partnerships with private hospital groups in the Gulf. Koninklijke Philips N.V. competes on point-of-care ultrasound and patient monitoring systems tailored to resource-variable clinical settings.
Medical devices encompass instruments, apparatus, implants, and software intended for diagnosis, prevention, monitoring, or treatment of disease, typically requiring biocompatibility testing and sterilization validation per ISO 13485 quality management standards. Their primary purpose spans acute intervention, chronic disease management, and clinical workflow optimization across healthcare delivery systems. Imaging Equipment commands substantial capital allocation from tertiary hospitals investing in magnetic resonance and computed tomography capacity, while Wearable Technology emerges as the fastest-expanding technology segment driven by remote patient monitoring programs in the UAE and Saudi Arabia. Diagnostic Devices maintains mature, high-volume demand through blood glucose monitoring and point-of-care testing platforms deployed in clinic networks.
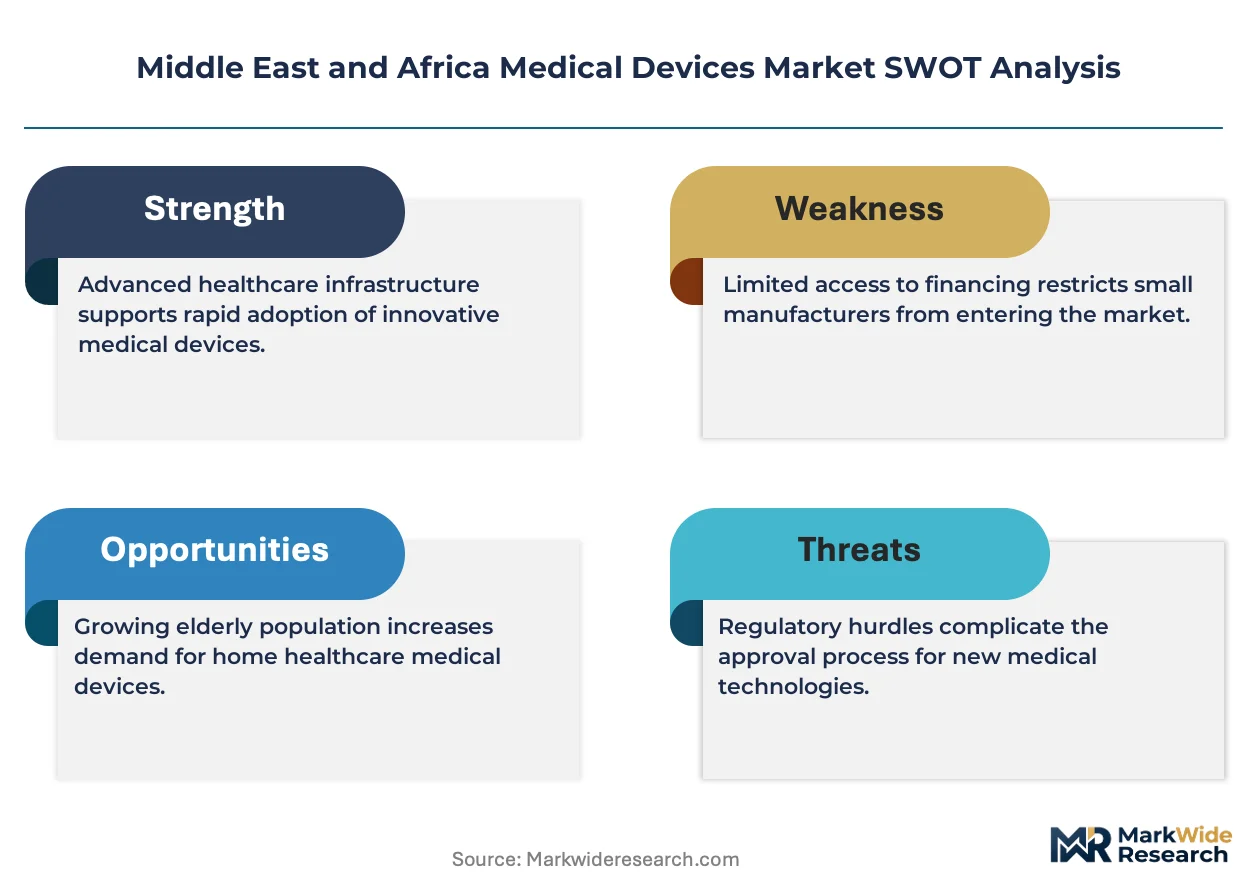
Saudi Arabia's SFDA enforces medical device marketing authorization requirements aligned with Global Harmonization Task Force principles, while South Africa's national health regulator mandates licensing through the Medicines Control Council pathway for higher-risk device classes. The UAE's Ministry of Health and Prevention operates a product registration system that conditions market entry on evidence of prior approval by recognized reference regulators. Stakeholders must monitor convergence between Gulf national regulatory frameworks and the African Medicines Agency's emerging harmonization protocols to anticipate compliance burdens and first-mover positioning.
Market Dynamics
Hospital procurement consolidation across Gulf Cooperation Council states is compressing distributor margins and forcing direct manufacturer engagement with centralized purchasing authorities in Saudi Arabia and the UAE.
Growth Catalysts
- SFDA Marketing Authorization Pathways:Saudi Arabia's streamlined registration aligned with Global Harmonization Task Force principles accelerates product entry for Class II and III devices, reducing time-to-revenue for compliant manufacturers.
- Remote Patient Monitoring Mandates:UAE Ministry of Health and Prevention digital transformation directives compel hospital networks to deploy wearable-connected monitoring infrastructure, creating pull-through for integrated device ecosystems.
- South African Private Hospital Expansion:Netcare and Mediclinic capital expenditure programs for surgical theater upgrades drive replacement demand for advanced imaging and anesthesia delivery systems.
Market Restraints
- Import Duty Volatility:Egyptian pound depreciation and periodic tariff recalibrations on electromechanical medical equipment inflate landed costs for European and Asian OEMs serving public hospital tenders.
- Single-Source Dependency:Contrast media and specialized catheter supply chains concentrate through Dubai's Jebel Ali Free Zone, exposing distributors to port congestion and geopolitical shipping disruptions.
- Reimbursement Fragmentation:South Africa's split public-private health financing creates divergent pricing ceilings, complicating pan-African portfolio strategies for multinational device manufacturers.
Strategic Opportunities
- Egyptian Public Health Infrastructure:Government hospital construction in Cairo, Alexandria, and the Delta region opens greenfield deployment of diagnostic imaging and surgical suites without legacy equipment displacement costs.
- African Medicines Agency Harmonization:Emerging centralized regulatory pathways promise reduced duplication of clinical evidence requirements across 15+ member states, lowering market entry barriers for higher-risk device classes.
- Point-of-Care Ultrasound Convergence:Integration of artificial intelligence-assisted image interpretation with handheld probe hardware enables deployment in resource-variable settings previously served by cart-based systems.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Gulf hospital networks compete for limited pools of MRI and CT service technicians, extending equipment downtime and compressing service contract profitability.
- ISO 13485 Certification Timelines:Notified body backlogs for quality management system audits delay product launches by 8-14 months, particularly affecting mid-cap manufacturers without established regulatory affairs capacity.
- Legacy PACS Integration Complexity:New diagnostic imaging installations must interface with decade-old picture archiving systems in South African public hospitals, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Medical Devices Market |
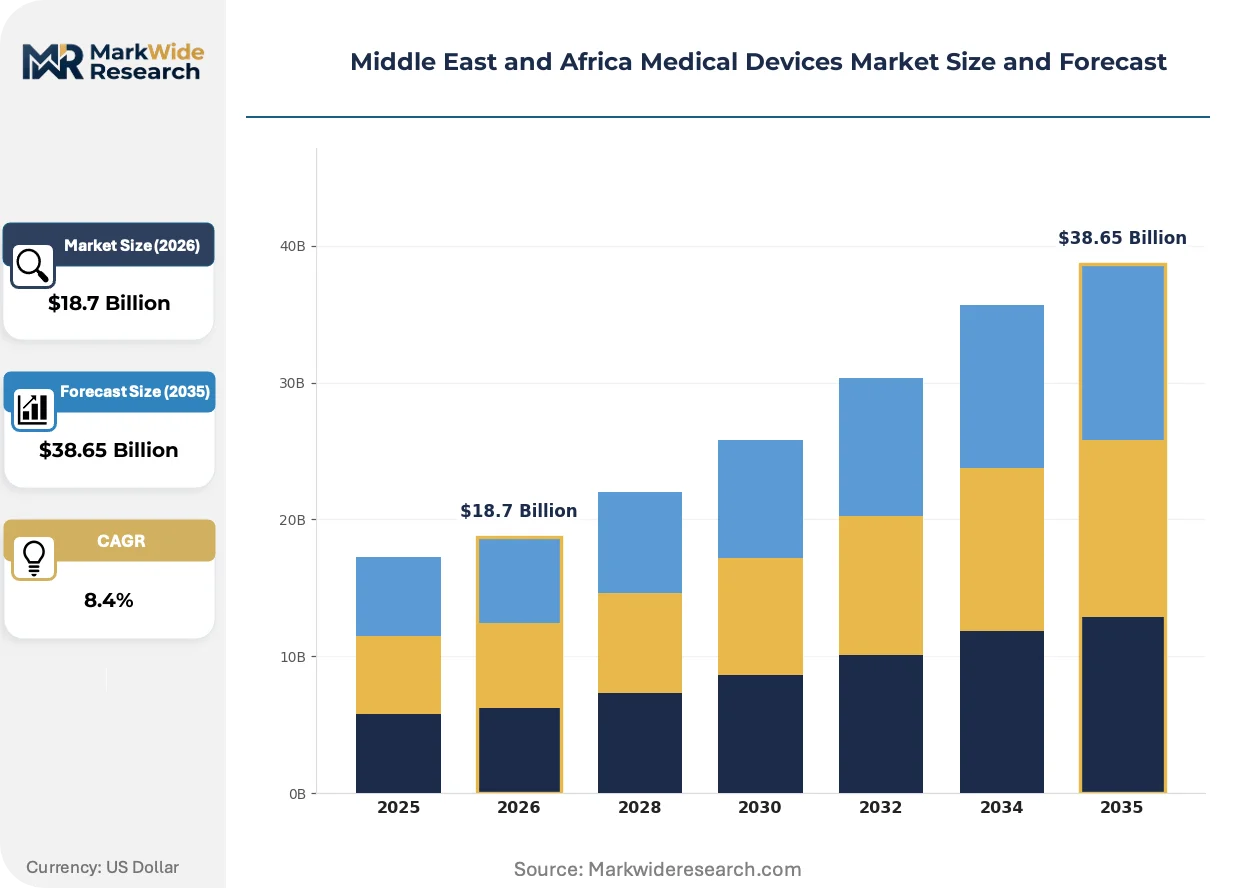
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Devices, Surgical Instruments, Imaging Equipment, Therapeutic Devices End User: Hospitals, Clinics, Home Healthcare, Rehabilitation Centers Technology: Wearable Technology, Robotic Surgery, Telemedicine, 3D Printing Application: Cardiology, Orthopedics, Neurology, Dermatology |
| Companies Covered | Siemens Healthineers, Stryker, Medtronic, F. Hoffmann-La Roche Ltd, B. Braun SE, Koninklijke Philips N.V., Johnson & Johnson, Getinge AB, GE HealthCare, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Medical Devices Market Shifts & Advancements
Artificial intelligence integration and portable diagnostic form factors are compressing the traditional hospital-centric device distribution model across Middle East and African healthcare systems.
Handheld ultrasound systems with embedded AI guidance are rendering obsolete the assumption that diagnostic imaging requires dedicated radiology departments and capital-intensive fixed installations. Primary care clinics in Saudi Arabia's remote governorates and South African rural health districts are adopting these devices for triage and referral decisions. The technology is compressing patient pathways by enabling point-of-care diagnosis without transport to tertiary facilities.
Saudi Arabia's SFDA has implemented post-market surveillance requirements mandating adverse event reporting through centralized digital platforms, mirroring EU MDR vigilance obligations. This regulatory convergence forces manufacturers to maintain localized quality management infrastructure rather than relying on distributor-mediated compliance. Higher-risk implantable device segments face the steepest adaptation burden as periodic safety update reporting becomes mandatory.
Hospital group procurement consortia in the UAE and Saudi Arabia are consolidating purchasing power and unbundling after-sales service contracts from equipment supply agreements. This disintermediation pressures traditional distributor margins and compels manufacturers to establish direct service operations or certify third-party technical partners. The shift is most visible in cardiac catheterization lab equipment tenders across Dubai Health Authority-affiliated facilities.
Middle East and Africa Medical Devices Market Segmentation
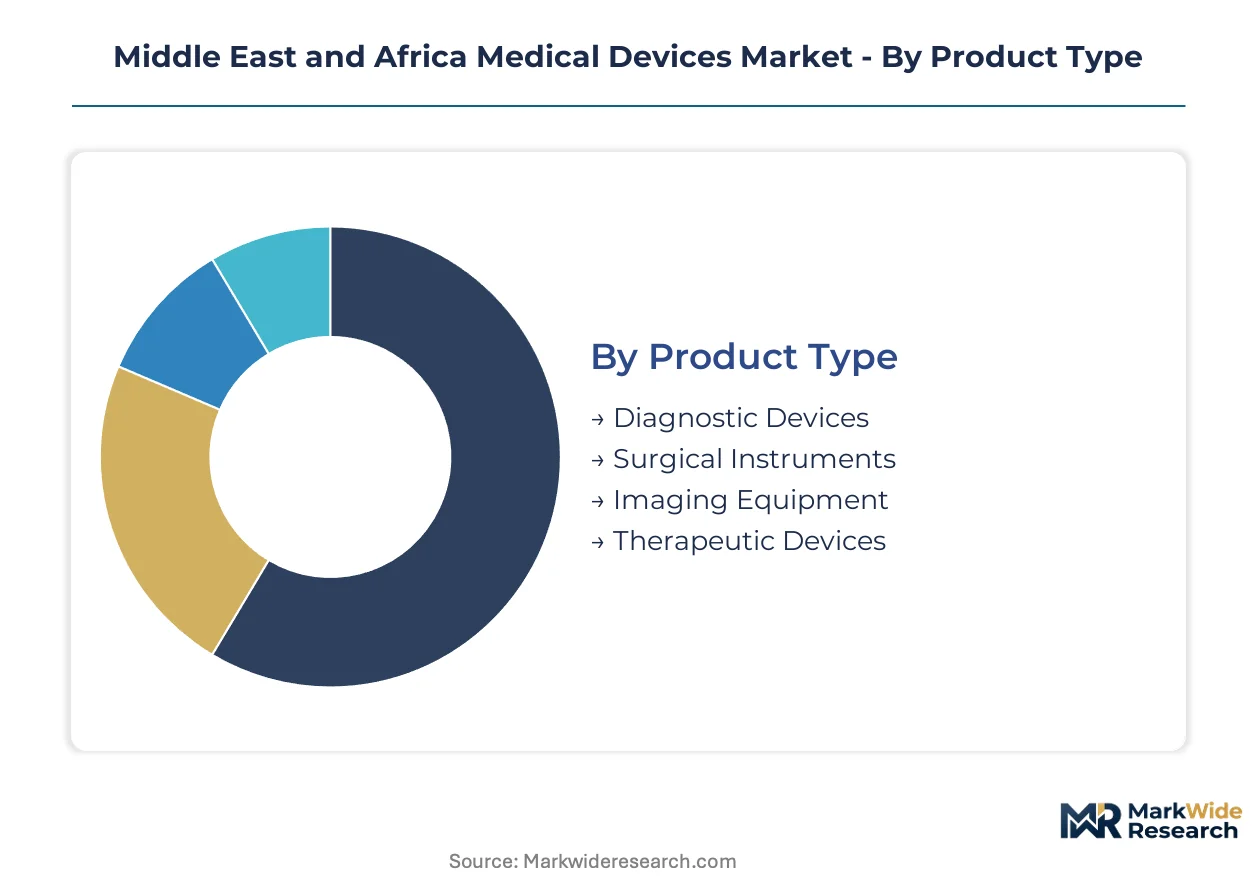
Segmentation reveals how procurement cycles, reimbursement pathways, and clinical workflows fragment demand across the Middle East and Africa medical devices market. Understanding these divisions enables manufacturers to align portfolio investments with the divergent capital expenditure rhythms of Gulf hospital networks versus African public health infrastructure.
Product Type:
Replacement cycles stretch from months for consumables to a decade for capital equipment, creating distinct cash flow profiles and service revenue opportunities.
- Imaging Equipment:Magnetic resonance and computed tomography systems anchor tertiary hospital capital budgets across Saudi Arabia and the UAE. Procurement concentrates through centralized Gulf Cooperation Council purchasing authorities with extended tender cycles and bundled service expectations.
- Diagnostic Devices:Blood glucose monitors, point-of-care testing platforms, and rapid diagnostic kits turn over fastest through clinic networks and retail pharmacy channels. Egyptian public health expansion and South African private laboratory chains drive recurring consumable demand.
- Surgical Instruments:Reusable and single-use instruments serve operating theater upgrades across Netcare and Mediclinic facilities in South Africa.
- Therapeutic Devices:Infusion pumps, ventilators, and dialysis equipment deploy across hospital and home care settings with mixed reimbursement coverage.
Diagnostic Devices anchors the volume base while Imaging Equipment gains share at the steepest rate.
End User:
Customer concentration varies sharply between consolidated Gulf hospital groups and fragmented African clinic networks, altering distribution economics.
- Hospitals:Tertiary facilities in Dubai, Riyadh, and Johannesburg concentrate demand for advanced surgical and imaging systems. Saudi Arabia's SFDA registration requirements and UAE Ministry of Health procurement mandates shape vendor qualification timelines.
- Clinics:Primary care and specialty clinics across Egypt's Delta region and South African urban corridors deploy point-of-care diagnostics with shorter procurement cycles.
- Home Healthcare:Remote patient monitoring programs in the UAE and Saudi Arabia pull through wearable-connected device ecosystems for chronic disease management.
- Rehabilitation Centers:Physical therapy and post-acute facilities in Gulf states and South Africa's private network absorb mobility and respiratory therapy equipment.
Hospitals capture the dominant revenue share while Home Healthcare expands most quickly on digital health mandate tailwinds.
Technology:
Technology maturity curves diverge between established telemedicine infrastructure and nascent robotic platforms requiring specialized training ecosystems.
- Wearable Technology:Connected monitoring devices integrate with UAE Ministry of Health digital transformation mandates for remote patient surveillance. Battery life, data security certification, and interoperability with hospital EMR systems determine procurement decisions.
- Telemedicine:Video consultation platforms and remote diagnostic tools serve South African rural health districts and Saudi Arabia's remote governorates where specialist access is constrained.
- Robotic Surgery:Da Vinci and comparable systems deploy selectively in Dubai Health Authority-affiliated facilities with trained surgical teams and high procedural volumes.
- 3D Printing:Patient-specific implants and surgical guides emerge in Gulf private hospital networks with dedicated biomedical engineering capacity.
Telemedicine sustains the broadest installed base while Wearable Technology climbs the fastest on regulatory mandate enforcement.
Application:
Disease burden patterns and reimbursement availability concentrate investment in cardiac and orthopedic interventions across the region's aging populations.
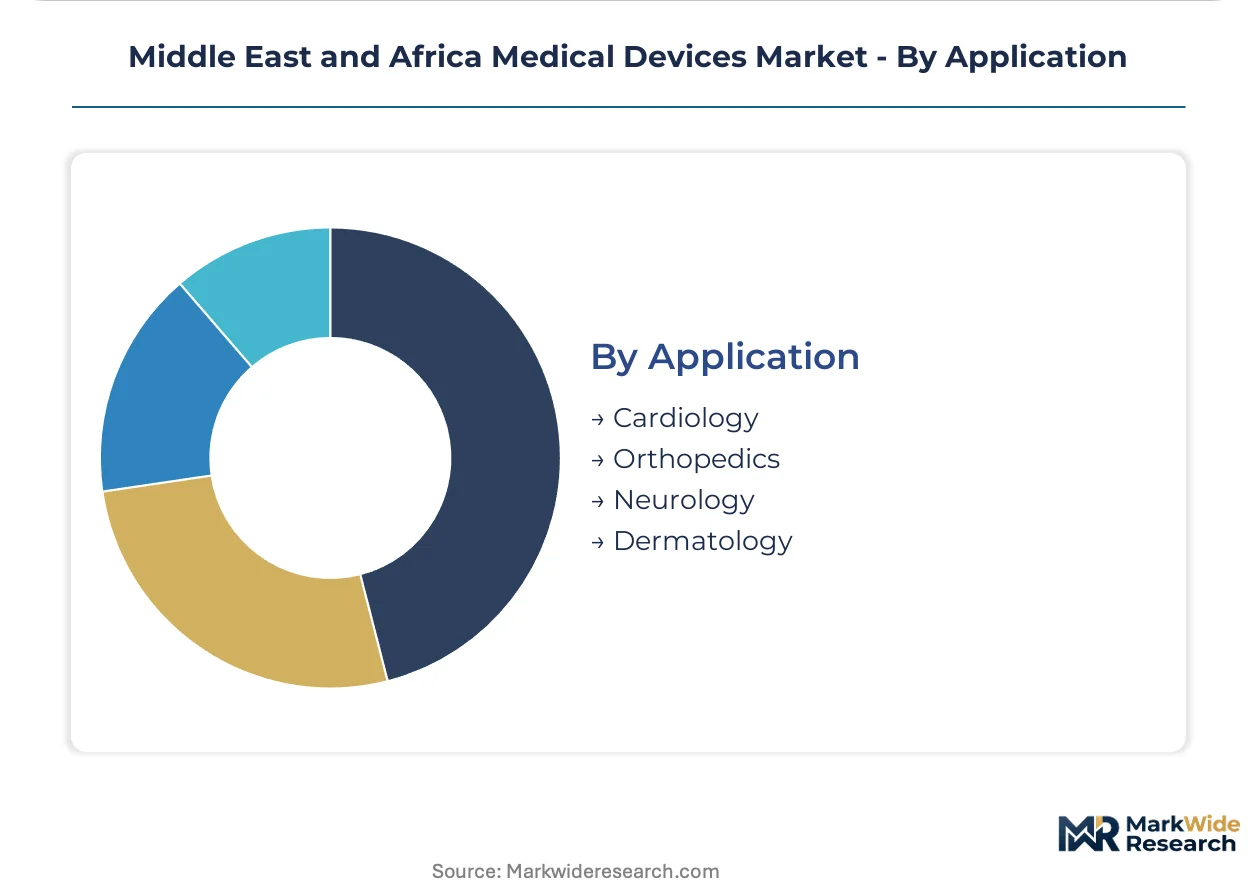
- Cardiology:Cardiac rhythm management devices, catheterization lab equipment, and interventional tools serve Gulf private hospital networks. Medtronic distribution partnerships and direct manufacturer service operations compete for replacement cycles.
- Orthopedics:Joint replacement implants and trauma fixation devices address South Africa's private hospital expansion and Egyptian public hospital construction programs.
- Neurology:Deep brain stimulation and neurodiagnostic equipment deploy in specialized tertiary centers with concentrated specialist expertise.
- Dermatology:Aesthetic and clinical dermatology devices serve Gulf medical tourism corridors and South African private practice networks.
Cardiology commands the highest equipment values per procedure while Orthopedics scales most broadly across public and private settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA registration pathways in Saudi Arabia anchor procurement standards across Gulf Cooperation Council states, while South Africa's Medicines Control Council and Egypt's health ministry shape divergent compliance requirements for sub-Saharan and North African markets.
Saudi Arabia
Hospital procurement of magnetic resonance and computed tomography systems concentrates through centralized purchasing authorities in Riyadh and Jeddah. The SFDA enforces marketing authorization aligned with Global Harmonization Task Force principles, compressing registration timelines for Class II and III devices. Medical city complexes in the Eastern Province absorb advanced surgical and imaging equipment without legacy system displacement costs.
United Arab Emirates
Dubai Health Authority-affiliated facilities drive demand for cardiac catheterization lab equipment and robotic surgery platforms. The Ministry of Health and Prevention mandates digital transformation protocols that compel wearable-connected monitoring infrastructure deployment. Procurement consortia across Abu Dhabi and Dubai are unbundling after-sales service contracts from equipment supply agreements.
South Africa
Netcare and Mediclinic capital expenditure programs for surgical theater upgrades sustain replacement demand for anesthesia delivery systems and advanced imaging. The Medicines Control Council pathway governs licensing for higher-risk device classes, creating divergence from public sector procurement ceilings. Private hospital networks in Johannesburg and Cape Town concentrate cardiac rhythm management device distribution partnerships.
Egypt
Government hospital construction in Cairo, Alexandria, and the Delta region opens greenfield deployment opportunities for diagnostic imaging suites. Egyptian pound depreciation and periodic tariff recalibrations on electromechanical equipment inflate landed costs for European and Asian original equipment manufacturers. Public health infrastructure expansion proceeds without legacy equipment displacement burdens.
Israel
Specialized tertiary centers concentrate neurodiagnostic equipment and deep brain stimulation device utilization with concentrated specialist expertise. The national health regulator maintains stringent quality management requirements that condition market entry on evidence of prior approval by recognized reference regulators. Medical technology clusters in Tel Aviv and Haifa anchor innovation spillover into Gulf market entry strategies.
Middle East and Africa Medical Devices Market Competitive Landscape
Multinational imaging conglomerates and diversified medtech portfolios split the market across divergent procurement channels. Gulf hospital group consolidation favors direct manufacturer engagement over distributor-mediated supply, compressing traditional margin structures. Three archetypes dominate: integrated diagnostic imaging suppliers, cardiac and surgical device specialists, and point-of-care technology platforms. Competitive positioning hinges on localized service infrastructure and regulatory affairs capacity rather than product differentiation alone.
Among European-origin conglomerates, Siemens Healthineers and Koninklijke Philips N.V. exemplify the integrated imaging archetype, leveraging installed base service revenue across sub-Saharan hospital networks. Medtronic occupies a position within the cardiac and surgical device tier, anchoring regional presence through distribution partnerships with private hospital groups in the Gulf. These three entities represent divergent strategic responses to procurement consolidation: direct service operation buildout, distributor relationship maintenance, and hybrid certification of third-party technical partners.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Stryker |
| Medtronic |
| F. Hoffmann-La Roche Ltd |
| B. Braun SE |
| Koninklijke Philips N.V. |
| Johnson & Johnson |
| Getinge AB |
| GE HealthCare |
| Others |
Supply & Pricing Matrix
Jebel Ali Free Zone freight corridors concentrate contrast media and specialized catheter flows, with port congestion surcharges feeding directly into distributor markup strategies across Gulf hospital networks and forcing tiered pricing stratification between emergency stockholding and scheduled procurement channels.
Pricing Analysis
Price spreads between Riyadh tertiary hospitals and South African public tenders reach multiples on identical imaging equipment, with premium-mid-economy pricing differentiation driven by ISO 13485 certification grade and bundled after-sales service coverage. Cost compression in mid-tier diagnostic devices is intensifying because Egyptian pound depreciation inflates landed costs for European OEMs serving Cairo public tenders. Private hospital groups in Dubai demonstrate lowest price sensitivity, while Delta region clinics in Egypt operate under severe budget ceilings.
Supply Chain Analysis
Export control regimes on advanced semiconductor components and AI-enabled imaging processors constrain flows from US and EU sources into Saudi medical city complexes. Manufacturing concentrates in Germany, the Netherlands, and China for high-field MRI magnets, flat-panel detectors, and consumable disposables respectively. Supply chains draw from rare earth deposits for magnet fabrication, specialized polymers for catheter extrusion, and precision optics for endoscopy stacks. Single-source vulnerability concentrates through Dubai's Jebel Ali hub. Distribution runs through authorized distributor networks with SFDA import licensing requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote patient monitoring mandates across Gulf health ministries constitute a regulatory inflection accelerating wearable-connected device deployment faster than traditional hospital procurement cycles can absorb.
For Market Incumbents: Entrench service infrastructure density across Saudi Arabia's Eastern Province medical cities to defend against emerging point-of-care ultrasound specialists threatening imaging installed bases. Deepen backward integration into consumable production within GCC free zones to offset distributor margin compression from procurement consortium unbundling. For New Entrants and Emerging Players: Pursue Egyptian public hospital construction programs in Alexandria and Delta regions as the most penetrable geography, where greenfield deployment avoids legacy PACS integration burdens. Position AI-assisted handheld ultrasound platforms for primary care triage in Saudi remote governorates, leveraging SFDA fast-track pathways for Class II devices with predicate approvals. For Investors and Strategic Acquirers: Regional service-only biomedical engineering firms with ISO 13485 certification and existing SFDA establishment registrations represent the priority acquisition archetype, given technician scarcity across Gulf networks. Watch for African Medicines Agency protocol ratification as the signal indicating harmonized regulatory pathways across fifteen-plus member states.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Marketing Authorization Fast-Track | Accelerates product entry for Class II devices with predicate approvals from FDA or CE-marked reference regulators. |
| Hospital System Partnership | Direct engagement with Dubai Health Authority procurement consortia bypasses distributor margin compression. |
| Software Companion Development | AI-enabled image interpretation modules differentiate handheld ultrasound platforms in resource-variable settings. |
| Reimbursement Strategy | Alignment with UAE Ministry of Health remote monitoring mandates pulls through wearable ecosystem adoption. |
| Biomedical Engineering Certification Program | Addresses MRI and CT technician scarcity extending equipment downtime across Gulf hospital networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of hospital procurement databases, GPO contracts, SFDA registration filings, and CMS Medicare-equivalent Gulf reimbursement schedules across the analysis window. Interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads at multinational device manufacturers informed demand-side validation. Bottom-up equipment installation tracking and top-down health expenditure flows were cross-referenced for triangulation.
Forecast inputs include modeled segmentation across product type, end user, technology, and application dimensions, with specific weighting for wearable technology adoption curves and imaging equipment replacement cycles. CAGRs were derived from installed base growth, capital expenditure pipeline visibility, and regulatory pathway acceleration effects. Reimbursement fragmentation between South African public and private financing, plus Egyptian tariff volatility, were incorporated as scenario variables.
The forecast holds incumbent behavior within observed patterns; aggressive direct service operation buildouts by imaging conglomerates would shift outcomes beyond projected distributor disintermediation timelines. Material shifts in African Medicines Agency ratification schedules or GCC customs union tariff recalibrations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Jet Nebulizers Market
Medical Devices
Transplant Monitoring Kits Market
Medical Devices
Venturi Mask Market
Medical Devices
Continuous Passive Motion Devices Market
Medical Devices
Global Hysteroscope Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
Capsule Endoscope Systems Market
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Hospital and Pre-Hospital External Defibrillator Market
Medical Devices
Medical Pendant Market
Medical Devices
Homecare Medical Devices Market
Medical Devices
Medical Device and Accessories Market
Medical Devices
Transportable Ventilator Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Pharmaceutical Robots Market