
 Carbon Steel Pipe Fittings Market | 2026-2036
Carbon Steel Pipe Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Steel Pipe Fittings Market Intelligence
Modular fitting bundles that combine elbows, tees, and reducers into pre-configured piping kits is consolidating buyer preference across midstream oil and gas contractors. Erne Fittings GmbH leverages its Austrian forging heritage to dominate high-pressure alloy fitting supply for European energy infrastructure. Parker Hannifin CORP sustains channel control through integrated distribution of threaded and flanged connection systems across industrial MRO networks. Awaji Materia Co. Ltd. anchors Asia-Pacific demand with specialized bending capabilities for large-diameter carbon steel configurations.
Carbon steel pipe fittings are forged or wrought components, typically conforming to ASTM A234 WPB specifications with carbon content below 0.30 percent, designed to change direction, branch, or terminate piping systems in pressurized fluid transport. These fittings join pipe sections through welded, threaded, or flanged connections and must withstand hydrostatic test pressures exceeding system design ratings to ensure structural integrity in critical infrastructure. Elbows and reducers capture the deepest margin pools in product type segments due to complex forming requirements and scrap rates in eccentric reduction production. Welded connections lead connection type demand in oil and gas and power generation end users where joint integrity standards prohibit mechanical alternatives in high-cycle thermal service. Piping systems application demand outpaces HVAC and fire protection segments, reflecting concentrated investment in petrochemical and utility-scale energy transfer networks.
ASTM International and ASME maintain dimensional and material standards that govern carbon steel fitting acceptance across US commercial and regulated infrastructure, while the EPA enforces emissions controls that shape foundry and forging facility siting decisions. The EU F-Gas Regulation and REACH compliance frameworks indirectly pressure European fitting suppliers to document supply chain material provenance and reduce process emissions in heat treatment operations. Stakeholders must monitor evolving hydrogen pipeline compatibility standards that will redefine pressure-temperature ratings and material qualification protocols for carbon steel fitting portfolios.
Market Dynamics
ASTM A234 and ASME B16.9 certification requirements are tightening across North American supply chains, forcing foundries to upgrade metallurgical testing protocols and traceability systems. Oil and gas pipeline operators in Texas and Louisiana are consolidating procurement around pre-qualified welded connection suppliers, compressing vendor lists and elevating compliance costs for smaller forging operations.
Growth Catalysts
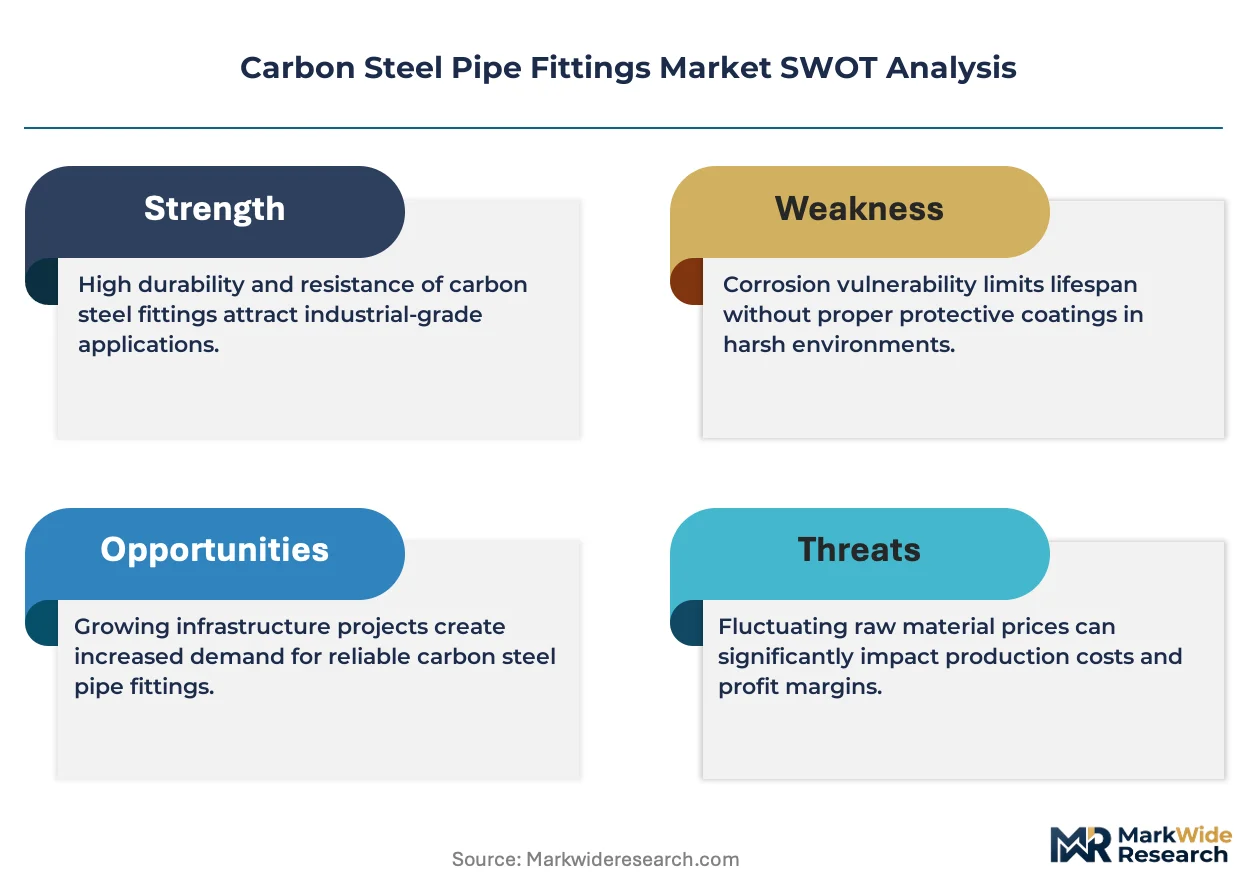
- Petrochemical capacity expansion:New ethylene crackers and LNG export terminals along the US Gulf Coast are accelerating demand for high-pressure carbon steel elbows and tees in process piping networks.
- ASTM A234 WPB material upgrades:Midstream operators are specifying enhanced carbon-manganese compositions for hydrogen-blended natural gas transport, extending fitting service life in corrosive service conditions.
- Welded connection preference:Power generation utilities are phasing out threaded fittings in high-cycle thermal applications, favoring butt-weld configurations that eliminate leak paths in steam and feedwater systems.
Market Restraints
- Scrap rate volatility:Eccentric reducer production generates 15-25 percent material waste in forging operations, exposing margins to ferrous scrap price swings at Midwest US processors.
- Supply concentration risk:Large-diameter seamless fitting production concentrates among a handful of German and Japanese forging houses, creating bottlenecks for urgent project timelines.
- Stainless steel substitution:Coastal petrochemical facilities in humid environments are specifying 316L alternatives for critical branches, eroding carbon steel share in corrosion-sensitive applications.
Strategic Opportunities
- Hydrogen pipeline compatibility:Emerging ASTM standards for high-pressure hydrogen service are creating first-mover advantage for fittings manufacturers qualifying embrittlement-resistant carbon steel grades.
- Modular piping kits:Pre-configured bundles combining elbows, tees, and reducers are penetrating midstream construction sites, reducing field welding hours and inspection costs for EPC contractors.
- EPA emissions compliance:Heat treatment facility upgrades to meet tightened foundry air standards are unlocking preferential sourcing status with utilities pursuing Scope 3 reduction targets.
Industry Challenges
- ASME Section IX welder certification backlog:Qualified welding procedure qualification records are accumulating 8-12 week delays at accredited test labs, stretching project commissioning schedules.
- Legacy ERP integration:Forging operations migrating to cloud-based quality management systems face data migration friction with decades-old heat lot traceability records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Steel Pipe Fittings Market |
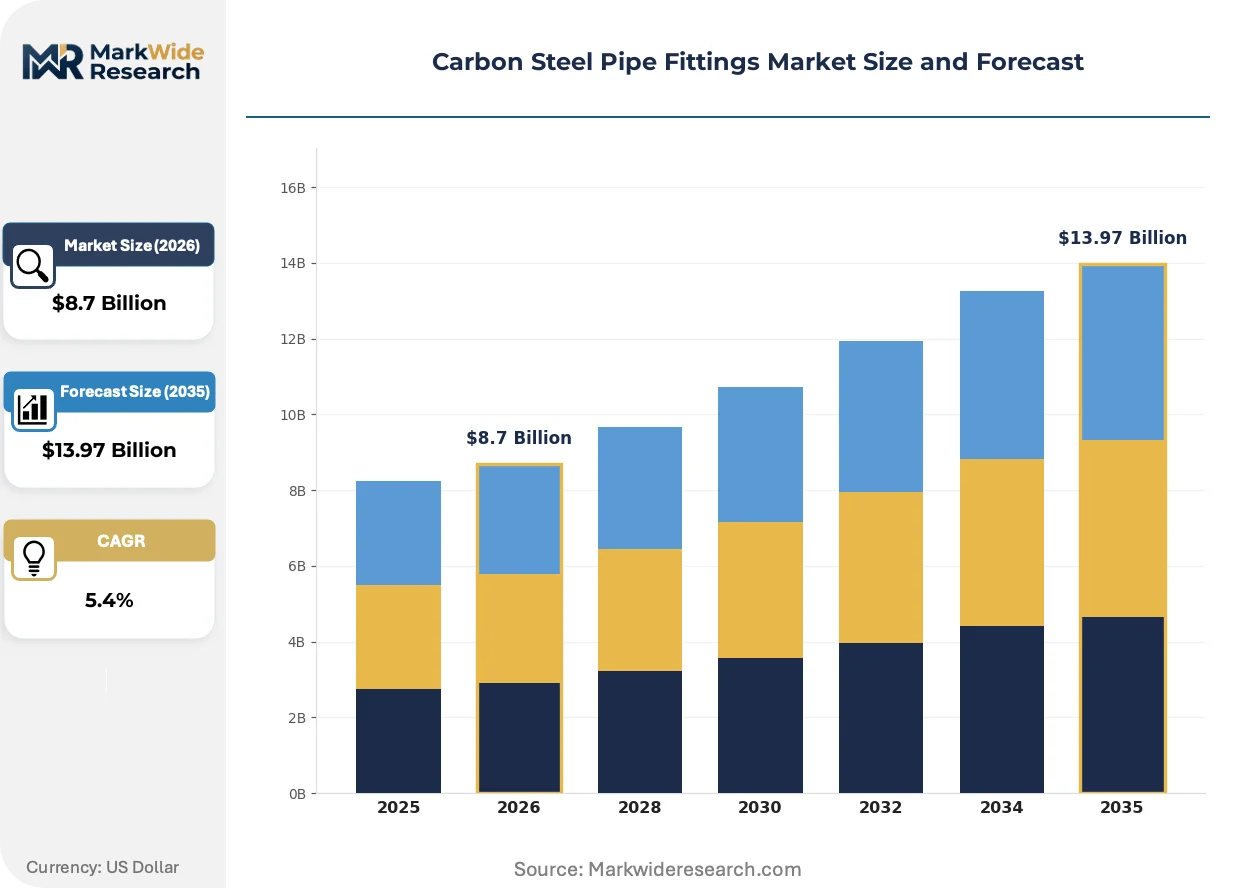
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elbows, Tees, Reducers, Caps End User: Construction, Oil & Gas, Water Supply, Power Generation Connection Type: Welded, Threaded, Flanged, Socket Weld Application: Piping Systems, Industrial Applications, HVAC, Fire Protection |
| Companies Covered | Erne Fittings GmbH, Parker Hannifin CORP, Awaji Materia Co. Ltd., SBC Bend Co. Ltd., S.S.E. Pipefittings Limited, Bassi Luigi and C. S.p.A, M.E.G.A. S.p.A., Sungkwang Bend Co. Ltd., Delcorte SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Steel Pipe Fittings Market Strategic Shifts & Innovations
Digital thread technologies and advanced forming methods are compressing production lead times while redefining quality assurance protocols across carbon steel fitting supply chains. Foundries are deploying sensor-integrated forging presses and automated ultrasonic testing to replace manual inspection workflows.
Induction bending technology for large-diameter carbon steel configurations is expanding into offshore platform fabrication and subsea pipeline tie-in applications. Japanese shipyards and Korean EPC contractors are adopting computer-controlled bending systems that eliminate welded joints in complex spool geometries. The technology is expanding into previously uneconomical niche diameters, compressing demand for segmented elbow fabrication in 24-inch and above sizes.
REACH compliance documentation requirements are forcing European suppliers to map full material provenance from ore source through heat treatment. ECHA substance of very high concern screening is extending certificate of analysis lead times by 3-4 weeks for alloy additions in WPB-grade fittings. German and Austrian forging houses are responding by consolidating supplier bases and pre-qualifying raw material streams against SVHC candidate lists.
Buyer consortiums among Texas and Louisiana petrochemical operators are unbundling inspection services from fitting supply contracts, engaging third-party labs directly for witness testing. This disintermediation is compressing margin capture for distributors while elevating transparency in hydrostatic test documentation. The pattern is most visible in ethylene cracker turnaround procurement, where owner-operators now specify independent witnessing for 100 percent of critical path fittings.
Carbon Steel Pipe Fittings Market Segmentation
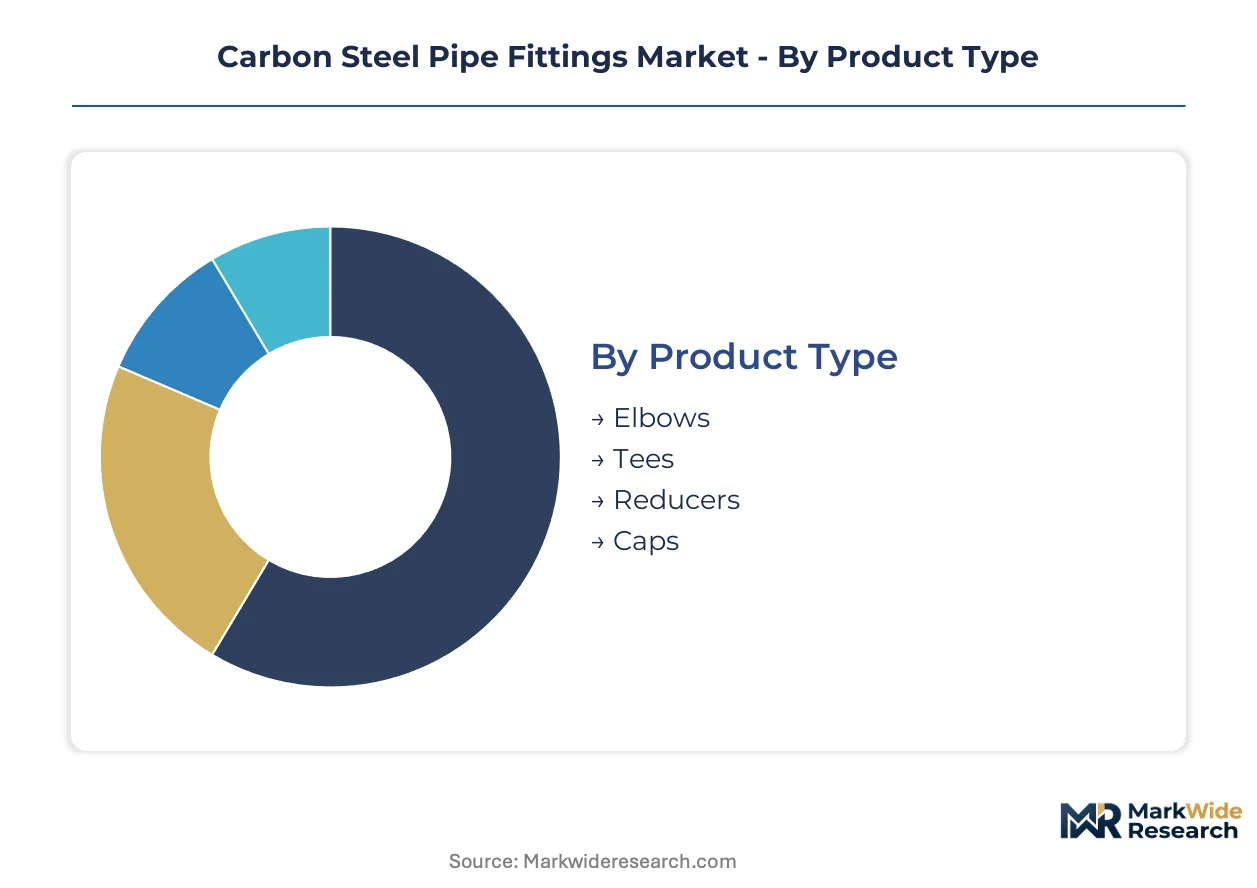
Carbon steel pipe fitting procurement patterns diverge sharply between standalone replacement demand and integrated new-build piping systems. Specification requirements for pressure-temperature ratings, material traceability, and connection geometry create distinct commercial dynamics across each segmentation axis.
Product Type:
Elbows and reducers function predominantly as embedded components within pre-engineered piping spools, while tees and caps see elevated standalone procurement for maintenance turnarounds and field modifications.
- Elbows:These directional change components conform to ASTM A234 WPB with center-to-end dimensions governed by ASME B16.9 long-radius specifications. Demand concentrates in Texas and Louisiana ethylene cracker construction where high-pressure steam piping requires 45-degree and 90-degree configurations in schedule 80 and heavier wall thicknesses.
- Reducers:Eccentric and concentric variants enable diameter transitions in process piping networks with carbon-manganese compositions specified for hydrogen-blended natural gas service. Procurement clusters around LNG export terminal projects along the US Gulf Coast where large-bore reductions face extended lead times from specialized forging houses.
- Tees:Branch connection fittings specified for equal and reducing configurations in header piping systems.
- Caps:Termination fittings deployed for hydrostatic test boundaries and temporary line closures during construction phases.
Volume placements concentrate in elbows; the faster expansion belongs to reducers as hydrogen infrastructure standards mature.
End User:
Cost tier stratification separates specification-intensive regulated industries from price-sensitive commercial construction segments.
- Oil & Gas:Midstream pipeline operators and downstream petrochemical facilities specify enhanced material certifications with full heat lot traceability from melt source through final heat treatment. Procurement is consolidating around pre-qualified welded connection suppliers in the Permian Basin and Marcellus Shale regions where FERC-regulated interstate lines mandate ASME Section IX welding protocols.
- Power Generation:Utility-scale combined cycle and supercritical coal plants require butt-weld configurations in high-cycle thermal service where joint integrity standards prohibit threaded alternatives in steam and feedwater systems. Specification authority rests with engineering procurement contractors executing EPC contracts for regulated utilities.
- Construction:Commercial building and infrastructure projects specify standard WPB grades with less stringent documentation requirements.
- Water Supply:Municipal transmission and distribution networks prioritize corrosion-resistant coatings and cement lining compatibility.
Revenue concentration sits with oil and gas; power generation is climbing the fastest as coal plant retirements accelerate combined cycle additions.
Connection Type:
Application context determines whether mechanical integrity or installation speed dominates specification decisions.
- Welded:Butt-weld and socket-weld configurations eliminate leak paths through metallurgical continuity between fitting and pipe. Oil and gas pipeline operators and power generation utilities specify these exclusively for high-pressure and high-cycle thermal applications where joint failure carries catastrophic cost consequences.
- Flanged:Bolted connections enable disassembly for maintenance access in pump stations, valve assemblies, and vessel nozzles where periodic inspection mandates removable joints.
- Threaded:NPT and BSPT configurations persist in low-pressure utility piping and instrument connections where field installation speed outweighs pressure rating requirements.
- Socket Weld:Smaller-diameter variants specified for high-pressure hydraulic and pneumatic tubing systems in process control applications.
Procurement volume clusters in welded connections; flanged configurations are gaining share fastest as modular fabrication practices expand.
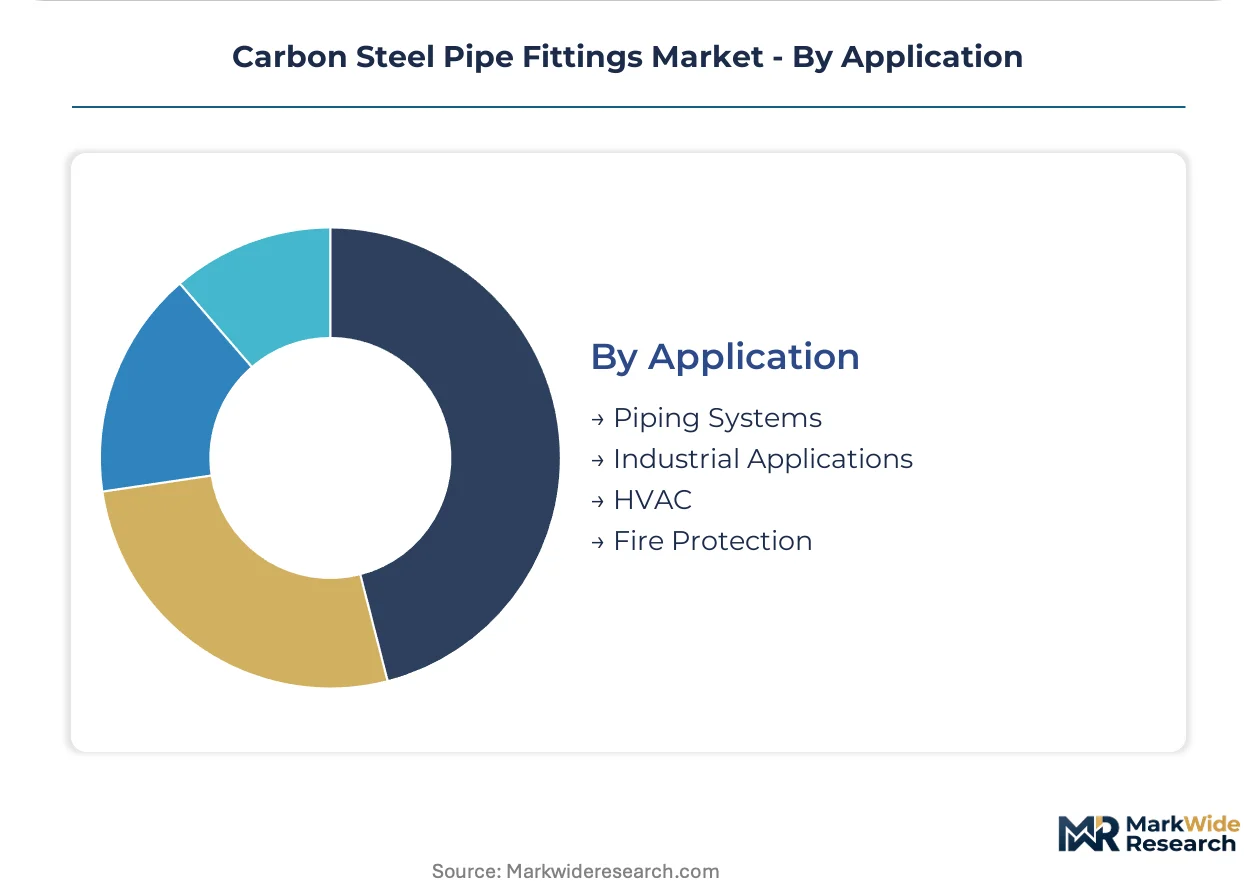
Application:
Customer type separation distinguishes engineered-to-order project demand from catalog-driven maintenance procurement.
- Piping Systems:Process piping for petrochemical, refining, and power generation applications demands comprehensive material certification packages with hydrostatic test documentation witnessed by third-party inspectors. Engineering procurement contractors bundle elbows, tees, and reducers into pre-configured spool packages that reduce field welding hours.
- Industrial Applications:Manufacturing facilities and heavy process industries specify carbon steel fittings for compressed air, cooling water, and fuel gas distribution with less stringent documentation than regulated infrastructure.
- HVAC:Commercial heating and cooling systems specify lighter schedule fittings with galvanized or painted finishes for corrosion protection in building environments.
- Fire Protection:Sprinkler and standpipe systems require UL-listed and FM-approved fittings with specific thread forms and groove configurations.
Project scale concentrates in piping systems; fire protection is expanding most quickly as building code enforcement tightens across municipal jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones along the US Gulf Coast accelerate carbon steel fitting demand through concentrated petrochemical investment and export infrastructure buildout. Tax-advantaged manufacturing corridors in Texas and Louisiana channel procurement toward pre-qualified welded connection suppliers.
United States
Ethylene cracker construction in Texas and Louisiana drives specification-intensive demand for schedule 80 elbows and high-pressure tees. FERC mandates ASME Section IX welding protocols for interstate pipeline networks. The Permian Basin anchors midstream procurement consolidation around certified forged fitting vendors.
Germany
Industrial hydrogen pipeline pilot projects require embrittlement-resistant carbon steel grades with enhanced certification packages. ECHA REACH compliance extends material provenance documentation lead times by 3-4 weeks. Bavarian and North Rhine-Westphalian forging houses consolidate supplier bases against SVHC candidate screening.
China
Refinery expansion along the Bohai Rim and Yangtze River Delta sustains large-diameter fitting procurement for process piping networks. GB standards and MIIT industrial policy shape domestic certification requirements for pressure-containing components. Shandong Province concentrates seamless forging capacity serving both domestic and export project demand.
Japan
Computer-controlled induction bending systems eliminate welded joints in offshore platform spool fabrication for Korean and domestic EPC contractors. METI industrial standards govern pressure-temperature ratings for carbon-manganese compositions in hydrogen service. Nagoya and Osaka industrial corridors specialize in large-diameter configurations previously uneconomical for automated bending.
Saudi Arabia
Giga-project construction in NEOM and Jubail Industrial City drives bulk procurement of flanged and welded connections for utility-scale piping systems. The country's national standards body enforces material traceability from melt source through final heat treatment. Eastern Province fabrication yards integrate carbon steel fittings into pre-assembled modular skids for accelerated field installation.
Carbon Steel Pipe Fittings Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base separates into three structural archetypes: integrated forging houses with captive heat treatment, specialized bending contractors with automated forming technology, and distribution-centric intermediaries controlling MRO channel access. Consolidation pressure concentrates in midstream oil and gas procurement, where pre-qualification requirements compress vendor lists. Capacity expansion and strategic partnerships represent the dominant competitive moves as players position for hydrogen infrastructure qualification.
Among European forging specialists, Erne Fittings GmbH and M.E.G.A. S.p.A. occupy positions within the premium-tier alloy fitting segment. Parker Hannifin CORP exemplifies the diversified conglomerate archetype through integrated distribution control. Awaji Materia Co. Ltd. represents the specialized bending contractor model with automated large-diameter capabilities. These three anchors illustrate the geographic and structural segmentation governing competitive positioning.
| Leading Market Players |
|---|
| Erne Fittings GmbH |
| Parker Hannifin CORP |
| Awaji Materia Co. Ltd. |
| SBC Bend Co. Ltd. |
| S.S.E. Pipefittings Limited |
| Bassi Luigi and C. S.p.A |
| M.E.G.A. S.p.A. |
| Sungkwang Bend Co. Ltd. |
| Delcorte SAS |
| Others |
Cost & Logistics Intelligence
Ferrous scrap volatility at Midwest US processors cascades through forging house cost structures into three-tier pricing stratification across premium certified, standard WPB-grade, and economy commercial fittings. Carbon-manganese alloy surcharges and heat treatment energy costs concentrate margin pressure on eccentric reducer production where material waste rates exceed concentric variants.
Pricing Analysis
Cost compression in standard-grade WPB fittings accelerates as Texas and Louisiana petrochemical operators consolidate procurement around pre-qualified welded connection vendors. Three-tier pricing structure across premium certified, standard WPB, and economy commercial levels differentiates on ASTM A234 certification depth and third-party witnessed hydrostatic documentation. Pricing pressure stems from buyer consortiums unbundling inspection services from supply contracts. Midstream oil and gas contractors exhibit lowest price sensitivity due to FERC-mandated joint integrity standards, while commercial construction buyers drive aggressive cost-down negotiations.
Supply Chain Analysis
Skilled forging press operator shortages in Shandong Province and Bavaria constrain seamless large-diameter fitting output for urgent project timelines. Supply concentrates in China, Germany, and Japan for specialized forging capacity serving hydrogen pipeline qualification requirements. Raw material flows draw from Australian iron ore, US ferrous scrap processors, and European alloy additive suppliers. Single-source vulnerability concentrates in German and Japanese forging houses for seamless configurations above 24-inch diameter. Distribution runs through integrated forging houses with captive heat treatment, specialized bending contractors, and MRO-centric distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon steel pipe fittings sector is consolidating around backward integration into heat treatment operations and upstream control over alloy additive supply streams. Players securing captive forging capacity and pre-qualified hydrogen service certifications will capture margin pools as ASTM embrittlement standards mature.
For Market Incumbents: Lock in hydrogen pipeline qualification status by accelerating ASTM A234 WPB material upgrades for high-pressure hydrogen service before competitor certification windows close. Defend against stainless steel substitution in coastal petrochemical facilities by embedding corrosion-resistant coating capabilities in-house. Prioritize ASME Section IX welding protocol pre-qualification with Texas and Louisiana owner-operators to compress vendor lists in your favor.
For New Entrants and Emerging Players: Municipal water supply contractors represent an underserved buyer archetype with less stringent documentation requirements than regulated oil and gas procurement. Penetrate the fire protection segment fastest by securing UL-listed and FM-approved fitting status as building code enforcement tightens across municipal jurisdictions. Deploy modular piping kit bundling as your go-to-market angle to reduce field welding hours for EPC contractors.
For Investors and Strategic Acquirers: First-mover ASTM hydrogen compatibility qualification announcements from forging houses are the leading indicator that material certification barriers are rising and consolidation premiums will follow. Frame long-term viability around hydrogen infrastructure buildout windows where embrittlement-resistant carbon steel grades displace legacy specifications. Target specialized bending contractors with computer-controlled induction systems for large-diameter configurations. Watch for EPA foundry emissions compliance upgrades as the signal that Scope 3 preferential sourcing status is becoming a durable competitive moat.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Captive heat treatment capacity secures EPA compliance and Scope 3 preferential sourcing status with utilities. |
| Hydrogen Service Certification | ASTM A234 WPB material upgrades for embrittlement resistance unlock first-mover advantage in hydrogen pipeline procurement. |
| Modular Piping Kit Development | Pre-configured elbow-tee-reducer bundles reduce field welding hours and inspection costs for Gulf Coast EPC contractors. |
| Automated Induction Bending Deployment | Computer-controlled systems eliminate welded joints in 24-inch and above configurations for offshore platform fabrication. |
| REACH Compliance Documentation Consolidation | Pre-qualified raw material streams against ECHA SVHC candidate lists compress European certificate of analysis lead times. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside structured primary interviews with forging house operations directors, petrochemical procurement leads at Texas and Louisiana owner-operators, EPC contractor piping specialists, and MRO distribution channel managers. Secondary sources included FERC interstate pipeline filings, EPA foundry emissions compliance databases, ASTM and ASME standards documentation, and import-export customs records for carbon steel fitting classifications. Bottom-up volume modeling and top-down value reconciliation triangulated across these streams.
Data-stream reconciliation across shipment volumes, project announcement tracking, and certification database monitoring shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed product type, connection geometry, end-use industry, application context, and regional regulatory cluster. CAGRs derived from fitted trend extrapolation against announced capacity additions and standards evolution timelines. Industry-specific forecast inputs included hydrogen pipeline pilot project announcements and ethylene cracker construction schedules along the US Gulf Coast.
Revisions become necessary when ASTM hydrogen compatibility standards accelerate material qualification timelines, EPA foundry emissions enforcement intensifies heat treatment facility siting constraints, or ferrous scrap price volatility exceeds historical bands. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global Lance Tubes Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market
Pipes and Tubes
Global Titanium Tube Market
Pipes and Tubes
ESR Tubes Market
Pipes and Tubes
Europe Copper Pipes and Tubes Market
Pipes and Tubes
Cold Drawn Seamless (CDS) Steel Pipes Market
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
Saw Pipes Market
Pipes and Tubes
Agricultural Pipes and Tubes Market
Pipes and Tubes
Composite Pipes Market
Pipes and Tubes
Steel Roll-On Tube Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
Stainless Steel Tank Container Market
Pipes and Tubes
Clad Pipe Market
Pipes and Tubes
Plastic Pipes and Fittings Market