
 Global Titanium Tube Market | 2026-2036
Global Titanium Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Global Titanium Tube Market Foresight
Market Context
Multi-source procurement is pivoting toward captive titanium sponge supply as volatile feedstock costs squeeze fabricator margins. VSMPO-AVISMA Corporation dominates Russian titanium output and leverages vertical integration from ore to finished tube. TIMET anchors North American aerospace qualification programs through long-term OEM contracts. ATI Inc. competes on specialty alloy formulations for chemical processing applications.
Technical Definition and Segment Structure
Titanium tubes are hollow cylindrical structures fabricated from titanium alloys, typically Grade 2 (commercially pure) or Grade 5 (Ti-6Al-4V), manufactured through extrusion or pilgering to achieve wall thicknesses from 0.5 mm to 50 mm for corrosion resistance in aggressive fluid environments. Seamless tubes command premium positioning in aerospace hydraulic lines where fatigue integrity is non-negotiable, while welded tubes occupy cost-sensitive chemical processing infrastructure. Cold-rolled products sustain margin pools in medical device catheter applications requiring ultra-fine dimensional tolerances.
Regulatory Framework and Outlook
FAA airworthiness directives and EASA certification standards mandate full material traceability for flight-critical titanium components, compelling suppliers to maintain NADCAP-accredited testing protocols. China's GB standards and Japan's JIS specifications create parallel compliance pathways for Asian industrial buyers. REACH substance restrictions in Europe constrain certain alloying element formulations, reshaping R&D priorities across the supply base. Stakeholders must monitor evolving OEM qualification timelines and dual-use export control classifications affecting titanium alloy shipments.
Market Dynamics
Aerospace OEMs are consolidating titanium tube suppliers around captive sponge sources as volatile Kroll process energy costs destabilize fabricator margins and force backward integration into upstream titanium production.
Growth Catalysts
- FAA Airworthiness Directives:Mandated full material traceability for flight-critical hydraulic systems compels tier-1 suppliers to maintain NADCAP-accredited testing protocols, locking in qualified tube vendors.
- China's NMPA Medical Device Standards:Tightened biocompatibility certification for implantable devices accelerates Grade 2 titanium tube demand in cardiovascular catheter manufacturing clusters.
- Additive Manufacturing Feedstock:Powder metallurgy expansion for aerospace near-net-shape components pulls premium-quality titanium tube scrap into atomization supply chains.
Market Restraints
- Rutile Ore Concentration:Over 60% of titanium feedstock concentrates in Australian and South African mining corridors, exposing fabricators to geopolitical supply interruptions.
- Kroll Process Energy Intensity:Sponge production consumes 45-50 MWh per metric ton, rendering European smelters uncompetitive against coal-powered Chinese titanium reduction facilities.
- EU REACH Substance Restrictions:Pending constraints on vanadium and aluminum alloying elements threaten Grade 5 (Ti-6Al-4V) tube formulations across chemical processing applications.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Production-linked incentives for domestic implant manufacturing create captive demand for imported titanium tube finishing capacity.
- Hydrogen Economy Infrastructure:Corrosion-resistant titanium tubing for high-pressure electrolyzer manifolds opens new demand verticals outside traditional aerospace and chemical markets.
- Japan's METI Carbon Neutrality Roadmap:Green hydrogen mandates for steel decarbonization incentivize titanium substitution in heat exchanger applications previously served by stainless alloys.
Industry Challenges
- NADCAP Audit Compression:Aerospace qualification timelines stretch 18-24 months for new tube suppliers, freezing out mid-cap fabricators lacking dedicated compliance infrastructure.
- Skill Migration to Adjacent Sectors:Experienced pilgering technicians exit titanium tube mills for semiconductor equipment manufacturing, hollowing out specialized workforce pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Titanium Tube Market |
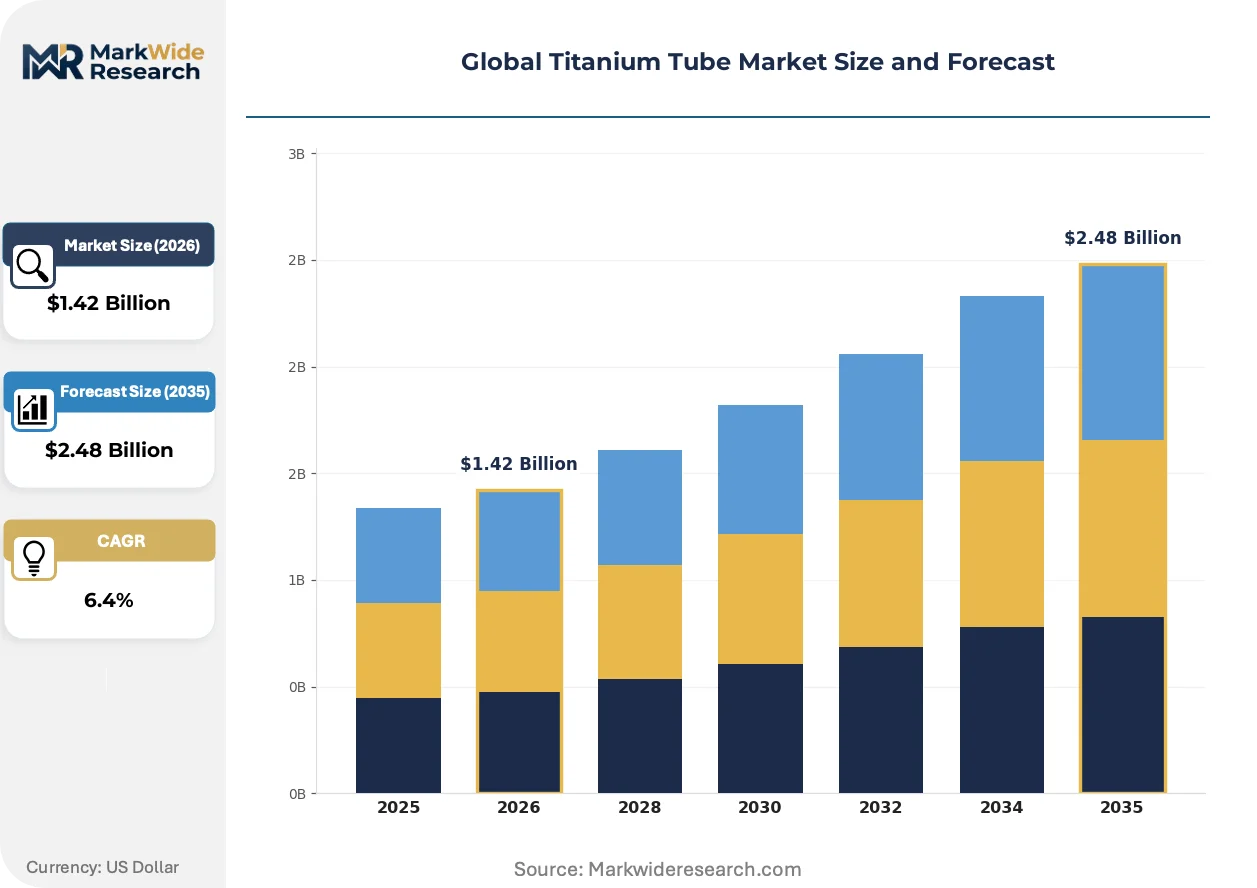
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless Tubes, Welded Tubes, Drawn Tubes, Cold-Worked Tubes Application: Aerospace Components, Chemical Processing, Power Generation, Marine Equipment, Sports Gear Technology: Cold Rolling, Hot Rolling, Extrusion, Annealing, Heat Treatment End User Industry: OEM Manufacturers, Fabricators, Construction Firms, Research Laboratories |
| Companies Covered | VSMPO-AVISMA Corporation, ATI Inc., TIMET, ABLTi Corporation, Toho Titanium Co Ltd, Allegheny Technologies Incorporated, Carpenter Technology, BAOTI Group, OSAKA Titanium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Titanium Tube Market Shifts & Advancements
Electron beam cold hearth refining is disrupting traditional vacuum arc remelting dominance, while digital twin implementations compress development cycles for next-generation alloy formulations.
Plasma arc melting technology is decentralizing titanium sponge production from centralized smelter complexes toward modular, electricity-proximate installations. Regional aerospace clusters in Italy and Sweden are piloting distributed reduction facilities to shorten qualified supply chains. This geographic fragmentation is decentralizing procurement leverage away from legacy Russian and Chinese sponge exporters toward captive, renewable-powered production nodes.
China's GB standards revision for titanium alloy medical devices is mandating full lot-level chemical analysis documentation, exceeding ISO 5832-3 baseline requirements. Domestic catheter manufacturers must now integrate blockchain-enabled traceability systems from sponge source to finished sterile packaging. Japanese orthopedic implant producers are accelerating dual-certification strategies to maintain parallel China and EU market access.
Aftermarket service unbundling is fragmenting traditional long-term aerospace supply agreements into discrete module contracts for tube inspection, refurbishment, and replacement scheduling. MRO providers in Singapore and Dubai are capturing value previously retained by OEM captive service divisions. This disaggregation is most pronounced in widebody hydraulic system maintenance, where fleet operators prioritize unit-cost transparency over bundled lifetime service commitments.
Global Titanium Tube Market Segmentation
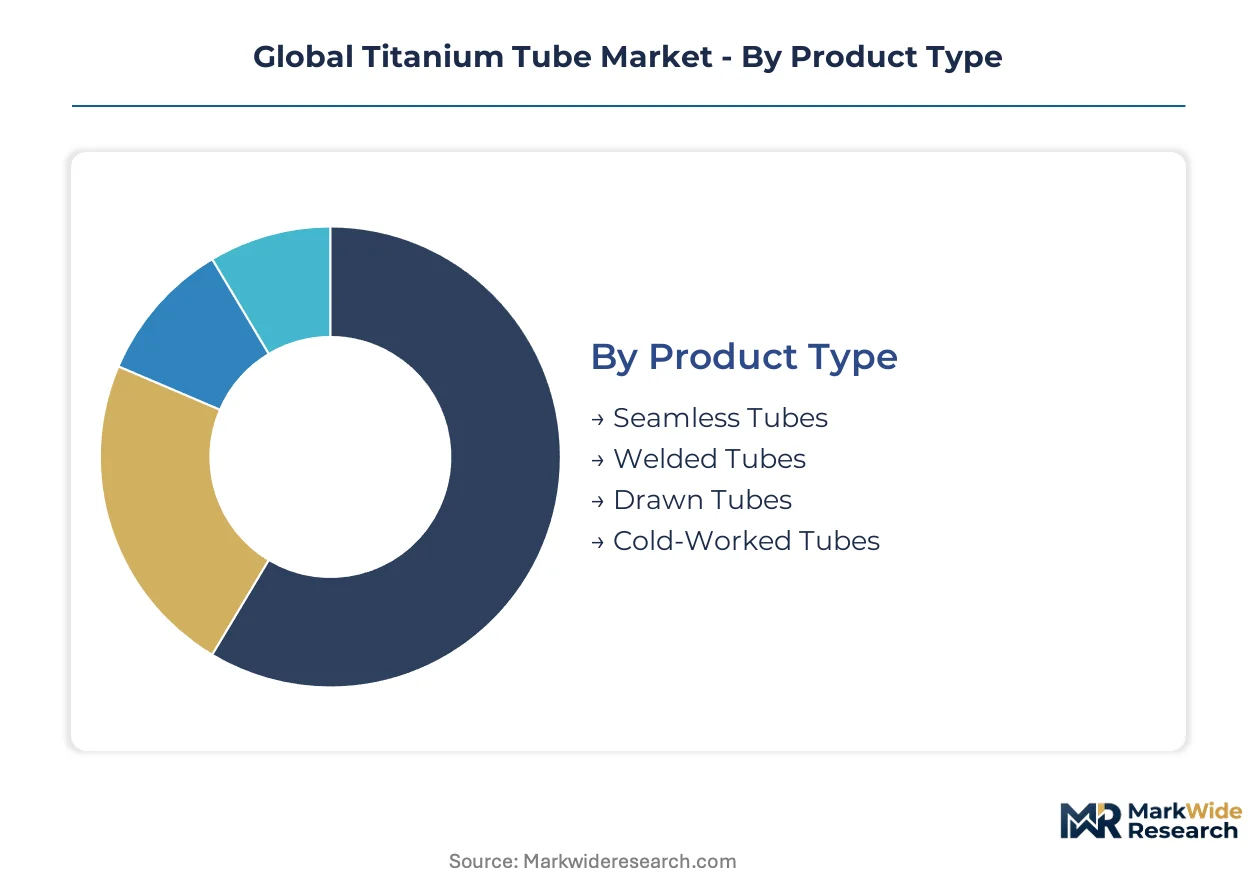
Titanium tube procurement patterns diverge sharply across manufacturing methods and end-use specifications, with aerospace qualification requirements creating rigid supplier lock-in effects that resist cross-segment migration. Fabricators must align production assets to distinct technical standards rather than pursuing flexible, multi-purpose capacity.
Product Type:
Supply of high-integrity tube formats concentrates among mills with NADCAP-accredited testing infrastructure, locking out generalist metal processors.
- Seamless Tubes:Manufactured through rotary piercing and pilgering to eliminate longitudinal weld seams, achieving uniform grain structure critical for fatigue resistance. Boeing and Airbus hydraulic system specifications mandate seamless construction for pressure lines above 3,000 psi, with VSMPO-AVISMA and TIMET controlling qualified supply.
- Welded Tubes:Formed from titanium strip via TIG or laser welding, then cold-drawn to final dimensions. Chemical processing infrastructure in Germany's Ruhr industrial cluster and China's Shandong province absorbs volume for heat exchanger applications where pressure cycling is moderate.
- Drawn Tubes:Cold-drawn over mandrels to precise OD/ID tolerances for medical catheter substrates.
- Cold-Worked Tubes:Work-hardened to elevated strength levels for sports equipment shafts.
Seamless tubes absorb the bulk of installed capacity; welded tubes are expanding most quickly in chemical processing substitution cycles.
Application:
End-use demand fragments across performance tiers, with flight-critical applications commanding 3-5x pricing multiples over industrial commodity grades.
- Aerospace Components:Landing gear actuators, engine bleed air ducts, and fuel transfer lines require full lot traceability from sponge source. FAA airworthiness directives mandate vacuum arc remelted stock for structural tube applications, compressing qualified supplier lists to fewer than ten mills globally.
- Chemical Processing:Chlor-alkali cell anodes, seawater desalination brine heaters, and acid handling manifolds exploit Grade 2 titanium's corrosion immunity. Saudi Arabia's Jubail industrial city and India's Gujarat chemical corridor drive regional demand clustering.
- Power Generation:Condenser tubing for coastal nuclear and thermal plants.
- Marine Equipment:Deep-sea pressure hull penetrators and submarine piping systems.
- Sports Gear:Bicycle frames, golf club heads, and lacrosse shafts.
Aerospace components command the dominant revenue share; chemical processing applications are climbing the fastest as chlorine chemistry capacity expands in the Middle East and South Asia.
Technology:
Process selection determines achievable wall thickness tolerances and surface finish specifications, with cold reduction methods dominating premium medical and aerospace segments.
- Cold Rolling:Reduces tube diameter and wall thickness at ambient temperature to achieve dimensional tolerances of ±0.05 mm. Japan's precision tube mills in Osaka prefecture supply orthopedic implant manufacturers with ultra-fine surface finishes required for bone integration coatings.
- Hot Rolling:Deforms titanium above beta transus temperatures for large-diameter structural tubing. Russian and Chinese integrated mills leverage hot rolling for cost-efficient production of industrial-grade tube for chemical plant construction.
- Extrusion:Forces billet through shaped dies for complex cross-sections and thick walls.
- Annealing:Stress-relief heat treatment to restore ductility after cold work.
- Heat Treatment:Solution and aging cycles to develop Grade 5 alloy strength properties.
Hot rolling retains the largest installed base; cold rolling is gaining share fastest as medical device tolerances tighten.
End User Industry:
Customer procurement sophistication varies dramatically, with OEMs imposing qualification barriers that exclude merchant distributors from flight-critical supply chains.
- OEM Manufacturers:Airbus, Boeing, Safran, and Rolls-Royce operate approved vendor lists requiring 18-24 month qualification cycles. These manufacturers specify exact sponge sources and melt histories, often mandating dual-qualified suppliers for single-source risk mitigation.
- Fabricators:Machine shops and assembly houses purchase mill-certified tube for value-added component production. Italy's Emilia-Romagna aerospace district and Connecticut's precision manufacturing corridor concentrate fabricator demand for semi-finished titanium products.
- Construction Firms:EPC contractors for desalination and chemical plant projects.
- Research Laboratories:National laboratories and university facilities for experimental alloy development.
OEM manufacturers dominate procurement volume; fabricators are expanding fastest as aftermarket MRO disaggregation creates new intermediary demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rutile ore deposits in Western Australia and ilmenite sands along South Africa's eastern seaboard anchor global titanium feedstock supply, concentrating sponge production and tube fabrication capacity in mining-proximate industrial corridors.
China
Baoji's titanium production zone in Shaanxi province processes over half of domestic aerospace-grade tube output for COMAC airframe programs. GB standards revision for medical devices mandates blockchain-enabled traceability from sponge source to finished packaging. Shandong province's chemical processing corridor absorbs industrial-grade welded tube for chlor-alkali infrastructure expansion.
United States
Boeing and Lockheed Martin hydraulic system procurement drives demand for seamless tube with full vacuum arc remelt documentation. FAA airworthiness directives compress qualified supplier lists through NADCAP-accredited testing mandates. Connecticut's precision manufacturing corridor concentrates fabricator demand for semi-finished titanium products serving defense OEMs.
Russia
VSMPO-AVISMA's vertical integration from ore to finished tube dominates domestic output and exports to Asian aerospace programs. Siberian smelter complexes leverage hydroelectric power for Kroll process sponge reduction. The Ural industrial region hosts pilgering mills qualified for Airbus and Safran long-term supply contracts.
Japan
Osaka prefecture's precision tube mills supply orthopedic implant manufacturers with ultra-fine surface finishes for bone integration coatings. METI carbon neutrality roadmaps incentivize titanium substitution in heat exchanger applications previously served by stainless alloys. JIS specifications create parallel compliance pathways for domestic and export medical device markets.
Germany
Ruhr industrial cluster chemical processors absorb welded tube volume for heat exchanger applications in chlorine chemistry infrastructure. REACH substance restrictions on vanadium and aluminum alloying elements reshape R&D priorities for Grade 5 tube formulations. Bavaria's aerospace suppliers maintain dual-certification strategies for EU and Asian market access.
Global Titanium Tube Market Competitive Landscape
Backward integration into captive sponge supply dominates the current landscape as volatile Kroll process energy costs destabilize fabricator margins. The vendor base stratifies into three tiers: integrated miners-to-tube producers, specialist alloy fabricators with NADCAP accreditation, and regional merchant mills serving industrial commodity grades. Two archetypes define competitive positioning: ore-adjacent Russian and Chinese producers leveraging feedstock proximity, and Western qualification-heavy specialists anchoring aerospace OEM approved vendor lists. Capacity expansion and strategic partnerships represent the dominant competitive moves, with modular plasma arc melting installations decentralizing production toward renewable-powered regional nodes.
Among integrated Russian producers, VSMPO-AVISMA Corporation exemplifies the ore-to-tube archetype with Siberian smelter and Ural milling assets. TIMET and ATI Inc. occupy positions within the North American aerospace qualification tier, anchoring OEM approved vendor lists through long-term supply relationships. BAOTI Group represents the Chinese state-backed integrated model, with Baoji-based capacity serving domestic aerospace and medical device manufacturing clusters. These three entities illustrate the geographic and structural segmentation defining competitive positioning across feedstock-adjacent, qualification-heavy, and state-integrated archetypes.
| Leading Market Players |
|---|
| VSMPO-AVISMA Corporation |
| ATI Inc. |
| TIMET |
| ABLTi Corporation |
| Toho Titanium Co Ltd |
| Allegheny Technologies Incorporated |
| Carpenter Technology |
| BAOTI Group |
| OSAKA Titanium |
| Others |
Supply & Pricing Matrix
Captive sponge supply integration anchors competitive positioning across the titanium tube value chain, with fabricators controlling upstream Kroll process output commanding pricing leverage over merchant mills dependent on volatile feedstock markets. Boeing and Airbus procurement teams exploit this concentration by mandating dual-qualified suppliers, compressing margin pools for non-integrated producers while locking in long-term offtake premiums for ore-adjacent Russian and Chinese mills.
Pricing Analysis
Aftermarket service unbundling now separates inspection, refurbishment, and replacement modules from bundled lifetime contracts, exposing unit-cost transparency pressures previously masked by comprehensive service agreements. Three-tier pricing structure across NADCAP-accredited premium, mill-certified standard, and industrial commodity grades reflects certification investment recovery timelines, with aerospace OEMs showing lowest price sensitivity due to flight-critical liability exposure and chemical processors in Saudi Arabia's Jubail cluster driving hardest bargain on welded tube volume commitments. Cost compression in European merchant grades intensifies because coal-powered Chinese sponge production undercuts energy-intensive Western smelters.
Supply Chain Analysis
Pilgering technician shortages in Japan's Osaka prefecture and Connecticut's precision manufacturing corridor constrain capacity expansion for ultra-fine medical tube output, forcing lead time stretching at qualified mills. Feedstock draws from Australian rutile corridors and South African ilmenite sands, with sponge production concentrating in Russian Siberian smelters and China's Baoji reduction facilities. Single-source vulnerability runs through VSMPO-AVISMA's ore-to-tube dominance, while distribution feeds through OEM-approved vendor lists and regional fabricator networks serving MRO providers in Singapore and Dubai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive titanium sponge supply has become the defining competitive race, with Kroll process energy costs forcing fabricators to secure upstream control or cede margin to ore-adjacent integrated producers. Players must now choose between qualification-heavy aerospace positioning and commodity-scale chemical processing volume.
For Market Incumbents: Anchor NADCAP-accredited testing infrastructure against emerging modular plasma arc melting entrants by extending qualification timelines and deepening OEM approved vendor list relationships. Defend against aftermarket MRO disaggregation by capturing inspection and refurbishment module contracts directly from Singapore and Dubai fleet operators. Prioritize sponge source diversification away from Australian-South African feedstock concentration through offtake agreements with emerging Indian reduction capacity. For New Entrants and Emerging Players: Regional hydrogen electrolyzer manufacturers represent the most penetrable buyer archetype, with corrosion-resistant high-pressure manifold demand outpacing established aerospace qualification barriers. Target India's PLI-subsidized medical device implant fabricators seeking imported tube finishing partnerships to bypass domestic capacity constraints. Enter through toll-processing arrangements with existing sponge producers rather than greenfield Kroll investment, accelerating time-to-revenue. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap fabricators with NADCAP accreditation and established OEM relationships, positioned for acquisition by ore-adjacent integrated players seeking downstream qualification assets. Long-term viability hinges on renewable-powered sponge production economics displacing coal-based Chinese cost advantages. Watch for FAA airworthiness directive expansion beyond hydraulic systems into engine bleed air ducts as inflection signal for qualification capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Sponge Supply Integration | Backward integration into Kroll process production secures margin control against feedstock volatility. |
| NADCAP Accreditation Investment | Testing protocol certification locks in Boeing and Airbus approved vendor list positioning. |
| Modular Plasma Arc Melting Deployment | Distributed reduction facilities shorten supply chains for Italy and Sweden aerospace clusters. |
| Aftermarket Service Module Capture | Inspection and refurbishment contracts recapture value from Singapore and Dubai MRO disaggregation. |
| Dual-Certification Strategy | Parallel China GB standards and EU REACH compliance maintains access to both medical device markets. |
Research Methodology
Trade databases, SEC 10-K filings, and customs export records formed the secondary backbone, cross-referenced against primary interviews with aerospace procurement directors, titanium mill operations managers, NADCAP audit specialists, and medical device catheter manufacturers. Bottom-up and top-down triangulation validated volume estimates across seamless, welded, and cold-drawn product categories.
Bottom-up modeling aggregated individual mill capacity and utilization rates while top-down approaches cross-checked against end-use demand from Boeing, Airbus, COMAC, and Saudi Aramco chemical division procurement disclosures. Segmentation dimensions spanned manufacturing method, alloy grade, application criticality, and regional regulatory cluster. CAGRs derived from sponge price elasticity modeling and OEM qualification timeline compression effects.
Revisions become necessary when FAA or EASA airworthiness directive scope expansion, REACH substance restriction enforcement, or Kroll process energy cost dislocation materialize outside modeled parameters. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
HPLC Fused Silica Tube Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
FRP Pipe Market
Pipes and Tubes
Pipe and Tube Cutters Market
Pipes and Tubes
Coiled Tubing Manufacturing Market
Pipes and Tubes
Clad Pipe Market
Pipes and Tubes
Stainless Steel Plumbing Pipes and Fittings Market
Pipes and Tubes
Global Polyethylene Pipes and Fittings Market
Pipes and Tubes
France PVC Pipes Market
Pipes and Tubes
Drum Funnel Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
Cold Drawn Seamless (CDS) Steel Pipes Market
Pipes and Tubes
UAE PVC Pipes Market
Pipes and Tubes
India PVC Pipes Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
Gas Pipe Fittings Market