
 Pipeline Processing and Pipeline Services Market | 2026-2036
Pipeline Processing and Pipeline Services Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Processing and Pipeline Services Market Outlook
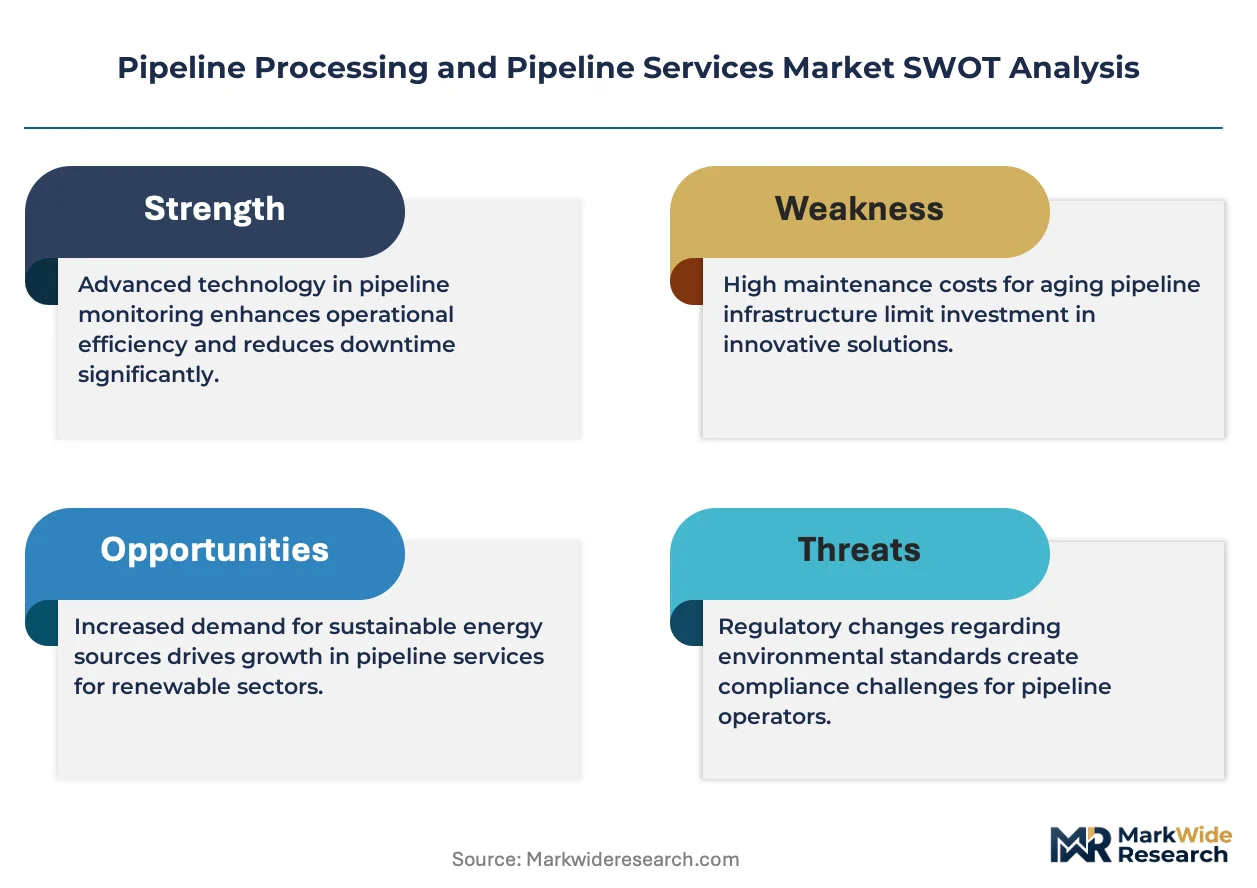
The EU Green Deal methane reduction framework is realigning investment toward leak detection and repair services across European pipeline networks. Halliburton Company leverages its integrated well construction and pipeline integrity portfolio to sustain project economics in unconventional basins. Baker Hughes Company anchors its position through advanced inline inspection technologies that compete on diagnostic precision. Schlumberger Limited differentiates via digital twin deployments that dominate real-time monitoring workflows for complex gathering systems.
Pipeline processing and pipeline services encompass the technical activities required to ensure continuous flow assurance, structural integrity, and operational safety of hydrocarbon and fluid transport systems, including inline inspection using magnetic flux leakage sensors capable of detecting metal loss anomalies as small as two percent wall thickness. These services prevent catastrophic failures, extend asset life, and maintain throughput efficiency across thousands of kilometers of installed infrastructure. Inspection services lead revenue contribution due to mandatory integrity assessment cycles, while smart pigging technology represents the fastest-growing segment as operators replace conventional gauge runs with multi-sensor intelligent platforms that combine geometry, crack detection, and mapping capabilities. Data analytics is emerging as a concentrated margin pool where specialized software layers transform raw inspection signals into predictive maintenance schedules.
PHMSA in the United States enforces pipeline safety regulations that mandate periodic integrity assessments for high-consequence areas, directly expanding demand for certified inline inspection providers. The EU AI Act and existing Pressure Equipment Directive frameworks are reshaping how automated robotics and machine-learning diagnostics gain market access across member state territories. Stakeholders must weigh capital allocation between incremental sensor upgrades and full platform replacements as regulatory thresholds for detection sensitivity tighten without corresponding tariff mechanisms to recover compliance costs.
Market Dynamics
PHMSA's tightening detection sensitivity thresholds are forcing midstream operators to accelerate replacement cycles for conventional gauge pigs with multi-sensor intelligent platforms, compressing vendor upgrade windows and reshaping capital allocation priorities across North American gathering systems.
Growth Catalysts
- EU Green Deal methane framework:Mandatory leak detection and repair protocols across European pipeline networks are expanding contract volumes for certified inline inspection providers in Germany, Italy, and the Netherlands.
- Permian Basin infrastructure density:Concentrated drilling activity in West Texas and southeastern New Mexico generates recurring demand for smart pigging runs on gathering lines and transmission corridors.
- Magnetic flux leakage advancement:Sensor platforms capable of detecting two percent wall thickness anomalies now satisfy regulatory minimums while reducing false-positive rates that previously triggered unnecessary excavations.
Market Restraints
- Specialized steel alloy supply:Tool body manufacturing depends on limited domestic sources for high-grade magnetic permeability steels, creating input cost volatility when mill capacity shifts to defense or aerospace contracts.
- PHMSA certification bottlenecks:Inline inspection provider qualification timelines have extended eighteen to twenty-four months, constraining market entry for new service entrants regardless of technical capability.
- Pipeline rehabilitation deferral:Tariff structures in regulated interstate markets lack cost recovery mechanisms for integrity-driven capacity reductions, incentivizing operators to delay non-mandatory assessments.
Strategic Opportunities
- Offshore decommissioning wave:North Sea and Gulf of Mexico platform abandonment schedules create demand for pre-abandonment integrity verification and flowline isolation services.
- CO2 transport infrastructure:Carbon capture and storage projects in Alberta, Texas, and Louisiana require corrosion-resistant inspection protocols adapted to dense phase and supercritical fluid conditions.
- EU AI Act diagnostic authorization:Machine-learning defect classification systems that satisfy conformity assessment procedures gain preferential access to automated robotics contracts across member state territories.
Industry Challenges
- Multi-physics simulation expertise:Finite element modeling of magnetic flux interaction with complex defect geometries requires scarce computational mechanics specialists, extending tool design cycles.
- Legacy SCADA integration:Real-time pig tracking and data telemetry must interface with decades-old control systems lacking standardized communication protocols, complicating digital twin deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Processing and Pipeline Services Market |
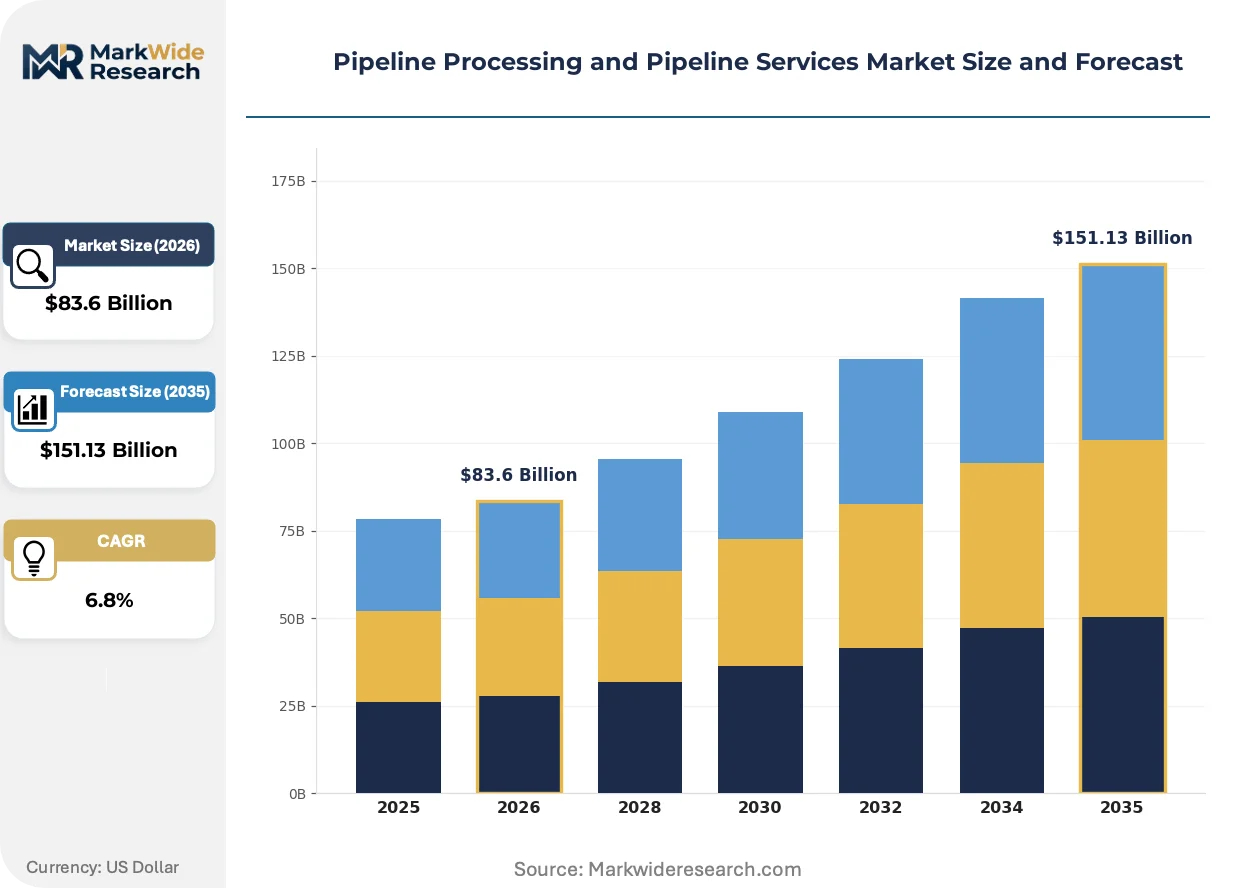
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $151.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Maintenance, Cleaning, Monitoring Pipeline Material: Steel, PVC, Polyethylene, Fiberglass End User: Oil & Gas, Water, Wastewater, Chemicals Technology: Smart Pigging, Robotics, Data Analytics, Coating |
| Companies Covered | Halliburton Company, Baker Hughes Company, Schlumberger Limited, Altus Intervention, EnerMech Group, IKM Gruppen AS, ROSEN Group, T.D. Williamson Inc., BlueFin Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Processing and Pipeline Services Market Strategic Shifts
Diagnostic precision is becoming the primary axis of competition as operators demand actionable intelligence rather than raw signal data, compressing margins for hardware-only vendors while elevating specialized analytics layers.
Electromagnetic acoustic transducer technology is decentralizing crack detection capabilities previously concentrated in laboratory settings. Permian Basin operators now deploy EMAT-equipped pigs on quarterly cycles for stress corrosion cracking assessment. Field adoption is compressing demand for conventional ultrasonic shear wave tools that require liquid couplant and extended downtime.
PHMSA's forthcoming rulemaking on advanced leak detection mandates performance-based standards rather than prescriptive technology requirements. This regulatory architecture permits optical gas imaging, satellite monitoring, and continuous sensor arrays to satisfy compliance alongside traditional survey methods. High-consequence area operators in Texas and Louisiana are diversifying detection portfolios to preempt enforcement exposure.
Service unbundling is fragmenting procurement patterns that previously locked operators into multi-year integrity management contracts. Mid-cap producers now source inline inspection, data analytics, and remediation planning from separate vendors, compressing switching costs and elevating price transparency. This pattern concentrates in the Appalachian Basin where private-equity-backed gathering system operators prioritize operational flexibility over vendor consolidation.
Pipeline Processing and Pipeline Services Market Segmentation
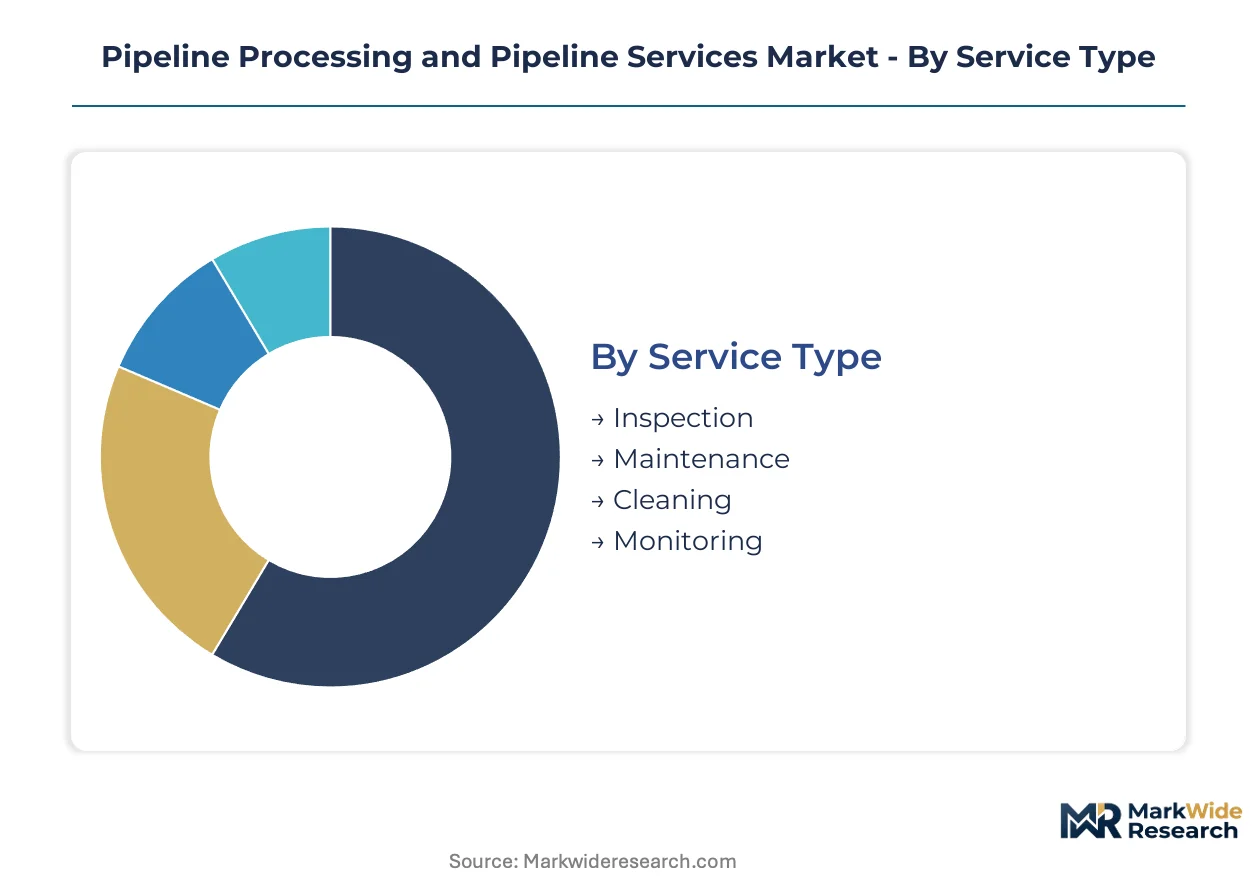
Segmentation in pipeline services reveals distinct procurement patterns across service tiers, material specifications, and technology maturity levels. Operators allocate capital differently across inspection protocols versus maintenance cycles, while material selection dictates tool compatibility and sensor calibration requirements.
Service Type:
Standardized service packages dominate high-frequency maintenance schedules, while customized inspection protocols command premium pricing for complex gathering system geometries.
- Inspection:Magnetic flux leakage and ultrasonic testing platforms detect metal loss anomalies down to two percent wall thickness. Demand clusters in Permian Basin gathering systems where PHMSA mandates periodic integrity assessments for high-consequence areas.
- Maintenance:Scheduled interventions include valve servicing, cathodic protection adjustment, and compression station overhaul. Appalachian Basin operators defer non-mandatory cycles due to tariff structures lacking cost recovery mechanisms for capacity reductions.
- Cleaning:Gel and brush pigging removes wax buildup and debris accumulation from crude oil and refined product lines.
- Monitoring:Continuous sensor arrays and satellite leak detection supplement traditional survey methods under forthcoming PHMSA performance-based standards.
Most installed capacity flows through Inspection. Expansion is steepest in Monitoring.
Pipeline Material:
Material selection determines pigging tool body specifications, sensor electromagnetic properties, and corrosion assessment protocols across operational environments.
- Steel:High-grade magnetic permeability alloys enable MFL sensor platforms with diagnostic precision for crack detection and geometry mapping. Supply bottlenecks in specialized steel mill capacity create input cost volatility when defense or aerospace contracts absorb domestic production.
- PVC:Thermoplastic construction requires non-metallic inspection tools and acoustic emission methods rather than electromagnetic sensors.
- Polyethylene:Flexible pipe systems in gas distribution networks deploy specialized geometry pigs for ovality assessment and squeeze-off verification.
- Fiberglass:Composite reinforced pipe in corrosive chemical service demands ultrasonic-guided wave inspection adapted to anisotropic material properties.
Steel carries the majority of hydrocarbon throughput volume. Fiberglass applications are climbing the fastest in chemical and offshore corrosion environments.
End User:
Regulatory intensity and asset criticality create divergent service procurement patterns across sector verticals.
- Oil & Gas:Midstream operators manage transmission corridors and gathering systems under PHMSA jurisdiction with mandatory integrity management programs. EU Green Deal methane reduction frameworks are expanding contract volumes for leak detection and repair across North Sea and continental European infrastructure.
- Water:Municipal distribution systems prioritize cleaning and coating services to maintain potable water quality standards.
- Wastewater:Gravity-fed collection networks require specialized inspection for infiltration and structural defect assessment.
- Chemicals:Process plant piping and dedicated transport lines demand corrosion-resistant protocols for aggressive fluid chemistries.
Oil & Gas commands the largest service contract value. Chemicals infrastructure is gaining share fastest as specialty material transport expands.
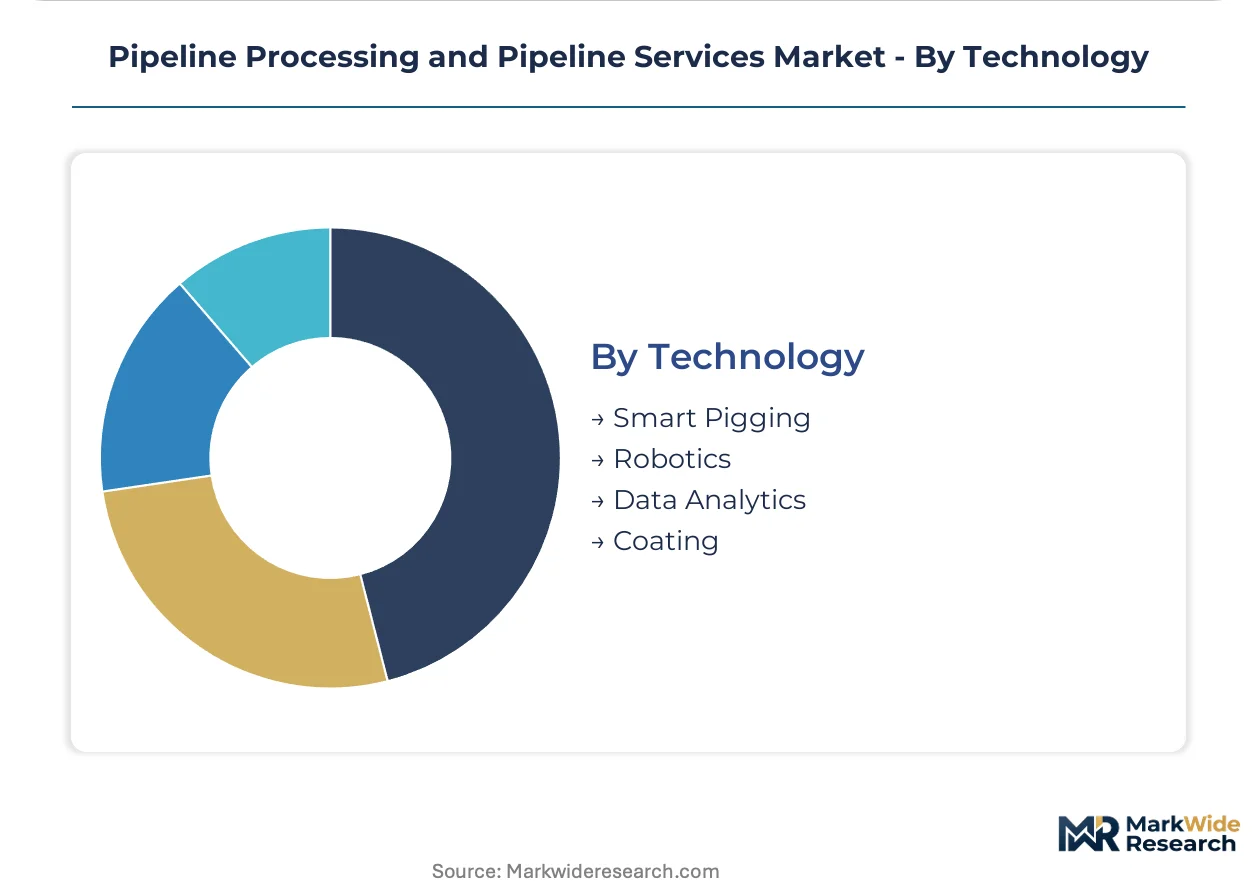
Technology:
Technology maturity curves separate established inline inspection methods from emerging autonomous and predictive capabilities.
- Smart Pigging:Multi-sensor intelligent platforms combine MFL, ultrasonic, and inertial mapping for comprehensive defect characterization. Permian Basin operators accelerate replacement cycles for conventional gauge pigs as PHMSA tightens detection sensitivity thresholds.
- Robotics:Tethered and autonomous systems access unpiggable pipeline segments through launcher modifications or external deployment.
- Data Analytics:Machine-learning defect classification transforms raw inspection signals into predictive maintenance schedules, creating concentrated margin pools for specialized software layers.
- Coating:Internal lining and external corrosion protection applications extend asset life in aggressive soil and fluid environments.
Smart Pigging accounts for the dominant share of inline inspection revenue. Data Analytics is expanding most quickly as operators demand actionable intelligence over raw signal outputs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pipeline integrity engineers and inline inspection technicians concentrate in Houston, Aberdeen, and Stavanger, anchoring service delivery capacity for complex subsea and unconventional infrastructure projects.
United States
Permian Basin gathering systems and Gulf Coast transmission corridors generate recurring smart pigging demand as operators replace conventional gauge runs with multi-sensor platforms. PHMSA mandates periodic integrity assessments for high-consequence areas, directly expanding contract volumes for certified inline inspection providers. West Texas and southeastern New Mexico field clusters concentrate vendor deployment schedules around quarterly assessment cycles.
Germany
North Sea pipeline networks and continental hydrogen blending pilot projects drive investment in leak detection and corrosion assessment services. The EU Green Deal methane reduction framework and Pressure Equipment Directive reshape procurement standards for automated robotics and machine-learning diagnostics. Industrial clusters in Lower Saxony and Bavaria host service centers coordinating cross-border integrity programs for Dutch and Austrian transit lines.
United Kingdom
North Sea platform decommissioning schedules and aging offshore flowline infrastructure create demand for pre-abandonment integrity verification. Health and Safety Executive regulations govern pipeline safety performance alongside EU-originated standards retained post-Brexit. Aberdeen anchors specialized contractor presence for subsea inspection and isolation services across the UK continental shelf.
Norway
Deepwater production systems and subsea tieback networks require advanced inline inspection adapted to high-pressure, high-temperature conditions. The Norwegian Petroleum Safety Authority enforces integrity management standards that exceed baseline EU requirements. Stavanger and Bergen host engineering centers developing autonomous robotics for unpiggable pipeline segments in the Norwegian Sea and Barents Sea.
Canada
Alberta oil sands gathering systems and British Columbia natural gas transmission lines sustain demand for corrosion-resistant inspection protocols. The Canada Energy Regulator oversees pipeline safety alongside provincial authorities in Alberta and British Columbia. Calgary-based service providers coordinate integrity programs spanning the Western Canadian Sedimentary Basin and emerging carbon capture transport infrastructure.
Pipeline Processing and Pipeline Services Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the service tier structure. Integrated oilfield services conglomerates with captive manufacturing capacity face pressure from specialized inspection boutiques that source tool bodies from third-party forges. Three archetypes dominate: full-stack integrators bundling construction and integrity services, pure-play inspection specialists competing on diagnostic precision, and data analytics layers extracting margin from software-based defect classification. Consolidation pressure intensifies as PHMSA certification timelines extend and sensor platform development costs escalate.
Among Houston-based integrated service providers, Halliburton Company and Baker Hughes Company occupy positions exemplifying the full-stack archetype, while Schlumberger Limited anchors the digital-forward tier through real-time monitoring and digital twin deployments. These three entities represent contrasting strategic postures toward hardware-software integration in unconventional basin markets.
| Leading Market Players |
|---|
| Halliburton Company |
| Baker Hughes Company |
| Schlumberger Limited |
| Altus Intervention |
| EnerMech Group |
| IKM Gruppen AS |
| ROSEN Group |
| T.D. Williamson Inc. |
| BlueFin Services |
| Others |
Value Chain & Pricing Dynamics
High-grade magnetic permeability steel costs cascade from limited domestic mill capacity through three distinct service tiers, with PHMSA certification requirements compressing margins for uncertified vendors while elevating pricing power for qualified providers in North American unconventional basins.
Pricing Analysis
Bundled multi-year integrity management contracts command premium pricing against unbundled procurement patterns that fragment inspection, analytics, and remediation across separate vendors. Price differentiation rests on PHMSA certification tier and sensor platform diagnostic precision, with certified providers capturing margin premiums for high-consequence area assessments. Cost compression in standard inspection tiers intensifies as mid-cap Appalachian operators prioritize operational flexibility over vendor consolidation. Private-equity-backed gathering system operators exhibit highest price sensitivity, while major transmission corridor operators accept premium pricing for integrated digital twin deployments.
Supply Chain Analysis
Regional distribution centers in Houston, Aberdeen, and Stavanger anchor hub-and-spoke deployment patterns for specialized tool bodies and sensor platforms. Manufacturing draws from domestic steel mills in the United States, precision forging capacity in Germany, and electronics assembly in South Korea. Single-source vulnerability concentrates in high-grade magnetic permeability steel supply when mill capacity shifts to defense contracts. Distribution runs through certified service hubs co-located with major pipeline corridors, with field technicians deployed from regional bases to minimize mobilization costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal methane compliance costs exceed North American PHMSA thresholds, creating margin expansion for inspection providers with cross-border certification capacity.
For Market Incumbents: Hedge certification concentration risk by acquiring specialized analytics boutiques before PHMSA qualification timelines extend further. Backward integration into sensor manufacturing reduces exposure to steel alloy supply volatility. Defensive positioning requires pre-emptive digital twin deployments to lock in recurring revenue streams ahead of service unbundling fragmentation.
For New Entrants and Emerging Players: Independent data analytics boutiques represent the most penetrable white-space target, as operators separate software procurement from hardware inspection contracts. CO2 transport infrastructure in Alberta and Texas offers uncrowded entry with corrosion-resistant protocol requirements distinct from hydrocarbon standards. Channel partnerships with regional pipeline construction firms provide embedded access to integrity management budgets.
For Investors and Strategic Acquirers: Consolidation pressure builds where PHMSA certification bottlenecks extend eighteen to twenty-four months, favoring acquisition of qualified providers over organic qualification timelines. Long-term viability frames around carbon capture infrastructure expansion and offshore decommissioning wave timing. The signal to watch is EU AI Act diagnostic authorization progress, which will determine automated robotics market access across member state territories.
| Strategic Initiative | Industry Significance |
|---|---|
| PHMSA Certification Investment | Qualification timelines create defensive moats for early movers in high-consequence area markets. |
| Digital Twin Platform Integration | Real-time monitoring workflows lock in recurring revenue from complex gathering system operators. |
| EU AI Act Diagnostic Authorization | Conformity assessment procedures determine automated robotics market access across German and Dutch networks. |
| CO2 Transport Protocol Development | Corrosion-resistant inspection methods for dense phase conditions capture carbon capture infrastructure spending. |
| Offshore Decommissioning Pre-Positioning | Pre-abandonment integrity verification contracts align with North Sea and Gulf of Mexico platform schedules. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with pipeline integrity engineers, midstream procurement directors, PHMSA compliance officers, and digital twin platform architects. Secondary validation draws from PHMSA enforcement databases, EU Pressure Equipment Directive filings, Canada Energy Regulator safety reports, and company SEC disclosures. Bottom-up segment sizing triangulates against top-down market aggregation across service type, pipeline material, and technology maturity tiers.
Rate-of-change decomposition separates volume growth from value expansion across inspection, maintenance, cleaning, and monitoring service categories. The analytical framework models smart pigging penetration curves, data analytics adoption rates, and regulatory-driven replacement cycles across the projection horizon. Segmentation dimensions include pipeline material specifications, end-use sector regulatory intensity, and technology platform diagnostic precision. CAGRs derive from fitted adoption curves weighted by regional infrastructure investment patterns and integrity management program expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PHMSA rulemaking finalization, EU AI Act implementation timelines, and carbon capture transport infrastructure buildout pacing. Forecasts reflect documented assumptions regarding certification bottleneck persistence and steel alloy supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Glass Reinforced Plastic (GRP) Piping Market
Pipes and Tubes
Industrial Tubes Market
Pipes and Tubes
HDPE Pipes Market
Pipes and Tubes
GRE Pipes Market
Pipes and Tubes
Saudi Arabia Copper Pipes and Tubes Market
Pipes and Tubes
PVDF Pipes Market
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
Fttx Pipes Market
Pipes and Tubes
PVC Pipes and Fittings Market
Pipes and Tubes
Heat Shrink Tubing Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
Steel Pipe Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
Oman PVC Pipes Market
Pipes and Tubes
Gas Fittings and Components Market
Pipes and Tubes
India PVC Pipes Market