
 Saw Pipes Market | 2026-2036
Saw Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Saw Pipes Market Analytics
The EU Green Deal is realigning steel procurement standards across European energy infrastructure, forcing pipe mills to certify lower-carbon production methods. ArcelorMittal leverages integrated electric-arc furnace capacity to supply certified low-emission line pipe for North Sea offshore wind export cables. Jindal SAW Ltd. anchors South Asian demand through its spiral-weld facilities serving cross-border oil and gas trunk lines. Tenaris S.A. dominates premium seamless and welded pipe supply for deepwater exploration projects requiring enhanced collapse resistance.
Submerged-arc welded (SAW) pipes are longitudinal or spiral seam steel tubes produced by fusing plate edges with granular flux-shielded electrodes, typically meeting API 5L grades for pressure service in hydrocarbon and water transmission. The manufacturing process accommodates wall thicknesses from 6 mm to over 50 mm and diameters exceeding 100 inches for high-volume fluid transport. Carbon steel spiral-weld configurations lead volume due to cost efficiency in large-diameter trunk lines, while heavy wall and extra heavy wall segments concentrate margin pools in sour service and deepwater applications. Epoxy-coated products are displacing legacy bitumen systems in corrosive soil environments, particularly within oil and gas gathering networks.
The American Petroleum Institute maintains specification authority through API 5L and 5CT standards governing chemical composition, mechanical testing, and hydrostatic verification for line pipe acceptance. In Europe, ECHA's REACH restrictions on hexavalent chromium are accelerating conversion to trivalent passivation and epoxy primer systems for external coatings. India's BIS certification mandates IS 3589 compliance for structural and water supply SAW applications, creating domestic testing infrastructure requirements. Stakeholders must monitor divergence between regional carbon accounting protocols and their cascading impact on cross-border project qualification timelines.
Market Dynamics
Offshore wind export cable corridors and carbon-adjusted procurement mandates are compressing qualification timelines for SAW pipe mills. API 5L certification cycles now overlap with EU carbon border documentation requirements, forcing integrated quality and emissions auditing.
Growth Catalysts
- EU Green Deal carbon border adjustments:Procurement officers in North Sea energy projects now require embodied carbon declarations, redirecting sourcing toward electric-arc furnace producers with verified low-emission grades.
- India's PLI scheme for specialty steel:Domestic manufacturers gain cost offsets for API-grade line pipe production, accelerating cross-border trunk line deployment into Bangladesh and Nepal.
- Spiral-weld automation:Robotic seam tracking and flux recovery systems are reducing rework rates in large-diameter water transmission contracts across Middle Eastern desalination networks.
Market Restraints
- Scrap steel price volatility:Electric-arc furnace operators face margin compression when shredded auto scrap spikes, disproportionately affecting mills without captive scrap yards.
- API 5L-Sour service grade concentration:Only twelve mills worldwide hold current certification for H2S-resistant heavy wall pipe, creating single-source risk for North American shale gathering projects.
- Polyethylene pipeline substitution:Corrosion-free HDPE systems are capturing distribution network contracts below 24-inch diameter in non-pressurized water applications.
Strategic Opportunities
- Saudi Arabia's NEOM hydrogen backbone:Planned green hydrogen export corridors require specialized 56-inch diameter line pipe with ultra-low sulfur specifications, opening premium contract windows.
- Epoxy-FBE coating convergence:Fusion-bonded epoxy systems combined with cathodic protection monitoring are displacing bitumen in subsea tie-in applications.
- Brazil's ANVISA offshore safety mandates:New collapse-resistance testing protocols for pre-salt fields are creating certified supplier shortages that qualified mills can exploit.
Industry Challenges
- Welding engineer scarcity:ASME Section IX certified inspectors command 40 percent wage premiums, constraining mill expansion timelines in competitive labor markets.
- Dual certification complexity:Simultaneous API Q1 and ISO 14064 carbon verification audits require dedicated compliance teams, stretching mid-cap mill resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saw Pipes Market |
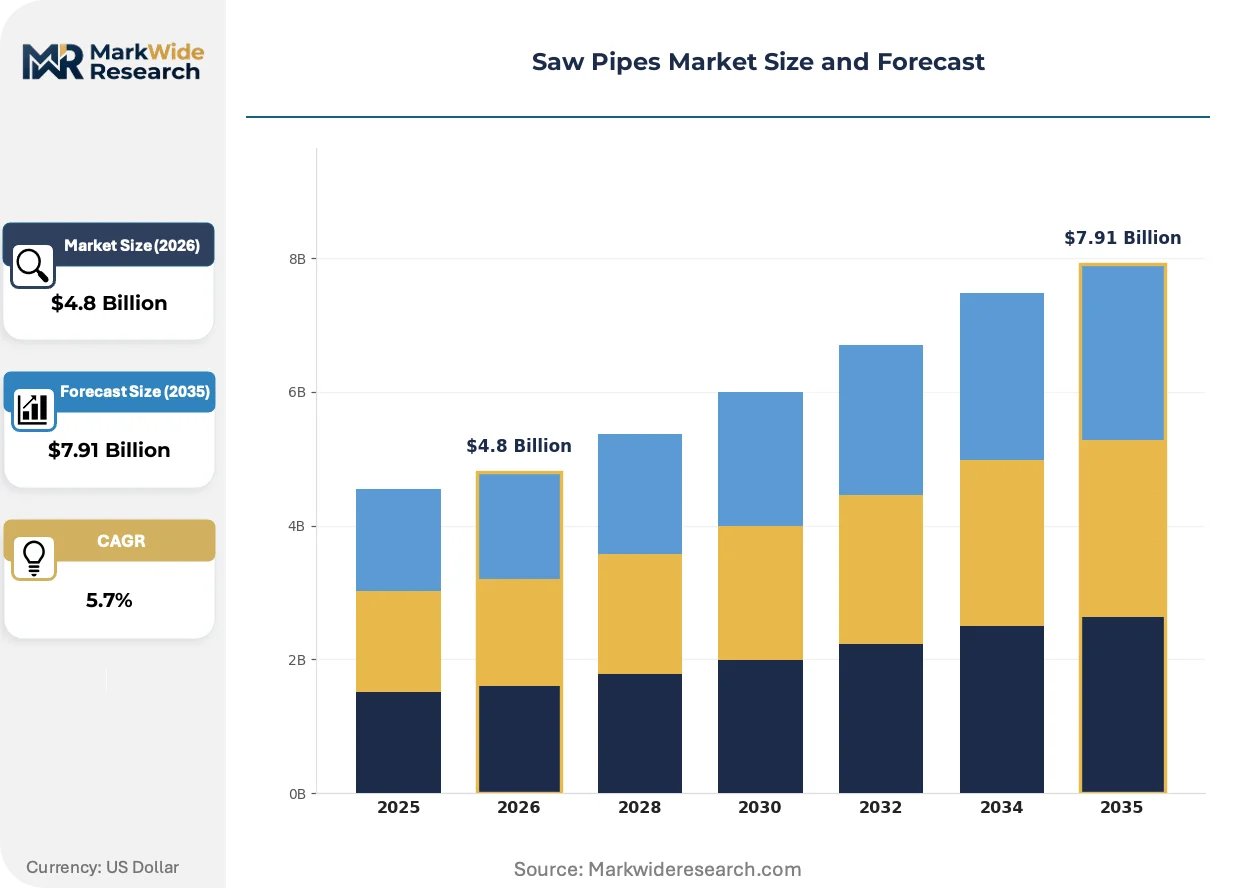
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Steel, Stainless Steel, Alloy Steel, PVC End User: Construction, Oil & Gas, Manufacturing, Marine Thickness: Thin Wall, Medium Wall, Heavy Wall, Extra Heavy Wall Coating Type: Galvanized, Black, Epoxy, Others |
| Companies Covered | Tenaris S.A., Jindal SAW Ltd., ArcelorMittal, Welspun Corp Ltd., Nippon Steel Corporation, JFE Steel Corporation, EUROPIPE GmbH, TMK Group, ChelPipe Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saw Pipes Market Evolving Landscape
Digital thread integration across pipe manufacturing is collapsing the gap between mill production data and field installation traceability. Real-time wall thickness mapping and coating adhesion testing now feed directly into blockchain-based custody records.
Hybrid laser-arc welding is unifying the speed advantages of submerged-arc processes with the precision of fiber laser keyhole control. Offshore contractors in the North Sea are specifying hybrid-seam pipe for monopile transition pieces, compressing fabrication cycle times from twelve weeks to seven. The technology is unifying previously separate quality assurance workflows into single-pass verification protocols.
ECHA's REACH restrictions on hexavalent chromium passivation are forcing coating applicators to convert to trivalent systems or epoxy primer alternatives. External corrosion protection specifications for buried oil and gas lines now exclude legacy chromate treatments across EU member states. Dutch and German transmission system operators are accelerating trivalent conversion timelines to avoid project qualification delays.
Buyers are consolidating annual pipe requirements into multi-year framework agreements with embedded price collars. Major European utilities now contract directly with mills for five-year offshore wind cable protection supply, displacing traditional distributor stocking models. This concentration is most visible in Denmark and the Netherlands, where Orsted and TenneT procurement teams manage integrated steel and coating sourcing.
Saw Pipes Market Segmentation
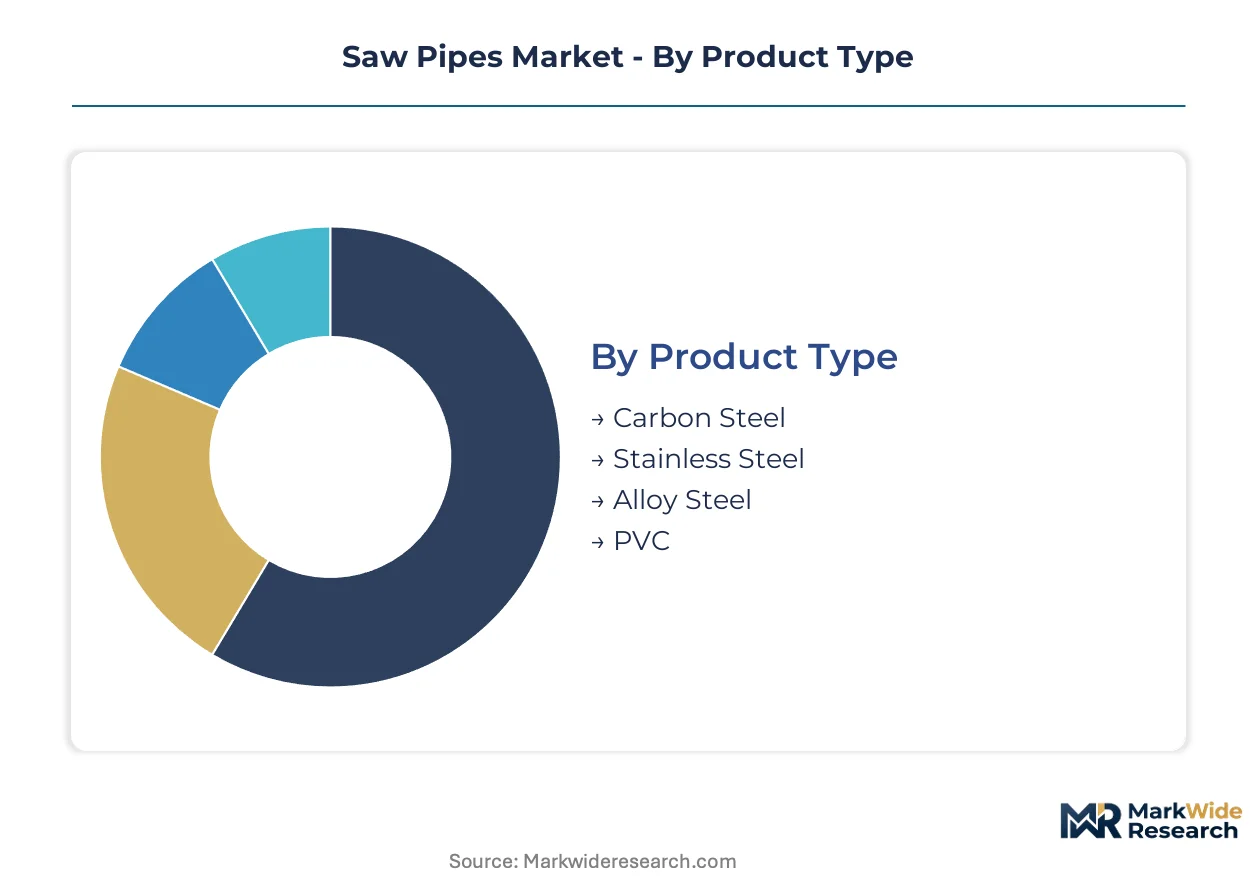
SAW pipe procurement decisions hinge on material grade, wall thickness, and corrosion protection specifications that align with pressure ratings and environmental exposure. Segment boundaries blur when mills offer hybrid configurations—carbon steel cores with stainless cladding, or heavy-wall sections with epoxy-FBE dual-layer systems.
Product Type:
Capital intensity peaks with alloy steel melting and refining infrastructure, while carbon steel leverages widely available blast furnace and electric-arc furnace capacity.
- Carbon Steel:Spiral-weld and longitudinal-seam configurations dominate trunk line deployment, with API 5L grades X52 through X70 serving hydrocarbon transmission across India's cross-border energy corridors and North American shale gathering networks. Demand concentrates in large-diameter water transmission and oil and gas gathering systems where cost efficiency outweighs corrosion resistance requirements.
- Stainless Steel:Austenitic and duplex grades address sour service environments with elevated H2S partial pressures, requiring vacuum-oxygen decarburization and argon-oxygen decarburization refining investments that limit supplier pools. Offshore pre-salt fields in Brazil and North Sea high-pressure tie-ins specify super-duplex seamless and welded configurations for chloride resistance.
- Alloy Steel:Chrome-molybdenum grades serve elevated-temperature boiler feedwater and process piping in refinery and petrochemical complexes.
- PVC:Thermoplastic extrusions compete in non-pressurized drainage and irrigation applications below 16-inch diameter.
Carbon steel absorbs the bulk of installed capacity; stainless steel is expanding most quickly as sour service specifications proliferate.
End User:
Application severity determines testing protocols—collapse resistance for deepwater, fatigue cycles for wind monopiles, pressure cycling for gas storage.
- Construction:Structural piling and foundation applications specify IS 3589 and ASTM A252 grades, with spiral-weld pipes serving bridge caissons and building columns across India's infrastructure buildout.
- Oil & Gas:Line pipe for gathering, transmission, and distribution networks commands the most stringent qualification regimes, with API 5L PSL2 sour service grades requiring HIC and SSC testing per NACE TM0284 and TM0177. Deepwater exploration in Brazil's pre-salt basins and North Sea redevelopment projects specify heavy-wall seamless and SAW hybrid configurations with enhanced collapse resistance.
- Manufacturing:Mechanical tubing for conveyor systems and pressure vessels operates under ASME Section VIII and EN 13445 standards.
- Marine:Subsea flowlines and riser systems require DNV-ST-F101 qualification with strain-based design acceptance criteria.
Oil and gas commands premium pricing tiers; marine applications are climbing the fastest as floating wind and subsea tie-in activity accelerates.
Thickness:
Wall thickness directly determines rolling mill configuration, with heavy and extra-heavy sections requiring specialized plate mills and extended forming cycles.
- Thin Wall:Sub-10 mm sections serve low-pressure water distribution and structural handrail applications with minimal forming energy requirements.
- Medium Wall:10-25 mm configurations balance pressure containment with weight efficiency in standard oil and gas transmission lines.
- Heavy Wall:25-50 mm grades address high-pressure gas transmission, cavern storage, and offshore riser applications where DNV collapse resistance protocols apply. Saudi Arabia's NEOM hydrogen backbone and North Sea carbon capture pipelines specify these sections for pressure containment assurance.
- Extra Heavy Wall:Above 50 mm configurations serve ultra-deepwater tie-ins and high-pressure CO2 injection wells, with limited mill capacity creating supply bottlenecks for pre-salt and Arctic projects.
Medium wall sections move the highest tonnage; extra heavy wall is gaining share fastest as deepwater and high-pressure hydrogen specifications proliferate.
Coating Type:
Surface preparation and coating application lines represent significant capital commitments, with fusion-bonded epoxy systems requiring automated blast cleaning and electrostatic spray booths.
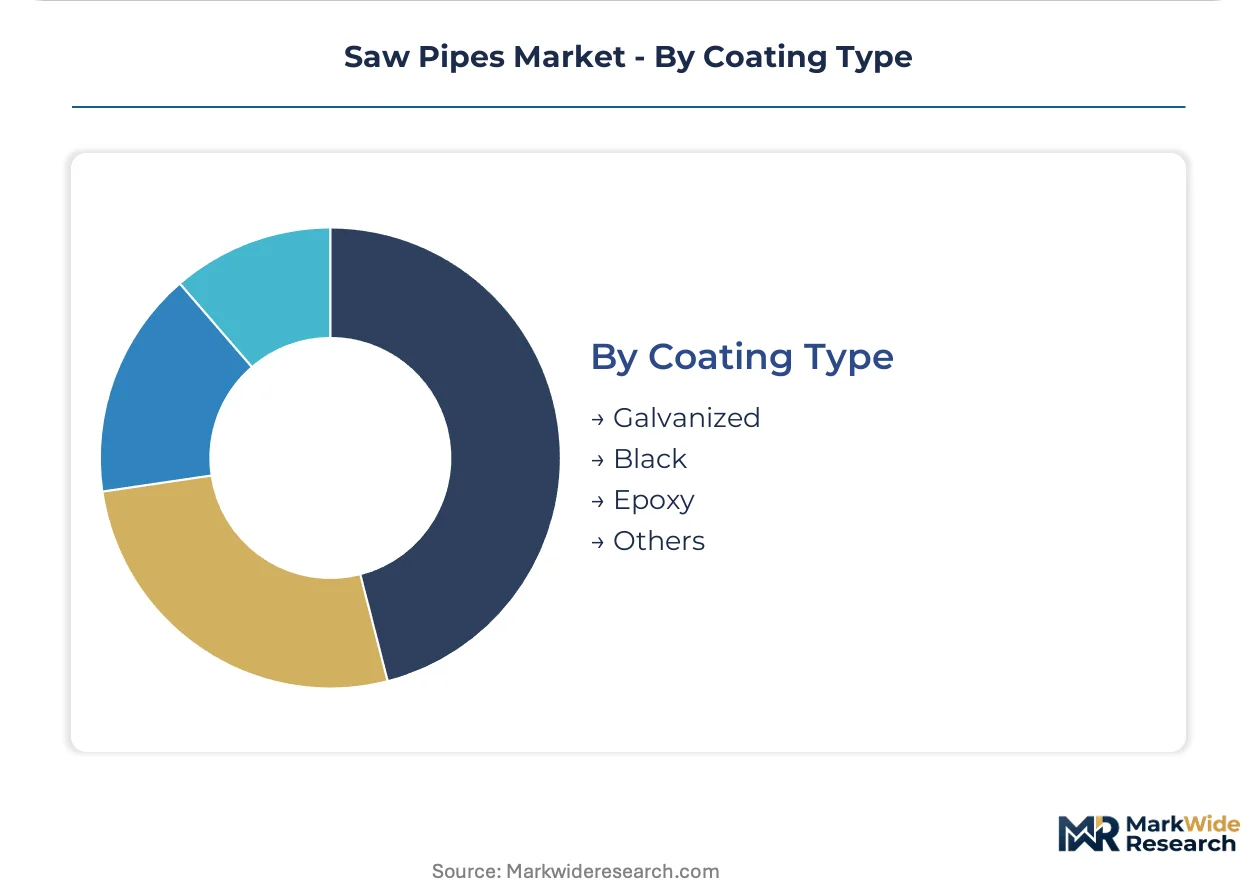
- Galvanized:Hot-dip zinc coatings protect structural and water supply pipes in moderate corrosion environments, with BIS IS 4736 and ASTM A53 specifications governing coating mass requirements.
- Black:Uncoated or mill-lacquered surfaces serve temporary construction applications and indoor process piping where atmospheric corrosion is negligible.
- Epoxy:Fusion-bonded epoxy and liquid epoxy systems displace bitumen in buried oil and gas gathering networks, with ECHA REACH restrictions on hexavalent chromium accelerating trivalent passivation and epoxy primer adoption across EU member states. Dutch and German transmission operators now mandate FBE with cathodic protection compatibility.
- Others:Polyethylene extrusion, polyurethane foam insulation, and concrete weight coating address specialized subsea and cryogenic applications.
Galvanized coatings retain volume leadership in structural segments; epoxy systems are expanding most quickly as corrosion protection specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American demand through its concentration of offshore engineering firms and pipeline contractors serving Gulf of Mexico developments. European procurement teams in Rotterdam and Hamburg coordinate carbon-certified sourcing for North Sea infrastructure. Mumbai and Delhi-NCR host the engineering headquarters for South Asia's cross-border trunk line expansion.
United States
Gulf of Mexico deepwater tie-ins and Permian Basin gathering networks drive specification-heavy procurement. FERC interstate pipeline safety mandates require hydrostatic testing documentation for all API 5L PSL2 line pipe. Houston-Galveston corridor mills concentrate on heavy-wall sour service grades for H2S-rich shale plays.
Germany
North Sea offshore wind export cable protection systems and carbon capture pipeline networks reshape mill qualification requirements. ECHA REACH restrictions on hexavalent chromium accelerate coating applicator conversions to trivalent passivation. Duisburg-Ruhr industrial cluster hosts electric-arc furnace producers supplying low-emission grades for Dutch and Danish transmission operators.
India
Cross-border energy corridors into Bangladesh and Nepal plus domestic city gas distribution networks expand API-grade line pipe consumption. BIS certification mandates IS 3589 compliance for water transmission SAW applications alongside API standards for hydrocarbon service. Gujarat and Maharashtra host spiral-weld facilities serving Middle Eastern export contracts.
Brazil
Pre-salt deepwater exploration and floating wind platform mooring systems demand enhanced collapse-resistance specifications. ANVISA offshore safety mandates create certified supplier shortages for strain-based design protocols. Rio de Janeiro-São Paulo industrial corridor concentrates pipe coating and logistics infrastructure for Atlantic basin projects.
Saudi Arabia
NEOM green hydrogen backbone and Red Sea coastal development schemes specify ultra-large-diameter line pipe with sulfur content below 0.003 percent. SFDA industrial product standards align with API 5L for pressure-containing applications. Eastern Province Jubail industrial city hosts plate mill and coating integration for domestic energy infrastructure.
Saw Pipes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and coating integration capabilities. The vendor base organizes into three tiers: integrated steel majors with captive plate production, specialized pipe mills with external steel sourcing, and regional fabricators serving structural applications. Strategic moves concentrate on dual certification for API Q1 quality systems and ISO 14064 carbon verification, plus coating line expansions for fusion-bonded epoxy capacity.
Within the integrated steel tier, Tenaris S.A. and ArcelorMittal occupy positions spanning seamless and welded pipe supply with electric-arc furnace flexibility for low-carbon grades. Jindal SAW Ltd. anchors the South Asian specialist segment with spiral-weld concentration for cross-border trunk lines. These three exemplify divergent paths: steel-backed integration versus pipe-centric specialization.
| Leading Market Players |
|---|
| Tenaris S.A. |
| Jindal SAW Ltd. |
| ArcelorMittal |
| Welspun Corp Ltd. |
| Nippon Steel Corporation |
| JFE Steel Corporation |
| EUROPIPE GmbH |
| TMK Group |
| ChelPipe Group |
| Others |
Value Network & Pricing Analysis
Hot-rolled coil indices at Rotterdam and Shanghai anchor SAW pipe pricing tiers, transmitting volatility from scrap and iron ore markets through electric-arc furnace and blast furnace mill cost structures into contract negotiations for API-grade line pipe.
Pricing Analysis
Collapse-resistance certification for deepwater applications anchors value-based pricing premiums, separating qualified mills from commodity-grade competitors. Three-tier pricing structure across premium, standard, and economy levels stratifies by API 5L PSL2 sour service grade, wall thickness category, and coating integration. Cost compression in standard carbon steel spiral-weld is intensifying because polyethylene substitution captures distribution contracts below 24-inch diameter. Municipal water authorities exhibit highest price sensitivity; offshore EPC contractors prioritize qualification certainty over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from North Sea offshore wind developers and Saudi hydrogen corridor operators mandate multi-supplier qualification for heavy-wall segments, preventing single-mill dependency. Plate production concentrates in India, China, and Germany, with coating integration clustering in Jubail, Duisburg-Ruhr, and Houston-Galveston. Supply chains draw from shredded auto scrap, direct-reduced iron, and granular welding flux as critical inputs. Single-source vulnerability persists for API 5L-Sour service certification holders. Distribution runs through mill-direct framework agreements with five-year price collars, displacing traditional distributor stocking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAW pipe manufacturing sits in a coating-technology transition phase, with fusion-bonded epoxy systems displacing bitumen and hexavalent chromium passivation across EU energy infrastructure.
For Market Incumbents: Hedge against polyethylene substitution in sub-24-inch water distribution by accelerating hybrid laser-arc welding adoption for monopile transition pieces. Backward integration into captive plate production secures margin control when scrap volatility spikes. Prioritize dual certification for API Q1 quality systems and ISO 14064 carbon verification to maintain North Sea procurement eligibility. For New Entrants and Emerging Players: Regional water utilities in Bangladesh and Nepal present underserved buyer archetypes for IS 3589-compliant spiral-weld pipe, bypassing API-grade qualification barriers. White-space targets include trivalent passivation coating services for Dutch and German transmission operators converting from hexavalent chromium. Go-to-market through engineering-procurement-contractor partnerships for cross-border trunk line projects. For Investors and Strategic Acquirers: Distressed-cycle entries favor electric-arc furnace pipe mills with verified low-emission grades in India and Germany, positioned for EU carbon border adjustment compliance. Long-term viability hinges on coating integration capabilities and sour service certification depth. Watch scrap-to-spread compression as the inflection indicator for mill margin stress.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Laser-Arc Welding Adoption | Compresses fabrication cycles for North Sea monopile contracts from twelve weeks to seven. |
| Dual Certification Investment | API Q1 and ISO 14064 alignment secures qualification for EU Green Deal procurement mandates. |
| Coating Line Expansion | Fusion-bonded epoxy capacity captures Dutch and German transmission operator conversion demand. |
| Backward Integration into Plate | Captive steel supply insulates margins from Rotterdam hot-rolled coil index volatility. |
| Regional Mill Acquisition | India-based spiral-weld facilities access PLI scheme offsets for Bangladesh and Nepal corridor deployment. |
Research Methodology
Trade databases, API certification registries, and ECHA regulatory filings formed the secondary backbone, cross-referenced with primary interviews with pipe mill operations directors, offshore EPC procurement managers, and transmission system operator engineering leads. Bottom-up and top-down triangulation validated volume estimates across product type, wall thickness, and coating specification segments.
Bottom-up modeling anchored projections, with top-down macro checks against energy infrastructure capex disclosures and cross-border pipeline development timelines. Segmentation dimensions included material grade, end-use application severity, wall thickness category, and corrosion protection specification. CAGRs were derived from fitted growth curves applied to disclosed capacity expansions and contract award patterns, with hydrogen backbone and floating wind demand curves as industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to scrap price volatility, REACH regulatory expansion, and polyethylene substitution rates in water distribution. Deviation in EU carbon border adjustment implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Multiflex Tubes Market
Pipes and Tubes
UAE PVC Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
GRE Pipes Market
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
Steel Pipes and Tubes Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
Aluminum Pipe Market
Pipes and Tubes
Global Polyolefin Pipes Market
Pipes and Tubes
Stainless Steel Tank Container Market
Pipes and Tubes
Global CPVC Pipes and Fittings Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
OCTG Pipe Market
Pipes and Tubes
Plastic Pipe Jointing and Welding Market
Pipes and Tubes
PVC Pipes Market
Pipes and Tubes
Americas Steel Pipes Market