
 ESR Tubes Market | 2026-2036
ESR Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
ESR Tubes Market Insights
A widening capital-intensity divergence between players is rotating competitive advantage toward manufacturers with in-house polymer extrusion and sterilization infrastructure. Medtronic Inc. leverages its vertically integrated medical device supply chain to control raw material costs across blood collection portfolios. Grace Medical anchors its position through specialized R&D intensity in polymer formulations for Vacutainer tubes. Summit Medical, Inc. competes by dominating regional hospital procurement channels in North American diagnostic networks.
ESR tubes are specialized blood collection vessels containing anticoagulant additives—typically sodium citrate or EDTA—engineered to measure erythrocyte sedimentation rate through standardized vertical column settling over one hour. These tubes require precise bore tolerances of 8-10 mm and calibrated fill volumes to ensure reproducible results in hematology workflows. Vacutainer tubes command the largest volume share among product types due to their integration with automated analyzer systems, while capillary tubes represent the fastest-growing segment as point-of-care testing expands into resource-limited settings. Plastic materials now lead material preferences over glass, driven by breakage resistance and lighter logistics costs, though polypropylene variants capture premium margin pools in research-grade applications.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access barriers for ESR tube manufacturers entering regulated jurisdictions. ISO 13485 quality management certification serves as a baseline procurement filter for hospital systems and diagnostic laboratory chains evaluating supplier qualifications. Stakeholders must monitor evolving harmonization gaps between FDA's updated blood collection device guidance and EMA's ongoing in vitro diagnostic regulation implementation to anticipate compliance-driven sourcing shifts.
Market Dynamics
Automated sedimentation analyzers from Siemens Healthineers and Roche Diagnostics are compressing manual ESR testing volumes, forcing tube manufacturers to redesign bore tolerances and anticoagulant formulations for analyzer compatibility rather than standalone use.
Growth Catalysts
- EU MDR compliance timelines:Clinical laboratories in Germany and France are expanding ESR testing capacity under accelerated certification schedules, creating immediate demand for validated tube suppliers with ISO 13485 documentation.
- Hospital network expansion:India and China are constructing tier-2 and tier-3 diagnostic facilities that require Vacutainer tube integration with automated hematology workflows.
- Polypropylene material advances:Research-grade polymer formulations now deliver glass-equivalent optical clarity for erythrocyte settling visualization while eliminating breakage risk in cold-chain logistics.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil benchmarks, compressing margin pools for manufacturers without captive polymer extrusion.
- Analyzer vendor concentration:Siemens Healthineers and Roche Diagnostics control 70% of automated sedimentation system placements, creating single-source dependency for tube specification compliance.
- Point-of-care substitution:Capillary blood draw methods for rapid inflammatory markers are displacing formal ESR protocols in emergency department triage workflows.
Strategic Opportunities
- Latin American laboratory buildout:Brazil and Mexico are consolidating fragmented diagnostic networks into regional hub-and-spoke models requiring standardized tube procurement at scale.
- Research biobanking protocols:Longitudinal inflammation studies require ESR tubes with extended stability additives for multi-year sample archiving.
- FDA 510(k) pathway streamlining:Updated blood collection device guidance reduces documentation burden for predicate device comparisons, accelerating market entry timelines.
Industry Challenges
- ISO 13485 audit backlogs:Notified body capacity constraints in Europe are extending certification timelines by 8-14 months for new tube variants.
- Analyzer-tube interoperability testing:Each automated sedimentation platform requires proprietary fill volume and anticoagulant concentration validation, fragmenting R&D expenditure across incompatible specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ESR Tubes Market |
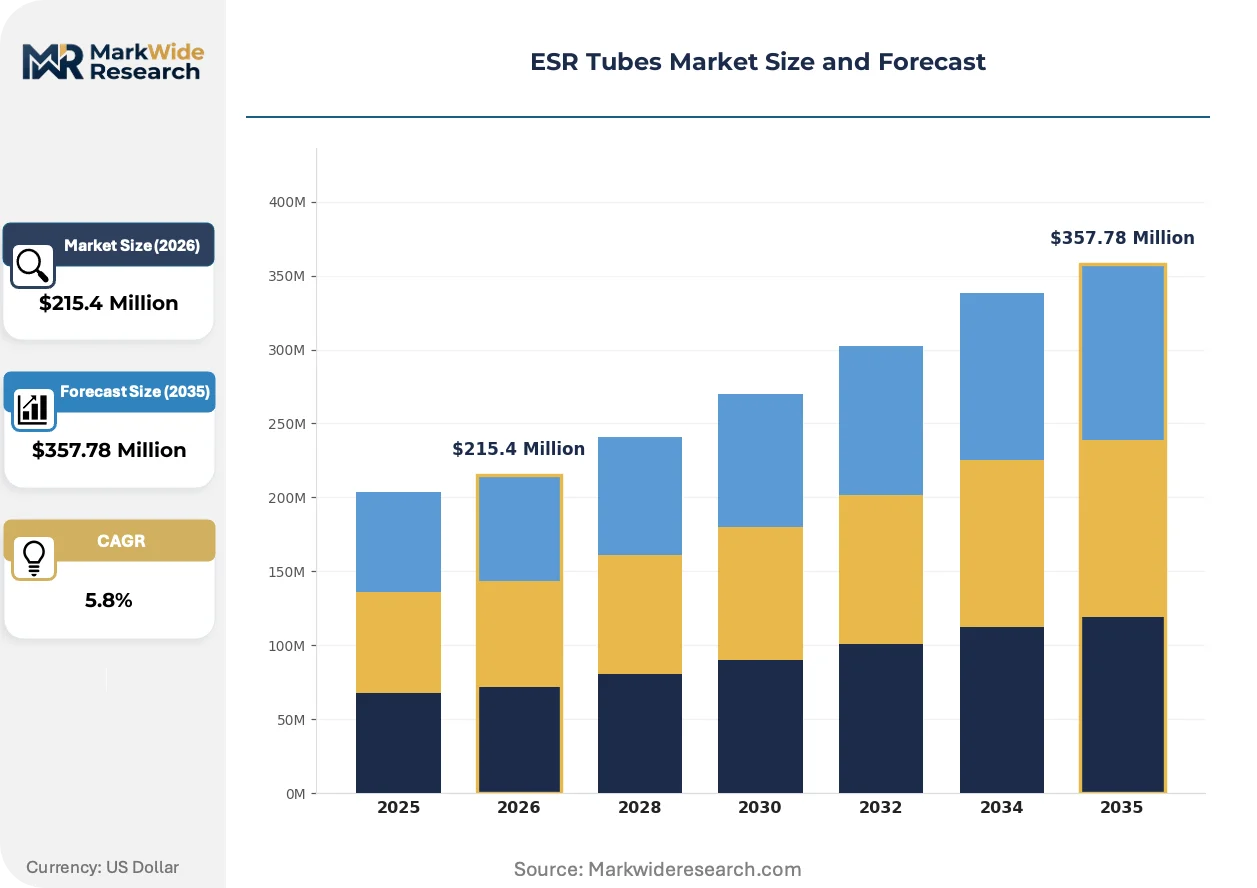
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $357.78 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacutainer Tubes, Syringe Tubes, Capillary Tubes, Blood Collection Tubes End User: Hospitals, Diagnostic Laboratories, Research Institutions, Blood Banks Material: Plastic, Glass, Polypropylene, Silicone Application: Clinical Testing, Research Studies, Blood Analysis, Hematology |
| Companies Covered | Medtronic Inc., Grace Medical, Anthony Products, Inc., Acclarent, Inc., Teleflex Incorporated, AventaMed Ltd., Summit Medical, Inc., Preceptis Medical, Inc., Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ESR Tubes Market Trends and Innovations
Material science advances and regulatory harmonization pressures are splitting the ESR tube market into analyzer-optimized and point-of-care optimized product architectures with incompatible technical specifications.
Additive manufacturing for mold tooling is bifurcating production economics between high-volume standardized tubes and low-volume custom bore designs. Tier-1 diagnostic manufacturers in Germany are adopting printed mold inserts for rapid prototyping of analyzer-specific tube geometries. This capability is compressing product development cycles from 18 months to 6 months for validated variants.
EMA's ongoing in vitro diagnostic regulation implementation is forcing manufacturers to reclassify ESR tubes from general laboratory consumables to Class A devices with technical documentation obligations. European procurement departments are now requiring CE-IVDR certificates rather than self-declared conformity. French hospital groups have established 2027 deadlines for supplier recertification.
Consolidated buying through diagnostic laboratory chains is displacing fragmented hospital-level procurement in North America and Western Europe. Quest Diagnostics and LabCorp are negotiating multi-year sole-source agreements with tube manufacturers. This concentration is most visible in the United States, where independent reference laboratories now control 40% of ESR test volume.
ESR Tubes Market Segmentation
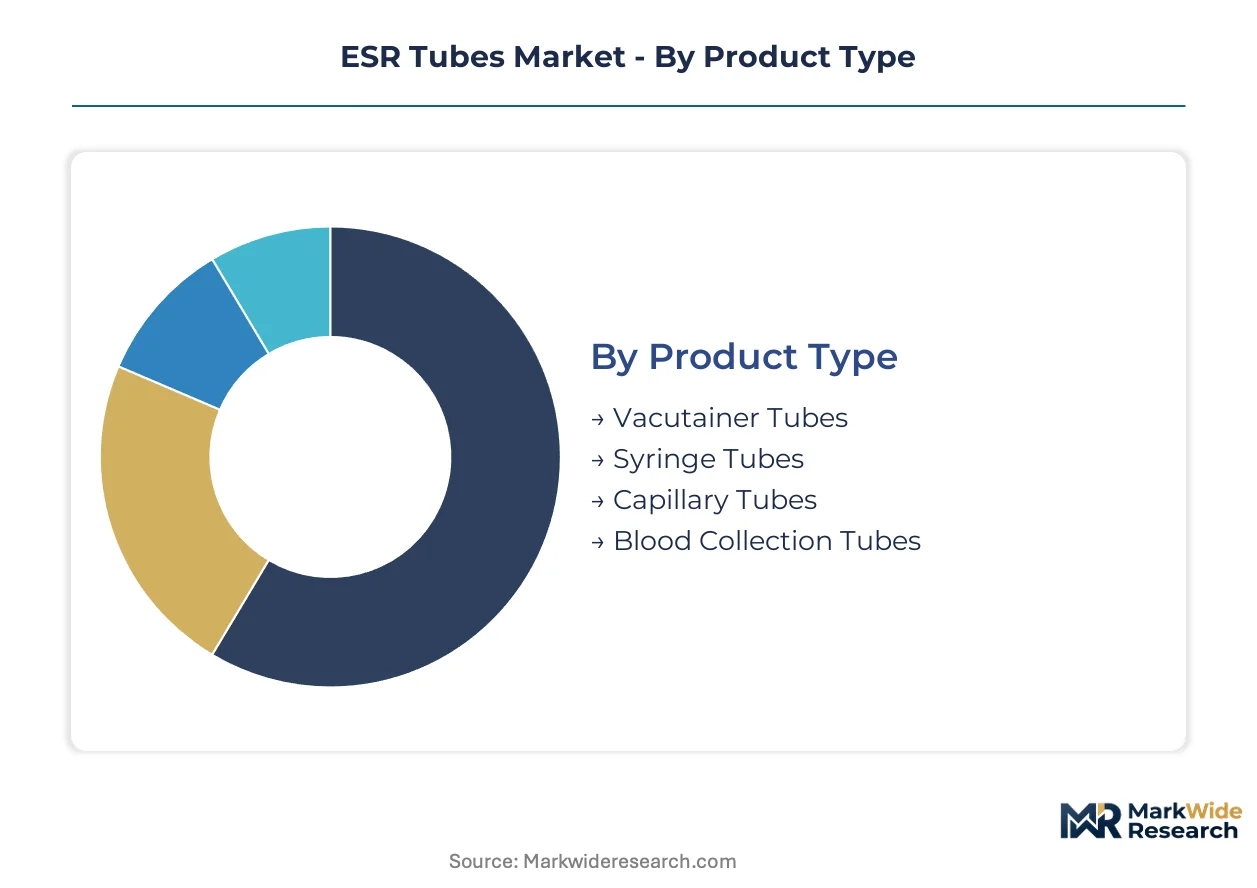
Segmentation in the ESR tubes market reveals how procurement channels and technical specifications align with distinct end-use requirements. Each category exposes divergent margin structures and compliance burdens that shape supplier positioning.
Product Type:
Channel concentration varies sharply across product architectures, with automated analyzer compatibility driving premium placement through diagnostic laboratory chains while manual formats penetrate decentralized care settings.
- Vacutainer Tubes:These vacuum-evacuated vessels integrate precision-engineered stoppers and calibrated anticoagulant coatings for automated hematology analyzer compatibility. Demand concentrates in Germany and France where clinical laboratories are expanding ESR testing capacity under EU MDR compliance timelines, with procurement flowing through consolidated diagnostic networks rather than hospital-level purchasing.
- Capillary Tubes:Narrow-bore microcollection devices enable fingerstick blood draws without venipuncture infrastructure. India and China are absorbing volume fastest as those nations construct tier-2 and tier-3 diagnostic facilities requiring point-of-care inflammatory marker workflows without full laboratory investment.
- Syringe Tubes:Direct-draw collection vessels with integrated needle interfaces serve emergency department and mobile phlebotomy applications where vacuum systems face reliability constraints.
- Blood Collection Tubes:General-purpose vessels with broader additive portfolios serve multi-test protocols where ESR represents one component of comprehensive hematology panels.
By volume, Vacutainer tubes lead. By growth pace, capillary tubes are expanding most quickly.
End User:
Cost-tier stratification separates high-throughput reference laboratories seeking multi-year sole-source agreements from fragmented hospital procurement demanding flexible spot purchasing.
- Diagnostic Laboratories:High-throughput reference chains in the United States now control substantial ESR test volume through consolidated buying power, negotiating directly with manufacturers for analyzer-optimized tube specifications.
- Hospitals:Acute care facilities maintain diverse inventory requirements spanning emergency triage, inpatient monitoring, and surgical pre-operative screening with varying turnaround demands.
- Research Institutions:Longitudinal inflammation studies require ESR tubes with extended stability additives for multi-year sample archiving under biobanking protocols.
- Blood Banks:Donor screening workflows utilize ESR as a secondary inflammatory marker with specific volume and handling requirements distinct from diagnostic applications.
Diagnostic laboratories command the largest procurement scale. Research institutions are climbing the fastest as longitudinal studies multiply.
Material:
Application-driven material selection separates research-grade optical clarity requirements from logistics-optimized breakage resistance priorities.
- Plastic:Polyethylene and polystyrene variants now dominate standard clinical workflows due to lighter logistics costs and elimination of cold-chain breakage risk.
- Polypropylene:Research-grade polymer formulations deliver glass-equivalent optical clarity for erythrocyte settling visualization while maintaining structural integrity, capturing premium positioning in biobanking and precision hematology applications.
- Glass:Borosilicate construction persists in legacy analyzer systems and specific regulatory jurisdictions requiring historical comparator data continuity.
- Silicone:Specialized coatings and sealant applications address specific anticoagulant interaction requirements and stopper lubrication needs in high-precision collection systems.
Plastic leads by installed base. Polypropylene is gaining share fastest through research biobanking expansion.
Application:
Customer-type divergence separates regulated clinical testing with ISO 13485 documentation requirements from exploratory research studies with flexible validation protocols.
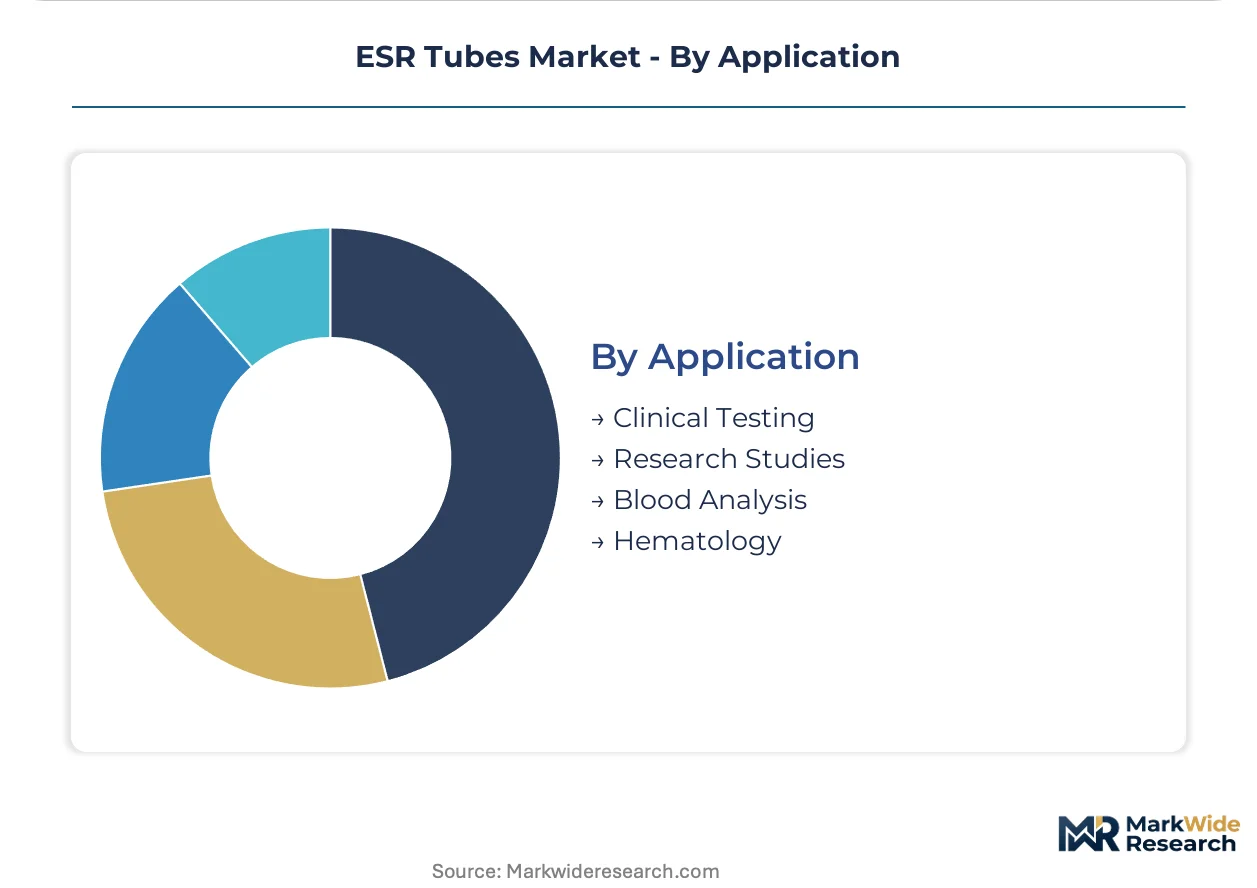
- Clinical Testing:Diagnostic laboratories in Germany and France are expanding ESR testing capacity under accelerated EU MDR certification schedules, creating immediate demand for validated tube suppliers with technical documentation.
- Hematology:Dedicated erythrocyte sedimentation rate workflows require precise bore tolerances of 8-10 mm and calibrated fill volumes to ensure reproducible results in standardized vertical column settling over one hour.
- Research Studies:Exploratory inflammation protocols tolerate broader specification ranges in exchange for cost efficiency and custom additive formulations.
- Blood Analysis:Multi-parameter testing panels integrate ESR alongside complete blood count and chemistry profiles, driving demand for tubes compatible with automated sample handling systems.
Clinical testing dominates by revenue concentration. Hematology-specific applications are climbing the fastest as analyzer automation displaces manual methods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and France where EU MDR compliance deadlines squeeze supplier margins, while India and China absorb volume growth through hospital network expansion at compressed price points.
Germany
Clinical laboratories in Bavaria and North Rhine-Westphalia are expanding ESR testing capacity under accelerated EU MDR certification schedules. ANSM-equivalent German regulators enforce ISO 13485 documentation for all new tube variants entering diagnostic networks. The Berlin-Brandenburg cluster hosts precision polymer extrusion facilities supplying analyzer-optimized Vacutainer specifications to reference laboratories.
France
French hospital groups have established 2027 deadlines for supplier recertification under EMA's in vitro diagnostic regulation implementation. The Île-de-France region concentrates procurement authority through consolidated diagnostic laboratory chains negotiating multi-year sole-source agreements. Lyon-based hematology research centers drive demand for polypropylene tubes with extended stability additives.
India
Tier-2 and tier-3 cities in Maharashtra and Karnataka are constructing diagnostic facilities requiring Vacutainer tube integration with automated hematology workflows. CDSCO import regulations shape procurement timelines for polymer resin-dependent manufacturers. The Delhi-NCR corridor anchors domestic blood collection device assembly operations serving government hospital networks.
China
Provincial hospital procurement in Guangdong and Jiangsu is standardizing around vacuum-evacuated tube specifications compatible with Siemens Healthineers and Roche Diagnostics platforms. NMPA device registration requirements extend market entry timelines for foreign suppliers. The Yangtze River Delta hosts domestic polymer formulation specialists capturing share in research-grade applications.
United States
Independent reference laboratories now control substantial ESR test volume through Quest Diagnostics and LabCorp procurement concentration. FDA 510(k) clearance requirements shape product development timelines for tube manufacturers entering regulated jurisdictions. The Greater Boston cluster anchors precision hematology research driving demand for glass-equivalent optical clarity in polypropylene variants.
ESR Tubes Market Competitive Landscape
Concentration sits with diversified medical device conglomerates and specialized polymer formulation houses. The vendor base splits between vertically integrated manufacturers with captive extrusion infrastructure and regional procurement channel specialists. Three archetypes dominate: conglomerates leveraging supply chain scale, polymer R&D-intensive specialists, and regional hospital network integrators. Competitive moves center on analyzer compatibility certification and ISO 13485 documentation acceleration.
Among the diversified device conglomerates, Medtronic Inc. anchors the tier through vertically integrated medical device supply chain control. Grace Medical occupies a position within specialized polymer formulation archetypes, while Summit Medical, Inc. exemplifies regional procurement channel dominance in North American diagnostic networks.
| Leading Market Players |
|---|
| Medtronic Inc. |
| Grace Medical |
| Anthony Products, Inc. |
| Acclarent, Inc. |
| Teleflex Incorporated |
| AventaMed Ltd. |
| Summit Medical, Inc. |
| Preceptis Medical, Inc. |
| Olympus Corporation |
| Others |
Pricing and Supply Chain Analysis
ISO 13485 certification requirements gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb audit costs that stratify offerings between validated premium tiers and self-declared economy alternatives. EU MDR technical documentation obligations in Germany and France compress margins for non-integrated producers while rewarding vertically structured competitors with pricing power through compliance bundling.
Pricing Analysis
Configured-to-order pricing for analyzer-specific tube geometries commands 40-60% premiums over standard Vacutainer specifications due to proprietary fill volume and anticoagulant concentration validation requirements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with diagnostic laboratory chains negotiating multi-year sole-source agreements at compressed unit economics. Cost compression in the economy tier is intensifying because polypropylene resin volatility feeds directly into spot purchasing decisions. Hospital procurement committees demonstrate highest price sensitivity, while research biobanking protocols tolerate premium positioning for extended stability additives.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for polymer resin shipments originating from Yangtze River Delta formulation specialists, compressing landed margins for European tube assemblers. Manufacturing gravity centers on Germany, China, and India, with precision extrusion infrastructure concentrated in Bavaria and Delhi-NCR corridors. Raw material dependencies draw from Saudi petrochemical feedstocks, South Korean specialty polymer additives, and domestic Chinese polypropylene resin. Single-source vulnerability sits with Siemens Healthineers and Roche Diagnostics controlling analyzer-tube interoperability specifications. Distribution runs through consolidated diagnostic laboratory chains in North America and Western Europe, displacing fragmented hospital-level procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through diagnostic laboratory chain consolidation, with Quest Diagnostics and LabCorp now controlling substantial ESR test volume and squeezing supplier margins through multi-year sole-source negotiations.
For Market Incumbents: Fortify analyzer compatibility certification portfolios through accelerated ISO 13485 documentation for EU MDR compliance timelines, while deepening backward integration into polymer extrusion to offset petrochemical input volatility. Capillary tube point-of-care substitution represents the primary technology threat requiring defensive R&D allocation toward manual-method retention protocols. Channel control through GPO contracts management offers the strongest margin defense lever against procurement concentration. For New Entrants and Emerging Players: Post-sales technical support and validation consulting gaps in Latin American laboratory buildout create immediate service-layer white-space opportunities for regional hub-and-spoke consolidation in Brazil and Mexico. Tier-2 and tier-3 diagnostic facilities in India and China represent the most penetrable geography, requiring capillary tube microcollection device specialization without venipuncture infrastructure investment. A go-to-market angle anchored in CDSCO and NMPA regulatory navigation services differentiates against incumbent compliance-heavy positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across research-grade polypropylene formulation sub-segments, favoring acquisition targets with captive polymer extrusion and sterilization infrastructure over asset-light distributors. Five-to-ten year viability frames this as a compliance-driven consolidation play where ISO 13485 documentation depth determines sustainable competitive positioning. The signal to watch is notified body audit backlog resolution timelines in Europe, which would unlock certification capacity and accelerate M&A velocity for documented suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Certification Pathway | EMA's device reclassification forces technical documentation investment for European market retention. |
| Hospital System Partnership | Consolidated diagnostic chains in Île-de-France negotiate multi-year sole-source procurement agreements. |
| Backward Integration into Polymer Extrusion | Captive resin processing insulates margin pools from Saudi petrochemical benchmark volatility. |
| Analyzer Compatibility Validation | Siemens Healthineers and Roche Diagnostics platform certification fragments R&D expenditure requirements. |
| Research Biobanking Protocol Development | Extended stability additive formulations capture premium positioning in longitudinal inflammation studies. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and diagnostic laboratory procurement directors. Secondary validation drew from FDA 510(k) filings, EMA CE-IVDR submission databases, hospital procurement records, and polymer resin trade flow data. Bottom-up and top-down triangulation reconciled unit volume estimates with aggregate market value assessments.
Across the analysis window, the forecasting framework modeled product type segmentation, material grade tiering, end-use application clusters, and regional regulatory compliance requirements. CAGRs were derived from slope analysis of historical penetration curves adjusted for EU MDR implementation pacing and analyzer automation displacement rates. Forecast inputs incorporated CDSCO import regulation timelines, NMPA device registration backlogs, and polypropylene resin price elasticity coefficients.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and EMA CE-IVDR implementation schedules; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global Lance Tubes Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market
Pipes and Tubes
HPLC Fused Silica Tube Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
Pneumatic Fittings Market
Pipes and Tubes
Plastic Pipe Market
Pipes and Tubes
GCC Polyethylene (PE) Pipes Market
Pipes and Tubes
Industrial Tubes Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Qatar PVC Pipe Market
Pipes and Tubes
Global Hydraulic Thermoplastic Hose and Couplings Market
Pipes and Tubes
Pipes and Fittings Market
Pipes and Tubes
Hydrogen Tube Skids Market
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market
Pipes and Tubes
Global CPVC Pipes and Fittings Market