
 Weld Overlay Process Clad Pipes Market | 2026-2036
Weld Overlay Process Clad Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Weld Overlay Process Clad Pipes Market Insights
Corrosion-resistant alloy overlays on carbon steel substrates is expanding as operators replace solid CRA pipe in high-CO2 well environments. Proclad leverages integrated overlay and clad pipe manufacturing across Europe and Asia-Pacific to sustain project delivery timelines for major energy contractors. Eisenbau Kramer anchors its position through specialized heavy-wall clad pipe production for offshore platform risers and flowlines. The Japan Steel Works differentiates via advanced hot-rolling bond technology for thick-wall transition joints in LNG service.
Weld overlay process clad pipes combine a corrosion-resistant inner layer metallurgically bonded to a structural carbon steel outer pipe, typically achieving overlay thicknesses of 3–12 mm with bond shear strengths exceeding 140 MPa per API 5LD. This construction delivers hydrocarbon containment integrity at roughly 40–60% of the installed cost of solid corrosion-resistant alloy pipe. Nickel based clad configurations command premium positioning in sour gas applications where hydrogen sulfide partial pressures exceed 0.05 psi. Submerged arc welding retains volume leadership in large-diameter line pipe overlay, while plasma transferred arc penetration is accelerating in precision bore cladding for downhole tubulars.
API 5LD governs dimensional and mechanical requirements for clad and lined steel pipe in US hydrocarbon service, while Norway's NORSOK M-630 mandates supplementary qualification testing for subsea applications in the North Sea. China's GB/T 28897 provides domestic overlay pipe standards aligned with offshore platform construction in the Bohai Bay and South China Sea. Buyers must monitor evolving hydrogen embrittlement test protocols and qualification thresholds as hydrogen pipeline repurposing gains traction among European transmission operators.
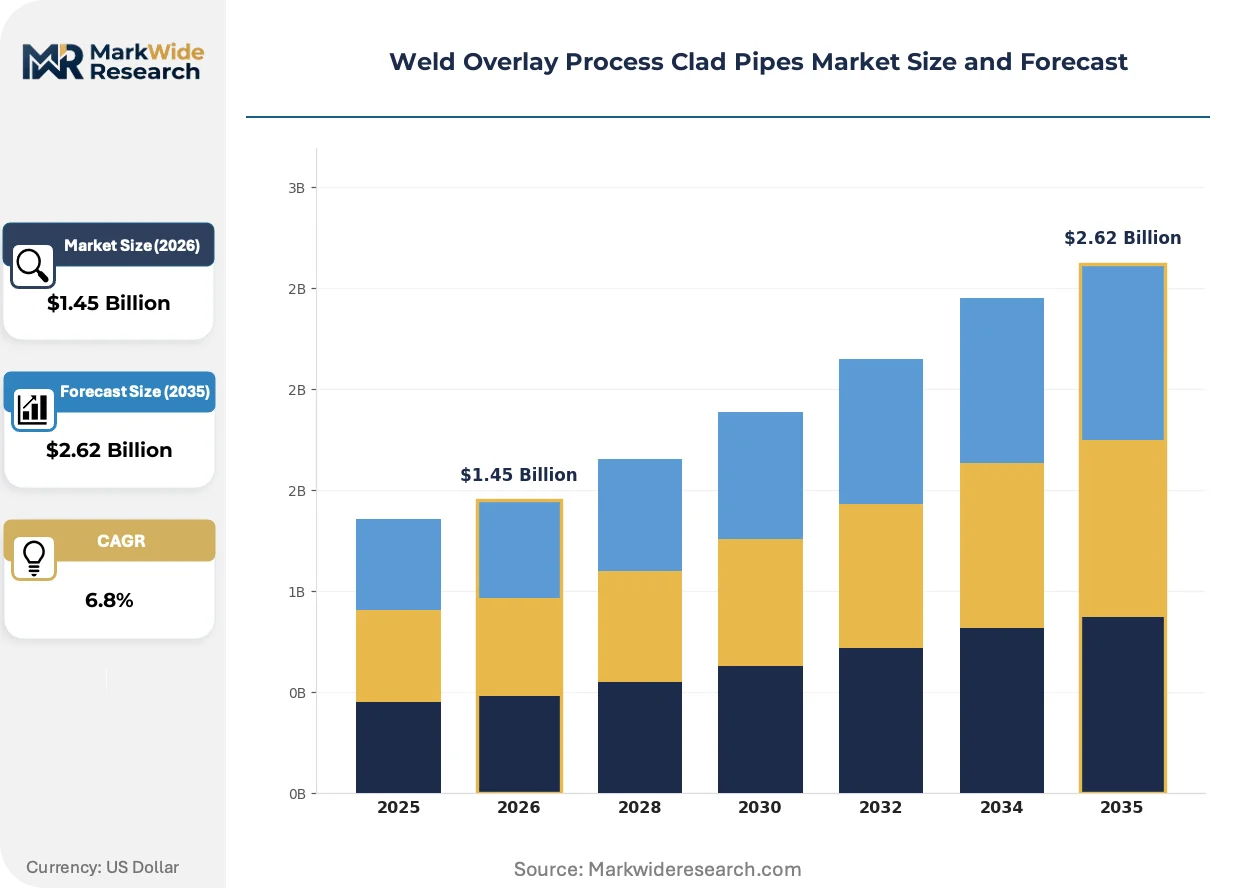
Market Dynamics
Plasma transferred arc welding penetration in precision bore cladding is compressing defect rates and tightening API 5LD certification thresholds, forcing overlay specialists to recalibrate quality systems and capital deployment toward automated deposition cells.
Growth Catalysts
- Subsea tieback expansion:Offshore operators in the Gulf of Mexico and North Sea are procuring corrosion-resistant clad piping for deepwater field development, displacing solid CRA pipe in high-pressure CO2 environments.
- API 5LD tightening:The American Petroleum Institute's updated mechanical and dimensional requirements for clad steel pipe are elevating bond shear strength benchmarks above 140 MPa, filtering out marginal suppliers.
- Hydrogen pipeline repurposing:European transmission operators are qualifying overlay pipe for hydrogen service, creating new demand for nickel-based clad configurations tested against evolving hydrogen embrittlement protocols.
Market Restraints
- Nickel alloy input volatility:Inconel and Alloy 625 overlay wire pricing swings compress margin predictability for job shops without long-term offtake agreements with specialty metal producers.
- Submerged arc welding supply concentration:Large-diameter line pipe overlay capacity clusters with a limited set of European and Asian fabricators, creating bottleneck risk for urgent project timelines.
- Solid CRA substitution in low-pressure service:Seamless stainless pipe retains cost advantage in onshore gathering systems below 1,000 psi, constraining clad pipe penetration in midstream infrastructure.
Strategic Opportunities
- Bohai Bay platform construction:China's offshore expansion under GB/T 28897 standards creates procurement windows for qualified overlay fabricators with domestic certification pathways.
- Plasma-transferred arc convergence with robotic deposition:Automated bore cladding systems are reducing labor content and cycle time for downhole tubulars, opening precision-service contracts with drilling contractors.
- NORSOK M-630 tailwinds:Norway's supplementary qualification mandate for North Sea subsea applications is accelerating qualification spending by suppliers targeting Statoil and Aker Solutions frameworks.
Industry Challenges
- PTA welder certification scarcity:Plasma transferred arc operators with subsea qualification records command premium wages, constraining throughput expansion for mid-tier fabricators.
- API 5LD audit compression:Third-party inspection timelines for bond shear and corrosion testing have extended from 12 to 20 weeks, delaying project handoffs and working capital recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weld Overlay Process Clad Pipes Market |
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Steel Clad, Stainless Steel Clad, Alloy Steel Clad, Nickel Based Clad Welding Technology: Submerged Arc Welding, Gas Tungsten Arc Welding, Plasma Transferred Arc, Laser Cladding End Use Industry: Power Generation, Petrochemical, Mining Equipment, Maritime Engineering Application: Corrosion Resistance, Wear Protection, High Temperature Service, Pressure Containment |
| Companies Covered | Proclad, Eisenbau Kramer (EBK), Butting Group, Cladtek Holdings, EEW Group, The Japan Steel Works (JSW), Inox Tech, Xinxing Ductile, NobelClad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weld Overlay Process Clad Pipes Market Trends and Innovations
Automation in overlay deposition and shifting qualification protocols for hydrogen service are restructuring competitive capabilities across the clad pipe supply base.
Plasma transferred arc welding is decentralizing precision bore cladding from centralized job shops to integrated pipe mills. Offshore drilling contractors in the North Sea are adopting PTA-clad downhole tubulars for sour gas wells. This technology is decentralizing repair and maintenance workflows toward field-service deposition units.
REACH chemical restrictions on hexavalent chromium in welding consumables are forcing European overlay fabricators to reformulate flux chemistry. The European Chemicals Agency's 2024 sunset date for certain chromium compounds is accelerating R&D spending on tungsten-based alternatives. Subsea contractors in Norway are qualifying chromium-free overlay systems ahead of NORSOK M-630 revision cycles.
Integrated procurement frameworks are consolidating vendor panels for major EPC contractors. Engineering-procurement-construction firms in the United States are reducing qualified clad pipe suppliers from twelve to four per project, favoring vertically integrated mills with captive overlay capacity. This consolidation is most visible in Gulf of Mexico deepwater developments where Shell and Chevron have standardized on single-source clad pipe agreements.
Weld Overlay Process Clad Pipes Market Segmentation
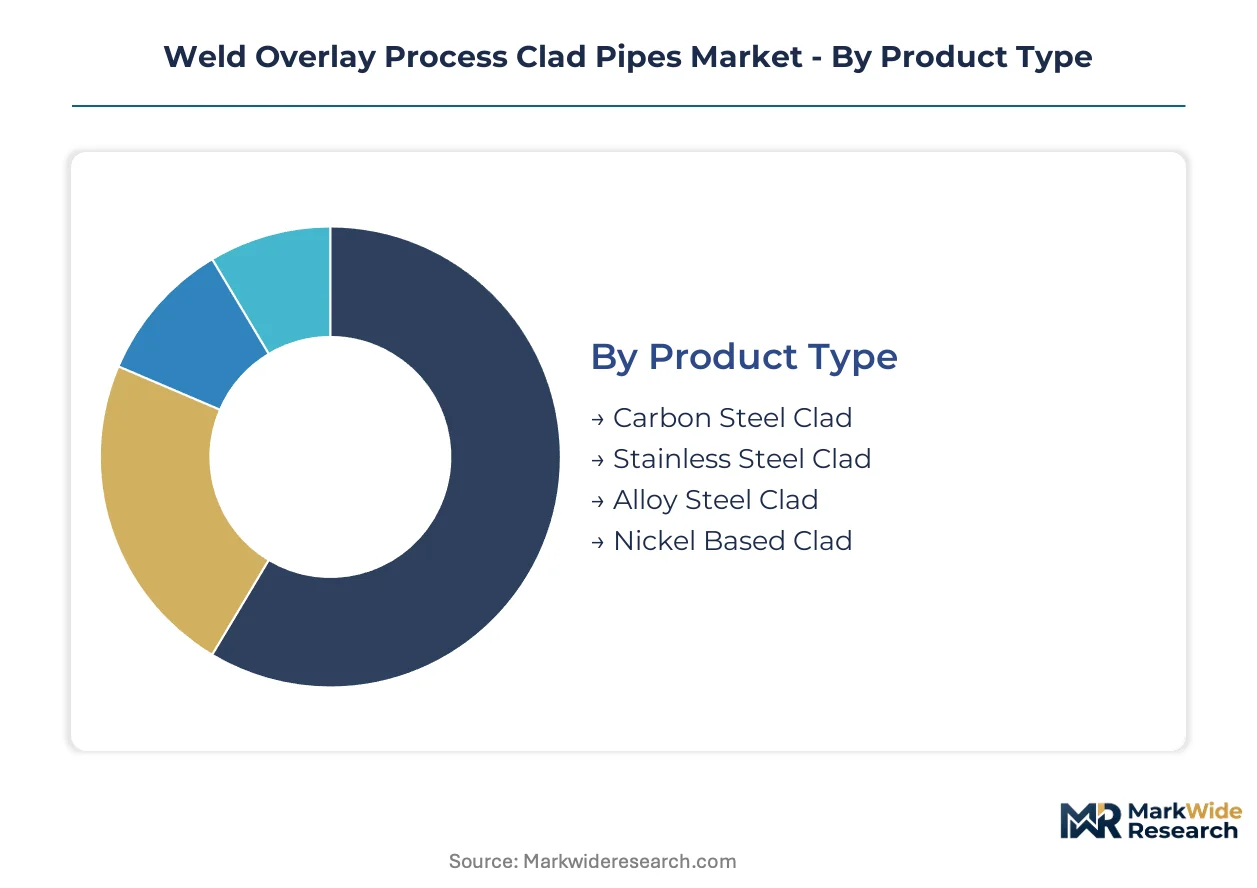
Weld overlay process clad pipes serve distinct technical requirements across hydrocarbon, power, and marine sectors. Procurement decisions hinge on corrosion chemistry, pressure ratings, and welding technology compatibility with field conditions.
Product Type:
Material selection tracks the severity of process fluid chemistry and capital cost constraints facing project engineers.
- Carbon Steel Clad:Combines structural carbon steel exteriors with thin corrosion-resistant alloy layers, typically 3–6 mm thick. Offshore platform fabricators in the Gulf of Mexico specify this configuration for flowlines where CO2 partial pressures remain below 2,000 psi and cost control dominates procurement.
- Nickel Based Clad:Inconel 625 and Alloy 825 overlays deliver hydrogen sulfide resistance for sour gas service. North Sea operators mandate nickel-based clad for subsea tiebacks where H2S partial pressures exceed 0.05 psi, accepting 40–60% cost premiums over solid CRA alternatives.
- Stainless Steel Clad:316L and 304L overlays address moderate corrosive environments in refinery service.
- Alloy Steel Clad:Chrome-molybdenum substrates with specialized overlays target high-temperature boiler applications.
Carbon steel clad leads on scale; nickel based clad leads on momentum.
Welding Technology:
Deposition method determines defect rates, overlay thickness precision, and qualification timelines for API 5LD certification.
- Plasma Transferred Arc:Concentrated arc energy achieves 1–3 mm precision bore cladding with dilution rates below 5%. Downhole tubular suppliers serving North Sea drilling contractors are automating PTA cells to compress cycle times for sour gas completion strings.
- Submerged Arc Welding:High-deposition-rate process dominates large-diameter line pipe overlay, achieving 3–12 mm thicknesses in single passes. European and Asian fabricators cluster SAW capacity for pipeline projects, though supply concentration creates bottleneck risk for urgent timelines.
- Gas Tungsten Arc Welding:Manual precision process for repair and small-batch overlay work.
- Laser Cladding:Emerging technology for minimal-dilution precision applications in aerospace and nuclear transfer.
Submerged arc welding anchors volume; plasma transferred arc is climbing the fastest.
End Use Industry:
Industry verticals impose distinct qualification protocols and performance benchmarks on overlay suppliers.
- Petrochemical:Refinery expansion programs in the United States and China drive demand for corrosion-resistant piping in hydrocracker and hydrotreater units. API 5LD certification with bond shear strengths above 140 MPa filters supplier panels for major EPC frameworks.
- Power Generation:Ultra-supercritical coal and combined-cycle gas turbine plants require high-temperature alloy overlays for steam piping. Chinese utility procurement under GB/T 28897 standards is accelerating qualification of domestic overlay fabricators.
- Maritime Engineering:Offshore platform risers and flowlines specify heavy-wall clad pipe for seawater corrosion resistance.
- Mining Equipment:Slurry pipeline systems utilize wear-resistant overlays for ore transport applications.
Petrochemical commands revenue concentration; power generation shows steepest expansion trajectory.
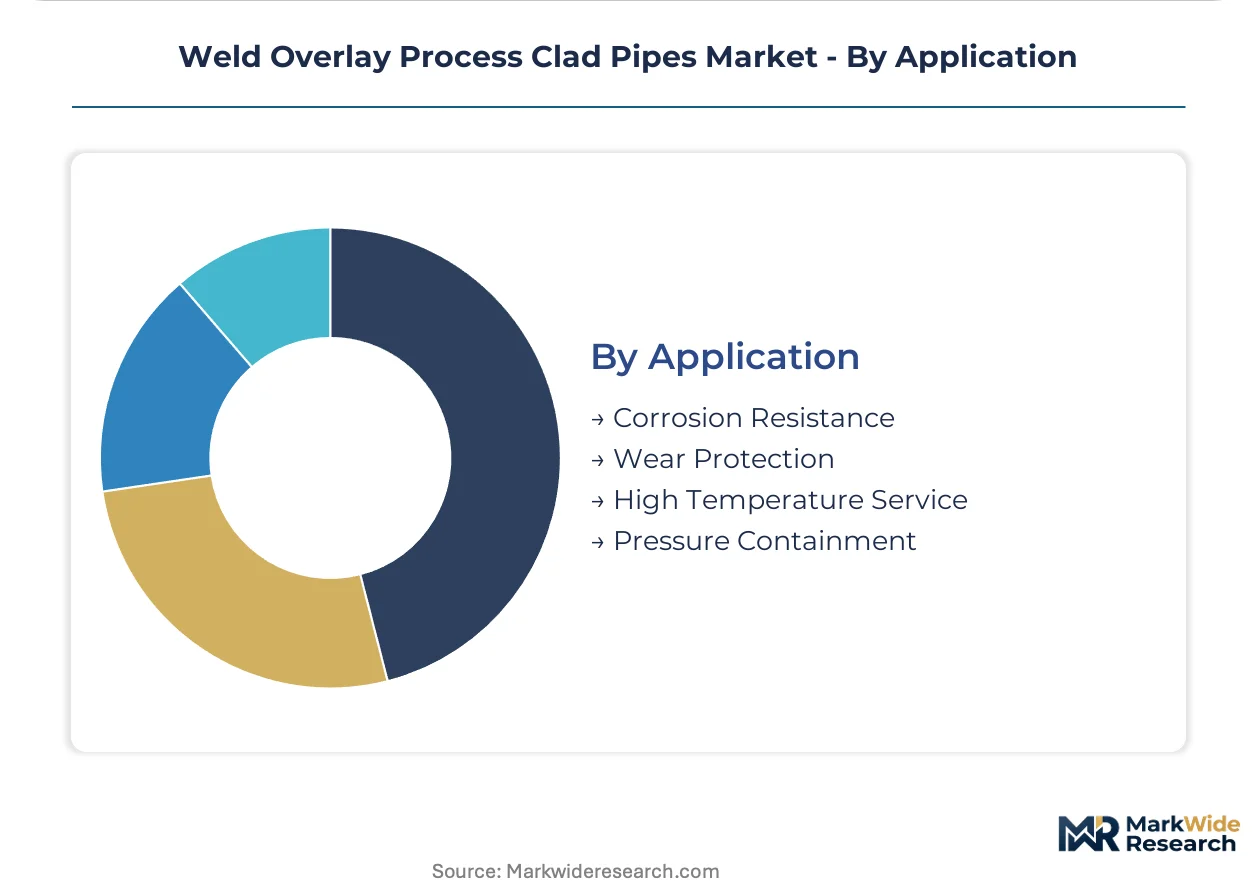
Application:
Functional requirement dictates overlay chemistry, thickness specification, and inspection protocols.
- Corrosion Resistance:Primary application spanning CO2-rich production fluids and sour gas environments. Nickel-based and stainless steel overlays metallurgically bonded to carbon steel substrates contain hydrocarbons at 40–60% of solid CRA installed cost.
- High Temperature Service:Chrome-carbide and nickel-based overlays maintain mechanical integrity above 500°C in boiler and furnace applications. Power plant engineers specify these configurations for steam circuits where thermal cycling resistance is mandatory.
- Wear Protection:Tungsten carbide and ceramic-metal composite overlays extend service life in slurry handling.
- Pressure Containment:Thick-wall overlay designs for subsea wellheads and Christmas tree components.
Corrosion resistance dominates installed base; high temperature service is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf of Mexico offshore fabricators drive procurement volumes for corrosion-resistant clad piping, with deepwater tieback projects displacing solid CRA alternatives in high-pressure CO2 service.
United States
Shell and Chevron have standardized single-source clad pipe agreements for Gulf of Mexico deepwater developments. API 5LD certification requirements filter supplier panels for major EPC frameworks. Houston anchors the procurement ecosystem, with engineering firms consolidating vendor lists from twelve to four qualified fabricators per project.
Norway
Statoil and Aker Solutions frameworks accelerate qualification spending by suppliers targeting North Sea subsea applications. NORSOK M-630 mandates supplementary qualification testing beyond API 5LD baseline requirements. Stavanger clusters specialized heavy-wall clad pipe production for platform risers and flowlines.
China
Offshore platform construction in Bohai Bay and South China Sea expands under GB/T 28897 domestic standards. Refinery expansion programs accelerate qualification of domestic overlay fabricators for hydrocracker units. Dalian and Shanghai house integrated mills with captive overlay capacity serving state-owned energy contractors.
Germany
REACH chemical restrictions on hexavalent chromium force overlay fabricators to reformulate flux chemistry ahead of 2024 sunset dates. Tungsten-based alternative R&D concentrates in industrial welding centers. Düsseldorf-area specialists qualify chromium-free overlay systems ahead of NORSOK M-630 revision cycles.
Japan
LNG service applications drive demand for thick-wall transition joints requiring advanced hot-rolling bond technology. METI standards align with offshore platform construction specifications in regional export markets. Yokohama-based engineering groups coordinate qualification protocols for nickel-based clad configurations in sour gas service.
Weld Overlay Process Clad Pipes Market Competitive Landscape
Global majors compete with regional champions across certification depth and captive overlay capacity. The supply base concentrates among vertically integrated pipe mills and specialized job shops with API 5LD qualification records. Three archetypes dominate: integrated steelworks with in-house deposition cells, independent overlay specialists serving project-specific contracts, and EPC-affiliated fabricators tied to major energy frameworks. Capacity expansion and automated deposition licensing represent the primary competitive vectors.
Within the integrated mill tier, The Japan Steel Works and Xinxing Ductile exemplify scale-driven positioning through captive metallurgical bond technology. Among European specialists, Eisenbau Kramer and Butting Group occupy positions anchored in heavy-wall production for offshore service. Proclad represents the multi-regional archetype with manufacturing footprints spanning Europe and Asia-Pacific to sustain project delivery timelines for major energy contractors.
| Leading Market Players |
|---|
| Proclad |
| Eisenbau Kramer (EBK) |
| Butting Group |
| Cladtek Holdings |
| EEW Group |
| The Japan Steel Works (JSW) |
| Inox Tech |
| Xinxing Ductile |
| NobelClad |
| Others |
Pricing and Supply Chain Analysis
Shell and Chevron's single-source clad pipe agreements for Gulf of Mexico deepwater developments are compressing supplier margins and forcing overlay specialists toward automated deposition cells to defend project economics. API 5LD certification thresholds above 140 MPa bond shear strength filter marginal fabricators, concentrating procurement leverage among vertically integrated mills with captive overlay capacity.
Pricing Analysis
Inconel 625 and Alloy 625 overlay wire pricing swings pass through directly to nickel-based clad configurations, compressing margin predictability for job shops lacking long-term offtake agreements with specialty metal producers. Three-tier pricing structure across premium, standard, and economy levels separates API 5LD-certified heavy-wall production for subsea service from uncertified line pipe overlay and repair-grade manual deposition. Cost compression in standard-tier SAW line pipe is intensifying because European and Asian fabricators cluster capacity, while premium-tier PTA-clad downhole tubulars retain pricing power through welder certification scarcity. Midstream infrastructure buyers below 1,000 psi service show highest price sensitivity, driving substitution toward seamless stainless pipe.
Supply Chain Analysis
Single-source vulnerability sits with European and Asian submerged arc welding fabricators for large-diameter line pipe overlay, where urgent project timelines face bottleneck risk from concentrated capacity. Raw material dependencies draw from nickel alloy wire producers in Germany, specialty flux formulators facing REACH chemical restrictions, and structural carbon steel substrate mills in China and Japan. Tariff exposure on specialty welding consumables imported into the United States threatens margin stability for domestic overlay job shops. Distribution runs through engineering-procurement-construction contractor vendor panels, with major frameworks reducing qualified suppliers from twelve to four per project.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where API 5LD tightening and hydrogen embrittlement protocol evolution are shifting procurement toward certified premium specifications that filter marginal suppliers.
For Market Incumbents: Deploy automated plasma transferred arc deposition cells to compress cycle times and defend margin position against PTA welder certification scarcity. Backward integration into specialty nickel alloy wire supply through long-term offtake agreements with Inconel producers anchors input cost predictability. Investment in NORSOK M-630 qualification ahead of revision cycles captures Statoil and Aker Solutions framework positions before audit timelines extend further. For New Entrants and Emerging Players: Begin with Bohai Bay platform construction under GB/T 28897 standards, where domestic certification pathways create procurement windows for qualified overlay fabricators. China's refinery expansion programs for hydrocracker units represent the most penetrable segment, with state-owned energy contractors seeking to reduce import dependency. A joint venture with established European PTA technology licensors accelerates qualification timelines versus greenfield capability buildout. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier overlay specialists holding API 5LD records and untapped automated deposition licensing potential. Five-to-ten year viability hinges on hydrogen pipeline repurposing qualification completion, where early movers in nickel-based clad hydrogen embrittlement testing capture European transmission operator procurement. The signal to watch is NORSOK M-630 revision adoption velocity, which will accelerate qualification spending and consolidate vendor panels further.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Deposition Cell Deployment | PTA robotic systems reduce labor content and cycle time for North Sea sour gas completion strings. |
| Backward Integration into Nickel Alloy Supply | Long-term offtake agreements with Inconel producers compress margin volatility from wire pricing swings. |
| NORSOK M-630 Pre-Qualification Investment | Early compliance ahead of revision cycles secures Statoil framework positions before audit compression intensifies. |
| Hydrogen Service Qualification Program | Nickel-based clad testing against evolving embrittlement protocols opens European transmission operator procurement. |
| GB/T 28897 Domestic Certification Pathway | China offshore platform construction creates procurement windows for qualified fabricators with local credentials. |
Research Methodology
Multiple input streams — executive interviews with overlay fabrication plant managers, procurement leads at major EPC contractors, and technical R&D directors at welding consumable suppliers — were reconciled against secondary validation from API certification databases, NORSOK M-630 qualification records, and customs trade data on nickel alloy wire imports. Bottom-up project pipeline analysis across Gulf of Mexico, North Sea, and China offshore developments was cross-referenced with top-down capacity assessments at integrated mills and independent job shops.
Historical capacity utilization and certification timeline patterns were cross-referenced against panel input from EPC contractor procurement officers to anchor growth projections across the analysis window. Segmentation modeling tracked material configuration, welding technology, end-use industry vertical, and regional regulatory framework. CAGRs were derived from project sanctioning velocity and qualification spending trajectories, with hydrogen pipeline repurposing assumptions stress-tested against European transmission operator disclosure patterns.
Caveats apply where nickel alloy input volatility, REACH chemical restriction enforcement timelines, or hydrogen embrittlement protocol finalization could materially shift the outlook. Forecasts reflect documented assumptions about project sanctioning rates and certification audit duration trends. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Drum Funnel Market
Pipes and Tubes
Composite Pipes Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
UAE PVC Pipes Market
Pipes and Tubes
Cold Drawn Seamless (CDS) Steel Pipes Market
Pipes and Tubes
Thermoplastic Pipe Market
Pipes and Tubes
GCC PVC Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
Metal Pipe Market
Pipes and Tubes
Global Polyolefin Pipes Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Industrial Tubes Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
India Process Piping Market
Pipes and Tubes
Saudi Arabia PVC Pipes Market