
 Europe Copper Pipes and Tubes Market | 2026-2036
Europe Copper Pipes and Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Copper Pipes and Tubes Market Intelligence
Subscription-based maintenance contracts for HVAC infrastructure is hardening how copper pipe and tube suppliers monetize long-term customer relationships. KME Group S.p.A. leverages vertical integration from smelting to finished tubing to control alloy consistency across European project specifications. Wieland Group sustains R&D intensity in low-lead and antimicrobial copper alloys that meet evolving potable water standards. Aurubis AG anchors its position through captive refining capacity and scrap recycling loops that buffer raw material volatility.
Copper pipes and tubes are hollow cylindrical conductors fabricated from copper or copper alloys, typically manufactured through extrusion, drawing, or welding processes with outer diameters ranging from fractions of a millimeter to over 400 millimeters, serving primarily as conduits for fluids, gases, and thermal energy in built environments and industrial systems. Seamless tubing dominates margin pools in high-pressure refrigeration and precision chemical processing applications where joint integrity failures carry catastrophic cost. Welded product lines compete on throughput economics in plumbing and standard HVAC installations where pressure ratings remain modest. The small diameter segment leads volume in residential water supply and compact refrigeration circuits across Southern Europe's dense housing stock.
REACH compliance and the EU F-Gas Regulation shape material certification requirements and refrigerant-compatible piping specifications that manufacturers must satisfy for market access. CE marking under the Construction Products Regulation mandates traceable mechanical and chemical performance declarations for copper installations in permanent building works. Germany's KBA and France's ANSM enforce sector-specific pressure equipment standards that diverge modestly from harmonized EN norms. Stakeholders must monitor how the EU Green Deal's building renovation wave redirects specification priorities toward thermal efficiency and lifecycle recyclability.
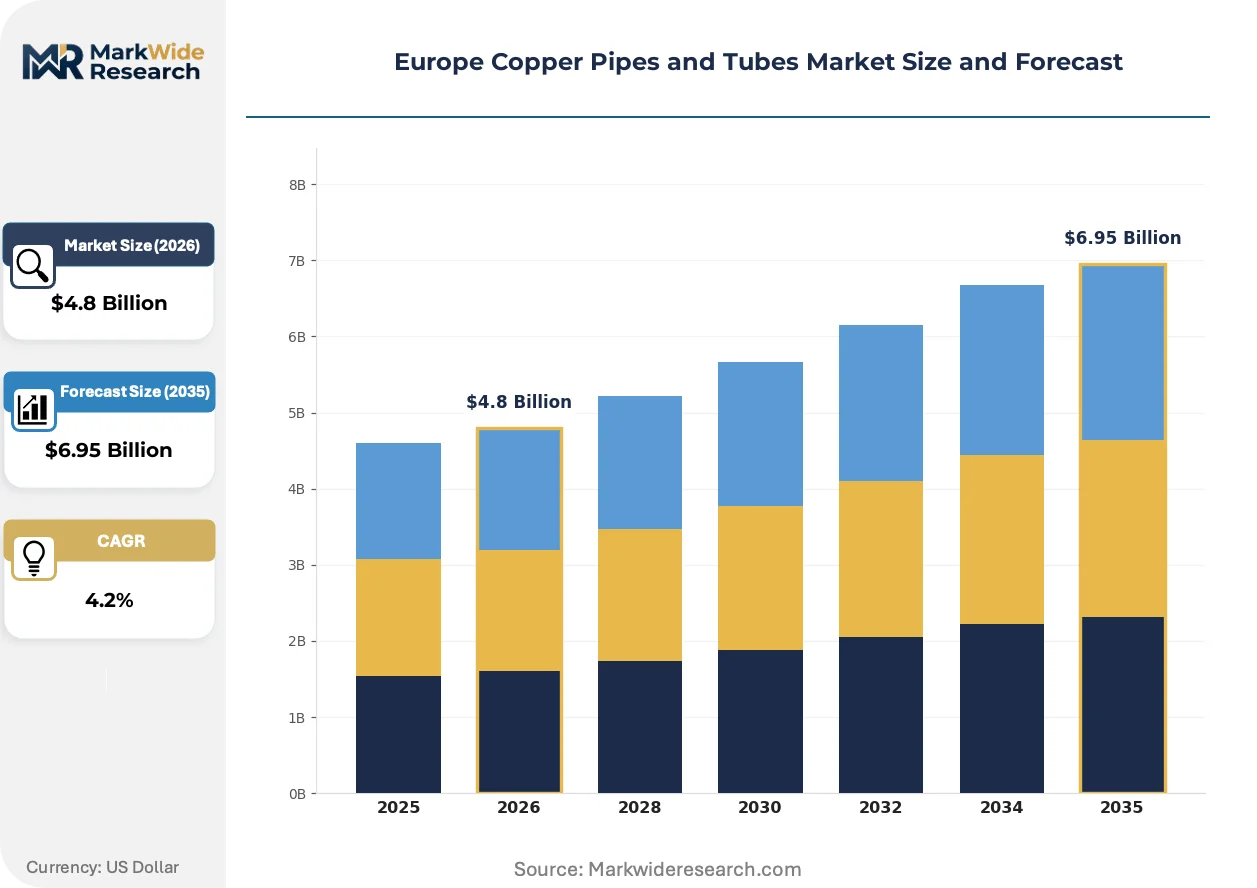
Market Dynamics
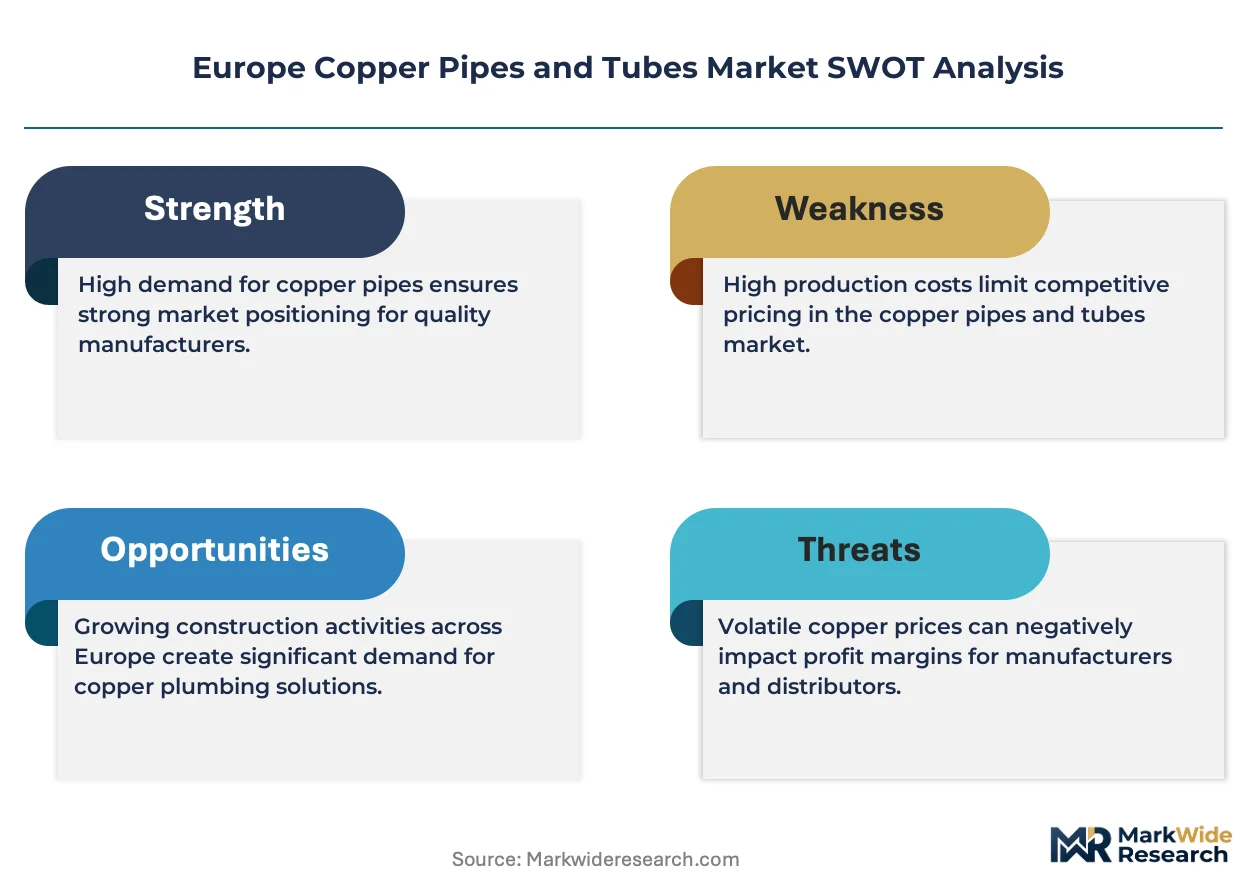
The EU F-Gas Regulation is compressing refrigerant transition timelines across European HVAC systems, forcing wholesale specification changes in copper tubing alloys and wall thicknesses to accommodate lower-GWP alternatives. This regulatory pressure is synchronizing replacement cycles with building renovation waves in Germany and France, creating concentrated demand pulses that reshape supplier capacity planning.
Growth Catalysts
- REACH compliance mandates:Chemical safety declarations under ECHA protocols are locking in copper purity standards for potable water applications, disqualifying non-compliant imports from Eastern European supply chains.
- District heating networks:Municipal heat distribution projects in Denmark and Sweden are specifying seamless copper tubing for corrosion resistance in pressurized hot water loops.
- HVAC retrofit acceleration:Building energy renovation subsidies in France are shortening replacement cycles for climate system piping by four to seven years.
Market Restraints
- Scrap copper volatility:Aurubis AG and KME Group S.p.A. depend on secondary raw material flows that swing with LME price cycles, compressing margin predictability.
- Cross-linked polyethylene substitution:PEX tubing is capturing residential plumbing share in Southern Europe where pressure ratings permit polymer alternatives.
- CE marking complexity:Construction Products Regulation conformity assessment delays are extending time-to-market for new alloy formulations by eight to fourteen months.
Strategic Opportunities
- Poland's building stock:Underpenetrated district heating infrastructure in Warsaw and Kraków corridors offers greenfield specification opportunities for seamless tubing.
- Antimicrobial alloy certification:Healthcare facility construction in Germany is creating premium demand for copper-zinc formulations meeting specific bacterial reduction protocols.
- Digital procurement platforms:HVAC contractors in the Netherlands are migrating to integrated e-procurement systems that favor suppliers with real-time inventory visibility.
Industry Challenges
- Precision drawing technician shortage:Germany's industrial corridor faces acute gaps in skilled operators for thin-wall refrigeration tubing production.
- Multi-standard harmonization:Divergent pressure equipment norms between Germany's KBA and France's ANSM force dual certification runs for cross-border projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Copper Pipes and Tubes Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless, Welded, Brazed, Fittings End User: Construction, HVAC, Plumbing, Industrial Application: Water Supply, Refrigeration, Heating, Chemical Processing Size: Small Diameter, Medium Diameter, Large Diameter, Custom Sizes |
| Companies Covered | KME Group S.p.A., Wieland Group, Aurubis AG, Mueller Industries Inc., MM Kembla, Luvata, Cerro Flow Products LLC, Kobe Steel, Cambridge-Lee Industries LLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Copper Pipes and Tubes Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry mandates are converging to redefine copper alloy specifications across European climate and water systems. Suppliers are racing to certify formulations that satisfy simultaneously tightening purity standards and refrigerant compatibility requirements.
Low-lead dezincification-resistant alloys are rewriting specification sheets for potable water infrastructure. Dutch and Belgian municipal water authorities are mandating these formulations for new connections at accelerating rates. The technology is compressing market share for traditional brass fittings in favor of engineered copper alternatives that meet stricter leaching thresholds.
REACH Annex XVII restrictions on lead content are forcing foundry process redesigns across European tubing manufacturers. The regulation is eliminating legacy casting methods that relied on lead-bearing brazing alloys. German plumbing wholesalers are now stocking exclusively lead-free jointing materials, shifting inventory composition toward certified low-lead SKUs.
Building renovation aggregators are consolidating HVAC contractor purchasing power in France and Germany. These platforms are disintermediating traditional distributor relationships by offering project-level pricing and logistics coordination. The channel shift is most visible in Paris and Berlin metropolitan zones where retrofit project density supports platform economics.
Europe Copper Pipes and Tubes Market Segmentation
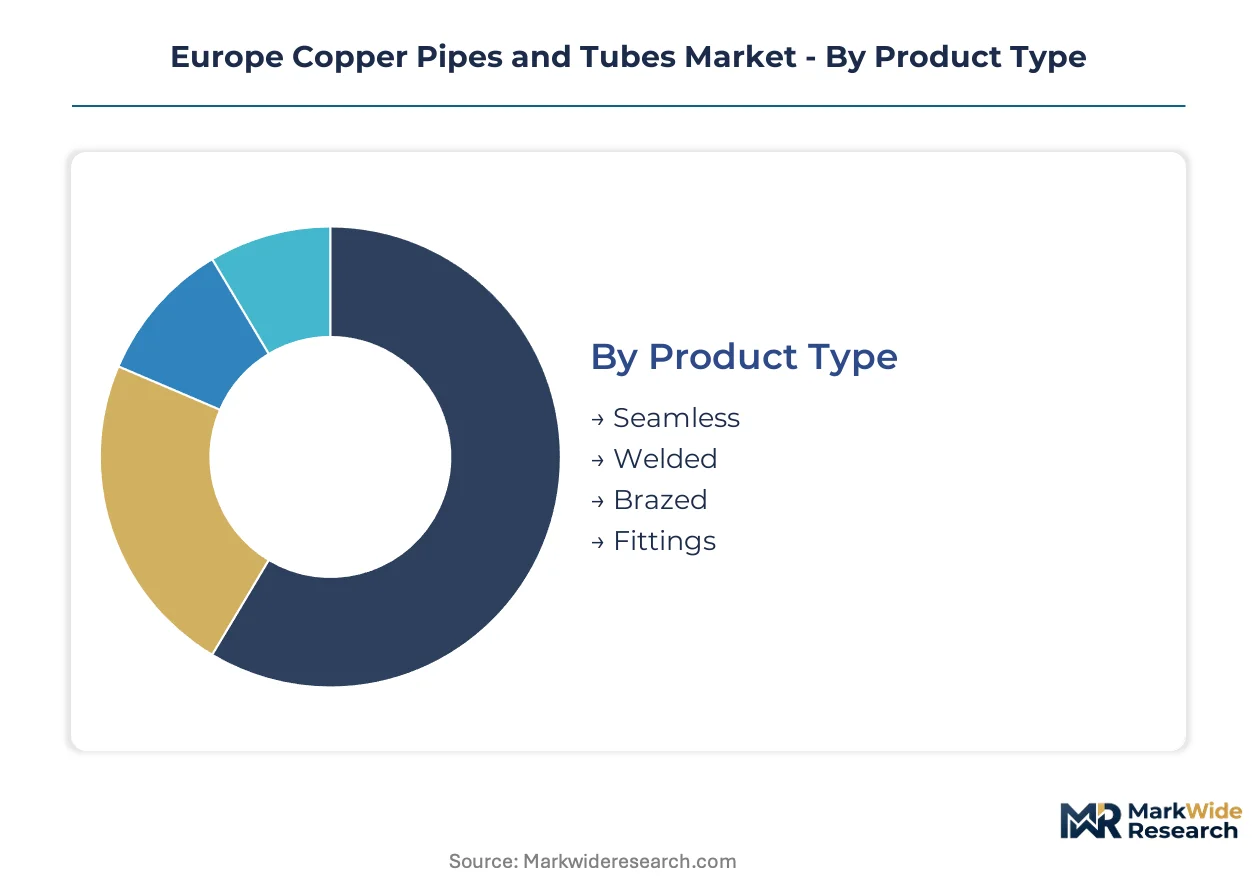
Copper pipe and tube specifications diverge sharply across European end-uses, with pressure ratings, alloy purity, and joint integrity requirements dictating product selection. Segmentation discipline separates commodity plumbing volumes from premium refrigeration margins, enabling suppliers to align capacity with profit pool concentration.
Product Type:
Cost tier separates high-performance seamless tubing from welded alternatives competing on throughput economics.
- Seamless:Manufactured through extrusion and precision drawing without longitudinal welds, delivering uniform grain structure for high-pressure containment. Germany's chemical processing corridor and Denmark's district heating networks specify seamless exclusively for corrosion resistance in pressurized hot water loops.
- Welded:Formed from strip stock with longitudinal seam fusion, offering dimensional flexibility at lower unit cost. France's HVAC retrofit wave absorbs welded volumes for standard climate system replacements where pressure ratings remain modest.
- Brazed:Pre-assembled joint configurations reduce field labor for plumbing contractors.
- Fittings:Connection hardware completes system integrity in permanent building works.
Volume sits with welded product lines; growth tilts toward seamless specifications as industrial applications harden purity requirements.
End User:
Application maturity dictates whether buyers prioritize certification depth or procurement efficiency.
- Construction:Permanent building works demand CE-marked products with traceable mechanical declarations under the Construction Products Regulation. France's building renovation aggregators are consolidating contractor purchasing power, shifting procurement toward platform-coordinated logistics.
- HVAC:Climate system manufacturers face compressed refrigerant transition timelines under the EU F-Gas Regulation, forcing alloy specification changes for lower-GWP compatibility. Germany's KBA enforces pressure equipment standards that diverge modestly from harmonized EN norms, requiring dual certification for cross-border projects.
- Plumbing:Residential water supply concentrates in Southern Europe's dense housing stock.
- Industrial:Chemical processing sustains above-average offtake in Germany's industrial corridor.
Construction commands the largest volume position; HVAC exhibits the steepest expansion trajectory as retrofit cycles synchronize with regulatory deadlines.
Application:
Fluid chemistry determines whether copper purity or wall thickness takes priority in specification negotiations.
- Water Supply:Potable infrastructure mandates REACH-compliant low-lead alloys as Dutch and Belgian municipal authorities accelerate dezincification-resistant formulation adoption. The technology is compressing market share for traditional brass fittings in favor of engineered copper alternatives that meet stricter leaching thresholds.
- Refrigeration:Precision tubing for compact circuits serves Southern Europe's residential cooling density and commercial cold chain expansion. REACH Annex XVII restrictions on lead content are eliminating legacy casting methods that relied on lead-bearing brazing alloys.
- Heating:District energy distribution favors seamless corrosion resistance.
- Chemical Processing:High-purity alloys prevent contamination in pharmaceutical and specialty chemical flows.
Water supply dominates installed base; refrigeration is climbing the fastest as refrigerant transitions force piping replacement.
Size:
Volume scale and customization depth separate commodity throughput from engineered solutions.
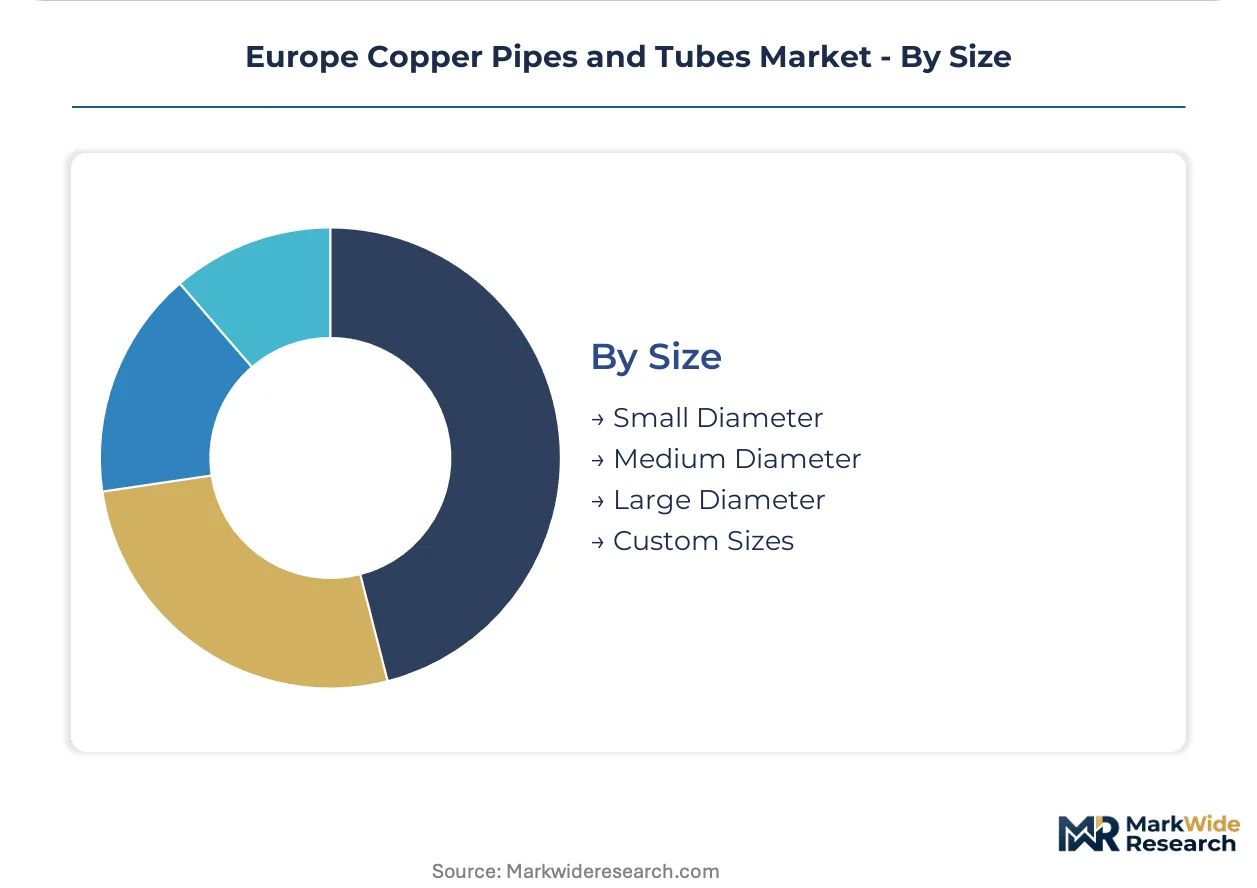
- Small Diameter:Fractions of a millimeter to approximately 25 millimeter outer diameter, dominating residential water supply and compact refrigeration circuits across Southern Europe's dense housing stock. Precision drawing requirements create capability scarcity in Germany's industrial corridor.
- Medium Diameter:Standard HVAC and commercial plumbing specifications balance availability with pressure rating flexibility.
- Large Diameter:Industrial process piping and district heating trunk lines exceed 100 millimeter outer diameter, with Sweden and Denmark municipal projects specifying seamless construction for pressurized hot water integrity.
- Custom Sizes:Non-standard dimensions serve project-specific pressure equipment and architectural integration requirements.
Small diameter captures the highest shipment volumes; custom sizes are gaining share fastest as building renovation complexity increases specification fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's copper pipe and tube production concentrates in Germany's industrial corridor, while consumption spreads across renovation-heavy Western markets and emerging Eastern European infrastructure. This geographic split shapes supplier logistics and specification requirements.
Germany
District heating network expansions in Hamburg and Berlin drive seamless tubing demand for pressurized hot water distribution. KBA pressure equipment standards diverge from harmonized EN norms, forcing dual certification for cross-border projects. The North Rhine-Westphalia chemical processing corridor sustains above-average offtake for high-purity alloy specifications.
France
HVAC retrofit subsidies compress replacement cycles for climate system piping by four to seven years in metropolitan zones. ANSM enforces sector-specific pressure equipment standards that modestly diverge from German KBA requirements. Paris building renovation aggregators consolidate contractor purchasing power through platform-coordinated logistics.
Poland
Underpenetrated district heating infrastructure in Warsaw and Kraków corridors offers greenfield specification opportunities for seamless tubing. EU Green Deal building renovation wave redirects specification priorities toward thermal efficiency. Silesian industrial zones absorb welded product lines for standard commercial installations.
Sweden
Municipal heat distribution projects specify seamless copper tubing for corrosion resistance in pressurized hot water loops. REACH compliance mandates lock in copper purity standards for potable water infrastructure. Stockholm's dense urban housing stock drives small-diameter volume in residential water supply applications.
Netherlands
Dutch municipal water authorities mandate dezincification-resistant low-lead alloys for new connections at accelerating rates. ECHA chemical safety declarations disqualify non-compliant imports from Eastern European supply chains. Rotterdam and Amsterdam HVAC contractors migrate to integrated e-procurement systems favoring real-time inventory visibility.
Europe Copper Pipes and Tubes Market Key Industry Players
Capital-heavy producers compete with asset-light distributors across tiered margin pools. The structure consolidates around vertically integrated smelter-to-tube operators, regional fabricators with captive refining, and specialized alloy developers. Strategic archetypes include backward-integrated metal producers controlling scrap-to-finished-tube flows, precision drawing specialists serving refrigeration OEMs, and commodity distributors competing on logistics coverage. Dominant competitive moves center on captive recycling capacity expansion and antimicrobial alloy certification programs.
Among Germany-based metal producers, Aurubis AG anchors the backward-integrated archetype through captive refining and scrap recycling loops. KME Group S.p.A. exemplifies vertical control from smelting to finished tubing for alloy consistency. Wieland Group occupies a position within the precision alloy tier, representing specialists in low-lead and antimicrobial formulations for evolving potable water standards.
| Leading Market Players |
|---|
| KME Group S.p.A. |
| Wieland Group |
| Aurubis AG |
| Mueller Industries Inc. |
| MM Kembla |
| Luvata |
| Cerro Flow Products LLC |
| Kobe Steel |
| Cambridge-Lee Industries LLC |
| Others |
Cost & Logistics Intelligence
Precision drawing automation in thin-wall refrigeration tubing is compressing unit labor costs while concentrating production capability in Germany's industrial corridor. This technology shift simultaneously reshapes cost economics and supply concentration, rewarding capital-intensive operators with captive alloy development.
Pricing Analysis
Margin tightening in welded product lines reflects cross-linked polyethylene substitution pressure across Southern European residential plumbing. Three-tier pricing structure across premium seamless, standard welded, and economy brazed configurations dominates contract negotiations. Pricing pressure stems from scrap copper volatility tied to LME cycles. Residential contractors exhibit highest price sensitivity; chemical processors prioritize certification grade over unit cost.
Supply Chain Analysis
CE marking and REACH Annex XVII compliance requirements gate market access for non-European producers. Primary supply concentrates in Germany, Italy, and Poland. Raw material flows draw from Chilean cathode imports, German scrap recycling loops, and Zambian concentrate. Single-source vulnerability sits with Chilean mining concentration for virgin cathode. Distribution runs through national plumbing wholesalers and building renovation aggregator platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Copper Pipes and Tubes Market functions as a cost-of-compliance story where REACH Annex XVII lead-content restrictions erect barrier-to-entry moats for certified alloy developers.
For Market Incumbents: Deploy captive recycling capacity expansion to buffer raw material volatility from Aurubis AG and KME Group S.p.A. scrap dependency. Deepen antimicrobial alloy certification programs for German healthcare construction specifications. Cross-linked polyethylene substitution in Southern European plumbing threatens welded product margins; respond with low-lead dezincification-resistant formulation differentiation. For New Entrants and Emerging Players: Digital procurement platform integration offers the fastest route to contractor visibility in Netherlands and French metropolitan renovation zones. Target Poland's underpenetrated district heating infrastructure in Warsaw and Kraków corridors for greenfield seamless tubing specifications. Lead with real-time inventory API connectivity to disintermediate traditional distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with precision drawing specialists given EU F-Gas Regulation refrigerant transition timelines forcing alloy specification changes. Five-to-ten-year viability favors operators with backward integration into scrap recycling and captive refining. Monitor CE marking conformity assessment backlog duration as inflection indicator for new entrant timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Recycling | Captive secondary raw material flows buffer LME price volatility for margin stability. |
| Antimicrobial Alloy Certification Program | German healthcare facility construction mandates copper-zinc bacterial reduction protocols. |
| Digital Procurement Platform Partnership | Netherlands HVAC contractor migration favors suppliers with real-time inventory APIs. |
| Precision Drawing Automation Investment | Thin-wall refrigeration tubing capability scarcity concentrates in Germany's industrial corridor. |
| Dual Certification for Cross-Border Projects | Germany's KBA and France's ANSM divergent standards require parallel compliance runs. |
Research Approach
Trade association filings, ECHA chemical safety databases, and national customs records formed the secondary backbone for this analysis. Primary interviews with HVAC procurement managers, plumbing distributor category heads, copper alloy R&D directors, and building renovation platform operators validated secondary findings. Bottom-up and top-down triangulation reconciled shipment data with end-use consumption estimates.
Bottom-up modeling aggregated product-type, end-user, and application-level volume assumptions across the projection horizon. Segmentation dimensions included seamless versus welded construction, construction versus HVAC versus industrial end-uses, and small versus medium versus large diameter specifications. CAGRs derived from regression against historical replacement cycle data and regulatory deadline synchronization. Forecast inputs incorporated EU F-Gas Regulation refrigerant transition timelines and building renovation subsidy intensity.
The model holds under stable scrap copper price bands and consistent CE marking processing durations; deviation in LME volatility spikes or ECHA restriction expansions would shift trajectory. Forecasts reflect documented assumptions about replacement cycle compression and alloy specification evolution. A model refresh is warranted upon material change in EU Green Deal building renovation wave funding allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Pipe and Tube Cutters Market
Pipes and Tubes
India PVC Pipes Market
Pipes and Tubes
Stainless Steel Plumbing Pipes Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
Steel Tubes Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
UAE PVC Pipes Market
Pipes and Tubes
Tapping Sleeves Market
Pipes and Tubes
Global CPVC Pipes and Fittings Market
Pipes and Tubes
Fttx Pipes Market
Pipes and Tubes
Global Lance Tubes Market
Pipes and Tubes
Global Polyolefin Pipes Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
Multiflex Tubes Market
Pipes and Tubes
North America PVC Pipes Market
Pipes and Tubes
GRE Pipes Market