
 Ethylene Urea Market | 2026-2036
Ethylene Urea Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene Urea Market Foresight
Direct procurement channels between Chinese manufacturers and European agrochemical formulators is rewriting traditional distributor-heavy supply chains for ethylene urea. AlzChem Group leverages its Bavarian production base to sustain REACH-certified supply lines into German and French agricultural markets. BASF SE anchors demand through backward integration into coating resin applications, while Koch Industries competes on manufacturing scale across North American industrial accounts.
Ethylene urea, the condensation product of ethylenediamine and urea with the formula C3H8N4O, functions primarily as a slow-release nitrogen source in fertilizer formulations and as a chemical intermediate in resin synthesis. Powder grades dominate agricultural blending operations due to uniform dissolution kinetics, while pharmaceutical-grade crystals command premium positioning among API manufacturers. Liquid formulations are gaining traction in coating applications where metered dosing replaces solid handling.
EPA Office of Chemical Safety and Pollution Prevention monitors ethylene urea under TSCA Section 5 for new use notifications, while REACH Annex XVII restrictions govern residual formaldehyde in EU-sourced material. China's MEE enforces GB standards on wastewater discharge from urea condensation facilities, elevating compliance costs for domestic producers. Stakeholders must track evolving fertilizer additive classifications in major import jurisdictions to anticipate reformulation requirements.
Market Dynamics
REACH Annex XVII formaldehyde restrictions and China's GB wastewater discharge standards are compressing supplier margins while redirecting procurement toward certified European and domestic Chinese manufacturers with captive synthesis capabilities.
Growth Catalysts
- Controlled-Release Fertilizer Mandates:China's Ministry of Agriculture promotes slow-release nitrogen additives to reduce groundwater nitrate contamination, elevating ethylene urea incorporation rates in compound fertilizer formulations.
- REACH Certification Premium:ECHA-registered suppliers command preferential placement in German and French agrochemical procurement tenders, creating tiered supply access based on compliance documentation.
- Resin Synthesis Scale-Up:Coating manufacturers in automotive and industrial sectors expand ethylene urea consumption for amino resin crosslinking, particularly in high-solid and waterborne systems.
Market Restraints
- Ethylenediamine Cost Volatility:Crude oil and natural gas price swings transmit directly to ethylene urea production economics, compressing margins for non-integrated processors lacking captive ethylenediamine supply.
- Formaldehyde Substitution Pressure:Melamine-formaldehyde and glyoxal-based crosslinkers compete in coating applications, threatening volume displacement where emission regulations tighten further.
- Chinese Supply Concentration:Domestic Chinese manufacturers control approximately two-thirds of exportable powder-grade capacity, creating geographic risk concentration for European and North American formulators.
Strategic Opportunities
- Pharmaceutical-Grade Crystallization:API manufacturers in India and Eastern Europe seek high-purity ethylene urea for antiviral and antifungal synthesis, commanding 40-60% price premiums over agricultural grades.
- Liquid Formulation Channel Expansion:Metered dosing systems in industrial coating operations favor liquid ethylene urea delivery, opening direct tanker-supply relationships that bypass traditional distributor networks.
- EU Green Deal Fertilizer Incentives:Carbon intensity scoring for nitrogen fertilizers creates preference for domestically synthesized ethylene urea with verified lifecycle emissions documentation.
Industry Challenges
- Multi-Jurisdiction Registration Burden:Suppliers must maintain parallel TSCA Section 5 notifications, REACH dossiers, and China's MEE chemical inventory listings, extending product launch timelines.
- Analytical Method Harmonization:Discrepancies between EPA, ECHA, and GB testing protocols for residual formaldehyde and heavy metals create certification complexity for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene Urea Market |
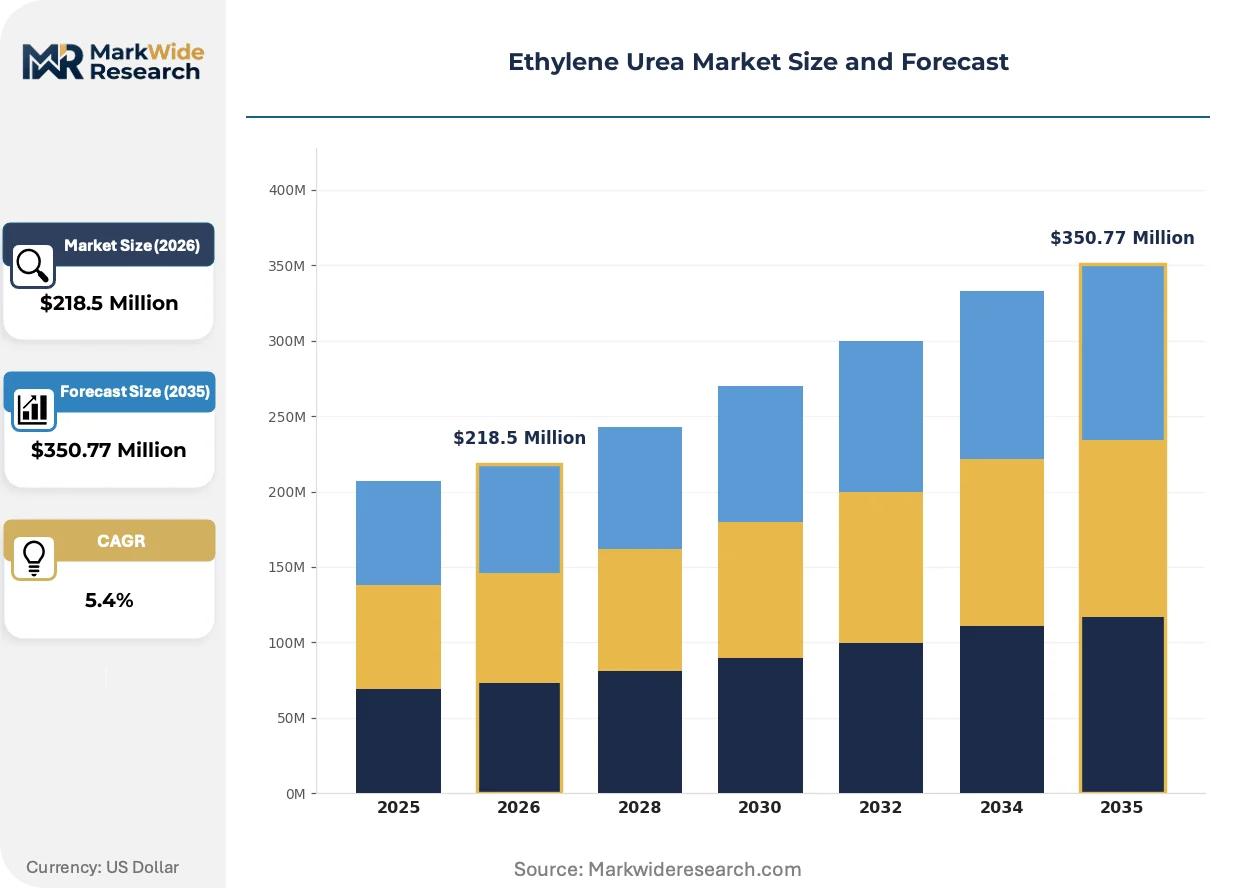
| Market Size in 2026 | $218.5 Million |
| Market Size in 2035 | $350.77 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Liquid, Crystals Application: Agriculture, Pharmaceuticals, Coatings, Adhesives End User: Chemical Manufacturers, Agrochemical Companies, Pharmaceutical Firms, Industrial Users Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | AlzChem Group, Hebei Kangzhuang, BASF SE, Suichang Limin, Jining JinYin Chemical, Koch Industries, Jiangsu Kolod Chemical, Zhuosheng Biotech, Shandong Ruixing Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene Urea Market Shifts & Advancements
Continuous condensation reactor technology is collapsing batch cycle times while regulatory data requirements for chemical intermediates intensify traceability investments across the value chain.
Membrane filtration systems for ethylene urea crystallization are collapsing solid-liquid separation energy requirements by eliminating traditional centrifugation stages. Agricultural blenders in the US Corn Belt and North China Plain adopt these systems to secure powder grades with tighter particle size distribution. The technology is collapsing capital barriers for mid-scale producers seeking pharmaceutical-grade certification.
REACH Annex XVII formaldehyde restrictions are tightening residual limits in EU-sourced ethylene urea, forcing suppliers to implement secondary purification stages or alternative condensation catalysts. German coating formulators now require certificates of analysis documenting formaldehyde content below detection thresholds. Agricultural distributors in France and Italy are screening suppliers based on ECHA registration completeness rather than price alone.
Direct manufacturer-procurement relationships are displacing multi-tier distributor networks for volume agricultural accounts. Chinese producers now operate European stocking locations near Rotterdam and Hamburg to bypass traditional chemical trading houses. This channel compression is most visible in German compound fertilizer operations, where formulators negotiate annual supply agreements with named production facilities rather than trading companies.
Ethylene Urea Market Segmentation
Ethylene urea's dual role as a nitrogen source and chemical intermediate fragments demand across incompatible specification tiers. Agricultural buyers prioritize dissolution kinetics and particle uniformity, while pharmaceutical and coating applications impose purity thresholds that eliminate cross-grade substitution.
Product Type:
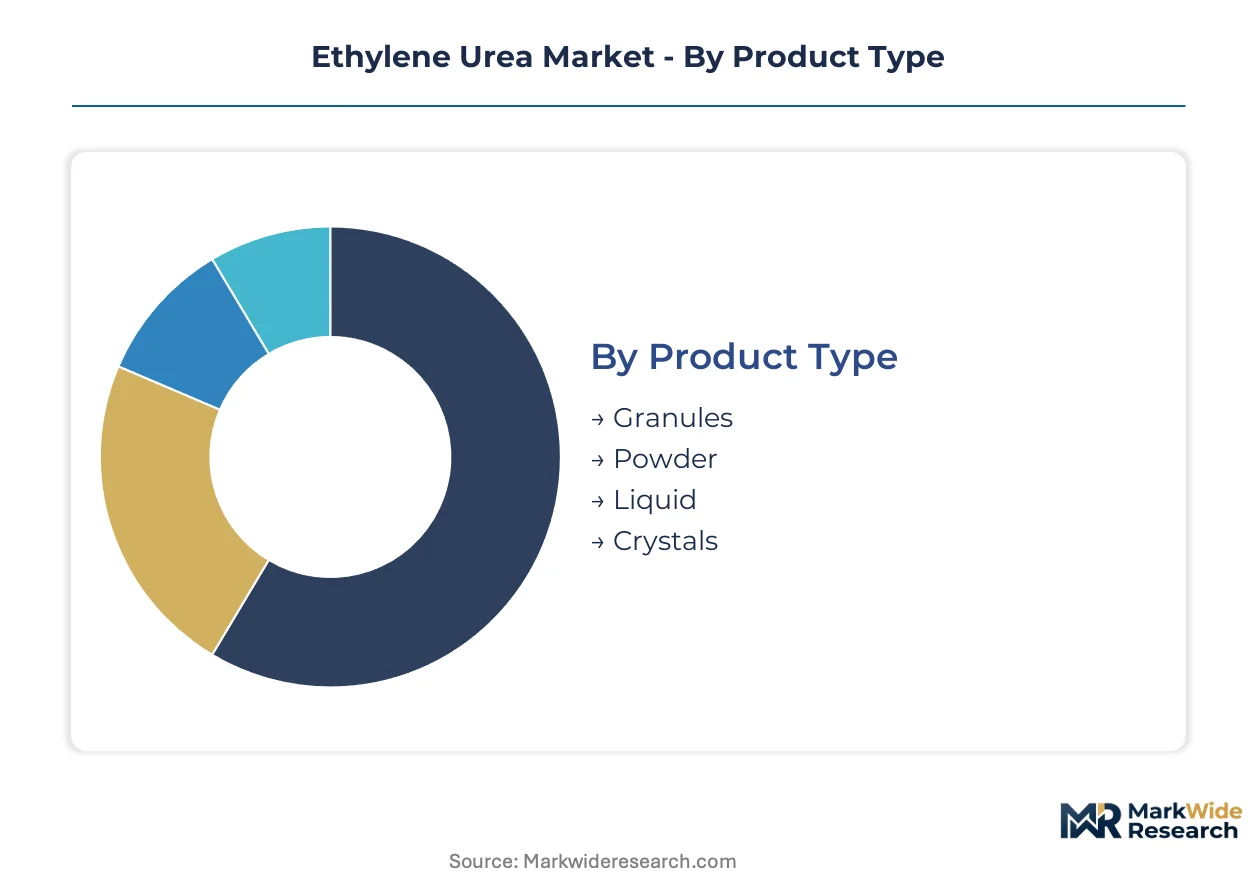
Mature powder and granule formats dominate agricultural procurement, while liquid and crystalline grades emerge from coating automation and API synthesis requirements.
- Granules:Spherodized particles with controlled dissolution profiles suit mechanical spreading equipment across the US Corn Belt and North China Plain. Fertilizer blenders specify 2-4mm diameter ranges to prevent segregation during pneumatic conveying. Granule demand concentrates in compound fertilizer operations where uniform nutrient release reduces groundwater leaching.
- Powder:Fine-milled material with sub-150 micron particle size distribution enables rapid dissolution in suspension concentrates and soluble fertilizer formulations. Powder grades retain volume leadership in agricultural blending due to lower production costs and established handling infrastructure.
- Liquid:Aqueous solutions eliminate dust exposure and enable metered dosing in automated coating lines. Metered dosing systems in automotive and industrial coating operations favor liquid delivery, opening direct tanker-supply relationships that bypass traditional distributor networks.
- Crystals:High-purity solid forms meeting pharmacopeial specifications for residual solvents and heavy metals serve antiviral and antifungal API synthesis.
Powder retains volume leadership; liquid holds the steepest expansion curve.
Application:
Application demand stratifies across cost tiers, with bulk agriculture at the base and pharmaceutical synthesis commanding premium positioning.
- Agriculture:Controlled-release nitrogen source in compound fertilizers, urea-formaldehyde resins, and soil amendment products. China's Ministry of Agriculture mandates slow-release additive incorporation to reduce nitrate contamination, elevating ethylene urea specification requirements for domestic compounders.
- Pharmaceuticals:Chemical intermediate for antiviral, antifungal, and cardiovascular active pharmaceutical ingredients requiring sub-ppm residual formaldehyde thresholds. API manufacturers in India and Eastern Europe seek high-purity material commanding substantial premiums over agricultural grades.
- Coatings:Amino resin crosslinking agent for automotive, industrial, and wood coating systems. High-solid and waterborne formulation trends expand consumption as manufacturers phase out solvent-based alternatives.
- Adhesives:Modifier for urea-formaldehyde and melamine-urea adhesive systems in wood panel manufacturing.
Agriculture retains volume leadership; pharmaceuticals holds the steepest expansion curve.
End User:
Customer type determines procurement sophistication, with chemical manufacturers and pharmaceutical firms operating direct sourcing models while agrochemical companies maintain distributor relationships.
- Chemical Manufacturers:Integrated producers consuming ethylene urea as captive intermediate for resin, adhesive, and specialty chemical synthesis. Backward integration into ethylenediamine supply secures margin protection against feedstock volatility.
- Agrochemical Companies:Formulators of compound fertilizers and controlled-release nutrient products. Direct procurement channels between Chinese manufacturers and European formulators are rewriting traditional distributor-heavy supply chains.
- Pharmaceutical Firms:API and intermediate manufacturers requiring REACH-registered or equivalent certified supply with complete CoA documentation.
- Industrial Users:Coating, adhesive, and textile processing operations with formulation-specific purity requirements.
Agrochemical companies retain volume leadership; pharmaceutical firms holds the steepest expansion curve.
Distribution Channel:
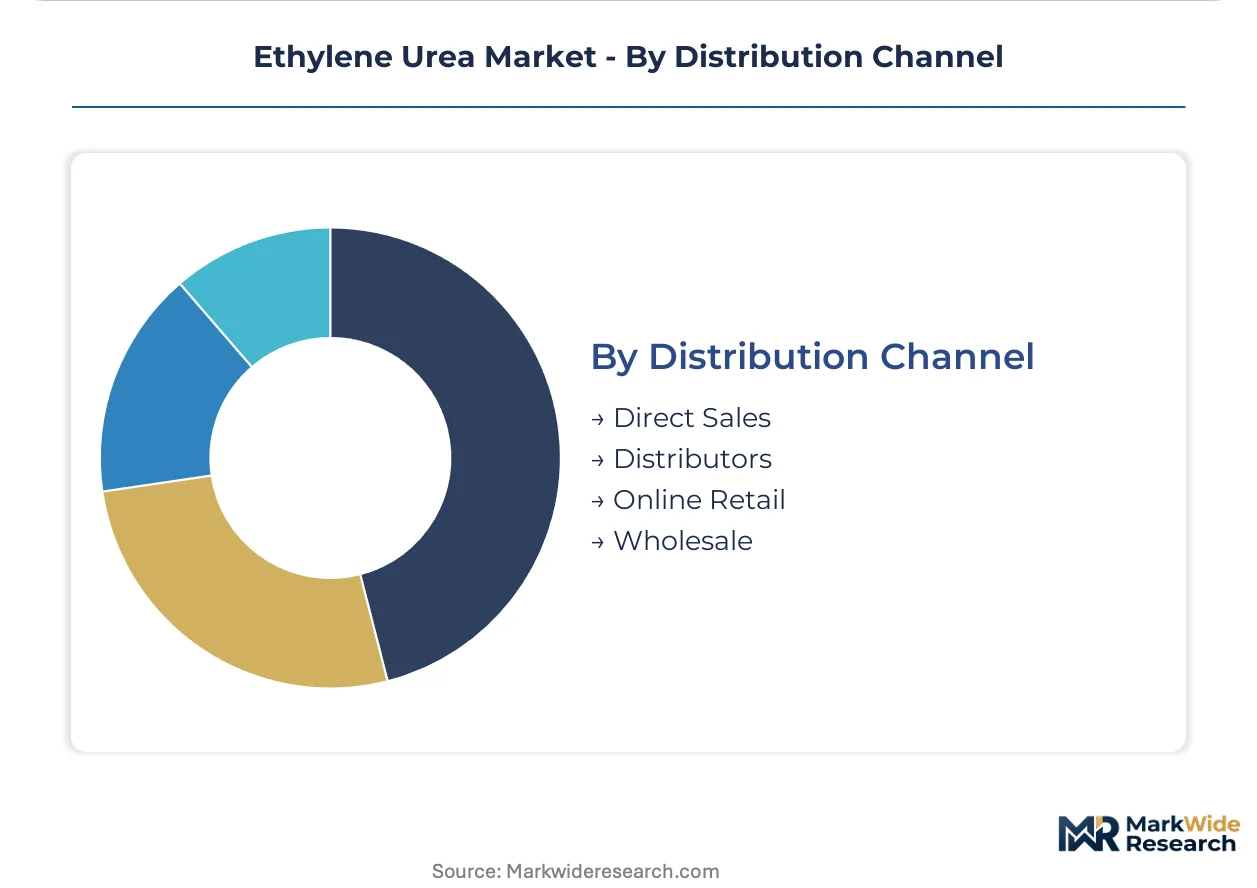
Channel selection correlates with shipment scale and specification complexity, with direct sales dominating bulk agricultural contracts and distributor networks serving fragmented industrial accounts.
- Direct Sales:Manufacturer-to-formulator relationships for volume agricultural and coating accounts. Chinese producers operate European stocking locations near Rotterdam and Hamburg to bypass traditional chemical trading houses.
- Distributors:Regional chemical distributors holding inventory for mid-scale industrial and pharmaceutical customers. Channel compression is most visible in German compound fertilizer operations, where formulators negotiate annual supply agreements with named production facilities rather than trading companies.
- Online Retail:E-commerce platforms serving small-volume laboratory, research, and specialty chemical buyers.
- Wholesale:Bulk commodity traders aggregating shipments for price-sensitive agricultural markets.
Direct sales retain volume leadership; online retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical tanker terminals anchor European ethylene urea distribution, while Shanghai's Yangshan deep-water facilities consolidate Asian export flows. These maritime nodes determine procurement economics for agricultural and pharmaceutical buyers across three continents.
China
Domestic manufacturers supply both local agricultural sectors and export-oriented pharmaceutical synthesis operations. The MEE enforces GB standards on wastewater discharge from urea condensation facilities, elevating compliance costs for producers. Shandong and Jiangsu provinces host the densest concentration of powder-grade capacity serving compound fertilizer blenders.
Germany
REACH-certified supply lines sustain demand from German and French agricultural markets. ECHA-registered suppliers command preferential placement in procurement tenders, creating tiered supply access based on compliance documentation. The Bavarian production base anchors domestic synthesis for coating resin applications.
United States
EPA Office of Chemical Safety and Pollution Prevention monitors ethylene urea under TSCA Section 5 for new use notifications. The US Corn Belt drives granule consumption for mechanical spreading equipment in compound fertilizer operations. Koch Industries competes on manufacturing scale across North American industrial accounts.
India
API manufacturers seek high-purity ethylene urea for antiviral and antifungal synthesis, commanding substantial premiums over agricultural grades. The country's national pharmaceutical regulator maintains import quality standards for chemical intermediates. Gujarat and Maharashtra clusters concentrate demand from generic drug producers.
France
Agricultural distributors screen suppliers based on ECHA registration completeness rather than price alone. EU Green Deal fertilizer incentives create preference for domestically synthesized material with verified lifecycle emissions documentation. The Hauts-de-France region hosts blending operations negotiating direct supply agreements with named production facilities.
Ethylene Urea Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated chemical conglomerates and specialized nitrogen compound producers. Capacity ownership clusters in China and Germany, with mid-scale processors occupying peripheral positions. Three archetypes dominate: backward-integrated petrochemical operators, regional agrochemical specialists, and pharmaceutical-grade refiners. Competitive moves center on REACH dossier maintenance and direct procurement channel development.
Among German-based chemical producers, BASF SE anchors demand through captive synthesis capabilities, while AlzChem Group exemplifies the regional specialist model with Bavarian production assets. Chinese manufacturers including Hebei Kangzhuang and Jiangsu Kolod Chemical occupy positions as scale-driven suppliers to export markets. These entities represent the geographic and structural poles of competitive positioning.
| Leading Market Players |
|---|
| AlzChem Group |
| Hebei Kangzhuang |
| BASF SE |
| Suichang Limin |
| Jining JinYin Chemical |
| Koch Industries |
| Jiangsu Kolod Chemical |
| Zhuosheng Biotech |
| Shandong Ruixing Chemical |
| Others |
Supply & Pricing Matrix
Overcapacity in Shandong province's powder-grade facilities is compressing spot pricing while forcing integrated producers toward long-term contract structures with named European formulators. This utilization imbalance rewards REACH-certified manufacturers with pricing power in German agricultural tenders while marginal non-compliant Chinese exporters absorb margin erosion.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade crystals, agricultural powder, and economy liquid separates buyers by certification burden and volume commitment. Pharmaceutical-grade material commands substantial premiums driven by sub-ppm formaldehyde thresholds and ECHA registration completeness, while agricultural blenders in the US Corn Belt negotiate annual offtake agreements indexed to ethylenediamine feedstock costs. Pricing pressure stems from melamine-formaldehyde substitution in coating applications, with automotive formulators most price-sensitive and API manufacturers least sensitive due to regulatory lock-in.
Supply Chain Analysis
Export-control scrutiny on dual-use condensation catalyst technology is fragmenting equipment sourcing between domestic Chinese fabricators and European specialist vendors. Manufacturing gravity centers on China, Germany, and India, with production economics drawing from ethylenediamine, urea, and formaldehyde input streams. Single-source vulnerability concentrates in Shandong and Jiangsu provinces where wastewater discharge permits restrict capacity expansion. Distribution runs through direct manufacturer-formulator relationships for volume agricultural accounts, bypassing traditional chemical trading houses near Rotterdam and Hamburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is emerging from a cyclical trough as agricultural nitrogen mandates in China and EU Green Deal fertilizer incentives restock channel inventory. Ethylenediamine cost normalization and REACH compliance investments are synchronizing to reward prepared suppliers.
For Market Incumbents: Insulate margin structures by deepening backward integration into ethylenediamine supply and securing captive synthesis capabilities in Bavaria or the US Gulf Coast. AlzChem Group's REACH-certified positioning demonstrates how ECHA registration completeness defends against Chinese price aggression in German compound fertilizer tenders. Prioritize liquid formulation channel development to capture coating automation demand. For New Entrants and Emerging Players: Eastern European pharmaceutical-grade refiners represent the most penetrable white space, with API manufacturers in Poland and Romania seeking alternatives to Chinese supply concentration. Target India's antiviral synthesis cluster with high-purity crystallization capabilities and complete CoA documentation. Enter through toll manufacturing arrangements with established ECHA-registered facilities to bypass multi-year dossier preparation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade crystallization as membrane filtration systems replace centrifugation stages. Five-to-ten year viability favors mid-scale European producers with verified lifecycle emissions documentation and direct procurement relationships with named German formulators. Watch for ethylenediamine price spikes as inflection indicators forcing consolidation among non-integrated processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylenediamine | Koch Industries and BASF SE anchor cost structures against feedstock volatility through captive supply. |
| REACH Dossier Maintenance Investment | ECHA-registered suppliers command preferential placement in French and German agricultural procurement tenders. |
| Liquid Formulation Channel Expansion | Metered dosing systems in automotive coating operations favor direct tanker-supply relationships bypassing distributors. |
| Membrane Filtration Technology Adoption | Energy-efficient crystallization collapses capital barriers for mid-scale pharmaceutical-grade producers. |
| European Stocking Location Establishment | Chinese manufacturers near Rotterdam and Hamburg compress lead times for German compound fertilizer blenders. |
Research Methodology
A standing panel of plant managers at Shandong and Jiangsu condensation facilities, procurement leads at German agrochemical formulators, and technical R&D directors at coating manufacturers provided ongoing calibration across the study period. Primary interview findings were validated against customs and trade data from China's General Administration of Customs, Cefic sector reports, SEC 10-K filings from disclosed chemical producers, and EPA TSCA Section 5 notification databases. Bottom-up capacity modeling and top-down demand segmentation were triangulated to reconcile volume estimates.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning grade tier, end-use industry, and regional production hub dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating ethylenediamine price trajectories, REACH enforcement intensity indices, and controlled-release fertilizer mandate implementation rates in China and the European Union.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, euro-yuan exchange rates, or agricultural commodity cycles would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement consistency and feedstock supply continuity. Material shifts in EPA formaldehyde restrictions, EU carbon border adjustment mechanisms, or Chinese wastewater discharge standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Tetrahydrocurcumin Reagent Market
Chemical Intermediates
Organometallic Compounds Market
Chemical Intermediates
Chemical Synthesizer Market
Chemical Intermediates
Molybdenum Disulfide (MoS2) Market
Chemical Intermediates
1, 3, 5-Triazine Market
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
Triisobutyl Phosphate Market
Chemical Intermediates
Penicillin Intermediate Market
Chemical Intermediates
3-Chloropropionyl Chloride Market
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
Enzyme Substrates Market
Chemical Intermediates
Preformulation Intermediates Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Global Aniline Derivative Market
Chemical Intermediates
9-Decanoic Acid Methyl Ester Market