
 Clad Pipe Market | 2026-2036
Clad Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Clad Pipe Market Analysis
API 5LD specification revisions are pivoting the cost-of-entry calculus for clad pipe qualification, forcing fabricators to retest metallurgical bonding under more severe sour service conditions. Tenaris leverages its seamless pipe backbone to control premium alloy supply chains from melt to final cladding. BUTTING Group anchors German engineering demand through precision hot-roll bonding of nickel alloy overlays. EEW Group competes on offshore project scale, sustaining North Sea and Middle East installation volumes with dedicated clad pipe mills.
Clad pipe consists of a carbon steel or low-alloy base material metallurgically bonded to a corrosion-resistant alloy layer, typically between 2 and 12 millimeters thick, serving to transport corrosive hydrocarbons without requiring solid alloy pipe throughout the full wall thickness. The manufacturing process dimension shows hot rolling dominates thick-wall offshore lines where bond integrity under hydrostatic collapse loading determines field acceptance, while welding-based overlay methods capture refinery turnaround demand where geometric flexibility outweighs unit cost. Stainless steel base grades occupy the largest product type position due to compatibility with standard offshore specifications, though duplex steel bases are capturing deepwater pre-salt awards where chloride stress cracking resistance governs material selection.
FDA and EPA frameworks in the US impose emissions and material traceability requirements that cascade into chemical plant piping specifications, while API standards govern oil and gas sector qualification protocols across all geographies. Japan's METI maintains JIS standards for pressure equipment that directly reference clad construction methods for high-temperature hydrogen service. Stakeholders must monitor how regulator convergence on hydrogen infrastructure standards redefines cladding alloy selection for emerging energy transport networks.
Market Dynamics
API 5LD specification revisions are forcing fabricators to retest metallurgical bonding under more severe sour service conditions, raising qualification costs and consolidating supply around integrated producers with captive alloy supply chains.
Growth Catalysts
- Pre-salt basin expansion:Brazil's offshore developments under sour gas conditions are accelerating demand for corrosion-resistant pipeline infrastructure with duplex steel base specifications.
- EPA emissions frameworks:US material traceability requirements are cascading into chemical plant piping specifications, mandating clad construction for high-temperature hydrogen transport networks.
- Hydrogen infrastructure buildout:Emerging energy transport networks are creating new cladding alloy selection criteria for hydrogen service compatibility across multiple geographies.
Market Restraints
- Nickel alloy input volatility:Premium alloy price swings compress fabricator margins and destabilize project bidding cycles for long-lead offshore contracts.
- Qualification cost concentration:API 5LD retesting requirements favor integrated producers with in-house melt-to-clad capabilities, marginalizing smaller overlay specialists.
- Welding overlay substitution:Refinery turnaround demand increasingly accepts geometrically flexible weld-overlay methods over hot-roll bonded pipe for non-critical service.
Strategic Opportunities
- Deepwater pre-salt awards:Chloride stress cracking resistance requirements in Brazil's offshore fields are opening specifications to duplex steel base materials previously excluded from standard offshore grades.
- Japan hydrogen service standards:METI's JIS standards for high-temperature hydrogen service are creating certified demand for nickel alloy cladding in emerging energy infrastructure.
- Digital bond inspection:Ultrasonic testing integration with automated cladding lines is compressing qualification timelines and reducing destructive test sampling rates.
Industry Challenges
- Metallurgical bonding certification timelines:API 5LD sour service retesting protocols are extending project qualification phases by 8-14 months for non-integrated fabricators.
- Skilled overlay welder scarcity:Precision hot-roll bonding operations face recruitment gaps for technicians capable of maintaining bond integrity specifications under high-tonnage rolling parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clad Pipe Market |
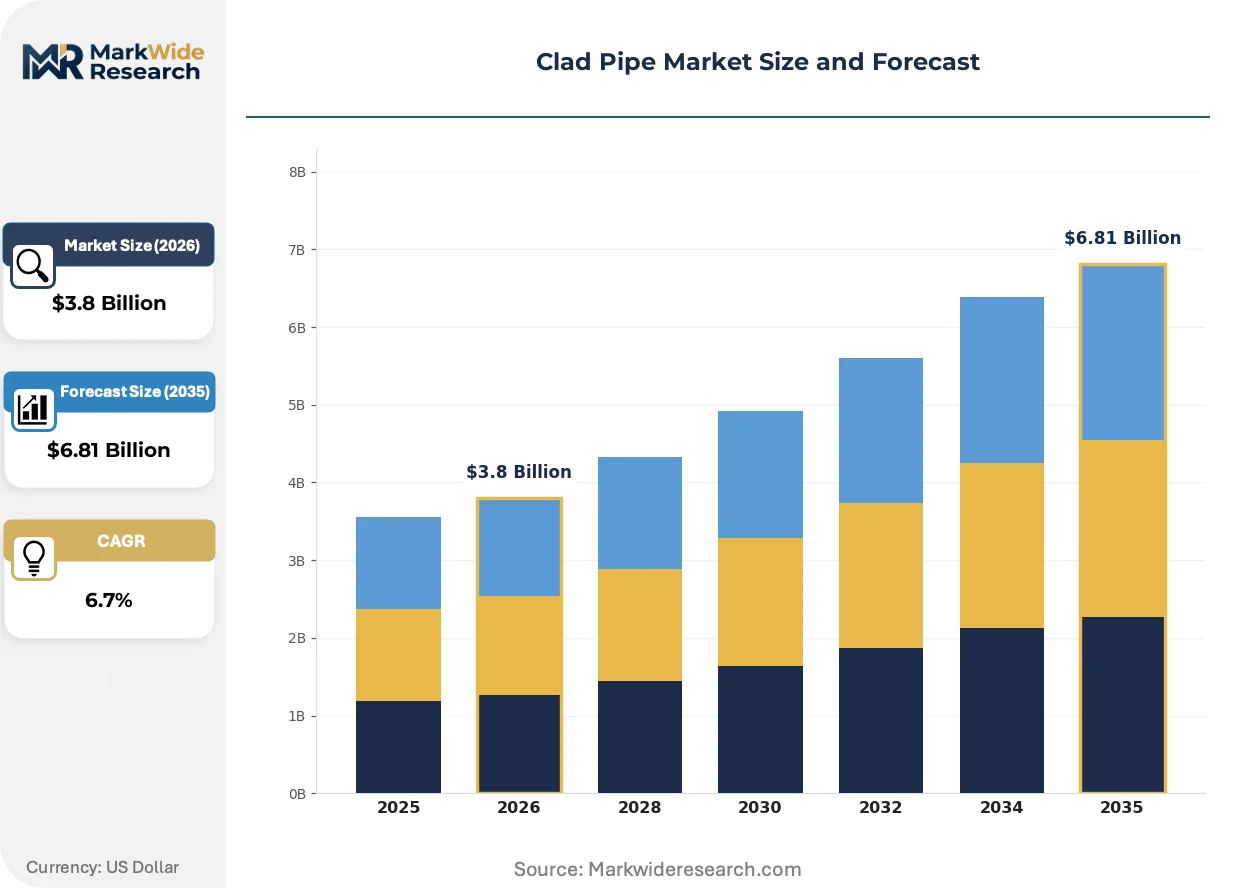
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Carbon Steel, Alloy Steel, Duplex Steel Cladding Material: Nickel Alloy, Titanium, Copper, Inconel End User: Oil & Gas, Chemical, Power Generation, Marine Manufacturing Process: Thermal Spraying, Hot Rolling, Cold Rolling, Welding |
| Companies Covered | BUTTING Group, The Japan Steel Works, LTD, EEW Group, Tenaris, Cladtek Holdings Pte Ltd., Inox Tech S.p.A, NobelClad, Proclad Group, Gieminox Tectubi Raccordi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clad Pipe Market Emerging Trajectories
Manufacturing automation and regulatory convergence on hydrogen compatibility standards are compressing traditional qualification timelines while fragmenting procurement patterns across project-specific alloy specifications.
Laser-assisted cladding deposition is decentralizing overlay production from centralized mill complexes to regional service centers capable of field-responsive geometry adaptation. Offshore operators in the North Sea and Middle East are piloting distributed cladding cells for emergency replacement spools. This topology is compressing logistics lead times from months to weeks for non-standard dimensions.
REACH substance restrictions on nickel compound emissions are tightening alloy processing environmental compliance across European fabrication facilities. The regulation is forcing capital deployment into closed-loop electrolyte recovery systems for cladding bath operations. German and Dutch mills are responding with dedicated emission-controlled bonding lines that trade higher opex for permit security.
Buyer specifications are fragmenting around project-specific sour service severity tiers rather than defaulting to standard API grades. Engineering contractors in Brazil and West Africa are unbundling cladding alloy selection from base pipe procurement, creating direct alloy supplier relationships that bypass traditional fabricator intermediaries. This disintermediation is most visible in pre-salt developments where chloride partial pressure thresholds dictate custom duplex-super duplex combinations outside standard catalogs.
Clad Pipe Market Segmentation
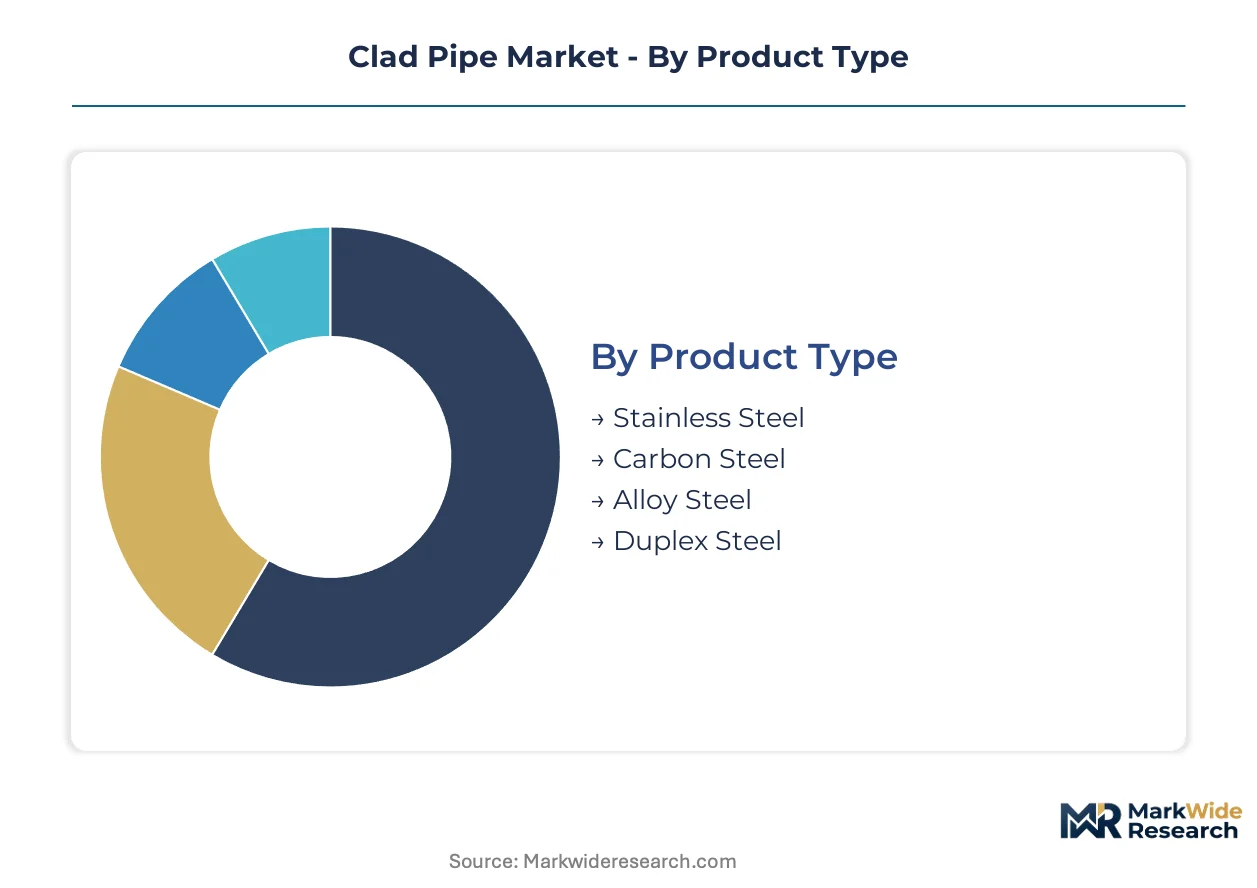
Clad pipe procurement patterns fragment across metallurgical specifications, manufacturing constraints, and end-use severity tiers. Buyers prioritize bond integrity certification, alloy availability, and installation logistics over unit cost in high-consequence applications.
Product Type:
Buyers differentiate by base material compatibility with pressure equipment codes and sour service severity.
- Stainless Steel:Austenitic grades dominate standard offshore specifications due to weldability and API 5LD qualification history. North Sea operators specify 316L bases for moderate chloride service where cost efficiency outweighs premium alloy performance.
- Duplex Steel:22Cr and 25Cr duplex bases are displacing austenitic grades in Brazil's pre-salt fields where chloride stress cracking resistance governs material selection. Chloride partial pressure thresholds above 0.5 bar now trigger automatic duplex specification in Petrobras field architecture.
- Carbon Steel:Low-alloy bases with nickel cladding capture onshore gathering systems where pressure ratings permit thinner wall construction.
- Alloy Steel:Cr-Mo bases serve high-temperature hydrogen service in US Gulf Coast refineries under API 941 Nelson curve constraints.
Volume sits with stainless steel bases; growth tilts toward duplex steel.
Cladding Material:
Alloy selection tracks corrosive species concentration and regulator certification scope.
- Nickel Alloy:UNS N06625 and N08825 overlays command premium positioning for sour gas service combining hydrogen sulfide and carbon dioxide. Weld overlay shops in Houston and Rotterdam maintain dedicated 625 wire inventory for emergency turnaround response.
- Inconel:High-nickel variants address extreme temperature hydrogen service in emerging energy infrastructure. Japan's METI JIS standards for hydrogen transport are certifying Inconel 625 cladding for high-pressure pipeline applications.
- Titanium:Grades 1 and 2 cladding serve seawater injection systems where crevice corrosion resistance overrides cost considerations.
- Copper:Oxygen-free copper overlays capture specialized chemical process applications requiring thermal conductivity alongside corrosion resistance.
Procurement concentrates on nickel alloys; titanium is climbing the fastest for subsea injection duty.
End User:
Application severity dictates qualification depth and supplier integration requirements.
- Oil & Gas:Offshore production and subsea tiebacks generate the largest contract values with mandatory third-party bond inspection. Brazil's pre-salt developments specify duplex-super duplex combinations outside standard fabricator catalogs.
- Chemical:High-temperature hydrogen and acid service drive nickel alloy cladding demand with EPA material traceability mandates cascading into plant piping specifications.
- Power Generation:Flue gas desulfurization systems and nuclear service require cladding for corrosion-erosion resistance in aggressive aqueous environments.
- Marine:Seawater cooling and ballast systems specify titanium-clad carbon steel for weight-critical naval and commercial vessel applications.
Contract value peaks in oil and gas; chemical sector specifications are expanding most quickly on hydrogen infrastructure buildout.
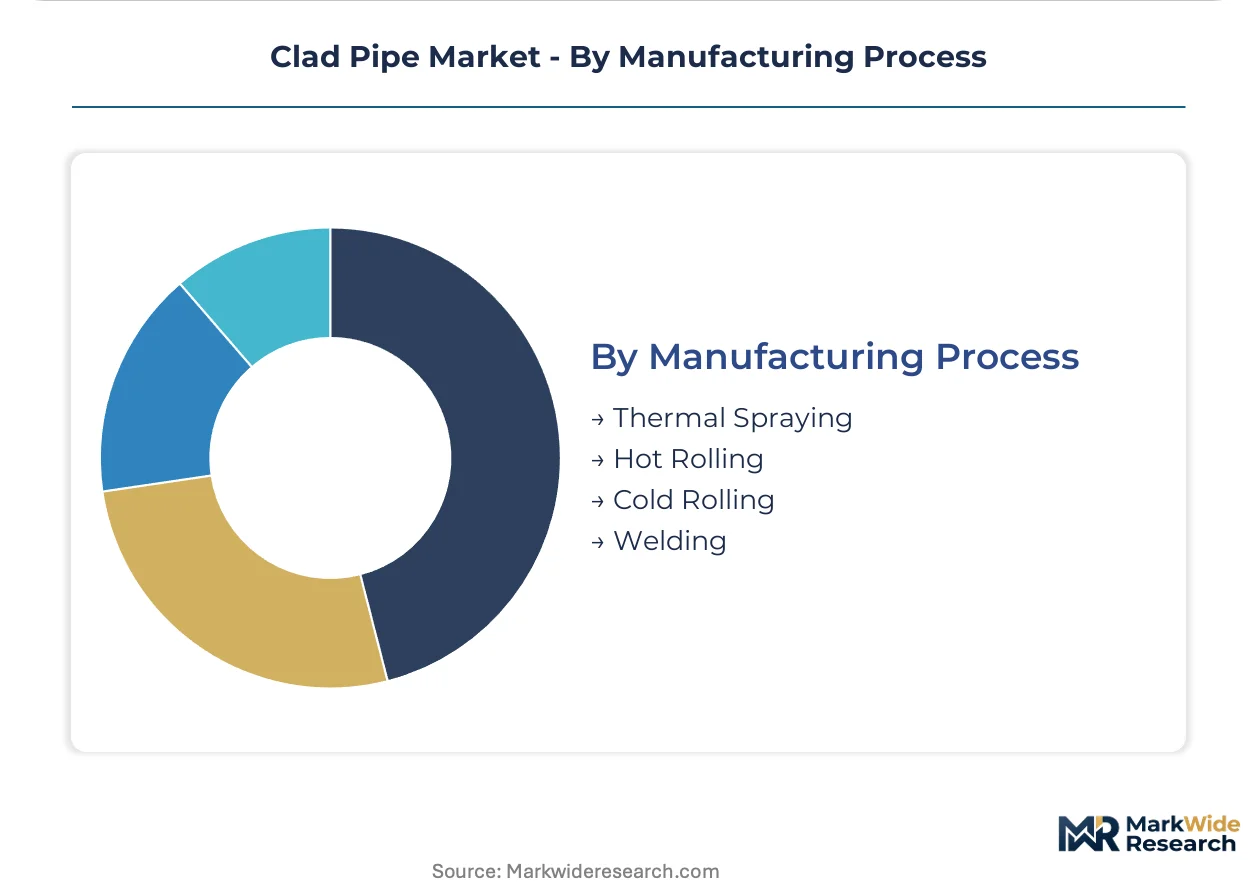
Manufacturing Process:
Process selection trades bond integrity assurance against geometric flexibility and lead time compression.
- Hot Rolling:Metallurgical bonding under high-tonnage rolling parameters produces thick-wall offshore lines where hydrostatic collapse loading determines field acceptance. German and Japanese mills control this segment through precision temperature control during bond formation.
- Welding:Overlay welding captures refinery turnaround demand where geometric flexibility for non-standard spool dimensions outweighs unit cost. Skilled welder scarcity is constraining capacity expansion in US Gulf Coast service centers.
- Thermal Spraying:Plasma and HVOF deposition serve repair and localized cladding applications where heat input must minimize base material distortion.
- Cold Rolling:Explosive bonding and roll-bonding without heating address specialized alloy combinations where thermal exposure risks intermetallic phase formation.
Offshore linepipe volume flows through hot rolling; welding is gaining share fastest on distributed service center expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for clad pipe concentrates in offshore oil and gas provinces where sour service conditions mandate corrosion-resistant pipeline infrastructure. Brazil's pre-salt developments anchor volume requirements, while regulatory tightening in industrialized economies reshapes qualification protocols across manufacturing centers.
Brazil
Petrobras field architecture specifies duplex-super duplex combinations for chloride partial pressures above 0.5 bar in pre-salt basins. ANVISA maintains material traceability requirements for subsea equipment that cascade into cladding qualification documentation. Rio de Janeiro clusters host engineering contractors unbundling alloy selection from base pipe procurement for custom specifications.
United States
Gulf Coast refineries drive nickel alloy cladding demand for high-temperature hydrogen service under API 941 constraints. EPA emissions frameworks mandate material traceability that extends into chemical plant piping specifications. Houston maintains dedicated weld overlay service centers with emergency turnaround response capabilities for 625 wire inventory.
Germany
REACH substance restrictions on nickel compound emissions force capital deployment into closed-loop electrolyte recovery systems for cladding operations. ECHA compliance requirements tighten environmental standards across European fabrication facilities. North Rhine-Westphalia mills operate emission-controlled bonding lines trading higher opex for permit security.
Japan
METI JIS standards for high-temperature hydrogen service certify Inconel 625 cladding for emerging energy transport infrastructure. Precision hot-roll bonding operations in industrial clusters face technician recruitment gaps for high-tonnage rolling parameter maintenance. Kanto region producers control thick-wall offshore linepipe segments through temperature-controlled bond formation.
Saudi Arabia
Offshore expansion in Arabian Gulf fields generates demand for corrosion-resistant pipeline infrastructure under sour gas conditions. SFDA equivalent frameworks govern pressure equipment material qualification for hydrocarbon service. Eastern Province industrial zones concentrate fabrication capacity serving Middle East installation volumes.
Clad Pipe Market Vendor Landscape
German and Japanese producers anchor the premium-tier segment through precision hot-roll bonding capabilities; US and Italian specialists hold refinery turnaround and distributed service center positions. The vendor base separates into integrated melt-to-clad operators, overlay welding service centers, and explosive bonding specialists. Strategic differentiation concentrates on captive alloy supply chains versus geometric flexibility for non-standard dimensions. Competitive moves center on qualification timeline compression through automated inspection integration and regional service center expansion for emergency spool replacement.
Within the integrated producer tier, Tenaris exemplifies seamless pipe backbone control from melt through final cladding, while The Japan Steel Works, LTD occupies a position in precision temperature-controlled bond formation for thick-wall offshore applications. Among European specialists, BUTTING Group anchors German engineering demand through hot-roll bonding operations. These fabricators represent archetypes where backward integration into premium alloy supply chains separates qualified bidders from marginal overlay operators facing API 5LD retesting cost concentration.
| Leading Market Players |
|---|
| BUTTING Group |
| The Japan Steel Works, LTD |
| EEW Group |
| Tenaris |
| Cladtek Holdings Pte Ltd. |
| Inox Tech S.p.A |
| NobelClad |
| Proclad Group |
| Gieminox Tectubi Raccordi |
| Others |
Supply Flow & Price Mechanics
Captive alloy supply chains from melt to final cladding anchor both supply security and pricing power for integrated producers, while non-integrated fabricators face margin compression from API 5LD retesting cost concentration and nickel alloy input volatility. German and Japanese mills leverage precision hot-roll bonding capabilities to command premium positioning, whereas US Gulf Coast weld overlay shops compete on turnaround speed at thinner margins.
Pricing Analysis
Volume flows through contract-based long-term offtake structures for offshore linepipe, while spot procurement captures refinery turnaround demand. Pricing stratifies across hot-roll bonded premium grades, standard API 5LD qualified products, and economy-tier weld overlay alternatives. Cost compression in the economy tier is intensifying because welding overlay methods substitute for bonded pipe in non-critical service. Engineering contractors driving Brazil's pre-salt developments show least price sensitivity due to chloride stress cracking severity, while onshore gathering system operators exhibit highest elasticity.
Supply Chain Analysis
Nickel alloy supply rests on specialty steel producers in Germany, Japan, and the United States with captive vacuum melting capabilities. UNS N06625 and N08825 wire feedstock, duplex stainless steel base plates, and precision rolling mill equipment constitute critical input dependencies. Single-source vulnerability concentrates in vacuum arc remelting capacity for super duplex grades. Distribution runs through mill-direct contracts for offshore projects and regional service center networks for turnaround maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clad pipe fabrication is transitioning from manual overlay welding to automated laser-assisted cladding deposition, displacing legacy geometric-flexibility-dependent methods with precision bond formation technologies.
For Market Incumbents: Hedge against welding overlay substitution by embedding ultrasonic testing automation into hot-roll bonding lines, compressing qualification timelines that API 5LD sour service retesting has extended. Secure captive nickel alloy supply through upstream control over vacuum melting capacity, insulating margin positions from input volatility that destabilizes project bidding cycles.
For New Entrants and Emerging Players: The gap between premium hot-roll bonded offshore grades and economy weld overlay alternatives opens white-space at the mid-tier for automated cladding cells serving distributed refinery service. Target North Sea and Middle East emergency replacement spool demand where logistics lead time compression commands pricing premiums. Pursue direct alloy supplier relationships with engineering contractors unbundling procurement in Brazil's pre-salt developments.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated seamless pipe producers seeking backward integration into corrosion-resistant alloy capabilities. Long-term viability favors fabricators with in-house melt-to-clad integration and certified hydrogen service positioning under emerging METI JIS standards. Watch for regulatory convergence on hydrogen infrastructure certification as inflection indicator for cladding alloy demand reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Cladding Line Deployment | Ultrasonic testing integration reduces destructive sampling rates and compresses API 5LD qualification timelines. |
| Captive Nickel Alloy Supply Integration | Backward integration into vacuum melting insulates margins from UNS N06625 wire feedstock price volatility. |
| Hydrogen Service Certification Investment | METI JIS standard compliance positions fabricators for emerging high-temperature hydrogen transport networks. |
| Distributed Service Center Expansion | Regional cladding cells in Rotterdam and Houston capture emergency turnaround demand with weeks-not-months lead times. |
| Closed-Loop Emission Control Systems | REACH-compliant electrolyte recovery at German mills trades higher opex for permit security under ECHA restrictions. |
Methodological Framework
Independent corroboration across pipe fabrication executives, procurement leads at offshore EPC contractors, metallurgical bonding specialists, and regulatory compliance officers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from API specification documentation, ANVISA material traceability filings, METI JIS standard registers, and customs trade data for nickel alloy inputs. Bottom-up project pipeline assessment and top-down macro demand modeling triangulate volume estimates.
Rate-of-change decomposition across base material grade evolution, cladding alloy specification fragmentation, manufacturing process automation adoption, and end-use severity tier unbundling structures the analytical framework. CAGRs derive from segmented demand buildups across stainless steel, duplex steel, carbon steel, and alloy steel base categories, with overlay from hydrogen infrastructure buildout and pre-salt basin development intensity. Modeled inputs include Petrobras field architecture specifications, EPA emissions framework compliance timelines, and REACH substance restriction implementation phases.
Inputs from API qualification databases and offshore project sanctioning announcements were available through the study window; gaps in proprietary fabricator cost structures introduce uncertainty bands around margin compression estimates. Forecasts reflect documented assumptions regarding regulatory convergence timelines and alloy substitution elasticity. A small set of triggers—including hydrogen infrastructure standard finalization and nickel compound emission restriction enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Bahrain PVC Pipes Market
Pipes and Tubes
Global CPVC Pipes and Fittings Market
Pipes and Tubes
PVC Pipes and Fittings Market
Pipes and Tubes
HPLC Fused Silica Tube Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
GCC PVC Pipes Market
Pipes and Tubes
Europe Line Pipe Market
Pipes and Tubes
Global Municipal Pipes Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Europe Pipe Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
Gathering Pipeline Market
Pipes and Tubes
Steel Pipe Market
Pipes and Tubes
Seamless Pipe Market