
 Plastic Pipes and Fittings Market | 2026-2036
Plastic Pipes and Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Pipes and Fittings Market Insights
Concrete is hardening into a secondary choice for buried water distribution as polymer systems deliver superior corrosion resistance and joint integrity. JM Eagle, Inc. leverages integrated resin-to-pipe manufacturing across multiple North American facilities. Sekisui Chemical Co., Ltd. anchors its position through advanced cross-linked polyethylene technology for high-tolerance applications. China Lesso Group Holdings Limited dominates Greater China distribution through an extensive dealer network serving municipal and residential contractors.
Plastic pipes and fittings comprise extruded or molded thermoplastic components—primarily polyvinyl chloride, high-density polyethylene, and polypropylene—engineered to transport fluids, gases, and solids across pressurized and gravity-flow systems. Wall thickness, SDR ratio, and temperature-pressure ratings determine suitability for potable water, drainage, or industrial chemical service. High-density polyethylene systems command premium positioning in trenchless and directional-drilling applications where flexibility and fusion-welded integrity reduce installation cost. Polyvinyl chloride maintains volume leadership in residential drainage and non-pressure sanitary systems across cost-sensitive procurement environments. Infrastructure end users represent the fastest-expanding demand pool as governments prioritize water security and sewer rehabilitation programs.
The US EPA Lead and Copper Rule revisions and NSF/ANSI 61 certification requirements are tightening material composition standards for potable water contact surfaces. China's SAMR enforces GB standards for plastic pipe dimensional consistency and recycled content disclosure in public procurement. India's BIS certification mandates and Jal Jeevan Mission implementation are accelerating formal channel adoption over unorganized supply. Stakeholders must monitor regulatory divergence between per-country certification regimes and assess backward integration into resin compounding to secure formulation flexibility.
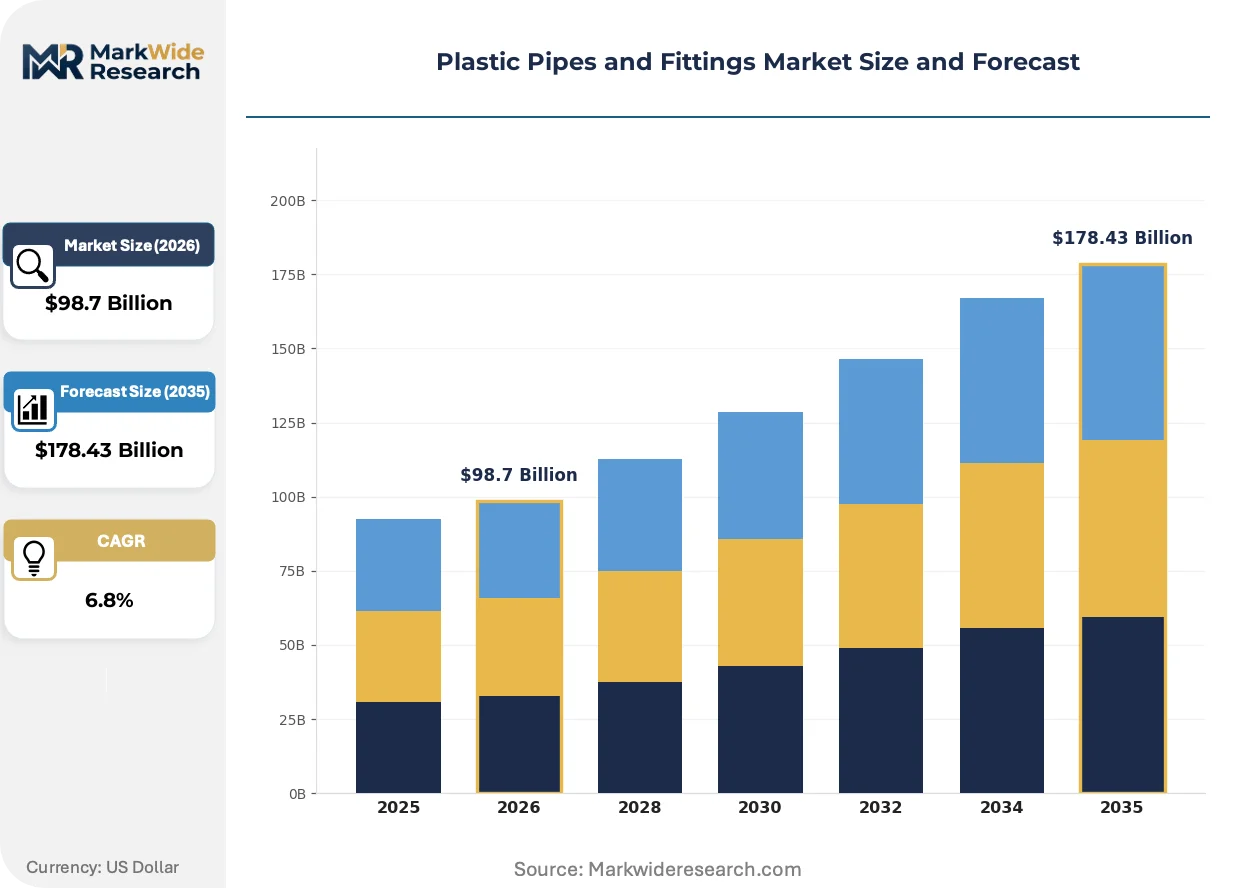
Market Dynamics
Municipal water infrastructure degradation across aging urban centers is accelerating specification shifts toward corrosion-resistant polymer systems that eliminate joint failure and extend service life beyond metallic alternatives.
Growth Catalysts
- EPA Lead and Copper Rule revisions:US municipalities face mandatory replacement timelines for lead service lines, creating surge demand for NSF/ANSI 61-certified polyethylene and PVC systems in potable water networks.
- Jal Jeevan Mission implementation:India's rural piped water program requires formal channel procurement of BIS-certified products, displacing unorganized supply and expanding addressable market for compliant manufacturers.
- Cross-linked polyethylene (PEX) technology:Advanced PEX formulations enable higher temperature-pressure ratings for district heating and industrial chemical transport, opening specification windows previously held by metal systems.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock costs fluctuate with crude oil benchmarks, compressing margin predictability for extrusion-dependent pipe manufacturers.
- EU REACH chemical compliance:Phthalate plasticizer restrictions and substance-of-very-high-concern listings force continuous formulation reformulation, raising R&D overhead for PVC compounders serving European markets.
- Concrete pipe residual preference:Municipal procurement inertia and established contractor relationships sustain specification of reinforced concrete for large-diameter gravity sewer in cost-sensitive developing markets.
Strategic Opportunities
- Trenchless rehabilitation technology convergence:Cured-in-place pipe (CIPP) lining and directional drilling methods favor flexible HDPE systems that reduce excavation cost and traffic disruption in dense urban corridors.
- Agricultural drip-irrigation networks:India's National Mission for Sustainable Agriculture mandates micro-irrigation expansion, creating demand for UV-stabilized LDPE laterals and emitter-integrated tubing.
- China's dual carbon goals:MEE enforcement of recycled content minimums in public procurement redirects formulation strategies toward post-industrial regrind integration and bio-based feedstock pilot programs.
Industry Challenges
- Fusion welding technician certification:HDPE joint integrity depends on qualified operators for butt and electrofusion processes, creating bottlenecks as infrastructure project velocity outpaces training pipeline capacity.
- Multi-jurisdictional certification timelines:Manufacturers seeking pan-regional contracts must navigate divergent potable water contact approvals—NSF/ANSI 61 in North America, WRAS in UK, ACS in France—extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Pipes and Fittings Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pipes, Fittings, Valves, Couplings Application: Water Supply, Agriculture, Waste Management, HVAC Material: Polyvinyl Chloride, High-Density Polyethylene, Polypropylene, Others End User: Residential, Commercial, Industrial, Infrastructure |
| Companies Covered | Orbia, Sekisui Chemical Co., Ltd., JM Eagle, Inc., Advanced Drainage Systems, China Lesso Group Holdings Limited, Aliaxis, Georg Fischer Ltd., The Supreme Industries Limited, Finolex Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Pipes and Fittings Market Trends and Innovations
Material science advances and installation method evolution are compressing total-project-cost differentials between polymer and legacy metallic systems. Three developments are redirecting competitive positioning.
Multilayer composite pipe systems incorporating aluminum or fiberglass reinforcement layers are absorbing structural loads previously requiring metal thickness. Water utilities in seismic zones specify these hybrids for their combination of flexibility and pressure rating. The technology is absorbing market share from ductile iron in transmission mains where joint deflection tolerance matters.
REACH framework updates on microplastic release are tightening discharge standards for polymer processing facilities across EU member states. Industrial consequence includes mandatory closed-loop cooling water systems and filtration investments for extrusion plants. PVC compounding operations serving construction drainage are most affected, accelerating migration toward calcium-zinc stabilizer formulations.
Consolidated procurement by national water utilities is compressing supplier bases and demanding extended performance warranties. Tier-one contractors in Saudi Arabia's Qiddum and India' Smart Cities Mission now require 50-year design-life documentation and in-situ installation supervision. This concentration is visible most acutely in Gulf Cooperation Council states where single-buyer tenders dominate municipal infrastructure awards.
Plastic Pipes and Fittings Market Segmentation
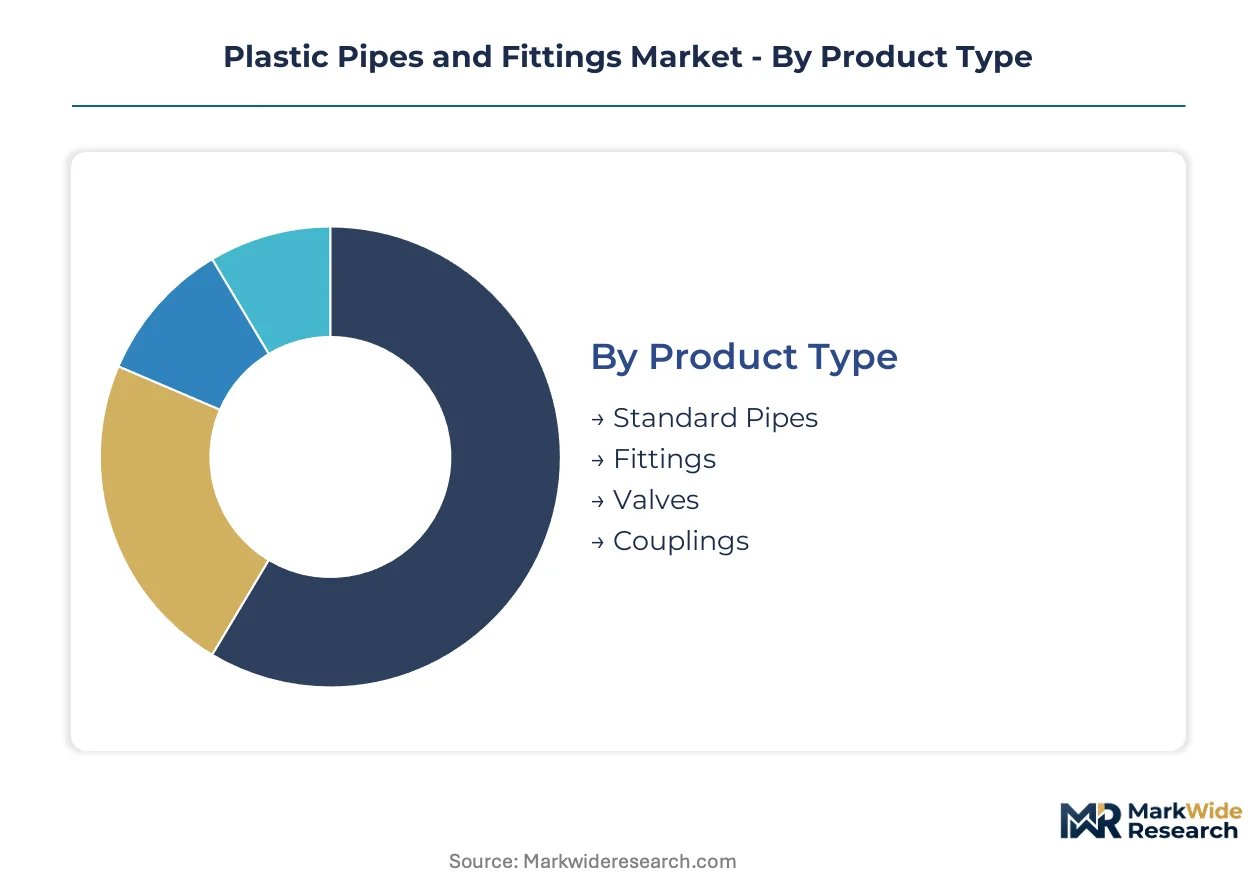
Plastic pipe specification varies dramatically across pressure ratings, chemical exposure, and installation methods. Certification requirements fragment procurement patterns, with potable water contact surfaces demanding NSF/ANSI 61 compliance while drainage systems accept lower-tier testing protocols.
Product Type:
NSF/ANSI 61 certification burdens concentrate on standard pipes and valves intended for potable water contact, while fittings and couplings face reduced testing overhead in non-pressure drainage applications.
- Standard Pipes:Extruded thermoplastic cylinders form the volume backbone, with wall thickness and SDR ratios determining pressure class. India's Jal Jeevan Mission procurement mandates BIS IS 4984 certification for HDPE water mains, displacing uncertified imports in rural distribution networks.
- Fittings:Molded elbows, tees, and reducers enable directional changes and diameter transitions. Fusion-welded HDPE fittings command premium positioning in US municipal trenchless rehabilitation contracts where joint integrity determines warranty terms.
- Valves:Flow control components integrate with pipe systems for isolation and pressure management. Industrial chemical service valves require ECHA REACH compliance for sealing materials in EU export markets.
- Couplings:Mechanical joining devices accommodate thermal expansion and ground movement. Seismic zone specifications in Japan's METI building codes drive demand for flexible couplings in high-rise plumbing risers.
Standard pipes sit at the top of the volume ranking, with fittings climbing the fastest as infrastructure rehabilitation accelerates joint-intensive replacement cycles.
Application:
Cost tier stratification separates pressure-rated potable systems from gravity-flow drainage, with agricultural micro-irrigation occupying a mid-tier pricing band between commodity drainage and engineered water transmission.
- Water Supply:Pressurized distribution networks for municipal and building service. EPA Lead and Copper Rule revisions in the US are forcing lead service line replacements, expanding specification windows for NSF/ANSI 61-certified polyethylene systems.
- Agriculture:Drip-irrigation laterals, sprinkler mains, and drainage tubing. India's National Mission for Sustainable Agriculture mandates UV-stabilized LDPE expansion across Maharashtra and Gujarat farming corridors.
- Waste Management:Sanitary sewer and stormwater collection systems. Non-pressure PVC dominates residential drainage in cost-sensitive Southeast Asian markets where concrete pipe residual preference persists.
- HVAC:Chilled water distribution and geothermal ground loops. Cross-linked polyethylene gains share in European district heating retrofits where temperature-pressure ratings exceed standard polyethylene capabilities.
Water supply commands the highest certification burden per linear meter, while agricultural applications are expanding most quickly on policy-mandated irrigation modernization.
Material:
Supply concentration among resin producers creates margin pressure differentials, with PVC compounders facing the steepest formulation reformulation costs under evolving chemical safety frameworks.
- Polyvinyl Chloride:Chlorinated thermoplastic dominates non-pressure drainage and electrical conduit. ECHA REACH phthalate restrictions force continuous reformulation, raising R&D overhead for European market participants.
- High-Density Polyethylene:Linear polymer with superior flexibility and fusion-welding characteristics. Trenchless directional drilling specifications across Saudi Arabia's Qiddum and India's Smart Cities Mission favor HDPE for reduced excavation cost.
- Polypropylene:Higher temperature resistance suits industrial chemical transport and hot water distribution. China's GB standards for building materials enforce dimensional consistency testing for PP-R hot water pipes in residential construction.
- Others:Cross-linked polyethylene, chlorinated polyvinyl chloride, and specialty fluoropolymers. Advanced PEX formulations penetrate district heating markets previously held by metal systems in Nordic climate zones.
Polyvinyl Chloride retains volume leadership on cost position, with High-Density Polyethylene gaining share fastest on infrastructure rehabilitation demand.
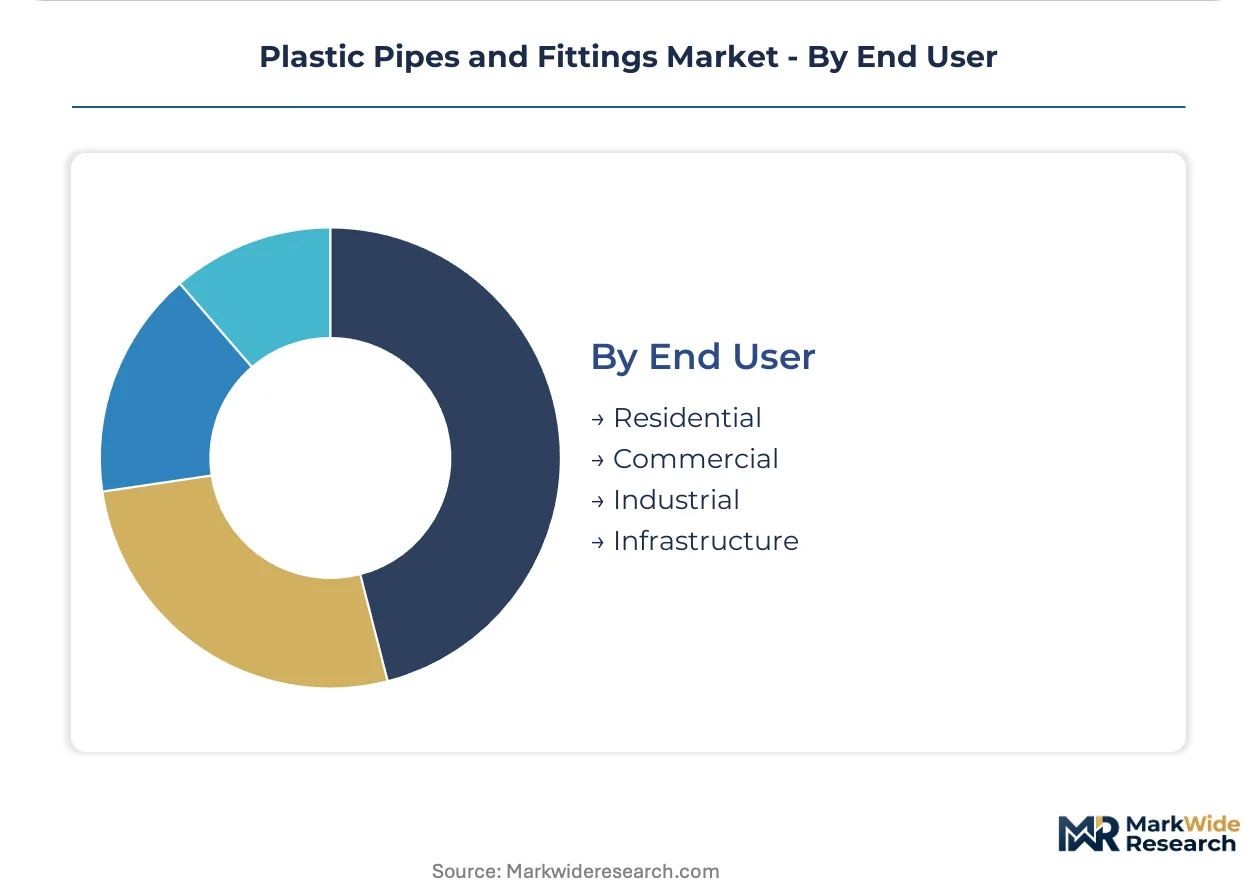
End User:
Customer type determines warranty duration and installation supervision requirements, with infrastructure end users demanding 50-year design-life documentation that residential contractors rarely specify.
- Residential:Single-family and multi-family building plumbing and drainage. India's urban corridor projects specify BIS-certified products, displacing unorganized supply in formal channel procurement.
- Commercial:Office, retail, and hospitality building systems. LEED certification requirements in North American green building codes drive specification of recycled-content piping in California and New York construction markets.
- Industrial:Manufacturing process lines, chemical transport, and cooling water. ANVISA pharmaceutical manufacturing standards in Brazil mandate specific resin grades for high-purity water systems.
- Infrastructure:Municipal water, sewer, and stormwater networks. Consolidated procurement by Saudi Arabia's national water utility compresses supplier bases and demands extended performance warranties with in-situ installation supervision.
Infrastructure represents the steepest expansion trajectory on government water security prioritization, with Residential maintaining the largest installed base replacement cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors polymer pipe manufacturing capacity, with municipal infrastructure rehabilitation across four continents redirecting specification standards toward corrosion-resistant thermoplastic systems.
United States
EPA Lead and Copper Rule revisions mandate lead service line replacement timelines across 10,000 municipal water systems. NSF/ANSI 61 certification requirements tighten material composition standards for potable water contact surfaces. Houston-Gulf Coast petrochemical corridors supply resin feedstock to extrusion facilities serving trenchless rehabilitation contracts in Chicago and Los Angeles metro areas.
China
GB standards for building materials enforce dimensional consistency testing across public procurement channels. MEE enforcement of recycled content minimums redirects formulation strategies toward post-industrial regrind integration. The Pearl River Delta manufacturing cluster ships PVC and HDPE systems to municipal contractors throughout Greater China's urban corridor projects.
India
Jal Jeevan Mission implementation requires formal channel procurement of BIS-certified HDPE and PVC products. BIS IS 4984 certification mandates displace uncertified imports in rural distribution networks. Maharashtra and Gujarat farming corridors absorb UV-stabilized LDPE laterals for micro-irrigation expansion under the National Mission for Sustainable Agriculture.
Germany
ECHA REACH phthalate restrictions and substance-of-very-high-concern listings force continuous PVC formulation reformulation. EU Green Deal implementation accelerates specification shifts toward recyclable polymer systems in district heating retrofits. Industrial chemical processors in the Rhine-Ruhr region specify cross-linked polyethylene for temperature-pressure ratings exceeding standard polyethylene capabilities.
Saudi Arabia
Qiddum infrastructure development and national water utility consolidation compress supplier bases toward tier-one contractors. SFDA-equivalent procurement standards demand 50-year design-life documentation with in-situ installation supervision. Eastern Province petrochemical integration supplies captive resin to extrusion facilities serving Gulf Cooperation Council municipal tenders.
Plastic Pipes and Fittings Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated resin-to-pipe manufacturers defend margin position against feedstock volatility. The vendor base concentrates around three strategic tiers: multinational integrated producers with captive resin supply, regional specialists with distribution density in single countries, and technology-focused developers of multilayer composite systems. M&A activity and backward integration into resin compounding represent the dominant competitive moves as manufacturers seek formulation flexibility under divergent regulatory regimes.
Among integrated North American producers, JM Eagle, Inc. and Advanced Drainage Systems exemplify the scale-driven archetype with multi-facility extrusion networks. Sekisui Chemical Co., Ltd. anchors the technology-specialist position through its cross-linked polyethylene development focus. China Lesso Group Holdings Limited occupies the regional-dominance tier with extensive dealer network coverage across Greater China municipal and residential contracting channels.
| Leading Market Players |
|---|
| Orbia |
| Sekisui Chemical Co., Ltd. |
| JM Eagle, Inc. |
| Advanced Drainage Systems |
| China Lesso Group Holdings Limited |
| Aliaxis |
| Georg Fischer Ltd. |
| The Supreme Industries Limited |
| Finolex Industries Ltd. |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-caps across India's Maharashtra and Gujarat manufacturing corridors anchor supply-side discipline through informal credit networks and dealer-loyalty programs that buffer price volatility for agricultural drip-irrigation distributors. Their captive access to recycled post-industrial regrind under China's MEE recycled content mandates creates cost advantages that multinational resin-to-pipe integrators struggle to replicate in spot polyethylene markets.
Pricing Analysis
Ethylene and propylene feedstock costs pass through to extrusion-dependent manufacturers with a three-to-six-month lag, compressing margin predictability for PVC compounders serving EU markets under ECHA REACH reformulation burdens. Three-tier pricing structure across premium, standard, and economy levels separates NSF/ANSI 61-certified potable water systems from drainage-grade PVC and uncertified agricultural tubing. Pricing pressure stems from resin price volatility tied to crude oil benchmarks, with municipal procurement in cost-sensitive developing markets exhibiting highest price sensitivity and Gulf Cooperation Council consolidated utility tenders showing lowest.
Supply Chain Analysis
Single-source vulnerability sits with ethylene cracker complexes concentrated along the US Houston-Gulf Coast, China's Yangtze River Delta, and Saudi Arabia's Eastern Province petrochemical integration zones. HDPE pipe extrusion draws from linear low-density resin grades, calcium-zinc stabilizer formulations, and UV-stabilizer masterbatches. Tariff exposure on Chinese PVC resin imports into India threatens margin structures for compounders lacking backward integration into captive resin production. Distribution runs through municipal contractor networks in infrastructure segments and dealer-retail channels for residential plumbing replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Lead and Copper Rule revisions and India's Jal Jeevan Mission implementation create structurally mandated replacement demand that outpaces organic construction cycles.
For Market Incumbents: Lock in resin supply security through backward integration into compounding facilities or long-term offtake agreements with Gulf Coast and Pearl River Delta petrochemical producers. Secure BIS, NSF/ANSI 61, and WRAS certification portfolios ahead of multi-jurisdictional tender requirements that compress supplier bases in Saudi Arabia's Qiddum and India's Smart Cities Mission.
For New Entrants and Emerging Players: Multilayer composite pipe systems incorporating aluminum or fiberglass reinforcement layers offer technology-first entry points into seismic-zone water transmission mains previously held by ductile iron. Target trenchless rehabilitation contractor networks in dense urban US and European corridors where fusion-welded HDPE joint integrity commands premium positioning and training bottlenecks limit incumbent capacity expansion.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with distribution density in single-country markets and undeveloped resin-compounding capabilities. Five-to-ten-year viability hinges on formulation flexibility under divergent regulatory regimes rather than scale alone. Watch for MEE enforcement actions on recycled content minimums as the inflection signal for post-industrial regrind integration premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Secures formulation flexibility under ECHA REACH and China's GB standards evolution. |
| Multi-Jurisdictional Certification Investment | Unlocks consolidated procurement by Saudi Arabia's national water utility and India's Jal Jeevan Mission. |
| Trenchless Technology Capability Buildout | Captures directional drilling specifications in Chicago, Los Angeles, and Qiddum infrastructure awards. |
| Recycled Content Integration Programs | Aligns with China's dual carbon goals and EU Green Deal recyclable polymer mandates. |
| Fusion Welding Training Pipeline Expansion | Resolves technician certification bottlenecks constraining HDPE infrastructure project velocity. |
Research Methodology
Multiple input streams — primary interviews with municipal procurement officers, resin compounding plant managers, and trenchless rehabilitation contractors; secondary validation through customs trade data, BIS certification registries, and SEC filings from integrated pipe manufacturers; plus technical literature on cross-linked polyethylene formulation advances — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, material grade, application pressure class, and end-user warranty requirements generated volume and value outputs throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macro infrastructure spending trajectories, with specific inputs including EPA lead service line replacement timelines and India's National Mission for Sustainable Agriculture micro-irrigation penetration targets.
The model holds under stable resin feedstock pricing and continued regulatory enforcement of potable water contact standards; deviation in crude oil volatility or certification regime fragmentation would shift trajectory bounds. Forecasts reflect documented assumptions on infrastructure spending prioritization and recycled content mandate implementation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
FRP Pipes and Tanks Market
Pipes and Tubes
Pipes and Fittings Market
Pipes and Tubes
Glass Reinforced Plastic (GRP) Piping Market
Pipes and Tubes
Reinforced Thermoplastic Pipes Market
Pipes and Tubes
PVC Pipes Market
Pipes and Tubes
Steel Pipes and Tubes Market
Pipes and Tubes
Steel Tubes Market
Pipes and Tubes
Global Polyethylene Pipes and Fittings Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Industrial Tubes Market
Pipes and Tubes
OCTG Pipe Market
Pipes and Tubes
Gas Fittings and Components Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
Global Flexible Pipes Market