
 Global Lance Tubes Market | 2026-2036
Global Lance Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lance Tubes Market Foresight
Advanced ceramic coating deposition on refractory substrates is reshaping lance tube durability and thermal performance in extreme furnace environments. Sandvik (Kanthal) leverages its Kanthal alloy portfolio to dominate high-temperature oxygen lance applications across European steelworks. Oxylance anchors North American market presence through specialized combustion lance systems for foundry and scrap metal processing. Yong Steel competes aggressively on cost-optimized carbon steel lance tubes serving Southeast Asian smelting operations.
Lance tubes are hollow cylindrical conduits, typically 50–300 mm in diameter and 3–12 meters in length, engineered to inject gases, liquids, or powdered reagents into molten metal baths, chemical reactors, and waste incineration chambers at operating temperatures exceeding 1,600°C. Stainless steel and nickel alloy constructions dominate steel production applications where thermal shock resistance and oxidation prevention determine service life. Oxygen lance tubes command premium positioning due to their critical role in basic oxygen furnace steelmaking, while composite lance tubes represent the fastest-growing material category as layered ceramic-metal architectures extend replacement intervals. Chemical processing and waste treatment applications favor carbon steel and aluminum alloy variants where corrosive reagent compatibility and cost efficiency outweigh extreme temperature demands.
EPA emissions standards for iron and steel facilities in the United States mandate cleaner combustion processes that directly increase demand for precision-engineered oxygen and steam lance tubes. REACH compliance in Europe restricts certain refractory coating chemistries, pushing manufacturers toward ECHA-registered alternative formulations. Japan's METI energy efficiency benchmarks and China's MEE environmental enforcement both tighten furnace performance requirements, creating dual regulatory pressure for lance tube upgrades. Stakeholders must monitor evolving alloy certification standards and carbon border adjustment mechanisms to align procurement strategies with compliance timelines.
Market Dynamics
Decarbonization mandates across steel-producing economies are forcing furnace operators to replace conventional lance tubes with precision-engineered oxygen injection systems capable of sustaining higher thermal loads and cleaner combustion profiles.
Growth Catalysts
- EU Green Deal compliance deadlines:German and Italian steelworks are accelerating oxygen lance tube procurement to meet mandated carbon intensity reductions in basic oxygen furnace operations.
- India's integrated steel corridor expansion:New blast furnace investments in Odisha and Jharkhand are generating concentrated demand for high-durability lance tube installations.
- Ceramic-metal composite architectures:Layered refractory coatings on nickel alloy substrates are extending replacement intervals and reducing unplanned furnace downtime.
Market Restraints
- Nickel and chromium price volatility:Input cost swings for austenitic stainless steel alloys compress margin visibility for lance tube fabricators.
- Supply concentration in specialty refractory coatings:European coating deposition capacity limits constrain output scaling for premium ceramic-lined products.
- REACH chemical restrictions:ECHA-registered alternative formulations require multi-year validation cycles before furnace deployment approval.
Strategic Opportunities
- Vietnam's emerging steel capacity:Greenfield electric arc furnace installations create first-mover positioning for combustion lance system suppliers.
- Hydrogen-ready furnace retrofits:Dual-fuel oxygen lance designs compatible with hydrogen injection protocols address Japan's METI efficiency benchmarks.
- Digital thermal monitoring integration:Embedded sensor arrays in lance tube walls enable predictive maintenance contracts and recurring revenue streams.
Industry Challenges
- Refractory metallurgist scarcity:Specialized expertise in high-temperature alloy behavior remains concentrated among retiring workforce cohorts in Pittsburgh and Sheffield.
- Multi-jurisdictional certification timelines:Parallel EPA emissions compliance and CE marking processes delay North American product introductions by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lance Tubes Market |
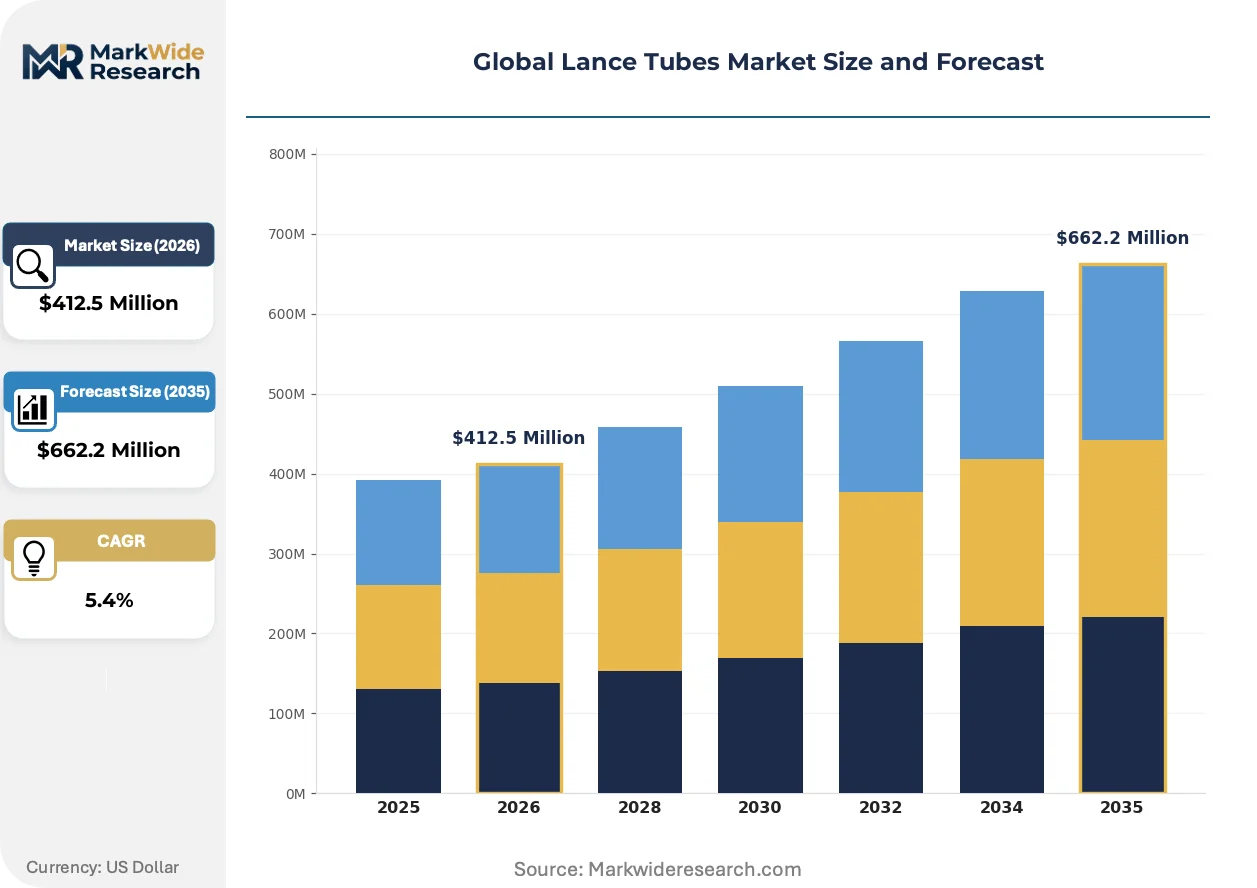
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Lance Tubes, Steam Lance Tubes, Chemical Lance Tubes, Oxygen Lance Tubes, Composite Lance Tubes Material: Stainless Steel, Carbon Steel, Aluminum Alloy, Titanium, Nickel Alloy Application: Steel Production, Chemical Processing, Power Generation, Waste Treatment, Metal Refining End User: Foundries, Smelting Plants, Power Plants, Chemical Manufacturers, Recycling Facilities |
| Companies Covered | Burkle, Giant, Sandvik (Kanthal), Yong Steel, Kraenzle, Oxylance, Bruker, Tubecon, Suttner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lance Tubes Market Shifts & Advancements
Material science breakthroughs and regulatory tightening are converging to redefine lance tube performance specifications, with furnace operators prioritizing thermal efficiency and emissions compliance over upfront equipment cost.
Advanced ceramic coating deposition is migrating from experimental pilot installations to standard specification for basic oxygen furnace lance tubes in European and Japanese steelworks. Sandvik's Kanthal division and specialized refractory contractors are scaling plasma-sprayed alumina-zirconia layer production to meet 18-month replacement cycle demands. This migration from bare alloy to composite architecture is compressing the addressable market for conventional stainless steel tubes while expanding service-contract opportunities for coating refurbishment.
EPA emissions standards for iron and steel facilities are mandating cleaner combustion processes that directly increase specification precision for oxygen and steam lance tubes. The Industrial Emissions Directive corollary in Europe imposes parallel technical requirements through BAT-associated emission levels. Basic oxygen furnace operators in Indiana, Ohio, and Pennsylvania are responding by consolidating procurement around suppliers with demonstrated EPA compliance documentation.
Integrated steel producers are consolidating lance tube procurement under long-term framework agreements with embedded technical support clauses. The spot market for replacement tubes is contracting as Bhilai Steel Plant, Tata Steel Jamshedpur, and comparable facilities shift toward single-source partnerships with predictive inventory management. This consolidation is most visible in India's eastern steel corridor where new blast furnace commissioning timelines demand guaranteed spare parts availability.
Global Lance Tubes Market Segmentation
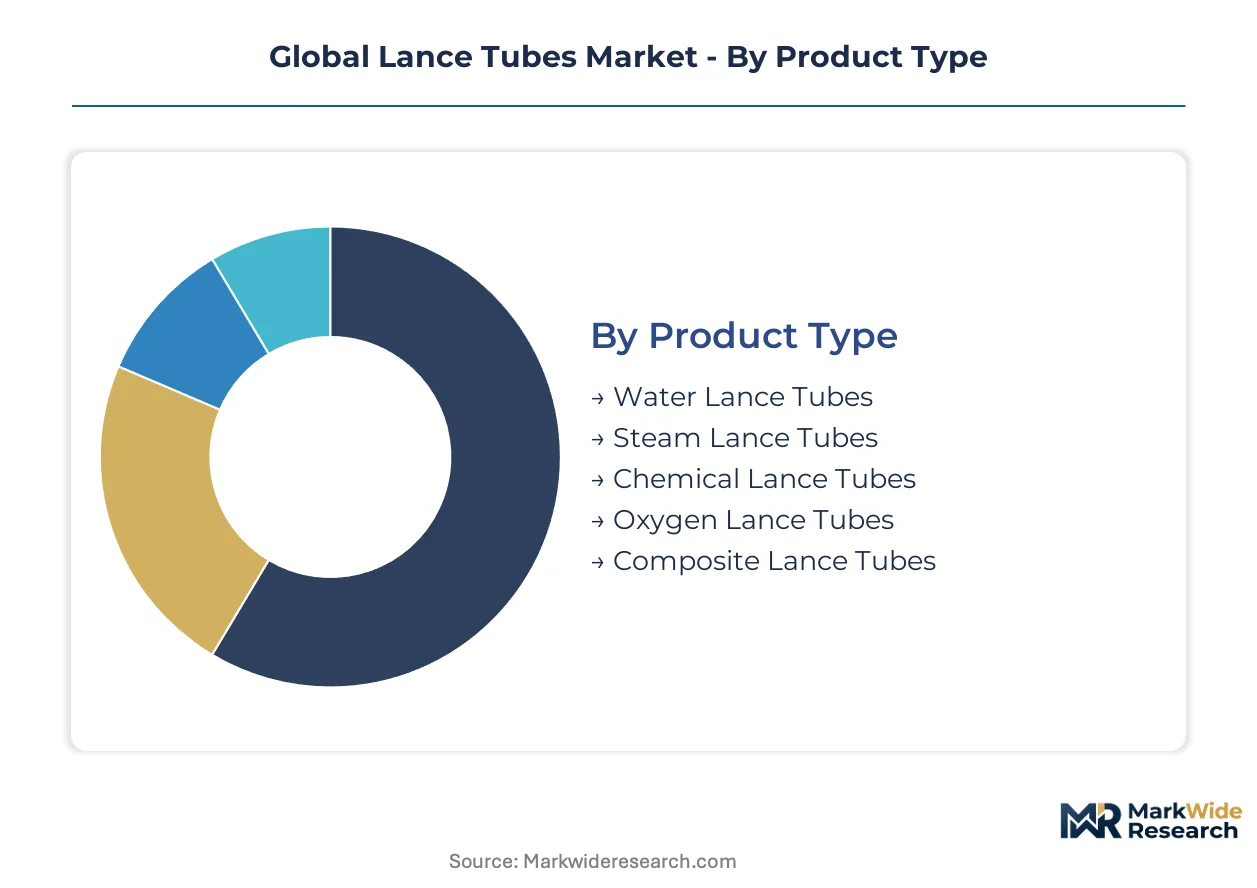
Lance tube procurement patterns diverge sharply across furnace technologies and metallurgical requirements. Material selection and application context determine replacement cycles, thermal performance thresholds, and regulatory compliance burdens for operators.
Product Type:
Mature oxygen injection systems coexist with emerging composite architectures as steelmakers balance proven reliability against extended service life.
- Oxygen Lance Tubes:Hollow cylindrical conduits engineered for high-velocity oxygen injection into basic oxygen furnaces at temperatures exceeding 1,600°C. German and Japanese steelworks under EU Green Deal and METI mandates are accelerating procurement of precision-engineered variants capable of sustaining cleaner combustion profiles. These tubes command premium positioning due to their critical role in decarbonizing steel production.
- Composite Lance Tubes:Layered ceramic-metal architectures featuring plasma-sprayed alumina-zirconia coatings on nickel alloy substrates. Foundries in India's Odisha-Jharkhand steel corridor are specifying these for new blast furnace installations where extended replacement intervals reduce unplanned downtime. This segment is expanding most quickly as coating deposition scales from pilot to standard specification.
- Water Lance Tubes:Carbon steel or stainless steel conduits for cooling and slag control in electric arc furnaces, favored where thermal shock resistance outweighs oxidation resistance.
- Steam Lance Tubes:Alloy constructions designed for steam injection in secondary metallurgy and temperature moderation applications across North American foundries.
- Chemical Lance Tubes:Corrosion-resistant variants for reagent injection in chemical processing and waste incineration where reagent compatibility determines material selection.
Oxygen lance tubes handle the majority of throughput; composite lance tubes are the fastest mover on share.
Material:
Cost tiers separate commodity carbon steel from specialty alloys where thermal performance justifies input price volatility.
- Stainless Steel:Austenitic grades dominate steel production applications where oxidation prevention and thermal shock resistance determine service life. EPA emissions standards in the United States are mandating cleaner combustion processes that increase specification precision for these tubes.
- Nickel Alloy:High-temperature formulations from Sandvik's Kanthal portfolio anchor European oxygen lance applications. REACH compliance restrictions on certain refractory coating chemistries are pushing manufacturers toward ECHA-registered alternative formulations validated for these substrates.
- Carbon Steel:Cost-optimized constructions serving Southeast Asian smelting operations where replacement frequency is managed through volume procurement rather than extended durability.
- Aluminum Alloy:Lightweight variants for chemical processing and waste treatment applications where corrosive reagent compatibility and cost efficiency outweigh extreme temperature demands.
- Titanium:Specialized corrosion-resistant grades for aggressive chemical environments where material inertness prevents reagent contamination.
Stainless steel commands the highest volume; nickel alloy is climbing the fastest as ceramic coating integration accelerates.
Application:
Application context dictates thermal load profiles and regulatory exposure, with steel production facing the most stringent emissions compliance burdens.
- Steel Production:Basic oxygen furnace and electric arc furnace operations consuming oxygen, steam, and composite lance tubes under tightening environmental enforcement. India's integrated steel corridor expansion in Odisha and Jharkhand is generating concentrated demand for high-durability installations.
- Waste Treatment:Incineration and pyrolysis applications favoring carbon steel and aluminum alloy variants where temperature moderation and reagent handling balance equipment cost against throughput requirements.
- Chemical Processing:Reactor injection systems requiring corrosion-resistant materials for aggressive chemistries and continuous operation cycles.
- Power Generation:Boiler and gasification applications utilizing steam and water lance tubes for temperature control and slag management.
- Metal Refining:Secondary metallurgy and foundry operations employing specialized combustion lance configurations for scrap processing and alloy adjustment.
Steel production absorbs the dominant share of premium alloy supply; waste treatment is gaining share fastest as incineration capacity expands under emissions regulations.
End User:
Customer scale determines procurement mode, with integrated producers consolidating under framework agreements while smaller operators remain in spot markets.
- Smelting Plants:Integrated steel producers in Germany, Japan, and India consolidating procurement under long-term agreements with embedded technical support and predictive inventory management.
- Foundries:Scrap metal processors and secondary metallurgy operators in North America sourcing specialized combustion lance systems from regional suppliers with EPA compliance documentation.
- Power Plants:Utility and industrial boiler operators specifying water and steam lance tubes for slag control and thermal efficiency optimization.
- Chemical Manufacturers:Process industry operators prioritizing reagent compatibility and corrosion resistance in continuous reactor injection applications.
- Recycling Facilities:Waste-to-energy and metal recovery operations balancing equipment cost against regulatory compliance for emissions and throughput.
Smelting plants drive the bulk of premium specification demand; foundries are shifting fastest toward consolidated procurement partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German steel mills export precision-engineered oxygen lance systems to blast furnace operators across India's eastern steel corridor, establishing a trade corridor that channels European coating technology toward Asia's fastest-expanding smelting capacity.
United States
Foundries in Indiana, Ohio, and Pennsylvania drive combustion lance procurement as EPA emissions standards tighten furnace performance requirements. The Industrial Emissions Directive corollary shapes technical specifications for equipment imports. Pittsburgh anchors domestic refractory metallurgist expertise, though workforce retirement threatens specialized knowledge transfer.
Germany
ThyssenKrupp and Salzgitter AG accelerate oxygen lance tube procurement to meet EU Green Deal carbon intensity deadlines. REACH compliance restricts certain refractory coating chemistries, pushing manufacturers toward ECHA-registered alternatives. The Ruhr industrial cluster concentrates high-temperature alloy fabrication capacity for export markets.
Japan
Nippon Steel and JFE Holdings source dual-fuel oxygen lance designs compatible with hydrogen injection protocols under METI efficiency benchmarks. The Kansai steel belt around Osaka and Kobe generates concentrated demand for ceramic-lined composite architectures. Domestic coating deposition capacity limits constrain premium product scaling.
India
Tata Steel Jamshedpur and Bhilai Steel Plant consolidate procurement under long-term framework agreements with predictive inventory management. The Odisha-Jharkhand integrated steel corridor generates the fastest-expanding demand for high-durability lance tube installations. New blast furnace commissioning timelines demand guaranteed spare parts availability from regional distributors.
Vietnam
Greenfield electric arc furnace installations at Formosa Ha Tinh and Hoa Phat Group create first-mover positioning opportunities for combustion lance system suppliers. The country's national environmental regulator tightens industrial emissions enforcement. Northern industrial zones around Hai Phong concentrate emerging steel capacity with European technology partnerships.
Global Lance Tubes Market Competitive Landscape
On the supply side, the industry is bifurcated between premium alloy specialists and cost-optimized carbon steel fabricators. European and Japanese manufacturers anchor the high-temperature segment through proprietary coating deposition capabilities. Three strategic archetypes dominate: vertically integrated refractory-metallurgy hybrids, regional volume producers, and specialized combustion system integrators. Capacity expansion and technology licensing represent the dominant competitive moves as players address coating deposition bottlenecks.
Within the premium alloy tier, Sandvik (Kanthal) exemplifies the vertically integrated archetype through its Swedish metallurgy heritage and Kanthal alloy portfolio. Oxylance occupies a position among North American specialists focused on combustion lance configurations. Yong Steel represents the cost-optimized Asian fabricator archetype, anchoring competitive dynamics in Southeast Asian smelting procurement.
| Leading Market Players |
|---|
| Burkle |
| Giant |
| Sandvik (Kanthal) |
| Yong Steel |
| Kraenzle |
| Oxylance |
| Bruker |
| Tubecon |
| Suttner |
| Others |
Supply & Pricing Matrix
The Ruhr industrial cluster's coating deposition capacity constraints compress premium ceramic-lined lance tube availability, transferring pricing power to Sandvik and specialized European refractory contractors serving German and Japanese steelworks under EU Green Deal and METI mandates.
Pricing Analysis
Next-generation ceramic-metal composite lance tubes command substantial premiums over bare stainless steel and carbon steel constructions still prevalent in Southeast Asian smelting operations. Pricing stratifies across premium, standard, and economy tiers based on coating certification grade and thermal performance guarantees. Cost compression in the carbon steel segment intensifies because Yong Steel and regional Asian fabricators compete on volume procurement contracts. Foundries and scrap metal processors in North America exhibit highest price sensitivity, while integrated steel producers in India and Germany prioritize replacement interval guarantees over unit cost.
Supply Chain Analysis
Nickel ore feedstock draws from Indonesian and Philippine mining operations, while chromium sourcing centers on South African and Turkish deposits. High-temperature alloy production concentrates in Sweden, Germany, and Japan, with coating deposition capacity limited to European specialists and select Japanese contractors. Single-source vulnerability in alumina-zirconia refractory coating supply creates bottleneck risk for composite lance tube scaling. Distribution runs through long-term framework agreements with embedded technical support, displacing spot market transactions among integrated steel producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized refractory metallurgist expertise is retiring from Pittsburgh and Sheffield workforce cohorts faster than knowledge transfer systems can replicate it, creating a capability gap that constrains premium lance tube development and coating validation cycles.
For Market Incumbents: Insulate proprietary coating deposition know-how through captive training programs and exclusive partnerships with Ruhr-based technical universities. Backward integration into nickel alloy substrate production secures margin visibility against chromium price volatility. Defend against emerging Asian composite fabricators by accelerating ECHA-registered alternative formulation validation ahead of REACH compliance deadlines. For New Entrants and Emerging Players: Build out combustion lance system capabilities targeting Vietnam's greenfield electric arc furnace installations at Formosa Ha Tinh and Hoa Phat Group, where European technology partnerships create reference customer pathways. Foundry and scrap metal processing applications in North America offer penetrable entry points given EPA emissions standard complexity that favors specialized regional suppliers with demonstrated compliance documentation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated refractory-metallurgy hybrids with proprietary alloy portfolios and coating deposition capabilities. Long-term viability hinges on hydrogen-ready furnace retrofit exposure and digital thermal monitoring integration potential. Watch for inflection signals in Japan's METI efficiency benchmark enforcement timelines and ceramic coating standardization across European basic oxygen furnace specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Deposition Capacity Expansion | Plasma-sprayed alumina-zirconia scaling addresses 18-month replacement cycle demands from German steelworks. |
| Dual-Fuel Lance Design Development | Hydrogen injection compatibility aligns procurement with Japan's METI efficiency benchmarks and EU Green Deal trajectories. |
| Digital Thermal Monitoring Integration | Embedded sensor arrays enable predictive maintenance contracts and recurring revenue streams beyond equipment sales. |
| Long-Term Framework Agreement Consolidation | Predictive inventory management partnerships with Tata Steel Jamshedpur and Bhilai Steel Plant displace spot market fragmentation. |
| Refractory Metallurgist Workforce Development | Specialized training programs counter retiring expertise concentration in Pittsburgh and Sheffield industrial clusters. |
Research Methodology
A spread of perspectives from plant engineers at integrated steel producers, procurement leads at foundry operators, refractory coating specialists, and aftermarket service directors converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC filings of listed metallurgy companies, customs trade data tracking nickel alloy and refractory material flows, and EPA emissions compliance documentation. Bottom-up installation forecasts and top-down steel production capacity triangulation anchored volume estimates across the analysis window.
Demand-supply-balance modeling tracked oxygen lance tube consumption against basic oxygen furnace and electric arc furnace commissioning timelines, segmented by material tier, coating architecture, and end-use application. CAGRs derived from regression analysis of replacement cycle compression, regulatory mandate enforcement intensity, and coating technology adoption curves. Forecast inputs incorporated REACH chemical restriction timelines, India's integrated steel corridor expansion schedules, and hydrogen-ready furnace retrofit penetration assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese composite fabricators or accelerated ECHA alternative formulation approvals would shift outcomes. Cross-checking against steel production capacity databases and blast furnace commissioning announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
ESR Tubes Market
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
Pipes and Fittings Market
Pipes and Tubes
Steel Roll-On Tube Market
Pipes and Tubes
Aluminium Tubes for OPC Drum Market
Pipes and Tubes
Pneumatic Fittings Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
Global Polyethylene Pipes and Fittings Market
Pipes and Tubes
China Industrial Hoses Market
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market
Pipes and Tubes
Oman PVC Pipes Market
Pipes and Tubes
PVC Pipes and Fittings Market
Pipes and Tubes
Tapping Sleeves Market
Pipes and Tubes
Polyethylene Pipes Market