
 Cold Drawn Seamless (CDS) Steel Pipes Market | 2026-2036
Cold Drawn Seamless (CDS) Steel Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Drawn Seamless (CDS) Steel Pipes Market Insights
Carbon fiber-reinforced polymers is decoupling from CDS steel pipes in certain low-pressure automotive applications, though CDS retains dominance in high-stress environments. Tenaris leverages integrated seamless pipe mills across the Americas to sustain cost advantages in OCTG grades. Nippon Steel Corporation anchors Japanese supply chains with proprietary heat-treatment protocols for ultra-high-strength variants. Vallourec differentiates through premium threading technologies that command pricing power in sour-service well conditions.
Cold drawn seamless steel pipes are hollow cylindrical sections produced by drawing a solid billet through a die at ambient temperature, yielding dimensional tolerances within 0.1 mm wall thickness and superior surface finish versus hot-finished alternatives. Their primary purpose is to transport pressurized fluids, withstand cyclic mechanical loads, and maintain structural integrity in extreme thermal environments across energy and mobility systems. Hydraulic tubes lead product-type demand due to precision requirements in mobile machinery, while heat exchanger tubes represent the fastest-expanding category as power utilities retrofit condenser systems. Small-diameter CDS pipes command concentrated margin pools in aerospace fuel-line applications where lot traceability and ultrasonic testing certification create supply scarcity.
API 5CT standards administered by the American Petroleum Institute govern chemical composition and mechanical testing for oil-country tubular goods, directly shaping procurement specifications for Permian Basin operators. ASME Boiler and Pressure Vessel Code Section II and ASTM A519 specifications define allowable stress limits and non-destructive examination protocols that determine market access for North American fabricators. China's GB/T 8162 and GB/T 8163 national standards, enforced by SAMR, set competing benchmarks for structural and fluid-transport grades in Asian project specifications. Stakeholders must monitor divergence between API and GB testing protocols when qualifying dual-source supply chains for multinational infrastructure projects.
Market Dynamics
API 5CT material traceability mandates and sour-service well proliferation are compressing supplier qualification timelines while fragmenting procurement pools across Permian Basin operators and Gulf Coast refiners.
Growth Catalysts
- Permian Basin high-pressure completions:Oil and gas operators are expanding CDS pipe procurement for well depths exceeding 15,000 feet where burst resistance and fatigue life dominate specification sheets.
- ASME Section II stress limits:Tighter allowable stress calculations for boiler and pressure vessel applications are disqualifying hot-finished alternatives in North American power generation retrofits.
- Carbon fiber substitution limits:CFRP decoupling from low-pressure automotive lines preserves CDS dominance in chassis and suspension systems where impact loading cycles exceed polymer fatigue thresholds.
Market Restraints
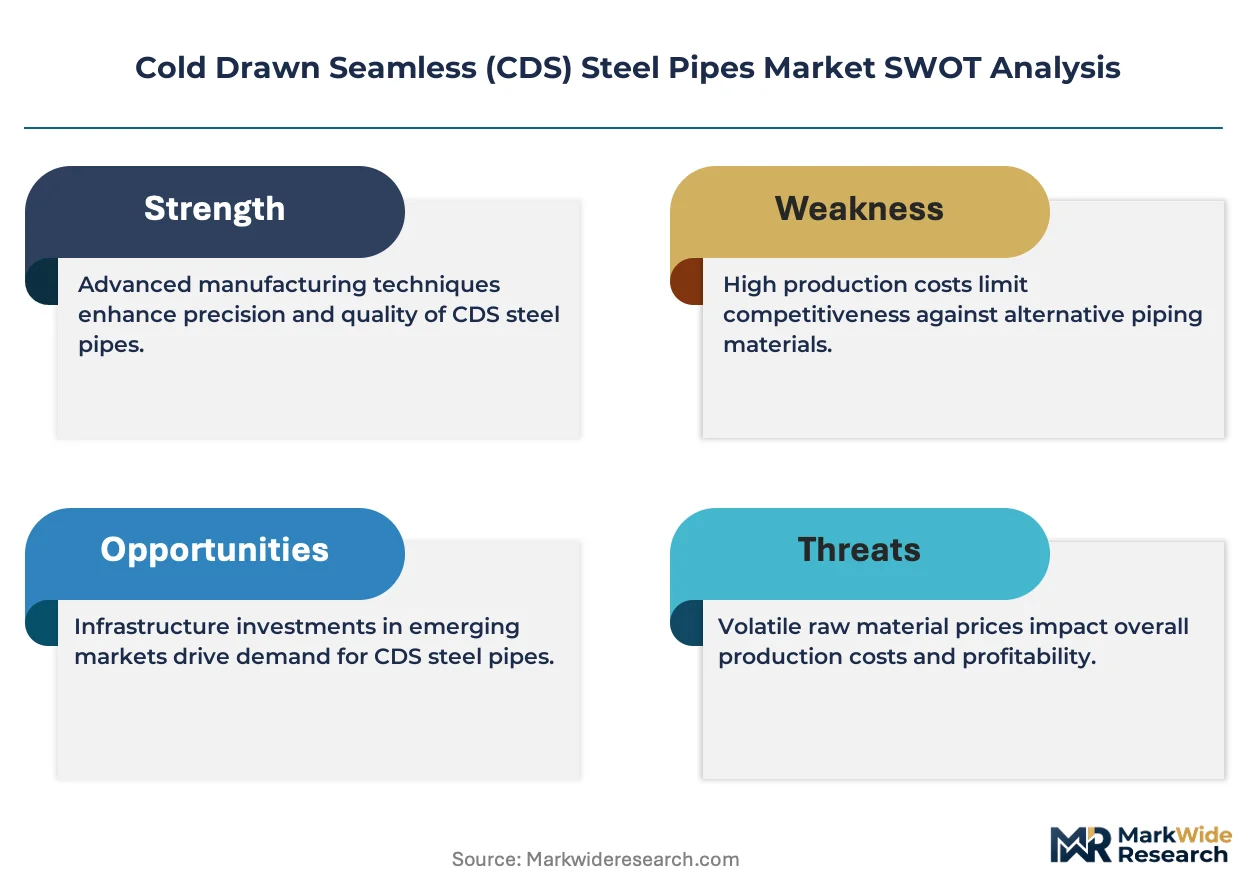
- Scrap steel volatility:Electric arc furnace feedstock costs swing with Turkish export tariffs and Chinese import quotas, compressing mill margin visibility for OCTG-grade producers.
- Japanese supply concentration:Proprietary heat-treatment IP for ultra-high-strength variants concentrates in Nagoya and Kobe mill complexes, creating single-source risk for aerospace fuel-line specifications.
- Carbon fiber creep limitations:Polymer matrix relaxation under sustained tensile load blocks CFRP substitution in pressurized hydrogen storage tubes above 700 bar.
Strategic Opportunities
- Indian nuclear condenser retrofits:CEA mandating stainless-clad CDS tubes for pressurized heavy water reactor steam generators opens specification windows for ASME-certified foreign suppliers.
- Hydrogen infrastructure tubing:700-bar automotive fueling stations and pipeline conversion projects require seamless high-pressure manifolds with hydrogen embrittlement-resistant microstructures.
- Direct mill-to-fabricator platforms:Digital procurement channels bypassing distributor markups are capturing share among mid-size Permian drilling contractors seeking lot-traceable API 5CT stock.
Industry Challenges
- Ultrasonic technician scarcity:API 5CT and ASTM A519 certification requirements for phased-array inspection exceed training pipeline output, extending order-to-ship timelines for aerospace and nuclear grades.
- Dual-standard qualification burden:Multinational projects requiring concurrent API and GB/T 8162 testing protocols force duplicate metallurgical runs, inflating non-recurring engineering costs for Asian-European supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Drawn Seamless (CDS) Steel Pipes Market |
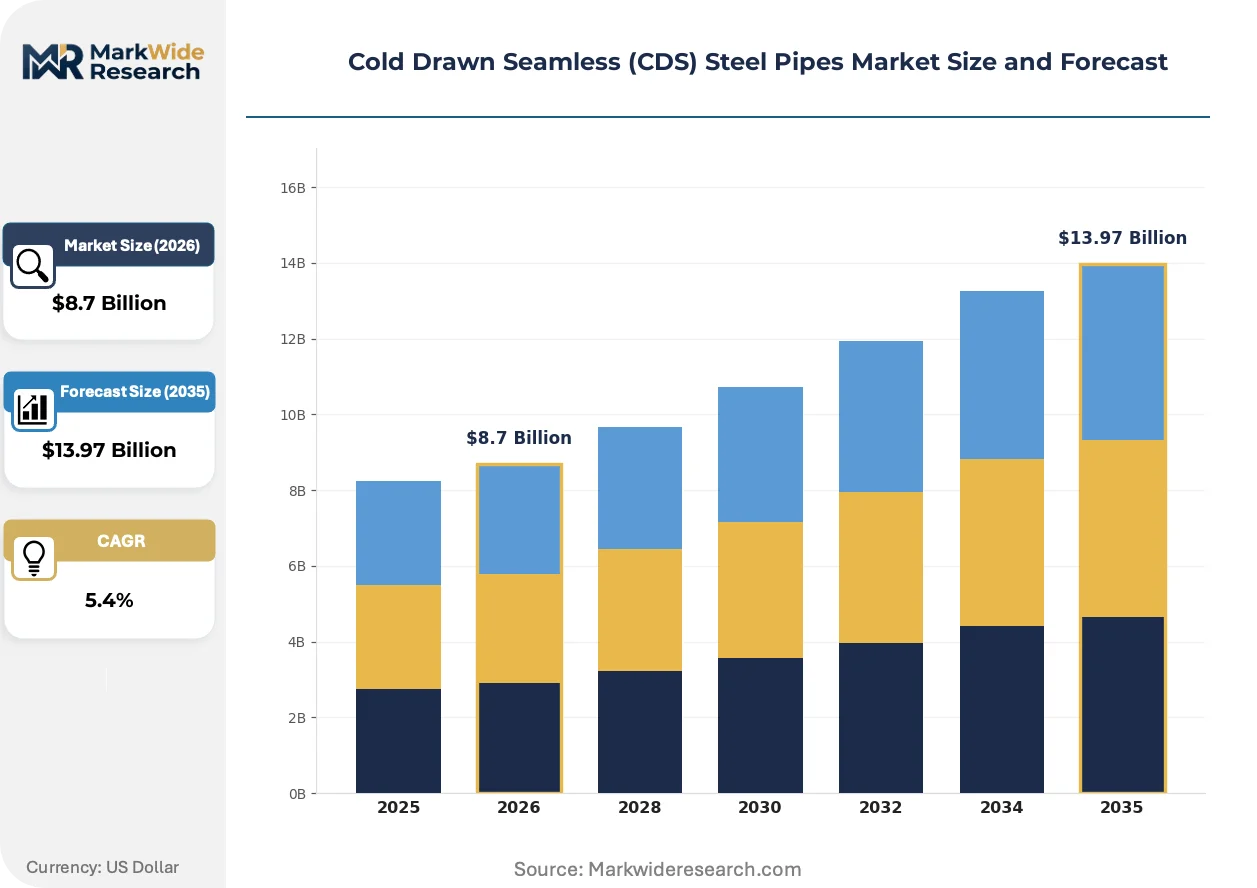
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Tubes, Structural Pipes, Heat Exchanger Tubes, Line Pipes End Use Industry: Oil & Gas, Construction, Automotive, Aerospace Manufacturing Stage: Raw Material Procurement, Processing, Fabrication, Quality Control Diametric Size: Small Diameter, Medium Diameter, Large Diameter, Extra Large Diameter |
| Companies Covered | Tenaris, Vallourec, Nippon Steel Corporation, JFE Steel Corporation, United States Steel Corporation, TMK Group, Sandvik AB, Maharashtra Seamless Ltd, Baosteel Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Drawn Seamless (CDS) Steel Pipes Market Trends and Innovations
Precision forming technologies and digital traceability systems are compressing dimensional tolerances while hardening supply chain audit requirements across energy and mobility end-uses.
Hybrid laser-arc welding of seamless pipe preforms is electrifying near-net-shape production for thick-wall OCTG grades. Permian operators adopting these tubes report reduced thread galling and improved make-and-break performance in extended-reach horizontals. The technology is electrifying cost structures by cutting intermediate heat-treatment cycles and reducing billet oversize requirements.
REACH SVHC disclosure requirements and EU Carbon Border Adjustment Mechanism transitional reporting are forcing mill-level emissions accounting for CDS exports into Rotterdam and Hamburg. European distributors now require ISO 14064-verified carbon footprints for API 5CT grades, compressing supplier lists to integrated mills with captive energy recovery. German KBA automotive certification has extended this mandate to chassis tubing, privileging electric-arc-furnace producers with renewable power purchase agreements.
Specification-driven vendor consolidation is concentrating procurement authority among supermajor engineering-procurement-construction firms. Tier-one oilfield service companies now mandate API 5CT monogramming plus mill-direct heat-treatment records, disintermediating spot-market distributors. This pattern is most visible in US Gulf Coast LNG liquefaction train construction, where Bechtel and McDermott qualification protocols exclude non-integrated pipe suppliers lacking in-house threading and inspection capabilities.
Cold Drawn Seamless (CDS) Steel Pipes Market Segmentation
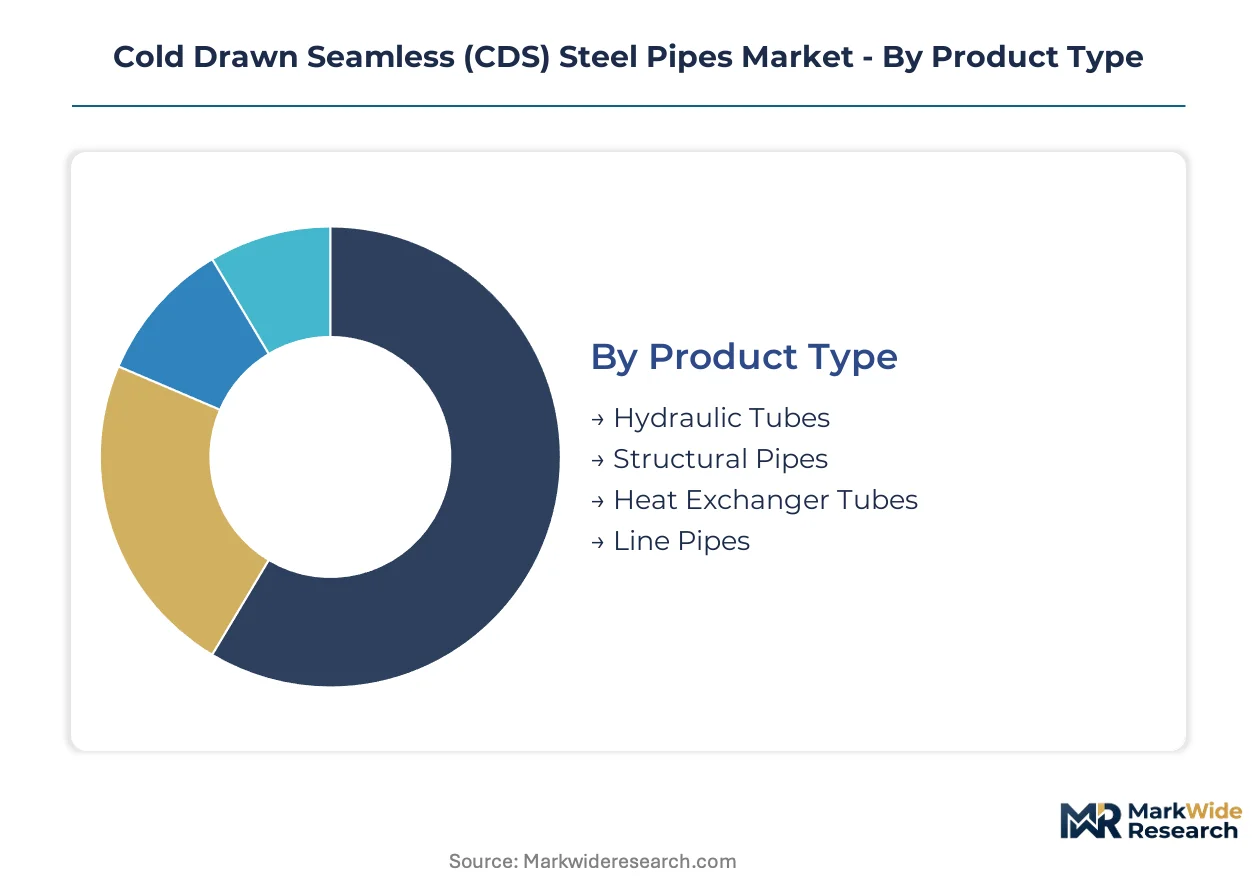
Cold drawn seamless steel pipes serve divergent performance requirements across energy infrastructure and precision engineering. Specification differentiation creates distinct margin pools and qualification barriers that reshape competitive positioning.
Product Type:
Supply concentration clusters around precision-forming capabilities and end-use certification intensity.
- Hydraulic Tubes:These pipes maintain dimensional tolerances within 0.1 mm wall thickness for fluid power transmission. Mobile machinery OEMs in Germany and the United States specify these for excavator boom circuits where fatigue resistance dominates procurement criteria.
- Heat Exchanger Tubes:Condenser retrofit demand from power utilities drives specification evolution. ASME Section II stress calculations now disqualify welded alternatives in North American nuclear steam generator replacements.
- Structural Pipes:GB/T 8162 compliance governs Asian construction project acceptance.
- Line Pipes:API 5CT monogramming remains mandatory for Permian Basin high-pressure completions.
Today's leader: Hydraulic Tubes. Tomorrow's challenger: Heat Exchanger Tubes.
End Use Industry:
Cost tier differentiation separates specification-heavy energy applications from volume-driven construction demand.
- Oil & Gas:OCTG grades for sour-service wells require proprietary heat-treatment protocols and mill-direct traceability. Permian operators now mandate lot-tracked API 5CT stock for depths exceeding 15,000 feet.
- Aerospace:Small-diameter fuel lines demand ultrasonic testing certification and complete metallurgical documentation. Japanese mill complexes concentrate supply for ultra-high-strength variants.
- Automotive:Chassis and suspension systems preserve CDS dominance where impact loading exceeds carbon fiber fatigue thresholds.
- Construction:Structural grades compete on mill proximity and distributor availability rather than certification intensity.
Volume concentrates in Oil & Gas. Value migrates toward Aerospace.
Manufacturing Stage:
Application-specific quality thresholds fragment process control requirements across customer tiers.
- Quality Control:Phased-array ultrasonic inspection certification now exceeds training pipeline output, extending lead times for aerospace and nuclear grades.
- Processing:Cold drawing at ambient temperature yields surface finishes superior to hot-finished alternatives.
- Raw Material Procurement:Electric arc furnace feedstock volatility compresses margin visibility for OCTG producers.
- Fabrication:Premium threading technologies command pricing power in sour-service well conditions.
Control intensity peaks at Quality Control. Automation investment flows toward Processing.
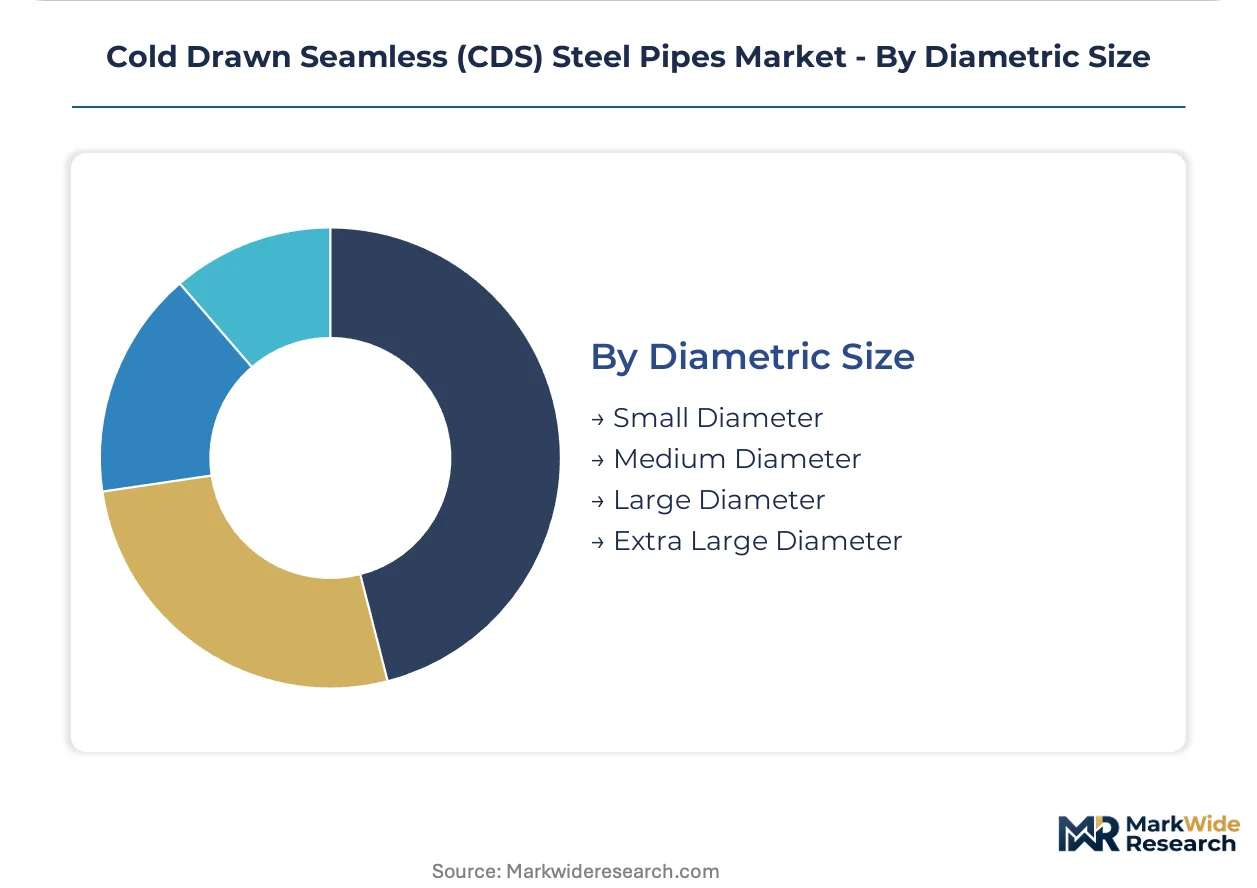
Diametric Size:
Margin structure inverts with diameter — smaller dimensions command scarcity premiums.
- Small Diameter:Aerospace fuel-line applications concentrate margin pools where lot traceability and ultrasonic certification create supply scarcity.
- Medium Diameter:Hydraulic system OEMs specify these for mobile machinery precision circuits.
- Large Diameter:Heat exchanger condenser retrofits drive specification evolution in power generation.
- Extra Large Diameter:Pipeline infrastructure projects compete on tonnage scale and logistics coordination.
Premium capture concentrates in Small Diameter. Expansion volume shifts toward Large Diameter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin shale patch anchors global demand concentration for cold drawn seamless steel pipes, with high-pressure well completions driving specification intensity across North American energy corridors.
United States
Gulf Coast LNG liquefaction train construction and Permian Basin drilling above 15,000 feet dominate procurement volumes. FERC pipeline safety mandates and API 5CT monogramming requirements tighten material traceability rules for domestic fabricators. Houston and Corpus Christi host the densest clustering of OCTG-qualified distributors and threading service providers.
China
Power utility condenser retrofits and nuclear steam generator projects expand specification-grade demand. SAMR enforces GB/T 8162 and GB/T 8163 standards for structural and fluid-transport grades in domestic infrastructure tenders. Shanghai and Tianjin mill complexes concentrate seamless pipe capacity serving both domestic project specifications and export markets.
Japan
Aerospace fuel-line specifications and ultra-high-strength automotive chassis applications preserve premium-tier demand. METI industrial standards and JIS certification protocols govern heat-treatment traceability for critical applications. Nagoya and Kobe mill complexes concentrate proprietary heat-treatment intellectual property for sour-service and high-fatigue grades.
Germany
Mobile machinery OEM hydraulic circuits and automotive chassis systems sustain precision-tube demand. KBA automotive certification and REACH SVHC disclosure requirements now mandate ISO 14064-verified carbon footprints for chassis tubing imports. Ruhr industrial corridor fabricators integrate electric-arc-furnace production with renewable power purchase agreements to meet distributor requirements.
India
Pressurized heavy water reactor steam generator retrofits and refinery expansion projects open specification windows for foreign suppliers. CEA mandates stainless-clad CDS tubes for nuclear condenser applications, requiring ASME Section II compliance. Gujarat and Maharashtra industrial zones concentrate domestic seamless pipe capacity serving infrastructure and energy project demand.
Cold Drawn Seamless (CDS) Steel Pipes Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated mills add seamless pipe capacity to capture API 5CT specification premiums. The vendor base separates into three tiers: multinational integrated producers with captive steelmaking and threading capabilities, regional specialists serving construction-grade structural demand, and precision-focused fabricators targeting aerospace and nuclear certification requirements. Strategic archetypes include backward-integrated energy-grade producers, certification-heavy precision specialists, and scale-driven commodity suppliers. M&A activity concentrates among European and Japanese mills seeking North American OCTG positioning, while technology licensing agreements proliferate for hybrid laser-arc welding of thick-wall preforms.
Among integrated multinational producers, Tenaris and Vallourec exemplify the backward-integrated archetype with seamless pipe mill networks spanning the Americas. Nippon Steel Corporation occupies a position within the certification-intensive tier, representing proprietary heat-treatment capabilities concentrated in Japanese industrial corridors. These three entities anchor distinct competitive vectors: geographic scale, premium threading technology, and ultra-high-strength metallurgical protocols respectively.
| Leading Market Players |
|---|
| Tenaris |
| Vallourec |
| Nippon Steel Corporation |
| JFE Steel Corporation |
| United States Steel Corporation |
| TMK Group |
| Sandvik AB |
| Maharashtra Seamless Ltd |
| Baosteel Group Corporation |
| Others |
Pricing and Supply Chain Analysis
Permian Basin operators mandating lot-tracked API 5CT stock for high-pressure completions are forcing supply chains toward integrated mills with captive threading and inspection capabilities, compressing distributor margins while elevating premium-tier pricing power for qualified producers.
Pricing Analysis
Scrap steel volatility in electric arc furnace feedstock passes through directly to OCTG-grade contract negotiations, with Turkish export tariffs and Chinese import quotas amplifying cost swings. Three-tier pricing structure across premium, standard, and economy levels separates API 5CT monogrammed sour-service grades from structural GB/T 8162 compliance tiers. Price differentiation centers on certification intensity and mill-direct heat-treatment documentation. Pricing pressure stems from carbon fiber substitution in low-pressure automotive lines, though CDS retains pricing power in chassis applications where impact loading exceeds polymer fatigue thresholds. Construction-grade structural buyers exhibit highest price sensitivity, while aerospace fuel-line procurement shows minimal elasticity due to ultrasonic certification scarcity.
Supply Chain Analysis
India's CEA mandating stainless-clad CDS tubes for pressurized heavy water reactor steam generators is redirecting foreign supplier qualification efforts toward ASME-certified mills with domestic fabrication partnerships. Production gravity centers on the United States Gulf Coast corridor, Japanese Nagoya and Kobe mill complexes, and Chinese Shanghai and Tianjin industrial zones. Raw material supply draws from scrap steel brokerage networks, high-grade billet producers, and proprietary alloy formulation houses. Single-source vulnerability concentrates in Japanese heat-treatment IP for ultra-high-strength variants. Distribution runs through mill-direct platforms bypassing traditional distributor markups, particularly among mid-size Permian drilling contractors seeking traceable API 5CT inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as specification intensity migrates toward premium sour-service and hydrogen embrittlement-resistant grades, with API 5CT traceability mandates and ASME Section II stress calculations disqualifying lower-tier alternatives.
For Market Incumbents: Hedge carbon fiber substitution risk in automotive chassis by deepening metallurgical R&D for 700-bar hydrogen storage applications, while securing captive billet supply through backward integration into electric arc furnace feedstock procurement. Tenaris and Vallourec demonstrate geographic scale advantages that emerging competitors cannot replicate without decade-long mill network buildouts. For New Entrants and Emerging Players: The price-point gap between Japanese ultra-high-strength aerospace grades and Chinese GB/T structural compliance tiers offers white-space capture for mid-market precision specialists targeting Indian nuclear condenser retrofits and German mobile machinery hydraulic circuits. Target CEA-mandated ASME certification pathways as the most penetrable specification window, leveraging digital mill-to-fabricator platforms to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-focused fabricators possessing phased-array ultrasonic inspection certification and proprietary threading IP for sour-service conditions. Long-term viability favors entities with demonstrated qualification across dual API and GB/T testing protocols, as multinational infrastructure projects increasingly require concurrent standard compliance. Watch hydrogen infrastructure tubing specifications as the critical inflection signal for premium-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| API 5CT Monogramming Investment | Mill-direct traceability records satisfy Permian operator procurement mandates above 15,000 feet. |
| Hybrid Laser-Arc Welding Adoption | Near-net-shape production cuts heat-treatment cycles for thick-wall OCTG grades. |
| ISO 14064 Carbon Footprint Verification | Renewable power purchase agreements unlock German KBA automotive certification pathways. |
| Phased-Array Ultrasonic Training Pipeline | Certified technician capacity determines lead times for aerospace and nuclear grades. |
| Dual-Standard Qualification Buildout | Concurrent API and GB/T testing capability captures Asian-European multinational project demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OCTG procurement managers at Permian operators, ASME certification engineers at nuclear fabricators, and hydraulic system buyers at German mobile machinery OEMs with secondary validation from API specification bulletins, FERC pipeline safety filings, and EIA energy infrastructure datasets. Bottom-up mill capacity assessments and top-down end-use demand modeling were triangulated against trade flow data and customs records.
Historical reference periods anchored the projection framework, with growth trajectories derived from specification-grade demand evolution across the analysis window. Segmentation dimensions modeled include product type precision tier, end-use certification intensity, manufacturing stage control requirements, and diametric size margin structure. CAGRs were computed from year-over-year progression rates adjusted for scrap steel cost volatility and sour-service well proliferation patterns. Hydrogen infrastructure tubing specifications and Indian nuclear retrofit timelines served as industry-specific demand inflection inputs.
The model assumes a particular technology adoption path for hybrid laser-arc welding and digital traceability platforms; alternative pathways for carbon fiber-reinforced polymer matrix relaxation solutions would alter the outlook for low-pressure automotive substitution. Forecasts reflect assumptions regarding API 5CT traceability mandate enforcement consistency, Turkish scrap export tariff stability, and phased-array technician training pipeline expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Thermoplastic Pipe Market
Pipes and Tubes
HPLC Fused Silica Tube Market
Pipes and Tubes
Global Polyolefin Pipes Market
Pipes and Tubes
GRP Pipe Market
Pipes and Tubes
Fttx Pipes Market
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
PVC Pipes Market
Pipes and Tubes
Europe Pipe Market
Pipes and Tubes
Aluminium Tubes for OPC Drum Market
Pipes and Tubes
Portugal PVC Pipes Market
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
China Industrial Hoses Market
Pipes and Tubes
Gathering Pipeline Market
Pipes and Tubes
Global Polyethylene Pipes and Fittings Market
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market