
 Carbon Steel Market | 2026-2036
Carbon Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Steel Market Intelligence
Value-added services, including customized cutting and just-in-time delivery, is shifting procurement focus from pure price-per-ton metrics to total cost of ownership. ArcelorMittal leverages its extensive global production footprint to serve diverse regional construction standards. China Baowu Group dominates the Asian market through immense production scale and government-backed infrastructure initiatives. Nippon Steel Corporation differentiates through its focus on high-strength steel grades for specialized applications like automotive and shipbuilding.
Carbon steel is an iron-carbon alloy containing up to 2.1% carbon by weight, with trace amounts of other elements. Its primary industrial purpose lies in providing structural strength and durability at a low cost for large-scale projects. Hot rolled products represent the largest volume segment due to their use in construction and heavy machinery. The shipbuilding application segment requires specialized grades of high-tensile strength steel plates, commanding higher margins.
International quality benchmarks like ISO 9001 and specific national standards, such as China's GB standards, govern material specifications and production quality. Emerging environmental regulations, including the EU's Carbon Border Adjustment Mechanism, are introducing carbon-cost considerations into global trade flows. Producers must now decide whether to invest in decarbonization technologies or risk losing access to key export markets.
Market Dynamics
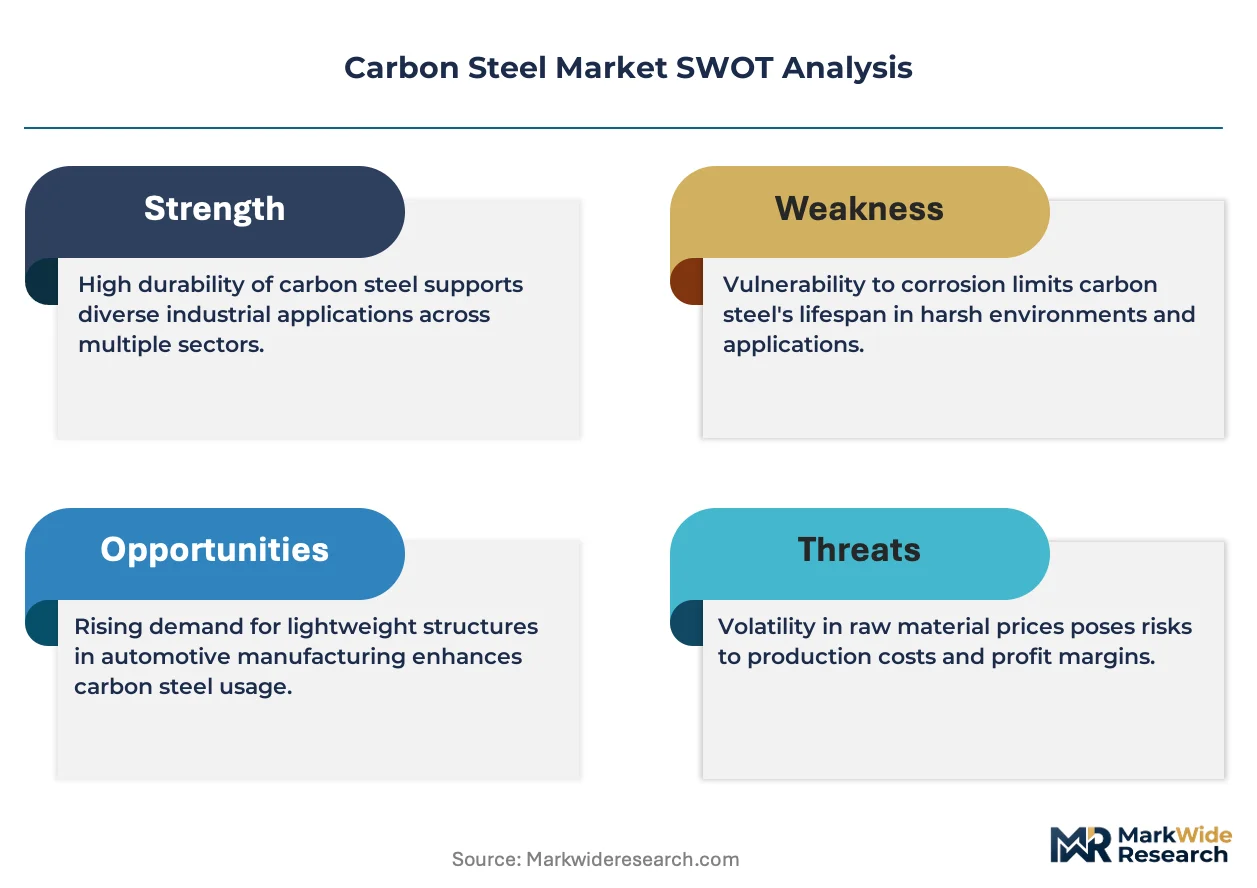
The carbon steel market is defined by a structural tension between large-scale infrastructure demand, which prioritizes low-cost volume, and mounting regulatory pressure for decarbonization. This dynamic forces producers to balance investments in green steel technologies against the price sensitivity of core construction and manufacturing customers.
Growth Catalysts
- Indian Infrastructure Expansion:National investment programs in India, such as the National Infrastructure Pipeline, are fueling substantial demand for structural steel in transportation, urban housing, and energy projects, creating a concentrated demand hub.
- Low-Emission Production Mandates:Policy frameworks like China's dual carbon goals are compelling steelmakers to invest in technologies that reduce emissions, such as electric arc furnaces, which in turn stimulates innovation and equipment upgrades.
- Specialized Marine Applications:The global shipbuilding industry's need for high-tensile strength and corrosion-resistant steel plates for constructing larger container ships and specialized LNG carriers drives demand for higher-margin, value-added products.
Market Restraints
- Input Cost Volatility:Producer margins are consistently exposed to price fluctuations in key raw materials, primarily seaborne iron ore and coking coal, which can disrupt project costing and profitability across the supply chain.
- Carbon Border Tariffs:The European Union's Carbon Border Adjustment Mechanism (CBAM) introduces a direct financial penalty on carbon-intensive steel imports, acting as a significant trade barrier for producers in regions without comparable carbon pricing.
- Material Substitution in Automotive:In the automotive sector, carbon steel faces persistent competition from aluminum alloys and advanced composites, which offer significant weight advantages for electric vehicle body structures and components.
Strategic Opportunities
- Green Steel Premiums:The development of steel produced via hydrogen-based direct reduced iron (H-DRI) and renewable-powered EAFs creates an opportunity to establish a premium market segment for certified low-carbon or zero-carbon steel products.
- Southeast Asian Modernization:Underpenetrated markets in Southeast Asia, including Vietnam and Indonesia, present significant growth potential as they undertake major public works projects to upgrade transportation and utility infrastructure.
- Carbon Capture Infrastructure:The build-out of carbon capture, utilization, and storage (CCUS) systems requires vast quantities of specialized steel for pipelines, pressure vessels, and structural components, opening a new industrial end-market.
Industry Challenges
- Decarbonization Capital Costs:The transition from traditional blast furnaces to lower-emission alternatives like electric arc furnaces or DRI plants requires massive, long-term capital investment that strains the financial capacity of many producers.
- Advanced Metallurgy Skill Gaps:A shortage of process engineers and metallurgists with expertise in operating next-generation steelmaking technologies and digital process controls hinders the efficient deployment of innovative production methods.
- Fragmented Green Certification:Producers face complexity in navigating a growing but inconsistent landscape of environmental product declarations (EPDs) and green building standards, which vary significantly by country and region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Steel Market |
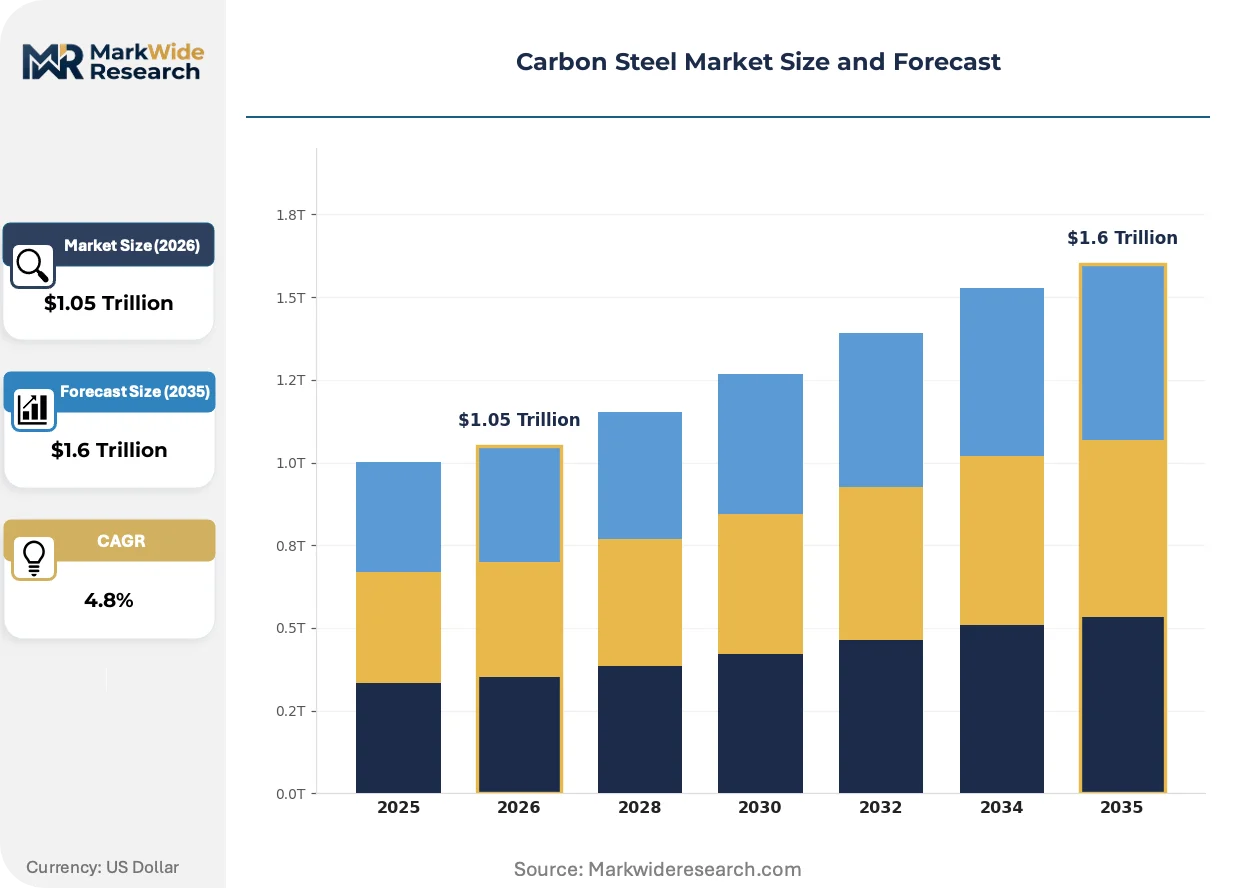
| Market Size in 2026 | $1.05 Trillion |
| Market Size in 2035 | $1.6 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Rolled, Cold Rolled, Galvanized, Annealed, Tempered Application: Construction, Shipbuilding, Machinery Manufacturing, Oilfield Equipment, Agricultural Implements End User: Fabricators, Heavy Equipment Manufacturers, Pipeline Suppliers, Structural Workshops Form: Coils, Sheets, Plates, Bars, Tubes |
| Companies Covered | Nippon Steel Corporation, Shagang Group, China Baowu Group, POSCO Holdings, Jianlong Group, ArcelorMittal, HBIS Group, Shougang Group, Ansteel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Steel Market Strategic Shifts & Innovations
The competitive landscape is being reshaped by the imperative to quantify and reduce embodied carbon. This shift transforms steel from a simple commodity into a material defined by its production process and environmental footprint, influencing everything from plant technology to international trade policy.
Electric Arc Furnace (EAF) technology is a primary method for lower-emission steel production. Adopted by producers seeking to reduce reliance on coal and utilize scrap steel, EAFs are gaining share over traditional blast furnaces. This transition is electrifying the manufacturing base, making steel production increasingly dependent on electricity grid stability, renewable energy availability, and the quality of recycled scrap feedstock.
The EU's Carbon Border Adjustment Mechanism (CBAM) is a pivotal regulatory development with global reach. It imposes a levy on imported goods, including steel, based on their embedded carbon emissions, effectively extending EU carbon pricing beyond its borders. This policy most directly impacts major steel exporters to Europe, such as those in Turkey and India, forcing them to accelerate decarbonization investments to maintain market access.
A notable shift in purchasing criteria is occurring, especially in regulated industries. Buyers for public infrastructure and automotive projects are increasingly specifying steel based on its certified carbon footprint, documented through Environmental Product Declarations (EPDs). This move away from price-only decisions is most prominent in European and North American markets, creating demand for traceable, low-carbon supply chains.
Carbon Steel Market Segmentation
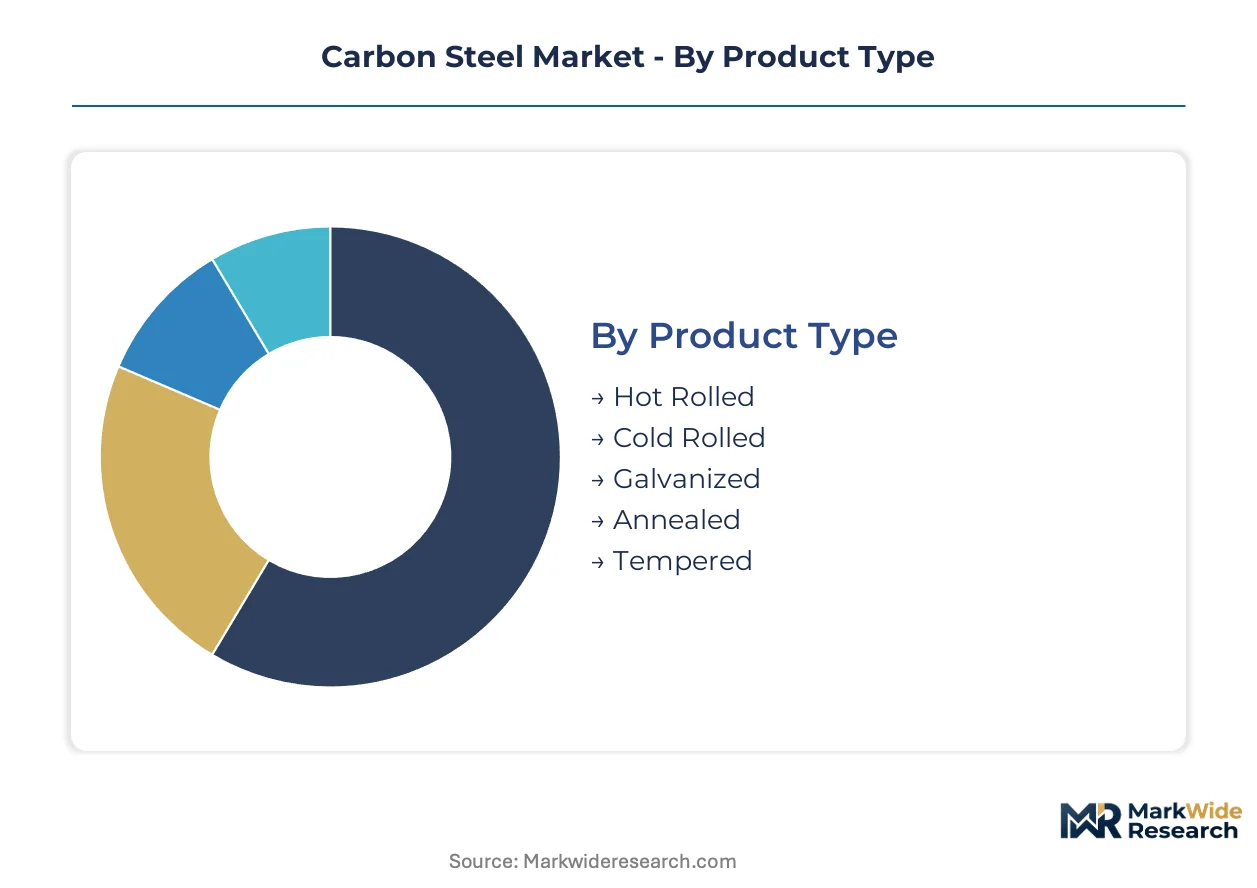
The carbon steel market features diverse product forms and end-use requirements. Understanding these segments clarifies demand drivers and production priorities. Distinct material specifications and processing methods dictate market sub-structures.
Product Type:
Carbon steel product types bifurcate into high-volume, low-cost options and specialized, higher-margin offerings.
- Hot Rolled:Hot rolled products are formed at high temperatures, allowing for easier shaping and larger deformations. Demand concentrates in infrastructure projects and heavy machinery, driven by its low production cost and structural integrity.
- Galvanized:Galvanized steel features a protective zinc coating, providing enhanced corrosion resistance. Construction and automotive applications in coastal regions or harsh environments drive demand for this durable product.
- Cold Rolled:Cold rolled steel offers improved surface finish and dimensional accuracy for automotive panels and appliances.
- Annealed:Annealed steel undergoes heat treatment to increase ductility and reduce hardness for deep drawing operations.
- Tempered:Tempered steel is heat-treated to enhance toughness and reduce brittleness for spring components.
Today's leader: Hot Rolled. Tomorrow's challenger: Galvanized.
Application:
Diverse applications dictate specific material properties and processing requirements for carbon steel.
- Construction:Construction applications utilize carbon steel for structural beams, rebar, and plates, providing foundational strength for buildings and bridges. Demand is robust in India and Southeast Asia due to significant infrastructure expansion.
- Shipbuilding:Shipbuilding requires specialized high-tensile strength and corrosion-resistant steel plates for large vessels and LNG carriers. This segment commands higher margins due to stringent material specifications and performance demands.
- Machinery Manufacturing:Machinery manufacturing uses carbon steel for components requiring high strength and wear resistance in industrial equipment.
- Oilfield Equipment:Oilfield equipment relies on carbon steel for drill pipes, casings, and platforms, needing durability in harsh environments.
- Agricultural Implements:Agricultural implements incorporate carbon steel for plows, cultivators, and tractor parts, demanding toughness and abrasion resistance.
Construction remains the largest volume consumer, while Shipbuilding applications are gaining share fastest due to specialized material needs.
End User:
End-user types vary in their purchasing volumes and technical specifications for carbon steel products.
- Fabricators:Fabricators process raw carbon steel into finished or semi-finished components for diverse industries, requiring a wide range of product forms. Their procurement often focuses on just-in-time delivery and customized cutting services.
- Heavy Equipment Manufacturers:Heavy equipment manufacturers integrate carbon steel into construction machinery, mining vehicles, and industrial equipment, demanding high-strength and wear-resistant grades. Their purchasing decisions prioritize material performance and consistent supply.
- Pipeline Suppliers:Pipeline suppliers require specialized steel grades for oil, gas, and water transmission systems, emphasizing corrosion resistance and weldability.
- Structural Workshops:Structural workshops specialize in assembling steel structures for buildings and bridges, procuring standard and custom-sized beams and plates.
Fabricators represent the most fragmented customer base, whereas Heavy Equipment Manufacturers drive demand for specialized high-performance alloys.
Form:
Carbon steel is supplied in various forms, each optimized for different manufacturing processes and end-use applications.
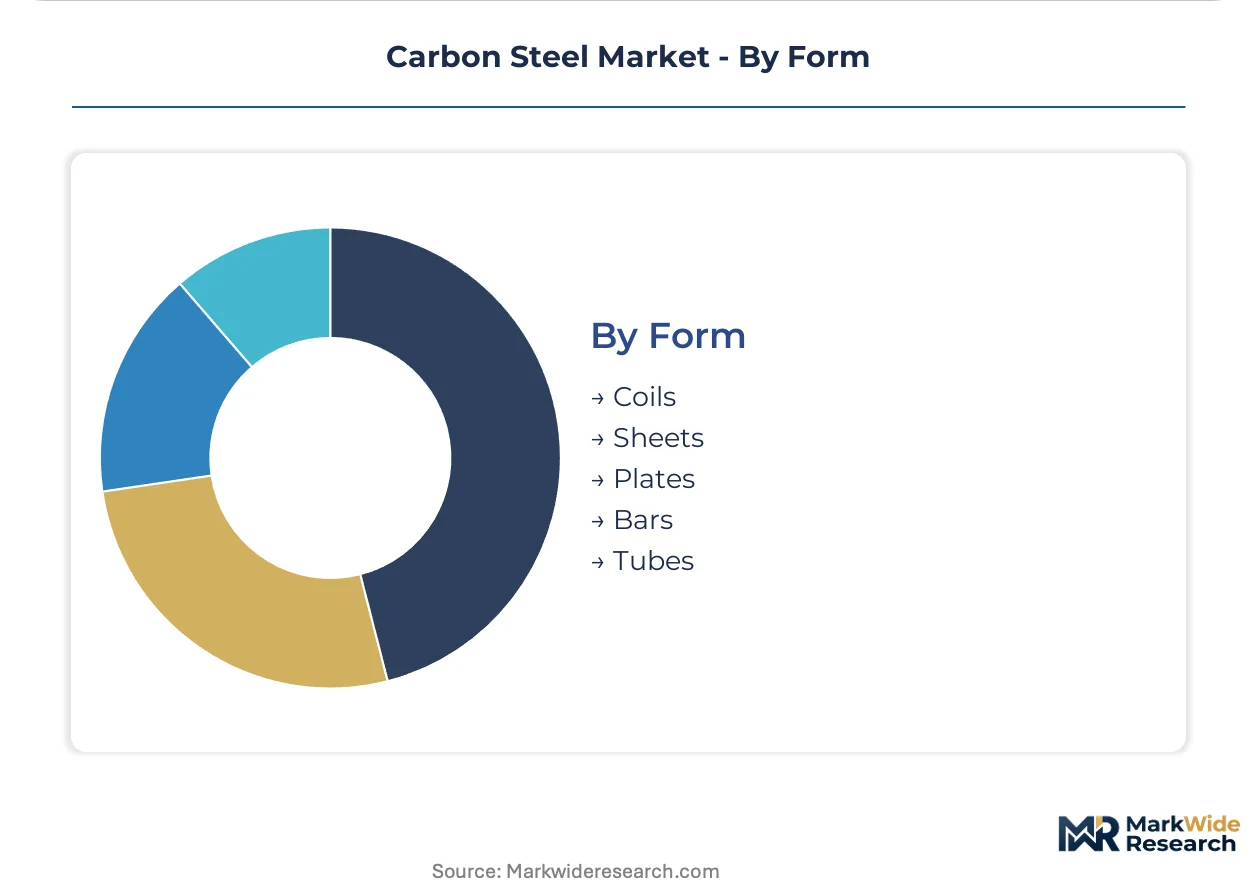
- Coils:Steel coils are long, rolled strips of metal, offering versatility for further processing into sheets or tubes across various industries. Automotive and appliance manufacturing are significant consumers, valuing continuous supply for high-volume production.
- Sheets:Steel sheets are thinner, flat products derived from coils, used in automotive body panels and consumer goods.
- Plates:Steel plates are thick, flat sections used for heavy construction, shipbuilding, and pressure vessels, providing structural integrity. Demand for plates is particularly strong in large-scale infrastructure projects in emerging economies.
- Bars:Steel bars are elongated sections, round or rectangular, essential for rebar in concrete and various machinery components.
- Tubes:Steel tubes are hollow sections, used for pipelines, structural frames, and automotive exhaust systems.
Coils and Plates together hold the largest share of the market, reflecting their fundamental role in industrial and construction sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's burgeoning infrastructure expansion contrasts with China's strategic focus on decarbonization within its steel sector. Both nations significantly influence global carbon steel demand through distinct market dynamics. This regional overview highlights key drivers and regulatory impacts across major economies.
India
India's National Infrastructure Pipeline fuels substantial demand for structural steel in transportation and urban housing projects. The PLI scheme for specialty steel incentivizes domestic production and quality improvements. Maharashtra and Gujarat anchor significant industrial clusters driving concentrated steel consumption.
China
China Baowu Group's immense production scale and government-backed infrastructure initiatives drive significant demand for carbon steel. China's dual carbon goals compel steelmakers to invest in low-emission technologies. The Yangtze River Delta region continues as a major hub for manufacturing and construction.
United States
Construction applications for structural beams and rebar generate consistent demand across the United States. EPA regulations influence steel production processes, encouraging environmental compliance. The Great Lakes region maintains a strong presence in heavy machinery manufacturing.
Germany
German machinery manufacturing and automotive sectors require high-strength steel grades for specialized components. The EU Green Deal and CBAM introduce carbon-cost considerations for steel imports. North Rhine-Westphalia remains a vital industrial heartland for steel production.
Japan
Japanese shipbuilding and automotive industries necessitate specialized high-tensile strength steel plates. METI industrial policies support advanced material research and development. The Tokyo Bay area concentrates significant industrial and manufacturing activities.
Carbon Steel Market Key Industry Players
Top-tier vendors anchor the global carbon steel market, while specialized regional players compete on niche applications. The market structure exhibits a tiered consolidation, with a few large integrated producers dominating volume. Strategic archetypes include global integrated producers, regional high-strength specialists, and local volume suppliers. Dominant competitive moves involve significant capacity expansion in emerging markets and strategic investments in decarbonization technologies.
Among global integrated producers, ArcelorMittal exemplifies a strategy of leveraging an extensive global production footprint to serve diverse regional construction standards and customer needs. China Baowu Group, a prominent Chinese entity, anchors significant production scale and benefits from government-backed infrastructure initiatives, particularly within the vast Asian market. Nippon Steel Corporation, a major Japanese firm, occupies a position focused on differentiating through its development of high-strength steel grades for specialized applications like the automotive and shipbuilding sectors, commanding higher margins.
| Leading Market Players |
|---|
| Nippon Steel Corporation |
| Shagang Group |
| China Baowu Group |
| POSCO Holdings |
| Jianlong Group |
| ArcelorMittal |
| HBIS Group |
| Shougang Group |
| Ansteel Group |
| Others |
Cost & Logistics Intelligence
The EU's Carbon Border Adjustment Mechanism (CBAM) gates qualified steel supply to European markets, compelling producers to invest in decarbonization technologies. This regulatory framework creates a premium-tier pricing segment for certified low-carbon steel products.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity-grade carbon steel across Asian markets. The dominant pricing model remains transactional, influenced by global commodity spot prices for raw materials. Price differentiation stems from specialized quality grades for automotive and shipbuilding, alongside emerging low-carbon certifications like Environmental Product Declarations (EPDs). Pricing softness persists for high-volume, standard products due to input cost volatility, while specialized applications and certified green steel command higher margins.
Supply Chain Analysis
Fabricators and direct channels to heavy equipment manufacturers handle significant carbon steel distribution. Geographic supply concentration centers on China, India, and Japan, which collectively produce vast quantities. The supply chain draws from critical raw materials like seaborne iron ore and coking coal, exposing producers to input cost volatility. Carbon border tariffs, such as the EU's CBAM, present a structural risk, potentially disrupting established trade flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon steel market acts as a regulatory compounder, with policy frameworks significantly shaping its evolution. China's dual carbon goals, for instance, drive substantial investments in low-emission production technologies and influence global manufacturing standards.
For Market Incumbents:Anticipate continued pressure from material substitution in the automotive sector and rising carbon costs from regulations like the EU CBAM. Invest heavily in decarbonization technologies, including hydrogen-based direct reduced iron and renewable-powered electric arc furnaces, to secure future market access. Deepen vertical integration into scrap collection and processing to ensure feedstock quality for EAFs. Prioritize green certification investment to differentiate products and command premiums in regulated markets.
For New Entrants and Emerging Players:The PLI scheme in India opens a window for new players focusing on specialty steel production and quality improvements. Target underpenetrated Southeast Asian markets embarking on major infrastructure projects, offering localized supply chains. Focus on developing certified low-carbon steel products, leveraging the growing demand for sustainable construction materials. Pursue niche applications like high-tensile strength steel for specialized marine vessels.
For Investors and Strategic Acquirers:Roll-up economics work for regional specialists because of fragmented local supply chains and varied construction standards. The carbon steel market presents long-term viability as a foundational material for global infrastructure and manufacturing. Target mid-sized producers with proprietary decarbonization technologies or strong market positions in high-growth regions like Southeast Asia. The signal to watch is accelerating investment in carbon capture, utilization, and storage (CCUS) infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Supports regional infrastructure growth and diversifies global production footprint. |
| Green Manufacturing Transition | Addresses regulatory mandates and unlocks premium market segments for low-carbon steel. |
| Long-term Offtake Agreements | Stabilizes revenue streams and provides certainty for large-scale capital investments. |
| Joint Ventures for H-DRI Plants | Shares massive capital costs and accelerates deployment of decarbonization technologies. |
| High-Strength Steel Product Development | Captures higher margins in specialized applications like automotive and shipbuilding. |
Research Approach
Direct dialogue with steel plant managers, procurement leads from heavy equipment manufacturers, construction project managers, and regulatory affairs specialists informed primary insights. This qualitative grounding was validated with extensive secondary research, including customs and trade data, national infrastructure pipeline reports, and corporate sustainability disclosures. A rigorous bottom-up and top-down triangulation approach ensured data consistency across all market segments.
Volume and value projections were generated using a robust analytical framework across the modeling period. The model incorporated segmentation dimensions including product type, application, end-user, form, and regional production capacity. Compound annual growth rates were derived from historical trends, projected demand from infrastructure spending forecasts, and technology adoption rates. Raw material price outlooks also served as critical inputs.
Revisions become necessary when significant shifts in global trade policies or unforeseen technological breakthroughs materialize. Forecasts reflect current assumptions, but geopolitical instability, rapid changes in raw material supply, or accelerated material substitution present risk factors. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Battery Metals Market
Metals
Metal Injection Molding (MIM) Parts Market
Metals
Galvanized Steel Market
Metals
Reconditioned Steel Drums Market
Metals
Silico Manganese Market
Metals
Aluminum Sheet Market
Metals
Silver Powder and Flakes Market
Metals
North America Metal Finishing Market
Metals
Nickel Foam Market
Metals
Galvanized Steel Coil Market
Metals
Smelting Chemicals Market
Metals
Cerium Market
Metals
Recycled Metal Market
Metals
Global Aluminum Market
Metals
United States Aluminum Extrusion Market
Metals
TMCP Steel Market