
 Agricultural Pipes and Tubes Market | 2026-2036
Agricultural Pipes and Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Pipes and Tubes Market Outlook
The divergence between premium and commodity tiers in agricultural piping is hardening around pressure ratings, UV stabilization grades, and warranty terms rather than diameter alone. Jain Irrigation Systems Ltd. leverages its captive polymer compounding capacity to control raw material quality across drip and sprinkler product lines. JM Eagle Inc. anchors its position through massive PVC extrusion scale serving surface irrigation and drainage contractors across North American row-crop regions.
Agricultural pipes and tubes are hollow cylindrical conduits manufactured from thermoplastic resins or coated steel, typically specified by nominal diameter, pressure class, and SDR (standard dimension ratio), designed to transport water, nutrients, and agrochemicals under gravity or pumped pressure across farm fields. HDPE pipes dominate subsurface drip networks where flexibility, chemical resistance, and leak-free fusion joints reduce field labor and water loss compared to rigid PVC alternatives. Steel tubes retain structural importance in large-diameter pivot irrigation systems where mechanical loads and spanning distances exceed polymer capabilities.
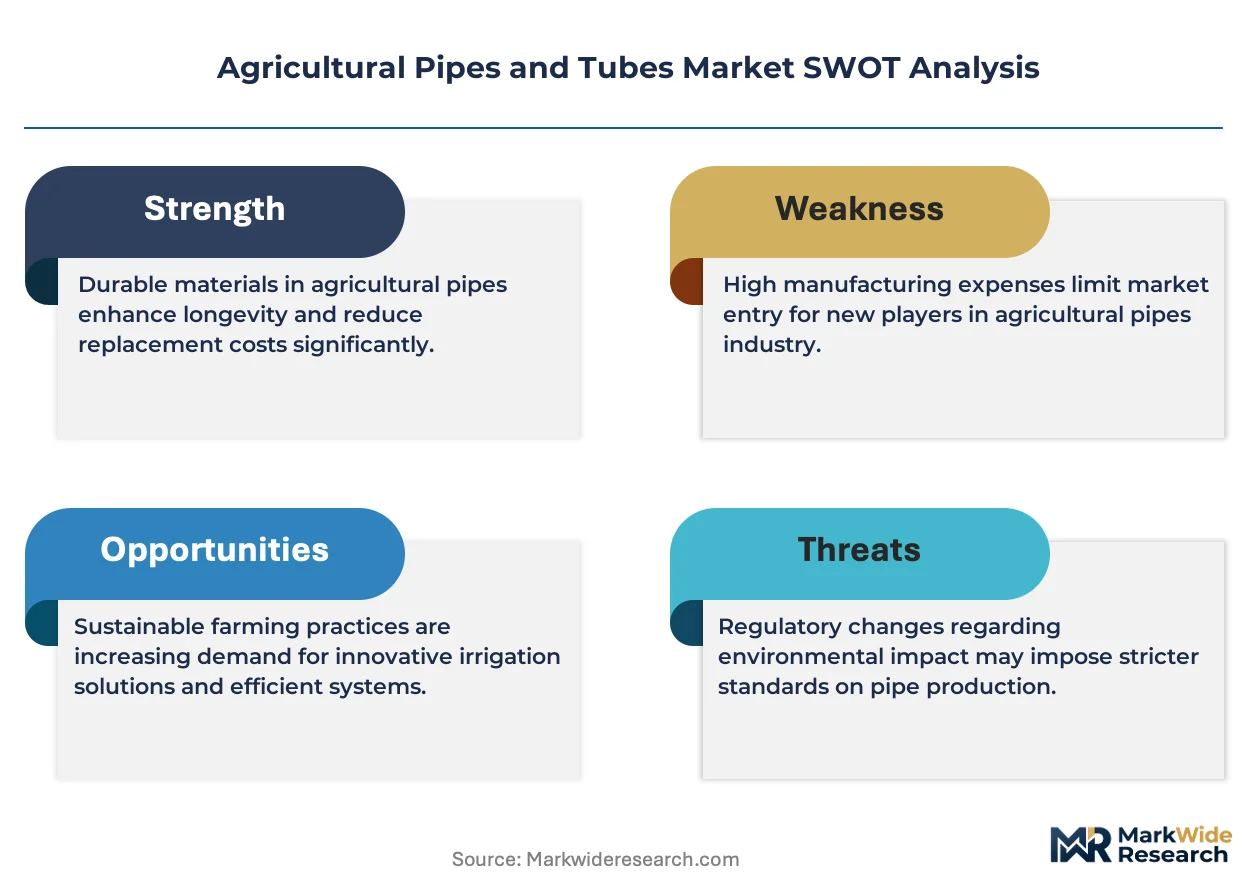
India's BIS mandates IS 4984 and IS 4985 standards for polyethylene and PVC agricultural pipes, while the US EPA's agricultural water quality guidelines influence material selection for runoff-sensitive watersheds. The EU F-Gas Regulation indirectly shapes demand by restricting fluorinated polymer additives once used in UV-stabilized tubing compounds. Stakeholders must monitor how water scarcity policies and subsidy program eligibility criteria redefine the acceptable cost-performance threshold between commodity PVC and engineered polymer systems.
Market Dynamics
Micro-irrigation adoption is fragmenting demand between engineered polymer systems and commodity PVC piping, with pressure ratings and UV stabilization grades replacing diameter as the primary specification differentiator.
Growth Catalysts
- Horticulture Expansion:Maharashtra and Gujarat states in India are driving procurement volumes through government subsidy programs for drip irrigation infrastructure.
- BIS Certification Mandates:India's IS 4984 and IS 4985 standards are pushing domestic manufacturers toward certified HDPE grades, elevating quality baselines across the supply base.
- Water Scarcity Policies:Subsurface drip networks are displacing surface irrigation in water-stressed agricultural regions, favoring flexible fusion-jointed polymer systems over rigid alternatives.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene and vinyl chloride monomer prices swing with crude oil markets, compressing margin visibility for extrusion-dependent manufacturers.
- HDPE Resin Supply Concentration:Polymer compounding capacity clusters among integrated petrochemical majors, limiting negotiating leverage for mid-scale pipe producers.
- Steel Tube Substitution Ceiling:Mechanical load requirements in large-diameter pivot irrigation systems exceed polymer tensile limits, locking steel into structural applications.
Strategic Opportunities
- Underpenetrated Sub-Saharan Markets:Surface irrigation dominance in East African row-crop regions presents white space for micro-irrigation retrofit campaigns.
- EU F-Gas Regulatory Tailwind:Restrictions on fluorinated polymer additives are accelerating reformulation toward bio-based UV stabilizers in tubing compounds.
- Digital-Physical Convergence:IoT-enabled flow monitoring is integrating with polymer distribution networks, creating bundled hardware-service offerings.
Industry Challenges
- Certification Timeline Compression:BIS testing protocols for agricultural plastics extend product development cycles, delaying market entry for reformulated grades.
- Fusion Welding Skill Scarcity:HDPE joint integrity depends on certified technician labor, creating bottlenecks in rapid deployment scenarios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Pipes and Tubes Market |
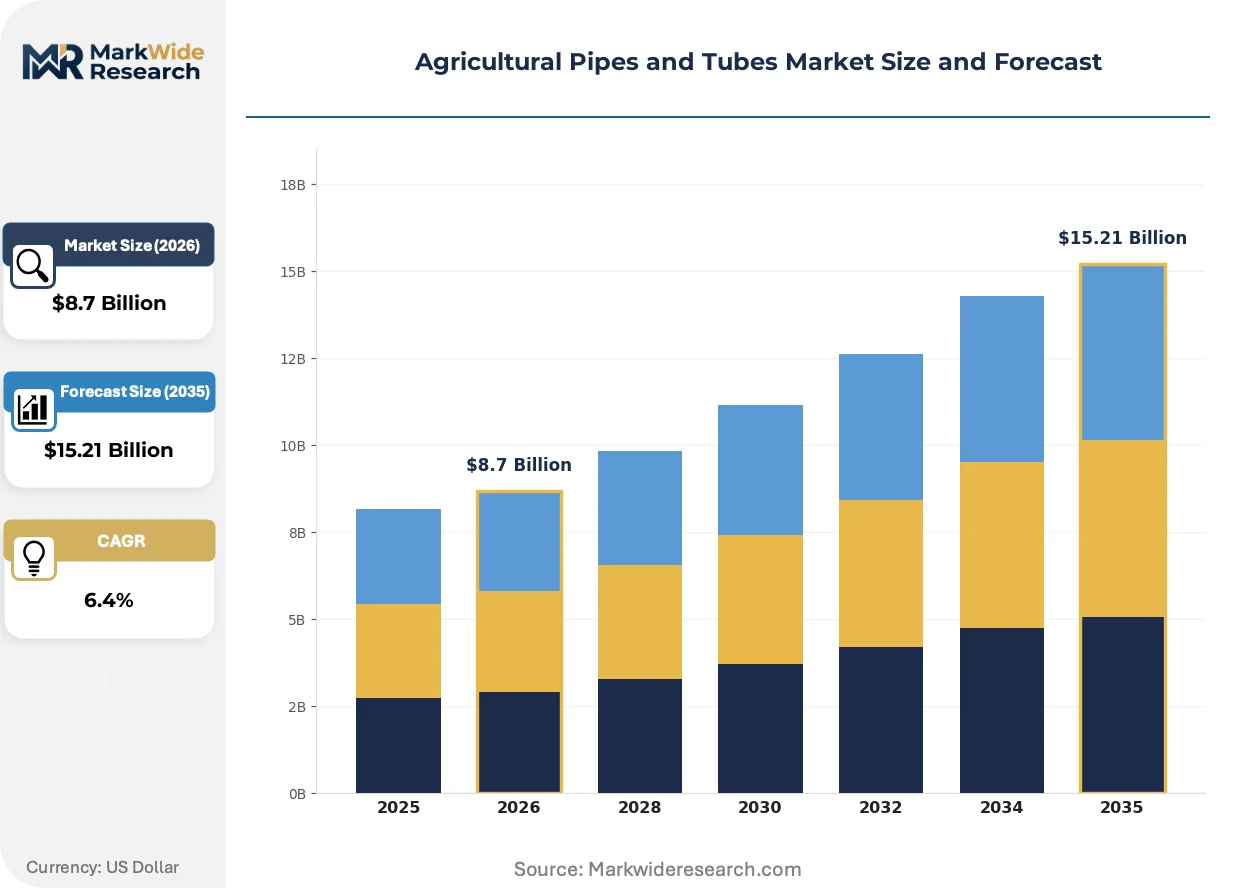
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC Pipes, HDPE Pipes, Polypropylene Tubes, Steel Tubes End Use Industry: Agriculture, Horticulture, Nursery, Landscaping Installation Method: Surface Installation, Subsurface Installation, Drip Irrigation, Sprinkler System Dimension: Standard Size, Custom Size, Large Diameter, Small Diameter |
| Companies Covered | Jain Irrigation Systems Ltd., Netafim Ltd., The Toro Company, Rivulis Irrigation, Lindsay Corporation, Rain Bird Corporation, JM Eagle Inc., Finolex Industries Limited, Uponor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Pipes and Tubes Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are rewriting formulation roadmaps, while procurement behavior shifts toward specification bundles that combine hardware with performance guarantees.
Co-extruded multi-layer tubing is integrating barrier polymers into irrigation laterals to prevent root intrusion and chemical leaching. Large-scale greenhouse operators in the Netherlands and Spain are specifying these constructions for recirculating hydroponic systems. The technology is integrating pressure-compensating emitters directly into extrusion lines, collapsing assembly steps and reducing field labor costs.
The EU F-Gas Regulation is prohibiting perfluorinated compounds in UV stabilization packages, forcing compounders toward hindered amine light stabilizers and carbon black masterbatches. Agricultural tubing exports to European markets now require reformulation certificates documenting additive chemistry. German and Italian distributors are prioritizing suppliers with pre-certified REACH-compliant material data sheets.
Specification bundling is displacing component-only procurement in commercial horticulture. Drip irrigation contractors now source pipe, emitter, and filtration systems as integrated packages with multi-season performance warranties. This consolidation is most visible in California's Central Valley and Almeria's greenhouse belt, where large growers negotiate directly with system integrators rather than fragmented material distributors.
Agricultural Pipes and Tubes Market Segmentation
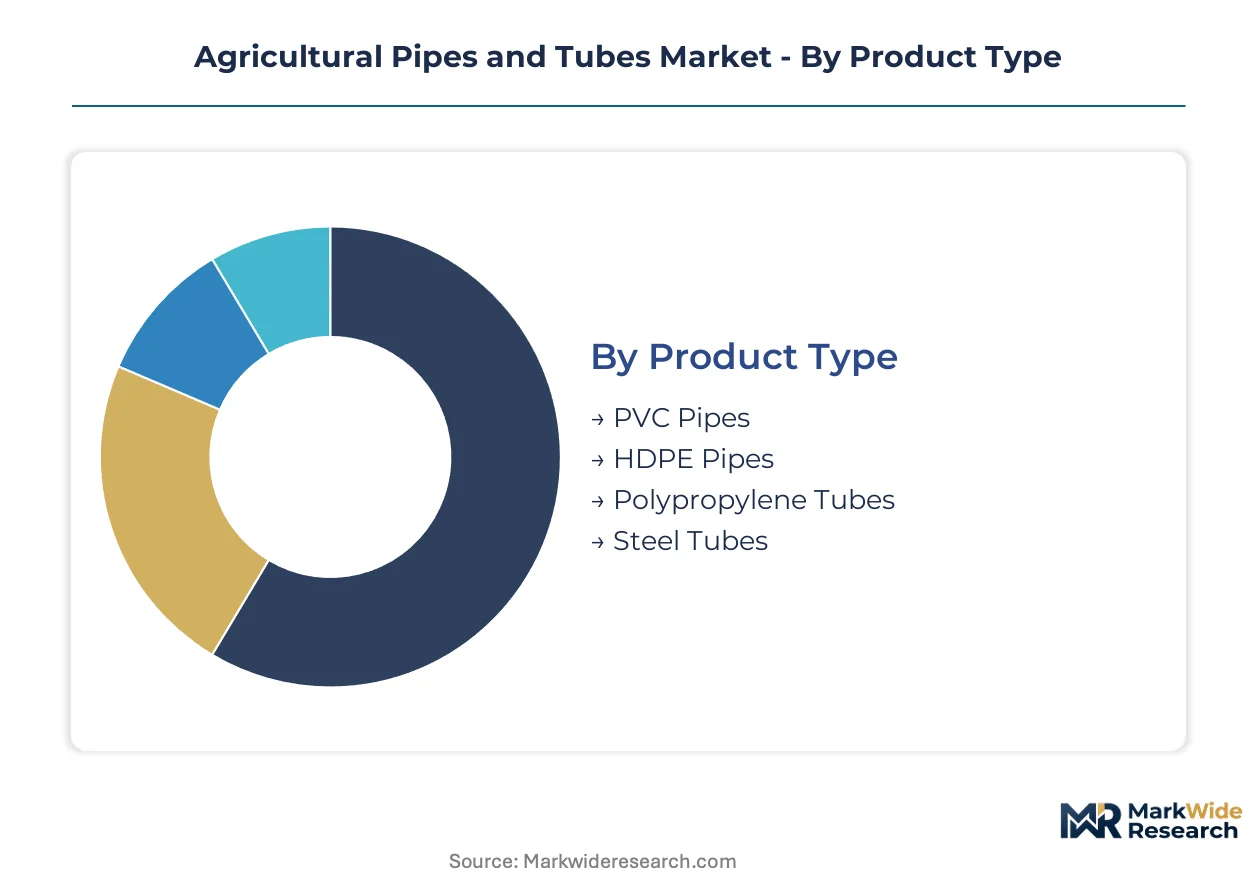
Agricultural piping procurement splits between standalone commodity products and integrated irrigation systems. Specification bundles now combine material grade, pressure rating, and installation method into unified purchasing decisions.
Product Type:
HDPE pipes operate as embedded infrastructure within subsurface drip networks, while PVC and steel tubes serve more frequently as standalone surface installations.
- HDPE Pipes:Flexible polyethylene conduits specified by SDR ratings and fusion-joint integrity. Maharashtra and Gujarat horticulture clusters specify these for pressure-compensated drip laterals where leak-free connections reduce field labor. BIS IS 4984 certification mandates are elevating quality baselines for domestic supply.
- PVC Pipes:Rigid thermoplastic extrusions dominate surface irrigation and drainage applications. North American row-crop contractors specify these for gravity-fed distribution where mechanical loads remain moderate and cost sensitivity runs high.
- Polypropylene Tubes:Lightweight alternatives for greenhouse nutrient delivery systems.
- Steel Tubes:Structural-grade piping for large-diameter pivot irrigation where polymer tensile limits fail.
Volume placements concentrate in PVC Pipes; the faster expansion belongs to HDPE Pipes.
End Use Industry:
Customer sophistication varies sharply—commercial horticulture demands engineered polymer systems while broad-acre agriculture tolerates commodity specifications.
- Horticulture:High-value crop operations in Almeria and California's Central Valley specify multi-layer tubing with integrated emitters and root-intrusion barriers. Recirculating hydroponic systems drive demand for chemical-resistant barrier polymers in greenhouse infrastructure.
- Agriculture:Row-crop and field-scale irrigation across water-stressed regions. Subsurface drip retrofit programs in water-scarce watersheds favor flexible fusion-jointed systems over rigid surface alternatives.
- Nursery:Containerized propagation operations requiring precise moisture control.
- Landscaping:Turf and ornamental irrigation with lower pressure and durability requirements.
Revenue margins peak in Horticulture; the steepest volume trajectory tracks Agriculture.
Installation Method:
Deployment complexity determines whether piping ships as standalone commodity or pre-assembled system component.
- Drip Irrigation:Precision water delivery through pressure-compensating emitters integrated into extrusion lines. Co-extruded multi-layer construction prevents root intrusion in recirculating systems. Dutch and Spanish greenhouse operators specify these for hydroponic nutrient loops.
- Subsurface Installation:Buried HDPE networks with fusion-welded joints eliminating evaporation losses. Certified technician labor creates deployment bottlenecks in rapid-scale scenarios.
- Surface Installation:Above-ground PVC distribution for flood and furrow irrigation.
- Sprinkler System:Pressurized overhead delivery with mechanical assembly requirements.
Technology investment concentrates in Drip Irrigation; infrastructure replacement cycles favor Subsurface Installation.
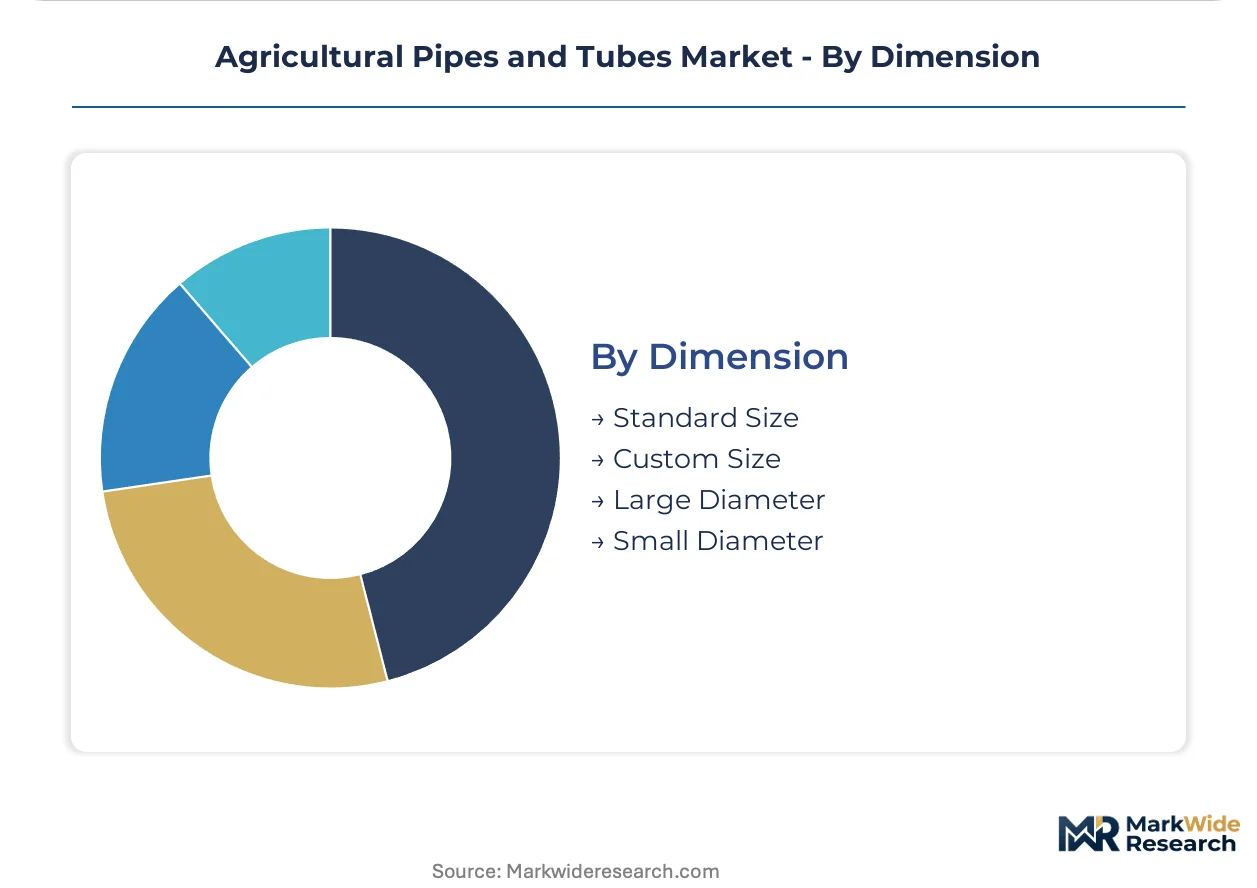
Dimension:
Scale economics and transportation constraints fragment supply chain configurations across diameter classes.
- Large Diameter:Steel-reinforced or thick-wall polymer constructions for mainline distribution. Pivot irrigation systems spanning mechanical loads require structural grades exceeding standard polymer capabilities.
- Small Diameter:Lateral tubing and emitter lines in micro-irrigation networks. Custom extrusion lines accommodate greenhouse-specific coil lengths and pressure ratings.
- Standard Size:Commodity extrusions for conventional surface irrigation.
- Custom Size:Project-specific dimensions for integrated system builds.
Production throughput centers on Standard Size; specification premiums attach to Custom Size.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jalgaon and Ahmednagar districts in Maharashtra anchor India's agricultural piping procurement, where drip irrigation subsidy programs and horticulture expansion concentrate demand for certified polymer systems.
United States
California's Central Valley and Arizona's Yuma County drive specification bundling for integrated drip systems. The EPA's agricultural water quality guidelines influence material selection in runoff-sensitive watersheds. Fresno-based contractors negotiate directly with system integrators for multi-season performance warranties.
India
Maharashtra and Gujarat states dominate procurement volumes through government subsidy programs for micro-irrigation infrastructure. BIS mandates IS 4984 and IS 4985 standards for polyethylene and PVC pipes, elevating quality baselines for domestic manufacturers. Jain Irrigation Systems leverages captive polymer compounding capacity in Jalgaon to control raw material quality across product lines.
Spain
Almería's greenhouse belt specifies multi-layer tubing with integrated emitters for recirculating hydroponic systems. The EU F-Gas Regulation restricts fluorinated polymer additives, forcing compounders toward hindered amine light stabilizers. German and Italian distributors prioritize suppliers with pre-certified REACH-compliant material data sheets.
Netherlands
Westland municipality greenhouse operators demand co-extruded barrier polymers for nutrient delivery loops. The EU Green Deal accelerates reformulation toward bio-based UV stabilizers in tubing compounds. Wageningen-area research clusters test pressure-compensating emitter integration directly into extrusion lines.
Brazil
São Paulo state citrus and sugarcane operations retrofit surface irrigation with subsurface drip networks. Water scarcity policies in the Cerrado biome favor flexible fusion-jointed HDPE systems over rigid PVC alternatives. Campinas-based distributors face certified technician labor bottlenecks in rapid deployment scenarios.
Agricultural Pipes and Tubes Market Competitive Environment
Premium-margin players sit above commodity-margin players across pressure ratings, UV stabilization grades, and warranty terms rather than diameter alone. The vendor base splits between integrated system providers with captive polymer compounding and standalone extrusion specialists serving surface irrigation contractors. Three archetypes dominate: horticulture-focused integrators bundling hardware with performance guarantees, scale-driven PVC commodity producers serving row-crop drainage, and regional HDPE specialists capturing subsurface drip retrofit cycles. Competitive moves center on backward integration into polymer compounding and geographic expansion through specification bundling.
Within the integrated-system tier, Jain Irrigation Systems Ltd. and Netafim Ltd. exemplify the horticulture-focused archetype with bundled hardware-service offerings. JM Eagle Inc. anchors the scale-driven commodity segment through massive extrusion capacity. Finolex Industries Limited occupies a position bridging certified domestic supply and subsidy-program eligibility in Indian states.
| Leading Market Players |
|---|
| Jain Irrigation Systems Ltd. |
| Netafim Ltd. |
| The Toro Company |
| Rivulis Irrigation |
| Lindsay Corporation |
| Rain Bird Corporation |
| JM Eagle Inc. |
| Finolex Industries Limited |
| Uponor Corporation |
| Others |
Value Chain & Pricing Dynamics
Co-extruded multi-layer tubing integration is compressing unit economics while concentrating polymer compounding capacity among integrated petrochemical majors, simultaneously reshaping cost structures and supplier power dynamics across the agricultural piping value chain.
Pricing Analysis
Yield-per-meter guarantees anchor value-based pricing in commercial horticulture segments. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified HDPE grades from commodity PVC extrusions and unbranded regional supply. Price differentiation hinges on pressure rating certification and UV stabilization chemistry grade. Cost compression in commodity PVC tiers is intensifying because ethylene and vinyl chloride monomer prices swing with crude oil volatility. Row-crop contractors across North American surface irrigation applications exhibit the highest price sensitivity, while Dutch greenhouse operators negotiating bundled system warranties show the least.
Supply Chain Analysis
Direct-to-contractor channels handle subsidy-program procurement volumes in Maharashtra and Gujarat, while system-integrator partnerships dominate California's Central Valley specification bundling. Manufacturing concentrates in India, the United States, and Germany, with compounding capacity clustering among integrated petrochemical majors in each hub. Raw material flows draw from ethylene crackers, vinyl chloride monomer producers, and carbon black masterbatch compounders. Single-source vulnerability in certified HDPE resin supply creates bottlenecks for mid-scale pipe producers seeking BIS compliance. Distribution runs through agricultural input distributors, irrigation system integrators, and direct government tender channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase where fusion-jointed HDPE networks displace rigid surface irrigation, with pressure-compensating emitter integration into extrusion lines replacing field assembly.
For Market Incumbents: Lock in polymer compounding capacity through captive production or long-term offtake agreements with certified resin suppliers. Defend margin position by accelerating backward integration into UV stabilizer formulation to meet EU F-Gas compliance deadlines. Jain Irrigation Systems' Jalgaon facility demonstrates how controlling raw material quality across drip and sprinkler lines insulates against commodity price swings. For New Entrants and Emerging Players: Begin with underpenetrated Sub-Saharan surface irrigation retrofit campaigns where certified technician scarcity has slowed incumbent deployment. Target East African row-crop regions with simplified mechanical-joint HDPE systems that reduce fusion-welding skill requirements. Partner with government agricultural extension services to embed product specifications into subsidy program eligibility criteria. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated system providers with REACH-compliant material data sheets and pre-certified additive chemistry. Long-term viability favors horticulture-focused bundlers over standalone extrusion specialists exposed to commodity PVC margin compression. Watch BIS certification timeline extensions as an inflection indicator for domestic Indian manufacturer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Jain Irrigation Systems' captive Jalgaon capacity controls raw material quality across product lines. |
| REACH-Compliant Material Reformulation | EU F-Gas restrictions on fluorinated additives force compounders toward hindered amine light stabilizers. |
| Certified Technician Training Programs | Brazil's Campinas distributors address fusion-welding bottlenecks through rapid-deployment skill pipelines. |
| Specification Bundling with Performance Warranties | California Central Valley growers negotiate multi-season guarantees directly with system integrators. |
| Subsurface Drip Retrofit Campaigns | Water scarcity policies in India's Maharashtra and Gujarat states drive procurement volume concentration. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews involving irrigation system integrators, polymer compounding plant managers, agricultural extension officers, and government subsidy program administrators. Secondary sources included BIS certification databases, EPA agricultural water quality guidelines, EU REACH substance registration data, and customs import records for polyethylene and PVC resin grades. Bottom-up volume estimates from state-level subsidy disbursements combined with top-down market sizing from polymer consumption patterns.
Segment-level modeling tracked product type, end-use industry, installation method, and dimension across the projection horizon. CAGRs derived from trend extrapolation of micro-irrigation adoption rates, horticulture expansion patterns, and regulatory compliance timeline impacts. Industry-specific inputs incorporated BIS IS 4984 and IS 4985 certification penetration curves, EU F-Gas reformulation cost pass-through assumptions, and drip irrigation subsidy program budget allocations.
Underlying measurement precision varies by segment; BIS-certified HDPE pipes in Maharashtra and Gujarat carry tighter precision than fragmented commodity PVC supply in unregulated regional markets. Forecasts reflect assumptions about petrochemical feedstock stability, subsidy program continuity, and fusion-welding technician availability. Periodic stress-testing of base assumptions is recommended against water policy shifts and polymer resin supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
Global Municipal Pipes Market
Pipes and Tubes
HDPE Pipes Market
Pipes and Tubes
Europe Copper Pipes and Tubes Market
Pipes and Tubes
India Process Piping Market
Pipes and Tubes
Global Fiberglass Pipe Market
Pipes and Tubes
OCTG Pipe Market
Pipes and Tubes
Heat Shrink Tubing Market
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market
Pipes and Tubes
Global Fluoropolymer Tubing Market
Pipes and Tubes
Galvanized Steel Tubes Market
Pipes and Tubes
Clad Pipe Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
Global Titanium Tube Market
Pipes and Tubes
Plastic Pipe Market