
 Composite Pipes Market | 2026-2036
Composite Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Pipes Market Analysis
Middle Eastern pipe fabricators is broadening output of spoolable composite lines for sour gas service. Future Pipe Industries leverages integrated filament winding operations across the UAE and Saudi Arabia. Amiantit anchors regional supply of glass-reinforced thermoset pipes for water transmission networks. Shawcor competes through specialized flexible composite riser technology for offshore installations.
Composite pipes consist of thermoset or thermoplastic matrices reinforced with continuous glass, carbon, or aramid fibers, typically manufactured through filament winding or pultrusion to achieve specific pressure ratings up to several hundred bar. These structures serve primarily to transport corrosive fluids, hydrocarbons, and water across infrastructure where metallic corrosion would impose unacceptable lifecycle costs. Glass fiber reinforced products dominate volume due to favorable cost-strength ratios in water and chemical applications, while carbon fiber reinforced variants command premium positioning in high-pressure oil and gas environments. Filament winding technology leads manufacturing throughput for large-diameter pressure pipe, whereas pultrusion occupies structural and electrical conduit segments where dimensional consistency drives specification.
API standards govern North American oil and gas composite pipe qualification, while ISO 14692 provides international design and installation protocols for glass-reinforced systems in petroleum service. The EU Pressure Equipment Directive and CE marking requirements shape market access for composite piping sold into European industrial plants. Stakeholders must monitor evolving hydrogen compatibility standards as pipeline operators evaluate composite materials for blended and pure hydrogen transport infrastructure.
Market Dynamics
The EU F-Gas Regulation is compressing permissible fluoropolymer content in composite pipe liners, forcing reformulation toward thermoplastic alternatives and accelerating qualification cycles for compliant materials across European industrial plants.
Growth Catalysts
- Corrosion-resistant infrastructure mandates:Pipeline operators in sour gas fields are specifying glass-reinforced epoxy systems to eliminate metal failure modes. API standards for composite qualification in petroleum service are tightening material performance thresholds.
- Water network modernization:Municipal utilities across Germany and China are replacing cast iron distribution mains with filament-wound thermoset pipes. The EU Drinking Water Directive is accelerating approval timelines for polymer-based transmission systems.
- REACH compliance pressure:Chemical processing facilities are adopting vinyl ester composite piping to satisfy substance restriction protocols. Glass fiber reinforced products dominate retrofit specifications where metallic corrosion has degraded legacy infrastructure.
Market Restraints
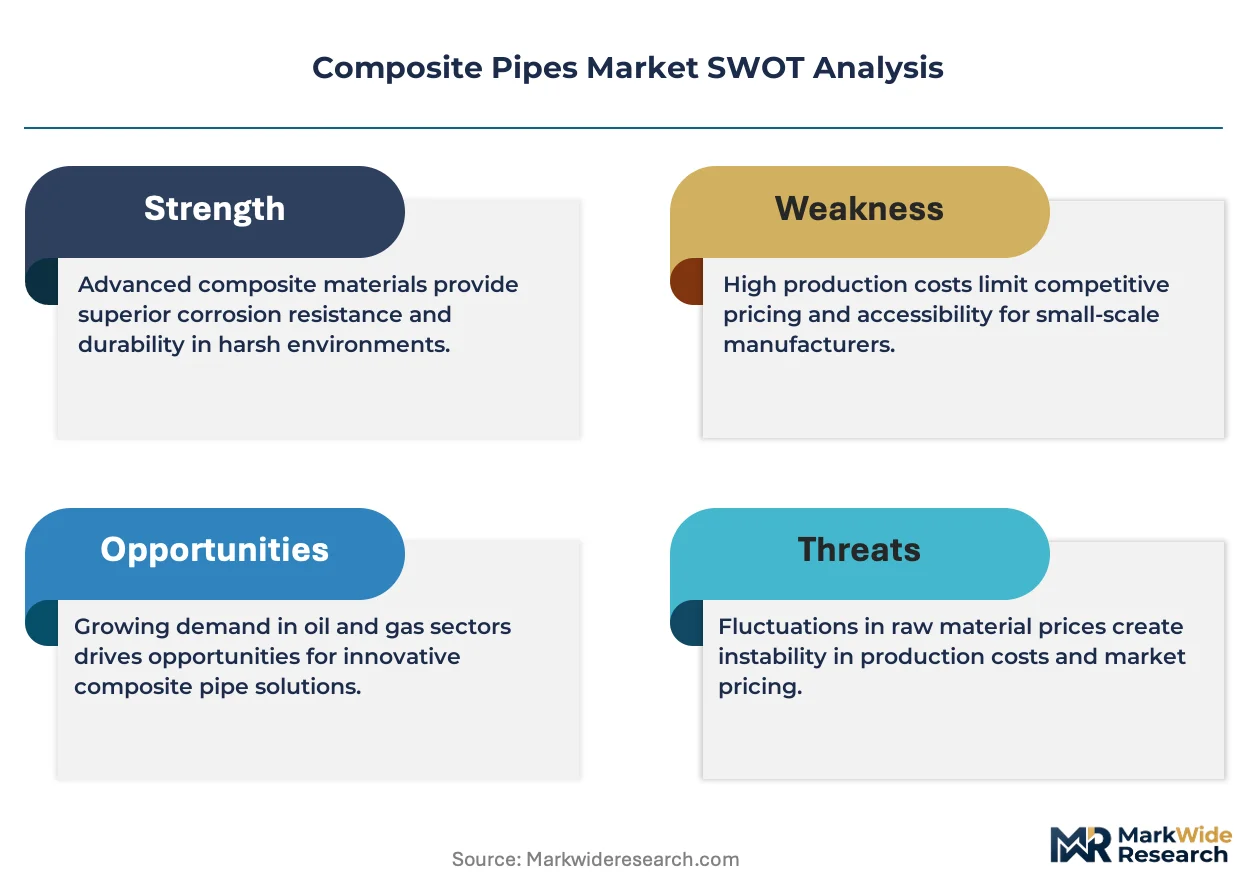
- Carbon fiber supply concentration:High-pressure oil and gas applications depend on Toray and Hexcel production facilities concentrated in Japan and the United States. Geopolitical friction threatens filament availability for premium composite riser manufacturing.
- Specialized installation labor scarcity:Filament wound pipe systems require certified fusion technicians and automated joining equipment. Training pipelines for qualified field crews lag deployment schedules in remote extraction regions.
- Steel pipe residual competitiveness:Commodity carbon steel maintains cost advantage in low-corrosion water transmission and non-sour hydrocarbon service. Composite penetration stalls where metallic lifecycle costs remain acceptable to procurement specifications.
Strategic Opportunities
- Hydrogen transport infrastructure:Pipeline operators in Germany and the Netherlands are evaluating glass-reinforced thermoplastic systems for blended hydrogen service. ISO standards for hydrogen compatibility in composite materials are under active development.
- Offshore flexible riser expansion:Deepwater production facilities in Brazil and West Africa require specialized spoolable composite lines for dynamic service. Subsea installation contractors are consolidating specifications around thermoset-based flexible pipe architectures.
- Modular fabrication models:Spoolable composite pipe manufacturers are deploying mobile filament winding units to reduce logistics costs for remote oilfield development. Portable production systems compress delivery timelines for customized pressure-rated segments.
Industry Challenges
- Qualification timeline compression:API 15HR and ISO 14692 certification cycles for new resin formulations extend 18-24 months. Product development teams struggle to synchronize material innovation with operator procurement windows.
- Legacy metallic system integration:Composite-to-steel transition joints require specialized adhesive bonding and mechanical anchoring protocols. Field installation crews face technical complexity when interfacing new thermoset lines with existing carbon steel headers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Pipes Market |
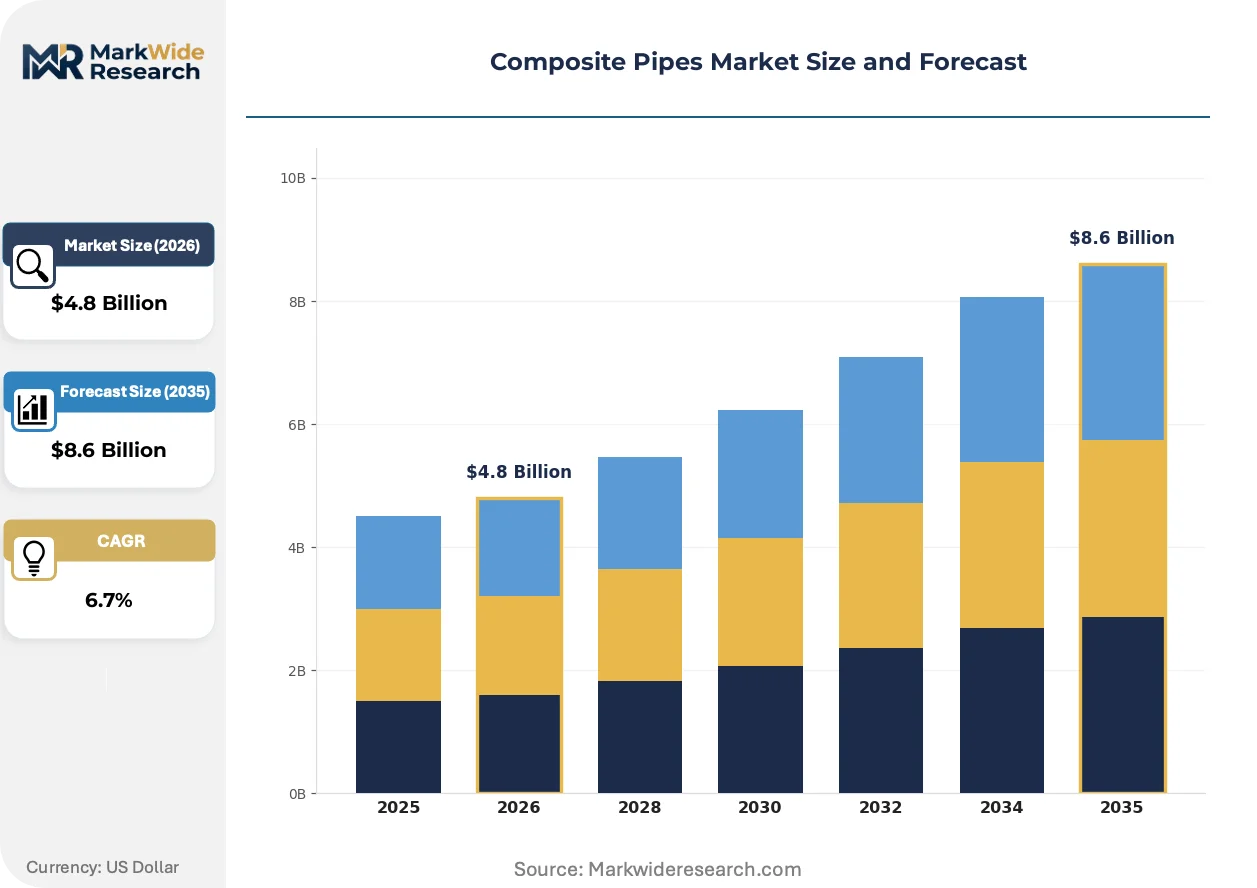
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Fiber Reinforced, Carbon Fiber Reinforced, Aramid Fiber Reinforced, Hybrid Composite End User: Aerospace, Oil & Gas, Chemical Processing, Water Supply Application: Structural Components, Piping Systems, Insulation, Automotive Parts Technology: Filament Winding, Pultrusion, Resin Transfer Molding, Compression Molding |
| Companies Covered | National Oilwell Varco, Future Pipe Industries, Amiantit, Tenaris, Owens Corning, Trelleborg, Shawcor, TechnipFMC, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Pipes Market Emerging Trajectories
Thermoplastic liner technology is displacing thermoset dominance in sour gas applications, while digital manufacturing controls are compressing dimensional tolerance bands. Regulatory frameworks in Europe and North America are accelerating material disclosure requirements.
Automated filament winding with in-situ thermoplastic consolidation is integrating continuous glass fiber reinforcement with polyamide liner systems. Offshore pipeline contractors in the North Sea are adopting these hybrid architectures for subsea tieback installations. The technology is integrating pressure containment and chemical resistance into single-structure designs that eliminate adhesive layer failure modes.
The EU F-Gas Regulation is banning hydrofluorocarbon blowing agents in insulation-core composite pipes effective 2027. German chemical processors are reformulating polyurethane foam cores to satisfy phase-down schedules. Water transmission network operators in Northern Europe are accelerating specification updates to lock in compliant material certifications before manufacturing transition deadlines.
Buyer consolidation among supermajor oil companies is compressing supplier qualification lists to three approved composite pipe vendors per region. Engineering procurement contractors in the United States are unbundling installation services from material supply to capture margin through captive construction crews. The Gulf of Mexico offshore sector exhibits the most pronounced concentration, where Chevron and ExxonMobil have reduced approved flexible riser suppliers to two specialized manufacturers.
Composite Pipes Market Segmentation
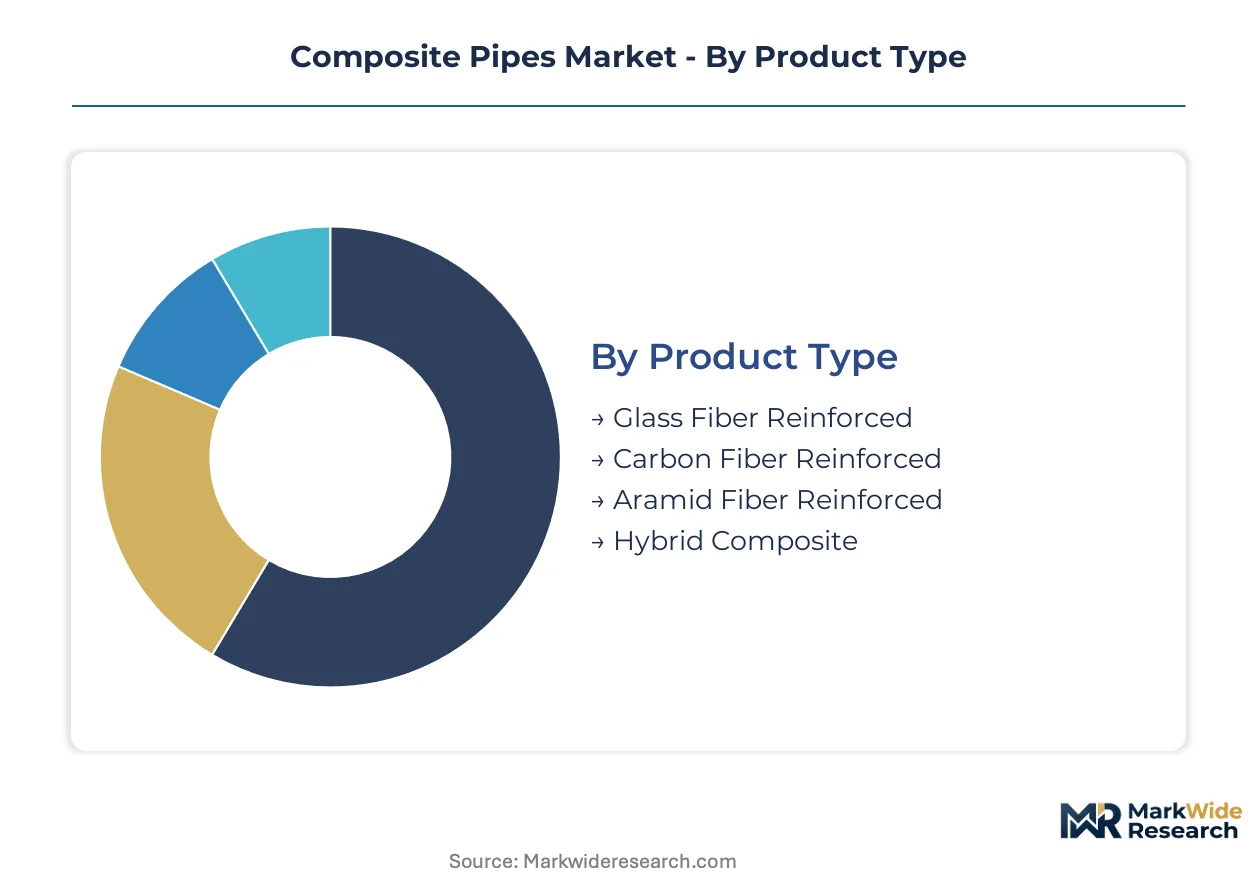
Composite pipe manufacturers configure production assets around fiber type and forming technology to capture value across pressure ratings and chemical resistance requirements. Segmentation discipline separates commodity water transmission from premium hydrocarbon service where qualification barriers protect margins.
Product Type:
Supply concentration in carbon fiber precursors and glass fiber roving operations shapes competitive positioning across reinforcement categories.
- Glass Fiber Reinforced:Continuous E-glass or S-glass filaments embedded in thermoset epoxy or vinyl ester matrices dominate volume production. Municipal utilities in Germany and China specify these systems for water distribution network replacement where corrosion resistance outweighs pressure requirements.
- Carbon Fiber Reinforced:High-modulus carbon fiber tows in specialized thermoplastic or thermoset matrices command premium positioning. Deepwater production facilities in Brazil require these systems for flexible riser applications where specific strength and fatigue resistance justify material costs.
- Aramid Fiber Reinforced:Kevlar or Twaron reinforcement layers serve specialized offshore dynamic service where impact resistance and weight reduction converge. Limited commercial penetration outside military and aerospace conduit applications.
- Hybrid Composite:Strategic fiber combinations—glass-carbon or glass-aramid—optimize cost-performance ratios in intermediate pressure service. Chemical processing facilities in the Netherlands evaluate hybrid architectures for sour gas transport where single-fiber solutions prove uneconomical.
Today's leader: Glass Fiber Reinforced. Tomorrow's challenger: Carbon Fiber Reinforced.
End User:
Procurement specifications diverge sharply between regulated municipal infrastructure and performance-driven hydrocarbon extraction.
- Oil & Gas:Pipeline operators specify API-qualified composite systems for sour gas gathering and subsea production flowlines. Offshore contractors in West Africa consolidate procurement around thermoset-based flexible pipe architectures that eliminate corrosion failure modes.
- Water Supply:German utilities accelerate cast iron replacement with filament-wound thermoset mains under EU Drinking Water Directive compliance deadlines. Chinese municipal authorities specify glass-reinforced epoxy for transmission networks spanning corrosive soil conditions.
- Chemical Processing:REACH-compliant vinyl ester piping displaces metallic systems in European chlor-alkali and acid handling facilities. Glass fiber reinforced products dominate retrofit specifications where substance restriction protocols have degraded legacy infrastructure.
- Aerospace:Specialized aramid or carbon fiber conduit systems serve fuel and hydraulic line applications where weight reduction drives specification. Limited volume relative to industrial segments due to qualification cycles and airframe production rates.
Oil & Gas commands premium pricing. Water Supply offers volume scale.
Application:
Functional requirements determine forming technology selection and fiber architecture complexity.
- Piping Systems:Pressure-rated cylindrical structures for fluid transport dominate commercial output. Filament winding technology achieves circumferential and axial strength optimization for buried and above-ground service.
- Structural Components:Load-bearing supports and platforms in corrosive industrial environments leverage pultruded profiles. Dimensional consistency and modulus customization drive specification in chemical plant construction.
- Insulation:Foam-core composite pipes for district heating and cryogenic service require specialized polyurethane or polyisocyanurate formulations. EU F-Gas Regulation is compressing permissible blowing agent options and forcing core material transitions.
- Automotive Parts:Lightweight fluid handling components in electric vehicle thermal management systems represent emerging specification territory. Material qualification cycles lag automotive platform development timelines.
Piping Systems anchor current revenue. Structural Components are gaining share fastest in industrial construction.
Technology:
Capital intensity and labor skill requirements separate scalable continuous processes from batch-oriented precision forming.
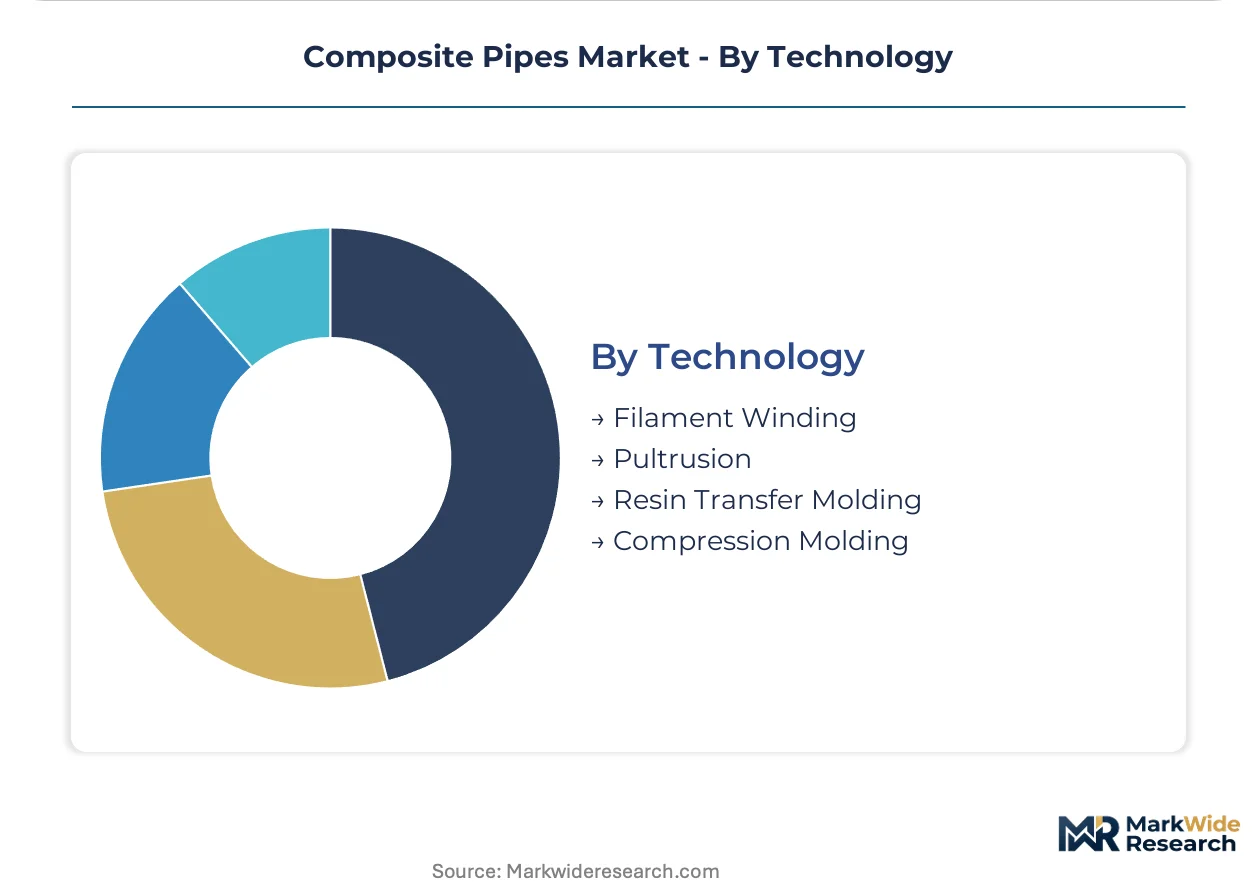
- Filament Winding:Automated fiber placement on rotating mandrels produces large-diameter pressure pipe with optimized layup patterns. Mobile winding units now deploy to remote oilfield locations to compress logistics costs.
- Pultrusion:Continuous pulling of resin-impregnated fiber through heated dies yields structural profiles with tight dimensional tolerances. Electrical conduit and grating applications favor this high-throughput approach.
- Resin Transfer Molding:Closed-mold injection of thermoset resins enables complex hollow sections with integral fittings. Specialized composite fitting manufacturers serve markets where filament wound pipe requires custom transition pieces.
- Compression Molding:Matched-die forming of thermoplastic composites suits high-volume automotive and electrical components. Limited penetration in pressure pipe due to fiber length constraints and weld line integrity concerns.
Filament Winding dominates pressure pipe. Pultrusion leads structural applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping composite pipe manufacturing as producers migrate toward jurisdictions with streamlined qualification protocols. The EU F-Gas Regulation imposes stricter material disclosure burdens than API certification cycles in North America, widening compliance cost differentials.
United States
Pipeline operators in the Permian Basin and Gulf of Mexico drive specification of API 15HR-qualified thermoset systems for sour gas gathering. EPA corrosion prevention mandates accelerate cast iron replacement in municipal water networks across Texas and California. Houston anchors flexible riser engineering clusters where Shawcor and TechnipFMC concentrate subsea composite technology development.
Germany
Municipal utilities in North Rhine-Westphalia and Bavaria deploy filament-wound epoxy mains under EU Drinking Water Directive compliance deadlines. The F-Gas Regulation forces polyurethane core reformulation for district heating pipes by 2027. Industrial fabricators in the Ruhr region specialize in REACH-compliant vinyl ester piping for chemical processing facilities.
China
State-owned pipeline operators specify glass-reinforced epoxy for West-East gas transmission corridors spanning corrosive soil zones. MIIT domestic content requirements favor local filament winding equipment over imported systems. Manufacturing clusters in Jiangsu and Shandong provinces supply municipal water utilities replacing aging cast iron distribution networks.
Saudi Arabia
Saudi Aramco sour gas expansion programs specify spoolable composite gathering lines to eliminate metal corrosion in high-H2S fields. SAMR technical regulations align with API standards for petroleum service qualification. Jubail Industrial City hosts integrated filament winding operations serving regional oilfield infrastructure deployment.
Brazil
Petrobras pre-salt development contracts mandate specialized flexible riser architectures for dynamic deepwater service. ANP local content requirements shape procurement specifications for subsea composite systems. Manufacturing presence concentrates around Rio de Janeiro state to support offshore installation logistics.
Composite Pipes Market Vendor Landscape
Middle Eastern fabricators anchor one tier serving regional oilfield infrastructure; North American and European specialists hold premium positioning in subsea and regulated industrial applications. The vendor base separates into integrated energy service conglomerates, dedicated pipe manufacturers, and materials-technology licensors. Three archetypes dominate: filament winding specialists, flexible riser engineers, and thermoset resin compounders. Competitive moves concentrate on qualification list consolidation by supermajor operators and backward integration into fiber precursor supply.
Among Middle Eastern-based fabricators, Future Pipe Industries and Amiantit exemplify regional scale archetypes with integrated manufacturing footprints. Shawcor occupies a position within the specialized subsea tier. These named entities represent competitive positioning patterns rather than operational specifics. The broader field includes energy service conglomerates with composite divisions, independent pipe manufacturers, and materials suppliers licensing resin technology. Market access depends increasingly on pre-qualification with Chevron, ExxonMobil, and other supermajor procurement systems that have compressed approved vendor lists to two or three regional suppliers.
| Leading Market Players |
|---|
| National Oilwell Varco |
| Future Pipe Industries |
| Amiantit |
| Tenaris |
| Owens Corning |
| Trelleborg |
| Shawcor |
| TechnipFMC |
| Baker Hughes |
| Others |
Supply Flow & Price Mechanics
Automated filament winding with in-situ thermoplastic consolidation is compressing production cycle times while concentrating equipment supply among German and Japanese machinery builders. This manufacturing transition simultaneously reduces per-meter labor costs and deepens dependency on specialized mandrel suppliers, reshaping how procurement teams negotiate volume contracts across sour gas and water transmission segments.
Pricing Analysis
Distributor margins on API-qualified thermoset systems typically run 12-18 percent before installation services, with direct-to-operator contracts commanding 8-12 point discounts for qualified supermajors. Three-tier pricing structure across API-premium, ISO-standard, and municipal-economy certification levels separates flexible riser specifications from water distribution retrofits. Cost compression in glass fiber reinforced segments is intensifying as Chinese filament winding capacity expands into Southeast Asian export markets. Municipal utilities in Germany exhibit the highest price sensitivity due to EU Drinking Water Directive compliance budget caps, while offshore contractors in Brazil accept premium positioning for fatigue-rated carbon fiber architectures.
Supply Chain Analysis
Single-source vulnerability sits with Toray and Hexcel carbon fiber precursor facilities concentrated in Japan and the United States. Raw material flows draw from S-glass roving operations in China, epoxy resin compounding in Germany, and specialized thermoplastic liner extrusion in the Netherlands. Tariff exposure on carbon fiber tows threatens margin stability for high-pressure riser manufacturers serving Petrobras pre-salt contracts. Distribution runs through regional pipe distributors in Houston and Rotterdam, with project-direct shipments dominating offshore flexible pipe procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Composite Pipes Market functions as a stable compounder anchored by infrastructure replacement cycles that operate independently of commodity price volatility. Regulatory corrosion mandates and network modernization programs provide predictable demand visibility across multi-year procurement horizons.
For Market Incumbents: Deepen backward integration into glass fiber roving supply through captive production in Jiangsu or strategic offtake agreements with Owens Corning. Incumbents must also accelerate API 15S qualification for thermoplastic-lined systems before emerging entrants capture sour gas specification shifts. Certification investment represents the critical defensive lever against specialized flexible riser engineers consolidating supermajor approved vendor lists. For New Entrants and Emerging Players: Begin with modular spoolable pipe fabrication targeting remote Permian Basin gathering systems where logistics costs disadvantage integrated manufacturers. The most penetrable white space sits in mobile filament winding services for Chinese municipal water utilities replacing cast iron distribution networks. A joint-venture structure with established resin compounders accelerates REACH and F-Gas compliance without captive R&D investment. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap filament winding specialists with underutilized capacity in Saudi Arabia and the UAE. The five-to-ten year viability window favors targets with established API qualification and existing supermajor procurement relationships rather than technology-stage materials innovators. The signal to watch is hydrogen compatibility standard finalization by ISO committees, which will trigger qualification spending waves and consolidate supplier positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Precursor Supply | Captive S-glass roving production in China reduces exposure to import tariff volatility. |
| Hydrogen Compatibility Certification Investment | Early ISO 14692 amendment qualification positions vendors for German and Dutch pipeline tenders. |
| Mobile Filament Winding Deployment | Portable production systems compress delivery timelines for remote West African oilfield development. |
| Thermoplastic Liner Technology Transition | Polyamide-lined systems displace thermoset dominance in high-H2S sour gas applications. |
| Supermajor Approved Vendor List Consolidation | Chevron and ExxonMobil procurement compression favors scale players with dual API-ISO qualification. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pipeline procurement officers, filament winding plant managers, API certification engineers, and municipal utility engineering directors with secondary validation through customs trade data, API qualification registries, SEC filings from energy service conglomerates, and EU F-Gas Regulation implementation tracking. Bottom-up segment sizing across fiber type, end user, and technology categories triangulated against top-down macroeconomic drivers.
Comparable historical periods anchored the projection framework, with growth rates derived from segment-specific demand elasticity models calibrated to infrastructure replacement cycle timing. The analytical framework modeled volume and value across glass-carbon-aramid reinforcement categories, oil-gas-water-chemical end-use splits, and filament winding-pultrusion-RTM technology trajectories. Forecast inputs included municipal water network age profiles, sour gas field development pipelines, and regulatory compliance deadline clustering.
Several conditions sit outside the modeled scope, including geopolitical disruption to carbon fiber precursor trade flows and acceleration of hydrogen economy infrastructure beyond current pilot project scales. Forecasts reflect documented assumptions about API standard revision timing and EU F-Gas phase-down adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Saudi Arabia PE Pipes Market
Pipes and Tubes
Global Fiberglass Pipe Market
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
Pipes and Fittings Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
North America PVC Pipes Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
GCC PVC Pipes Market
Pipes and Tubes
Europe Pipe Market
Pipes and Tubes
Piping System and Piping Spools Market
Pipes and Tubes
Kuwait PVC Pipes Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
Galvanized Steel Tubes Market
Pipes and Tubes
Gas Fittings and Components Market
Pipes and Tubes
Global Lance Tubes Market