
 Piping System and Piping Spools Market | 2026-2036
Piping System and Piping Spools Market Size, Share, and Industry Trends Forecast 2026-2036
Piping System and Piping Spools Market Outlook
Buyer concentration in the oil and gas sector is consolidating, with supermajors and national oil companies narrowing supplier panels to prefabrication specialists who can deliver modular spool packages at scale. ChelPipe Group anchors its position through captive steel production and integrated pipe mills stretching from Volzhsky to Chelyabinsk. Larsen & Toubro competes on EPC bundling, leveraging its construction execution capability to wrap piping into larger infrastructure contracts. Cimtas Pipe Fabrication and Trading Co Ltd. specializes in export-oriented spool fabrication, operating accredited shops that serve North Sea and Middle East project specifications.
Piping systems and piping spools encompass the interconnected network of pipes, fittings, supports, and prefabricated assemblies that convey fluids, gases, or slurries under pressure, temperature, and corrosion constraints across industrial facilities; spools are shop-fabricated sections welded to exact isometric drawings, then field-bolted to reduce site labor and improve quality control. Carbon steel dominates material selection for oil and gas and power generation end users due to its cost efficiency and weldability in high-pressure service, while stainless steel commands premium positioning in chemical processing where chloride corrosion resistance is non-negotiable. Flanges and valves represent concentrated margin pools because they require precision machining, material traceability, and third-party certification that smaller fabricators struggle to replicate.
API standards, ASME Boiler and Pressure Vessel Code sections, and EU Pressure Equipment Directive compliance shape product design, welding procedure qualification, and market access for fabricated spools destined for hazardous service. India's BIS certification and the country's national petroleum regulator enforce local content requirements that redirect procurement toward domestic fabrication shops. Stakeholders must monitor how carbon border adjustments and evolving methane-emission standards recalibrate material sourcing and welding energy intensity across their supplier networks.
Market Dynamics
Modular construction methods are compressing field-weld schedules and redirecting fabrication volume toward accredited shop environments with robotic welding cells and automated NDT lines.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant-phaseout mandates are redirecting material specifications toward lower-emission alloys and polymer alternatives in HVAC and process cooling systems.
- Power generation utilities:Prefabricated spool adoption is accelerating to compress construction schedules and reduce critical-path exposure at combined-cycle and nuclear sites.
- India infrastructure buildouts:National refinery expansions and petrochemical complexes are absorbing record volumes of fabricated piping systems with integrated EPC bundling.
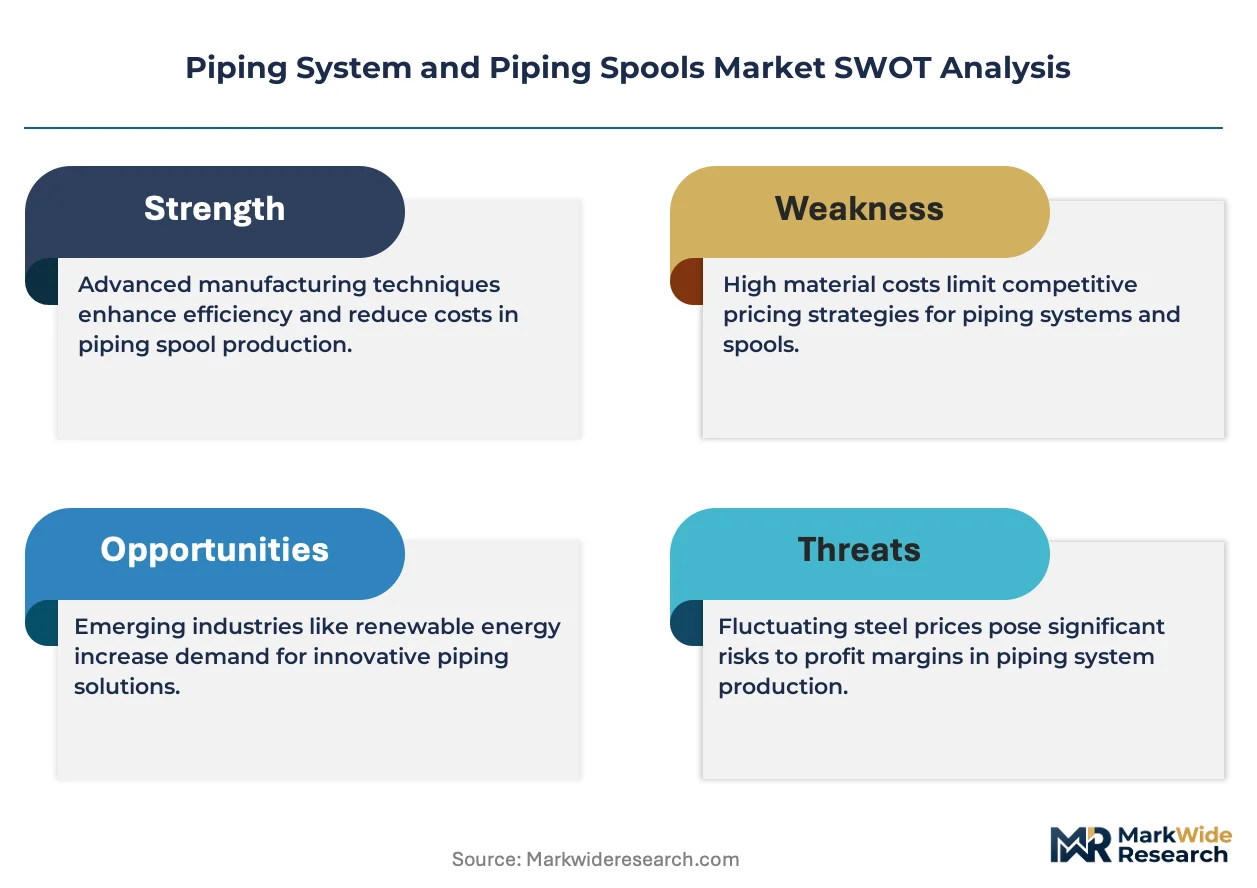
Market Restraints
- Alloy input volatility:Nickel and molybdenum price swings compress margin predictability for stainless steel spool fabricators serving chemical processing contracts.
- Specialized welder scarcity:ASME Section IX certified welders concentrate in legacy industrial clusters, constraining capacity expansion in emerging fabrication hubs.
- Carbon border adjustments:Emerging trade mechanisms threaten to recalibrate sourcing economics for carbon-intensive steel feedstock from traditional supplier geographies.
Strategic Opportunities
- Hydrogen transport infrastructure:High-pressure hydrogen service specifications are opening demand for 316L and duplex stainless spool packages with specialized cleaning and testing protocols.
- Digital twin integration:Convergence of laser scanning and cloud-based spool management platforms enables real-time fabrication tracking and predictive logistics coordination.
- India PLI scheme:Domestic manufacturing incentives are redirecting multinational procurement toward accredited Indian fabrication shops with API and ASME certifications.
Industry Challenges
- Welding procedure qualification delays:ASME Section IX and API 1104 requalification timelines stretch project kickoffs when base materials or processes change mid-contract.
- Material traceability complexity:MTR verification and third-party witness requirements multiply administrative burden across multi-tier supplier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piping System and Piping Spools Market |
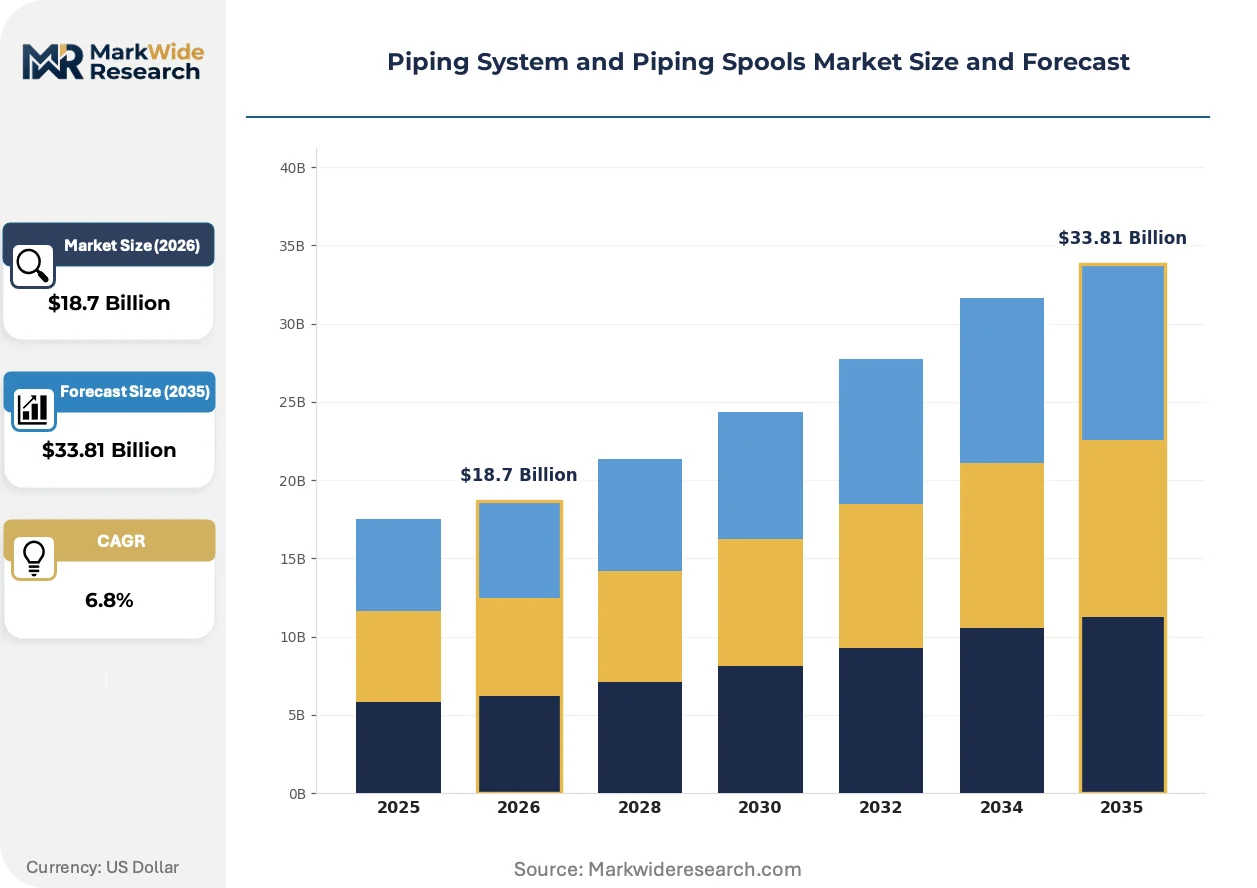
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pipe Fittings, Pipe Supports, Flanges, Valves Material: Stainless Steel, Carbon Steel, PVC, Copper End User: Oil & Gas, Power Generation, Water Treatment, Chemical Processing Installation Type: Above Ground, Below Ground, Indoors, Outdoors |
| Companies Covered | International Co for Steel Structure (AIC), CCI Leiding systemen B.V., ChelPipe Group, Cimtas Pipe Fabrication and Trading Co Ltd., Cogbill Construction LLC, Dee Development Engineering Limited, Metal Forge India, Prosaic Steel and Alloys, Larsen & Toubro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piping System and Piping Spools Market Strategic Shifts
Digital fabrication workflows and automated inspection protocols are displacing manual coordination methods. Three developments are restructuring competitive capability requirements.
Automated orbital welding systems are decentralizing spool production from concentrated fabrication centers toward distributed job-site containers and regional micro-factories. Offshore platform operators and remote mining developers are deploying containerized welding cells to eliminate logistics exposure and compress schedule risk. This capability dispersion is fragmenting the traditional shop-fabrication model and enabling new geographic entrants.
REACH substance restrictions and the EU F-Gas Regulation are forcing material substitutions across process piping specifications. Industrial refrigeration and chemical transfer systems face reformulation pressure as legacy elastomers and brazing alloys lose authorization. German and Dutch engineering contractors are accelerating qualification programs for polymer-lined carbon steel and mechanically bonded composite alternatives.
Integrated EPC contractors are unbundling spool fabrication from construction management and awarding direct to specialized shops with captive NDT and heat-treatment capabilities. This disintermediation strips margin from generalist fabricators and concentrates volume with accredited specialists. The pattern is most visible in Middle East petrochemical expansions where owner-operators mandate direct supplier relationships for critical-path spool packages.
Piping System and Piping Spools Market Segmentation
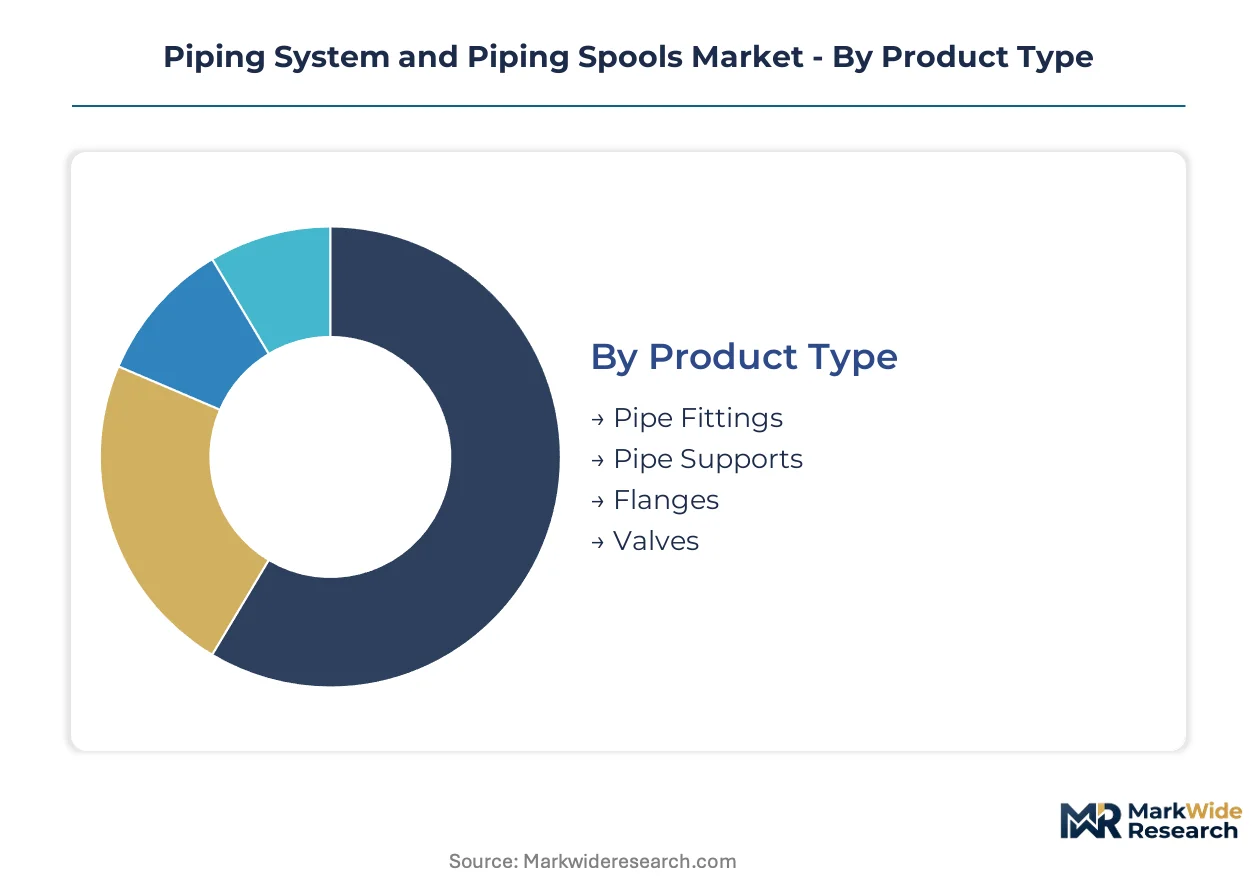
Piping system segmentation directly governs procurement economics and fabrication workflows. Material selection and product specifications cascade through welding procedures, inspection protocols, and logistics planning.
Product Type:
Standardization concentrates in commodity fittings while precision-machined components demand project-specific customization.
- Flanges:Forged rings with precision-machined sealing faces connect pipe sections under pressure and temperature cycling. API 6A and ASME B16.5 specifications govern dimensional tolerances for oil field and refinery service. Demand clusters in Middle East petrochemical expansions where owner-operators mandate direct supplier relationships for critical-path packages.
- Valves:Flow control devices with actuated or manual operation isolate, throttle, or divert process streams. Ball and gate configurations dominate hydrocarbon service while butterfly valves concentrate in water treatment. Margin pools here exceed commodity fittings due to material traceability and third-party certification requirements that smaller fabricators cannot replicate.
- Pipe Fittings:Elbows, tees, and reducers redirect or combine flow paths in standard pressure classes.
- Pipe Supports:Structural anchors and guides manage thermal expansion and seismic loading in elevated and buried service.
Most installed capacity flows through Pipe Fittings. Expansion is steepest in Valves.
Material:
Cost tiers separate commodity carbon grades from corrosion-resistant alloys with specialized welding protocols.
- Carbon Steel:ASTM A106 and API 5L grades dominate oil and gas transmission due to weldability and cost efficiency in high-pressure service. Specifiers favor this material for above-ground pipeline and power plant boiler feedwater systems where chloride exposure remains minimal.
- Stainless Steel:Austenitic 304/316 and duplex 2205 grades resist chloride stress corrosion in chemical processing and offshore environments. Premium positioning here reflects nickel and molybdenum content volatility that compresses margin predictability for fabricators serving long-term contracts.
- PVC:Thermoplastic piping serves low-pressure water distribution and drainage with solvent-weld jointing.
- Copper:Seamless tubing dominates refrigeration and potable water applications requiring antimicrobial properties.
Carbon Steel carries the largest installed base. Stainless Steel is gaining share fastest in hydrogen transport and chemical processing retrofits.
End User:
Application severity dictates material grade, inspection intensity, and documentation depth across customer categories.
- Oil & Gas:Upstream gathering networks, midstream transmission, and downstream refining impose ASME Section IX welding and API 1104 inspection protocols. Supermajors and national oil companies are narrowing supplier panels to prefabrication specialists who deliver modular spool packages at scale.
- Power Generation:Combined-cycle and nuclear sites specify high-purity feedwater and steam systems with rigorous cleanliness requirements. Utilities are accelerating prefabricated spool adoption to compress construction schedules and reduce critical-path exposure.
- Chemical Processing:Acid service and high-temperature reactors demand alloy selection with full material traceability.
- Water Treatment:Municipal and industrial desalination plants specify linings and coatings for corrosion management.
Oil & Gas absorbs the highest fabrication volume. Power Generation shows the steepest expansion trajectory as nuclear and hydrogen-ready units advance.
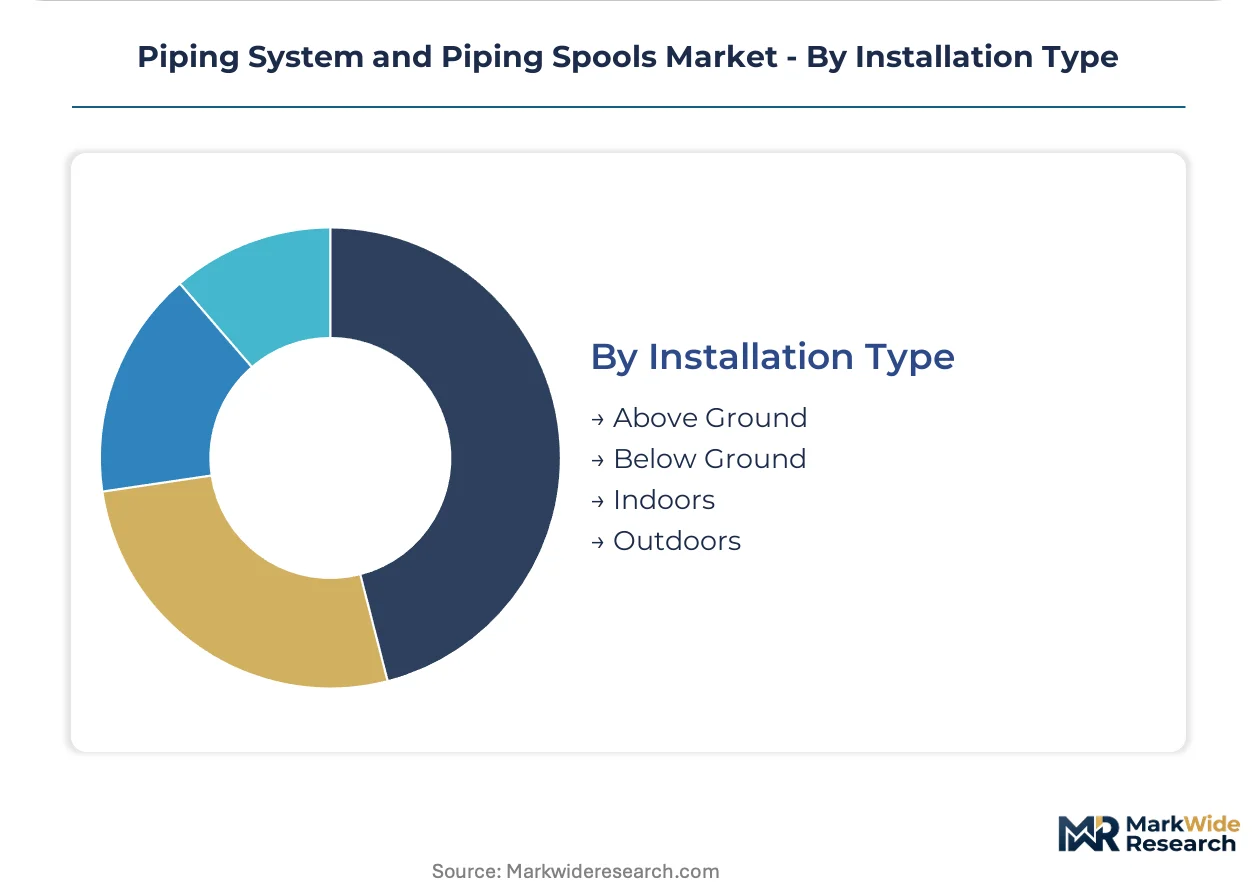
Installation Type:
Geographic and structural constraints determine spool configuration, coating systems, and jointing methods.
- Below Ground:Buried pipelines and utility distribution networks require external corrosion coatings, cathodic protection, and trenchless installation methods. Demand concentrates in India where national infrastructure buildouts and refinery expansions are absorbing record volumes of fabricated piping systems.
- Above Ground:Elevated rack piping and process unit interconnects allow welded construction with visual inspection access. Modular fabrication shops preassemble these sections for bolted field erection.
- Indoors:Controlled environments permit tighter tolerances and cleaner welding conditions for high-purity service.
- Outdoors:Weather exposure drives coating selection and thermal expansion accommodation in structural supports.
Below Ground represents the largest installed base. Above Ground is expanding most quickly with modular construction adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India absorbs record fabrication volumes while Germany redirects specifications toward lower-emission alloys under refrigerant-phaseout mandates. This divergence reflects contrasting infrastructure cycles and regulatory pressures across major economies.
United States
Power generation utilities accelerate prefabricated spool adoption to compress nuclear and combined-cycle construction schedules. FERC grid interconnection standards and EPA methane-emission monitoring reshape material sourcing for gas transmission infrastructure. Houston-Gulf Coast fabrication clusters concentrate robotic welding capacity serving Permian Basin midstream expansions.
India
National refinery expansions and petrochemical complexes absorb fabricated piping systems at unprecedented scale. BIS certification and petroleum regulator local-content requirements redirect procurement toward domestic shops with API and ASME accreditations. Gujarat and Maharashtra industrial corridors host integrated EPC bundling operations capturing PLI scheme incentives.
Germany
REACH substance restrictions and EU F-Gas Regulation force material substitutions in process refrigeration and chemical transfer systems. Engineering contractors in the Ruhr and Bavaria accelerate qualification programs for polymer-lined carbon steel and composite alternatives. Dortmund fabrication specialists serve North Sea project specifications with accredited NDT and heat-treatment capabilities.
Saudi Arabia
Mega-project pipelines in hydrogen-ready ammonia and blue hydrogen facilities specify high-pressure service spool packages. SFDA industrial safety protocols and Saudi Aramco engineering standards govern welding procedure qualification and material traceability. Jubail Industrial City hosts specialized shops delivering direct supplier relationships for critical-path packages.
China
Dual carbon goals and MIIT industrial efficiency mandates compress steel-intensive fabrication timelines. Yangtze River Delta and Shandong Peninsula clusters integrate automated orbital welding systems into distributed micro-factory networks. NMPA-equivalent pressure equipment oversight tightens documentation depth for hazardous service exports.
Piping System and Piping Spools Market Competitive Environment
Russian and Indian producers anchor one tier; Dutch and Turkish specialists hold accredited export positions. The vendor base concentrates around integrated steel-pipe mills, EPC bundling contractors, and standalone fabrication shops with captive NDT capabilities. Three archetypes dominate: captive steel producers, construction-integrated EPCs, and export-oriented specialists. Capacity expansion and strategic disintermediation represent the dominant competitive vectors as owner-operators mandate direct supplier relationships.
Within the integrated steel-producer tier, ChelPipe Group exemplifies backward control through captive pipe mills stretching from Volzhsky to Chelyabinsk. Larsen & Toubro occupies a position representing EPC-bundling archetypes that wrap piping fabrication into larger infrastructure execution contracts. Cimtas Pipe Fabrication and Trading Co Ltd. anchors the export-specialist segment with accredited shops serving North Sea and Middle East project specifications.
| Leading Market Players |
|---|
| International Co for Steel Structure (AIC) |
| CCI Leiding systemen B.V. |
| ChelPipe Group |
| Cimtas Pipe Fabrication and Trading Co Ltd. |
| Cogbill Construction LLC |
| Dee Development Engineering Limited |
| Metal Forge India |
| Prosaic Steel and Alloys |
| Larsen & Toubro |
| Others |
Value Chain & Pricing Dynamics
ASME Section IX certified welders concentrated in legacy industrial clusters from Houston-Gulf Coast to the Ruhr create labor-cost differentials that separate premium-tier project-based pricing from commoditized spot-market fittings. This workforce geography compresses margin predictability for fabricators serving long-term chemical processing contracts while enabling tiered pricing spreads between accredited shop environments and field-weld alternatives.
Pricing Analysis
Capacity additions in India are reshaping price floors for carbon steel spool packages as PLI scheme incentives redirect multinational procurement toward accredited domestic fabrication shops. Pricing stratifies across premium, standard, and economy tiers based on API/ASME certification depth and material traceability documentation. Cost compression in standard-grade carbon steel intensifies because alloy input volatility, particularly nickel and molybdenum swings, squeezes fabricator margins. National oil companies and supermajors exhibit lowest price sensitivity due to critical-path schedule exposure, while municipal water treatment authorities demonstrate highest sensitivity to unit economics.
Supply Chain Analysis
Specialty alloy feedstock rests on Russian integrated steel-pipe mills, Indian domestic shops with BIS certification, and German REACH-compliant processors. Raw material dependencies center on nickel-bearing stainless grades, molybdenum-enhanced duplex alloys, and polymer-lined carbon steel alternatives. Single-source vulnerability concentrates in ASME-accredited heat-treatment and NDT capabilities clustered in legacy industrial corridors. Distribution runs through direct supplier relationships mandated by Middle East petrochemical owner-operators for critical-path spool packages, bypassing generalist EPC intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The piping system and piping spools market functions as a stable compounder anchored by infrastructure replacement cycles and energy transition capital deployment that sustains fabrication demand across volatile commodity cycles.
For Market Incumbents: Lock in captive NDT and heat-treatment capabilities to defend against disintermediation as integrated EPC contractors unbundle spool fabrication from construction management. Prioritize backward integration into specialty alloy sourcing to buffer margin compression from nickel and molybdenum price volatility. Expand robotic welding cell deployment in India to capture PLI scheme incentives and preempt emerging fabrication hub competition.
For New Entrants and Emerging Players: Remote mining developers and offshore platform operators represent underserved buyer archetypes seeking containerized welding cells that eliminate logistics exposure and compress schedule risk. Hydrogen-ready ammonia facilities in Saudi Arabia offer the most penetrable application segment given high-pressure service specification gaps and specialized cleaning protocol demands. Pursue direct accreditation pathways with Saudi Aramco engineering standards and API certifications to bypass established supplier panel barriers.
For Investors and Strategic Acquirers: Integrated EPC contractors are the most active acquirer in this space, seeking accredited fabrication shops with captive quality infrastructure to internalize critical-path spool supply. Long-term viability centers on hydrogen transport infrastructure buildouts and nuclear power generation expansion that extend fabrication demand visibility. Monitor carbon border adjustment mechanism implementation progress as the signal to watch for sourcing economics recalibration and welding energy intensity compliance costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Automated orbital welding cells in India capture PLI scheme incentives and redirect multinational procurement. |
| Backward Integration | Captive steel production from Volzhsky to Chelyabinsk insulates ChelPipe Group from alloy input volatility. |
| Long-term Supply Agreement | Direct supplier relationships with Saudi Aramco bypass EPC intermediaries and secure critical-path volume. |
| Joint Venture | Gujarat and Maharashtra industrial corridors enable integrated EPC bundling with domestic content compliance. |
| Green Certification Program | REACH substance restrictions and EU F-Gas Regulation redirect specifications toward lower-emission alloys. |
Study Parameters
Coverage spans the United States, India, Germany, Saudi Arabia, and China, with primary inputs from each region combining structured interviews with plant managers, EPC procurement leads, downstream OEM engineering teams, and aftermarket service heads with secondary validation. Trade data from customs filings, ASME certification registries, API licensee databases, and national petroleum regulator local-content disclosures anchor quantitative baselines. Bottom-up project pipeline aggregation and top-down industrial capex trajectories triangulate market sizing.
Granularity-level modeling disaggregates volume and value across material grade tiers, end-use severity classifications, installation environment constraints, and regional regulatory clusters throughout the forecast period. CAGRs derive from segmented growth rate application with cross-validation against macro industrial production indices. Hydrogen transport infrastructure specifications and nuclear construction restart timelines constitute industry-specific forecast inputs.
Underlying measurement precision varies by segment; oil and gas and power generation end-use categories carry tighter precision than emerging hydrogen service applications due to established project reporting conventions. Forecasts reflect documented assumptions regarding alloy price stabilization, welder certification throughput, and carbon border adjustment implementation scope. Regulatory timeline shifts, methane-emission standard tightening, and trade mechanism evolution warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global Fluoropolymer Tubing Market
Pipes and Tubes
Global Cured-In-Place Pipe Market
Pipes and Tubes
Saudi Arabia PVC Pipes Market
Pipes and Tubes
Cold Drawn Seamless (CDS) Steel Pipes Market
Pipes and Tubes
Saudi Arabia Copper Pipes and Tubes Market
Pipes and Tubes
Perfusion Tubing Systems Market
Pipes and Tubes
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market
Pipes and Tubes
Steel Tubes Market
Pipes and Tubes
Qatar PVC Pipe Market
Pipes and Tubes
Stainless Steel Plumbing Pipes and Fittings Market
Pipes and Tubes
Tapping Sleeves Market
Pipes and Tubes
Saw Pipes Market
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market
Pipes and Tubes
Global Polyolefin Pipes Market
Pipes and Tubes
Global Titanium Tube Market
Pipes and Tubes
Steel Pipes and Tubes Market