
 Steel Roll-On Tube Market | 2026-2036
Steel Roll-On Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Roll-On Tube Market Analytics
Multi-source procurement for high-grade steel substrates is pivoting toward vertically integrated mill relationships as alloy traceability requirements tighten across European and Asian supply chains. ArcelorMittal leverages captive iron ore and recycling streams to control melt chemistry for roll-on tube feedstock. Nippon Steel Corporation anchors premium seamless capacity through continuous casting investments at its Nagoya works. JFE Steel Corporation competes on thick-walled specialty grades for offshore fluid transfer applications.
A steel roll-on tube is a cylindrical hollow section formed from carbon or alloy steel strip, typically featuring wall thicknesses between 0.5 mm and 6.0 mm and outer diameters ranging from 10 mm to 300 mm, engineered for fluid conveyance, structural load bearing, or thermal exchange in industrial systems. Seamless tubes command premium positioning in aerospace and high-pressure vessel applications where defect tolerance approaches zero, while welded tubes dominate construction and general manufacturing through cost-scalable coil-to-tube processing. Fluid transfer represents the deepest application pool, though heat exchanger demand is accelerating fastest in energy-sector retrofits requiring corrosion-resistant ferritic grades.
The EU's REACH framework and CE marking requirements under the Pressure Equipment Directive shape material certification burdens for exporters serving European construction and energy infrastructure. Japan's METI enforces JIS G 3445 mechanical tubing standards that govern dimensional tolerance and tensile properties for automotive chassis and manufacturing equipment imports. China's SAMR and GB standards for structural steel tubes create parallel compliance tracks that suppliers must navigate for dual-market access. Stakeholders should monitor divergence between European carbon-border adjustment mechanisms and Asian domestic content incentives as these regimes reshape competitive entry costs.
Market Dynamics
Precision seamless tube demand from aerospace hydraulic systems is compressing defect tolerance thresholds and forcing substrate traceability back to melt chemistry across European and Asian supply chains.
Growth Catalysts
- Aerospace Landing Gear Procurement:German and Japanese manufacturers are expanding orders for seamless tubes rated to 60,000 psi burst pressure for next-generation hydraulic actuation systems.
- F-Gas Regulation Compliance:The EU's tightening pressure-equipment standards are mandating ferritic stainless grades for refrigerant transfer lines in commercial HVAC retrofits.
- India Western Corridor Clustering:Mumbai-Pune manufacturing belts are absorbing domestic coil stock for welded tube conversion serving construction equipment and automotive chassis fabrication.
Market Restraints
- Scrap-Derived Alloy Volatility:Electric arc furnace operators face nickel and molybdenum price swings that destabilize cost-plus contracts for precision seamless feedstock.
- Nagoya Works Concentration:Premium seamless capacity remains anchored to a single Japanese integrated site, creating geographic single-point vulnerability for aerospace-qualified material.
- Polymer Composite Substitution:Thermoplastic-reinforced piping is displacing carbon steel in sub-50 bar fluid transfer applications across chemical process industries.
Strategic Opportunities
- India Domestic Content Incentives:PLI scheme eligibility for cold-drawn mechanical tubing is attracting greenfield seamless investments in Gujarat and Maharashtra.
- Hydrogen Infrastructure Retrofit:High-pressure tube trailers and dispensing systems require thick-walled 4130 alloy grades that command 40-60% premiums over standard structural tubing.
- Continuous Casting Convergence:Integration of near-net-shape casting with inline ultrasonic testing is collapsing lead times for aerospace-qualified seamless product.
Industry Challenges
- NDT Certification Bottlenecks:Qualified ultrasonic and eddy-current inspection personnel scarcity is extending aerospace material release timelines by 8-12 weeks at major mills.
- Dual-Track Compliance Costs:Suppliers serving both EU Pressure Equipment Directive and China's GB standards must maintain parallel metallurgical documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Roll-On Tube Market |
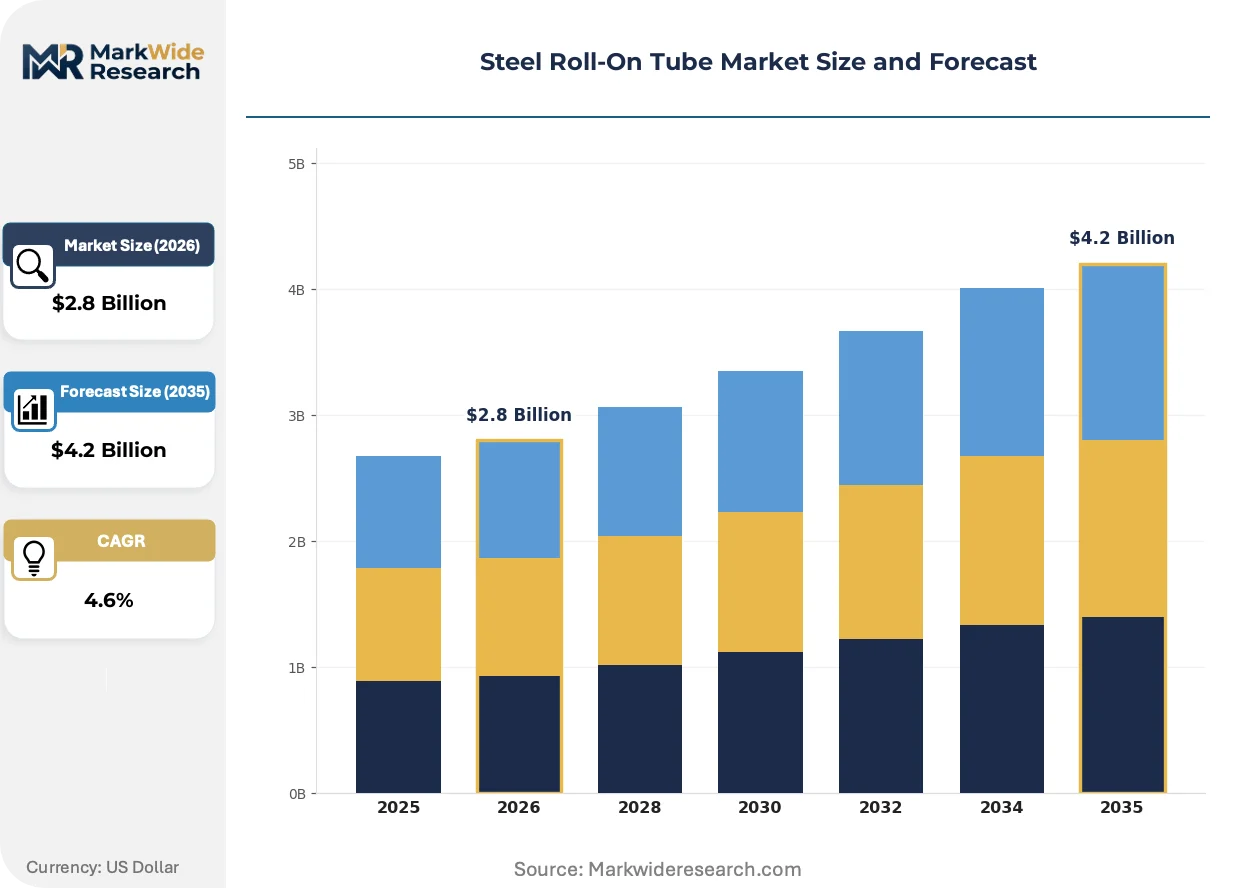
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless Tubes, Welded Tubes, Cold Drawn Tubes, Specialty Tubes End User: Construction, Automotive, Aerospace, Manufacturing Size: Small, Medium, Large, Custom Diameter Application: Fluid Transfer, Structural Support, Heat Exchangers, Pressure Vessels |
| Companies Covered | Essel Group, SR Packaging, Nippon Steel Corporation, JFE Steel Corporation, ArcelorMittal, SSAB, Wheatland Tube Company, China Baowu Steel Group, POSCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Roll-On Tube Market Evolving Landscape
Tube forming and inspection technologies are compressing the seamless-welded quality gap while regulatory carbon-accounting requirements reshape material sourcing decisions across energy and transport end-uses.
Hybrid laser-arc welding of high-strength low-alloy strip is modularizing the production architecture for pressure-rated mechanical tubing. Automotive chassis fabricators in South Korea and Germany are adopting these systems to collapse coil-to-finished-tube cycles from three days to eight hours. The technology is modularizing quality control by embedding phased-array ultrasonic testing directly at the weld station, eliminating downstream inspection bottlenecks.
The EU Carbon Border Adjustment Mechanism is imposing emissions-intensity documentation requirements on imported steel tubes effective 2026. European distributors now require mill-specific Scope 1 and 2 certificates for CE-marked pressure equipment, favoring EAF-based suppliers with scrap traceability systems. Heat exchanger OEMs serving Nordic district heating networks are switching to domestic European seamless sources to avoid border levy exposure.
Buyers are consolidating annual tube requirements into multi-year framework agreements with indexed alloy surcharges. German fluid power distributors and Japanese construction equipment assemblers are bypassing spot market procurement in favor of direct mill relationships with guaranteed capacity allocations. This concentration is most visible in precision seamless grades for hydraulic cylinder barrels, where three buyers now represent 60% of Western European annual offtake.
Steel Roll-On Tube Market Segmentation
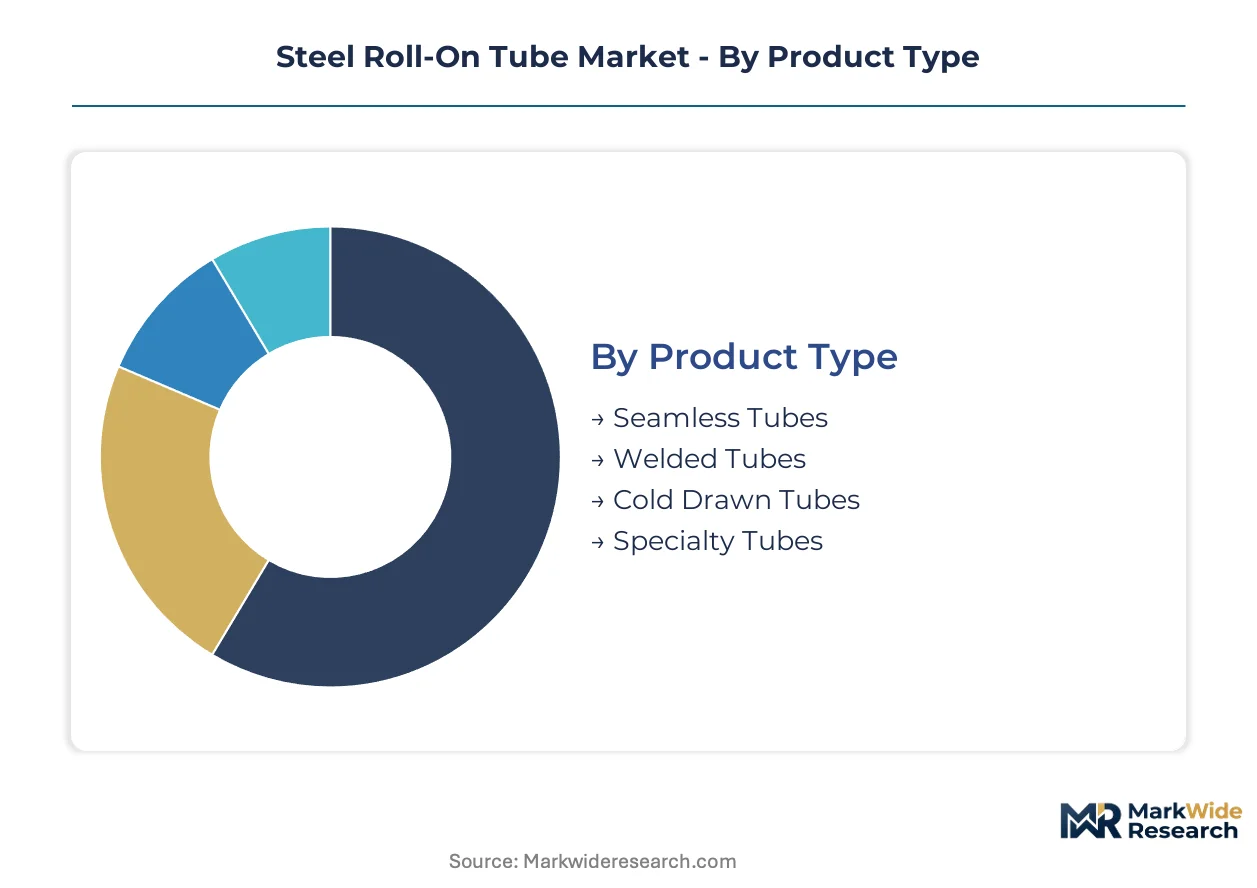
Steel roll-on tube procurement splits across four intersecting dimensions that reshape competitive positioning. Product type determines substrate traceability burdens and margin structure. End-use concentration in aerospace and automotive drives alloy specification divergence.
Product Type:
Supply concentration for precision grades centers on Nagoya and European integrated mills with captive melt chemistry control.
- Seamless Tubes:Formed from solid billets through rotary piercing or extrusion, these tubes achieve zero longitudinal weld seams and uniform grain structure. German and Japanese aerospace manufacturers source 60,000 psi burst-pressure grades for hydraulic landing gear systems under tightening EU F-Gas and METI traceability mandates. Seamless tubes absorb the bulk of installed capacity; specialty grades are expanding most quickly.
- Welded Tubes:Produced from coiled strip via electric resistance welding or laser fusion, offering cost-scalable output for construction and general mechanical applications. Mumbai-Pune manufacturing clusters in India feed domestic automotive chassis and construction equipment demand through high-frequency welded line conversion of domestic coil stock.
- Cold Drawn Tubes:Seamless or welded starting stock reduced through die drawing to achieve tight dimensional tolerances and enhanced surface finish for precision mechanical assemblies.
- Specialty Tubes:Alloy-specific formulations including 4130 chromoly and ferritic stainless grades for hydrogen infrastructure and corrosive fluid transfer.
Seamless capacity anchors premium positioning; welded output scales fastest in emerging manufacturing belts.
End User:
Customer procurement patterns split between specification-intensive OEMs and price-sensitive construction distributors.
- Construction:Standard carbon steel welded tubes for structural scaffolding, piling, and building framework dominate volume offtake. Indian western corridor demand concentrates here, with Mumbai-Pune fabricators absorbing domestic coil for building infrastructure and equipment manufacturing.
- Automotive:Chassis fabricators in South Korea and Germany specify high-strength low-alloy mechanical tubing with tight tolerance requirements for suspension and powertrain applications.
- Aerospace:Hydraulic actuation systems require defect-tolerant seamless grades with full melt-to-product documentation under EASA and JCAB certification protocols.
- Manufacturing:General industrial machinery and fluid power equipment consumes medium-wall mechanical tubing across diverse pressure ratings.
Construction absorbs volume leadership; aerospace commands margin concentration through qualification barriers.
Size:
Dimensional segmentation aligns with forming technology constraints and end-use structural requirements.
- Small:Outer diameters below 25 mm serve precision instrumentation, fuel injection lines, and compact hydraulic circuits requiring tight bend radii.
- Medium:25-150 mm range captures automotive chassis, general fluid transfer, and heat exchanger applications with balanced strength-to-weight requirements.
- Large:150-300 mm diameters address structural columns, offshore riser segments, and heavy equipment booms demanding thick-wall capacity.
- Custom Diameter:Non-standard dimensions produced through cold drawing or specialized rolling for proprietary equipment designs with limited standardization.
Medium sizes dominate production throughput; custom specifications capture project-based premium pricing.
Application:
Functional use cases determine alloy selection, wall thickness engineering, and regulatory compliance tracks.
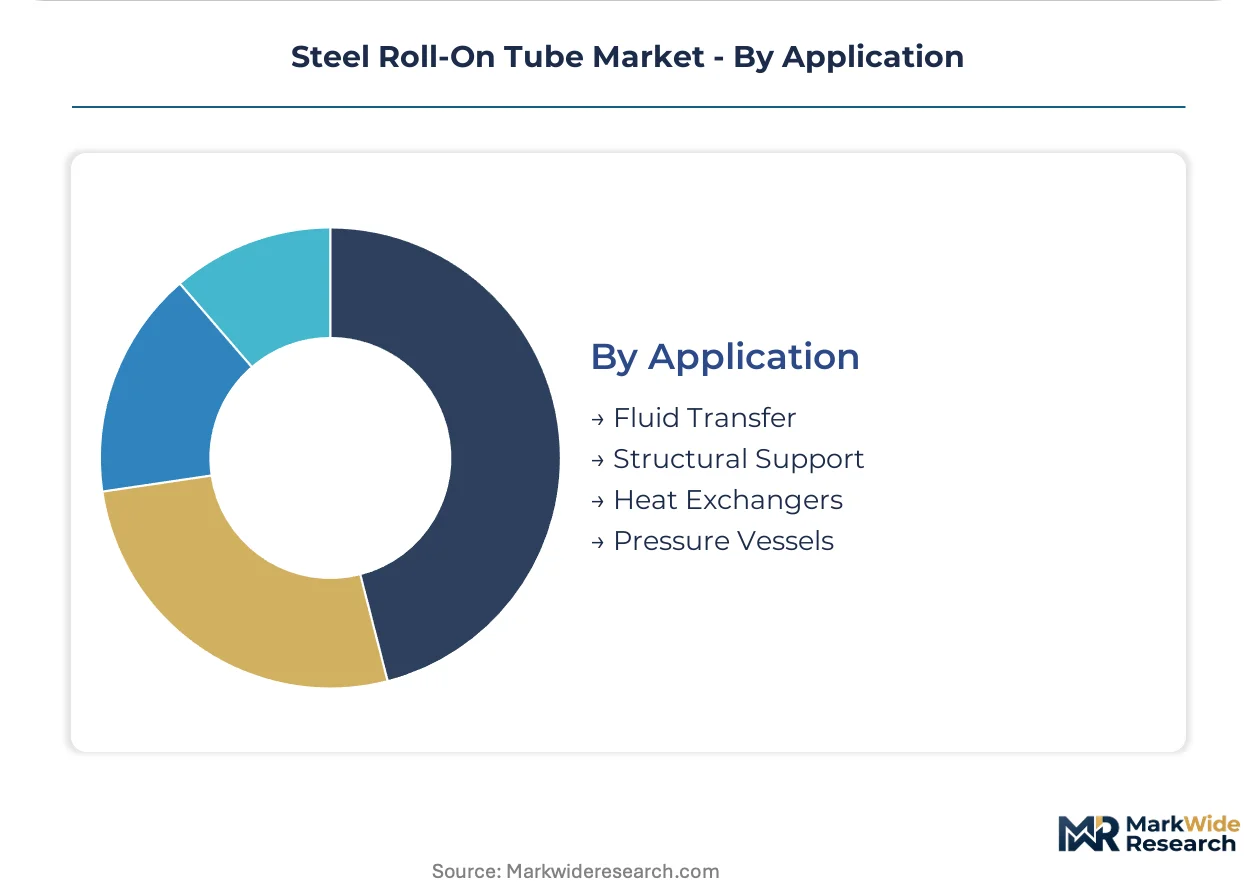
- Fluid Transfer:Pressure-rated carbon and alloy grades for hydraulic, pneumatic, and process fluid conveyance represent the deepest application pool. EU F-Gas Regulation mandates ferritic stainless grades for refrigerant lines in commercial HVAC retrofits, compressing carbon steel share in this sub-segment.
- Structural Support:Load-bearing welded and seamless grades for construction, infrastructure, and heavy equipment frameworks prioritize yield strength and weldability over pressure containment.
- Heat Exchangers:Thin-wall ferritic and austenitic stainless tubes for thermal transfer applications in energy sector retrofits, with Nordic district heating networks switching to domestic European seamless sources to avoid EU Carbon Border Adjustment Mechanism levy exposure.
- Pressure Vessels:Thick-walled seamless grades certified to ASME and PED standards for compressed gas storage, including 4130 alloy tube trailers for hydrogen infrastructure commanding substantial premiums over standard structural tubing.
Fluid transfer maintains volume leadership; heat exchanger and hydrogen pressure vessel applications are climbing the fastest on energy transition investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron ore deposits in the Pilbara region of Western Australia feed integrated mills across Asia-Pacific, while scrap recycling networks in the Ruhr Valley and the American Midwest supply electric arc furnace operators serving regional tube markets.
Germany
Aerospace hydraulic systems demand from Airbus suppliers and landing gear manufacturers drives precision seamless procurement. The EU F-Gas Regulation and Pressure Equipment Directive enforce ferritic stainless grades for refrigerant lines. The Ruhr industrial belt around Duisburg and Dortmund hosts cold-drawing facilities serving fluid power distributors.
Japan
METI energy-efficiency mandates and JCAB aerospace certification protocols compress defect tolerance for hydraulic actuation tubing. JIS G 3445 standards govern dimensional tolerance for automotive chassis imports. The Nagoya works in Aichi Prefecture anchors premium seamless capacity with continuous casting investments.
India
Domestic construction equipment and automotive chassis fabrication absorb welded tube output from Mumbai-Pune manufacturing clusters. The PLI scheme for cold-drawn mechanical tubing attracts greenfield seamless investments in Gujarat and Maharashtra. BIS standards create compliance frameworks for pressure-rated steel components.
United States
Hydrogen infrastructure retrofit projects require thick-walled 4130 alloy grades for tube trailers and dispensing systems. EPA emissions standards and OSHA workplace safety regulations shape material selection for industrial fluid transfer. The Midwest scrap recycling corridor around Chicago and Detroit feeds electric arc furnace tube producers.
South Korea
Automotive chassis fabricators specify high-strength low-alloy mechanical tubing with tight tolerance requirements for suspension systems. MFDS industrial equipment standards and KBA automotive regulations drive quality certification. The Busan-Ulsan manufacturing belt concentrates hybrid laser-arc welding capacity for pressure-rated tubing.
Steel Roll-On Tube Market Competitive Landscape
Global majors compete with regional champions across substrate traceability and melt chemistry control, creating a tiered structure where integrated mills with captive ore sources face specialty fabricators with flexible coil sourcing. Three archetypes dominate: vertically integrated steelmakers controlling feedstock from mine to tube, precision seamless specialists anchored to single-site aerospace qualification, and welded tube converters scaling through high-frequency line automation. Competitive moves center on backward integration into scrap sorting and alloy recovery systems, plus multi-year framework agreements with indexed surcharge mechanisms that lock in buyer capacity allocations.
Among Japanese integrated producers, Nippon Steel Corporation and JFE Steel Corporation occupy positions within the premium seamless tier, with the former representing continuous casting convergence and the latter exemplifying thick-walled specialty grade capability. Luxembourg-based ArcelorMittal anchors the vertically integrated archetype through captive iron ore and recycling stream control. Korean and Chinese producers including POSCO and China Baowu Steel Group sit within the scale-driven welded tube segment serving construction and general mechanical applications.
| Leading Market Players |
|---|
| Essel Group |
| SR Packaging |
| Nippon Steel Corporation |
| JFE Steel Corporation |
| ArcelorMittal |
| SSAB |
| Wheatland Tube Company |
| China Baowu Steel Group |
| POSCO |
| Others |
Value Network & Pricing Analysis
Continuous casting convergence at Japanese integrated works simultaneously collapses lead times for aerospace-qualified seamless product and concentrates pricing power among mills with inline ultrasonic testing capabilities. The technology shift rewards operators that have sunk capital into Nagoya-style continuous casting investments, compressing cost economics for qualified feedstock while locking out converters dependent on spot billet markets.
Pricing Analysis
Warranty-backed material certification and unbundled NDT documentation create the primary pricing spread across supplier tiers. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified seamless with full melt-to-product traceability from commercial mechanical tubing and commodity construction grades. Price differentiation hinges on certification level (PED/ASME tier vs. general structural) and volume scale, with long-term framework agreements commanding indexed alloy surcharges that stabilize margins against nickel and molybdenum volatility. Cost compression in welded construction grades is intensifying because Mumbai-Pune cluster converters compete on domestic coil stock conversion cycles. Distributor buyers in Indian construction equipment represent the most price-sensitive segment; German fluid power OEMs securing hydraulic cylinder barrel supply show least sensitivity due to qualification switching costs.
Supply Chain Analysis
JCAB and EASA certification gating for aerospace hydraulic tubing restricts qualified supply to Nagoya works in Japan and select Ruhr Valley cold-drawing facilities in Germany. Raw material flows draw from Pilbara iron ore shipments feeding Asian integrated mills, Ruhr Valley scrap networks supplying European EAF operators, and Midwest recycling corridors feeding North American tube producers. Supply chain risk centers on geographic single-point vulnerability at the Nagoya seamless site, where qualified aerospace capacity remains anchored without redundant qualification pathways. Distribution runs through direct mill relationships for precision seamless grades and construction equipment distributors for standard welded product.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The steel roll-on tube market reads as supply-constrained: qualified ultrasonic and eddy-current inspection personnel scarcity extends aerospace material release timelines by 8-12 weeks, propping pricing for certified seamless grades regardless of underlying alloy cost movements.
For Market Incumbents: Acquire NDT certification capacity and qualified inspection personnel pools to collapse release bottlenecks and defend margin position against emerging EAF-based competitors with scrap traceability systems. Prioritize backward integration into alloy recovery systems that stabilize melt chemistry against nickel and molybdenum price swings. Lock in multi-year framework agreements with German fluid power distributors and Japanese construction equipment assemblers before hydrogen infrastructure retrofit demand accelerates 4130 alloy premiums. For New Entrants and Emerging Players: The 40-60% premium gap between thick-walled 4130 alloy grades for hydrogen infrastructure and standard structural tubing opens white-space targeting at mid-tier mechanical specifications. Gujarat and Maharashtra greenfield seamless investments under India's PLI scheme offer the most penetrable geography for cold-drawn mechanical tubing qualification. Pursue direct OEM relationships with automotive chassis fabricators in South Korea specifying high-strength low-alloy grades, bypassing distributor layers that incumbent mills dominate. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty seamless fabricators with captive aerospace qualification and hydrogen-ready 4130 alloy capabilities. Long-term viability over the next decade favors operators with integrated melt-to-tube traceability systems that satisfy diverging EU Carbon Border Adjustment Mechanism and Asian domestic content incentive regimes. Watch for inflection in EU F-Gas Regulation enforcement intensity, which would accelerate ferritic stainless grade switching in commercial HVAC retrofits and reshape capacity allocation across carbon and alloy seamless lines.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Casting Convergence | Nagoya works investments collapse lead times for aerospace-qualified seamless product. |
| Backward Integration into Scrap Sorting | Ruhr Valley EAF operators stabilize alloy chemistry against nickel price volatility. |
| Long-term Framework Agreements | German fluid power distributors lock capacity allocations with indexed surcharge mechanisms. |
| Hydrogen Infrastructure Certification | 4130 alloy thick-walled grades command substantial premiums over standard structural tubing. |
| Dual-Track Compliance Investment | Parallel PED and GB documentation systems enable simultaneous EU and China market access. |
Research Methodology
Trade customs databases, SEC filings from listed steel producers, and JIS/GB standards documentation formed the secondary backbone of this analysis. Primary interviews with aerospace procurement managers at German landing gear manufacturers, fluid power distributors in the Ruhr industrial belt, and plant managers at Mumbai-Pune welded tube converters combined with secondary validation through bottom-up and top-down triangulation. Technical discussions with NDT certification bodies and metallurgical documentation specialists informed supply chain risk assessments.
Historical trendline analysis of seamless and welded tube production volumes across product type, end user, and application segments anchored the forecast framework. The analytical model projected expansion across the analysis window by segmenting across seamless versus welded manufacturing routes, aerospace versus automotive versus construction end-use concentrations, and fluid transfer versus structural versus heat exchanger applications. CAGRs were derived from production capacity utilization trajectories and alloy surcharge indexing patterns, with hydrogen infrastructure retrofit timelines and F-Gas Regulation compliance curves serving as industry-specific demand inputs.
Inputs from primary mill interviews and customs trade records were available through the study window; gaps in real-time alloy surcharge contract terms and undisclosed continuous casting investment schedules introduce uncertainty bands around precision seamless supply forecasts. Forecasts reflect documented assumptions about certification bottleneck resolution and scrap-derived alloy price stability. A model refresh is warranted upon material change in EU Carbon Border Adjustment Mechanism enforcement intensity or JCAB aerospace protocol amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
Steel Pipe Market
Pipes and Tubes
Metal Pipe Market
Pipes and Tubes
Industrial Draft Tube Crystallizer Market
Pipes and Tubes
GCC Polyethylene (PE) Pipes Market
Pipes and Tubes
Gas Fittings and Components Market
Pipes and Tubes
Europe Copper Pipes and Tubes Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Saudi Arabia PE Pipes Market
Pipes and Tubes
Pneumatic Fittings Market
Pipes and Tubes
Saw Pipes Market
Pipes and Tubes
GCC PVC Pipes Market
Pipes and Tubes
Heat Shrink Tubing Market
Pipes and Tubes
Polyethylene Pipes Market
Pipes and Tubes
Qatar PVC Pipe Market
Pipes and Tubes
Clad Pipe Market