
 Stainless Steel Tank Container Market | 2026-2036
Stainless Steel Tank Container Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel Tank Container Market Insights
Multi-source procurement among chemical logistics operators is rebalancing supply relationships across the stainless steel tank container value chain. CST Industries leverages its North American fabrication network to sustain large-diameter vessel output for industrial clients. Paul Mueller Company anchors premium sanitary tank production for food and pharmaceutical applications. EXSIF Worldwide competes through fleet scale and intermodal coverage across major trade lanes.
A stainless steel tank container is a cylindrical pressure vessel constructed from austenitic grades such as 304 or 316 stainless steel, designed for the intermodal transport and temporary storage of liquids, gases, and powders under ISO frame dimensions. The 20 feet and 40 feet size categories dominate operational deployment, with the former optimized for dense chemical cargoes and the latter maximizing volume efficiency on rail and maritime routes. ISO tank containers command the largest product-type share due to universal compatibility with existing intermodal infrastructure, while the pharmaceutical end-user segment differentiates through stringent surface-finish and cleanability specifications that command premium positioning.
The International Maritime Organization's tank container inspection regime and the European Union's F-Gas Regulation shape equipment standards and refrigerant-handling compliance across trade corridors. The US Department of Transportation and China's SAMR enforce parallel pressure-vessel certification pathways that fragment market access requirements. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate retesting costs and certification renewal timelines.
Market Dynamics
Asia-Pacific chemical manufacturers are accelerating fleet renewal cycles to comply with the International Maritime Organization's updated tank inspection protocols, compressing replacement timelines and reshaping procurement volumes across the stainless steel tank container supply base.
Growth Catalysts
- IMO Inspection Protocols:Tighter certification requirements across member states are forcing premature retirement of aging fleets and stimulating replacement demand for ISO-certified units.
- China Chemical Output:Domestic production scaling and port infrastructure modernization in Shanghai, Ningbo, and Qingdao are concentrating demand for 40-foot high-capacity tank containers.
- Pharmaceutical Surface Standards:Stringent cleanability specifications for biologics transport are expanding the addressable market for electropolished 316-grade vessels.
Market Restraints
- Nickel Price Volatility:Austenitic stainless steel input costs fluctuate with LME nickel trading, compressing fabrication margins and triggering surcharge negotiations.
- European F-Gas Compliance:Refrigerant-handling equipment retrofits add capital burden for temperature-controlled tank operators serving EU trade corridors.
- Road Tanker Substitution:Flexible bulk liquid transport in non-intermodal lanes competes for chemical logistics spend, capping tank container penetration in regional haulage.
Strategic Opportunities
- India Chemical Corridor:Dahej and Mundra port expansions create greenfield deployment potential for corrosive liquid intermodal services.
- Digital Fleet Telemetry:Integration of pressure-monitoring IoT sensors with blockchain documentation is opening premium service tiers for high-value cargo assurance.
- SAMR Harmonization:China's pressure-vessel certification alignment with ISO standards is reducing dual-testing burden for multinational fleet operators.
Industry Challenges
- Welder Certification Bottlenecks:ASME Section IX qualified welder scarcity in North American fabrication yards extends order-to-delivery timelines.
- Multi-Jurisdiction Retesting:Divergent US DOT, EU ADR, and China SAMR recertification calendars fragment maintenance scheduling and inflate compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel Tank Container Market |
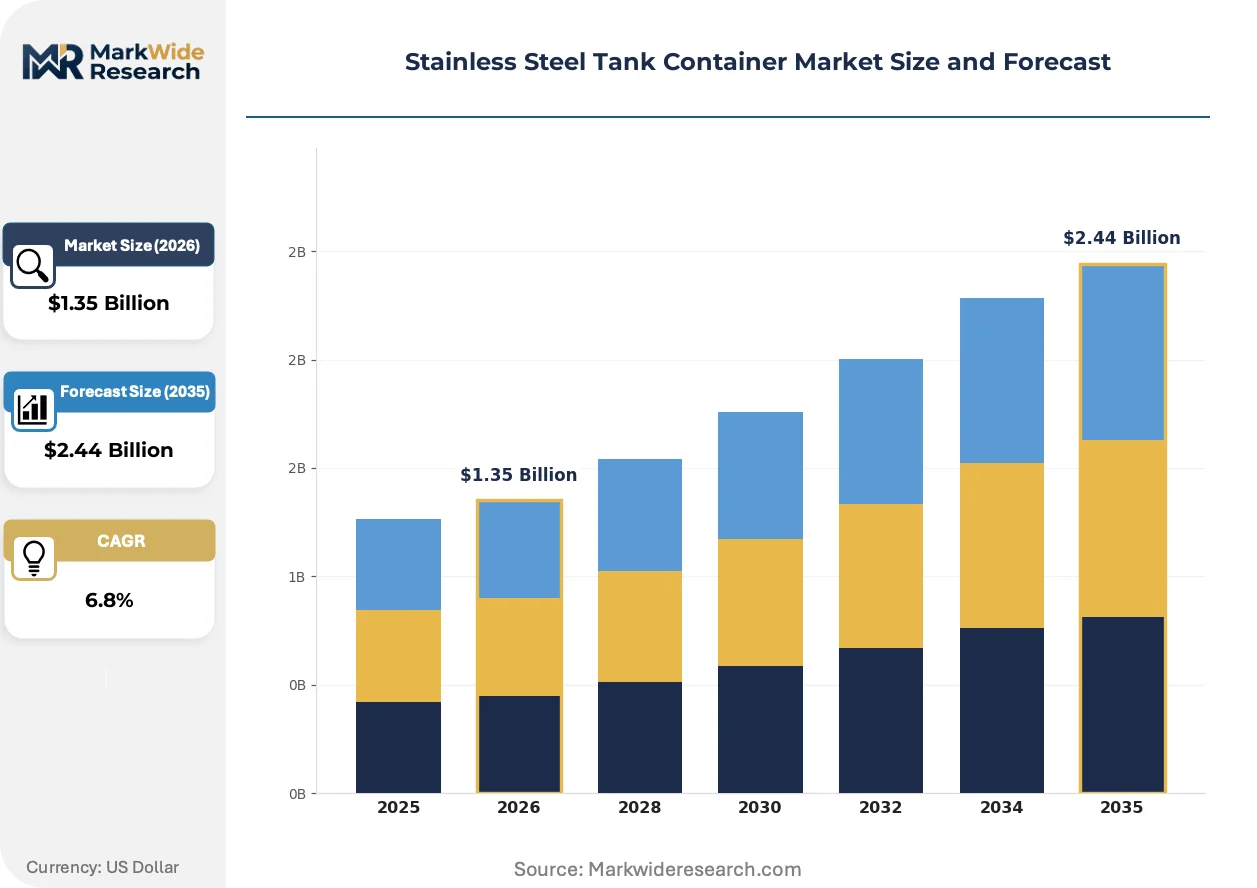
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ISO Tank Container, Half-Height Container, Special Container, Portable Container End User: Chemical Industry, Food & Beverage, Oil & Gas, Pharmaceutical Size: 20 Feet, 40 Feet, 10 Feet, 30 Feet Application: Bulk Transport, Storage, Tanker Services, Refueling |
| Companies Covered | CST Industries, Paul Mueller Company, Gpi Tanks, Ziemann Holvrieka, Apache Stainless, Feldmeier Equipment, EXSIF Worldwide, Stolt Tank Containers, Eurotainer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel Tank Container Market Trends and Innovations
Equipment intelligence and regulatory digitization are converging to transform how tank container fleets are monitored, certified, and monetized across chemical and pharmaceutical logistics chains.
Smart pressure-monitoring systems with embedded IoT sensors are integrating real-time cargo condition telemetry into fleet management platforms. Pharmaceutical shippers and specialty chemical distributors are adopting these systems fastest, with temperature-sensitive biologics corridors showing deployment rates above other segments. The technology is integrating predictive maintenance protocols that compress unplanned downtime and extend vessel service intervals beyond traditional fixed schedules.
The European Union's F-Gas Regulation is mandating refrigerant phase-down schedules that cascade into tank container refrigeration unit specifications. Equipment lessors must now retrofit or retire R-404A dependent units ahead of 2030 bans, accelerating capital deployment into compliant systems. Temperature-controlled pharmaceutical lanes between Belgium, the Netherlands, and Germany are absorbing the highest compliance costs as operators consolidate onto low-GWP refrigerant platforms.
Long-term charter contracting is displacing spot-market leasing for high-utilization chemical routes. Multinational logistics operators are locking five-to-seven-year vessel commitments with maintenance-included terms, compressing the spot market to distressed cargo and seasonal overflow. This pattern is most visible on China-to-Europe chemical corridors where volume predictability justifies dedicated fleet allocation over flexible leasing.
Stainless Steel Tank Container Market Segmentation
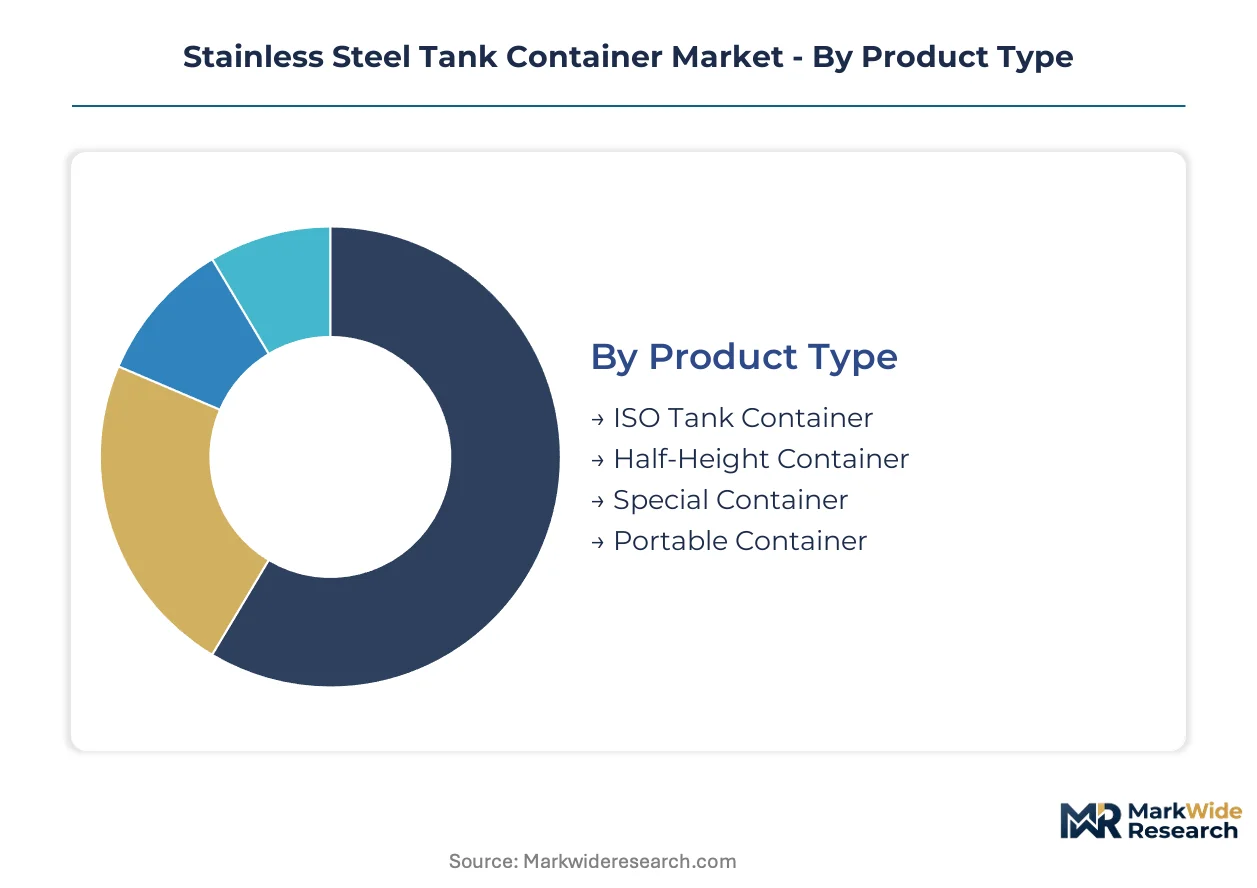
Segmentation in stainless steel tank containers reveals how vessel specifications align with cargo chemistry, modal constraints, and regulatory exposure across chemical and pharmaceutical logistics chains.
Product Type:
Buyers differentiate by intermodal compatibility and cargo access requirements, with fleet standardization decisions rippling through maintenance networks and certification costs.
- ISO Tank Container:Cylindrical pressure vessels built to ISO 668 frame dimensions enable seamless transfer between ship, rail, and truck without cargo discharge. Chemical manufacturers in China favor 40-foot variants for high-volume corrosive liquid corridors between Shanghai, Ningbo, and Qingdao port clusters.
- Half-Height Container:Reduced-height cylindrical tanks optimize dense powder and granular chemical transport where weight limits bind before volume constraints. Mining chemical distributors in Australia's Pilbara region deploy these for concentrated acid delivery to remote extraction sites.
- Special Container:Custom-engineered vessels accommodate cryogenic liquids, pressurized gases, or multi-compartment segregation for incompatible cargoes.
- Portable Container:Smaller-capacity units serve temporary storage and short-haul distribution where fixed infrastructure is absent.
Volume sits with ISO Tank Container; growth tilts toward Special Container as pharmaceutical and cryogenic applications expand.
End User:
Surface finish standards and cleaning protocols separate buyers by contamination risk tolerance and regulatory scrutiny intensity.
- Chemical Industry:Corrosive liquid and solvent transport demands 316-grade austenitic steel with passivated welds resisting chloride attack. Fleet operators serving Germany's Ludwigshafen chemical cluster prioritize IMO-certified units with accelerated inspection cycles.
- Pharmaceutical:Electropolished 316L vessels with Ra 0.8 surface finishes prevent biologics contamination and satisfy FDA and EMA validation requirements. Temperature-controlled lanes between Belgium and the Netherlands absorb premium pricing for compliant equipment.
- Food & Beverage:Sanitary-grade construction with CIP (clean-in-place) compatibility serves edible oil, wine, and dairy intermodal movements.
- Oil & Gas:Pressurized designs handle drilling fluids, lubricants, and refined product logistics to remote extraction and generation sites.
Revenue concentrates in Chemical Industry; margin expansion favors Pharmaceutical as surface-finish premiums widen.
Size:
Dimensional choice reflects density economics and modal capacity constraints across maritime, rail, and road legs.
- 20 Feet:Standard ISO frame optimized for dense chemical cargoes where weight limits bind before cubic capacity. Dense acid and base transport from India's Dahej port corridor favors this format for road-rail intermodal efficiency.
- 40 Feet:Extended frames maximize volume efficiency on deep-sea maritime routes and double-stack rail corridors. China's domestic chemical production scaling drives deployment concentration at Shanghai and Qingdao terminals.
- 10 Feet:Compact units serve limited-access sites and short-haul distribution where maneuverability dominates capacity.
- 30 Feet:Intermediate format balances payload and handling flexibility for regional chemical networks.
Deployment tilts toward 40 Feet on long-haul corridors; 20 Feet retains share in dense cargo and emerging market access lanes.
Application:
Utilization patterns distinguish between asset-heavy dedicated fleets and flexible service models.
- Bulk Transport:Core intermodal service moving liquid chemicals, food-grade products, and pharmaceutical ingredients between production and consumption nodes. Long-term charter contracting on China-Europe chemical corridors is displacing spot-market exposure for high-utilization operators.
- Storage:Temporary tank container deployment at production sites, ports, and consumption centers substitutes for fixed tank farm capital. Pharmaceutical manufacturers in Switzerland leverage this for buffer inventory management.
- Tanker Services:Integrated logistics offerings combining equipment provision with cargo handling and documentation.
- Refueling:Specialized units serving aviation, marine, and remote site fuel logistics where pipeline infrastructure is absent.
Asset intensity clusters in Bulk Transport; service margin expansion favors integrated Tanker Services as operators bundle telemetry and compliance management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nickel ore processing clusters in Indonesia and the Philippines anchor raw material flows for austenitic stainless steel fabrication serving tank container manufacturing networks across Asia-Pacific and European conversion centers.
China
Domestic chemical production scaling and port infrastructure modernization at Shanghai, Ningbo, and Qingdao concentrate demand for 40-foot high-capacity ISO tank containers. SAMR pressure-vessel certification requirements are tightening inspection protocols for intermodal equipment serving corrosive liquid corridors. The Yangtze River Delta chemical cluster absorbs the highest deployment volumes for domestic soda ash and acid transport.
Germany
Ludwigshafen and Leverkusen chemical complexes sustain replacement demand for IMO-certified 316-grade vessels with accelerated inspection cycles. The EU F-Gas Regulation mandates refrigerant phase-down schedules that cascade into tank container refrigeration retrofits. BASF and Bayer supply chains prioritize electropolished units for specialty chemical intermodal movements through Rotterdam and Hamburg gateways.
United States
Gulf Coast petrochemical expansion and shale-derived chemical feedstock growth drive ISO tank container procurement for export corridors. US DOT pressure-vessel certification pathways diverge from European ADR standards, fragmenting fleet interoperability. Houston and Corpus Christi terminals concentrate 20-foot dense cargo deployments for acid and base transport to Latin American markets.
India
Dahej and Mundra port expansions create greenfield deployment potential for corrosive liquid intermodal services connecting Gujarat chemical parks. BIS standards alignment with ISO tank container specifications is reducing dual-testing burden for multinational fleet operators. The Mumbai-Pune industrial corridor absorbs growing volumes for specialty chemical distribution to domestic formulation plants.
Netherlands
Antwerp-Rotterdam-Amsterdam chemical logistics hub status sustains premium demand for pharmaceutical-grade electropolished vessels with Ra 0.8 surface finishes. EMA validation requirements for biologics transport command pricing premiums on temperature-controlled lanes between Belgium and Germany. Rotterdam terminal operators are consolidating maintenance networks to service long-term charter fleets on China-Europe corridors.
Stainless Steel Tank Container Market Competitive Landscape
Global majors compete with regional champions across fabrication scale and certification breadth, producing a tiered structure where fleet operators, specialized fabricators, and diversified industrial equipment makers occupy distinct competitive positions. Consolidation pressure concentrates among European lessors seeking intermodal coverage density, while Asian fabrication yards compete on austenitic steel conversion cost. Three archetypes dominate: integrated fleet operators with telemetry-enabled service bundles, precision fabricators serving pharmaceutical surface-finish specifications, and diversified tank specialists leveraging backward integration into steel processing. Capacity expansion and strategic partnerships represent the dominant competitive moves, with joint ventures bridging certification gaps across US DOT, EU ADR, and China SAMR jurisdictions.
Among North American fabricators, CST Industries and Paul Mueller Company exemplify divergent strategic archetypes. CST Industries leverages fabrication network scale for industrial vessel output serving chemical and energy clients. Paul Mueller Company anchors premium sanitary tank production for food and pharmaceutical applications where surface-finish specifications command structural margin premiums. At the fleet-operator end, EXSIF Worldwide sits within the intermodal coverage tier, competing through vessel scale and lane density across major chemical trade corridors rather than fabrication ownership.
| Leading Market Players |
|---|
| CST Industries |
| Paul Mueller Company |
| Gpi Tanks |
| Ziemann Holvrieka |
| Apache Stainless |
| Feldmeier Equipment |
| EXSIF Worldwide |
| Stolt Tank Containers |
| Eurotainer |
| Others |
Pricing and Supply Chain Analysis
Long-term charter contracting by multinational chemical logistics operators is forcing equipment lessors toward bundled service models and compressing spot-market pricing flexibility across vessel categories.
Pricing Analysis
Warranty and maintenance-included service bundling now separates premium fleet operators from unbundled transactional sellers in the stainless steel tank container market. Three-tier pricing structure across electropolished pharmaceutical-grade, standard IMO-certified chemical, and economy refurbished units reflects surface-finish certification and telemetry integration levels. Cost compression in standard chemical-grade units is intensifying because Asian fabrication yards compete on austenitic steel conversion efficiency. Pharmaceutical shippers demonstrate the lowest price sensitivity due to EMA and FDA validation requirements, while regional chemical distributors in emerging markets drive hardest bargain on capital equipment.
Supply Chain Analysis
Maritime freight cost fluctuations between Indonesian nickel ore ports and Chinese fabrication centers directly compress margins for austenitic steel conversion. Supply concentrates in China, South Korea, and Germany for pressure-vessel fabrication, with raw material flows drawing from Indonesian and Philippine nickel processing clusters. The supply chain rests on LME nickel price volatility, ASME-certified welder availability, and specialized surface-finishing equipment. Single-source vulnerability in electropolishing capacity for pharmaceutical-grade vessels concentrates risk. Distribution runs through integrated fleet operators, regional equipment lessors, and direct sales to chemical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASME Section IX qualified welder scarcity across North American and European fabrication yards sustains supply-constrained conditions that prop pricing for certified vessel output.
For Market Incumbents: Anticipate accelerated fleet renewal demand from IMO inspection protocol tightening by locking multi-year austenitic steel supply agreements with Indonesian nickel processors. Defensive consolidation through acquisition of regional maintenance networks in the Antwerp-Rotterdam-Amsterdam corridor protects service-margin capture from emerging telemetry-enabled competitors. For New Entrants and Emerging Players: Capture greenfield deployment potential in India's Dahej and Mundra port corridors where BIS-ISO alignment reduces certification barriers for multinational fleet operators. Specialty pharmaceutical-grade electropolishing services for biologics transport represent the most penetrable white-space segment. Go-to-market execution should leverage partnerships with established European lessors seeking Asia-Pacific coverage density without fabrication ownership. For Investors and Strategic Acquirers: The window for entry favors precision fabricators with captive electropolishing capability and SAMR certification access. Long-term viability over the mid-decade horizon rests on regulatory digitization integration and IoT-telemetry service bundling. Acquisition target archetype: mid-cap European lessors with concentrated China-Europe lane exposure and maintenance network assets. The signal to watch is refrigerant-handling equipment retrofit completion rates ahead of EU F-Gas Regulation phase-down deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Processing | Captive ore supply from Indonesian smelters hedges LME price volatility for austenitic steel input. |
| Long-term Charter Fleet Commitments | Five-to-seven-year vessel contracts with maintenance-included terms lock utilization on China-Europe chemical corridors. |
| Refrigerant Retrofit Compliance Program | R-404A phase-out ahead of EU F-Gas Regulation deadlines preserves temperature-controlled pharmaceutical lane access. |
| Digital Fleet Telemetry Integration | Pressure-monitoring IoT sensors with blockchain documentation open premium service tiers for biologics assurance. |
| Multi-Jurisdiction Certification Harmonization | Joint ventures bridging US DOT, EU ADR, and China SAMR standards reduce dual-testing burden for multinational operators. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this stainless steel tank container market assessment. Primary interviews with fleet operations directors, pressure-vessel fabrication plant managers, chemical logistics procurement leads, and pharmaceutical supply chain managers combined with IMO inspection protocol documentation, SAMR certification databases, and SEC equipment manufacturer disclosures. Bottom-up vessel deployment tallies by port cluster triangulated against top-down chemical trade flow estimates.
Granularity-level modeling distinguished ISO tank containers, half-height units, special containers, and portable containers by 20-foot, 40-foot, 10-foot, and 30-foot frame dimensions across chemical, pharmaceutical, food and beverage, and oil and gas end-use segments. CAGRs were derived from replacement cycle compression analysis, port infrastructure investment pipelines, and regulatory inspection interval changes throughout the forecast period. Nickel price trajectory assumptions and welder certification capacity constraints informed fabrication cost modeling.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to International Maritime Organization inspection protocol enforcement consistency and China SAMR harmonization progress with ISO standards. Forecasts reflect documented assumptions regarding chemical production scaling trajectories, nickel ore supply stability, and refrigerant regulation implementation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
OCTG Pipe Market
Pipes and Tubes
UAE PVC Pipes Market
Pipes and Tubes
Global Polyethylene Pipes and Fittings Market
Pipes and Tubes
Global Hydraulic Thermoplastic Hose and Couplings Market
Pipes and Tubes
United States Copper Pipes and Tubes Market
Pipes and Tubes
GCC Polyethylene (PE) Pipes Market
Pipes and Tubes
Cold Drawn Seamless (CDS) Steel Pipes Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Polyethylene Pipes Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
India Process Piping Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Metal Pipe Market
Pipes and Tubes
Perfusion Tubing Systems Market
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
Kuwait PVC Pipes Market