
 Industrial Blast Hoses Market | 2026-2036
Industrial Blast Hoses Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Blast Hoses Market Analytics
Surface preparation contractors are rotating toward higher-durability hose specifications as infrastructure refurbishment cycles compress. Gates Corporation leverages integrated elastomer compounding capabilities to control material consistency across abrasive-service product lines. Parker Hannifin Corp anchors its position through hydraulic-adjacent distribution channels that extend into blast equipment aftermarket networks. Trelleborg Group specializes in polymer-engineered constructions that sustain flex fatigue under cyclic pressure loading in marine dry-dock operations.
Industrial blast hoses are reinforced flexible conduits, typically comprising abrasion-resistant rubber or thermoplastic elastomer layers with textile or wire reinforcement, designed to convey pressurized abrasive media at operating pressures commonly ranging from 150 to 400 psi. Their primary commercial purpose centers on surface cleaning, coating removal, and substrate preparation across metal fabrication, maritime maintenance, and civil infrastructure restoration. Rubber constructions dominate current volume owing to established supply chains and repairability, while polyurethane formulations represent the fastest-expanding category as operators prioritize weight reduction and kink resistance in elevated-platform work. Mining and oil & gas applications command premium pricing due to extreme-service specifications, whereas construction segment procurement standardizes around mid-duty specifications with shorter replacement intervals.
OSHA workplace exposure limits and hose integrity inspection mandates shape North American product liability and replacement demand cycles. REACH substance restrictions and the EU Machinery Directive pressure European manufacturers toward phthalate-free formulations and documented pressure-test certifications. Stakeholders must monitor evolving MSHA underground equipment standards and the trajectory of thermoplastic material qualification for sustained pressure service, as these will determine which compound technologies capture replacement volume in hazardous-environment deployments.
Market Dynamics
Surface preparation contractors in shipyards and infrastructure refurbishment are compressing replacement cycles as abrasive blasting intensity rises, forcing manufacturers to engineer higher-durability compounds that withstand cyclic flex fatigue under sustained pressure loading.
Growth Catalysts
- OSHA respiratory protection mandates:North American workplace exposure limits and hose integrity inspection requirements are accelerating replacement demand cycles among surface preparation contractors.
- Germany's industrial manufacturing belt:Automotive and heavy equipment OEMs in this cluster sustain premium hose procurement for automated blasting operations.
- Polyurethane formulation advances:Thermoplastic elastomer constructions are capturing elevated-platform work as operators prioritize weight reduction and kink resistance over traditional rubber.
Market Restraints
- Natural rubber price volatility:Abrasion-resistant compound feedstocks fluctuate with tropical supply disruptions, compressing margin visibility for mid-tier manufacturers.
- REACH substance restrictions:ECHA phthalate limitations and documented pressure-test certification requirements are elevating European compliance costs and qualification timelines.
- Steel-braided hydraulic hose substitution:Adjacent product categories with established distribution networks threaten to capture price-sensitive construction segment volume.
Strategic Opportunities
- Marine dry-dock specialization:Polymer-engineered constructions for cyclic pressure loading in saltwater environments represent underserved premium positioning.
- MSHA underground equipment trajectory:Evolving standards for hazardous-environment thermoplastic qualification will determine compound technology winners in mining replacement volume.
- Integrated elastomer compounding:Captive control over material consistency enables specification differentiation against distributed supply chain competitors.
Industry Challenges
- Pressure-test certification backlog:EU Machinery Directive documentation requirements are extending product launch timelines for multi-layer reinforced constructions.
- Abrasive-media compatibility mapping:Matching compound formulations to specific garnet, coal slag, or steel grit chemistries demands specialized application engineering talent that concentrates among legacy manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Blast Hoses Market |
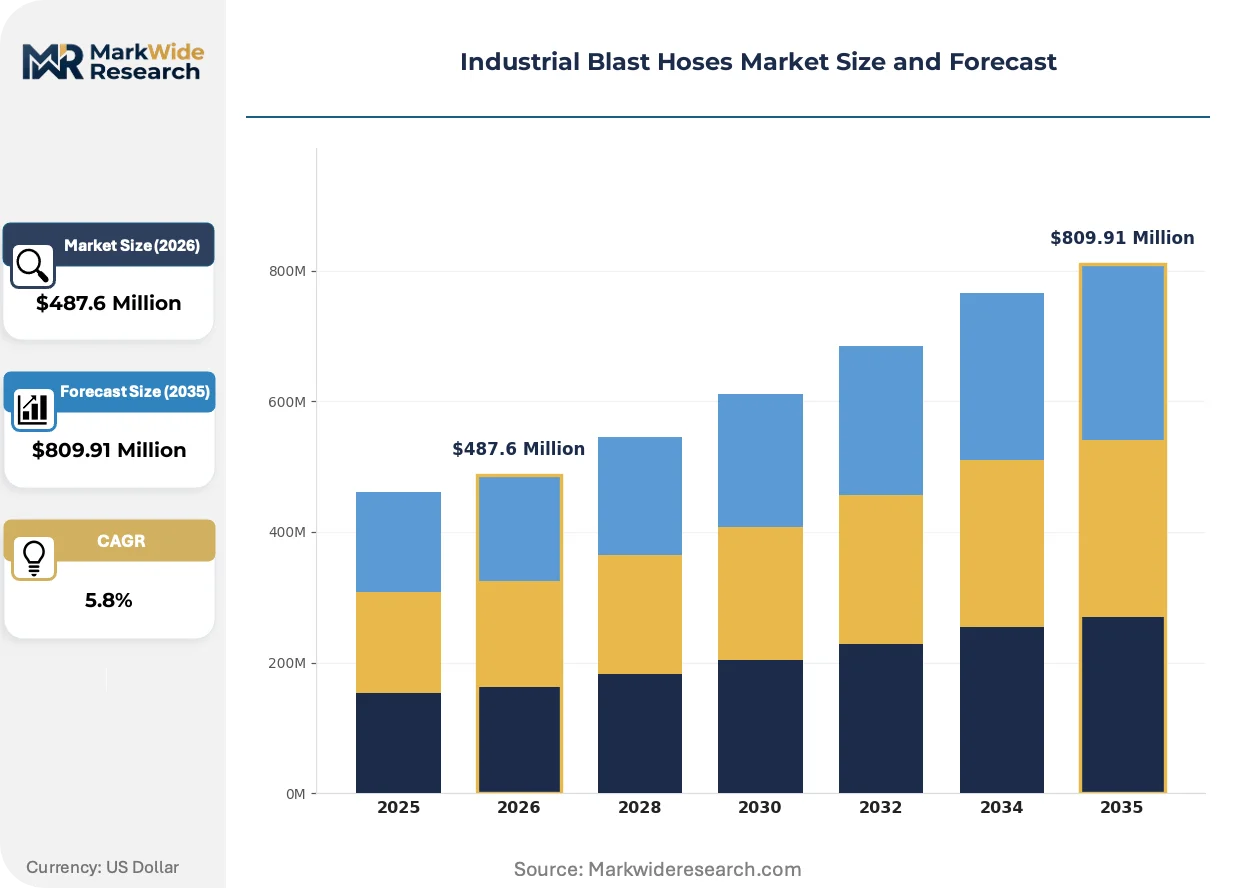
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber, PVC, Polyurethane, Thermoplastic Application: Construction, Manufacturing, Mining, Oil & Gas Diameter: 1 inch, 2 inch, 3 inch, 4 inch End User: Aerospace, Automotive, Marine, Industrial |
| Companies Covered | Gates Corporation, Parker Hannifin Corp, Continental AG, Danfoss, Trelleborg Group, Semperit AG Holding, Clemco Industries Corp, Marco Group International, Airblast Eurospray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Blast Hoses Market Evolving Landscape
Material science advances and regulatory documentation requirements are restructuring how blast hose specifications are validated, procured, and deployed across hazardous-environment applications.
Thermoplastic polyurethane constructions are decomposing the traditional rubber-dominant volume structure as weight-critical applications in elevated scaffolding and offshore platforms prioritize kink recovery and flex fatigue resistance. Marine contractors in North Sea and Gulf of Mexico operations are specifying these formulations for cyclic loading conditions. The technology is decomposing established repairability advantages that sustained rubber's market position.
REACH substance restrictions and the EU Machinery Directive are forcing phthalate-free compound reformulations and documented pressure-test certifications across European supply chains. Manufacturers must now maintain batch traceability and third-party validation records for multi-layer textile and wire-reinforced constructions. German automotive OEMs and Dutch shipyard operators are qualifying suppliers based on ECHA-compliant material declarations ahead of procurement decisions.
Service-interval contracting is displacing transactional hose replacement among large surface preparation contractors managing fleet-scale abrasive blasting operations. Predictive wear monitoring and scheduled swap-out programs are compressing spot-buying patterns in North American infrastructure refurbishment. Shipyard operators in Virginia and Louisiana are consolidating vendor relationships around integrated hose-and-nozzle service packages rather than component procurement.
Industrial Blast Hoses Market Segmentation
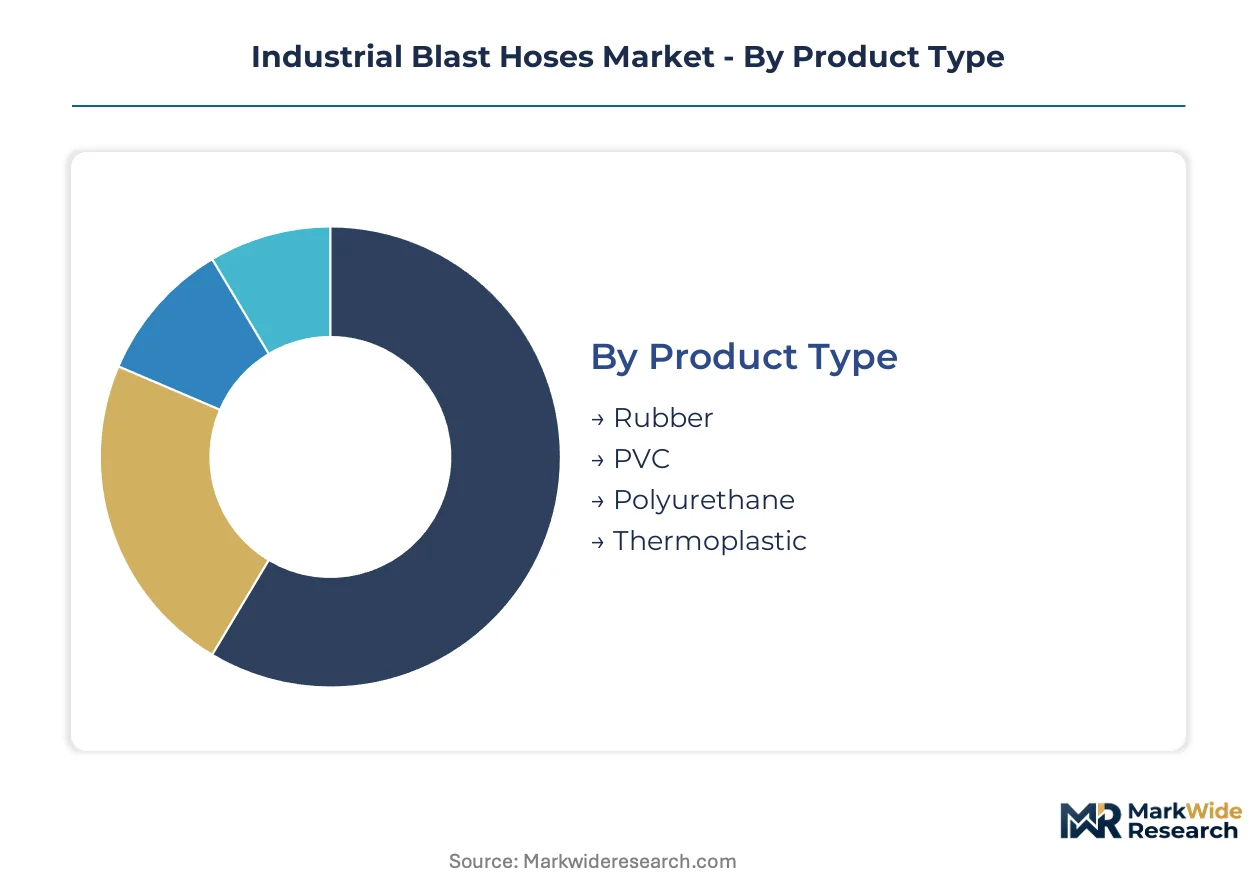
Blast hose procurement patterns diverge sharply across material formulations and end-use environments. Specification requirements for abrasive media compatibility and pressure ratings create distinct margin tiers that manufacturers must navigate to capture replacement volume.
Product Type:
Polyurethane and thermoplastic constructions command premium positioning as weight-critical applications displace legacy rubber specifications.
- Rubber:Multi-layer abrasion-resistant elastomer constructions with textile or wire reinforcement dominate current installed base. Shipyard operators in Louisiana and Virginia specify these for repairability in heavy-duty surface preparation cycles.
- Polyurethane:Thermoplastic elastomer formulations deliver kink recovery and flex fatigue resistance under cyclic pressure loading. Elevated-platform contractors in North Sea offshore operations prioritize these for weight reduction in scaffolding deployments.
- PVC:Lower-pressure thermoplastic constructions serve light-duty construction applications with standardized replacement intervals.
- Thermoplastic:Advanced polymer-engineered layers target MSHA-qualifying hazardous-environment specifications in underground mining.
Rubber holds installed capacity. Polyurethane is rotating up the share rankings.
Application:
End-use intensity determines specification grade and procurement contract structure across abrasive-service environments.
- Construction:Mid-duty standardized specifications with shorter replacement intervals concentrate volume in infrastructure refurbishment. OSHA hose integrity mandates compress buying cycles for surface preparation contractors.
- Oil & Gas:Extreme-service specifications for offshore platform maintenance command premium pricing. Gulf of Mexico operators specify polymer-engineered constructions for saltwater corrosion resistance.
- Manufacturing:Automated blasting operations in automotive OEM facilities sustain premium procurement for consistency under sustained pressure.
- Mining:Underground equipment applications face evolving MSHA thermoplastic qualification standards that will determine compound technology winners.
Construction absorbs the highest replacement volume. Oil & Gas maintains the steepest expansion trajectory.
Diameter:
Hose dimension selection tracks abrasive media flow requirements and platform mobility constraints.
- 1 inch:Compact-diameter specifications serve precision blasting in aerospace component finishing and confined-space refurbishment.
- 2 inch:Balanced flow-to-weight ratio dominates elevated-platform work in marine dry-dock operations.
- 3 inch:High-volume media delivery for heavy equipment OEM automated blasting lines in Germany's industrial manufacturing belt.
- 4 inch:Maximum-flow constructions for shipyard infrastructure refurbishment and large-scale substrate preparation.
2 inch specifications anchor current procurement. 3 inch diameter is climbing the fastest in automated manufacturing uptake.
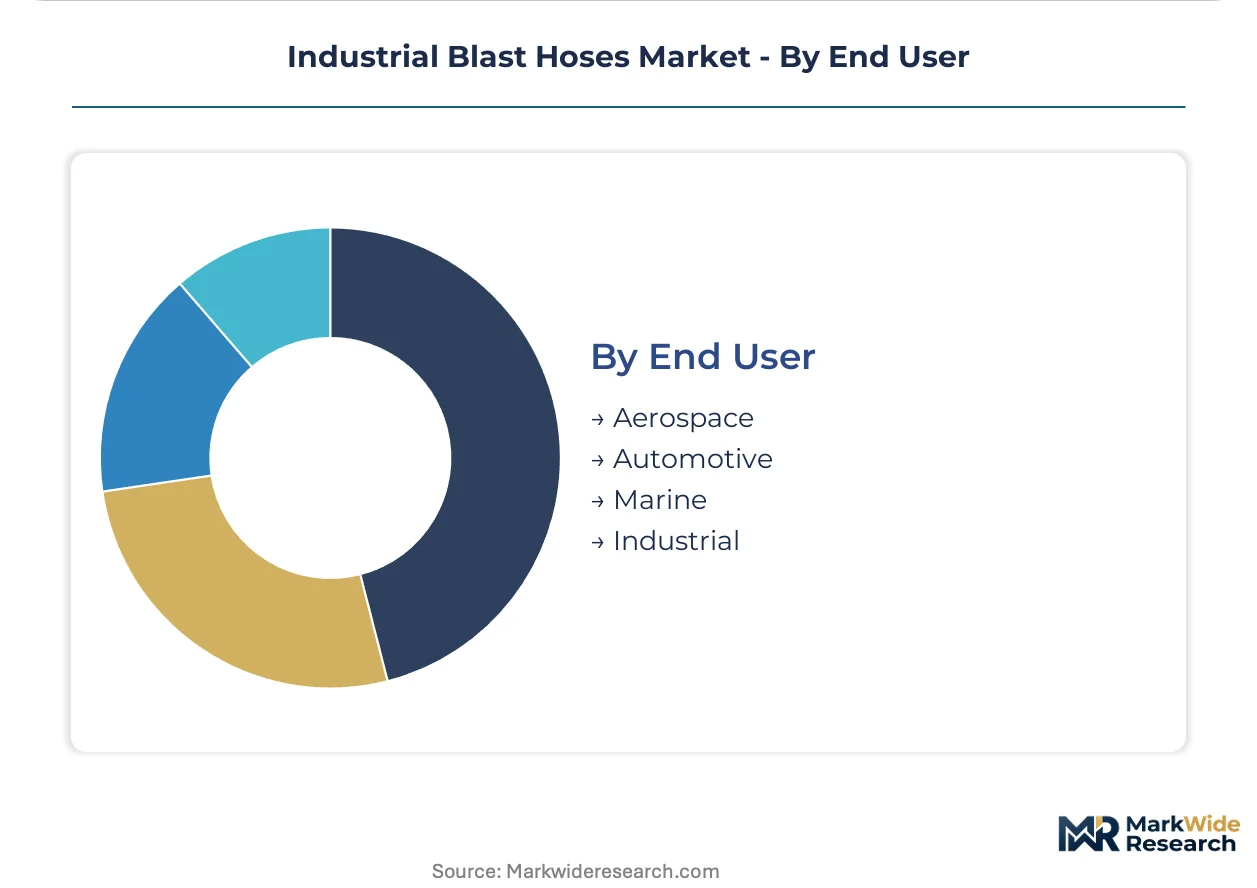
End User:
Customer-type requirements fragment across certification standards, service-interval contracting, and abrasive-media compatibility demands.
- Industrial:Fleet-scale surface preparation contractors consolidate vendor relationships around integrated hose-and-nozzle service packages. Predictive wear monitoring compresses spot-buying patterns.
- Marine:Dry-dock operators specify polymer-engineered constructions for cyclic flex fatigue in saltwater environments. REACH-compliant material declarations gate European supplier qualification.
- Automotive:German OEM automated blasting operations demand documented pressure-test certifications under EU Machinery Directive requirements.
- Aerospace:Precision finishing applications require specialized compound formulations matched to specific garnet and steel grit chemistries.
Industrial end users concentrate replacement volume. Marine specifications are gaining share fastest on offshore platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized abrasion-resistant formulations to shipyard operators across the North Sea and Baltic Sea corridors. Italian fabricators supply Mediterranean marine maintenance networks through consolidated distributor relationships.
United States
OSHA respiratory protection mandates and hose integrity inspection requirements accelerate replacement cycles among Gulf Coast surface preparation contractors. Virginia and Louisiana shipyard clusters specify polymer-engineered constructions for cyclic flex fatigue in saltwater environments. Houston-area oilfield service companies drive premium procurement for offshore platform maintenance specifications.
Germany
Automotive OEM automated blasting operations in Baden-Württemberg and Bavaria sustain documented pressure-test certification requirements under EU Machinery Directive. ECHA phthalate limitations force compound reformulations across industrial manufacturing belt supply chains. Stuttgart and Munich industrial corridors concentrate premium hose procurement for consistency under sustained pressure loading.
China
MIIT industrial equipment standards and GB certification requirements shape domestic manufacturing specifications for abrasive-service applications. Yangtze River Delta shipyards compress replacement intervals as infrastructure refurbishment intensity rises. Shanghai and Ningbo marine maintenance clusters specify mid-duty standardized constructions with shorter replacement cycles.
Netherlands
Rotterdam and Amsterdam port maintenance operations prioritize REACH-compliant material declarations ahead of procurement decisions. ECHA substance restrictions gate European supplier qualification for marine dry-dock specifications. Randstad industrial belt distributors consolidate vendor relationships around integrated hose-and-nozzle service packages.
United Kingdom
North Sea offshore platform operators specify thermoplastic polyurethane constructions for weight-critical elevated scaffolding deployments. HSE workplace exposure limits align with OSHA-equivalent hose safety standards for surface preparation contractors. Aberdeen and Grimsby marine service clusters drive polymer-engineered procurement for saltwater corrosion resistance.
Industrial Blast Hoses Market Competitive Landscape
Player mix skews toward integrated elastomer compounders with captive material consistency control. The supplier base concentrates among hydraulic-adjacent manufacturers extending into blast equipment aftermarket networks and specialized polymer engineers serving marine dry-dock specifications. Two strategic archetypes dominate: diversified industrial conglomerates leveraging distribution scale and focused hose specialists competing on abrasive-media compatibility engineering. Competitive moves center on backward integration into raw material supply and predictive wear monitoring service bundling.
Among diversified industrial conglomerates, Gates Corporation and Parker Hannifin Corp exemplify the hydraulic-adjacent distribution archetype extending specification reach into abrasive-service applications. Trelleborg Group occupies a position within the polymer-engineered specialization tier, representing marine-focused compound technology differentiation. These three anchors demonstrate how material science capabilities and distribution network density determine competitive positioning across replacement volume capture.
| Leading Market Players |
|---|
| Gates Corporation |
| Parker Hannifin Corp |
| Continental AG |
| Danfoss |
| Trelleborg Group |
| Semperit AG Holding |
| Clemco Industries Corp |
| Marco Group International |
| Airblast Eurospray |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day compound formulation lead times concentrate pricing power among integrated elastomer compounders with captive mixing capacity, while distributed supply chain competitors absorb margin compression from tropical natural rubber price volatility. This lead-time band separates specification-grade procurement for German automotive OEMs from spot-buying construction segments.
Pricing Analysis
Rubber-to-polyurethane-to-thermoplastic generational pricing gaps stratify procurement tiers, with legacy rubber constructions anchoring economy positioning and advanced polymer-engineered layers commanding premium placement for MSHA-qualifying specifications. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with documented pressure-test certifications under EU Machinery Directive gating access to top-tier marine and automotive contracts. Cost compression in mid-duty construction specifications is intensifying because steel-braided hydraulic hose substitutes threaten price-sensitive volume. Surface preparation contractors in infrastructure refurbishment exhibit highest price sensitivity, while oilfield service companies in Gulf of Mexico operations demonstrate lowest sensitivity due to extreme-service specification requirements.
Supply Chain Analysis
Malacca Strait logistics throughput underwrites Southeast Asian natural rubber feedstock flows to German and Italian compounding facilities. Supply concentration clusters in Malaysia, Indonesia, and Thailand for abrasion-resistant elastomer feedstocks, with textile reinforcement sourcing from India and China. Raw material dependencies center on natural rubber, synthetic polyisoprene, and high-tenacity polyester yarn. Single-source vulnerability runs through tropical climate disruption exposure for natural rubber harvests. Distribution runs through hydraulic-adjacent aftermarket networks and consolidated shipyard service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
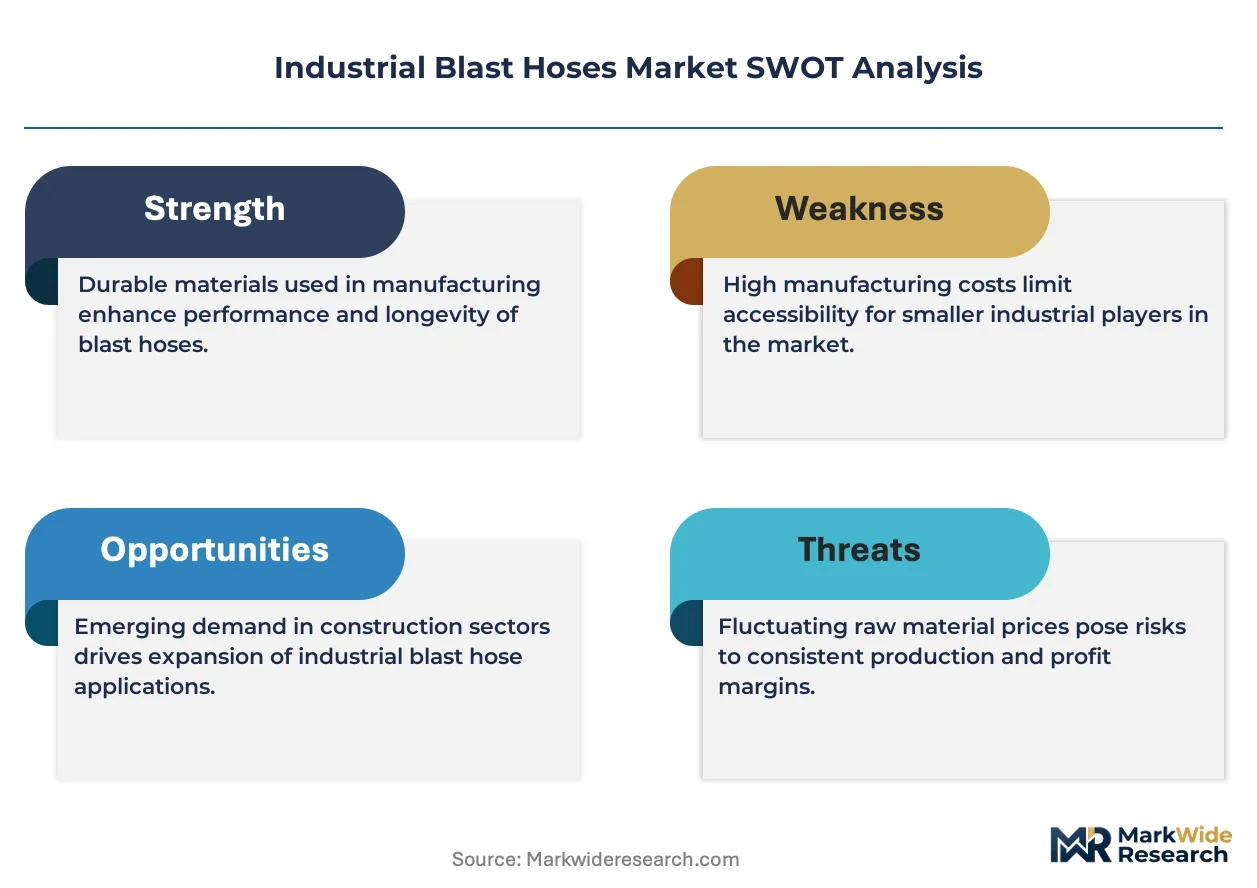
This market functions as a defensive-moat story anchored in regulatory entrenchment, where REACH-compliant material declarations and documented pressure-test certifications create switching costs that lock in qualified supplier relationships.
For Market Incumbents: Fortify specification-grade positioning by deepening backward integration into captive elastomer compounding capacity in Baden-Württemberg and Bavaria industrial corridors. Expand predictive wear monitoring service bundling to compress spot-buying patterns among fleet-scale surface preparation contractors. Steel-braided hydraulic hose substitution threats demand accelerated polyurethane formulation R&D to defend premium tier access. For New Entrants and Emerging Players: Predictive maintenance service-layer gaps among mid-tier construction contractors offer white-space entry points. Target MSHA-qualifying thermoplastic specifications for underground mining replacement volume as standards evolve. Marine dry-dock specialization in saltwater corrosion-resistant constructions represents the most penetrable premium segment. Go-to-market leverage through integrated hose-and-nozzle service packages rather than component sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across polymer-engineered construction segments as batch traceability systems and third-party validation infrastructure become mandatory. Long-term viability over the next decade favors compound technology specialists with documented ECHA-compliant material declarations. Acquisition target archetype: focused hose specialists with abrasive-media compatibility engineering talent concentrated among legacy manufacturers. Signal to watch: MSHA thermoplastic qualification timeline acceleration as inflection indicator for mining replacement volume capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Captive material consistency control enables specification differentiation against distributed supply chain competitors in German automotive corridors. |
| Predictive Wear Monitoring Service Bundling | Scheduled swap-out programs compress spot-buying patterns among Virginia and Louisiana shipyard operators. |
| Phthalate-Free Compound Reformulation | ECHA-compliant material declarations gate European supplier qualification ahead of Rotterdam and Amsterdam procurement decisions. |
| Marine Dry-Dock Specialization | Polymer-engineered constructions for cyclic flex fatigue in North Sea operations capture underserved premium positioning. |
| MSHA Thermoplastic Qualification Investment | Evolving underground equipment standards determine compound technology winners in mining replacement volume. |
Research Methodology
Operator-level perspectives from surface preparation contractors, shipyard maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with fleet-scale abrasive blasting operators and channel partners with secondary validation from customs/trade data, SEC 10-K filings of diversified industrial conglomerates, and ECHA substance restriction databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across material formulation, application intensity, and end-user certification requirements.
Sensitivity analysis tested volume and value outputs against variable replacement cycle compression rates and regulatory timeline shifts across the projection horizon. The analytical framework modeled material type, application environment, diameter specification, and end-user certification tier as core segmentation dimensions. CAGRs derived from historical procurement pattern analysis and forward-looking intensity projections for infrastructure refurbishment and offshore platform maintenance. Industry-specific forecast inputs incorporated OSHA inspection mandate enforcement trajectories and REACH substance restriction phase-in schedules.
Forecasts assume regulatory continuity in OSHA workplace exposure limit regimes and EU Machinery Directive documentation requirements; material policy shifts would require re-modeling. Abrasive-media compatibility mapping talent concentration and tropical supply disruption frequency represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as MSHA thermoplastic qualification standards and polyurethane formulation cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
Portugal PVC Pipes Market
Pipes and Tubes
GRP Pipe Market
Pipes and Tubes
Plastic Pipe Jointing and Welding Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
Glass Reinforced Plastic (GRP) Piping Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
North America Hydraulic Fluid Connectors Market
Pipes and Tubes
Pneumatic Fittings Market
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
Seamless Pipe Market
Pipes and Tubes
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market
Pipes and Tubes
Stainless Steel Plumbing Pipes and Fittings Market
Pipes and Tubes
Qatar PVC Pipe Market
Pipes and Tubes
Americas Steel Pipes Market