

Acid Resistant Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Acid Resistant Pipe Market Insights
High-density polyethylene is broadening its addressable scope in acid service as fabricators improve thermal and mechanical ratings for sulfuric acid duty. Georg Fischer leverages captive resin compounding to secure batch consistency across European chemical installations. Saint-Gobain anchors its position through proprietary glass-flake lining systems that extend service life in hydrochloric acid environments. Sekisui Chemical dominates Asian project specifications with integrated design-build contracting for FRP process piping.
An acid resistant pipe is a pressure-retaining conduit engineered from corrosion-proof materials such as fiberglass reinforced plastic with vinyl ester resin matrices or thermoplastic alloys, designed to transport aggressive media including sulfuric, hydrochloric, and nitric acids without wall degradation. These systems typically operate at temperatures up to 120°C for FRP constructions and rely on filament winding or extrusion processes to achieve uniform wall thickness and chemical resistance. Chemical processing plants represent the most established demand pool where process piping installations command premium specification tiers due to leak-tightness requirements. Water treatment facilities emerge as the fastest-growing end use segment as utilities retrofit legacy metallic infrastructure with polypropylene and HDPE systems to handle chlorinated effluent streams.
The EPA enforces secondary containment and leak detection rules under the Clean Water Act that directly mandate corrosion-resistant materials in hazardous waste piping. OSHA's process safety management standard for highly hazardous chemicals compels facilities to specify acid resistant pipe in sulfuric acid and hydrochloric acid service above threshold quantities. ASTM D2996 and ISO 14692 provide dimensional and performance baselines that govern FRP pipe qualification for industrial projects. Stakeholders must track evolving state-level corrosion control mandates and resin price volatility to time capital deployment effectively.
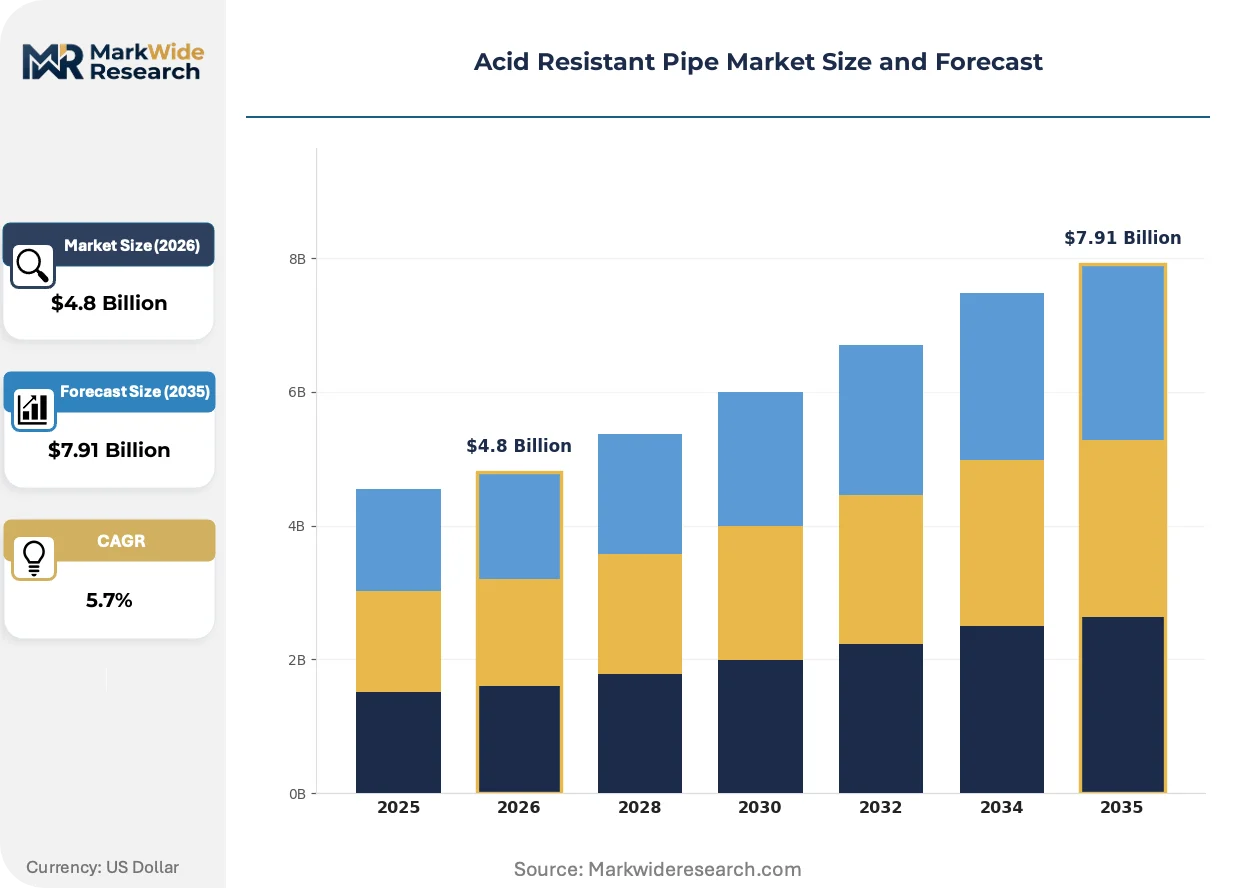
Market Dynamics
Petrochemical corridor expansion along the US Gulf Coast is forcing specification upgrades across acid service infrastructure as operators confront chlorine-induced stress cracking in legacy carbon steel systems. Vinyl ester resin formulations and thermoplastic barrier layers are displacing conventional metallurgy in sulfuric acid transport loops.
Growth Catalysts
- EPA corrosion prevention mandates:Secondary containment rules under the Clean Water Act compel hazardous waste piping upgrades at chemical processing facilities. Utilities must replace metallic infrastructure with FRP or thermoplastic systems to achieve compliance.
- Water treatment retrofit cycles:Chlorinated effluent handling requirements drive polypropylene and HDPE adoption at municipal utilities. Infrastructure renewal programs prioritize corrosion-resistant materials for secondary containment networks.
- OSHA process safety management:Threshold quantity rules for sulfuric acid and hydrochloric acid service mandate leak-tight specification tiers. Facilities above storage limits must install acid resistant pipe with enhanced monitoring capabilities.
Market Restraints
- Resin feedstock volatility:Vinyl ester and epoxy raw material costs fluctuate with benzene and styrene spot markets. Compounders face margin compression when passing through petrochemical price spikes.
- Filament winding capacity concentration:Large-diameter FRP pipe production clusters in coastal manufacturing zones. Project logistics costs escalate when transporting oversized spools to inland chemical installations.
- Thermoplastic temperature ceilings:HDPE and polypropylene constructions face mechanical degradation above 80°C in concentrated acid service. High-temperature process streams still require glass-flake lined steel or exotic alloys.
Strategic Opportunities
- Desalination brine handling:Reverse osmosis concentrate disposal creates demand for chloride-resistant piping at coastal facilities. Thermoplastic systems offer lifecycle cost advantages over super-duplex stainless steel in marine environments.
- EU Green Deal industrial decarbonization:Carbon border adjustment mechanisms incentivize corrosion-resistant materials that extend asset life. Chemical producers specify acid resistant pipe to avoid premature replacement emissions.
- Modular skid fabrication:Pre-assembled process units with integrated piping reduce field welding requirements. Fabricators capture margin by delivering plug-and-play acid service modules to remote mining and metallurgical sites.
Industry Challenges
- FRP laminate inspection protocols:Void detection and delamination assessment require specialized ultrasonic equipment. Third-party certification bodies face backlogs qualifying field inspection personnel.
- Legacy metallic system integration:Cathodic protection schemes and flange compatibility complicate hybrid installations. Engineers must resolve galvanic isolation between thermoplastic and steel components.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acid Resistant Pipe Market Trends and Innovations
Material science advances are compressing the performance gap between thermoplastics and fiber-reinforced composites in aggressive chemical service. Fabricators now engineer multi-layer constructions that combine cost efficiency with extended duty cycles.
Vinyl ester resin systems with nano-silica reinforcement are integrating into high-pressure acid transport applications previously reserved for metallic alloys. Offshore chemical injection facilities adopt these formulations for subsea umbilical cores. The technology is integrating mechanical ratings comparable to carbon steel at one-third the weight, enabling platform operators to reduce structural load requirements.
REACH authorization procedures for chromium compounds are restricting hexavalent chrome pretreatments in glass-flake lining systems. European chemical installations must qualify alternative surface preparation protocols. The regulation is compressing supplier lead times as coating applicators revalidate adhesion performance with trivalent chrome and silane coupling agents.
Asset owner engineering teams are consolidating specifications around performance-based material standards rather than prescriptive resin formulations. Major petrochemical operators now issue functional requirements for acid resistance, temperature rating, and permeation limits. This behavior is compressing proprietary product differentiation and forcing compounders to compete on tested property data rather than brand recognition.
Acid Resistant Pipe Market Segmentation
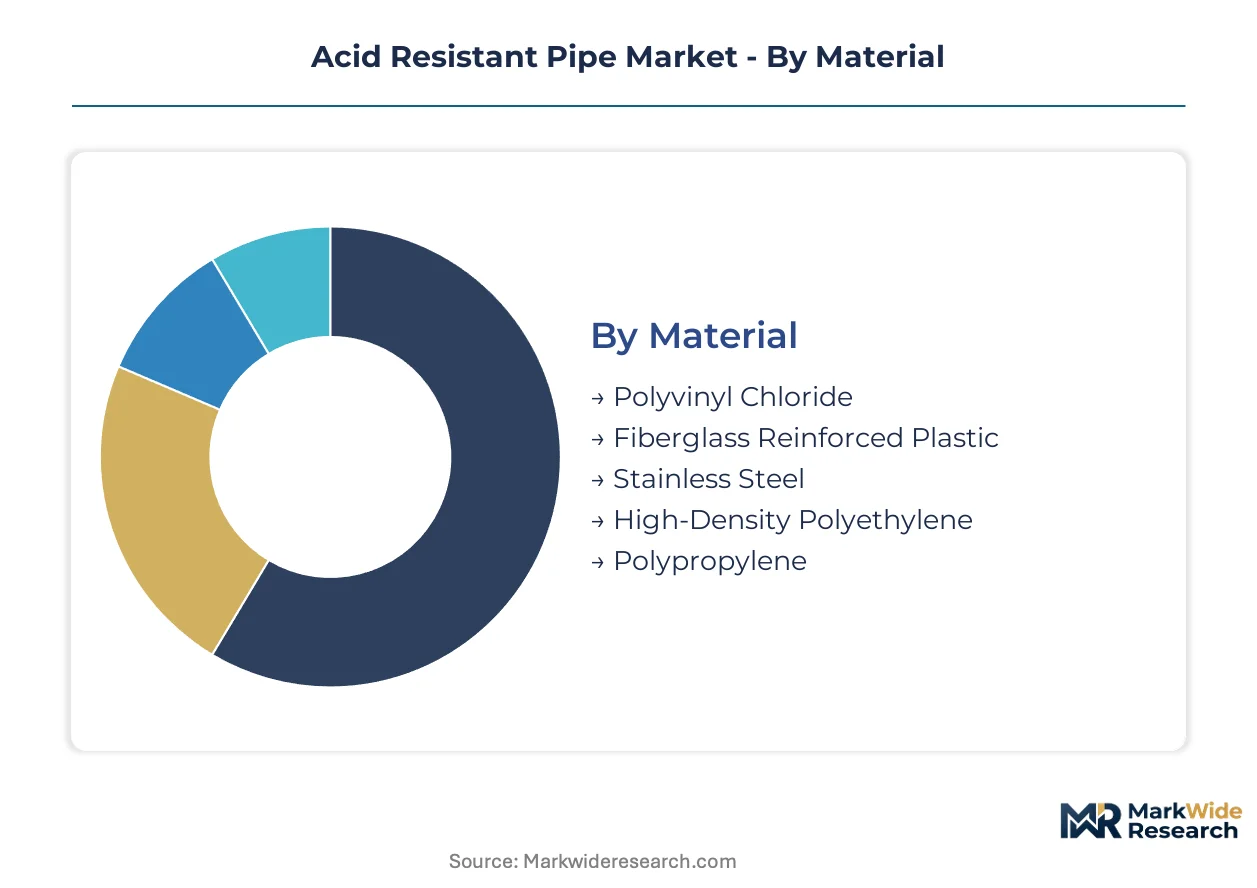
Acid resistant pipe procurement splits sharply between specification-grade materials commanding premium pricing and commodity thermoplastics competing on installed cost. Understanding these tier boundaries enables suppliers to align compounding investments with end-use qualification requirements.
Material:
Volume concentrates in thermoplastic extrusions while premium applications sustain fiber-reinforced composite margins.
- Fiberglass Reinforced Plastic:Vinyl ester resin matrices deliver pressure ratings to 16 bar and temperature tolerance to 120°C for sulfuric acid loops. Chemical processing plants along the US Gulf Coast specify filament-wound constructions for chlorine-resistant process piping.
- High-Density Polyethylene:Thermoplastic extrusions offer weldable joints and impact resistance for secondary containment networks. Water treatment facilities in Texas and Florida retrofit chlorinated effluent systems with HDPE to satisfy EPA corrosion prevention mandates.
- Polypropylene:Homopolymer formulations resist hydrochloric acid permeation at sub-80°C operating envelopes.
- Polyvinyl Chloride:Chlorinated PVC variants handle dilute acid service at municipal infrastructure price points.
- Stainless Steel:Super-duplex alloys retain niche positions for high-temperature acid streams exceeding thermoplastic ceilings.
Today's leader: Fiberglass Reinforced Plastic. Tomorrow's challenger: High-Density Polyethylene.
End Use Industry:
Established chemical infrastructure sustains replacement demand while emerging applications in electronics fabrication open specification opportunities.
- Chemical Processing Plants:Process piping installations require leak-tight specification tiers for sulfuric acid and hydrochloric acid service above OSHA threshold quantities. Operators confront chlorine-induced stress cracking in legacy carbon steel systems across the US Gulf Coast petrochemical corridor.
- Water Treatment Facilities:Chlorinated effluent handling drives thermoplastic adoption as utilities replace metallic infrastructure. Infrastructure renewal programs prioritize corrosion-resistant materials for secondary containment networks.
- Metal Surface Treatment:Pickling line operators specify acid resistant pipe for nitric and hydrofluoric acid circulation.
- Pulp & Paper Mills:Digestor blowline and bleach plant applications demand chloride-resistant constructions.
- Semiconductors:Ultra-high purity acid delivery systems require electro-polished surfaces and permeation barriers.
Chemical Processing Plants anchor current procurement volumes. Water Treatment Facilities are climbing the fastest as municipal retrofit cycles accelerate.
Application:
Transport functions dominate unit volumes while storage and containment applications capture higher per-foot margins.
- Acid Transport:Pressure-rated piping systems move concentrated sulfuric acid between production units and bulk storage. Vinyl ester FRP dominates high-volume corridors where mechanical rating requirements exclude thermoplastic alternatives.
- Industrial Waste Management:Secondary containment piping handles corrosive effluent streams under EPA Clean Water Act mandates. Double-wall thermoplastic constructions with leak detection capability satisfy regulatory requirements.
- Corrosion-Resistant Fluid Transfer:Process cooling and heating loops utilize barrier-lined constructions.
- Chemical Storage Systems:Tank farm interconnects and fill lines require permeation-resistant materials.
- Process Piping:Integrated unit operations specify acid resistant pipe for reactor feed and product transfer.
Acid Transport commands the largest installed base. Industrial Waste Management is gaining share fastest on regulatory compliance spending.
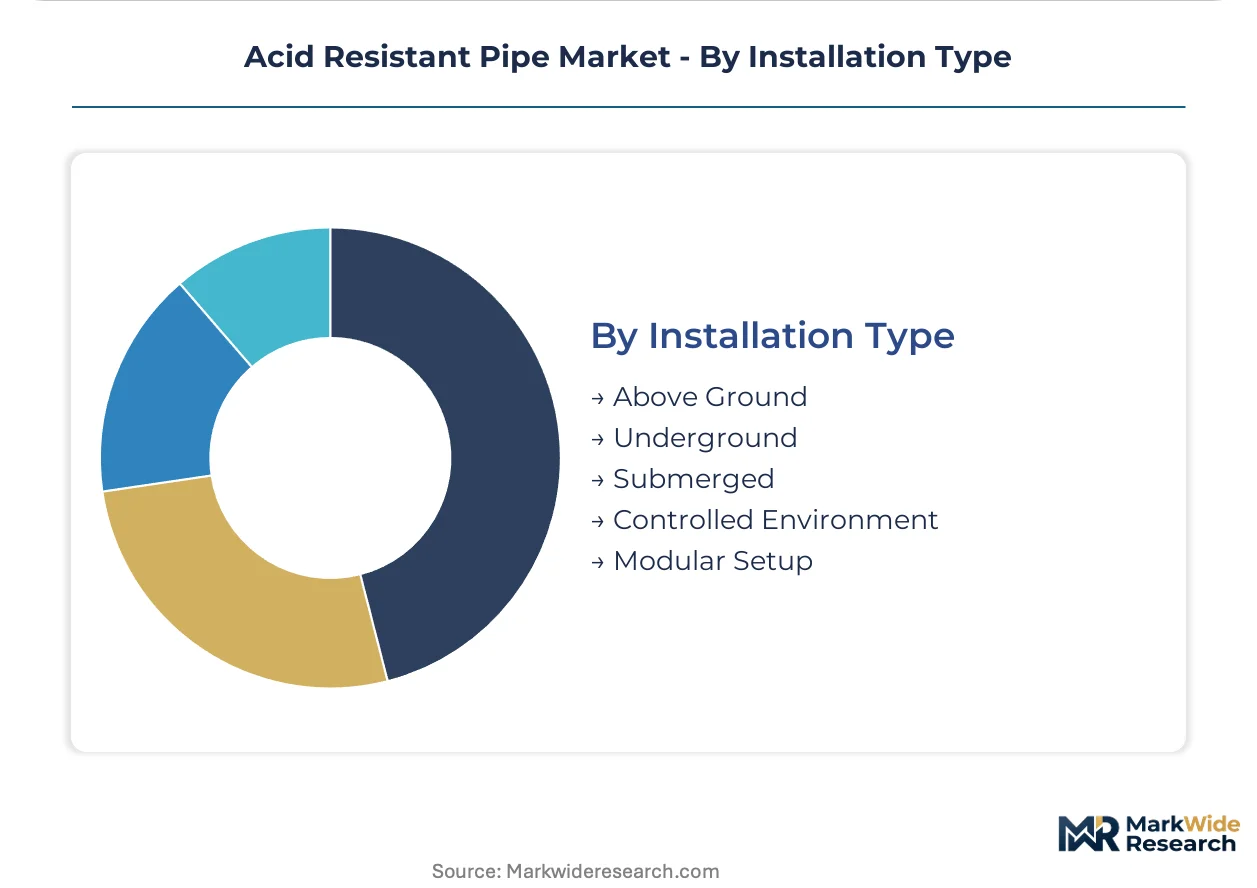
Installation Type:
Above-ground accessibility favors modular fabrication while buried and submerged applications impose additional barrier requirements.
- Above Ground:Rack-mounted and sleeper-supported installations enable visual inspection and maintenance access. Modular skid fabricators pre-assemble process units with integrated piping to reduce field welding requirements at remote mining sites.
- Underground:Direct burial applications demand enhanced stiffness and soil load resistance. Double-wall constructions with interstitial monitoring satisfy secondary containment rules for hazardous waste piping.
- Submerged:Marine and tank-bottom installations require cathodic protection compatibility.
- Controlled Environment:Cleanroom and containment building specifications impose particulate and outgassing limits.
- Modular Setup:Pre-fabricated process skids integrate piping with pumps and instrumentation.
Above Ground retains the dominant specification share. Modular Setup is expanding most quickly as remote project logistics costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical corridor generates concentrated demand for acid-resistant infrastructure as chlorine-induced stress cracking forces replacement of legacy carbon steel systems across Texas and Louisiana refineries.
United States
EPA corrosion prevention mandates under the Clean Water Act compel hazardous waste piping upgrades at chemical processing facilities. OSHA process safety management rules for sulfuric acid threshold quantities tighten material specifications. The Gulf Coast corridor from Houston to New Orleans anchors North American procurement volumes for vinyl ester FRP systems.
Germany
REACH authorization procedures for chromium compounds restrict hexavalent chrome pretreatments in glass-flake lining systems. The EU Green Deal's carbon border adjustment mechanisms incentivize corrosion-resistant materials that extend asset life. Chemical producers in the BASF-Ludwigshafen cluster specify acid resistant pipe to avoid premature replacement emissions.
China
National dual carbon goals accelerate industrial decarbonization investments across chemical processing infrastructure. GB standards govern FRP pipe qualification for sulfuric acid service in coastal manufacturing zones. The Yangtze River Delta petrochemical belt concentrates filament winding capacity for domestic project supply.
Japan
METI industrial efficiency programs promote lifecycle cost optimization in corrosive fluid handling systems. JIS standards provide dimensional baselines for thermoplastic pipe in municipal water treatment applications. The Keiyo industrial corridor east of Tokyo sustains premium specification demand for semiconductor-grade acid delivery systems.
Saudi Arabia
Vision 2030 industrial diversification drives chemical sector capacity expansion requiring acid service infrastructure. The national petroleum regulator mandates corrosion-resistant materials in sour gas processing facilities. The Jubail industrial city complex anchors Middle Eastern demand for high-pressure FRP transport systems.
Acid Resistant Pipe Market Competitive Landscape
Global majors compete with regional champions across resin formulation expertise and project specification relationships. The market structure splits between integrated compounders controlling captive resin supply and specialized fabricators competing on installation proximity. Three archetypes dominate: European glass-flake lining specialists, Asian integrated design-build contractors, and North American thermoplastic extrusion houses. Competitive moves concentrate on backward integration into resin compounding and pre-fabricated modular skid offerings.
Among Swiss-based industrial specialists, Georg Fischer exemplifies the captive resin compounding archetype securing batch consistency across European chemical installations. Sekisui Chemical occupies a position within the Asian integrated contracting tier dominating project specifications through design-build capabilities. Saint-Gobain anchors the proprietary lining systems segment with glass-flake technologies extending service life in aggressive acid environments.
| Leading Market Players |
|---|
| NOV Fiber Glass Systems |
| Future Pipe Industries |
| Amiblu |
| Georg Fischer |
| IPEX |
| AGRU |
| Sekisui Chemical |
| Crane Resistoflex |
| Saint-Gobain |
| Others |
Pricing and Supply Chain Analysis
EPA corrosion prevention mandates under the Clean Water Act gate qualified supply and premium-tier pricing access for acid resistant pipe, as fabricators must certify FRP and thermoplastic systems to satisfy secondary containment rules before bidding hazardous waste piping projects.
Pricing Analysis
Input-cost pass-through from benzene and styrene spot markets compresses margins for vinyl ester compounders during petrochemical price spikes. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade FRP with filament-wound construction from commodity HDPE extrusions and basic PVC alternatives. Cost compression in thermoplastic segments is intensifying because water treatment utilities prioritize installed cost over mechanical ratings. Municipal procurement teams exhibit highest price sensitivity, while Gulf Coast petrochemical operators accept premium pricing for leak-tight specification tiers.
Supply Chain Analysis
Vinyl ester resin supply rests on specialty chemical producers in the United States, Germany, and Japan with captive compounding capabilities. Raw material feeds draw from benzene derivatives, styrene monomers, and glass fiber rovings sourced from coastal manufacturing zones. Single-source vulnerability concentrates in large-diameter filament winding capacity clustered near the US Gulf Coast and China's Yangtze River Delta. Distribution runs through project-based direct sales to EPC contractors and integrated design-build channels for modular skid fabrication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
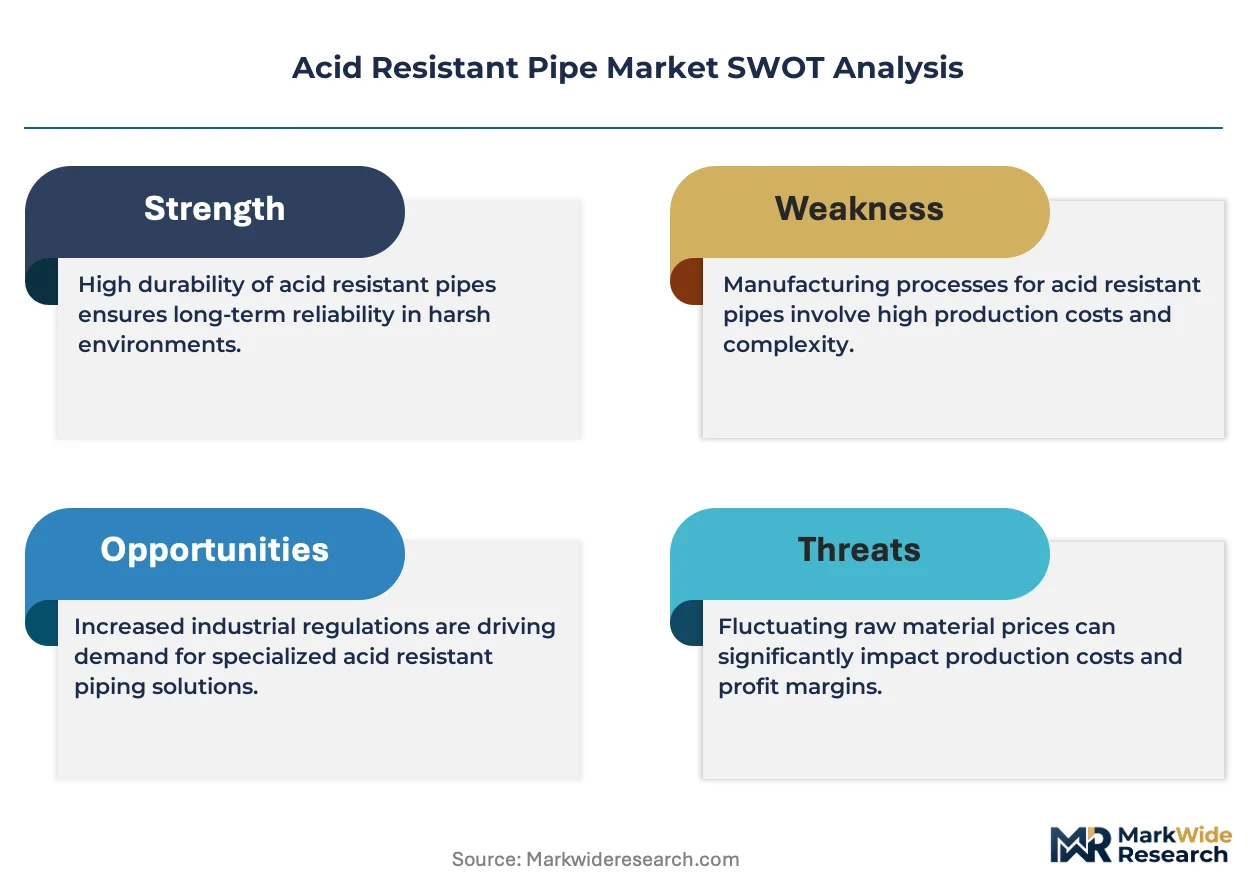
The acid resistant pipe market functions as a geographic-arbitrage play where EPA compliance costs in the United States exceed EU Green Deal carbon border adjustment pressures, creating margin expansion opportunities for European exporters with validated low-emission production.
For Market Incumbents: Anchor Gulf Coast specification relationships through captive resin compounding investments that secure batch consistency for vinyl ester FRP systems. Defend against Asian integrated contractors by qualifying alternative surface preparation protocols ahead of REACH chromium restrictions. Prioritize backward integration into glass fiber roving supply to offset filament winding capacity concentration risks. For New Entrants and Emerging Players: A mid-tier price-point gap between premium FRP and economy PVC creates entry space for reinforced thermoplastic hybrids targeting water treatment retrofit cycles. Municipal utilities in Texas and Florida represent the most penetrable buyer segment given EPA-mandated infrastructure renewal timelines. Pursue design-build contracting capabilities to bypass established specification relationships held by integrated Asian suppliers. For Investors and Strategic Acquirers: Roll-up economics work for regional thermoplastic extrusion houses because project logistics costs escalate when transporting oversized FRP spools inland, creating local fabrication premiums. Target mid-cap specialists with established municipal utility relationships and pending ISO 14692 certification. Watch resin feedstock volatility indices as inflection indicators for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive vinyl ester supply secures batch consistency for Gulf Coast chemical projects. |
| Modular Skid Fabrication Capability | Pre-assembled acid service units reduce field welding at remote mining installations. |
| Alternative Surface Preparation Qualification | Trivalent chrome protocols satisfy REACH restrictions on glass-flake lining systems. |
| Design-Build Contracting Expansion | Integrated project delivery captures margin from Asian specification dominance. |
| Thermoplastic Hybrid Product Development | Multi-layer constructions bridge performance gaps between FRP and commodity plastics. |
Research Methodology
Multiple input streams — executive interviews with plant managers and procurement leads at chemical processing facilities, technical consultations with FRP fabricators and resin compounders, and validation sessions with EPC contractors — were reconciled against customs data, ACC industry reports, and SEC filings from publicly traded material suppliers. Bottom-up project pipeline analysis triangulated with top-down spend estimates from infrastructure renewal program disclosures.
Data-stream reconciliation across material grade tiers, end-use industry classifications, and regional production hub definitions shaped the analytical framework over the projection horizon. CAGRs derived from installed base replacement cycles and capacity expansion announcements were stress-tested against EPA enforcement trend data and OSHA threshold quantity rule updates.
Caveats apply where resin feedstock volatility, state-level corrosion control mandate evolution, or filament winding capacity relocation could materially shift the outlook. A small set of named triggers — benzene derivative pricing, REACH authorization timelines, and Gulf Coast petrochemical corridor expansion announcements — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.