
 Capnography Devices Market | 2026-2036
Capnography Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Capnography Devices Market Analysis
Ambulatory surgical centers are redrawing the demand map for capnography equipment, pulling purchasing power away from traditional hospital anesthesia departments. Medtronic leverages its integrated care portfolio to bundle capnography with broader patient monitoring ecosystems. Masimo anchors its position through proprietary signal processing algorithms that reduce false alarms in high-noise clinical environments. Smiths Medical specializes in portable capnography formats purpose-built for pre-hospital and transport settings.
Capnography devices measure the concentration of carbon dioxide in exhaled breath, typically employing infrared absorption spectroscopy with wavelength specificity near 4.26 micrometers to achieve clinical-grade accuracy. These instruments serve primarily to verify endotracheal tube placement, monitor ventilation adequacy, and detect circulatory collapse during sedation and critical care. Integrated monitors command the dominant revenue position due to their embedding within multiparameter platforms, while handheld capnometers represent the fastest-expanding format as point-of-care diagnostics decentralize beyond traditional operating rooms. Infrared absorption technology leads installed base metrics, though optical sensors are gaining traction in cost-sensitive segments where semiconductor miniaturization enables disposable single-use designs.
The FDA enforces Class II device controls with 510(k) premarket notification requirements for capnography systems, while the EU Medical Device Regulation mandates notified body conformity assessment and post-market surveillance through EUDAMED. These frameworks elevate barriers for new entrants and compel incumbents to maintain dedicated regulatory affairs functions. Stakeholders must monitor evolving interoperability standards that will determine whether capnography data flows into centralized electronic health records or remains trapped within proprietary monitoring ecosystems.
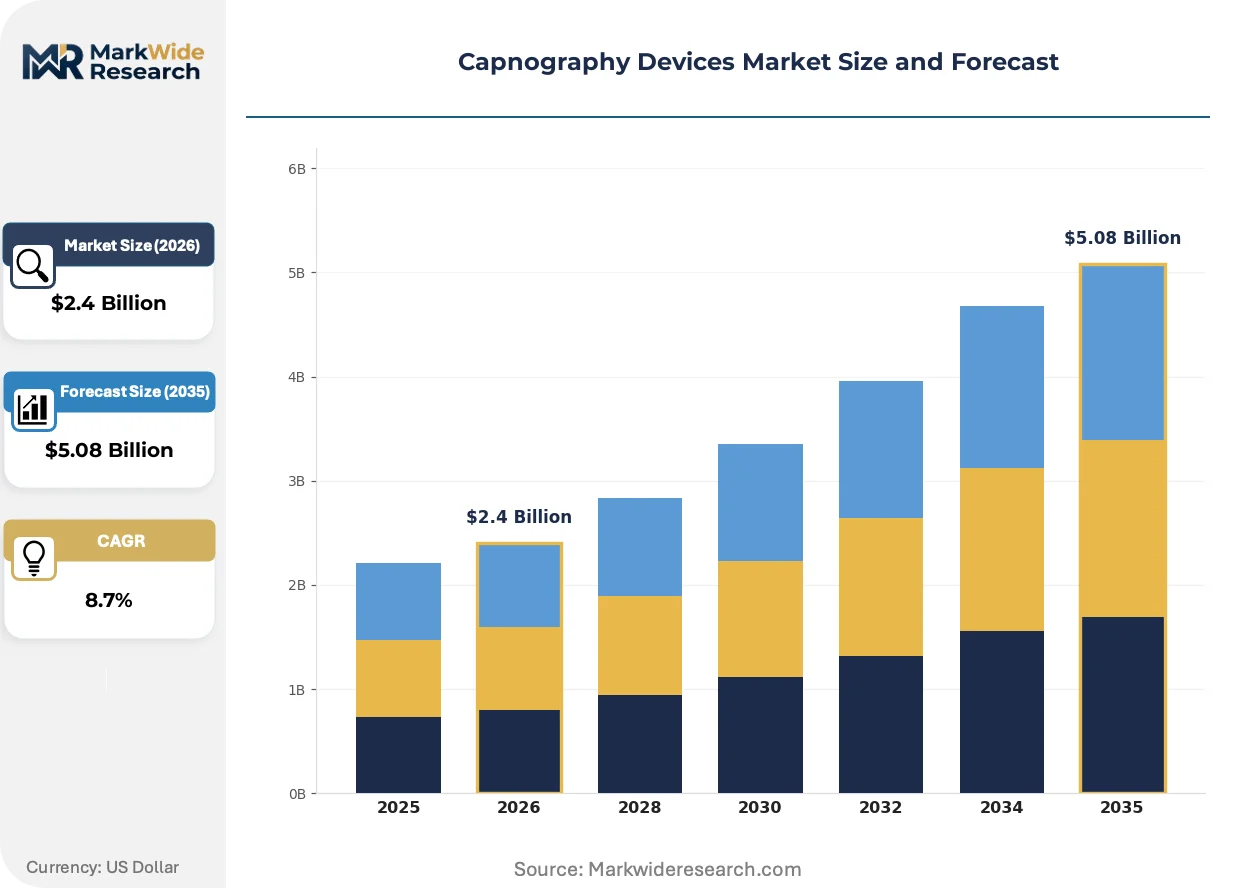
Market Dynamics
The central structural force reshaping capnography devices is the migration of procedural sedation monitoring from centralized anesthesia workstations toward distributed point-of-care settings, fragmenting purchasing authority across emergency departments, procedural suites, and pre-hospital transport networks.
Growth Catalysts
- CMS reimbursement incentives:United States health systems now tie capnography utilization to patient safety quality metrics that directly impact Medicare reimbursement rates, compelling capital allocation toward continuous respiratory monitoring infrastructure.
- Ambulatory surgical center expansion:Freestanding ASCs in Florida, Texas, and California are mandating capnography for moderate sedation cases, creating dedicated equipment procurement workflows separate from hospital anesthesia departments.
- Microelectromechanical systems miniaturization:Semiconductor foundries in Taiwan and South Korea now fabricate optical CO2 sensors at wafer scale, enabling disposable capnography attachments priced for single-patient use.
Market Restraints
- Indium gallium arsenide detector costs:Infrared spectroscopy modules depend on III-V compound semiconductors subject to export control volatility and foundry capacity constraints in East Asian manufacturing hubs.
- FDA 510(k) pathway congestion:Premarket notification backlogs for Class II respiratory monitors now extend review timelines, delaying product launches and compressing effective patent exclusivity windows.
- Pulse oximetry substitution:Widespread deployment of Masimo SET and similar photoplethysmography platforms creates clinical inertia against incremental capnography adoption for routine sedation monitoring.
Strategic Opportunities
- Home-based respiratory monitoring:Post-acute care discharge protocols in Germany and the Netherlands now reimburse remote capnography for high-risk COPD patients, opening direct-to-patient distribution channels.
- EU MDR Article 10 technical documentation:Stricter clinical evidence requirements for legacy devices create first-mover advantage for manufacturers with robust post-market surveillance databases already established.
- Veterinary anesthesia crossover:Companion animal surgical volumes at specialty veterinary hospitals in the United Kingdom and Australia now specify human-grade capnography, leveraging identical sensor platforms with modified software interfaces.
Industry Challenges
- Biomedical engineering talent scarcity:Signal processing expertise for artifact rejection algorithms concentrates at Massachusetts Institute of Technology, Stanford, and ETH Zurich pipelines, constraining R&D scaling for mid-tier manufacturers.
- IEC 60601-1-8 alarm fatigue compliance:Harmonized international standards for alarm signal differentiation require substantial firmware redevelopment, extending certification cycles and freezing product roadmaps.
- Legacy monitor integration:Proprietary data protocols from 1990s-era patient monitoring ecosystems resist HL7 FHIR interoperability, forcing expensive middleware development for health system IT departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capnography Devices Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Capnometers, Bench-top Analyzers, Integrated Monitors, Disposable Capnometers End User: Hospitals, Emergency Medical Services, Home Care, Anesthesia Providers Technology: Infrared Absorption, Mass Spectrometry, Semiconductor Sensors, Optical Sensors Application: Monitoring, Research, Diagnostic Procedures, Veterinary Use |
| Companies Covered | Medtronic, Koninklijke Philips N.V., Masimo, Drägerwerk AG & Co. KGaA, Smiths Medical, Nihon Kohden Corporation, Becton Dickinson and Company, GE Healthcare, ICU Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capnography Devices Market Emerging Trajectories
Capnography technology is fragmenting across performance tiers as semiconductor economics enable disposable formats while integrated systems pursue premium clinical decision support capabilities. This divergence is compressing mid-market positioning and forcing strategic clarity on value proposition architecture.
Optical CO2 sensing based on photonic integrated circuits is bifurcating the installed base. High-acuity integrated monitors embed wavelength-specific infrared benches for surgical anesthesia, while EMS and transport applications adopt silicon photonics disposable sensors from STMicroelectronics and ams OSRAM foundry partnerships. The structural consequence is bifurcating R&D investment between precision spectroscopy and cost-optimized single-use manufacturing, with few vendors sustaining competence across both domains.
The FDA's 2023 guidance on physiologic closed-loop control systems now mandates explicit capnography integration for any automated sedation delivery device seeking premarket approval. This industrial consequence elevates capnography from standalone monitoring to critical safety interlock status. General anesthesia device manufacturers in the United States are responding by acquiring capnography module suppliers or developing captive optical sensing capabilities to secure supply chain control.
Hospital procurement departments now unbundle capnography modules from multiparameter monitor bundles, negotiating separate pricing for sensors, cables, and software licenses. This purchasing pattern disruption fragments vendor lock-in strategies that previously relied on integrated ecosystem pricing. The shift is most visible in United States academic medical centers where supply chain rationalization initiatives separate capital equipment from recurring consumable commitments.
Capnography Devices Market Segmentation
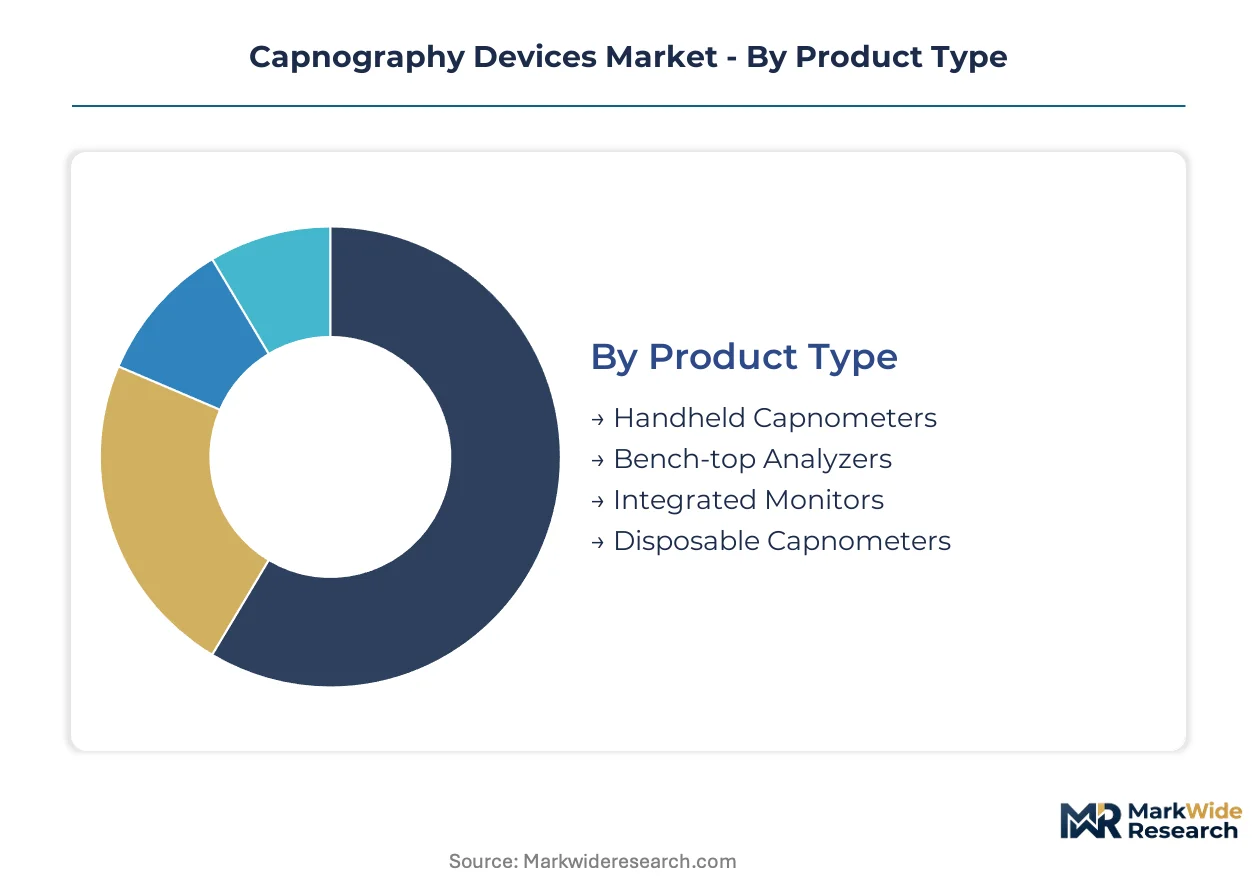
Capnography devices fragment across four intersecting dimensions that determine procurement workflows, regulatory pathways, and recurring revenue models. Product format dictates capital intensity and consumable attachment rates. End-user concentration shapes distribution channel economics and service contract structures.
Product Type:
Margin pools concentrate in integrated systems where software licensing and sensor consumables compound lifetime value, while handheld formats compete on unit economics and replacement velocity.
- Integrated Monitors:These systems embed capnography modules within multiparameter patient monitoring platforms, sharing power supplies, displays, and data infrastructure. Demand concentrates in United States academic medical centers where CMS reimbursement incentives reward continuous respiratory monitoring during moderate sedation procedures. Bundled software subscriptions for trend analysis and alarm management extend recurring revenue streams.
- Handheld Capnometers:Portable battery-operated units deliver spot-check CO2 measurements through mainstream or sidestream sampling configurations. Emergency Medical Services in Texas, Florida, and California represent the fastest-expanding demand cluster as pre-hospital protocols mandate quantitative waveform capnography for intubation verification. Semiconductor miniaturization from Taiwanese foundries enables sub-$500 unit pricing for single-patient-use disposability.
- Bench-top Analyzers:Laboratory-grade instruments with reference-level accuracy serve calibration verification and research applications requiring NIST-traceable measurements.
- Disposable Capnometers:Single-use optical sensors eliminate cross-contamination risk in ambulatory surgical centers and transport settings where sterilization logistics prove prohibitive.
Integrated monitors hold installed capacity in hospital anesthesia departments. Handheld capnometers are rotating up the share rankings as point-of-care diagnostics decentralize beyond traditional operating rooms.
End User:
Procurement authority is fragmenting as purchasing decisions migrate from centralized anesthesia departments toward distributed clinical units with distinct technical requirements.
- Hospitals:Inpatient facilities deploy capnography across operating rooms, intensive care units, and procedural sedation suites with enterprise-wide standardization mandates. United States health systems prioritize interoperability with existing electronic health record infrastructure, favoring vendors with HL7 FHIR connectivity. Capital equipment procurement cycles extend 18-36 months with dedicated clinical engineering evaluation committees.
- Anesthesia Providers:Physician practices and anesthesia management companies operate captive equipment fleets for hospital contracts and ambulatory surgical center coverage. Demand concentrates in high-volume ophthalmology and gastroenterology centers where moderate sedation case volumes justify dedicated monitoring infrastructure. Malpractice insurance carriers increasingly require documented capnography utilization for policy renewal eligibility.
- Emergency Medical Services:Ground and air transport agencies specify ruggedized formats with extended temperature operating ranges and rapid calibration protocols.
- Home Care:Post-acute discharge programs in Germany and the Netherlands now reimburse remote respiratory monitoring for high-risk COPD patients, opening direct-to-patient distribution channels.
Hospitals retain the deepest installed base. Anesthesia providers are climbing the fastest as freestanding surgical center expansion redistributes procedural volume.
Technology:
Cost tier stratification separates precision spectroscopy for surgical anesthesia from semiconductor economics enabling single-use disposability.
- Infrared Absorption:Wavelength-specific detection near 4.26 micrometers delivers clinical-grade accuracy through mainstream or sidestream gas sampling configurations. United States integrated monitor manufacturers specify indium gallium arsenide detectors subject to export control volatility and foundry capacity constraints in East Asian manufacturing hubs. This technology dominates high-acuity installed bases where alarm fatigue compliance requires artifact rejection sophistication.
- Optical Sensors:Photonic integrated circuits fabricated at wafer scale enable disposable CO2 sensing for cost-sensitive segments. STMicroelectronics and ams OSRAM foundry partnerships supply silicon photonics platforms to EMS and transport equipment manufacturers. The structural consequence bifurcates R&D investment between precision spectroscopy and cost-optimized manufacturing.
- Semiconductor Sensors:Microelectromechanical systems miniaturize thermal conductivity and metal oxide detection principles for consumer-health crossover applications.
- Mass Spectrometry:Reference-grade analytical precision serves research and calibration laboratory environments where absolute accuracy validation proves essential.
Infrared absorption holds installed capacity in operating room anesthesia workstations. Optical sensors are rotating up the share rankings as ambulatory and pre-hospital applications expand.
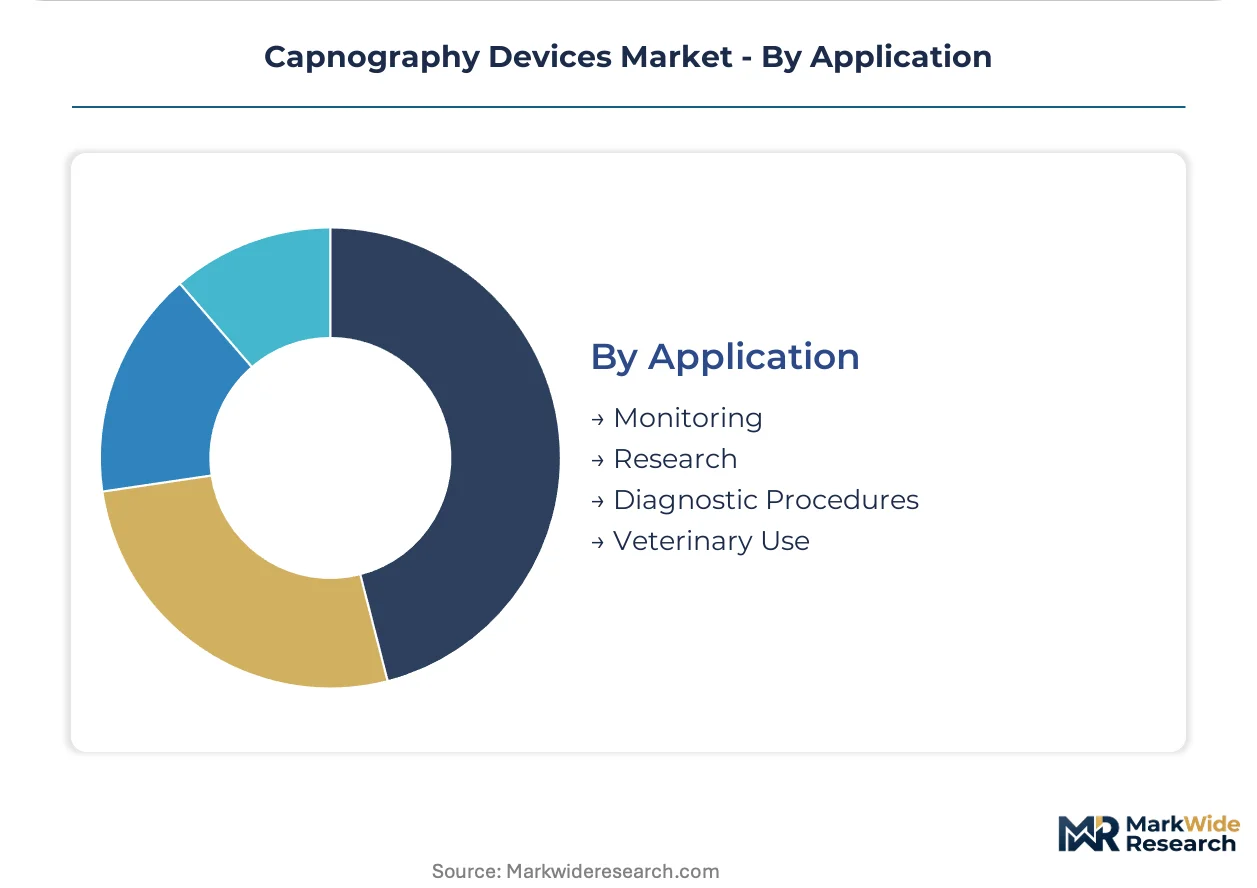
Application:
Volume concentration sits with continuous monitoring during procedural sedation, while research and veterinary segments command premium pricing with lower competitive intensity.
- Monitoring:Real-time ventilation assessment during sedation, anesthesia, and critical care represents the dominant volume application. United States hospital systems tie capnography utilization to patient safety quality metrics that directly impact Medicare reimbursement rates. The FDA's updated premarket guidance for respiratory monitoring devices accelerates compliance investments among manufacturers targeting this segment.
- Veterinary Use:Companion animal surgical volumes at specialty veterinary hospitals in the United Kingdom and Australia now specify human-grade capnography. Equipment vendors leverage identical infrared sensor platforms with modified software interfaces for species-specific respiratory rate interpretation. Regulatory pathways bypass human medical device controls, compressing time-to-market for qualified manufacturers.
- Diagnostic Procedures:Capnography serves bronchoscopy, laparoscopy, and cardiac catheterization suites for procedural sedation safety verification.
- Research:Metabolic and pulmonary physiology studies require calibrated instruments with data logging capabilities and exportable waveform archives.
Monitoring commands the deepest installed base. Veterinary use is climbing the fastest as specialty animal hospitals upgrade from pulse oximetry substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics infrastructure underwrites the Netherlands' distribution centrality for European capnography supply chains. Hospital procurement networks in Düsseldorf and Hamburg cluster around this maritime gateway.
United States
Academic medical centers in Boston and Houston drive integrated monitor procurement tied to CMS reimbursement incentives for moderate sedation safety metrics. The FDA's 510(k) premarket notification pathway governs Class II respiratory device approvals. Manufacturing concentration clusters in Minnesota and Massachusetts around precision optical sensing supply chains.
Germany
Post-acute care discharge protocols in Bavaria and North Rhine-Westphalia now reimburse remote capnography for high-risk COPD patients. The EU Medical Device Regulation mandates notified body conformity assessment through EUDAMED surveillance. Medical technology manufacturing concentrates in Baden-Württemberg around Stuttgart's precision engineering ecosystem.
Japan
Aging demographic pressures in Tokyo and Osaka metropolitan areas expand home-based respiratory monitoring demand. The PMDA enforces stringent clinical evidence requirements for Class II medical device approvals. Yokohama's biomedical corridor hosts semiconductor foundries fabricating optical CO2 sensors at wafer scale.
United Kingdom
Specialty veterinary hospitals in London and Manchester specify human-grade capnography for companion animal surgical volumes. MHRA post-Brexit regulatory alignment with EU MDR technical documentation requirements creates compliance complexity. Cambridge's photonics cluster supplies silicon photonics platforms for disposable sensor manufacturing.
Australia
Emergency medical services in New South Wales and Victoria mandate quantitative waveform capnography for pre-hospital intubation verification. The TGA's medical device regulatory framework requires conformity assessment for infrared spectroscopy modules. Sydney's biomedical precinct concentrates distribution infrastructure for Asia-Pacific market access.
Capnography Devices Market Vendor Landscape
Listed leaders compete with private specialists across integrated monitoring ecosystems and point-of-care portability dimensions. The vendor base stratifies into three tiers: diversified medical technology conglomerates with multiparameter platforms, mid-cap anesthesia equipment specialists with regional service networks, and semiconductor-enabled disposable sensor manufacturers with foundry partnerships. Archetypes include ecosystem bundlers leveraging integrated care portfolios, algorithm-focused signal processing specialists, and transport-format portability engineers. Dominant competitive moves encompass strategic partnerships with EMS procurement consortiums and portfolio diversification into veterinary anesthesia crossover applications.
Within the ecosystem bundler tier, Medtronic and Koninklijke Philips N.V. represent integrated care portfolio architectures that embed capnography within broader patient monitoring infrastructure. Masimo occupies a position exemplifying proprietary signal processing specialization for high-noise clinical environments. Drägerwerk AG & Co. KGaA anchors German precision engineering heritage in anesthesia workstation integration. These three named entities collectively illustrate the competitive divergence between multiparameter platform dominance and discrete monitoring module specialization.
| Leading Market Players |
|---|
| Medtronic |
| Koninklijke Philips N.V. |
| Masimo |
| Drägerwerk AG & Co. KGaA |
| Smiths Medical |
| Nihon Kohden Corporation |
| Becton Dickinson and Company |
| GE Healthcare |
| ICU Medical |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) premarket notification requirements gate both supplier qualification and price tiering in capnography devices, as Class II respiratory monitor certification separates premium integrated systems from uncertified economy alternatives while concentrating procurement authority among buyers with dedicated regulatory affairs resources.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates capnography procurement, with FDA-cleared integrated monitors commanding premium positioning against uncertified handheld units. Price differentiation rests on alarm fatigue compliance certification and HL7 FHIR interoperability depth. Cost compression in handheld segments is intensifying because Taiwanese foundry partnerships enable sub-$500 disposable sensor economics. Ambulatory surgical centers exhibit highest price sensitivity, while United States academic medical centers prioritize certification tier over unit cost.
Supply Chain Analysis
East Asian foundry capacity constraints in Taiwan and South Korea create chokepoint vulnerability for indium gallium arsenide detector supply. Optical CO2 sensor production draws from III-V compound semiconductor wafer fabrication, sidestream sampling tubing polymers, and precision optical bench assemblies. Single-source dependency on East Asian III-V foundries exposes manufacturers to export control volatility and geopolitical disruption. Distribution runs through hospital GPO contracts, EMS procurement consortiums, and direct-to-patient channels for home care reimbursement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capnography device demand fragments across distributed point-of-care settings, creating niche specialization opportunities as purchasing authority migrates from centralized anesthesia departments toward emergency departments, procedural suites, and pre-hospital transport networks.
For Market Incumbents: Compound ecosystem lock-in through proprietary alarm management software subscriptions and sensor consumable bundling. Deepen backward integration into optical CO2 sensor foundry partnerships to secure III-V semiconductor supply against export control volatility. Prioritize IEC 60601-1-8 alarm fatigue compliance certification as defensive moat against mid-tier competitors lacking firmware redevelopment resources. For New Entrants and Emerging Players: Differentiate on veterinary anesthesia crossover applications where regulatory pathways bypass FDA 510(k) requirements, compressing time-to-market for qualified manufacturers. Target United Kingdom and Australia companion animal surgical centers as most penetrable segment. Pursue direct distribution through specialty veterinary equipment distributors rather than human medical device channels. For Investors and Strategic Acquirers: EU MDR Article 10 technical documentation requirements reshape the acquisition landscape toward manufacturers with established post-market surveillance databases. Five-to-ten year viability favors targets with robust clinical evidence libraries and EUDAMED registration history. Monitor FDA 510(k) review timeline compression as signal for patent exclusivity window erosion and accelerated consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership for Optical Sensors | Taiwanese wafer-scale fabrication secures supply chain control for disposable CO2 sensing modules. |
| FDA 510(k) Parallel Submission | Dual-track respiratory monitor approvals compress time-to-market for integrated sedation safety systems. |
| Veterinary Software Interface Development | Species-specific respiratory rate algorithms unlock companion animal hospital procurement workflows. |
| HL7 FHIR Interoperability Certification | Electronic health record connectivity satisfies United States academic medical center procurement mandates. |
| EMS Procurement Consortium Engagement | Texas and Florida transport agency contracts establish pre-hospital market beachhead against hospital-centric incumbents. |
Methodological Framework
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and EMS procurement officers and refined through secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR EUDAMED surveillance data. Bottom-up sensor unit economics and top-down health system capital expenditure patterns were triangulated to reconcile volume estimates.
Variance decomposition across product format, end-user concentration, technology tier, and application intensity shaped the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycles, ambulatory surgical center expansion trajectories, and semiconductor miniaturization adoption curves. Modeled inputs included Taiwan foundry capacity utilization, United States moderate sedation procedure volume trends, and EU MDR notified body assessment timelines.
Material uncertainties — FDA 510(k) review backlog resolution, III-V compound semiconductor export control adjustments, and CMS quality metric reimbursement weighting changes — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and foundry capacity expansion. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and East Asian manufacturing hub geopolitical conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Digital BTE Market
Medical Devices
Medical Device and Accessories Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
Non-Invasive Ventilators Market
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
Oxygen Delivery Units Market
Medical Devices
Prefilled Syringes Market
Medical Devices
Catheter Systems Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
Global Centesis Catheters Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market