
 Global Medical Grade Coating Market | 2026-2036
Global Medical Grade Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Grade Coating Market Intelligence
The substitution of traditional polymers with advanced hydrogel coatings is broadening the functional capabilities of medical devices. Surmodics Inc specializes in surface modification technologies for vascular and ophthalmic applications. DSM-Firmenich leverages its extensive material science portfolio to offer a wide range of biocompatible coating solutions. Hydromer Inc competes on the basis of its hydrophilic and antimicrobial coating technologies, targeting high-performance device categories.
Medical grade coatings are specialized surface treatments applied to medical devices, implants, and instruments. These coatings are formulated for biocompatibility, often exhibiting properties like hydrophilicity, antimicrobial action, or drug-eluting capabilities to enhance device performance and patient safety. Hydrogel and silicone-based coatings lead the market due to their superior lubricity and biocompatibility. Within applications, coatings for cardiovascular devices and orthopedic implants represent the largest and most technically demanding segments.
Market access is governed by stringent regulatory frameworks, including clearance from the US FDA, CE marking under the EU's MDR, and approval from China's NMPA. These regulations mandate extensive testing for biocompatibility, toxicity, and coating integrity, directly influencing material selection and development timelines. Suppliers must navigate the complex validation pathways while innovating materials to meet demands for next-generation combination devices and smart implants.
Market Dynamics
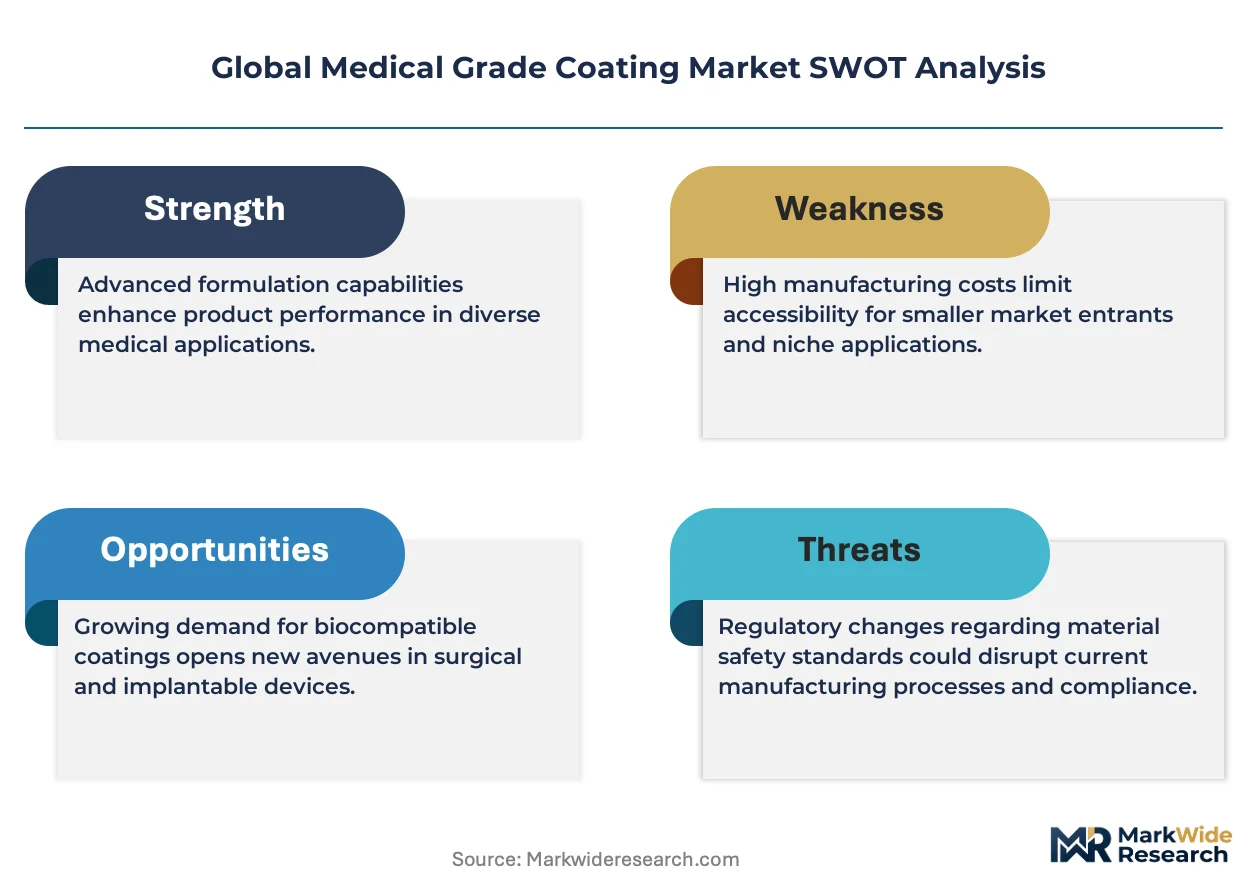
The market's structure is defined by intensifying regulatory scrutiny over biocompatibility. Stringent frameworks from the FDA and the EU's MDR are compelling a fundamental shift toward advanced, functionally specific coating formulations for high-risk medical devices.
Growth Catalysts
- Complex Cardiovascular Devices:Proliferation of minimally invasive procedures fuels demand for coatings on devices like drug-eluting stents and guidewires, which require superior lubricity and therapeutic delivery capabilities.
- EU Medical Device Regulation (MDR):The regulation's stricter requirements for clinical evidence and biocompatibility are driving adoption of well-characterized, high-performance coatings over older, less-documented materials.
- Manufacturing Hub Concentration:Demand is concentrated in established medical device manufacturing centers in Germany, the United States, and Japan, creating localized ecosystems for coating innovation and application.
Market Restraints
- Regulatory Validation Costs:The extensive biocompatibility and toxicity testing mandated by bodies like the US FDA and China's NMPA represents a significant financial and time barrier to entry for new materials.
- Adhesion on Novel Substrates:Achieving durable adhesion on new polymers and metal alloys used in next-generation implants and instruments remains a significant technical hurdle for coating formulators.
- Raw Material Dependencies:The supply chain relies on a limited number of specialized suppliers for critical raw materials like specific hydrophilic polymers or pharmaceutical ingredients for drug-eluting coatings.
Strategic Opportunities
- Combination Devices:The development of smart implants that integrate sensors or electronics creates an opportunity for coatings that provide electrical insulation, biocompatibility, and signal fidelity.
- Antimicrobial-Lubricious Coatings:There is a significant opportunity for dual-function coatings that combine antimicrobial action with lubricity to reduce infection rates associated with catheters and other invasive devices.
- Emerging Manufacturing in Brazil:As Brazil's medical device industry grows, there is an unmet need for local, high-quality coating application services that can meet ANVISA regulatory standards.
Industry Challenges
- Lengthy Validation Pathways:Navigating the complex and time-consuming device approval processes of regulators like the FDA and Japan's PMDA significantly delays the commercialization of innovative coating technologies.
- Intellectual Property Complexity:Formulating drug-eluting coatings requires navigating a complex web of patents and licensing agreements for the active pharmaceutical ingredients, creating legal and financial hurdles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Grade Coating Market |
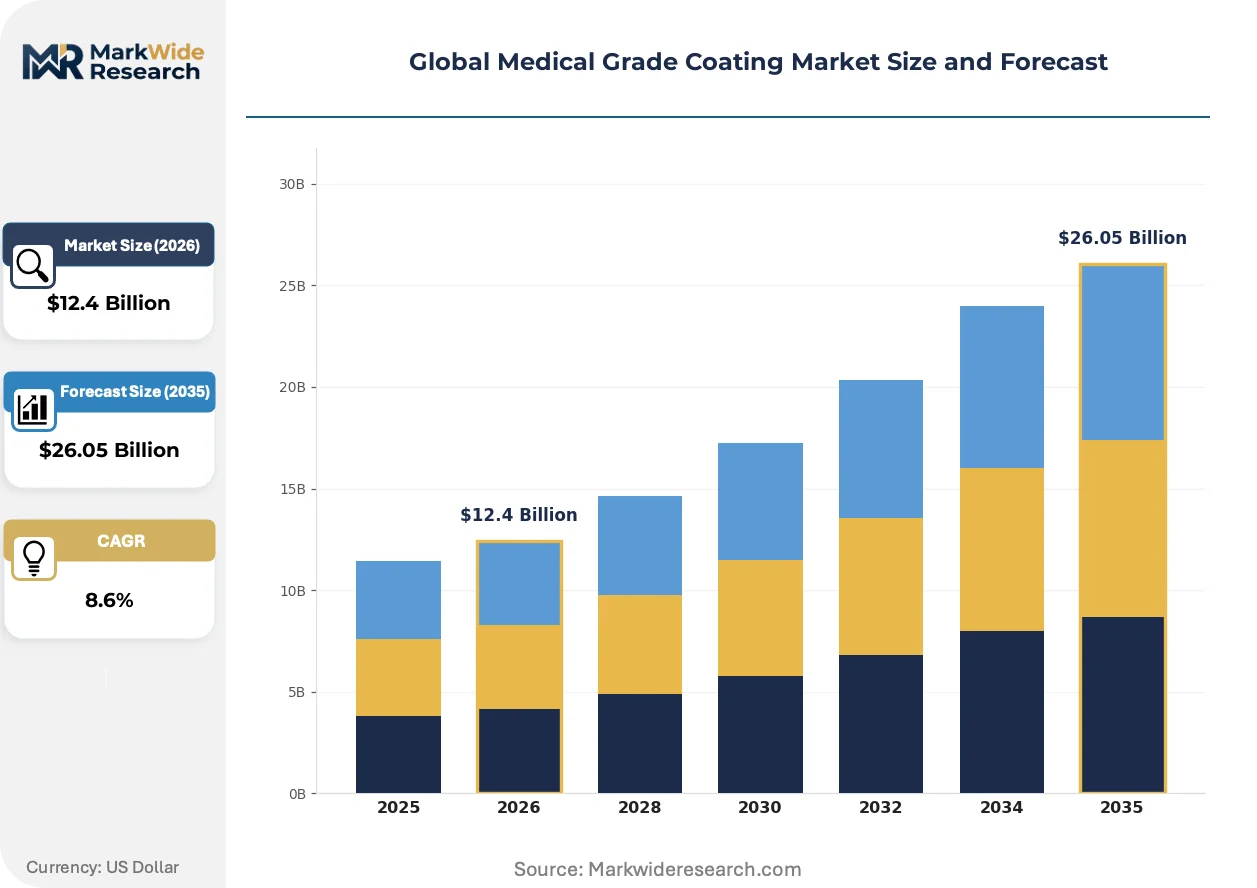
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogel, Silicone, Polyurethane, Acrylic, Fluoropolymer, Epoxy Application: Orthopedic Implants, Cardiovascular Devices, Surgical Instruments, Diagnostic Equipment, Contact Lenses, Drug Delivery Systems End User: Hospitals, Ambulatory Surgery Centers, Specialized Clinics, Diagnostic Laboratories, Research Institutes, Rehabilitation Facilities Technology: Spray Coating, Dip Coating, Electrostatic Coating, Plasma Polymerization, Chemical Vapor Deposition, Physical Vapor Deposition |
| Companies Covered | AST Products Inc, DSM-Firmenich, Surmodics Inc, Precision Coating Co. Inc, Harland Medical Systems Inc, Biocoat Inc, Covalon Technologies Ltd, Medicoat AG, Hydromer Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Grade Coating Market Strategic Shifts & Innovations
Innovation in medical grade coatings is increasingly focused on multifunctionality. Material science advancements are enabling single coating systems to perform tasks that previously required multiple materials or complex device designs, driven by stricter performance standards.
Advanced hydrogel coatings provide exceptional lubricity and biocompatibility, reducing tissue trauma during device insertion. Manufacturers of vascular and urological catheters are rapidly adopting these materials to improve patient outcomes. This technology is absorbing the functions of separate lubricating agents and surface treatments, simplifying the manufacturing process.
The EU's Medical Device Regulation (MDR) has intensified scrutiny on the entire lifecycle of coated medical devices. This regulation forces manufacturers to provide more extensive data on coating integrity, leaching, and long-term biocompatibility. Orthopedic and cardiovascular implant segments are most impacted, prompting investment in advanced analytical testing and material characterization.
A clear shift from transactional purchasing to collaborative development partnerships is underway between device OEMs and coating specialists. The standard model of buying off-the-shelf coatings is being replaced by joint R&D to create application-specific formulations. This trend is most visible in the United States and Germany for complex combination device development.
Global Medical Grade Coating Market Segmentation
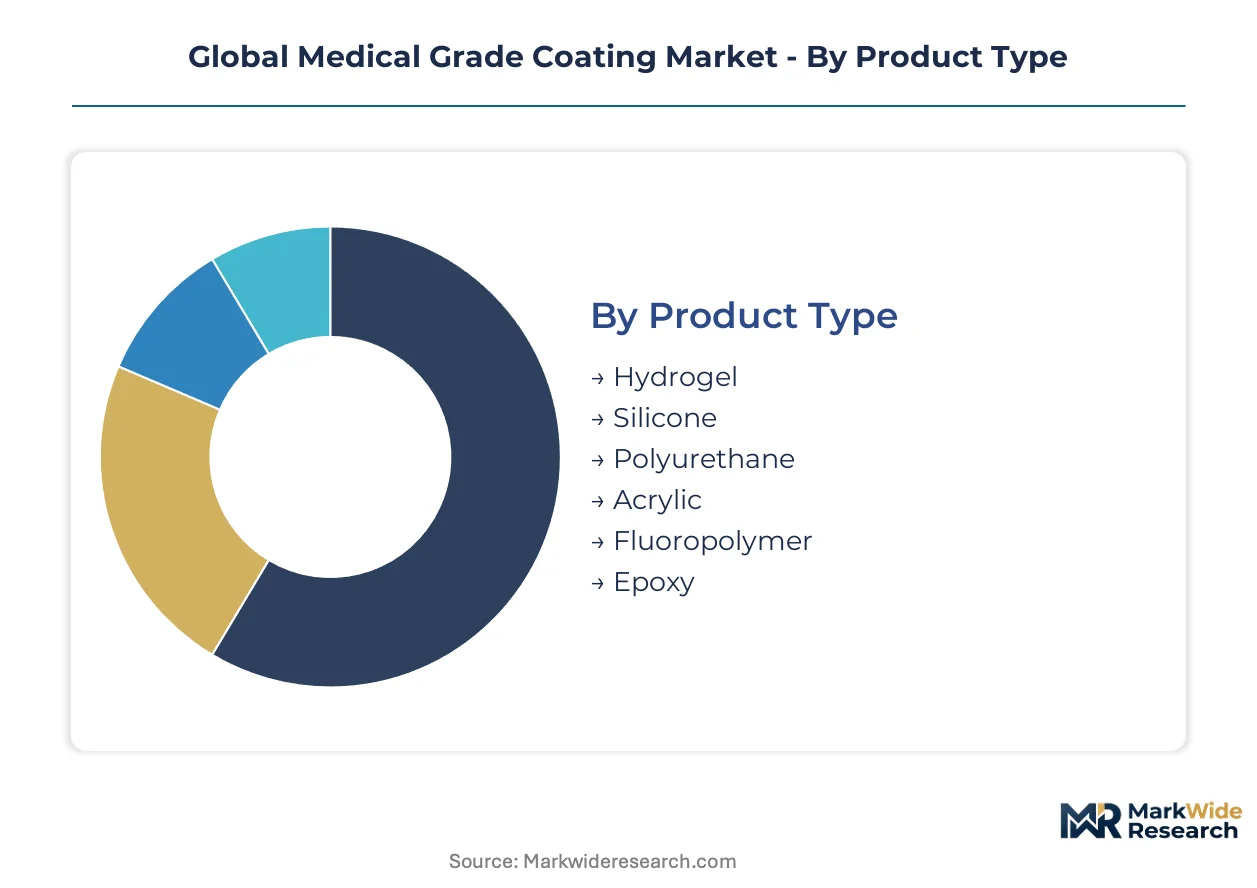
The medical grade coating market segments reveal distinct performance requirements and adoption patterns across diverse device categories. Understanding these segments is crucial for manufacturers navigating regulatory complexities and targeting innovation effectively. Each segment reflects specific material science challenges and opportunities for enhanced patient outcomes.
Product Type:
The emphasis on medical device longevity and performance drives a continuous upgrade cycle within coating product types, favoring materials that offer superior biocompatibility and functionality.
- Hydrogel:These coatings are hydrophilic polymers that absorb water, creating a lubricious, low-friction surface. They are widely adopted in vascular and urological catheters to reduce tissue trauma and improve patient comfort.
- Silicone:Known for its flexibility, biocompatibility, and chemical inertness, silicone coatings provide excellent barrier properties and lubricity. They are extensively used on implantable devices and surgical instruments for enhanced performance.
- Polyurethane:This versatile polymer offers good mechanical strength and abrasion resistance, finding use in various medical applications requiring durable surface protection.
- Acrylic:Acrylic coatings provide clarity and hardness, often employed for protective layers on diagnostic equipment components and some external medical devices.
- Fluoropolymer:Valued for their non-stick properties and chemical resistance, fluoropolymers are applied to guidewires and specialized surgical tools.
- Epoxy:Epoxy coatings offer strong adhesion and chemical resistance, typically used for encapsulating electronic components within smart implants and sensors.
Volume placements concentrate in Silicone; the faster expansion belongs to Hydrogel.
Application:
Medical device applications dictate precise coating requirements, demanding specialized formulations for patient safety and efficacy across a wide range of therapeutic areas.
- Cardiovascular Devices:Coatings for drug-eluting stents, guidewires, and advanced catheters require exceptional lubricity, hemocompatibility, and controlled drug release. These devices operate in highly sensitive physiological environments.
- Orthopedic Implants:This segment demands coatings that enhance osseointegration, reduce friction in joint replacements, and provide antimicrobial properties. Long-term durability and biocompatibility are paramount for these permanent implants.
- Surgical Instruments:Coatings on surgical instruments improve handling, reduce glare, and provide antimicrobial protection, enhancing precision and sterilization efficacy in operating rooms.
- Diagnostic Equipment:Surface treatments for diagnostic equipment components ensure chemical resistance, ease of cleaning, and optical clarity for accurate measurements.
- Contact Lenses:Hydrophilic coatings on contact lenses enhance comfort and oxygen permeability, improving wearability for extended periods.
- Drug Delivery Systems:Coatings play a critical role in controlled release mechanisms for various pharmaceutical formulations, ensuring targeted and sustained therapeutic effects.
The primary growth vector stems from cardiovascular devices and orthopedic implants, reflecting their high technical demands.
End User:
Diverse end-user environments, from surgical settings to research laboratories, shape the demand for specialized medical grade coatings tailored to specific operational needs.
- Hospitals:Hospitals represent the largest end-user segment, driven by high volumes of surgical procedures, implantations, and diagnostic tests requiring coated devices and instruments.
- Ambulatory Surgery Centers:These facilities conduct a growing number of outpatient procedures, increasing demand for cost-effective, high-performance coated devices with rapid turnaround.
- Specialized Clinics:Clinics focusing on specific medical areas like ophthalmology or cardiology utilize specialized coated devices, including contact lenses and cardiac catheters.
- Diagnostic Laboratories:Laboratories employ coated consumables and equipment components for accurate sample analysis and chemical resistance in various testing procedures.
- Research Institutes:Academic and private research entities utilize advanced coated materials for developing next-generation medical devices and testing novel coating formulations.
- Rehabilitation Facilities:These centers use medical devices with coatings that enhance patient comfort and device longevity, particularly for long-term use and physical therapy aids.
Demand across end-user segments varies by regulatory stringency and procedural volume, with hospitals leading consumption.
Technology:
The choice of coating technology directly impacts adhesion, uniformity, and cost-effectiveness, influencing manufacturing process efficiency and device performance characteristics.
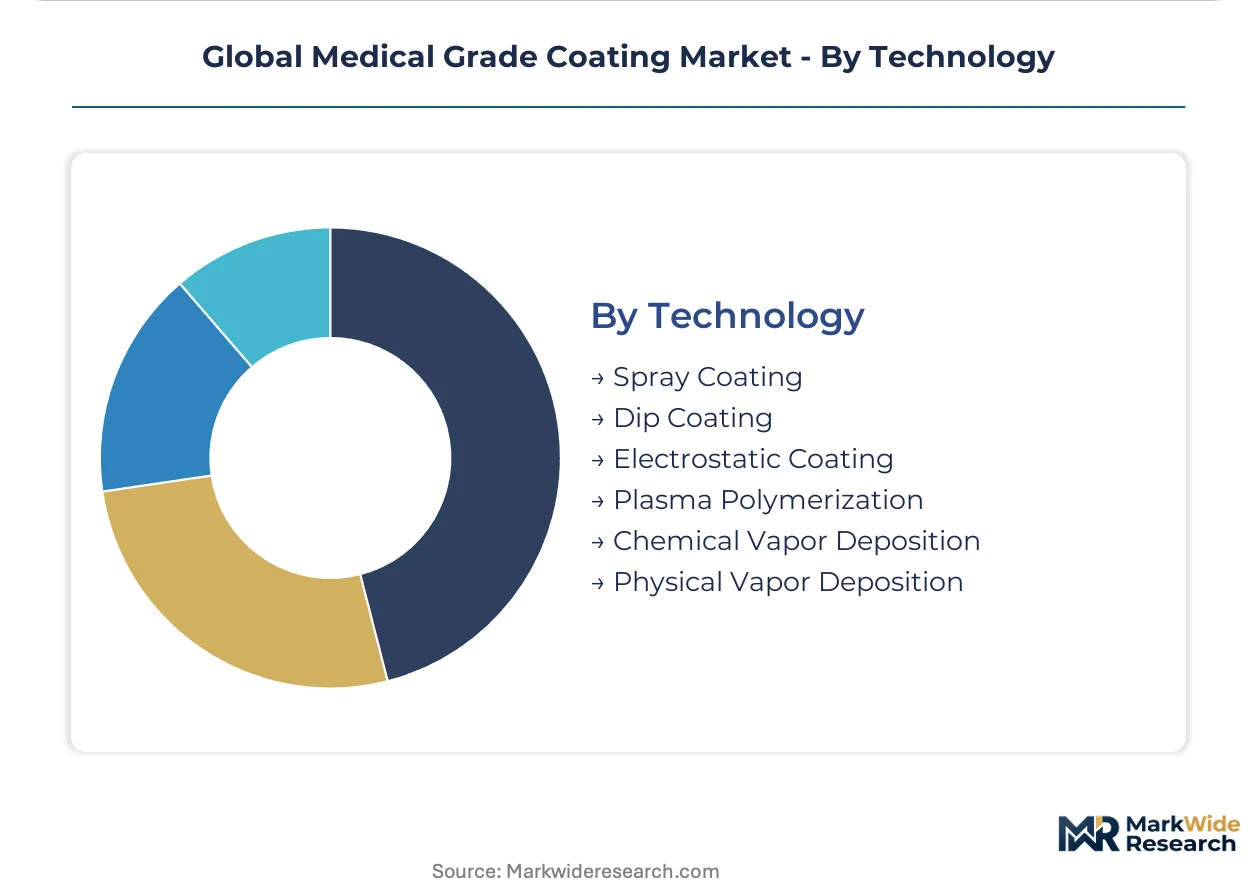
- Spray Coating:This widely used method applies coatings by atomizing liquid material onto a substrate, offering versatility for complex geometries and high-volume production.
- Dip Coating:Dip coating involves immersing a device into a liquid coating solution, providing uniform coverage for many medical devices, particularly those with intricate designs.
- Electrostatic Coating:Utilizing an electric field to attract coating particles to the substrate, this technology minimizes waste and achieves excellent adhesion, especially for conductive materials.
- Plasma Polymerization:This advanced technique uses plasma to deposit thin, highly uniform, and biocompatible films, crucial for sensitive implantable devices requiring precise surface modification.
- Chemical Vapor Deposition:CVD processes create high-purity, high-performance solid materials from gaseous precursors, offering exceptional control over coating properties and thickness for specialized applications.
- Physical Vapor Deposition:PVD techniques apply thin films by vaporizing a solid material in a vacuum and depositing it onto a substrate, enhancing hardness and wear resistance for surgical tools.
Technological evolution prioritizes advanced deposition methods for their precision and ability to handle complex device geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for medical grade coatings concentrates heavily in regions with established medical device manufacturing capabilities and stringent regulatory environments. Key markets in the United States, Germany, and Japan drive innovation and adoption of advanced coating solutions. Switzerland and China also contribute significantly to the market's global landscape, reflecting diverse healthcare needs and manufacturing strengths.
United States
The United States medical device market generates substantial demand for coatings on complex cardiovascular devices and orthopedic implants. Strict US FDA guidelines for biocompatibility and performance necessitate high-quality, well-validated coating formulations. Major medical technology clusters in Minneapolis, Boston, and the Silicon Valley region lead in developing next-generation coated devices.
Germany
Germany's robust medical device sector drives significant demand for specialized coatings, particularly for advanced surgical instruments and orthopedic applications. The EU Medical Device Regulation (MDR) intensifies the need for extensive data on coating integrity and long-term biocompatibility. Clusters in Bavaria and North Rhine-Westphalia are focal points for medical technology innovation and coating application services.
Japan
An aging population and high technological adoption rates in Japan fuel demand for coatings on diagnostic equipment and precision implants. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures rigorous approval processes for all medical device components, including surface treatments. Tokyo and Osaka serve as key centers for medical device R&D and advanced manufacturing capabilities.
China
China's rapidly expanding healthcare infrastructure and domestic medical device production capabilities create a growing market for medical grade coatings. The National Medical Products Administration (NMPA) sets increasingly stringent standards for imported and domestically manufactured medical devices. The Yangtze River Delta region is a prominent hub for medical device manufacturing and coating technology development.
Switzerland
Switzerland's focus on high-value medical implants and precision instruments generates demand for highly specialized and innovative coating solutions. Swissmedic regulations ensure that medical devices and their components meet stringent quality and safety requirements. The country's MedTech cluster, particularly around Zurich and Basel, is known for advanced material science and surface modification expertise.
Global Medical Grade Coating Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure. The competitive environment includes both large material science conglomerates and niche coating technology providers. Strategic archetypes range from broad portfolio suppliers to highly specialized application-focused firms. Competitive moves often involve strategic partnerships with device OEMs and targeted technology licensing.
Specialists in surface modification technologies include Surmodics Inc and Hydromer Inc, which exemplify a focus on specific application areas like vascular and ophthalmic devices or hydrophilic and antimicrobial coatings. Surmodics, for instance, concentrates on surface modification for complex devices, while Hydromer competes on advanced hydrophilic and antimicrobial solutions. DSM-Firmenich, a material science conglomerate, represents a broader approach, leveraging its extensive material science portfolio to offer diverse biocompatible coating solutions across many device categories. These firms collectively anchor the market's innovation curve, driving advancements in functionality and material performance to meet evolving regulatory and clinical demands.
| Leading Market Players |
|---|
| AST Products Inc |
| DSM-Firmenich |
| Surmodics Inc |
| Precision Coating Co. Inc |
| Harland Medical Systems Inc |
| Biocoat Inc |
| Covalon Technologies Ltd |
| Medicoat AG |
| Hydromer Inc |
| Others |
Cost & Logistics Intelligence
Vertical integration into specialized material science anchors both the supply position and pricing power for advanced medical grade coatings. This strategic control allows key players to command premium pricing for high-performance, compliant formulations while securing critical inputs.
Pricing Analysis
Pricing for medical grade coatings exhibits a clear split between high-volume, standard products and specialized, high-margin formulations. Contract-based long-term offtake dominates for custom formulations, ensuring stable supply for device OEMs. Price differentiation stems from biocompatibility certification, such as FDA or CE marking, and the customization level for specific device applications. Pricing pressure emerges from device OEMs seeking cost efficiencies for high-volume products. Hospitals represent the most price-sensitive buyers for commodity coatings, while research institutes prioritize performance over cost for novel applications.
Supply Chain Analysis
Single-source vulnerability sits with specialized suppliers of critical raw materials like specific hydrophilic polymers and pharmaceutical ingredients for drug-eluting coatings. Geographic supply concentration exists in Germany, the United States, and Japan, which are key medical device manufacturing hubs driving innovation. The supply chain relies on a limited number of specialized raw material producers. Regulatory restrictions, such as those from the EU MDR, represent a structural risk, demanding extensive material characterization. Distribution runs through direct sales channels to large device OEMs and specialized distributors for smaller manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical grade coating market presents a vertical-integration race, with players pursuing control over advanced material science and application services. This competition drives innovation and consolidates expertise across the value chain.
For Market Incumbents:
Acquire specialized coating IP portfolios, particularly those with proven multifunctionality or advanced deposition techniques. Market incumbents should consolidate niche technology providers to mitigate competitive threats from specialized entrants. Investment in advanced analytical testing capabilities ensures compliance with evolving regulatory standards like the EU MDR. This strategy counters margin pressure from commoditized segments by securing high-value intellectual property and enhancing regulatory defensibility.
For New Entrants and Emerging Players:
Channel partners like contract manufacturing organizations or specialized distributors offer effective market entry for novel coating technologies. New entrants should target underpenetrated applications, such as antimicrobial-lubricious coatings for catheters, or smart implant surfaces. Focusing on emerging manufacturing hubs like Brazil, aligning with ANVISA regulatory standards, provides a distinct go-to-market angle. This strategy allows smaller players to establish a foothold without directly confronting established market leaders.
For Investors and Strategic Acquirers:
Exit pathways concentrate in strategic acquisitions by large medical device OEMs seeking to internalize critical surface modification capabilities. Long-term viability remains strong, driven by increasing complexity of medical devices and tightening regulatory frameworks. Acquisition targets include firms with validated coating intellectual property, robust regulatory compliance records, and expertise in plasma polymerization. The signal to watch is an uptick in M&A activity for companies specializing in combination devices or advanced biocompatible materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership with Device OEM | Secures long-term contracts and co-development for next-generation implants. |
| Investment in Plasma Polymerization | Enables precise deposition for sensitive implantable devices and advanced sensors. |
| Pursue CE Marking for New Formulations | Expands market access to the stringent European medical device market. |
| Develop Antimicrobial-Lubricious Coatings | Addresses critical infection risks in catheters and other invasive devices. |
| Establish Local Application Services in Brazil | Captures demand in a growing medical device manufacturing hub with ANVISA standards. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with industry stakeholders. This approach combined insights from biomedical engineers, hospital purchasing committees, regulatory affairs specialists, and R&D directors. Secondary data sources included FDA filings, EU MDR guidance, NMPA announcements, and peer-reviewed scientific literature. Both bottom-up market sizing and top-down validation were employed to ensure robust data triangulation.
Granularity of the model extended to segmenting the market by product type, application, end user, technology, and key regional markets. The analytical framework integrated historical data with future projections across the analysis window. Compound annual growth rates were derived from detailed supply-demand dynamics and technological adoption trends. Key industry-specific forecast inputs included medical device approval rates and evolving regulatory compliance costs.
Caveats apply where unforeseen regulatory shifts or material supply disruptions could materially shift the outlook for medical grade coatings. Forecasts reflect documented assumptions regarding technological advancements and market dynamics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Allergic Rhinitis Treatment Device Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
Pipette Controllers Market
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Absorbable PGLA Surgical Sutures Market
Medical Devices
Gel Implants Market
Medical Devices
Temporary Pacing Leads Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Radiotherapy Patient Positioning Accessories Market
Medical Devices
Canada Insulin Delivery Devices Market
Medical Devices
Varicose Vein Treatment Devices Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Global Reflex Hammer Market
Medical Devices
Digital Phoropter Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Education Microscope Market