
 Non-Invasive Ventilators Market | 2026-2036
Non-Invasive Ventilators Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Ventilators Market Outlook
Modular platform designs that separate the ventilator base unit from interchangeable mask interfaces and data modules is repositioning how procurement teams evaluate total cost of ownership. ResMed Inc. leverages its cloud-connected ecosystem to sustain recurring revenue from software subscriptions and mask replenishment. Koninklijke Philips N.V. anchors its position through integrated sleep diagnostics-to-therapy workflows that span home and clinical environments. Fisher & Paykel Healthcare differentiates via humidification technology leadership that reduces airway complications during extended non-invasive ventilation.
Non-invasive ventilators are pressure- or volume-driven respiratory support devices that deliver conditioned gas through sealed nasal or orofacial interfaces without endotracheal intubation, typically operating at pressures between 4 and 25 cm H₂O with integrated humidification and leak-compensation algorithms to maintain therapeutic efficacy during patient movement and sleep. Their primary purpose is to augment spontaneous breathing in patients with acute or chronic respiratory insufficiency while avoiding the infectious and traumatic complications associated with invasive mechanical ventilation. Portable ventilators command premium positioning as homecare migration accelerates, though hospital-grade systems retain the deepest margin pools due to bundled service contracts and clinical training dependencies. Continuous Positive Airway Pressure technology dominates volume across sleep-disordered breathing applications, while Adaptive Support Ventilation captures the fastest expansion in acute care settings where automated weaning protocols reduce clinician workload.
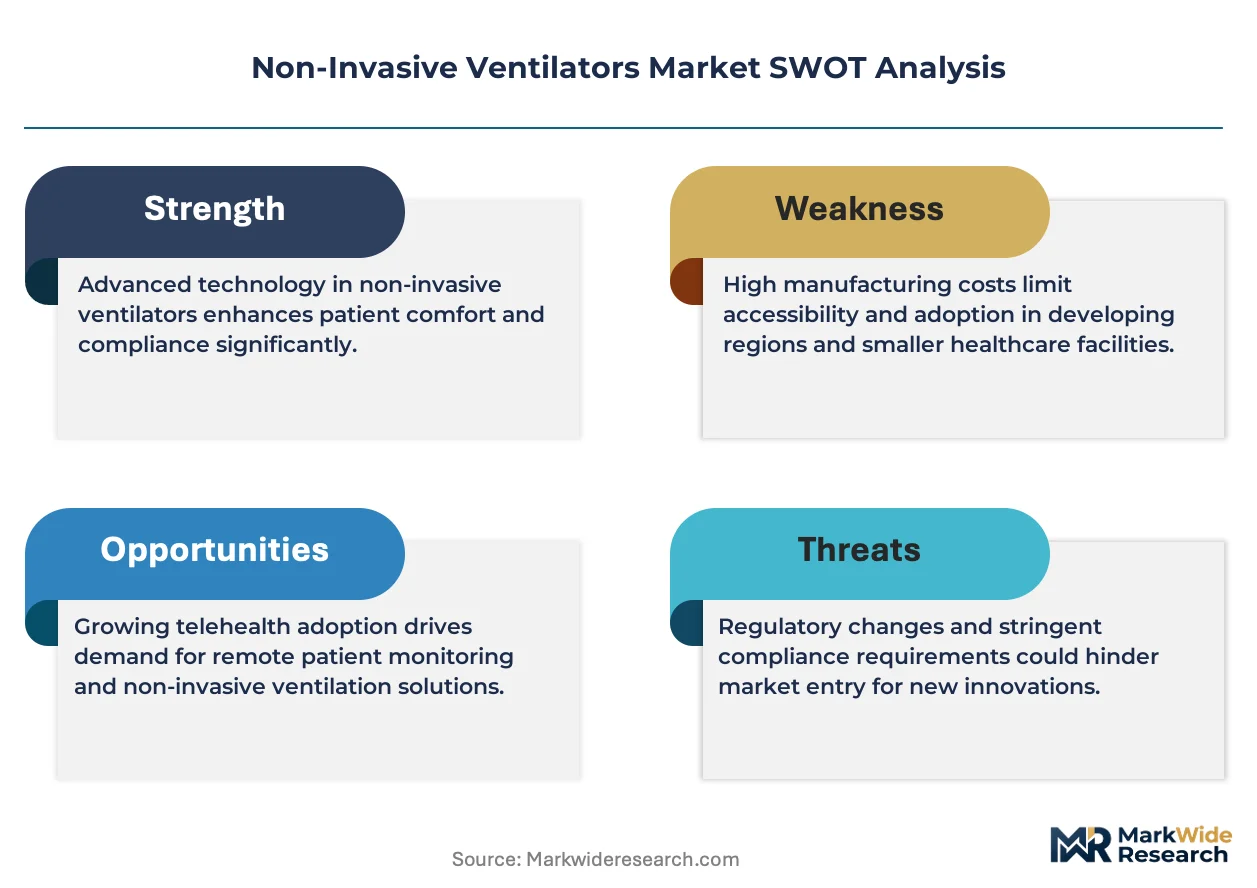
The FDA enforces 510(k) premarket notification pathways for new non-invasive ventilator systems, with particular scrutiny of software-controlled pressure algorithms and alarm reliability under IEC 60601-1-8 standards, while ISO 80601-2-80 governs basic safety and essential performance requirements that manufacturers must demonstrate before US commercialization. The Centers for Medicare & Medicaid Services reimbursement schedules for home respiratory therapy directly shape patient access and manufacturer pricing power across the American market. Stakeholders must monitor how the impending convergence of ventilator-software-as-medical-device regulations with cybersecurity mandates reshapes development timelines and post-market surveillance obligations.
Market Dynamics
Homecare migration is compressing hospital procurement cycles while forcing manufacturers to reengineer devices for untrained caregivers, creating a bifurcation between clinical-grade reliability and consumer-grade simplicity.
Growth Catalysts
- CMS reimbursement expansion:The Centers for Medicare & Medicaid Services extended coverage for home respiratory therapy, eliminating out-of-pocket barriers for COPD and neuromuscular patients in the United States.
- Cloud-connected remote monitoring:Continuous data streaming from ventilator-to-physician dashboards enables proactive intervention, reducing emergency readmissions and justifying premium device placement.
- Aging respiratory disease burden:Japan's super-aged demographic and Italy's elderly population concentration generate sustained demand for chronic ventilation management outside acute facilities.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundries dominate microcontroller production for pressure-sensing algorithms, exposing manufacturers to single-source vulnerability.
- FDA software validation requirements:IEC 62304 medical device software lifecycle compliance adds 14-18 months to development timelines for algorithm-controlled ventilation modes.
- High-flow nasal cannula substitution:Heated humidified high-flow oxygen systems capture mild-to-moderate respiratory failure cases previously routed to non-invasive ventilation.
Strategic Opportunities
- India's underpenetrated homecare sector:Less than 12% of eligible COPD patients in India access prescribed ventilation, presenting volume expansion potential as private insurance penetration rises.
- EU MDR cybersecurity mandates:The Medical Device Regulation's explicit software security requirements create first-mover advantage for manufacturers with pre-validated threat-mitigation architectures.
- Pediatric adaptive interfaces:Neonatal and pediatric mask systems remain technically underserved, with specialized sizing and pressure algorithms commanding 40-60% price premiums over adult equivalents.
Industry Challenges
- Clinical respiratory therapist shortage:The American Association for Respiratory Care reports 23% vacancy rates in sleep and ventilation clinics, constraining patient onboarding capacity.
- Legacy EMR integration complexity:Home ventilator data streams require HL7 FHIR mapping to hospital electronic medical records, demanding bespoke middleware development per health system.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Ventilators Market |
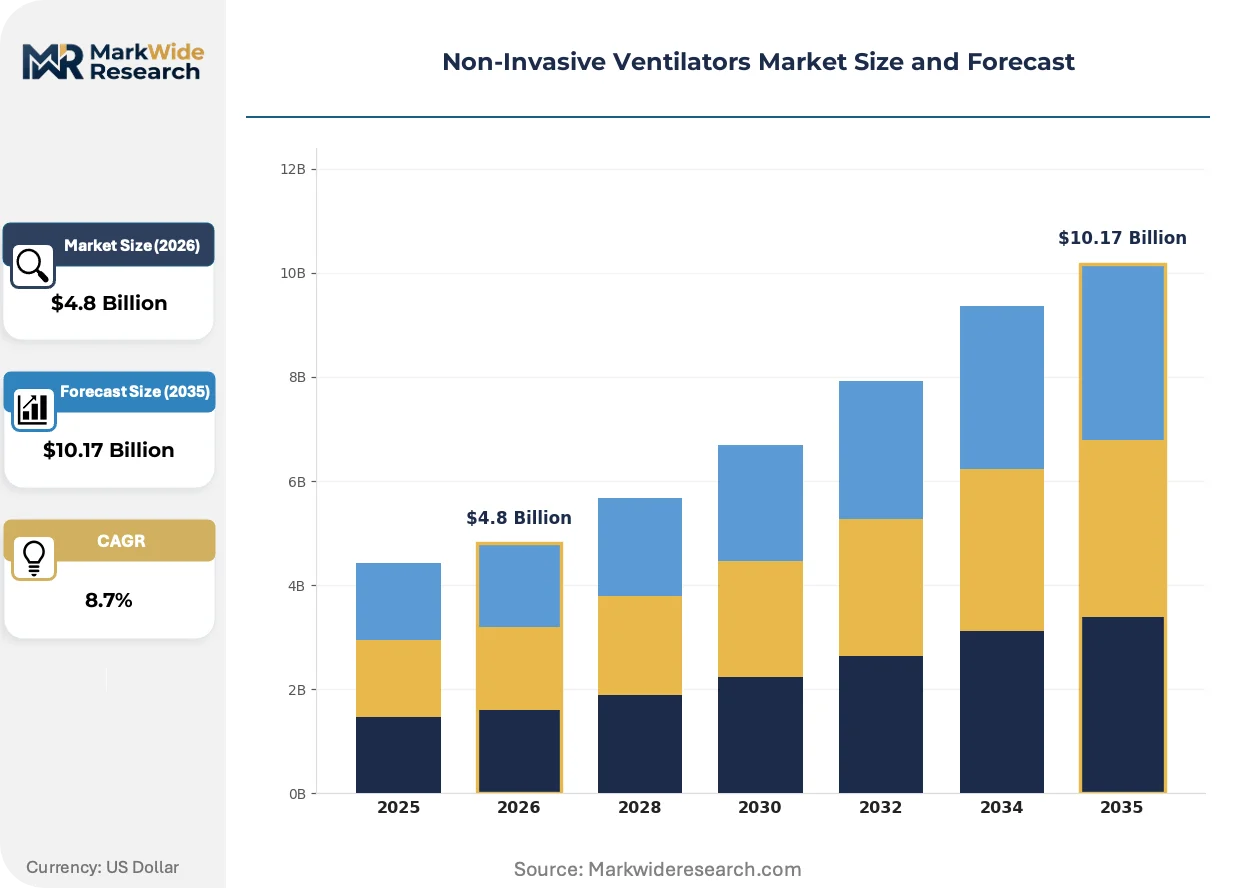
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ventilators, Full-Face Masks, Nasal Masks, Accessories End User: Homecare Settings, Hospitals, Emergency Services, Long-Term Care Facilities Technology: Bi-Level Positive Airway Pressure, Continuous Positive Airway Pressure, Volume Support Ventilation, Adaptive Support Ventilation Application: Chronic Obstructive Pulmonary Disease, Obesity Hypoventilation Syndrome, Neuromuscular Disorders, Acute Respiratory Distress |
| Companies Covered | ResMed Inc., Koninklijke Philips N.V., Fisher & Paykel Healthcare, Hamilton Medical, Teleflex Incorporated, GE Healthcare, Drägerwerk AG & Co. KGaA, Getinge, Heyer Medical AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Ventilators Market Strategic Shifts
Algorithmic automation and connectivity infrastructure are redefining where clinical expertise resides, shifting monitoring burden from bedside staff to distributed sensor networks and predictive analytics.
Adaptive servo-ventilation algorithms for central sleep apnea is decentralizing diagnostic authority from sleep laboratories to home-based devices with embedded polysomnography-equivalent signal processing. Cardiology practices and heart failure clinics in Germany and the United States are deploying these systems to capture Cheyne-Stokes respiration cases without formal sleep study referral. The technology is decentralizing revenue capture from hospital-based sleep centers to primary cardiology and pulmonology workflows.
The FDA's 2023 guidance on predetermined change control plans for machine-learning-enabled devices is accelerating submission pathways for adaptive pressure algorithms that learn patient breathing patterns. Manufacturers must now demonstrate locked algorithm architectures with bounded modification protocols before commercialization. Critical care ventilator segments face the steepest compliance burden, while homecare device developers gain competitive runway through simplified algorithm categories.
Hospital procurement committees are unbundling device acquisition from mandatory service contracts, forcing manufacturers to compete on standalone hardware pricing while monetizing connectivity and consumables separately. The Veterans Health Administration and NHS England have pioneered this disaggregation, with German hospital networks following. Home medical equipment distributors in the United States report compressed margins on base units, offset by recurring mask and filter replenishment revenue streams.
Non-Invasive Ventilators Market Segmentation
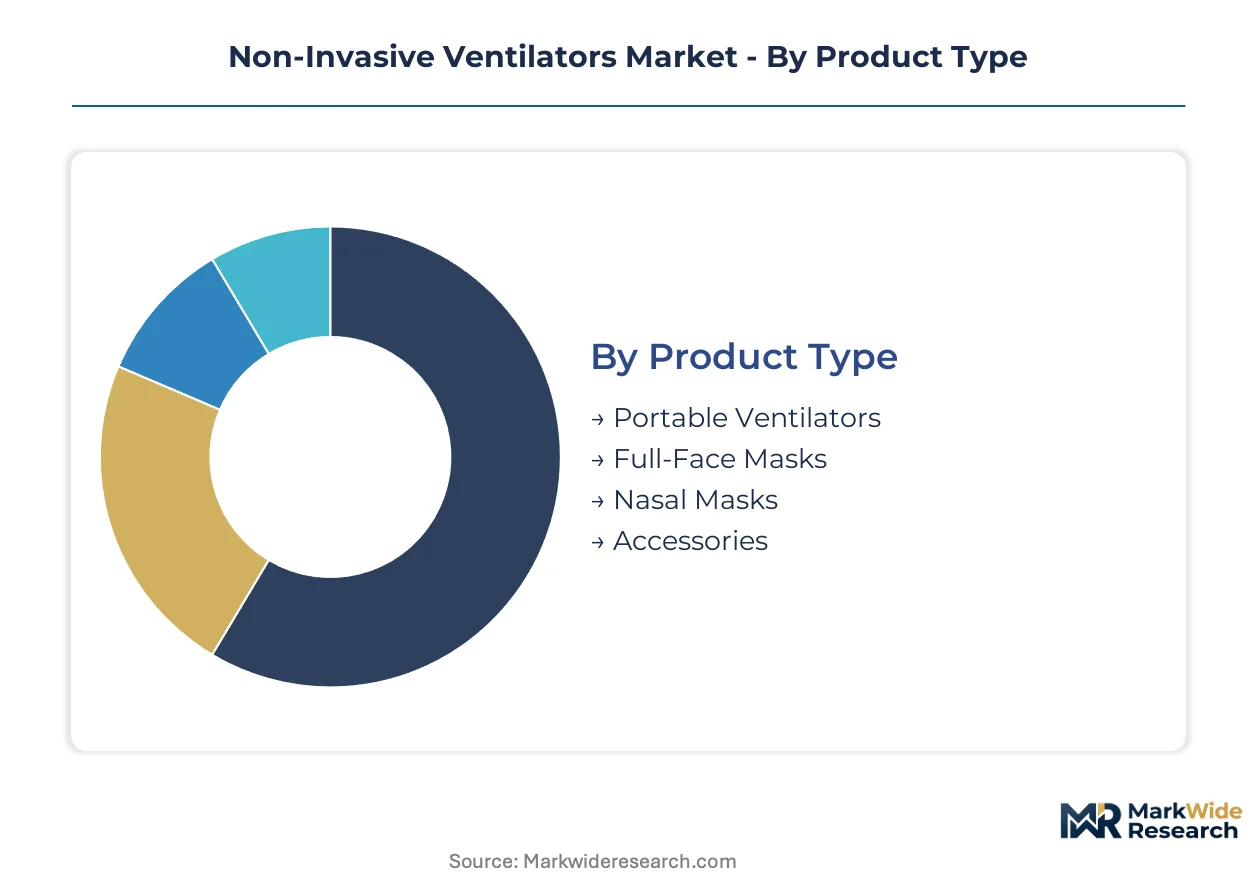
Non-invasive ventilator procurement varies sharply across clinical and home environments, with device specifications, connectivity requirements, and reimbursement pathways diverging by end-use setting. Manufacturers configure product portfolios around these segment boundaries to capture recurring revenue from consumables versus one-time hardware placements.
Product Type:
Portable ventilators function as standalone therapeutic systems, while masks and accessories embed into broader respiratory care workflows as replenishment-dependent components.
- Portable Ventilators:Battery-powered pressure or volume-driven units weighing under 5 kg, designed for ambulatory and overnight use with integrated humidification and leak compensation. Demand clusters in United States homecare settings where CMS reimbursement covers device rental and remote monitoring services for COPD and neuromuscular patients.
- Full-Face Masks:Orofacial silicone interfaces with dual-wall cushion technology and magnetic clip headgear, sealing across nasal and oral cavities for mouth-breathing patients. Hospital procurement in Japan and Germany favors these for acute respiratory failure cases requiring higher pressure settings that nasal alternatives cannot tolerate.
- Nasal Masks:Minimal-contact nasal cradle designs reducing facial pressure points for claustrophobia-prone users.
- Accessories:Replacement tubing, filters, and humidifier chambers generating recurring revenue streams.
Volume placements concentrate in Portable Ventilators; the faster expansion belongs to Accessories as mask replacement cycles compress from 90-day to 30-day intervals.
End User:
Cost tiers separate institutional purchasers with bundled service contracts from individual patients navigating insurance copayments and direct-to-consumer channels.
- Homecare Settings:Patient-managed environments with untrained caregivers operating cloud-connected devices under remote physician oversight. United States demand dominates as Medicare Advantage plans expand home respiratory therapy benefits and telehealth reimbursement.
- Hospitals:Acute care facilities requiring IEC 60601-1-8 compliant alarm systems and centralized fleet management for pressure algorithm reliability. German hospital networks and NHS England facilities drive procurement for automated weaning protocols in step-down units.
- Emergency Services:Pre-hospital transport applications prioritizing battery endurance and ruggedized construction.
- Long-Term Care Facilities:Skilled nursing environments with hybrid clinical oversight and limited on-site respiratory therapy staffing.
Revenue concentrates in Hospitals; Homecare Settings are climbing the fastest as pandemic-accelerated discharge protocols persist.
Technology:
Maturity gradients separate decades-established pressure modes from algorithmic innovations reshaping clinician workflow automation.
- Bi-Level Positive Airway Pressure:Dual-pressure systems delivering inspiratory and expiratory positive airway pressure with spontaneous/timed backup rates for central apnea events. Sleep clinics in the United States and cardiology practices in Germany deploy these for Cheyne-Stokes respiration in heart failure populations.
- Continuous Positive Airway Pressure:Fixed-pressure delivery for obstructive sleep apnea with auto-titrating variants adjusting pressure breath-by-breath. Volume leadership persists in United States retail channels and Australian pharmacy networks where direct-to-consumer pathways bypass formal sleep study requirements.
- Volume Support Ventilation:Pressure-limited volume-guaranteed mode for neuromuscular patients with variable respiratory drive.
- Adaptive Support Ventilation:Closed-loop control measuring respiratory mechanics and adjusting support levels automatically.
Installed base concentrates in Continuous Positive Airway Pressure; Adaptive Support Ventilation represents the fastest-growing trajectory as FDA predetermined change control plans accelerate algorithmic device submissions.
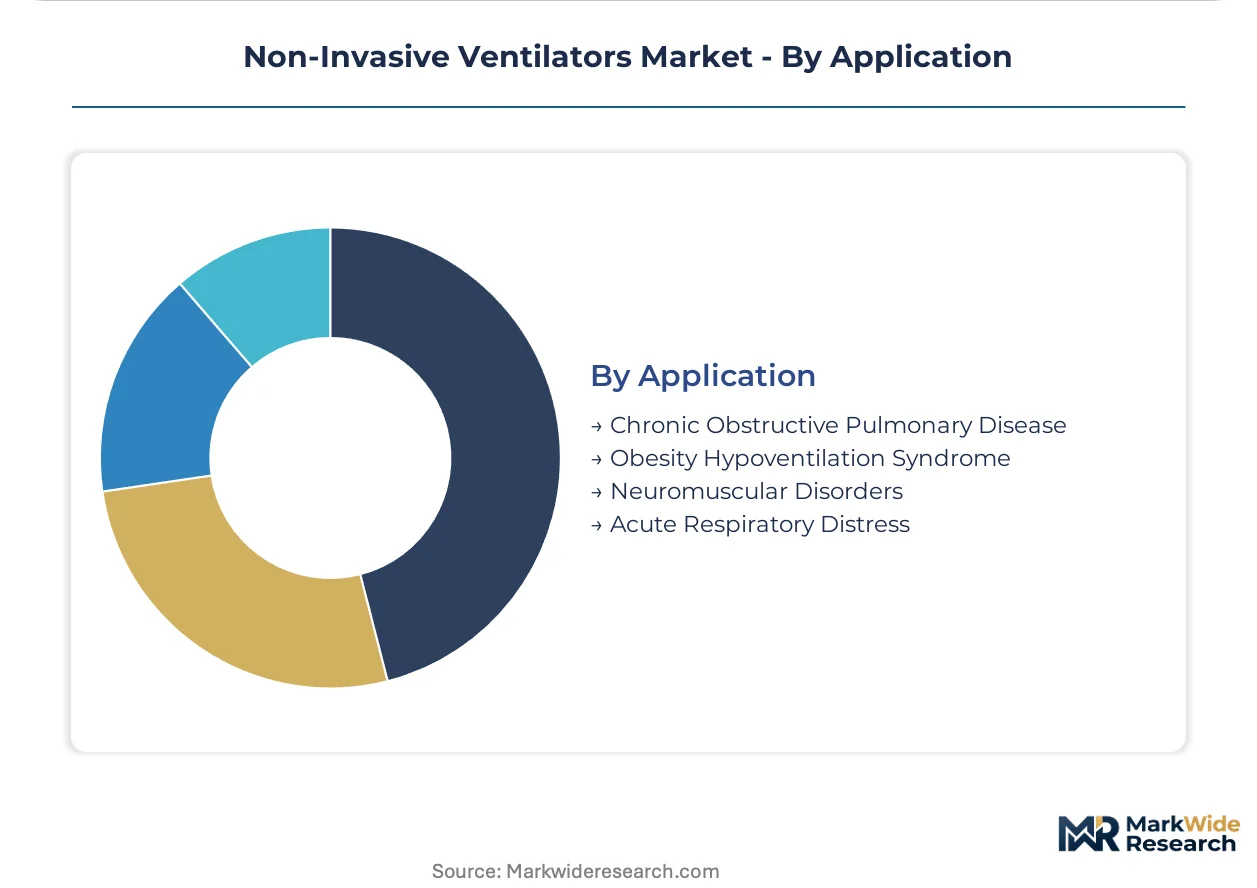
Application:
Geographic disease burden distributions determine where manufacturers concentrate clinical evidence generation and reimbursement lobbying resources.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation requiring nocturnal ventilatory support to reduce hypercapnia and hospitalization frequency. Italy and Spain exhibit concentrated demand as smoking prevalence and aging demographics expand eligible populations for home non-invasive ventilation.
- Obesity Hypoventilation Syndrome:Daytime hypercapnia and nocturnal hypoventilation in morbidly obese patients, often overlapping with obstructive sleep apnea. United States bariatric surgery centers and integrated health systems in the Gulf Cooperation Council states drive dual-diagnostic workflows combining sleep studies and arterial blood gas monitoring.
- Neuromuscular Disorders:Progressive respiratory muscle weakness in amyotrophic lateral sclerosis and muscular dystrophy requiring anticipatory ventilation initiation.
- Acute Respiratory Distress:Reversible lung injury cases in step-down units avoiding intubation through early non-invasive intervention.
Patient volumes concentrate in Chronic Obstructive Pulmonary Disease; the steepest expansion trajectory belongs to Obesity Hypoventilation Syndrome as metabolic disease prevalence climbs across Gulf and North American markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany, Switzerland, and the United States, while patient demand clusters in aging societies with established homecare reimbursement frameworks. This production-consumption divide shapes cross-border supply chain configurations and regulatory harmonization pressures.
United States
Medicare Advantage expansion and telehealth reimbursement codes drive home respiratory therapy volume. FDA 510(k) pathways for software-controlled pressure algorithms set compliance benchmarks that manufacturers must satisfy before commercialization. The Minneapolis-Saint Paul corridor hosts device engineering clusters serving both domestic and export markets.
Germany
Automated weaning protocols in step-down units and cardiology-integrated sleep diagnostics fuel hospital procurement. EU MDR cybersecurity mandates for connected medical devices accelerate validation timelines for cloud-enabled ventilation systems. The Baden-Württemberg region anchors precision manufacturing for pressure-sensing components and algorithm development.
Japan
Super-aged demographics and concentrated elderly populations generate chronic ventilation management demand outside acute facilities. PMDA alignment with IEC 60601-1-8 alarm reliability standards shapes product registration requirements. The Kanto region around Tokyo hosts respiratory device distribution networks serving both institutional and homecare channels.
India
Private insurance penetration rises in urban centers, expanding access for COPD patients previously excluded from prescribed ventilation. CDSCO medical device rules for software-as-medical-device classifications are tightening quality benchmarks for imported systems. Maharashtra and Karnataka clusters concentrate home medical equipment distribution infrastructure.
Italy
Smoking prevalence and aging demographics expand eligible populations for home non-invasive ventilation in COPD management. CE marking under EU MDR governs market access for pressure-support devices and mask interfaces. The Lombardy region anchors respiratory therapy service networks linking hospital discharge protocols with homecare providers.
Non-Invasive Ventilators Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The structure consolidates around respiratory-centric divisions of large health technology portfolios and dedicated ventilation manufacturers with deep clinical training dependencies. Three archetypes dominate: cloud-connected platform operators monetizing recurring consumables, integrated sleep-to-therapy workflow providers, and humidification technology specialists reducing airway complications. Competitive moves center on unbundling hardware from service contracts and expanding remote monitoring capabilities.
Among diversified health technology groups, Koninklijke Philips N.V. and GE Healthcare exemplify portfolio breadth spanning diagnostics through therapy. ResMed Inc. and Fisher & Paykel Healthcare occupy pure-play positions with specialized respiratory focus. Drägerwerk AG & Co. KGaA represents European engineering heritage in critical care ventilation. Hamilton Medical and Getinge sit within premium-tier acute care segments. These named entities anchor archetype positions without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| ResMed Inc. |
| Koninklijke Philips N.V. |
| Fisher & Paykel Healthcare |
| Hamilton Medical |
| Teleflex Incorporated |
| GE Healthcare |
| Drägerwerk AG & Co. KGaA |
| Getinge |
| Heyer Medical AG |
| Others |
Value Chain & Pricing Dynamics
Clinical-grade versus homecare-grade certification divergence manifests in three-tier pricing stratification across premium, standard, and economy levels, with FDA 510(k) clearance and IEC 60601-1-8 compliance separating hospital procurement budgets from direct-to-consumer retail channels and supply chains routing through distinct distribution architectures.
Pricing Analysis
Margin tightening in homecare ventilator tiers reflects unbundling of hardware from service contracts by Veterans Health Administration and NHS England procurement committees. Three-tier pricing stratification across premium, standard, and economy levels separates cloud-connected platform operators with recurring SaaS revenue from transactional mask-and-tubing suppliers. Cost-down pressure on base units accelerates because distributors report compressed hardware margins offset by 30-day mask replacement cycles. Hospital purchasing committees demonstrate lowest price sensitivity due to bundled clinical training dependencies, while direct-to-consumer channels face acute sensitivity to Medicare Advantage copayment structures.
Supply Chain Analysis
IEC 62304 software lifecycle certification and EU MDR cybersecurity validation gate component sourcing for algorithm-controlled pressure systems. Microcontroller production concentrates in Taiwan, precision pressure sensors in Germany and Switzerland, and silicone mask molding in Malaysia and Mexico. Semiconductor supply draws from Taiwan-based foundries with single-source vulnerability to geopolitical disruption. Distribution runs through home medical equipment distributors in the United States, hospital procurement consortia in Germany, and pharmacy retail networks in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's evolving software-as-medical-device guidance creates a cost-of-compliance moat that favors established players with validated quality management systems over capital-constrained entrants.
For Market Incumbents: Lock in recurring revenue streams by expanding cloud-connected remote monitoring subscriptions and compressing mask replacement cycles from 90-day to 30-day intervals. Deepen backward integration into pressure-sensing algorithm development to reduce Taiwan foundry dependency. Prioritize IEC 62304 pre-certification investment to accelerate FDA predetermined change control plan submissions ahead of machine-learning-enabled device guidance tightening. For New Entrants and Emerging Players: Home medical equipment distributors in India's underpenetrated urban centers present the most penetrable channel partner type for volume expansion. Target pediatric adaptive interfaces where specialized sizing commands 40-60% price premiums over adult equivalents. Pursue white-label manufacturing partnerships with Maharashtra-based distributors to bypass CDSCO import registration timelines while building clinical evidence for eventual branded entry. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-connected platform operators given CMS reimbursement expansion for telehealth-integrated respiratory therapy. Long-term viability favors manufacturers with locked algorithm architectures and bounded modification protocols already validated under FDA 2023 guidance. Watch for inflection where EU MDR cybersecurity mandates trigger consolidation among mid-tier players lacking pre-validated threat-mitigation architectures.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Predetermined Change Control Plan Submission | Accelerates market access for adaptive pressure algorithms under 2023 machine-learning device guidance. |
| Cloud-Connected Remote Monitoring Platform | Enables proactive physician intervention and justifies premium device placement through reduced emergency readmissions. |
| Pediatric Interface Development Program | Captures underserved neonatal and pediatric segments with specialized sizing commanding substantial price premiums. |
| EU MDR Cybersecurity Pre-Validation | Creates first-mover advantage as explicit software security requirements reshape competitive positioning in European markets. |
| Hospital System Partnership Integration | Secures step-down unit placement for automated weaning protocols in German and NHS England procurement cycles. |
Study Parameters
Multi-period observation of CMS reimbursement schedule revisions, FDA 510(k) clearance timelines, and EU MDR implementation milestones anchored the trend analysis, supplemented by interviews with respiratory therapists, hospital biomedical engineers, GPO contracts managers, and home medical equipment distributors. Secondary validation drew from FDA 510(k) database filings, CMS Medicare fee schedules, hospital procurement databases, and ISO/IEC standard publication records. Bottom-up patient-volume modeling triangulated against top-down manufacturer revenue segmentation.
Segment-weighting across product type, end-user setting, technology mode, and application disease state shaped volume and value outputs throughout the forecast period. CAGRs derived from logistic adoption curves fitted to reimbursement expansion trajectories and aging demographic projections. Industry-specific inputs incorporated COPD prevalence data from respiratory disease registries and sleep study diagnostic volumes from cardiology-integrated workflows.
Caveats apply where FDA software validation requirement tightening or Taiwan semiconductor supply disruption could materially shift the outlook. Forecasts reflect assumptions regarding CMS reimbursement stability and EU MDR enforcement consistency. A model refresh is warranted upon material change in Medicare Advantage home respiratory therapy benefit expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Artificial Disc Replacement Market
Medical Devices
Pharmaceutical Robots Market
Medical Devices
Vortex Mixer Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
Cervical Spacer Systems Market
Medical Devices
Computer Aided Trauma Fixators Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
Brachytherapy Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
Advanced Infusion Systems Market
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
Anesthesia Vaporizers Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
PET-CT Scanner Device Market
Medical Devices
Tissue Sectioning Market
Medical Devices
Ehealth Devices Market