
 Global Mobile Endoscopic Workstations Market | 2026-2036
Global Mobile Endoscopic Workstations Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Endoscopic Workstations Market Foresight
Multi-source procurement for imaging subsystems is hardening as OEMs seek to de-risk component supply. Aesculap, Inc. leverages its surgical instrument heritage to anchor premium workstation configurations across European teaching hospitals. Olympus dominates integrated display technologies through captive optical engineering, while Elmed Electronics & Medical Industry & Trade Inc. competes on modular design flexibility for mid-tier outpatient clinics.
Mobile endoscopic workstations are self-contained, wheeled platforms that integrate high-definition cameras, LED light sources, insufflation pumps, and video processors into a transportable unit for bedside or OR-based endoscopy. These systems typically support 1080p to 4K imaging pipelines with battery-backed operation lasting two to four hours for uninterrupted procedural workflows. Touchscreen interface configurations command margin premiums due to intuitive sterilization-friendly surfaces that reduce cross-contamination risks in gastrointestinal diagnostics. Wireless-enabled segments are capturing fastest growth as hospitals prioritize cable-free endoscope connectivity and centralized data archiving across minimally invasive surgery suites.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and commercial launch sequencing for workstation manufacturers. The FDA's cybersecurity premarket guidance and EU MDR post-market surveillance requirements are forcing redesign cycles for networked devices, elevating compliance costs for smaller vendors. Stakeholders must monitor evolving battery transport regulations and insulation monitoring standards as workstation mobility and electrical safety protocols tighten across jurisdictions.
Market Dynamics
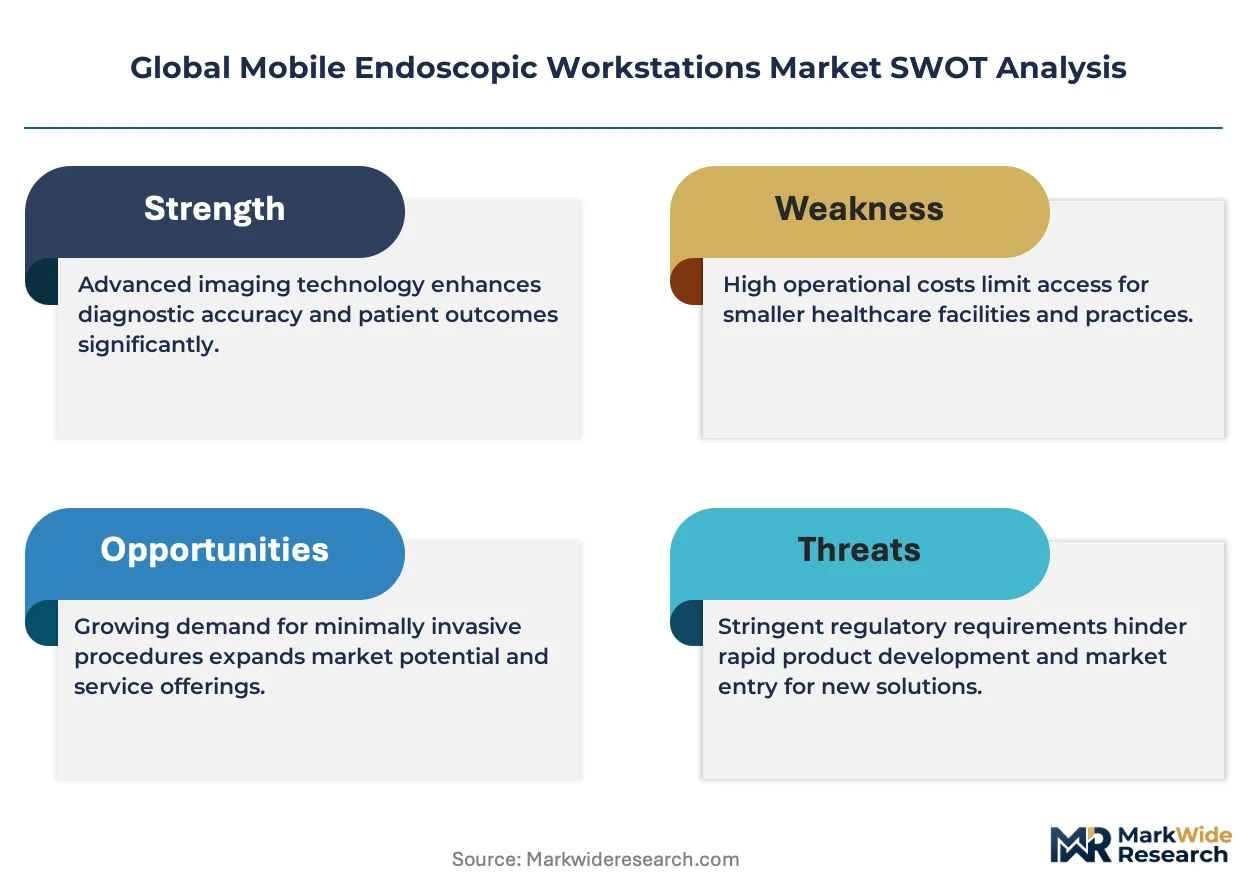
Wireless-enabled connectivity architectures are forcing manufacturers to redesign hardware-software interfaces around FDA cybersecurity premarket guidance, compressing development timelines while elevating compliance expenditures for networked mobile endoscopic platforms.
Growth Catalysts
- Outpatient procedural volume expansion:Ambulatory surgery centers across Germany and the United States are scaling procurement of transportable endoscopy units to support same-day discharge protocols in gastrointestinal diagnostics.
- EU MDR post-market surveillance mandates:Stricter vigilance requirements for Class IIa medical devices are accelerating replacement cycles for legacy workstations in European hospital networks.
- 4K imaging pipeline adoption:High-definition visualization standards are automating demand for integrated LED light sources and video processors capable of 2160p output resolution.
Market Restraints
- Lithium-ion battery transport regulations:IATA dangerous goods protocols and UN 38.3 testing requirements are constraining air freight logistics for battery-backed workstation configurations.
- Optical component supply concentration:Specialized CMOS sensors and fiber optic bundles depend on concentrated Asian manufacturing clusters, exposing OEMs to single-source vulnerabilities.
- Insulation monitoring standard fragmentation:Divergent electrical safety testing protocols across IEC 60601-1 national derivatives are inflating certification costs for multi-jurisdiction product launches.
Strategic Opportunities
- Mid-tier outpatient clinic penetration:Modular design configurations targeting India's diagnostic center expansion under CDSCO regulatory pathways offer volume scaling potential.
- Touchscreen interface premiumization:Sterilization-friendly capacitive surfaces command margin expansion as infection control protocols tighten in Japanese tertiary care facilities.
- Centralized data archiving convergence:Wireless-enabled segments are capturing hospital IT integration contracts by enabling DICOM-compliant image routing across minimally invasive surgery suites.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-functional expertise spanning optical engineering, embedded systems, and clinical workflow design remains concentrated in Germany and Japan.
- 510(k) clearance timeline compression:FDA cybersecurity documentation requirements are extending premarket review durations for wireless-enabled submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Endoscopic Workstations Market |
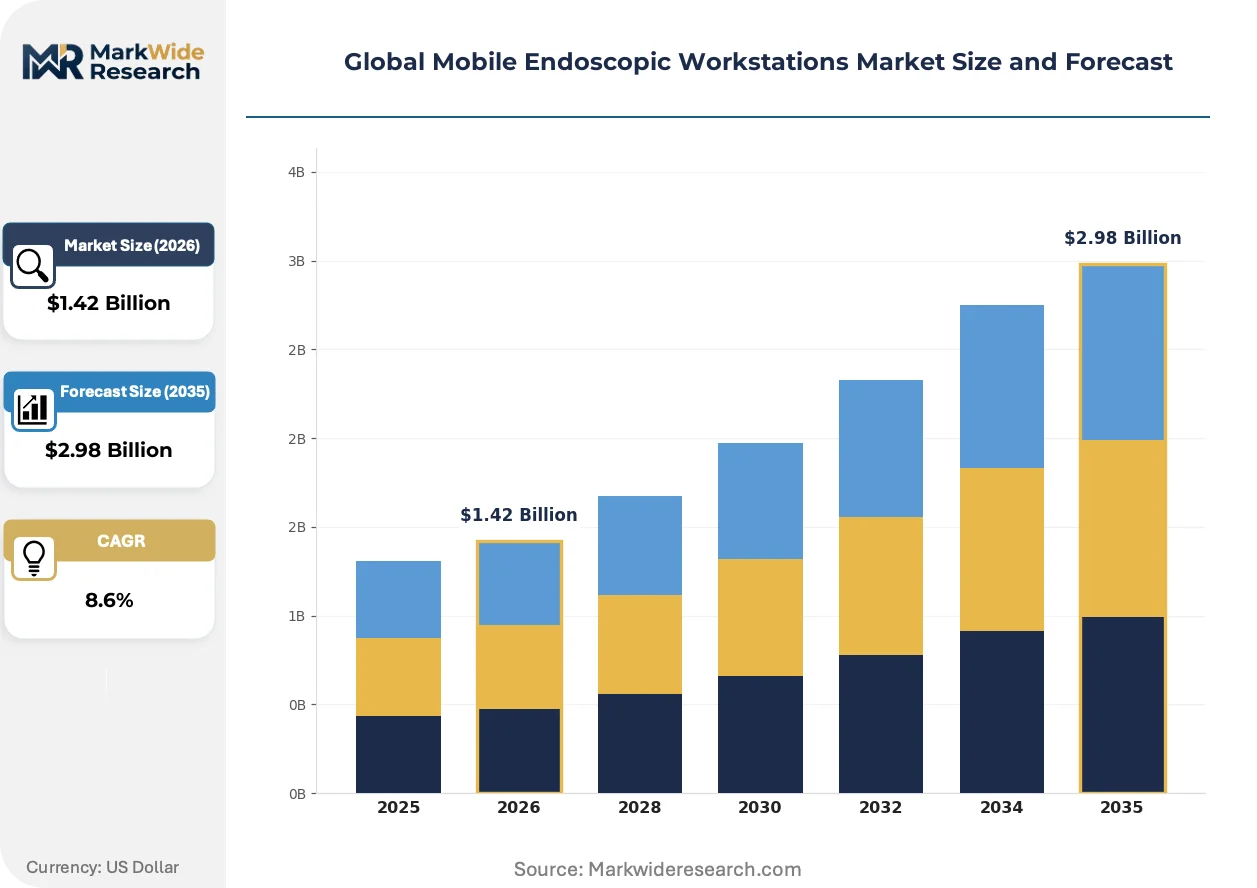
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push Button, Touchscreen Interface, Wireless Enabled, Modular Design, Integrated Display Technology: HD Imaging, 3D Visualization, LED Illumination, Battery Powered, Insulation Monitoring Application: Minimally Invasive Surgery, Otolaryngology Procedures, Gastrointestinal Diagnostics, Urology Interventions, Gynecological Assessments End User: Outpatient Clinics, Ambulatory Surgery Centers, Academic Medical Centers, Specialty Care Facilities, Teaching Hospitals |
| Companies Covered | ENDO-TECHNIK W. Griesat, Aesculap, Inc., ARC Group of Companies Inc., Elmed Electronics & Medical Industry & Trade Inc., Armstrong Medical Inc., Cura Carts, Ecleris S.R.L, Olympus, EMOS Technology Gmbh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Endoscopic Workstations Market Shifts & Advancements
Computational imaging and edge-processing architectures are redefining workstation capabilities, while regulatory frameworks harden around data security and electrical safety. These shifts are compressing product lifecycles and reshaping vendor competitive positions.
Machine-vision algorithms embedded in video processors are automating polyp detection and tissue characterization during real-time endoscopic procedures. Gastroenterology departments in academic medical centers are piloting these systems to reduce physician cognitive load. The technology is automating workflow standardization across high-volume screening programs by flagging suspicious regions for targeted biopsy.
EU MDR technical documentation requirements for software as a medical device are forcing workstation manufacturers to implement structured lifecycle processes. The regulation mandates clinical evidence for algorithm-assisted diagnostic functions previously cleared under less stringent pathways. German notified bodies are experiencing backlog delays that are sequencing commercial launches toward 2027-2028 windows.
Hospital procurement committees are consolidating vendor relationships around full-platform contracts that bundle hardware, software maintenance, and cybersecurity updates. Traditional equipment distributors face margin compression as manufacturers establish direct service organizations. This concentration is most visible in United States integrated delivery networks negotiating enterprise-wide workstation standardization.
Global Mobile Endoscopic Workstations Market Segmentation
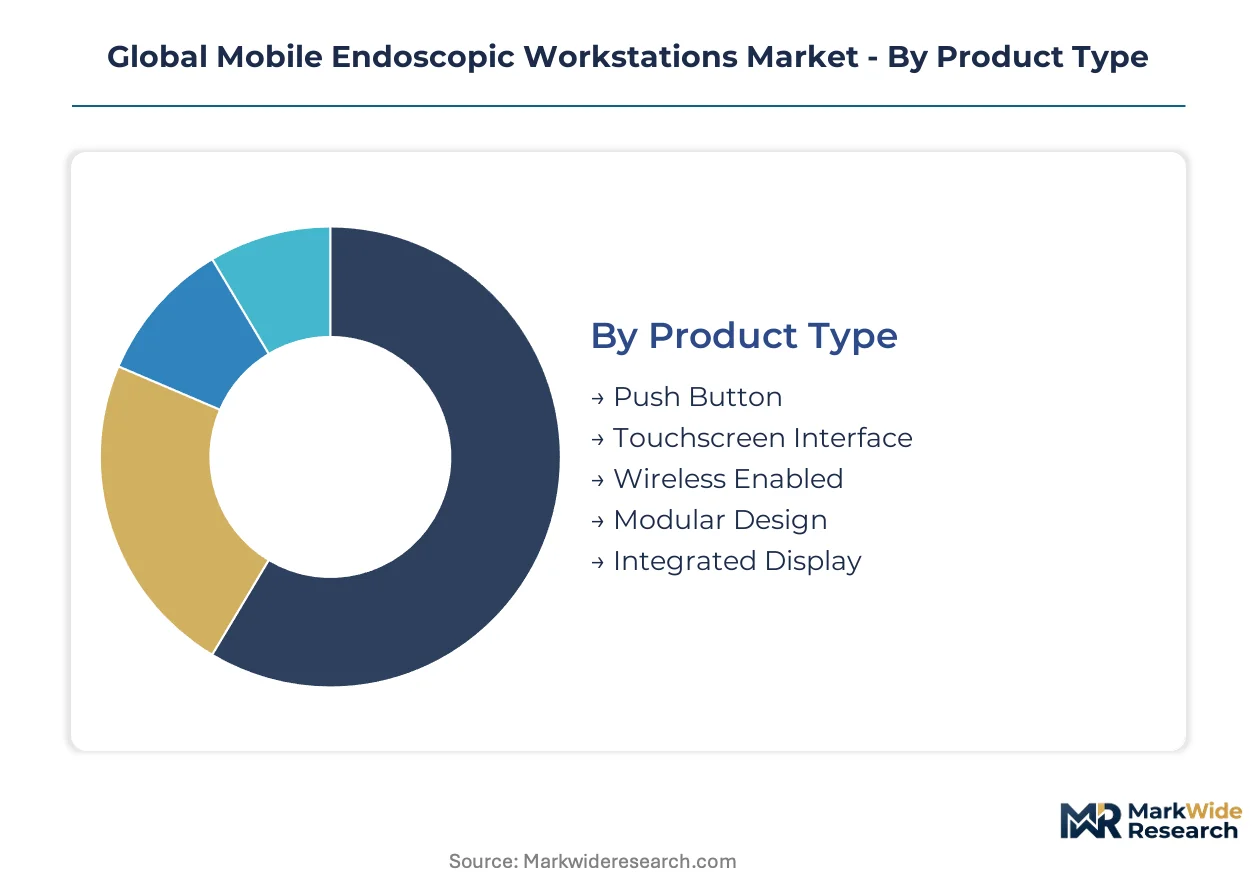
Mobile endoscopic workstations segment across hardware interfaces, imaging architectures, procedural applications, and care delivery settings. Each dimension shapes procurement specifications, regulatory pathways, and vendor competitive positioning differently.
Product Type:
Procurement committees differentiate configurations primarily by sterilization protocols and IT integration depth.
- Touchscreen Interface:Capacitive glass surfaces withstand repeated disinfection cycles without degradation. German tertiary hospitals prioritize these units to reduce cross-contamination risks in high-throughput endoscopy suites.
- Wireless Enabled:Cable-free endoscope connectivity eliminates trip hazards and enables centralized image archiving. United States integrated delivery networks are standardizing on these platforms to streamline DICOM routing across minimally invasive surgery departments.
- Push Button:Physical control interfaces dominate budget-constrained installations where durability trumps interface sophistication.
- Modular Design:Component-swappable architectures allow Indian outpatient clinics to upgrade imaging pipelines incrementally rather than replacing entire platforms.
- Integrated Display:Captive monitor configurations reduce setup complexity for Japanese academic medical centers running multi-specialty procedural schedules.
Touchscreen Interface leads volumes today; Wireless Enabled is gaining share fastest.
Technology:
Imaging resolution and power autonomy separate premium configurations from standard offerings.
- HD Imaging:1080p video processors remain the baseline specification for mid-tier outpatient clinics balancing visualization quality against capital expenditure constraints.
- LED Illumination:Solid-state light sources deliver consistent color temperature across extended procedural durations. Ambulatory surgery centers in the United States specify these modules to reduce lamp replacement downtime.
- 3D Visualization:Stereoscopic imaging pipelines support depth perception in complex laparoscopic interventions. Academic medical centers in Germany pilot these systems for advanced minimally invasive surgery training curricula.
- Battery Powered:Two-to-four-hour autonomous operation enables bedside endoscopy outside fixed procedure rooms.
- Insulation Monitoring:Real-time electrical safety systems comply with IEC 60601-1 derivatives for patient leakage current protection.
HD Imaging dominates installed base; LED Illumination is climbing the fastest as replacement cycles accelerate.
Application:
Procedure complexity and reimbursement rates drive workstation specification intensity.
- Gastrointestinal Diagnostics:Colonoscopy and upper endoscopy workflows demand rapid image capture with polyp detection support. Screening program expansions in Japan concentrate procurement for high-definition platforms with automated flagging capabilities.
- Minimally Invasive Surgery:Laparoscopic and thoracoscopic procedures require synchronized insufflation, irrigation, and imaging control. German hospital networks prioritize integrated workstations for operating theater standardization.
- Otolaryngology Procedures:Compact form factors with flexible endoscope compatibility serve ENT outpatient suites.
- Urology Interventions:Cystoscopy and ureteroscopy applications specify irrigation pump integration and enhanced saline resistance.
- Gynecological Assessments:Hysteroscopy workflows drive demand for small-diameter endoscope compatibility and precise insufflation control.
Gastrointestinal Diagnostics anchors current volumes; Minimally Invasive Surgery shows steepest expansion trajectory.
End User:
Capital availability and procedure throughput determine configuration tier selection.
- Ambulatory Surgery Centers:Same-day discharge protocols demand reliable, rapid-setup platforms with minimal maintenance requirements. United States ASC networks are consolidating vendor relationships around full-service contracts bundling hardware and cybersecurity updates.
- Academic Medical Centers:Research and training missions drive procurement of 4K-capable systems with algorithm-assisted diagnostic functions. EU MDR software-as-medical-device requirements are sequencing these purchases through notified body backlogs.
- Outpatient Clinics:Volume-constrained settings favor modular configurations enabling incremental capability expansion.
- Specialty Care Facilities:Single-specialty focus permits optimized endoscope inventories and procedure-specific workstation tuning.
- Teaching Hospitals:Resident training requirements prioritize intuitive interfaces and standardized workflow documentation.
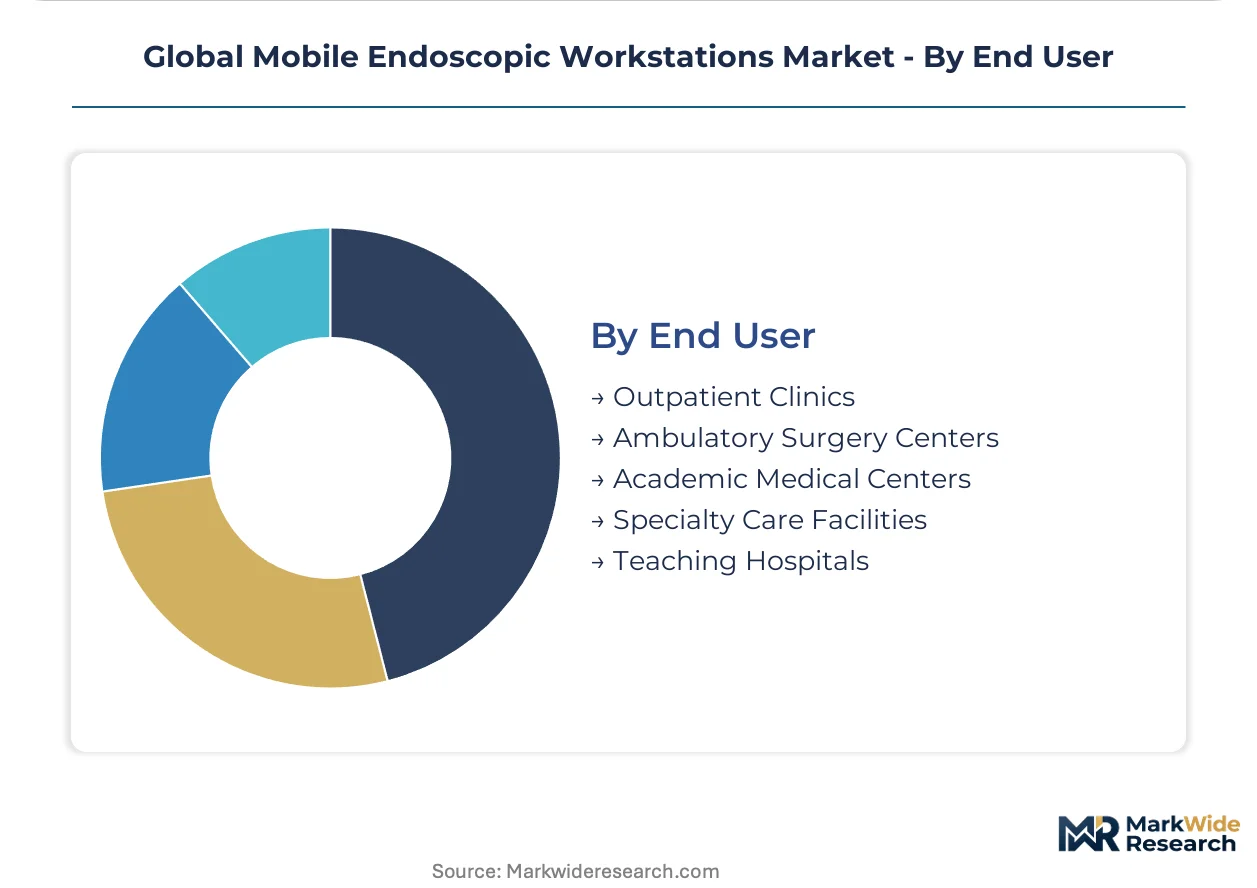
Ambulatory Surgery Centers lead procurement volumes today; Academic Medical Centers are expanding fastest as research funding flows into computational imaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hospital modernization programs concentrate procurement authority for flexible endoscopy infrastructure in Baden-Württemberg and Bavaria, where integrated delivery networks standardize on mobile platforms with EU MDR certification.
United States
Ambulatory surgery centers in Texas and Florida are scaling transportable endoscopy units to support same-day discharge protocols under CMS reimbursement frameworks. FDA cybersecurity premarket guidance is compressing 510(k) clearance timelines for wireless-enabled submissions. Boston's academic medical corridor pilots algorithm-assisted diagnostic workstations with NIH research funding.
Germany
Hospital networks in North Rhine-Westphalia prioritize 4K-capable systems with LED illumination modules under statutory health insurance procurement tenders. EU MDR post-market surveillance mandates accelerate replacement cycles for legacy workstations. Tübingen's medical technology cluster anchors optical engineering talent for integrated display manufacturing.
Japan
Metropolitan Tokyo hospitals specify sterilization-friendly touchscreen interfaces to reduce cross-contamination risks in high-throughput gastrointestinal screening programs. PMDA software-as-medical-device pathways regulate algorithm-assisted polyp detection functions. Osaka's precision manufacturing base supplies specialized CMOS sensors for video processor integration.
India
Diagnostic center expansion in Maharashtra and Karnataka drives demand for modular workstation configurations under CDSCO regulatory pathways. Government health infrastructure schemes prioritize mid-tier capital equipment for tier-2 city penetration. Hyderabad's medical device corridor assembles component-swappable architectures for incremental capability upgrades.
China
Provincial hospital procurement in Jiangsu and Guangdong concentrates on battery-powered configurations for bedside endoscopy outside fixed procedure rooms. NMPA medical device registration requirements shape commercial launch sequencing for domestic and imported platforms. Shenzhen's electronics manufacturing ecosystem supplies LED light source modules and video processors.
Global Mobile Endoscopic Workstations Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular configurations for cost-sensitive outpatient settings. The vendor base stratifies across three capability tiers: integrated platform specialists, component subsystem suppliers, and regional assembly operations. Two strategic archetypes dominate: optical engineering heritage firms leveraging captive display technologies, and modular design specialists targeting mid-tier clinic expansion. Competitive dynamics center on direct service organization establishment and cybersecurity update bundling within full-platform contracts.
Among Germany-based fabricators, ENDO-TECHNIK W. Griesat and EMOS Technology Gmbh exemplify precision engineering archetypes anchored in European teaching hospital supply relationships. Aesculap, Inc. represents surgical instrument heritage extension into premium workstation configurations. Elmed Electronics & Medical Industry & Trade Inc. occupies a position within the modular design tier targeting mid-market outpatient penetration. Olympus anchors the integrated display technology segment through optical engineering capabilities. These named entities illustrate geographic and capability clustering rather than exhaustive market coverage.
| Leading Market Players |
|---|
| ENDO-TECHNIK W. Griesat |
| Aesculap, Inc. |
| ARC Group of Companies Inc. |
| Elmed Electronics & Medical Industry & Trade Inc. |
| Armstrong Medical Inc. |
| Cura Carts |
| Ecleris S.R.L |
| Olympus |
| EMOS Technology Gmbh |
| Others |
Supply & Pricing Matrix
EU MDR post-market surveillance mandates and IEC 60601-1 electrical safety certifications gate qualified supply access, restricting premium-tier pricing to manufacturers with notified body backing and insulation monitoring capabilities. This regulatory filtering concentrates pricing power among optical engineering heritage firms while compressing margins for modular design competitors serving mid-tier outpatient clinics.
Pricing Analysis
Input-cost pass-through from specialized CMOS sensors and fiber optic bundles anchors workstation pricing, with LED illumination modules and battery subsystems driving tier differentiation. Price differentiation hinges on EU MDR certification grade and touchscreen interface sterilization ratings. Cost compression in standard-tier configurations intensifies as Indian diagnostic centers scale modular procurement. Ambulatory surgery centers in the United States exhibit lowest price sensitivity due to bundled cybersecurity update contracts, while tier-2 city clinics in Maharashtra prioritize capital expenditure minimization.
Supply Chain Analysis
Biomedical engineering talent scarcity in Germany and Japan constrains optical subsystem production scaling, forcing OEMs to anchor precision manufacturing in Baden-Württemberg and Tokyo metropolitan clusters. Specialized CMOS sensors draw from Osaka's precision manufacturing base, while LED light source modules feed from Shenzhen's electronics ecosystem. Single-source vulnerability in fiber optic bundle supply exposes manufacturers to logistics chokepoint risks. Distribution runs through direct service organizations established by integrated platform specialists, bypassing traditional equipment distributors facing margin compression.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Mobile Endoscopic Workstations Market reads as a late-cycle quality story, with 4K imaging pipeline adoption and algorithm-assisted diagnostic functions shifting procurement specifications toward premium integrated configurations.
For Market Incumbents: Acquire computational imaging software assets to anchor algorithm-assisted diagnostic capabilities against emerging modular design entrants. Consolidate optical engineering talent in Tübingen and Osaka through targeted hiring programs. Deepen backward integration into CMOS sensor supply to mitigate single-source exposure from Asian manufacturing clusters. For New Entrants and Emerging Players: Regional assembly partnerships with Hyderabad's medical device corridor unlock CDSCO pathway access for India's diagnostic center expansion. Target Maharashtra and Karnataka outpatient clinics with component-swappable architectures enabling incremental 1080p-to-4K upgrades. Pursue government health infrastructure scheme eligibility to secure tier-2 city procurement tenders. For Investors and Strategic Acquirers: Roll-up economics work for modular design specialists because EU MDR compliance costs are sequencing smaller vendors toward exit windows amid notified body backlogs. Five-to-ten year viability favors firms with captive optical engineering and direct service organization scale. Watch FDA 510(k) clearance timeline compression for wireless-enabled submissions as inflection indicator for cybersecurity compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Notified body backing unlocks German hospital procurement tenders and accelerates replacement cycle capture. |
| Hospital System Partnership | United States integrated delivery networks consolidate vendor relationships around full-platform cybersecurity bundles. |
| Software Companion Development | Machine-vision algorithms for polyp detection command premium positioning in Japanese screening programs. |
| Backward Integration into Optical Components | Captive CMOS sensor supply mitigates single-source vulnerability from concentrated Asian manufacturing. |
| Geographic Manufacturing Footprint | Hyderabad assembly operations reduce logistics costs for CDSCO-regulated Indian diagnostic center expansion. |
Research Methodology
Multiple input streams — primary interviews with biomedical engineers and hospital purchasing committees, secondary validation against FDA 510(k) filings and EU MDR technical documentation — were reconciled through bottom-up and top-down triangulation. Clinicians, GPO contracts managers, and ambulatory surgery center administrators provided procedural volume and specification intensity perspectives. Secondary sources included hospital procurement databases, CMS reimbursement frameworks, and notified body certification records.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product interface type, imaging resolution tier, procedural application, and end-user capital availability. CAGRs were derived from installed base replacement cycle modeling and outpatient volume expansion trajectories. Forecast inputs incorporated EU MDR post-market surveillance mandate compliance costs and FDA cybersecurity premarket guidance implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IATA lithium-ion battery transport regulation tightening and optical component supply concentration shifts. Assumptions reflect current regulatory trajectories and procurement consolidation patterns. Material deviation in notified body backlog resolution or CMOS sensor supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopic Balloon Dilator Market
Endoscopy
Japan Endoscopy Devices Market
Endoscopy
Single Use Bronchoscopes Market
Endoscopy
Hysteroscopy Procedures Market
Endoscopy
High-Resolution Anoscopy Market
Endoscopy
Non-Invasive Colon Cancer Screening Market
Endoscopy
Saudi Arabia Endoscopy Devices Market
Endoscopy
Bronchoscopy Market
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
Endorectal Balloon Market
Endoscopy
Canada Endoscopy Devices Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
Europe Disposable Endoscopes Market
Endoscopy
Global Bronchoscopes Market
Endoscopy
Dermatology Endoscopy Devices Market