
 Oxygen Delivery Units Market | 2026-2036
Oxygen Delivery Units Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Delivery Units Market Analytics
ISO 80601-2-69 and FDA 510(k) clearance cycles is bifurcating the competitive landscape into qualified incumbents and marginal entrants. Koninklijke Philips N.V. leverages its vertical integration across concentrator manufacturing and sleep therapy platforms to sustain brand loyalty among home care distributors. Inogen, Inc. specializes in portable oxygen concentrator miniaturization, while Chart Industries, Inc. anchors the liquid oxygen systems segment through cryogenic engineering depth.
Oxygen delivery units encompass devices that generate, store, or administer supplemental oxygen through nasal cannulas, masks, or tracheal interfaces at flow rates typically ranging from 0.5 to 15 liters per minute. These systems employ pressure swing adsorption, cryogenic distillation, or membrane separation to extract oxygen from ambient air or stored liquid reserves, serving patients with chronic obstructive pulmonary disease, hypoxemia, and acute respiratory failure. Portable concentrators command the fastest expansion trajectory as ambulatory patients demand mobility-optimized devices weighing under five pounds. Fixed systems retain stable revenue pools within hospital infrastructure, while membrane separation technology lags in clinical penetration due to lower purity output relative to pressure swing adsorption alternatives.
FDA 510(k) premarket notification requirements and ISO 13485 quality management standards govern device commercialization in the United States, compelling manufacturers to maintain rigorous design controls and post-market surveillance. The European Medical Device Regulation imposes additional conformity assessment burdens through notified body oversight of Class IIa and IIb oxygen delivery systems. Stakeholders must monitor evolving reimbursement thresholds from the Centers for Medicare & Medicaid Services, as competitive bidding outcomes directly determine addressable revenue for home oxygen suppliers.
Market Dynamics
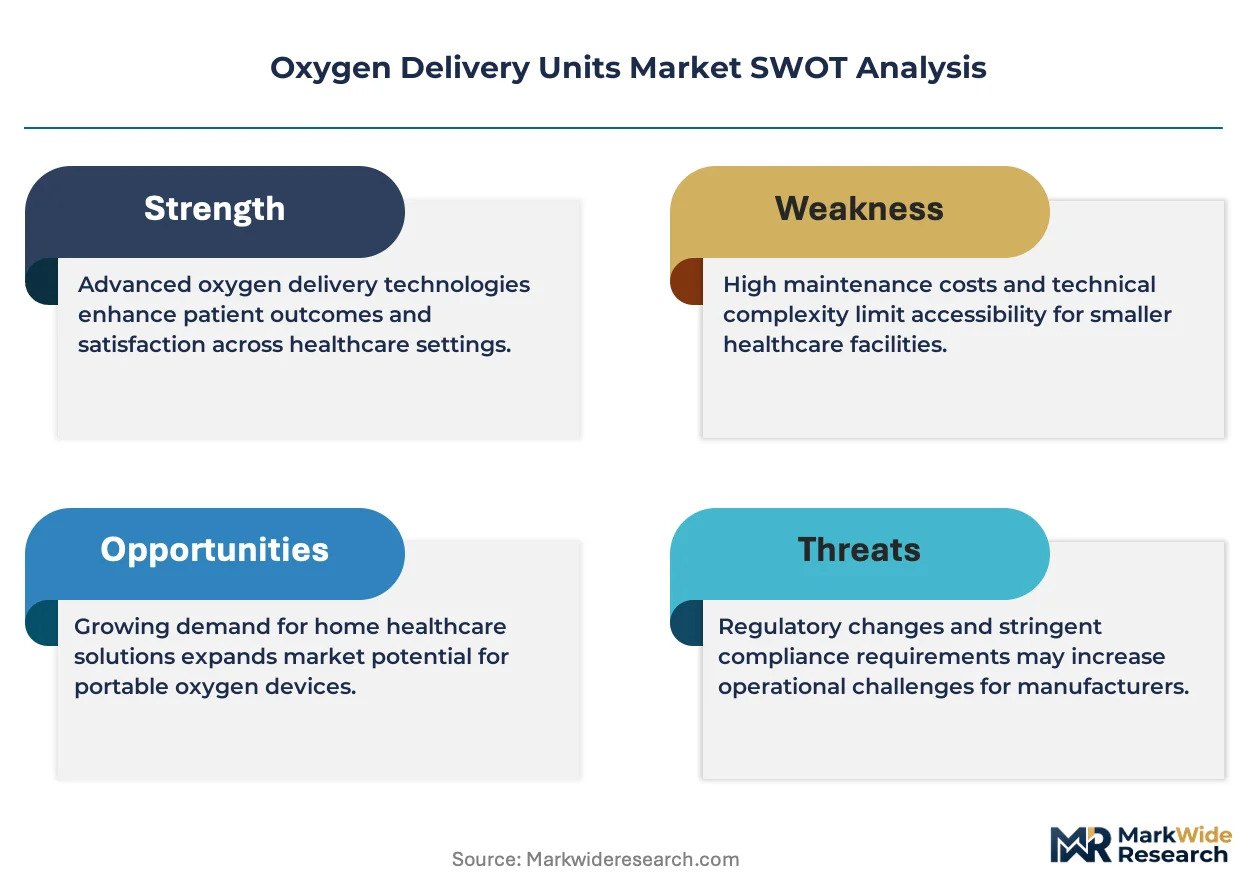
Post-acute care decentralization is compressing hospital oxygen infrastructure while expanding home-based device deployment, forcing manufacturers to rebalance R&D portfolios toward portable systems and remote monitoring integration.
Growth Catalysts
- Medicare competitive bidding:CMS reimbursement adjustments sustain home oxygen therapy access for COPD patients across the United States, stabilizing supplier revenue pools.
- Pressure swing adsorption miniaturization:Advances in molecular sieve engineering enable sub-five-pound portable concentrators without purity degradation.
- Aging demographics in Japan:METI guidelines for home medical equipment accelerate concentrator adoption among elderly hypoxemia patients.
Market Restraints
- Cryogenic liquid oxygen distribution:Cold-chain logistics concentration in North American bulk suppliers limits geographic expansion of stationary reservoir systems.
- ISO 80601-2-69 compliance costs:Electromagnetic compatibility and alarm system testing extend product development cycles by 8-14 months for new entrants.
- Membrane separation purity ceiling:40% oxygen concentration output fails clinical thresholds for severe respiratory failure, constraining application scope.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import dependence for concentrator components and compress landed costs.
- Telehealth-integrated pulse oximetry:Remote SpO2 monitoring convergence with concentrator telemetry enables predictive maintenance and adherence tracking.
- Subscription-based equipment provision:Direct-to-patient rental models bypass traditional durable medical equipment distributors in fragmented European markets.
Industry Challenges
- FDA 510(k) predicate device matching:Substantial equivalence determinations for novel flow-delivery algorithms require extensive clinical validation documentation.
- Biomedical technician certification gaps:Shortage of ISO 13485-audited service personnel delays field repair turnaround times for home care providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Delivery Units Market |
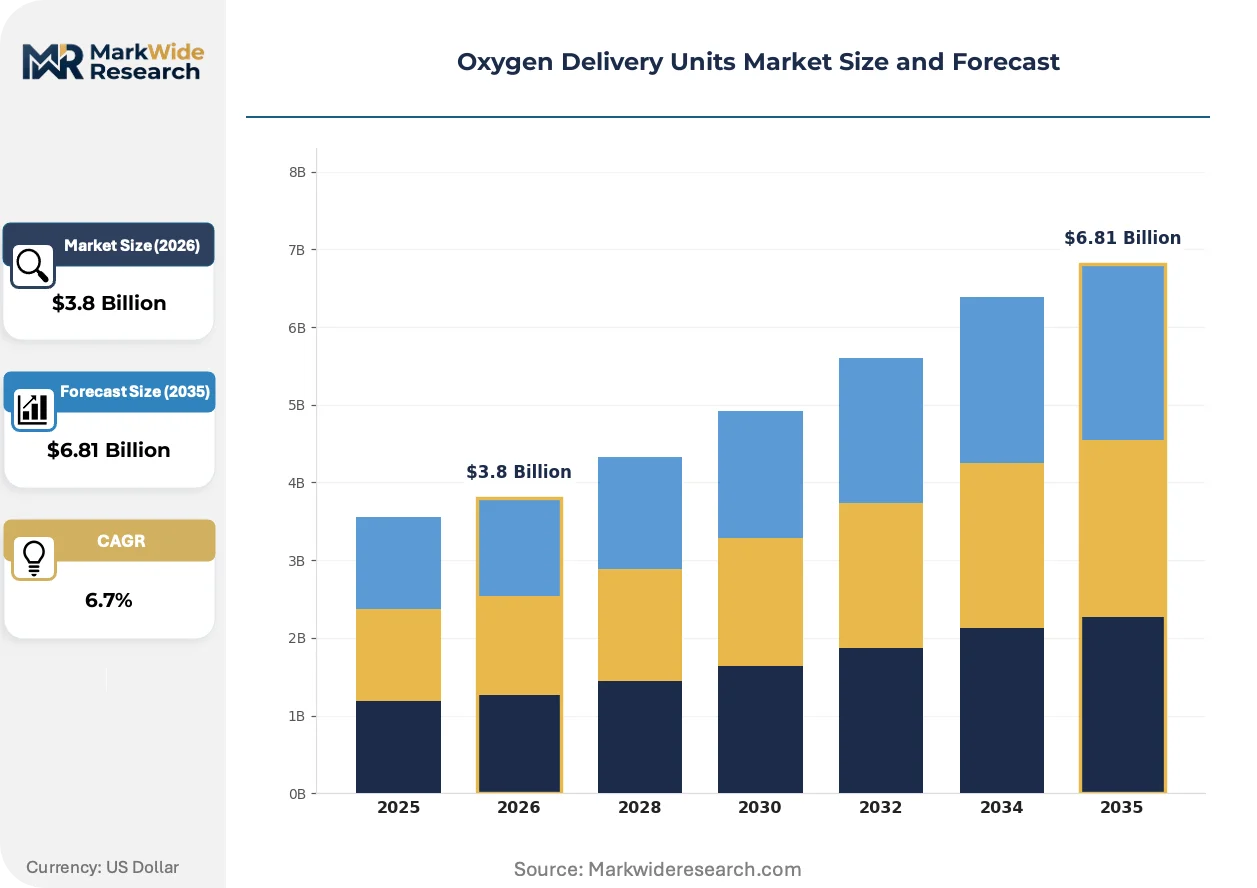
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Fixed Systems, Concentrators, Liquid Oxygen Systems End User: Hospitals, Home Care Providers, Emergency Services, Nursing Facilities Technology: Cryogenic, Mechanical, Membrane Separation, Adsorption Application: Respiratory Disorders, Anesthesia, Cardiovascular Treatment, Emergency Care |
| Companies Covered | Koninklijke Philips N.V., Inogen, Inc., Chart Industries, Inc., Invacare Corporation, Drive DeVilbiss Healthcare, ResMed Inc., Caire, Inc., Fisher & Paykel Healthcare Corporation Limited, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Delivery Units Market Evolving Landscape
Device intelligence and connectivity protocols are redefining competitive differentiation beyond flow-rate specifications, shifting value capture toward data-enabled patient management ecosystems.
Portable oxygen concentrators leveraging single-lithium-ion battery architectures are supplanting compressed gas cylinder systems in ambulatory patient segments. Home care providers across Germany and France are consolidating procurement around these devices to eliminate cylinder exchange logistics. The transition is compressing revenue per patient for liquid oxygen suppliers while expanding addressable margins for electronics-integrated manufacturers.
EU Medical Device Regulation Class IIa conformity assessment is extending notified body review timelines for oxygen delivery systems. Manufacturers must now submit clinical evaluation reports against MEDDEV 2.7/1 rev 4 guidelines for all new concentrator variants. The burden falls heaviest on small-to-mid tier suppliers lacking in-house regulatory affairs capacity, accelerating consolidation toward vertically integrated device houses.
Patients and caregivers are demanding ownership of usage data generated by connected concentrators, disrupting traditional equipment-lessor control over therapy analytics. Home care agencies in the United States are responding with patient-facing mobile applications that unbundle adherence reporting from device rental contracts. This behavioral shift is most pronounced in Medicare Advantage populations where supplemental benefits cover smartphone-enabled remote monitoring.
Oxygen Delivery Units Market Segmentation
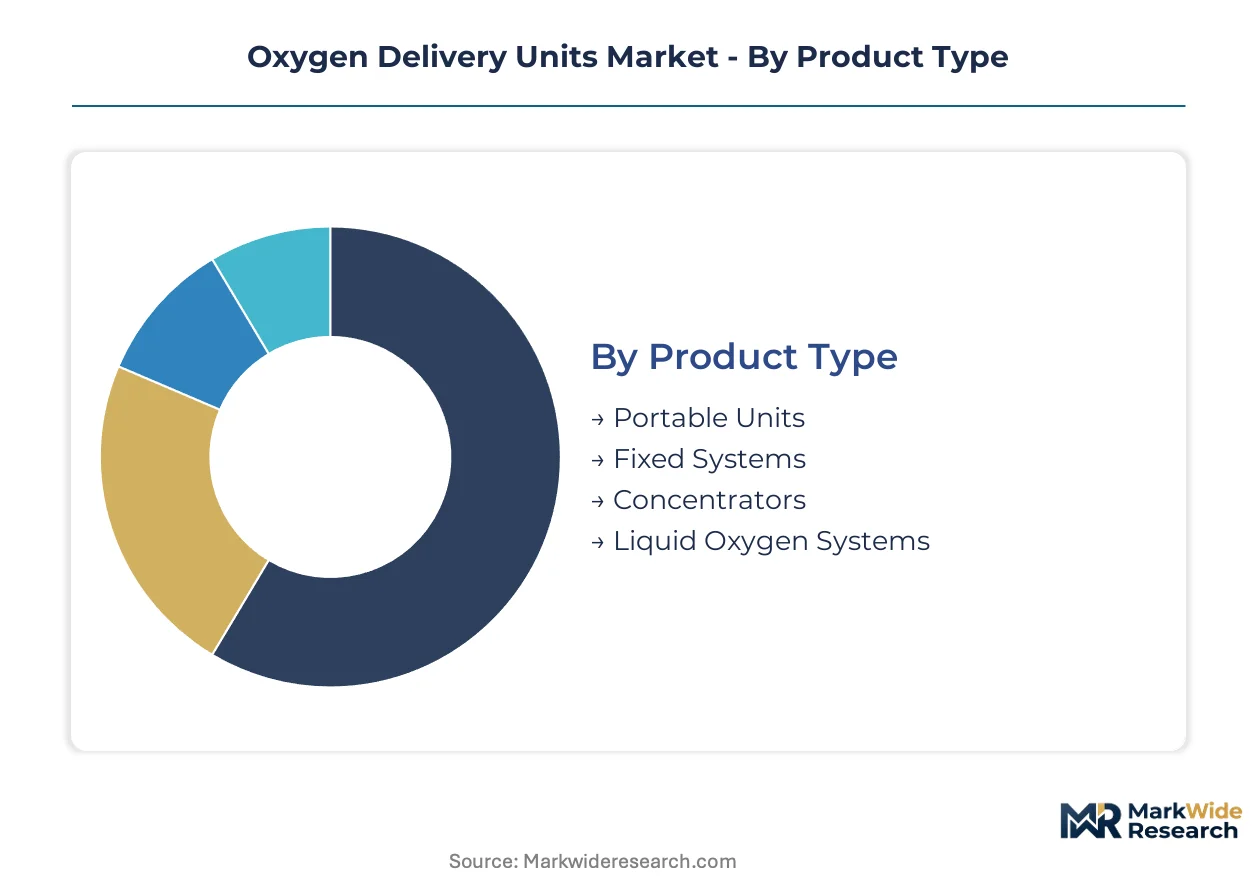
Oxygen delivery units fragment across four critical dimensions that determine procurement patterns and margin capture. Product type and technology choices define capital intensity and service revenue potential, while end-user concentration shapes distribution channel economics.
Product Type:
Margin pools concentrate in portable systems where miniaturization commands pricing premiums and recurring battery replacement revenue.
- Portable Units:Pressure swing adsorption compressors weighing under five pounds extract oxygen from ambient air for ambulatory COPD patients. Medicare reimbursement in the United States sustains supplier margins despite competitive bidding compression, while German home care providers eliminate cylinder logistics through consolidated portable procurement.
- Fixed Systems:Stationary concentrators delivering continuous flow up to 10 liters per minute anchor hospital infrastructure and long-term nursing facility installations. Japan's METI guidelines for home medical equipment accelerate concentrator placement among elderly hypoxemia patients in Tokyo and Osaka prefectures.
- Concentrators:Molecular sieve-based devices dominate clinical settings requiring 90%+ oxygen purity at flow rates of 0.5–5 liters per minute.
- Liquid Oxygen Systems:Cryogenic reservoirs store oxygen at minus 183 degrees Celsius for high-flow prescriptions exceeding 10 liters per minute.
The dominant share belongs to Fixed Systems, while Portable Units is closing the gap fastest.
End User:
Volume concentration tilts toward institutional purchasers with consolidated procurement power and multi-year service contracts.
- Hospitals:Acute care facilities deploy centralized liquid oxygen infrastructure alongside bedside concentrators for perioperative and critical care. FDA 510(k) clearance requirements and Joint Commission accreditation standards govern equipment selection in United States health systems.
- Home Care Providers:Durable medical equipment suppliers manage concentrator fleets across patient residences with remote monitoring integration. India's PLI scheme for medical devices reduces component import dependence and compresses landed costs for domestic home care distributors.
- Emergency Services:Ambulance and air medical operators prioritize lightweight compressed gas cylinders for rapid deployment.
- Nursing Facilities:Skilled nursing and assisted living centers balance stationary concentrator reliability with portable backup systems.
Hospitals retain the largest installed base, though Home Care Providers is expanding most quickly as post-acute care decentralizes.
Technology:
Supply concentration clusters around pressure swing adsorption where molecular sieve engineering creates captive manufacturing advantages.
- Cryogenic:Distillation systems liquefy air for bulk oxygen separation, serving high-flow clinical applications and industrial medical gas suppliers. North American bulk suppliers control cold-chain logistics for liquid oxygen distribution, limiting geographic expansion of stationary reservoir systems.
- Mechanical:Compressor-based systems pressurize ambient air for oxygen enrichment in resource-constrained settings.
- Membrane Separation:Polymeric filters separate oxygen from nitrogen through differential permeation rates. Forty percent oxygen concentration output fails clinical thresholds for severe respiratory failure, constraining application scope to wellness and altitude sickness markets.
- Adsorption:Pressure swing and vacuum swing variants cycle molecular sieves to achieve 90–95% purity at clinical flow rates.
Adsorption commands the dominant technology share, while Cryogenic maintains premium positioning in high-flow institutional segments.
Application:
Revenue stability varies across clinical use cases with chronic disease management offering predictable replacement cycles versus emergency deployment.
- Respiratory Disorders:COPD, pulmonary fibrosis, and interstitial lung disease patients require continuous or nocturnal oxygen supplementation. ISO 80601-2-69 electromagnetic compatibility and alarm system testing extends product development cycles by 8–14 months for new concentrator entrants targeting this segment.
- Anesthesia:Operating rooms blend oxygen with anesthetic gases for controlled sedation during surgical procedures.
- Cardiovascular Treatment:Myocardial infarction and heart failure protocols deploy supplemental oxygen to reduce cardiac workload.
- Emergency Care:Trauma and acute respiratory failure interventions demand immediate high-flow oxygen delivery.
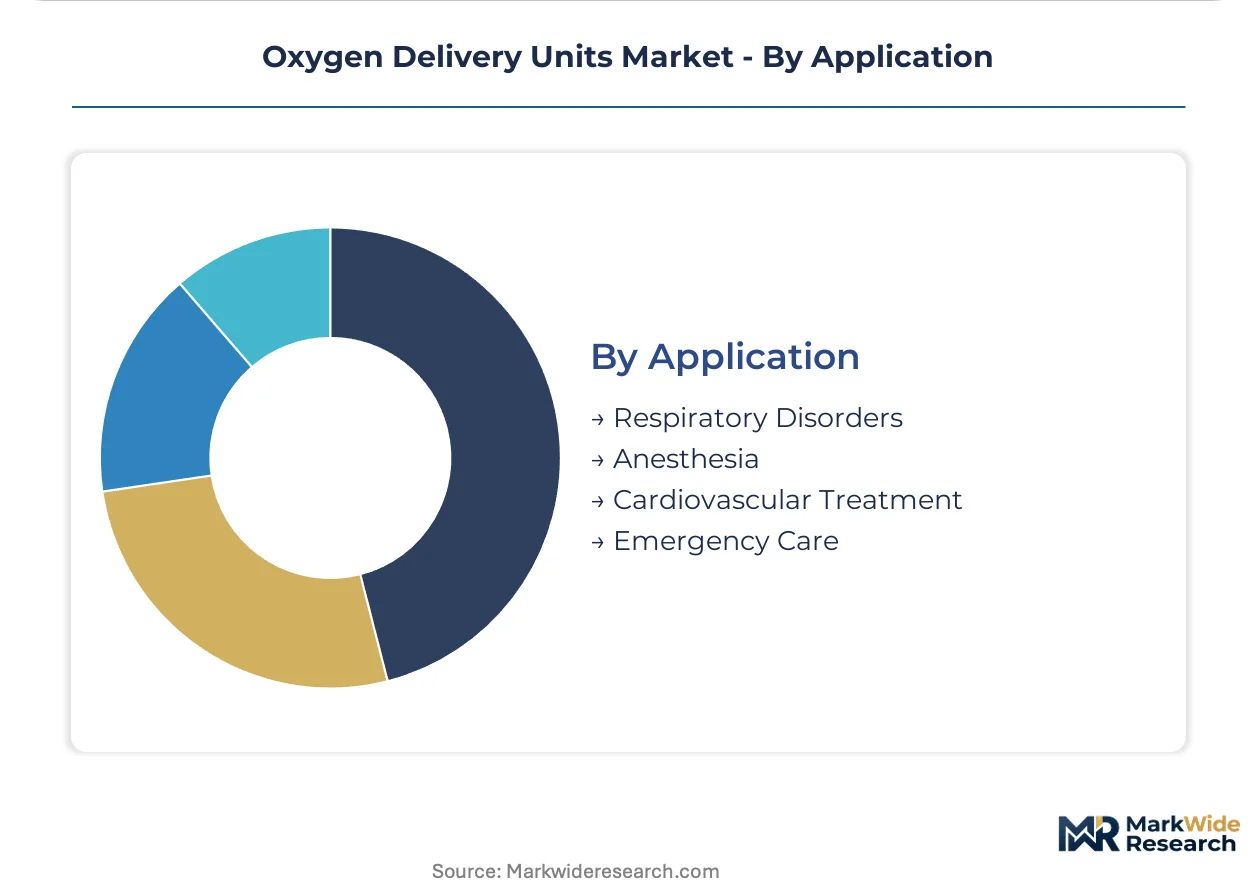
Respiratory Disorders anchors the largest patient population, while Emergency Care shows the steepest expansion trajectory driven by pre-hospital system investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement frameworks and industrial policy incentives are redrawing geographic deployment patterns for oxygen delivery infrastructure. CMS competitive bidding sustains supplier networks in the United States, while India's PLI scheme for medical devices accelerates domestic concentrator manufacturing capacity.
United States
Medicare competitive bidding outcomes determine durable medical equipment supplier viability across metropolitan statistical areas. FDA 510(k) clearance requirements and Joint Commission accreditation standards govern hospital procurement decisions. Texas and Florida concentrate home oxygen therapy patient populations due to aging demographics and COPD prevalence in Gulf Coast states.
Germany
Home care providers in Bavaria and North Rhine-Westphalia are consolidating portable concentrator procurement to eliminate compressed gas cylinder logistics. EU Medical Device Regulation Class IIa conformity assessment extends notified body review timelines for new concentrator variants. The Eindhoven-Randstadt corridor anchors distribution networks serving German and Benelux markets.
Japan
METI guidelines for home medical equipment accelerate concentrator placement among elderly hypoxemia patients in Tokyo and Osaka prefectures. PMDA quality management standards align with ISO 13485 for device commercialization. The Kansai region hosts manufacturing clusters supplying molecular sieve components to domestic concentrator assemblers.
India
PLI scheme incentives reduce import dependence for concentrator components and compress landed costs for domestic distributors. CDSCO medical device rules govern Class B and C oxygen delivery system registration. Maharashtra and Gujarat concentrate contract manufacturing capacity serving both domestic demand and export markets.
China
NMPA registration requirements for Class II medical devices structure market entry pathways for oxygen concentrator manufacturers. MIIT industrial policy supports domestic production of molecular sieve materials and compressor assemblies. The Yangtze River Delta anchors electronics-integrated portable concentrator manufacturing clusters.
Oxygen Delivery Units Market Competitive Landscape
Listed leaders compete with private specialists across regulatory qualification and reimbursement access dimensions. The competitive landscape bifurcates between vertically integrated device houses with in-house regulatory affairs capacity and component-dependent assemblers facing extended certification cycles. Strategic archetypes include sleep therapy platform extenders, cryogenic engineering specialists, and portable electronics miniaturizers. Incumbents defend position through M&A absorption of notified body-qualified smaller suppliers and backward integration into molecular sieve manufacturing.
Within the vertically integrated tier, Koninklijke Philips N.V. and ResMed Inc. exemplify platform-extender positioning across respiratory therapy categories. Inogen, Inc. represents the portable specialization archetype, while Chart Industries, Inc. anchors cryogenic system expertise. These three listed entities occupy distinct competitive vectors: sleep therapy convergence, ambulatory miniaturization, and bulk medical gas infrastructure respectively.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Inogen, Inc. |
| Chart Industries, Inc. |
| Invacare Corporation |
| Drive DeVilbiss Healthcare |
| ResMed Inc. |
| Caire, Inc. |
| Fisher & Paykel Healthcare Corporation Limited |
| Teleflex Incorporated |
| Others |
Value Network & Pricing Analysis
Eight-to-fourteen-month product development cycles for ISO 80601-2-69 compliance concentrate pricing power among incumbents with captive regulatory affairs capacity, while new entrants absorb extended certification costs through compressed hardware margins.
Pricing Analysis
Certification level creates the primary spread between premium FDA 510(k)-cleared portable concentrators and economy-tier mechanical alternatives lacking electromagnetic compatibility validation. Subscription-based equipment provision dominates in fragmented European markets, while Medicare competitive bidding anchors transactional pricing in the United States. Price differentiation hinges on molecular sieve purity ratings and remote monitoring integration depth. Cost compression in the portable segment intensifies as lithium-ion battery commoditization erodes electronics-integrated premiums. Home care providers exhibit highest price sensitivity due to competitive bidding margin pressure, whereas hospital purchasing committees prioritize Joint Commission compliance over unit economics.
Supply Chain Analysis
China and the United States anchor molecular sieve manufacturing and compressor assembly respectively, with the Kansai region in Japan supplying specialized zeolite materials for high-purity clinical applications. The industry draws from lithium-ion cell production in South Korea, precision compressor components from Germany, and polymeric membrane substrates from specialized chemical suppliers. Single-source vulnerability concentrates in cryogenic cold-chain logistics controlled by North American bulk suppliers. Distribution runs through durable medical equipment distributors in the United States and direct-to-patient rental platforms in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance subscriptions and remote adherence monitoring expand faster than hardware replacement cycles.
For Market Incumbents: Fortify regulatory qualification moats by accelerating FDA 510(k) predicate device libraries and backward integration into molecular sieve manufacturing. Absorb notified body-qualified smaller suppliers before EU MDR Class IIa review timelines extend further. Defend against portable electronics specialists by embedding telehealth-integrated pulse oximetry into core concentrator platforms. For New Entrants and Emerging Players: Lead with India's PLI scheme manufacturing incentives to compress landed costs for domestic distributors serving price-sensitive home care segments. Target Maharashtra and Gujarat contract manufacturing clusters for component localization. Pursue subscription-based direct-to-patient models in fragmented European markets to bypass entrenched durable medical equipment distribution. For Investors and Strategic Acquirers: Carve-out targets emerge from sleep therapy platform extenders seeking respiratory category consolidation and cryogenic engineering specialists with hospital infrastructure relationships. Long-term viability centers on data-enabled patient management ecosystems rather than hardware margins alone. Watch CMS competitive bidding outcomes as inflection indicators for home oxygen supplier network stability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Expands addressable revenue pools among Medicare-reimbursed home oxygen therapy patients. |
| Backward Integration into Molecular Sieves | Captures margin compression from zeolite material suppliers and shortens procurement lead times. |
| Telehealth Platform Partnership | Converges remote SpO2 monitoring with concentrator telemetry for predictive maintenance revenue. |
| PLI Scheme Manufacturing Localization | Reduces import dependence for compressor components serving Indian home care distributors. |
| Subscription-Based Equipment Provision | Bypasses traditional durable medical equipment channels in fragmented German and French markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and home care procurement directors; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body registers, and concentrator import customs records. Bottom-up triangulation across patient population estimates and top-down reconciliation against manufacturer revenue disclosures anchored volume and value outputs.
Across the analysis window, forecasts model product type segmentation by portable versus fixed systems, technology differentiation across pressure swing adsorption and cryogenic variants, and end-user concentration among hospitals, home care providers, and nursing facilities. CAGRs derive from patient population epidemiology, replacement cycle assumptions for molecular sieve degradation, and reimbursement policy continuity scenarios. Industry-specific inputs include Medicare competitive bidding round outcomes and METI guideline implementation timelines for Japanese home medical equipment.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways, EU MDR Class IIa conformity assessment procedures, and India's PLI scheme incentive structures; material policy shifts in CMS reimbursement thresholds or CDSCO medical device rules would require re-modeling. Recalibration cycles align with material shifts in competitive bidding outcomes, notified body capacity constraints, and molecular sieve material cost volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Knee Braces Market
Medical Devices
Global Extremities Market
Medical Devices
Self-Sampling Blood Collection and Storage Devices Market
Medical Devices
Medical Device Complaint Management Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Buccal Drug Delivery System Market
Medical Devices
Luer Lock Connector Market
Medical Devices
Europe Otoscope Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
Power Wheelchairs and Mobility Scooters Market
Medical Devices
Global Mobile ECG Devices Market
Medical Devices
UHD Surgical Display Market
Medical Devices
Flexible Spinal Implants Market
Medical Devices
Wearable Pulse Oximeters Market
Medical Devices
Global Nerve Monitoring System Market