
 Global Centesis Catheters Market | 2026-2036
Global Centesis Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Centesis Catheters Market Intelligence
The end-user landscape for centesis catheters is pivoting from a hospital-centric model to include more procedures in ambulatory surgical centers. This shift reflects a move towards cost-effective, outpatient care settings. Becton, Dickinson and Company leverages its extensive distribution network to serve both hospitals and ASCs. Teleflex Incorporated specializes in safety-engineered devices for complex procedures, while Cook Medical sustains its market position through a focus on minimally invasive product lines.
Centesis catheters are sterile, single-use medical devices designed for fluid aspiration or drainage from body cavities. They are typically made from materials like polyurethane or silicone and feature specific gauge sizes and lengths for different procedures. Paracentesis catheters, used for draining ascites, represent a mature application segment. The ultrasound-guided technology segment is expanding rapidly, displacing older blind techniques due to enhanced safety and precision provided to clinicians in hospitals.
Market access for centesis catheters is governed by stringent regulatory approvals. In the United States, the FDA's 510(k) clearance process is critical, while in Europe, compliance with the Medical Device Regulation (MDR) and CE marking is mandatory for all manufacturers. China's National Medical Products Administration (NMPA) imposes its own rigorous standards for device registration. Stakeholder success will depend on navigating these varied international regulatory pathways while investing in clinical evidence for specific applications.
Market Dynamics
The primary structural force shaping the centesis catheters market is the clinical transition to image-guided procedures. The widespread adoption of ultrasound technology is fundamentally altering procedural risk profiles, improving accuracy, and making older blind-puncture techniques obsolete in established healthcare systems.
Growth Catalysts
- Ultrasound Integration:The shift to ultrasound-guided techniques enhances procedural safety for applications like pleural effusion management in hospitals, reducing complication rates and encouraging broader use.
- Aging Demographics:An increasing prevalence of chronic conditions such as ascites and congestive heart failure in developed nations like Germany and Japan expands the patient population requiring fluid drainage.
- Outpatient Care Shift:Favorable reimbursement policies in the United States for procedures performed in ambulatory surgical centers (ASCs) create a cost-effective alternative to traditional hospital settings, expanding access.
Market Restraints
- Reimbursement Variation:Inconsistent reimbursement codes and payment levels across different healthcare systems create economic uncertainty for both providers and manufacturers, particularly for premium, safety-engineered devices.
- Regulatory Friction:The stringent requirements of the European Union's Medical Device Regulation (MDR) increase the time and cost for manufacturers to obtain or maintain CE marking, slowing product updates.
- Alternative Therapies:For certain conditions like ascites, pharmacological treatments such as diuretics or more invasive shunts present clinical alternatives that can defer or eliminate the need for paracentesis.
Strategic Opportunities
- Emerging Economies:Expanding healthcare infrastructure and rising middle-class incomes in countries like Brazil and Mexico present significant growth potential for centesis catheter manufacturers.
- Smart Catheter Development:The integration of micro-sensors into catheters to provide real-time data on fluid properties or pressure offers a new frontier for product differentiation and clinical value.
- Pediatric Applications:Designing and marketing catheters specifically sized and engineered for neonatal and pediatric patients represents a specialized, high-value market segment with unmet needs.
Industry Challenges
- Clinician Training:The effective use of ultrasound-guided centesis systems requires specialized training, and a shortage of proficient sonographers and clinicians can limit adoption rates in some facilities.
- Global Regulatory Divergence:Navigating the distinct and complex submission requirements of the FDA in the U.S., the NMPA in China, and the EU's MDR framework demands significant regulatory expertise and resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Centesis Catheters Market |
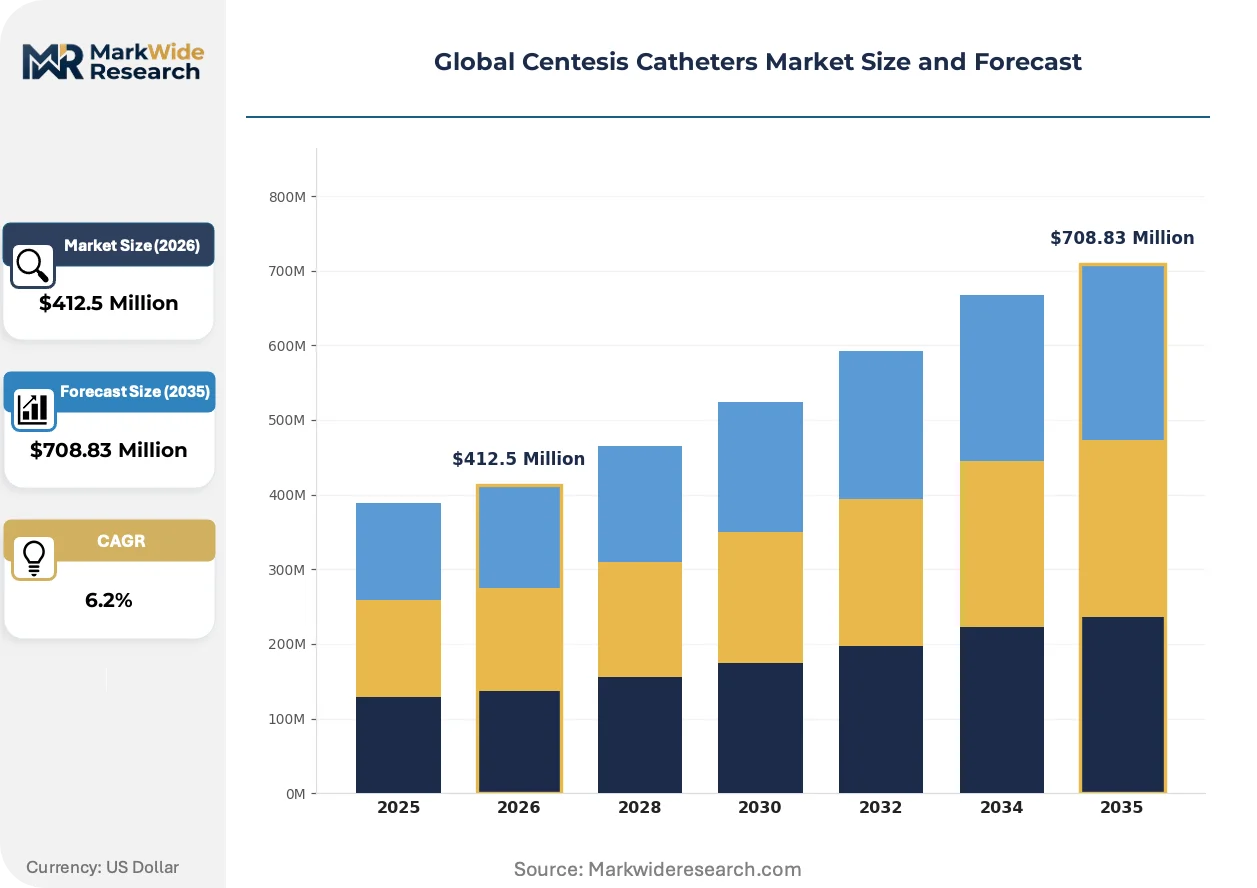
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $708.83 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thoracentesis Catheters, Paracentesis Catheters, Pericardiocentesis Catheters, Others Application: Pleural Effusion, Ascites, Pericardial Effusion, Diagnostic Procedures End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Laboratories Technology: Ultrasound-Guided, Fluoroscopy-Guided, Blind Technique, CT-Guided |
| Companies Covered | AngioDynamics, Inc., Medtronic, Boston Scientific Corporation, Becton, Dickinson and Company, B. Braun Melsungen AG, Teleflex Incorporated, Merit Medical Systems, Cook Medical, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Centesis Catheters Market Strategic Shifts & Innovations
The market's evolution is defined by a dual focus on enhancing procedural safety through technological advancement and improving economic efficiency by shifting care to outpatient settings. Innovations are centered on better visualization, material science, and procedural kits that support this transition.
Advanced catheter designs feature echogenic materials and specialized tip geometries that enhance visibility under ultrasound. Clinicians in high-volume hospitals and specialized clinics are rapidly adopting these devices to improve needle tracking and placement accuracy. This technology is integrating real-time imaging directly into the procedural workflow, reducing risks of inadvertent puncture and improving first-pass success rates for fluid aspiration.
Europe's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence and post-market surveillance. This regulation forces manufacturers to generate more robust data to support the safety and performance claims of their centesis catheters. The segment most affected is new product development, where companies must now allocate more resources to clinical trials and technical documentation to achieve CE marking.
A clear behavioral shift is occurring as procedures migrate from hospital inpatient wards to ambulatory surgical centers (ASCs) and outpatient clinics. This disrupts traditional bulk purchasing models, creating demand for procedure-specific kits and just-in-time logistics that cater to smaller, more agile facilities. This trend is most advanced in the United States, where payer incentives strongly encourage the use of lower-cost care settings.
Global Centesis Catheters Market Segmentation
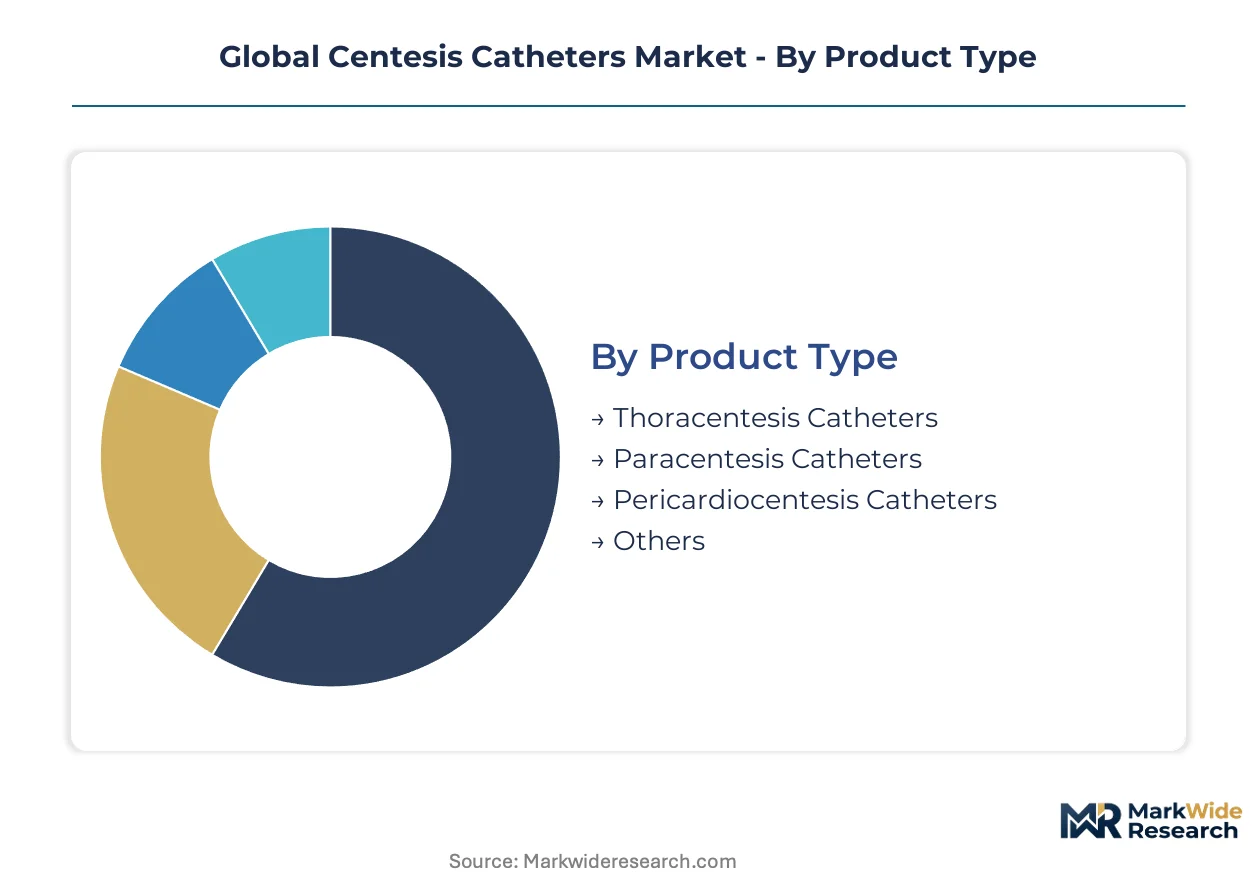
The centesis catheters market segmentation reveals distinct product types and applications driving demand across varied end-user settings. These categories highlight how technological advancements influence procedural approaches and overall market dynamics. Understanding these segments is crucial for strategic planning.
Product Type:
The product type segmentation delineates between high-volume applications and those requiring specialized designs for delicate procedures.
- Paracentesis Catheters:These devices are specifically engineered for draining ascites fluid from the peritoneal cavity, often featuring larger gauge sizes and multiple side holes to facilitate efficient drainage. Demand for paracentesis catheters is consistently high in hospitals across the United States due to the prevalence of liver disease and associated ascites.
- Thoracentesis Catheters:Designed for removing fluid from the pleural space surrounding the lungs, these catheters typically include safety features like blunt tips or self-sealing valves to minimize lung injury. Hospitals in Germany frequently utilize thoracentesis catheters for managing pleural effusions, driven by an aging population.
- Pericardiocentesis Catheters:These are fine-gauge catheters used for aspirating fluid from the pericardial sac, demanding precision for cardiac applications.
- Others:This category encompasses various specialized catheters for less common centesis procedures or niche anatomical sites.
Mature deployment sits with Paracentesis Catheters. Newer deployment is concentrated in Thoracentesis Catheters.
Application:
Market applications for centesis catheters range from routine fluid management to critical diagnostic interventions.
- Pleural Effusion:This application involves draining fluid accumulation around the lungs, frequently managed with ultrasound-guided thoracentesis procedures in hospital settings. The rising incidence of congestive heart failure in Japan contributes to the demand for these interventions.
- Ascites:Centesis catheters are widely used for therapeutic drainage of ascites, a common complication of liver cirrhosis, particularly in older patient populations. Outpatient clinics in Brazil are increasingly performing paracentesis for ascites due to cost-effectiveness.
- Pericardial Effusion:This critical application requires precise fluid removal from around the heart, often performed in emergency or specialized cardiac units.
- Diagnostic Procedures:Centesis catheters facilitate the collection of fluid samples for laboratory analysis, aiding in the diagnosis of various underlying conditions.
The Ascites application commands a significant volume share. Pleural Effusion is gaining share fastest, driven by improved diagnostic capabilities.
End User:
The end-user landscape for centesis catheters is undergoing a strategic shift, driven by evolving healthcare delivery models.
- Hospitals:These institutions remain the primary purchasers and users of centesis catheters, particularly for complex cases and inpatient procedures requiring extensive post-procedural care. Hospitals in the United States maintain high demand for a broad range of catheter types.
- Ambulatory Surgical Centers:ASCs are increasingly adopting centesis procedures due to favorable reimbursement policies and a focus on cost-effective outpatient care. This shift is particularly evident in the US market, expanding access to procedures.
- Specialty Clinics:These clinics, often focusing on specific conditions like oncology or gastroenterology, utilize centesis catheters for targeted patient populations.
- Diagnostic Laboratories:While not directly performing procedures, these labs receive fluid samples collected via centesis catheters for analysis.
Hospitals represent the established end-user base. Ambulatory Surgical Centers are showing the steepest expansion trajectory.
Technology:
Technological advancements define the safety and precision of centesis procedures, influencing adoption rates across clinical settings.
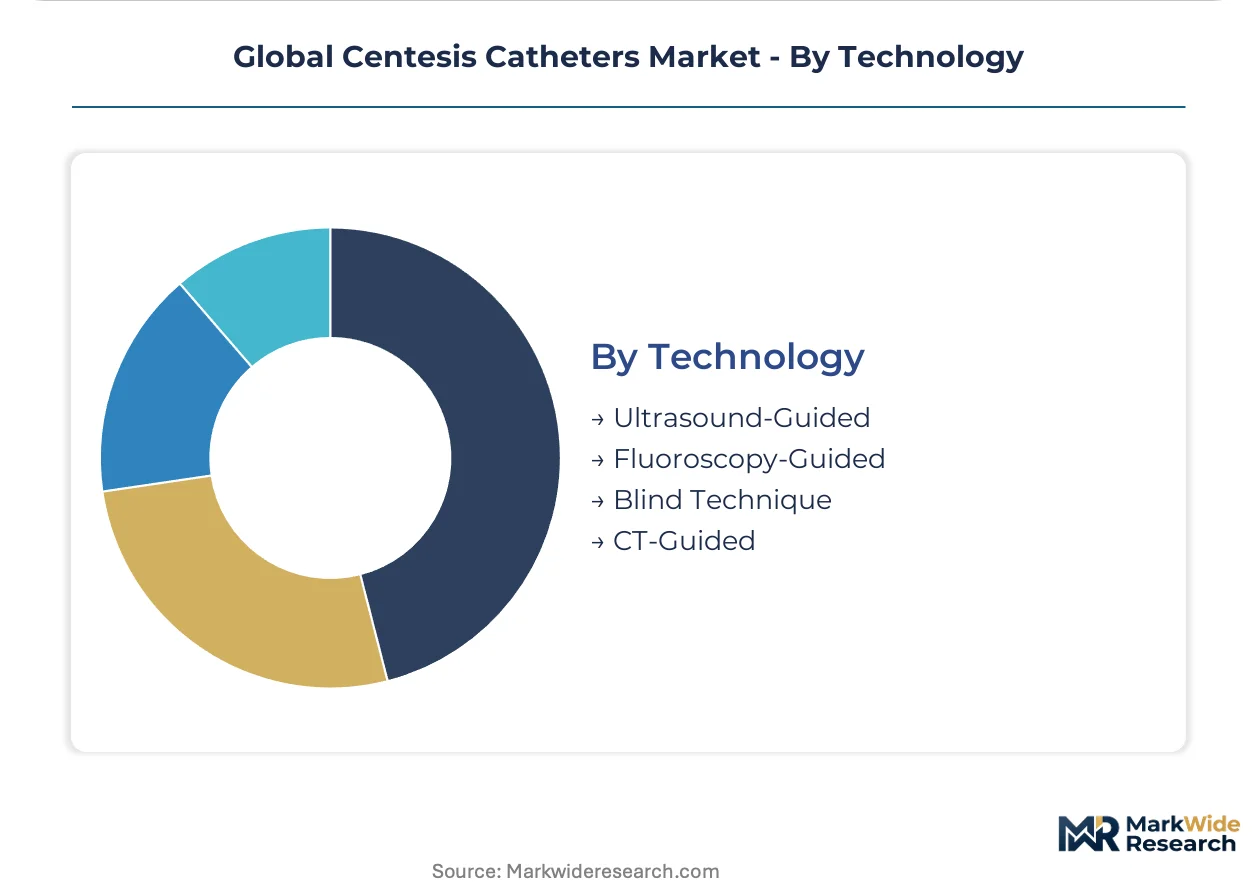
- Ultrasound-Guided:This technology segment involves using real-time ultrasound imaging to guide catheter placement, enhancing safety and accuracy by visualizing anatomical structures and fluid pockets. Adoption of ultrasound-guided techniques is widespread in developed healthcare systems like Germany.
- Blind Technique:Older blind puncture methods rely on anatomical landmarks and tactile feedback, carrying higher risks of complications compared to image-guided alternatives. This technique is being displaced in established healthcare systems.
- Fluoroscopy-Guided:This technique uses continuous X-ray imaging for catheter guidance, often employed in specific interventional radiology procedures.
- CT-Guided:Computed Tomography guidance provides detailed cross-sectional imaging for highly complex or deeply seated fluid collections, used in specialized hospital departments.
The Blind Technique reflects older procedural standards. Ultrasound-Guided technology is experiencing the most rapid adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical technology innovation hubs across the United States drive significant concentration for centesis catheter development and deployment. These regions benefit from targeted state-level incentives and robust research ecosystems. Such focused environments foster advanced device manufacturing and clinical adoption.
United States
Demand for paracentesis catheters in the United States remains high due to prevalent liver disease. Favorable reimbursement policies from CMS for ASCs encourage outpatient procedures. The FDA's 510(k) clearance process is essential, with medical device clusters in Minnesota driving innovation.
Germany
German hospitals frequently utilize thoracentesis catheters for pleural effusions, driven by an aging population. Compliance with the European Medical Device Regulation (MDR) ensures high device quality. Medical technology hubs in Baden-Württemberg lead advanced device development.
China
China's expanding healthcare infrastructure and rising middle-class incomes present significant growth potential for centesis catheters. The National Medical Products Administration (NMPA) imposes rigorous standards for device registration. Medical device parks in Shanghai attract investment in local manufacturing capabilities.
Japan
Japan's aging demographics and rising incidence of congestive heart failure contribute to demand for pleural effusion management. The PMDA ensures stringent regulatory oversight for device approvals. Medical technology firms in Osaka focus on advanced catheter development for precision procedures.
Brazil
Brazilian outpatient clinics increasingly perform paracentesis for ascites due to cost-effectiveness and accessibility. ANVISA governs medical device registration and market entry, supporting market expansion. Medical technology clusters in Minas Gerais support local innovation and manufacturing.
Global Centesis Catheters Market Key Industry Players
Top-tier vendors anchor the premium segment, offering comprehensive product portfolios and global distribution networks. Specialized mid-tier players, conversely, concentrate on niche applications or specific technological advancements like ultrasound-guided devices. The market exhibits a tiered structure, with established multinational corporations alongside agile regional manufacturers. Strategic archetypes include diversified medical device giants and focused minimally invasive solution providers. Competitive moves involve portfolio diversification, geographic expansion, and strategic partnerships to enhance market presence.
Within the diversified medical device giant archetype, Becton, Dickinson and Company exemplifies broad market reach through its extensive distribution network, serving both hospitals and ambulatory surgical centers. Teleflex Incorporated represents specialists in safety-engineered devices, focusing on complex procedural solutions for clinicians. Cook Medical anchors the minimally invasive product line segment, sustaining its market position through targeted innovation in catheter materials and designs. These entities collectively demonstrate the varied strategic approaches to product development, market access, and end-user engagement within the centesis catheters industry, addressing different segments of clinical need.
| Leading Market Players |
|---|
| AngioDynamics, Inc. |
| Medtronic |
| Boston Scientific Corporation |
| Becton, Dickinson and Company |
| B. Braun Melsungen AG |
| Teleflex Incorporated |
| Merit Medical Systems |
| Cook Medical |
| Cardinal Health |
| Others |
Cost & Logistics Intelligence
The widespread adoption of ultrasound-guided technology simultaneously reshapes cost economics and supply concentration for centesis catheters. This shift demands higher-precision manufacturing processes and specialized materials, influencing both production costs and the geographic distribution of advanced manufacturing capabilities.
Pricing Analysis
Premium pricing for short lead times reflects the critical nature of centesis procedures and the need for immediate device availability. Per-unit transactional pricing dominates the market, with price differentiation driven by certification levels like CE marking or FDA 510(k) clearance and specialized material science. Pricing softness stems from the increasing shift towards cost-effective outpatient settings, particularly for high-volume procedures. Hospitals purchasing complex, safety-engineered devices exhibit lower price sensitivity compared to ambulatory surgical centers focused on routine interventions.
Supply Chain Analysis
Single-source vulnerability sits with specialized material suppliers providing medical-grade polyurethane or silicone. Geographic supply concentration for advanced manufacturing centers on the United States, Germany, and Japan. Raw material dependencies include medical-grade polymers and precision-engineered components. Regulatory divergence across the FDA, EU MDR, and NMPA presents a structural supply chain risk, increasing compliance costs and market entry barriers. Distribution typically runs through established medical device distributors serving hospitals and ambulatory surgical centers globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a supply-constrained story, with the rigorous regulatory approval process for new devices acting as a significant capacity bottleneck propping pricing.
For Market Incumbents: Anticipate continued regulatory scrutiny, particularly under the EU MDR, by investing heavily in post-market surveillance and clinical evidence generation. Defend market share against emerging competitors by deepening vertical integration into specialized material production. Counter the threat of alternative therapies through continuous innovation in minimally invasive designs. Reinforce distribution networks to serve both established hospitals and expanding ambulatory surgical centers.
For New Entrants and Emerging Players: A price-point gap exists between premium, safety-engineered devices and more cost-effective, high-volume solutions for routine procedures. Target underpenetrated pediatric applications with specialized, smaller-gauge catheters engineered for precision. Focus on developing smart catheter technologies that offer real-time data, providing a unique value proposition. Penetrate emerging economies like Brazil and Mexico with localized manufacturing and tailored product offerings.
For Investors and Strategic Acquirers: Re-rating potential sits with companies demonstrating robust regulatory compliance and a clear pathway for next-generation, image-guided devices given the clinical transition. Target mid-tier manufacturers with strong intellectual property in material science or sensor integration for future growth. The signal to watch is the accelerated adoption rate of ultrasound-guided techniques in outpatient settings, indicating broader market acceptance and volume expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand ultrasound-guided product portfolio | Enhances procedural safety and accuracy for clinicians, driving adoption in hospitals. |
| Invest in advanced material science | Improves catheter flexibility and biocompatibility, reducing patient complications. |
| Strengthen regulatory affairs capabilities | Ensures compliance with evolving global standards like EU MDR and FDA 510(k). |
| Forge partnerships with ASC networks | Captures market share in the rapidly expanding outpatient care segment. |
| Develop pediatric-specific catheter lines | Addresses unmet needs in a high-value, specialized patient population. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. The study combined primary interviews with clinicians, hospital procurement managers, regulatory affairs specialists, and R&D engineers across North America and Europe. Bottom-up and top-down triangulation ensured data consistency and accuracy.
The data-stream reconciliation framework integrated market sizing from historical trends with future projections across the analysis window. Segmentation dimensions modeled included product type, application, end-user, technology, and regional regulatory environments. Compound annual growth rates were derived from a synthesis of historical performance and anticipated market dynamics, incorporating inputs like the prevalence of chronic conditions and healthcare spending growth.
Underlying measurement precision varies by segment; established paracentesis catheter markets carry tighter precision than nascent smart catheter development. Forecasts reflect assumptions regarding regulatory stability and the pace of technological adoption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neurovascular Catheters Market
Medical Devices
Endodontic Files Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Devices Market
Medical Devices
Transcatheter Pacing System Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Glass Syringe Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Syndesmosis Repair System Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
Global Prefilled Auto Injectors Market
Medical Devices
Self-Destructing Syringe Market
Medical Devices
Asia-Pacific Radiotherapy Market
Medical Devices
Pharmacy Automation Devices Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
EEG Electrodes Market